
 Advanced Process Control (APC) and Online Optimization Market | 2026-2036
Advanced Process Control (APC) and Online Optimization Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Process Control (APC) and Online Optimization Market Outlook
Subscription-based model predictive control (MPC) licensing is recalibrating how vendors monetize process optimization, shifting capital expenditure into recurring operational budgets. Siemens AG leverages its Simatic portfolio to anchor long-term service contracts across European chemical complexes. Honeywell International Inc. competes through Experion-based APC modules that sustain margin capture in North American refining. Aspen Technology Inc. specializes in rigorous optimization software that dominates advanced process control in pharmaceutical batch operations.
Advanced Process Control (APC) and Online Optimization encompasses multivariable model-based algorithms, real-time dynamic optimization engines, and sensor fusion architectures that adjust process variables within operational constraints to maximize throughput or minimize energy consumption. These systems typically execute control moves at minute-level frequencies while reconciling laboratory assay data with online analyzer measurements for closed-loop regulatory compliance. Software and controllers represent the dominant value pool where margin concentrates, though edge computing deployments are gaining traction as latency-sensitive applications migrate computation closer to field devices. Machine learning technology is expanding fastest within the technology dimension as neural network surrogates complement first-principles models in nonlinear process zones.
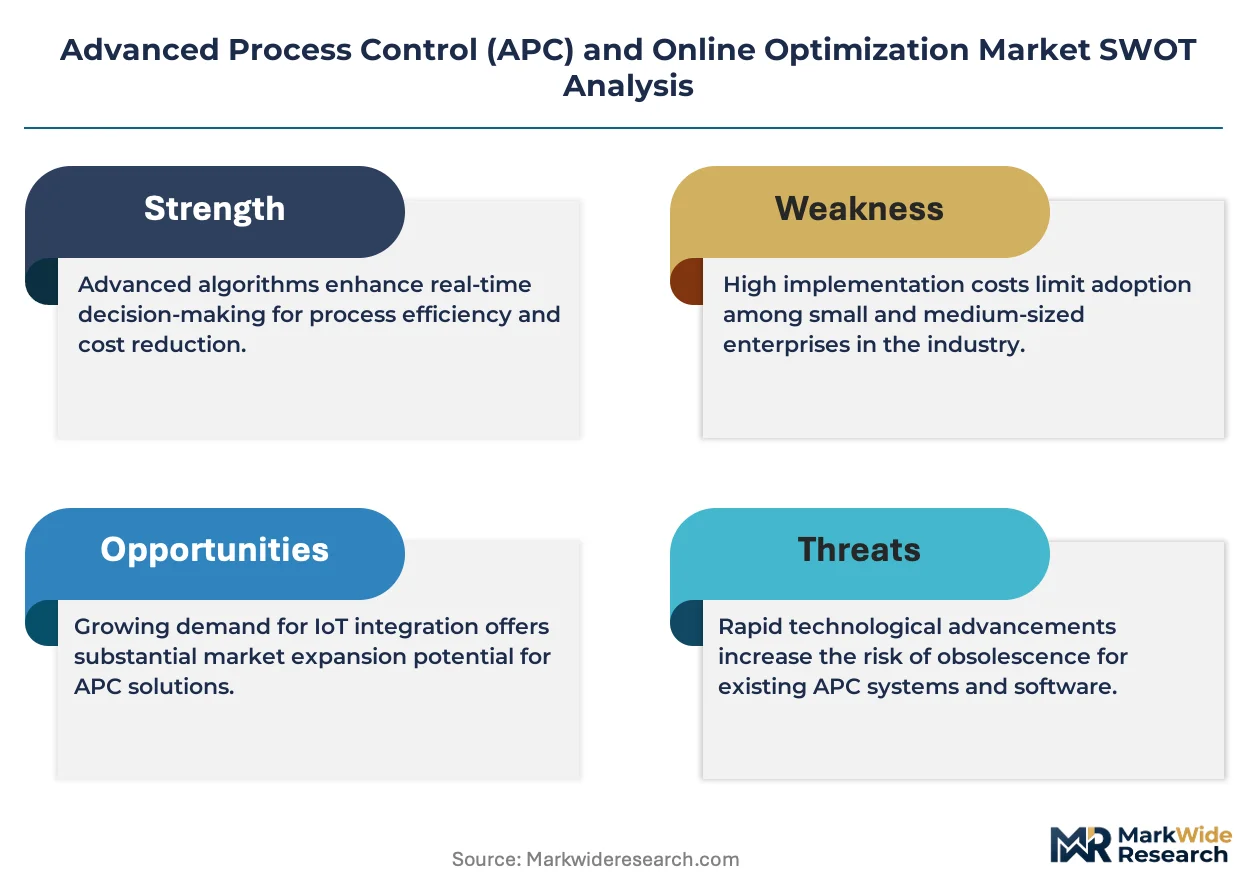
The EPA enforces emissions monitoring requirements that mandate continuous parameter tracking in covered chemical and petroleum facilities, directly expanding the installed base of online optimization infrastructure. REACH and the EU F-Gas Regulation impose material traceability and fluorinated gas phase-down obligations that APC systems must document through automated data historians. OSHA process safety management standards in the United States mandate mechanical integrity programs where predictive control layers serve as engineered safeguards. Stakeholders must evaluate whether cloud-based deployment architectures satisfy cross-border data residency requirements as jurisdictional frameworks for industrial data governance continue diverging.
Market Dynamics
Machine learning is displacing first-principles models in nonlinear process zones, forcing vendors to re-architect optimization engines around neural network surrogates while maintaining regulatory-grade audit trails for EPA and REACH compliance.
Growth Catalysts
- EU F-Gas Regulation:Fluorinated gas phase-down mandates drive retrofit demand for leak-detection-integrated APC systems in German chemical clusters.
- Edge computing architectures:Latency-sensitive refining applications migrate computation to field devices, expanding controller hardware attach rates.
- Pharmaceutical batch operations:Rigorous optimization software penetrates biologics manufacturing where PAT guidance demands real-time release testing.
Market Restraints
- Specialized control engineer scarcity:Multivariable model predictive control expertise concentrates in Ludwigshafen and Houston, inflating implementation timelines.
- Semiconductor component volatility:Industrial-grade FPGA lead times for embedded controllers extend to 52 weeks, constraining hardware shipments.
- Legacy DCS lock-in:Proprietary communication protocols in installed base block seamless APC layer integration without costly gateway infrastructure.
Strategic Opportunities
- Carbon capture integration:Amine-based post-combustion capture units require dynamic optimization of solvent regeneration cycles, opening greenfield APC deployments.
- Subscription licensing models:SaaS-based MPC shifts capital expenditure to operational budgets, lowering barriers for mid-scale specialty chemical producers.
- India's PLI scheme:Production-linked incentives for bulk drugs and intermediates attract APC investment to Dahej and Visakhapatnam manufacturing corridors.
Industry Challenges
- First-principles model maintenance:Aspen HYSYS and gPROMS surrogates demand continuous recalibration as catalyst deactivation and fouling alter process fundamentals.
- Cross-border data residency:Cloud-hosted optimization engines face jurisdictional fragmentation as Germany's BSI, France's CNIL, and India's CERT-In impose divergent industrial data governance requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Process Control (APC) and Online Optimization Market |
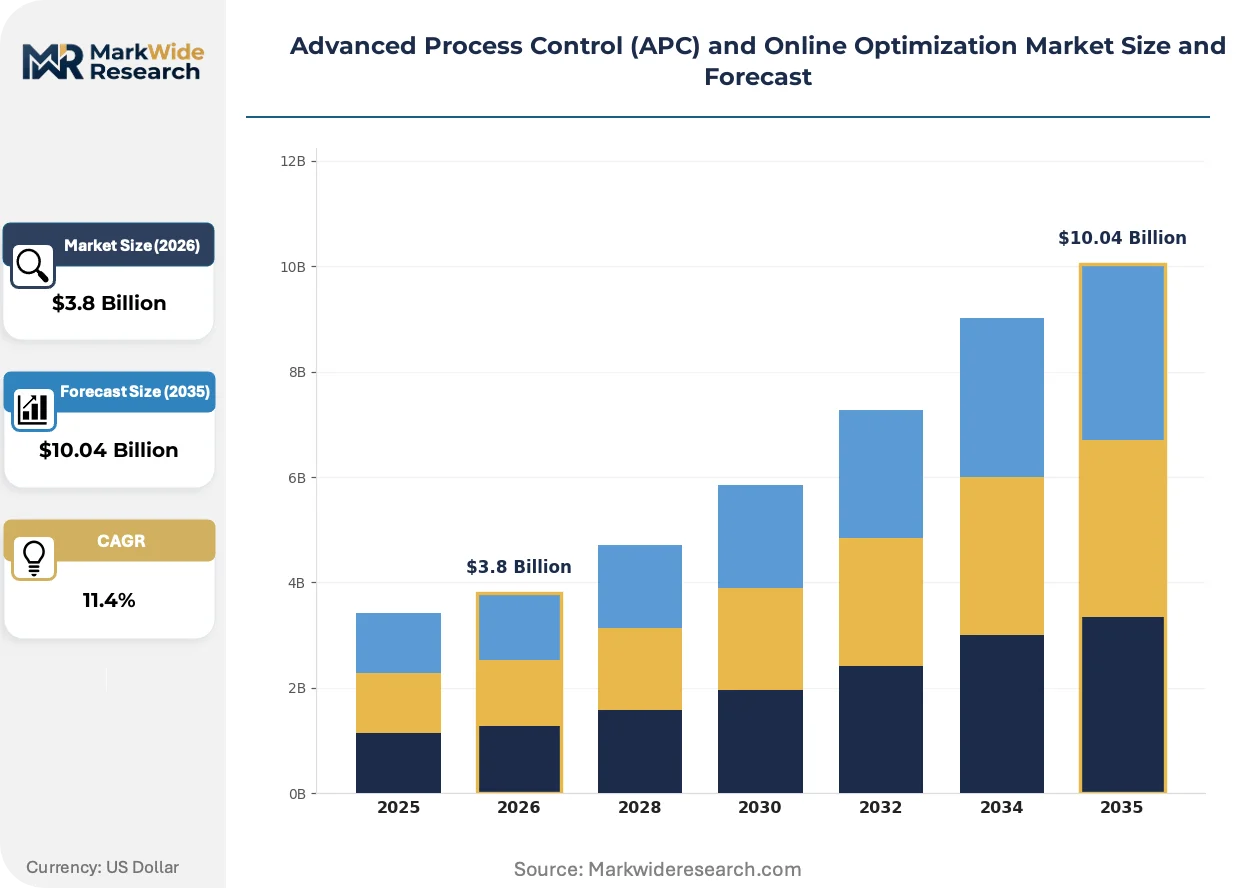
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Controllers, Sensors, Hardware Technology: Machine Learning, Statistical Process Control, Fuzzy Logic, Neural Networks End User: Chemical Processing, Oil & Gas, Pharmaceuticals, Food & Beverage Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Siemens AG, Rockwell Automation Inc., Honeywell International Inc., Schneider Electric SE, Yokogawa Electric Corporation, Emerson Electric Co., ABB Ltd., General Electric Company, Aspen Technology Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Process Control (APC) and Online Optimization Market Strategic Shifts
Digital twin architectures are collapsing the boundary between offline design and online operation, enabling real-time reconciliation of laboratory assays with virtual process models.
Neural network-based soft sensors are integrating laboratory-grade prediction into control loops where online analyzers fail. Refinery operators in the US Gulf Coast deploy these surrogates for octane blending optimization. The technology is integrating first-principles constraints with data-driven adaptability, compressing model development cycles from months to weeks.
REACH substance restriction proposals are tightening data historian requirements for material traceability across European chemical complexes. Automated batch records must now link raw material lots to finished product certificates of analysis. Pharmaceutical API manufacturers in Ireland and Belgium are retrofitting validation protocols to satisfy ECHA documentation demands.
Refinery procurement departments are unbundling APC software licenses from long-term service contracts, forcing vendors to compete on standalone optimization performance. North American downstream operators now benchmark vendor algorithms against open-source alternatives before renewal decisions. This pattern concentrates in independent refiners lacking captive engineering resources.
Advanced Process Control (APC) and Online Optimization Market Segmentation
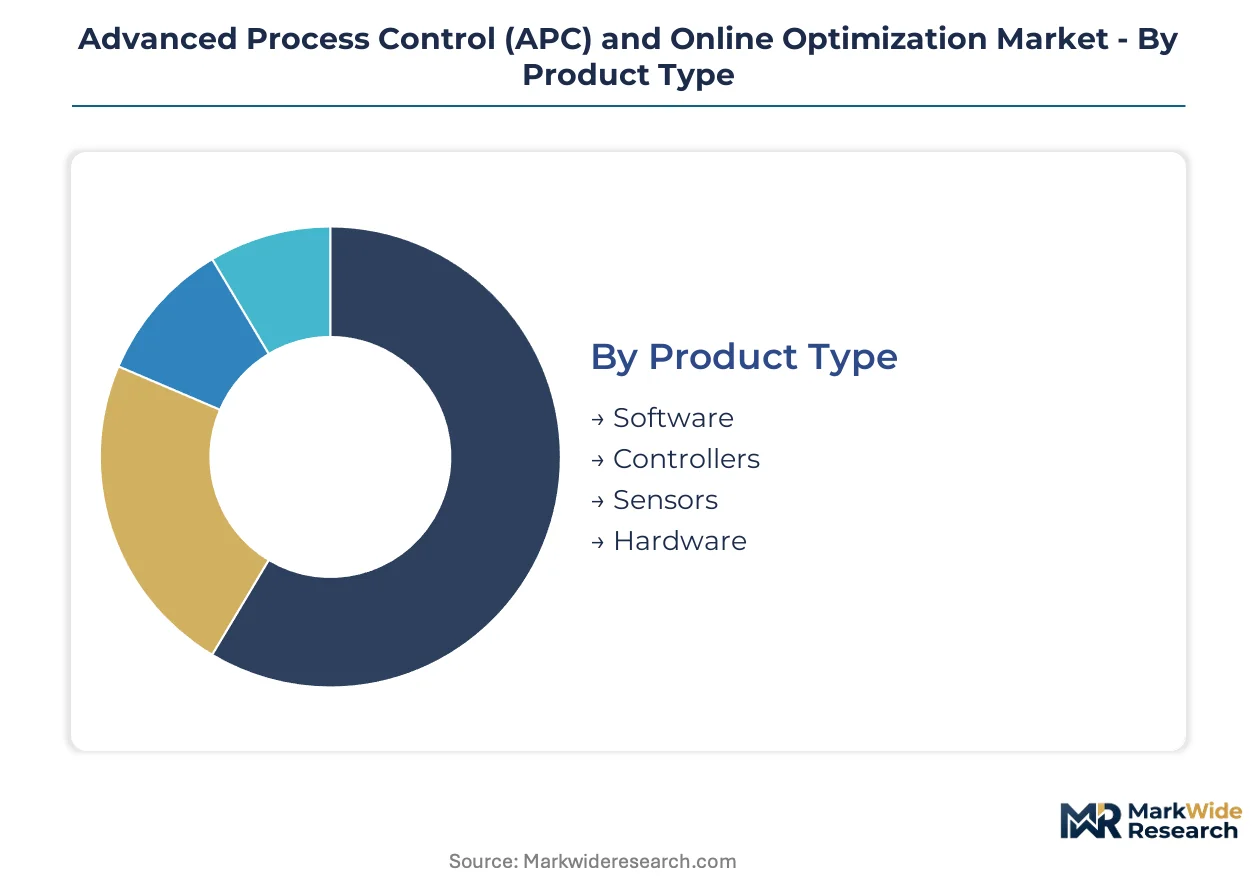
Segmentation in the APC and Online Optimization Market reveals how certification burdens, latency requirements, and process complexity reshape procurement priorities across industrial verticals. Each dimension carries distinct regulatory and technical constraints that determine vendor selection criteria and implementation timelines.
Product Type:
Software solutions face REACH documentation mandates for material traceability, while hardware components must satisfy EU F-Gas Regulation phase-down requirements for fluorinated gas containment. Controllers and sensors carry additional CE marking obligations for electromagnetic compatibility in European chemical clusters.
- Software:Model predictive control algorithms and dynamic optimization engines execute multivariable calculations at minute-level frequencies. German chemical complexes in Ludwigshafen and Leverkusen concentrate demand as operators retrofit legacy distributed control systems with regulatory-grade audit trails for ECHA compliance.
- Controllers:Embedded industrial-grade FPGAs and programmable logic controllers manage real-time setpoint adjustments. Oil and gas refineries in Houston attach these units to existing DCS infrastructure, though 52-week semiconductor lead times constrain hardware shipments and extend project timelines.
- Sensors:Online analyzers and laboratory assay interfaces provide closed-loop feedback for quality control.
- Hardware:Edge devices and gateway infrastructure bridge proprietary communication protocols.
Software sits at the top of the volume ranking, with controllers climbing the fastest as latency-sensitive applications migrate computation toward field devices.
Technology:
Cost tier differentiation separates capital-intensive first-principles modeling from subscription-based machine learning deployments, with neural network surrogates commanding premium licensing fees for nonlinear process zones.
- Machine Learning:Neural network surrogates displace traditional models in biologics manufacturing and refinery octane blending. Pharmaceutical API producers in Ireland deploy these algorithms for real-time release testing under FDA Process Analytical Technology guidance, compressing model development cycles from months to weeks.
- Neural Networks:Soft sensor architectures predict laboratory-grade measurements where online analyzers fail. US Gulf Coast refineries integrate these predictions into control loops for dynamic optimization of product specifications.
- Statistical Process Control:Shewhart charts and multivariate statistical methods monitor batch consistency.
- Fuzzy Logic:Rule-based inference engines handle qualitative operator heuristics in ill-defined process zones.
Machine learning commands the highest licensing premiums, with neural networks gaining share fastest in pharmaceutical batch operations.
End User:
Application maturity varies sharply across verticals, with oil and gas refining representing established deployments while pharmaceutical biologics manufacturing demands rigorous validation protocols that extend implementation cycles.
- Oil & Gas:Refinery operators deploy real-time optimization platforms for crude unit fractionation and catalytic reforming. North American downstream operators benchmark vendor algorithms against open-source alternatives, unbundling software licenses from long-term service contracts to compete on standalone performance.
- Pharmaceuticals:Biologics manufacturers require automated batch records linking raw material lots to finished product certificates of analysis. Belgian and Irish API producers retrofit validation protocols to satisfy ECHA documentation demands under REACH substance restriction proposals.
- Chemical Processing:German chemical clusters integrate leak-detection-integrated APC systems for F-Gas compliance.
- Food & Beverage:Pasteurization and fermentation control applications prioritize cost-effective standardized solutions.
Oil and gas retains the largest installed base, with pharmaceuticals expanding most quickly as PAT guidance mandates real-time quality assurance.
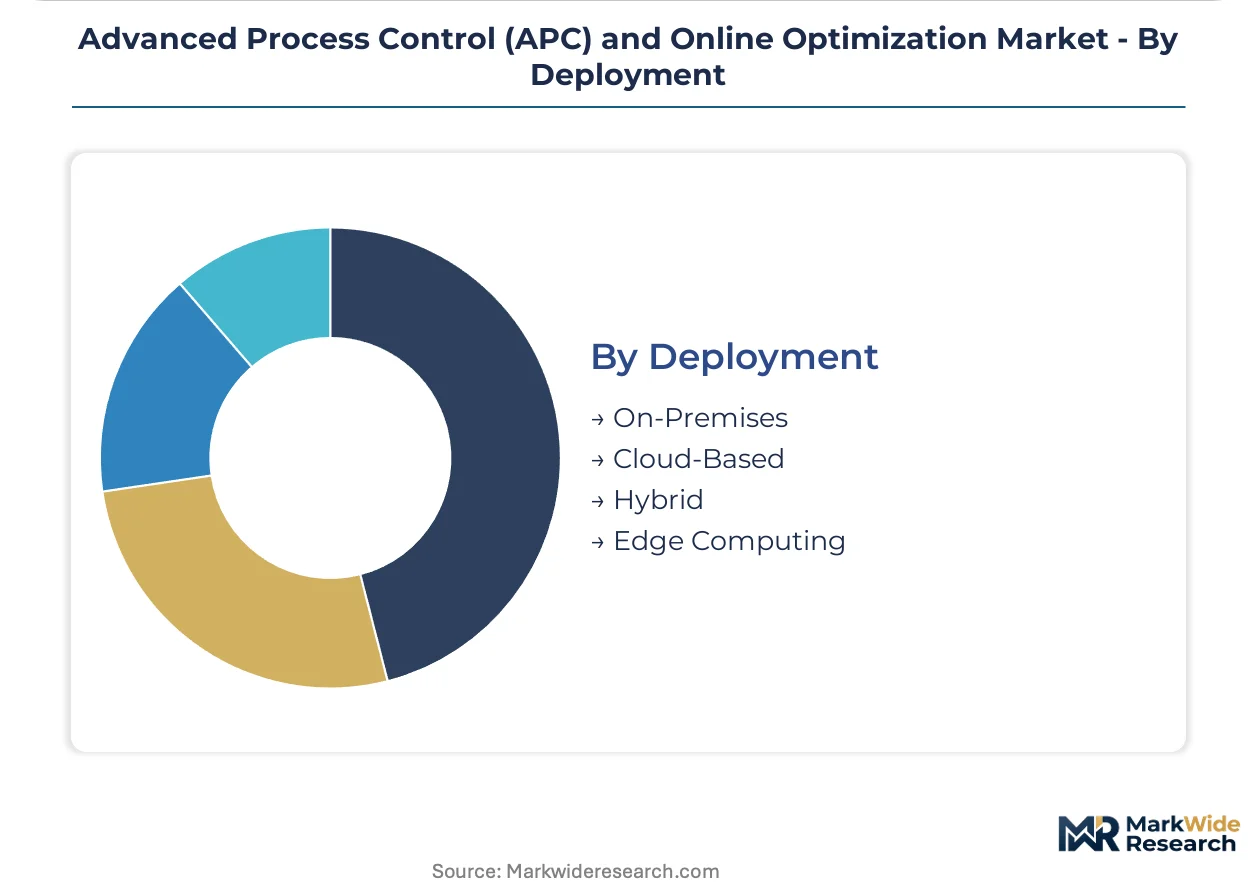
Deployment:
Customer type segmentation separates asset-heavy integrated operators with captive engineering resources from mid-scale specialty producers seeking operational expenditure flexibility through subscription models.
- Edge Computing:Latency-sensitive refining applications migrate computation to field devices, reducing round-trip delays for emergency shutdown systems. Controller hardware attach rates expand as vendors re-architect optimization engines for distributed architectures.
- Cloud-Based:SaaS-based MPC licensing shifts capital expenditure to operational budgets, lowering barriers for mid-scale specialty chemical producers. Cross-border data residency requirements complicate adoption as Germany's BSI, France's CNIL, and India's CERT-In impose divergent industrial data governance frameworks.
- On-Premises:Air-gapped installations satisfy cybersecurity requirements in critical infrastructure.
- Hybrid:Split architectures balance sensitive control loops on-premises with optimization workloads in cloud environments.
Edge computing leads deployment growth, with cloud-based solutions steepest in expansion trajectory among specialty chemical producers seeking budget flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migrates toward jurisdictions where emissions compliance costs diverge, with German chemical operators absorbing F-Gas phase-down investments while Gulf Coast refiners exploit regulatory arbitrage in carbon pricing gaps.
Germany
Ludwigshafen and Leverkusen anchor European APC deployment as BASF and Covestro retrofit legacy distributed control systems. REACH substance restrictions mandate automated batch records linking raw material lots to certificates of analysis. Chemical clusters along the Rhine integrate leak-detection-integrated APC systems to satisfy EU F-Gas Regulation phase-down timelines.
United States
Houston refineries benchmark vendor algorithms against open-source alternatives, unbundling software licenses from service contracts. EPA emissions monitoring requirements expand online optimization infrastructure across Texas and Louisiana petrochemical corridors. The US Gulf Coast deploys neural network soft sensors for octane blending optimization where online analyzers fail.
India
Production-linked incentives for bulk drugs attract APC investment to Dahej and Visakhapatnam manufacturing corridors. CDSCO Process Analytical Technology guidance drives real-time release testing adoption in biologics manufacturing. Specialty chemical producers in Gujarat adopt subscription-based MPC licensing to shift capital expenditure to operational budgets.
China
Yangtze River Delta refineries deploy edge computing architectures to reduce latency for emergency shutdown systems. Dual carbon goals tighten emissions benchmarks that APC systems must document through automated data historians. Petrochemical complexes in Shandong integrate machine learning surrogates for nonlinear catalytic process zones.
Saudi Arabia
Eastern Province refining capacity expands real-time optimization platforms for crude unit fractionation and catalytic reforming. National industrial diversification programs mandate technology transfer agreements for advanced control system deployments. Jubail industrial city attracts vendor engineering centers to service regional downstream operators.
Advanced Process Control (APC) and Online Optimization Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated automation conglomerates commanding premium pricing in refinery deployments while software-focused vendors capture recurring revenue in pharmaceutical batch operations. The vendor landscape organizes around three archetypes: diversified industrial conglomerates with captive hardware-software stacks, specialized optimization software developers, and regional system integrators with vertical industry expertise. Competitive moves concentrate on strategic partnerships for carbon capture integration and subscription licensing model transitions that shift customer procurement from capital to operational expenditure.
Among diversified industrial conglomerates, Siemens AG and Honeywell International Inc. anchor the premium-tier vector through long-term service contracts tied to installed automation bases. Aspen Technology Inc. exemplifies the specialized software archetype, occupying a position where rigorous optimization algorithms command licensing premiums in validated pharmaceutical environments. These three entities represent distinct competitive postures: hardware-software integration at scale, standalone algorithmic performance, and vertical application depth.
| Leading Market Players |
|---|
| Siemens AG |
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| Schneider Electric SE |
| Yokogawa Electric Corporation |
| Emerson Electric Co. |
| ABB Ltd. |
| General Electric Company |
| Aspen Technology Inc. |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up automation specialists concentrate controller hardware manufacturing in German industrial corridors, tightening pricing discipline through captive service bundling while subscription-based MPC licensing shifts procurement toward operational expenditure models.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for edge computing hardware as domestic FPGA production expands. Three-tier pricing structure across premium, standard, and economy levels separates Siemens AG's long-term service contracts from mid-tier Rockwell deployments and economy-focused regional integrators. Price differentiation rests on certification grade and vertical integration depth, with CE-marked controllers commanding premiums for REACH compliance. Cost compression in standard-tier hardware is intensifying because 52-week semiconductor lead times constrain shipments. Mid-scale specialty chemical producers exhibit highest price sensitivity, while integrated refiners prioritize performance over procurement cost.
Supply Chain Analysis
Control engineer scarcity in Ludwigshafen and Houston concentrates implementation capacity around these clusters, extending project timelines for multivariable MPC deployments. Manufacturing draws from Germany, the United States, and Japan for industrial-grade FPGAs, programmable logic controllers, and precision sensors. Raw material dependencies include silicon wafers, rare earth magnets, and fluorinated gas containment systems for leak-detection-integrated units. Single-source vulnerability in semiconductor fabrication creates supply chain risk for controller hardware shipments. Distribution runs through authorized system integrators and direct OEM channels to refinery operators and pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Advanced Process Control and Online Optimization Market functions as a stable compounder, with regulatory mandates for emissions monitoring and batch record traceability generating recurring infrastructure investment cycles across process industries.
For Market Incumbents: Anchor long-term service contracts through predictive maintenance capabilities that lock in pharmaceutical API producers facing ECHA documentation demands. Deepen backward integration into edge computing hardware to offset semiconductor supply volatility. Defend against open-source algorithm benchmarking by embedding proprietary optimization engines within validated DCS infrastructures that block seamless substitution.
For New Entrants and Emerging Players: Begin with SaaS-based MPC licensing for India's specialty chemical corridors, where PLI scheme incentives attract production capacity but automation penetration remains uneven. Target carbon capture integration projects as greenfield deployments lack incumbent legacy lock-in. Pursue partnership-based go-to-market models with regional system integrators possessing vertical expertise in biologics manufacturing.
For Investors and Strategic Acquirers: Industrial automation conglomerates are the most active acquirer in this space, seeking algorithmic capabilities to complement captive hardware-software stacks. Five-to-ten year viability hinges on machine learning surrogate development for nonlinear process zones. Monitor CDSCO PAT guidance enforcement in Indian biologics manufacturing as inflection indicator for real-time release testing demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Surrogate Development | Neural network algorithms displace first-principles models in refinery octane blending optimization. |
| Carbon Capture Integration Partnership | Amine-based post-combustion capture units require dynamic solvent regeneration cycle optimization. |
| Subscription Licensing Model Transition | SaaS-based MPC shifts capital expenditure to operational budgets for mid-scale chemical producers. |
| Edge Computing Architecture Deployment | Latency-sensitive refining applications migrate computation to field devices for emergency shutdown systems. |
| Regulatory Compliance Certification Investment | CE marking and REACH audit trail capabilities differentiate vendors in European chemical clusters. |
Study Parameters
Bottom-up refinery and pharmaceutical modeling reconciled against top-down automation vendor tracking forms the analytical core of this study. Primary interviews with plant managers, control engineers, procurement leads at downstream operators, and technical R&D directors combined with secondary validation against SEC 10-K filings, customs and trade data, ACC and Cefic industry reports, and EPA emissions compliance disclosures. Triangulation between stakeholder perspectives and documented infrastructure investments ensures statistical integrity across segmentation dimensions.
Input-output matrices map software licensing volumes, controller hardware shipments, and service contract values against process industry capital expenditure cycles across the analysis window. Segmentation modeling incorporates deployment architecture, end-use vertical, technology tier, and regional regulatory cluster as structural dimensions. CAGRs derive from fitted growth curves reconciled against historical adoption patterns in oil and gas refining and pharmaceutical batch operations. Forecast inputs include F-Gas Regulation phase-down timelines and CDSCO PAT guidance enforcement trajectories.
Several conditions sit outside the modeled scope, including geopolitical disruptions to semiconductor supply chains and unanticipated regulatory reversals in emissions monitoring mandates. Forecasts reflect assumptions about continued chemical and petroleum facility capital investment and stable cloud data governance frameworks. Practitioners should monitor FPGA lead time normalization and REACH substance restriction proposal finalization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Transit Station Display Board Market
Digital Solutions
Messaging Platform Market
Digital Solutions
Computer Aided Design (CAD) Market
Digital Solutions
Price Optimization and Management Software Market
Digital Solutions
Electronic Contract Manufacturing and Design Services Market
Digital Solutions
Product Lifecycle Management Consumer Packaged Goods and Retail (PLM Cpandr) Market
Digital Solutions
Application Performance Management Market
Digital Solutions
Global Referral Management Market
Digital Solutions
India Engineering Research and Development (ER&D) Services Market
Digital Solutions
North America Everything As a Service (Xaas) Market
Digital Solutions
Online Recruitment Market
Digital Solutions
Real-Time Temperature and Location Monitoring Platforms for Cold Chain Market
Digital Solutions
Global Industrial Design Market
Digital Solutions
Global Enterprise Information Archiving Market
Digital Solutions
Qatar ICT Market
Digital Solutions
Anticipatory Commerce Infrastructure Market