
 Cloud MFT Services Market | 2026-2036
Cloud MFT Services Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud MFT Services Market Analysis
Healthcare's share of cloud MFT consumption is broadening as hospitals and insurers replace legacy FTP with encrypted, auditable pipelines for PHI exchange. IBM Sterling anchors enterprise-grade deployments through its Sterling File Gateway and B2B integration stack. Kiteworks competes on content-defined networking, sustaining differentiation via FedRAMP and ISO 27001 certifications that govern sensitive-sector procurement.
Cloud MFT services orchestrate the secure, automated exchange of structured and unstructured data between organizations, employing protocols such as AS2, AS4, SFTP, and HTTPS with AES-256 encryption at rest and in transit to guarantee integrity, non-repudiation, and regulatory traceability. These platforms serve as critical infrastructure for supply chain synchronization, financial settlement flows, and inter-agency document exchange where latency, compliance, and auditability carry operational weight. Hybrid cloud deployment models are capturing the fastest expansion as enterprises retain on-premises control for regulated workloads while bursting peak volumes to public infrastructure. Secure file sharing solutions concentrate margin pools in BFSI and government verticals where encryption key escrow and granular access policies command pricing premiums over commoditized transfer automation.
FDA 21 CFR Part 11 and HIPAA shape healthcare demand by mandating electronic signature validity and access logging, while the EU GDPR and NIS2 Directive impose breach-notification timelines and processor accountability that elevate managed service provider liability. FERC's CIP standards for North American utilities further segment the addressable market by requiring segmented network architectures for bulk electric system data. Stakeholders must weigh sovereign data residency requirements against multi-cloud redundancy architectures as jurisdictional fragmentation hardens.
Market Dynamics
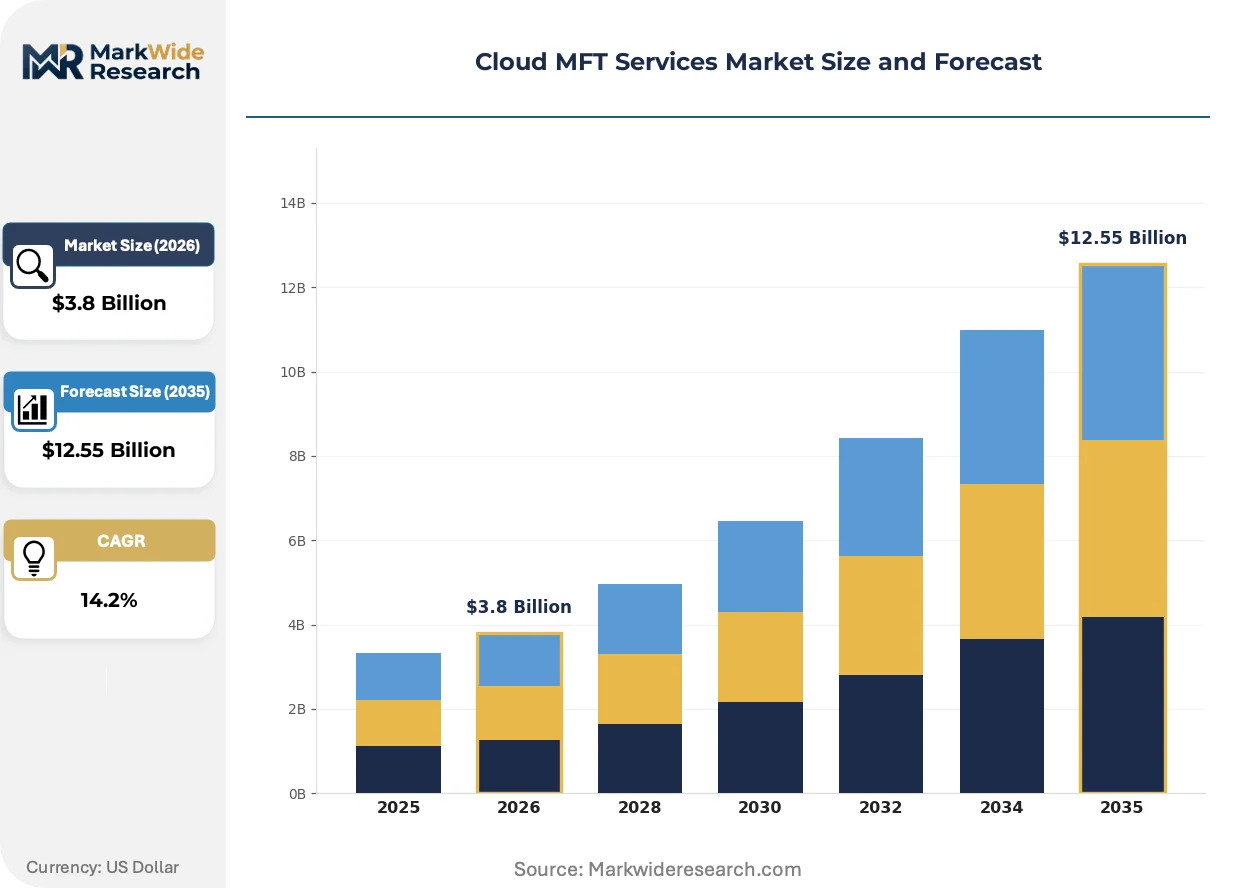
Hybrid cloud deployment architectures are compressing traditional on-premises MFT estates as enterprises seek burst capacity for peak data volumes without surrendering sovereignty over regulated workloads.
Growth Catalysts
- HIPAA-mandated audit trails:US healthcare providers are retiring FTP infrastructure in favor of encrypted, logged pipelines for PHI exchange, expanding addressable consumption within hospitals and insurers.
- EU AI Act cross-border governance:Automated file orchestration platforms with embedded data lineage capabilities are capturing procurement preference as enterprises pre-validate AI training data provenance.
- German automotive supply chains:Tier-1 suppliers in Stuttgart and Wolfsburg are consolidating vendor count for secure EDI and engineering file exchange, concentrating volume with certified cloud MFT providers.
Market Restraints
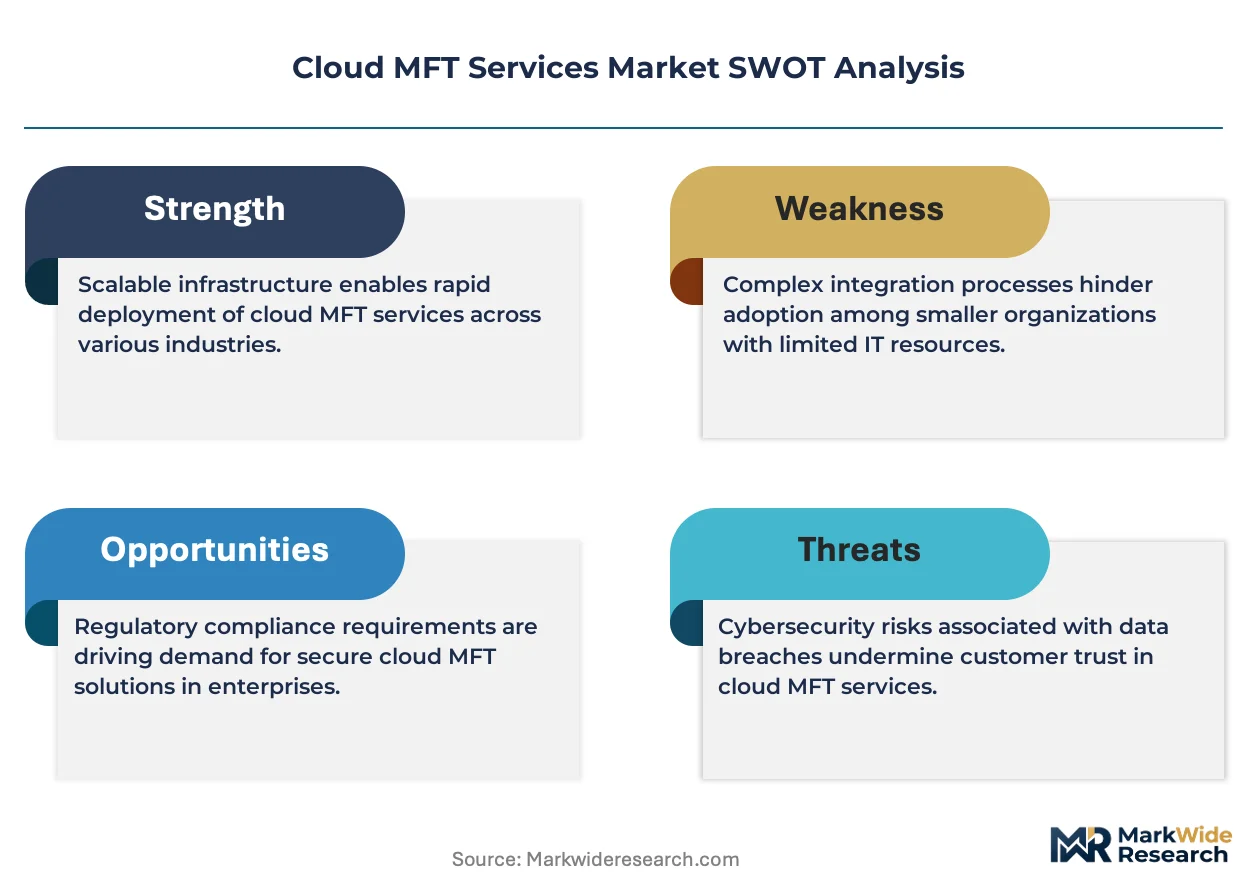
- Sovereign data residency mandates:Fragmented jurisdictional requirements across EU member states, Switzerland, and post-Brexit UK are forcing redundant infrastructure deployment, elevating operational cost bases.
- Skilled security architect scarcity:Shortage of practitioners certified in AES-256 key management and zero-trust segmentation is extending implementation timelines and inflating professional services dependency.
- Legacy protocol persistence:AS2 and SFTP infrastructure sunk costs in financial services are retarding migration velocity despite superior API-native alternatives.
Strategic Opportunities
- India's PLI scheme manufacturing digitization:Electronics and pharmaceutical contract manufacturers under production-linked incentive programs require auditable file exchange with foreign OEMs, creating greenfield demand.
- API-SFTP convergence:Hybrid architectures bridging synchronous REST interfaces with asynchronous batch transfers are opening wedge into cloud-native fintech stacks previously closed to traditional MFT.
- FERC CIP-013 supply chain standards:North American electric utilities facing mandatory vendor risk management are outsourcing file exchange governance to managed service providers with pre-certified segmentation architectures.
Industry Challenges
- FedRAMP authorization timelines:US federal sales cycles extend 18-24 months due to assessor backlog and control documentation requirements, compressing revenue recognition windows.
- ISO 27001 surveillance audit burden:Annual certification maintenance across multiple geographic scopes consumes product engineering resources that would otherwise advance platform differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud MFT Services Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Service Type: File Transfer Automation, Secure File Sharing, Large File Transfer, Managed File Transfer End User: Healthcare, Retail, BFSI, Government Solution: Transfer Protocols, Encryption, Compliance Management, Reporting |
| Companies Covered | Coviant Diplomat, MOVEit, Kiteworks, MASV, IBM Sterling, Cleo Integration Cloud, GoAnywhere, Aspera, Globalscape EFT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud MFT Services Market Emerging Trajectories
Zero-trust network architectures are electrifying competitive positioning as perimeter-based security models lose procurement viability in regulated verticals.
Confidential computing enclaves are electrifying data-in-use protection for cloud MFT workloads. Pharmaceutical manufacturers evaluating multi-party computation for clinical trial data exchange are piloting Intel SGX and AMD SEV-based pipelines. This hardware-rooted isolation is electrifying the displacement of traditional encryption-at-rest as the sole compliance checkbox, compressing vendor evaluation criteria toward attestation capabilities.
The EU NIS2 Directive's supply chain security mandates are forcing managed service providers to document subprocessor risk registers and incident response playbooks. Critical infrastructure operators in energy and transport must now validate file exchange partners' cybersecurity postures contractually. German chemical conglomerates and French water utilities are consolidating vendor panels to reduce due diligence overhead, favoring providers with pre-mapped NIS2 control mappings.
Consumption-based metering is displacing perpetual licensing in enterprise procurement. Financial services buyers in London and Singapore are negotiating transaction-volume tiers with burst allowances rather than capacity reservations. This shift compresses upfront commitment sizes while extending contract durations, altering cash flow profiles for platform vendors and forcing pricing discipline on marginal cost estimation.
Cloud MFT Services Market Segmentation
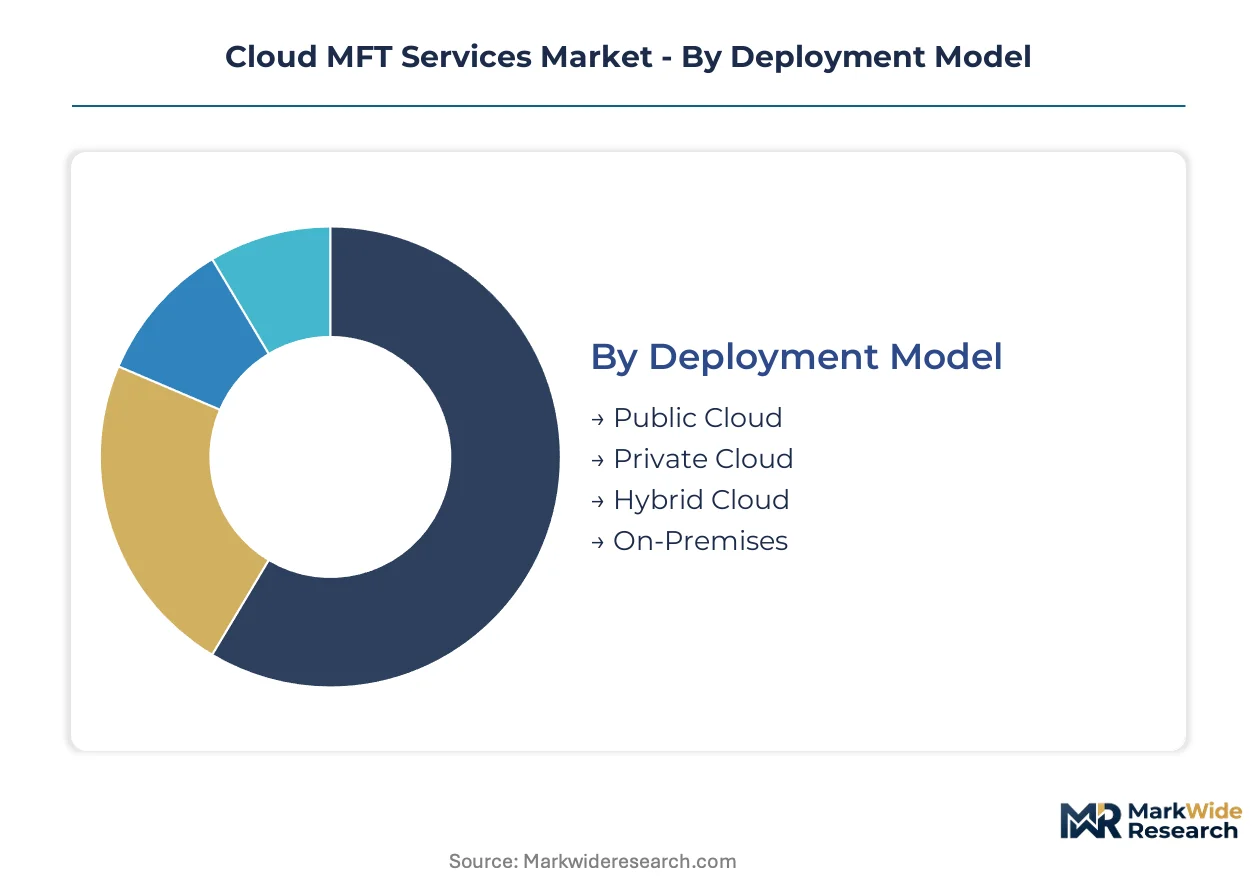
Cloud MFT services fragment across deployment architecture, service modality, and regulatory exposure. Buyers select configurations based on data sovereignty requirements, transaction velocity needs, and audit burden tolerance. Each segmentation axis carries distinct margin profiles and implementation complexity.
Deployment Model:
Cost tier separates buyers in this category — enterprises with heavy compliance overhead pay premiums for control, while digital-native firms prioritize elasticity over sovereignty.
- Hybrid Cloud:Architectures split regulated workloads across on-premises infrastructure and burst capacity to public clouds. German automotive manufacturers and US healthcare providers favor this model for PHI and engineering file exchange where GDPR and HIPAA mandate residency controls.
- Private Cloud:Dedicated tenant environments deliver single-tenant isolation with managed infrastructure overhead. French water utilities and Swiss pharmaceutical manufacturers specify private deployments for NIS2-critical infrastructure and clinical trial data.
- Public Cloud:Multi-tenant SaaS delivery minimizes capital commitment and accelerates time-to-value. Fintech startups in Singapore and London procurement desks select public tiers for non-regulated batch orchestration.
- On-Premises:Customer-managed infrastructure persists in North American electric utilities subject to FERC CIP segmentation mandates and legacy AS2 protocol dependencies.
Volume sits with hybrid architectures; growth tilts toward private cloud as NIS2 and EU AI Act harden processor accountability.
Service Type:
Application criticality drives selection — synchronous transaction settlement demands different reliability engineering than asynchronous bulk document distribution.
- Managed File Transfer:Comprehensive platforms orchestrate protocol translation, encryption lifecycle, and audit logging through centralized policy engines. BFSI settlement flows and healthcare claims processing concentrate demand here.
- Secure File Sharing:Collaboration-centric services emphasize granular access policies and encryption key escrow for external partner engagement. Legal advisory and board document exchange in London and New York anchor consumption.
- File Transfer Automation:Event-triggered pipelines eliminate manual intervention for recurring batch operations. Retail supply chain synchronization and manufacturing EDI represent core use cases.
- Large File Transfer:Accelerated protocols optimize for media, genomic, and CAD/CAM payloads exceeding standard transfer thresholds. Life sciences research consortia and Hollywood post-production facilities specify these capabilities.
Revenue concentrates in managed file transfer; secure file sharing expands most quickly as external collaboration governance tightens.
End User:
Margin structure varies sharply by vertical — regulated sectors accept higher per-transaction costs in exchange for pre-certified compliance architectures.
- BFSI:Settlement systems, regulatory reporting, and correspondent banking relationships demand sub-second latency with immutable audit trails. Tier-1 institutions in Frankfurt and Zurich drive premium pricing.
- Healthcare:HIPAA-mandated PHI exchange and FDA 21 CFR Part 11 electronic signatures shape procurement criteria. US hospital systems and insurers are retiring FTP infrastructure for encrypted, logged pipelines.
- Government:FedRAMP authorization and classified information handling requirements extend sales cycles. Federal civilian and defense agencies specify pre-certified managed service providers.
- Retail:Omnichannel inventory synchronization and supplier onboarding prioritize cost efficiency over advanced security features. Private label manufacturers and franchise networks represent volume buyers.
Transaction volume sits with BFSI; healthcare climbs the fastest as HIPAA enforcement tightens and hospital digitization accelerates.
Solution:
Technology maturity separates buyers — early adopters specify embedded compliance automation while laggards prioritize protocol compatibility.
- Compliance Management:Embedded policy engines automate GDPR breach notification, HIPAA access logging, and SOX audit preparation. Financial services and healthcare procurement mandates favor these integrated capabilities.
- Encryption:AES-256 at rest and in transit remains table stakes; differentiation shifts toward confidential computing enclaves and hardware security module integration. Pharmaceutical manufacturers piloting multi-party computation specify these advanced protections.
- Transfer Protocols:AS2, AS4, SFTP, and HTTPS interoperability ensures legacy system connectivity. Financial services retain AS2 infrastructure despite API-native alternatives.
- Reporting:Dashboard and analytics modules deliver operational visibility and forensic reconstruction for incident response. Regulated verticals specify these capabilities for regulator examination readiness.
Deployment breadth sits with transfer protocols; compliance management gains share fastest as EU AI Act and NIS2 documentation requirements intensify.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud MFT consumption concentrates in economies with dense B2B transaction volumes and stringent data governance regimes. Supply-side platform development clusters in technology hubs with deep cybersecurity talent pools.
United States
HIPAA-mandated PHI exchange and FERC CIP standards for electric utilities drive procurement of encrypted, auditable file pipelines. FDA 21 CFR Part 11 shapes pharmaceutical manufacturer requirements for electronic signatures and access logging. Hospital systems in Boston and insurers in Hartford are retiring legacy FTP infrastructure for managed service deployments.
Germany
Industrial automation and automotive supply chains require secure EDI orchestration between OEMs and tiered suppliers. EU AI Act cross-border governance mandates embedded data lineage for AI training data provenance. Stuttgart and Wolfsburg manufacturing clusters are consolidating vendor panels for engineering file exchange and supplier onboarding.
United Kingdom
Post-Brexit data adequacy arrangements and GDPR residual obligations complicate cross-border file routing for financial services. FCA regulatory reporting requirements enforce immutable audit trails for settlement flows. London-based investment banks and insurance underwriters specify FedRAMP-equivalent certifications for cloud MFT procurement.
India
PLI scheme manufacturing digitization creates greenfield demand for auditable file exchange between contract manufacturers and foreign OEMs. RBI data localization guidelines constrain cross-border data flows for financial services. Electronics and pharmaceutical clusters in Bengaluru and Hyderabad are deploying cloud-native transfer automation for supply chain synchronization.
Japan
METI cybersecurity frameworks and sector-specific guidelines elevate managed service provider accountability for critical infrastructure data exchange. Pharmaceutical manufacturers piloting multi-party computation for clinical trial data specify hardware-rooted isolation. Tokyo and Osaka-based financial institutions prioritize sub-second latency with immutable audit trails for settlement systems.
Cloud MFT Services Market Vendor Landscape
Top-tier vendors anchor enterprise-grade deployments with pre-certified compliance architectures, while mid-tier specialists compete on vertical-specific protocol support and regional data residency. The vendor base stratifies across three tiers: global platforms with multi-cloud sovereignty, regional specialists with deep local certification expertise, and protocol-specific tools for legacy system integration. Dominant competitive moves include geographic expansion through local data center deployment and portfolio diversification into adjacent API management and data integration categories.
Within the enterprise platform tier, IBM Sterling and Kiteworks exemplify divergent positioning strategies. IBM Sterling anchors deployments through B2B integration stacks and Sterling File Gateway infrastructure. Kiteworks occupies a position defined by content-defined networking and FedRAMP certification concentration. MOVEit represents the mid-market specialist archetype with focused secure transfer automation capabilities.
| Leading Market Players |
|---|
| Coviant Diplomat |
| MOVEit |
| Kiteworks |
| MASV |
| IBM Sterling |
| Cleo Integration Cloud |
| GoAnywhere |
| Aspera |
| Globalscape EFT |
| Others |
Supply Flow & Price Mechanics
FedRAMP authorization timelines and ISO 27001 surveillance audit burdens gate qualified supply for premium-tier cloud MFT services, concentrating pricing power with pre-certified providers while elevating operational cost bases for market access. Healthcare providers and federal agencies demand these certifications as non-negotiable procurement criteria, compressing vendor panels and sustaining margin premiums for compliant architectures.
Pricing Analysis
Margin tightening in public cloud tiers reflects hyperscaler infrastructure commoditization and consumption-based metering displacement of perpetual licensing. Pricing stratifies across FedRAMP-authorized premium deployments, ISO 27001-certified standard tiers, and uncertified economy SaaS offerings. Cost-down pressure accelerates in retail and non-regulated segments as buyers negotiate transaction-volume tiers with burst allowances. Financial services institutions in Frankfurt and Zurich exhibit least price sensitivity, prioritizing sub-second latency and immutable audit trails over per-transaction economics.
Supply Chain Analysis
FedRAMP and ISO 27001 certifications gate supply chain participation, filtering platform vendors and managed service providers through 18-24 month authorization cycles. Infrastructure supply concentrates in the United States, Germany, and India, with hyperscaler regions in Virginia, Frankfurt, and Mumbai anchoring data residency-compliant deployments. Raw material dependencies span Intel SGX and AMD SEV confidential computing hardware, AES-256 encryption modules, and zero-trust segmentation software stacks. Single-source vulnerability in assessor capacity extends certification timelines. Distribution runs through direct enterprise sales, hyperscaler marketplaces, and systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FedRAMP assessor backlog creates a supply-constrained certification pipeline, propping pricing premiums for pre-authorized providers and extending competitive moats beyond pure technology differentiation.
For Market Incumbents: Hedge against API-native fintech disruption by embedding synchronous REST interfaces alongside legacy AS2 and SFTP protocol support. Acquire confidential computing enclave capabilities through hardware security module integration to defend pharmaceutical manufacturer segments piloting multi-party computation. Extend geographic footprint through local data center deployment in India's PLI scheme manufacturing clusters. For New Entrants and Emerging Players: Launch via API-SFTP hybrid architectures targeting cloud-native fintech stacks in Singapore and London previously closed to traditional MFT. Concentrate on India's electronics and pharmaceutical contract manufacturers requiring auditable file exchange with foreign OEMs. Pursue vertical-specific NIS2 control mappings for German chemical conglomerates consolidating vendor panels. For Investors and Strategic Acquirers: FedRAMP authorization receipt is the leading indicator that a cloud MFT provider has crossed the procurement viability threshold for federal civilian and defense agency segments. Target mid-market specialists with focused secure transfer automation capabilities and established ISO 27001 certification maintenance across multiple geographic scopes. Monitor EU AI Act cross-border governance implementation as the signal for embedded data lineage platform valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Compresses 18-24 month sales cycles for federal agency procurement viability. |
| Confidential Computing Integration | Captures pharmaceutical manufacturer demand for hardware-rooted clinical trial data isolation. |
| API-SFTP Hybrid Architecture Development | Opens wedge into cloud-native fintech stacks resistant to legacy protocol migration. |
| NIS2 Control Mapping Pre-Certification | Reduces due diligence overhead for German chemical and French utility vendor consolidation. |
| India Data Center Localization | Satisfies RBI data localization guidelines for electronics and pharmaceutical PLI scheme manufacturers. |
Methodological Framework
SEC filings, hyperscaler capex disclosures, and FedRAMP authorized product listings formed the secondary backbone, combined with primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across BFSI, healthcare, and government verticals. Bottom-up segmentation modeling triangulated against top-down market sizing derived from enterprise software spend analysis and managed service provider revenue disclosures.
Historical trendline analysis established baseline growth patterns across deployment architecture, service modality, and regulatory exposure dimensions. The analytical framework modeled consumption shifts over the projection horizon, with CAGRs derived from segment-level elasticity estimates and technology substitution curves. Forecast inputs incorporated HIPAA enforcement intensity, EU AI Act implementation velocity, and FERC CIP-013 supply chain standard adoption rates among North American electric utilities.
Regulatory enforcement variance, assessor capacity constraints, and hyperscaler pricing volatility are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context and certification timeline requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Ad Tech Software Market
Digital Solutions
Graphical Situational Display Market
Digital Solutions
Landing Page Builders Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Agriculture Software Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
Service Mesh Market
Digital Solutions
OSS/BSS Market
Digital Solutions
IT Asset Management Solutions (ITAM) Market
Digital Solutions
Cloud Project Portfolio Management (CPPM) Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Desktop Virtualization in Manufacturing Market
Digital Solutions
Cloud Based Simulation Application Market
Digital Solutions
US Supply Chain Management Software Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Interactive Projector Market