
 Location-Based Services (LBS) Market | 2026-2036
Location-Based Services (LBS) Market Size, Share, and Industry Trends Forecast 2026-2036
Location-Based Services (LBS) Market Intelligence
The ISO/IEC 19762-5 standard for harmonized location-based services vocabulary is rotating market access toward platforms that ensure interoperability and data consistency. Google LLC leverages its dominant Android and Maps ecosystems to integrate LBS across consumer and enterprise applications. HERE Technologies specializes in high-definition mapping and location data for the automotive and logistics sectors. Qualcomm Technologies Inc. embeds advanced positioning capabilities directly into its mobile chipsets, controlling a critical hardware layer.
Location-based services (LBS) are information and entertainment services accessible with mobile devices through the mobile network, utilizing the ability to make use of the geographical position of the device. These services rely on technologies like GPS, which provides positioning accuracy often within five meters, to deliver context-aware information. The navigation and mapping service type remains the foundational segment, while location analytics represents the fastest-growing category. Among applications, fleet management and retail marketing are mature, high-volume sectors.
Privacy regulations are a primary force shaping LBS development, with the EU's GDPR and California's CCPA setting global precedents for user consent and data handling. In parallel, bodies like the US Federal Communications Commission (FCC) regulate E911 location accuracy requirements for mobile carriers. Navigating the fragmented landscape of data privacy laws while improving positioning accuracy for indoor environments remains the central challenge for service providers.
Market Dynamics
The proliferation of location-aware applications in sectors from retail to logistics creates intense demand for higher precision. This demand directly conflicts with a tightening global privacy regime, led by regulations like the EU's GDPR, forcing a difficult trade-off for service providers.
Growth Catalysts
- 5G Network Proliferation:The rollout of 5G infrastructure enables low-latency LBS applications, including connected vehicle services and augmented reality navigation, which require constant data exchange.
- Smart City Mandates:Government-led projects in China and Singapore integrate LBS for traffic management and public safety, creating systemic demand for location intelligence platforms.
- Retail Sector Integration:The retail industry's use of geofencing and indoor positioning for personalized marketing drives adoption.
Market Restraints
- Fragmented Privacy Regulations:The complex nature of data privacy laws, like the EU's GDPR and California's CCPA, increases compliance costs and legal risks for global providers.
- Indoor Positioning Inaccuracy:GPS signal unreliability indoors remains a technical barrier, limiting LBS effectiveness for in-building navigation, asset tracking, and emergency services.
- Infrastructure Cost:High capital expenditure for satellite constellations and ground stations creates a significant barrier to entry for new market participants.
Strategic Opportunities
- Emerging Economies:Rapid smartphone penetration in Southeast Asia and Latin America creates opportunities for consumer LBS applications like mobile payments and local search.
- Autonomous Systems Integration:Providing high-definition, real-time mapping for autonomous vehicles and industrial robots is a high-value opportunity for specialized providers.
- Advanced Location Analytics:Developing platforms that turn raw location data into business intelligence for urban planning and supply chain optimization is a key growth area.
Industry Challenges
- Data Harmonization:Ensuring data consistency and interoperability between different LBS platforms and data sources, guided by standards like ISO/IEC 19762-5, remains a complex technical challenge for developers.
- Legacy System Integration:Integrating modern LBS capabilities with entrenched enterprise systems, such as older fleet management or CRM platforms, is often costly and technically complex, slowing adoption rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Location-Based Services (LBS) Market |
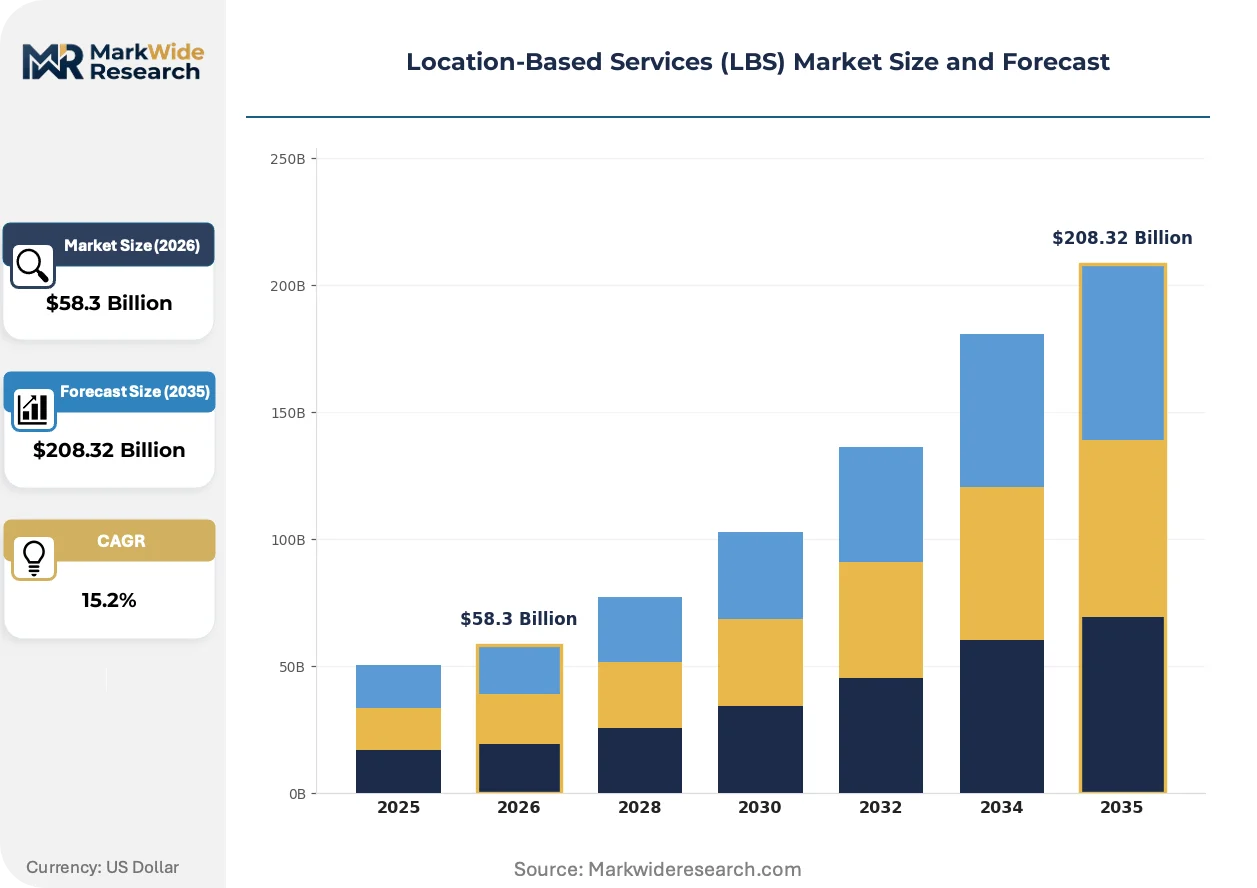
| Market Size in 2026 | $58.3 Billion |
| Market Size in 2035 | $208.32 Billion |
| CAGR (2026 – 2036) | 15.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Real-Time Tracking, Navigation & Mapping, Location Analytics, Emergency Response, Asset Management Technology: GPS, Wi-Fi Positioning, Cellular Network, Bluetooth Beacons, RFID Application: Fleet Management, Urban Planning, Tourism, Retail Marketing, Disaster Management End User: Telecommunications, Public Safety Agencies, Transportation Providers, Marketing Firms, Government Authorities |
| Companies Covered | Google LLC, Apple Inc., Microsoft Corporation, IBM Corporation, Cisco Systems Inc., HERE Technologies, Oracle Corporation, Qualcomm Technologies Inc., Zebra Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Location-Based Services (LBS) Market Strategic Shifts & Innovations
A push toward ambient location awareness is reshaping the market, where services become an invisible, integrated layer within broader applications. This shift is driven by hardware miniaturization, evolving privacy frameworks, and new enterprise consumption models that demand seamless integration.
Next-generation Global Navigation Satellite System (GNSS) chipsets provide multi-band frequency support for improved accuracy and resilience. The automotive and mobile device sectors are rapidly adopting these components to enhance navigation and safety features. This trend is miniaturizing the core positioning hardware, enabling its integration into a wider range of smaller IoT devices and wearables.
The US Federal Communications Commission (FCC) enforces stricter E911 location accuracy rules, including vertical z-axis requirements for multi-story buildings. This mandate forces network operators to invest in new positioning technologies and network-based location determination methods. The public safety segment is the primary beneficiary, gaining more precise caller location data.
Enterprises are shifting from purchasing raw location data feeds to subscribing to full-stack location intelligence platforms. This model displaces the need for in-house data science teams to process geospatial information, offering a more accessible, service-based approach. The trend is most visible in logistics and retail for route optimization and site selection.
Location-Based Services (LBS) Market Segmentation
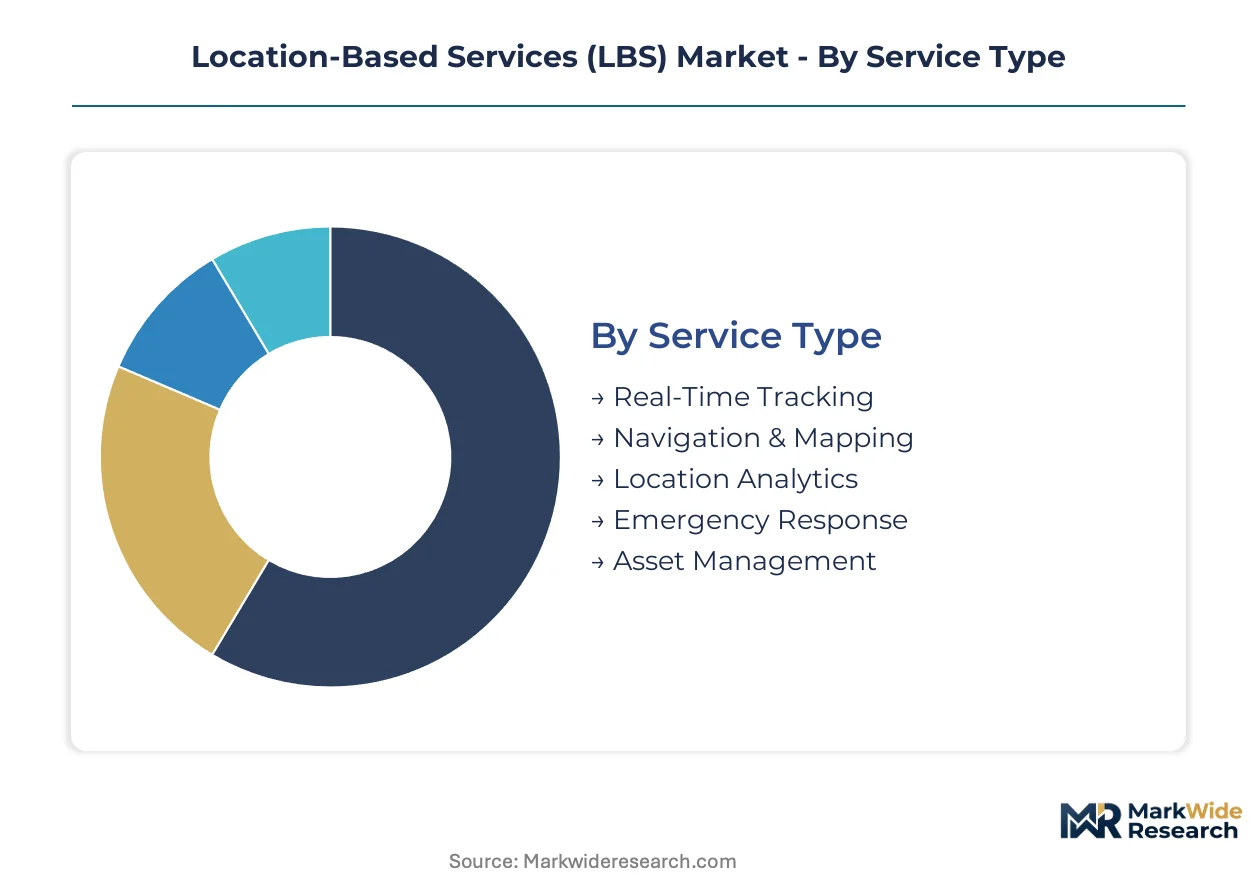
The Location-Based Services (LBS) market is highly differentiated by the nature of the information delivered, the underlying technological infrastructure, specific use cases, and the ultimate consumer of the data. Understanding these segmentations is critical for providers to tailor offerings and navigate diverse regulatory landscapes, such as the EU's GDPR and California's CCPA, which significantly impact data collection across various service types and end-user applications.
Service Type:
The distribution channels for LBS vary significantly by service type, with some flowing directly to consumers via mobile apps and others through enterprise platforms or government mandates.
- Navigation & Mapping:This foundational service type provides real-time route guidance, point-of-interest identification, and geographic visualization. Widespread smartphone penetration and integration into automotive infotainment systems drive demand for accurate, up-to-date mapping data across all major economies.
- Location Analytics:This service transforms raw geospatial data into actionable business intelligence, often through advanced algorithms and visualization tools. Enterprises in logistics and urban planning sectors concentrate demand for these platforms to optimize operations and improve decision-making processes.
- Real-Time Tracking:This segment offers continuous monitoring of mobile assets or individuals, providing immediate positional updates. Logistics companies utilize real-time tracking for supply chain visibility.
- Emergency Response:Services in this category focus on quickly and accurately locating individuals in distress for public safety and disaster relief operations. The US Federal Communications Commission (FCC) mandates specific accuracy for E911 calls.
- Asset Management:This service type enables organizations to monitor and manage the physical location of their valuable assets, often using IoT devices. Industrial and healthcare sectors leverage asset management for operational efficiency.
By volume, Navigation & Mapping leads. By growth pace, Location Analytics is ahead.
Technology:
The maturity and deployment scale of various LBS technologies dictate their market penetration and the types of services they can reliably support, influencing infrastructure investment decisions.
- GPS:Global Positioning System leverages satellite signals to provide precise outdoor positioning data, forming the backbone for most traditional LBS applications. Its ubiquitous integration into mobile chipsets ensures broad availability across consumer devices.
- Wi-Fi Positioning:This technology triangulates a device's location based on nearby Wi-Fi access points, offering improved accuracy in indoor environments where GPS signals are often obstructed. Retailers and venue operators adopt Wi-Fi positioning for indoor navigation and analytics.
- Cellular Network:This method utilizes cell tower triangulation or signal strength to estimate device location, providing a broad coverage area even without GPS. Telecommunication providers integrate cellular network capabilities for emergency services.
- Bluetooth Beacons:Small, low-cost transmitters broadcast signals that devices can detect, enabling highly localized positioning and proximity-based interactions. Retail marketing frequently deploys Bluetooth beacons for personalized promotions.
- RFID:Radio Frequency Identification tags allow for short-range identification and tracking of items, commonly used in inventory management and access control systems. Manufacturing and logistics operations utilize RFID for asset tracking.
GPS technologies maintain the broadest market penetration, while Wi-Fi Positioning tackles critical indoor accuracy challenges.
Application:
Customer demands for LBS applications vary significantly across industries, with each sector prioritizing different attributes such as precision, real-time updates, or data privacy compliance.
- Fleet Management:This application optimizes vehicle routes, monitors driver behavior, and tracks cargo in real-time, crucial for logistics and transportation companies. High-volume commercial fleets adopt LBS for operational efficiency and cost reduction.
- Retail Marketing:This application uses location data for targeted advertisements, personalized promotions, and store traffic analysis, enhancing customer engagement. Geofencing and indoor positioning drive adoption within the retail sector.
- Urban Planning:This application leverages aggregated location data to analyze population movement, traffic patterns, and infrastructure usage for city development and resource allocation. Government authorities in smart cities utilize LBS for informed decision-making.
- Tourism:LBS applications in tourism provide tourists with navigation, local attraction information, and personalized recommendations. Mobile apps for travel and hospitality integrate LBS to enhance visitor experiences.
- Disaster Management:This application assists in coordinating emergency responses, locating affected individuals, and managing resources during natural disasters or crises. Public safety agencies rely on LBS for critical incident management.
Fleet Management represents a high-volume, mature application, whereas Retail Marketing offers significant growth opportunities through personalization.
End User:
Regulatory compliance and specific operational requirements shape the LBS adoption patterns among different end-user segments, from public safety mandates to commercial marketing strategies.
- Public Safety Agencies:These entities utilize LBS for emergency call routing, first responder dispatch, and disaster relief coordination, often driven by regulations like the FCC's E911 mandates. The need for precise location data in critical situations defines their demand profile.
- Telecommunications:This sector provides the foundational network infrastructure for LBS, integrating positioning capabilities directly into mobile networks and devices. Global mobile network operators invest in LBS to enhance service offerings and meet regulatory obligations.
- Transportation Providers:These include logistics companies, ride-sharing services, and public transport operators that rely on LBS for fleet tracking, route optimization, and passenger information systems. The demand for efficiency and real-time visibility drives their LBS investments.
- Marketing Firms:These agencies leverage location data for targeted advertising campaigns, foot traffic analysis, and consumer behavior insights. GDPR and CCPA regulations heavily influence their data collection practices.
- Government Authorities:Beyond public safety, government bodies use LBS for urban planning, resource management, and smart city initiatives. China's smart city projects represent a significant driver for LBS adoption in this segment.
Public Safety Agencies drive LBS innovation due to stringent accuracy requirements, while Telecommunications underpin the broad accessibility of location services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ubiquitous cellular and satellite network infrastructure underwrites the global role of various geographies in the Location-Based Services market. These foundational assets enable the precise positioning and data transfer critical for modern LBS applications. Regulatory frameworks and technological advancements further shape regional market dynamics.
China
China's widespread smartphone penetration generates intense demand for consumer LBS applications and mobile payments. Government-led smart city projects, often under the guidance of the Ministry of Industry and Information Technology (MIIT), integrate LBS for traffic management and public safety. The Yangtze River Delta region exemplifies advanced smart city implementations, driving demand for location intelligence platforms.
United States
The United States market is driven by both robust consumer adoption and enterprise solutions in fleet management and retail marketing. The US Federal Communications Commission (FCC) enforces stringent E911 location accuracy requirements, influencing technology development for mobile carriers. Silicon Valley remains a hub for LBS innovation, with companies developing next-generation positioning and analytics platforms.
Germany
German industry demand concentrates on high-precision LBS for the automotive sector and sophisticated logistics operations. The EU's General Data Protection Regulation (GDPR) mandates strict data privacy standards, influencing LBS development across the European Union. Munich's automotive R&D cluster leverages advanced mapping and location data for autonomous vehicle development.
India
India's rapid smartphone penetration and burgeoning digital economy create opportunities for consumer LBS applications like local search and navigation. The Telecom Regulatory Authority of India (TRAI) oversees mobile network infrastructure, which is crucial for LBS accessibility. Bengaluru's tech startup ecosystem fosters innovation in mobile LBS and location analytics platforms.
Singapore
Singaporean government-led smart nation initiatives create systemic demand for LBS in urban planning and public safety. The city-state's focus on digital transformation and smart infrastructure integrates location intelligence across various public services. Government agencies actively deploy LBS for traffic optimization and emergency response within the urban environment.
Location-Based Services (LBS) Market Key Industry Players
Listed leaders compete with private specialists across technology stack and service offerings within the LBS market. The market exhibits a tiered structure, with large platform providers dominating consumer-facing applications and specialized firms focusing on high-precision data or hardware. Strategic partnerships and targeted mergers and acquisitions remain common competitive moves to expand capabilities and market reach.
Within the platform provider archetype, Google LLC leverages its dominant Android and Maps ecosystems to integrate LBS across consumer and enterprise applications. Specialized data and hardware integrators, such as HERE Technologies and Qualcomm Technologies Inc., occupy critical positions by providing foundational mapping data and advanced positioning capabilities directly into mobile chipsets. These companies anchor specific segments by offering essential components for the broader LBS ecosystem.
| Leading Market Players |
|---|
| Google LLC |
| Apple Inc. |
| Microsoft Corporation |
| IBM Corporation |
| Cisco Systems Inc. |
| HERE Technologies |
| Oracle Corporation |
| Qualcomm Technologies Inc. |
| Zebra Technologies Corporation |
Cost & Logistics Intelligence
Integrated hardware miniaturization and software platform development drive scale economies, shaping both supply concentration and competitive price floors across the Location-Based Services market. This dynamic favors large-scale providers capable of amortizing high R&D and infrastructure costs over broad user bases.
Pricing Analysis
Service complexity and data accuracy create the primary spread in LBS pricing. The dominant pricing model for enterprise solutions is SaaS-tiered, while consumer applications often utilize freemium or subscription models. Price differentiation stems from factors like real-time data refresh rates, geographical coverage, and the level of customization for location analytics platforms. Pricing pressure stems from the increasing commoditization of basic navigation services, particularly in consumer segments. Public safety agencies demonstrate the least price sensitivity due to critical functionality, whereas individual consumers exhibit the highest sensitivity for basic mobile LBS.
Supply Chain Analysis
Just-in-time provisioning dominates the software and data layers of the LBS supply chain, while hardware components rely on strategic stockpiles. Geographic supply concentration for core GNSS chipsets centers on Taiwan and the United States, while high-definition mapping data often originates from Europe and North America. Raw material dependencies include specialized semiconductors and access to satellite constellation infrastructure. Geopolitical risks affecting global satellite access represent a structural supply chain risk. Distribution runs through mobile app stores for consumer services, and direct enterprise sales channels or hardware OEMs for business-to-business applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LBS market incumbents must defend their positions against the growing threat of open-source mapping platforms and privacy-enhanced operating system features. Navigating these substitutes requires continuous innovation in data processing and user experience.
For Market Incumbents:
Consolidate specialized location analytics firms to broaden platform capabilities and intellectual property. Deepen integration with existing enterprise resource planning and customer relationship management systems to create sticky solutions. Invest in advanced indoor positioning R&D to counter technical limitations and meet evolving regulatory requirements like FCC's z-axis mandates. Form strategic partnerships with hardware manufacturers to ensure seamless integration of next-generation positioning chipsets.
For New Entrants and Emerging Players:
Hyper-local indoor analytics for niche retail environments represents a significant service-layer gap where incumbents under-serve. Target specialized industrial asset tracking applications in manufacturing and healthcare, where precision and real-time data are paramount. The most penetrable segment is vertical-specific solutions for small and medium-sized enterprises in emerging economies. An API-first go-to-market strategy enables rapid integration into diverse third-party applications and platforms, fostering ecosystem growth.
For Investors and Strategic Acquirers:
Mid-cycle technology positioning favors firms specializing in advanced location analytics and high-precision indoor positioning solutions. The long-term viability of LBS remains robust, driven by the proliferation of autonomous systems and smart city initiatives. Acquisition targets should include companies with proprietary algorithms for data fusion and those holding key patents in z-axis location determination. A signal to watch for inflection is the widespread adoption of standardized indoor positioning protocols across major commercial venues.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deeper LBS integration into existing enterprise software enhances operational efficiency for businesses. |
| Indoor Positioning R&D | Investment in high-accuracy indoor location technologies addresses critical market gaps and regulatory demands. |
| Data Privacy Frameworks | Development of robust, compliant data handling solutions builds user trust and ensures market access. |
| Autonomous Systems Partnerships | Collaborating on real-time mapping for self-driving technology unlocks high-value future revenue streams. |
| Location Analytics Specialization | Focusing on niche data-to-insight services provides differentiated offerings for urban planning and logistics. |
Research Approach
Desk research of regulatory documents, technology journals, and geospatial data reports preceded structured interviews with LBS platform architects, fleet managers, retail marketing strategists, and smart city planners. This primary fieldwork was crucial for understanding market dynamics and validating secondary data. Bottom-up and top-down triangulation methods ensured comprehensive data coverage and consistency.
Variance decomposition formed the core of the forecast framework, modeling growth across the analysis window by segmenting the market across service type, technology, application, end user, and regional regulatory compliance. Compound annual growth rates were derived from historical data and projected growth drivers, including smartphone penetration rates and 5G infrastructure rollout. The framework integrated industry-specific inputs like E911 accuracy requirements.
Underlying assumptions cover geopolitical stability, technological advancements, and regulatory consistency, with deviation risk concentrated in rapid shifts in privacy laws. Unforeseen technological breakthroughs could also alter market trajectories. Revision becomes warranted when key regulatory or adoption conditions cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Email Marketing Market
Digital Solutions
Container Management Software Market
Digital Solutions
Warehouse Management System (WMS) Market
Digital Solutions
API Management Market
Digital Solutions
Part-Time Job Platform Market
Digital Solutions
Utility Cases Market
Digital Solutions
Data Labeling Solution and Services Market
Digital Solutions
Global Digital Asset Management Software Market
Digital Solutions
Tail Spend Management Solutions Market
Digital Solutions
Australia System Integration Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
Demand Planning Solutions Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Social Employee Recognition Systems Market
Digital Solutions
EHS Software Market
Digital Solutions
AQI App Market