
 Contactless Ticketing Solutions Market | 2026-2036
Contactless Ticketing Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Contactless Ticketing Solutions Market Analytics
Tokenized credential architecture is reconfiguring how transit operators deploy fare collection infrastructure across multimodal networks. NXP Semiconductors leverages its secure-element portfolio to anchor chip-based transit credential programs across European and Asian deployments. Cubic Transportation Systems sustains its position through deep integration with municipal back-office revenue management platforms. Thales Group differentiates via dual-interface card production combined with cloud-based validation services for regional rail operators.
Contactless ticketing solutions encompass hardware and software systems enabling fare payment through proximity-based credential exchange without physical ticket insertion or cash handling, typically operating at 13.56 MHz via NFC or low-frequency RFID protocols with transaction completion under 300 milliseconds. The primary commercial purpose centers on reducing dwell time at fare gates, eliminating cash handling costs, and generating granular origin-destination data for service planning. NFC Solutions leads product-type deployment where transit agencies prioritize interoperability with existing payment card infrastructure. Mobile Ticketing represents the fastest-growing product category as smartphone penetration and digital wallet integration reduce issuance costs for operators. Cloud-Based Systems within the technology dimension command expanding margin pools by shifting capital expenditure to recurring SaaS models and enabling real-time fare policy adjustments.
EMVCo specifications shape terminal certification requirements for open-loop contactless acceptance in transit environments across multiple jurisdictions. The European Union's GDPR and national data-protection authorities constrain how passenger journey data is stored and monetized by private operators. The Federal Transit Administration in the United States conditions capital grants on accessibility compliance and open-architecture procurement standards. Stakeholders must monitor regulatory divergence between closed-loop proprietary systems and open-payment mandates as this tension determines vendor selection criteria and contract tenures.
Market Dynamics
Transit operators face a forced hardware refresh as EMV contactless mandates from card networks collide with legacy proprietary closed-loop infrastructure nearing end-of-life. This tension accelerates procurement cycles and compresses vendor margins.
Growth Catalysts
- EMV Open-Loop Mandates:Visa and Mastercard contactless transit specifications require terminal upgrades at urban metro gates, forcing capital deployment across North American and European agencies.
- Smartphone Wallet Integration:Apple Pay and Google Pay native transit credential storage eliminates physical card issuance costs for municipal operators.
- Cloud Migration:SaaS-based fare collection platforms enable real-time dynamic pricing and reduce on-premise server maintenance burdens.
Market Restraints
- Secure Element Supply Concentration:NXP Semiconductors and Samsung dominate NFC controller production, creating single-source vulnerability for terminal manufacturers.
- GDPR Data Localization:European journey analytics storage requirements impose redundant infrastructure costs on cross-border rail operators.
- Legacy System Stranding:Magnetic-stripe infrastructure sunk costs exceed replacement economics for rural transit districts with low passenger density.
Strategic Opportunities
- India Urban Rail Expansion:Metro construction in Bangalore, Hyderabad, and Pune creates greenfield contactless deployment opportunities without legacy migration burdens.
- Account-Based Ticketing Convergence:Integration of transit credentials with banking apps enables interchange revenue sharing between transport agencies and financial institutions.
- Mobility-as-a-Service Platforms:Whim and Citymapper aggregation models demand interoperable fare engines spanning bus, rail, bike-share, and ride-hail modes.
Industry Challenges
- Embedded Firmware Talent Scarcity:Secure-element programming expertise concentrates in semiconductor hubs, forcing transit agencies to outsource terminal customization.
- Multi-Acquirer Certification Complexity:EMVCo and local transit authority testing protocols create 12-18 month product launch timelines for new terminal vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contactless Ticketing Solutions Market |
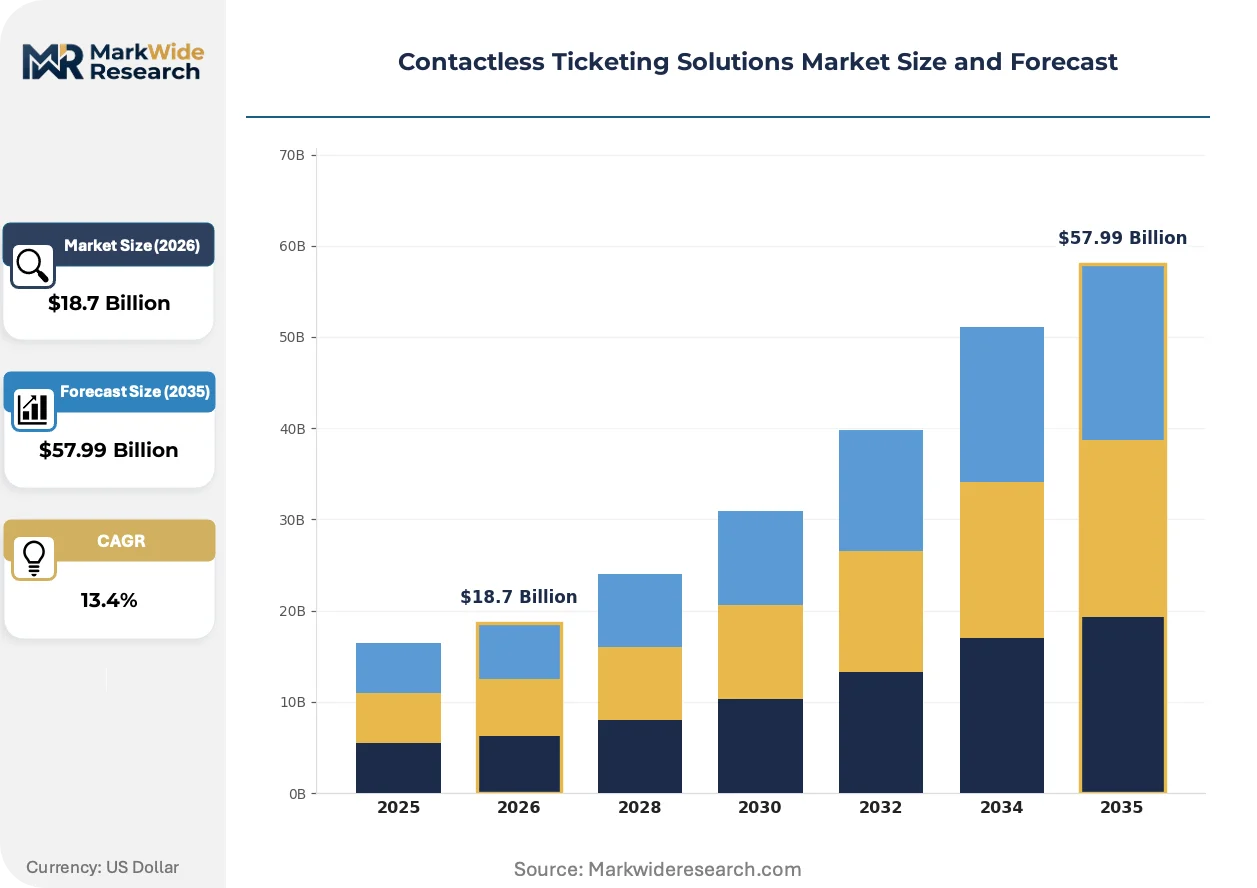
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Ticketing, Smart Cards, QR Codes, NFC Solutions End User: Transportation, Events, Sports, Entertainment Technology: Cloud-Based Systems, RFID, Blockchain, Biometric Verification Distribution Channel: Online Platforms, Retail Outlets, Kiosks, Direct Sales |
| Companies Covered | Giesecke+Devrient, HID Global, Cubic Transportation Systems, Siemens Mobility, Conduent Incorporated, Thales Group, Infineon Technologies, Confidex Ltd., NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contactless Ticketing Solutions Market Evolving Landscape
Tokenized credential architectures are collapsing the distinction between transit-specific closed-loop systems and general-purpose payment networks. This convergence reshapes vendor competitive boundaries and operator procurement criteria.
Biometric face-and-gate validation is migrating from pilot deployments to production corridors. Transport for London and Moscow Metro deploy camera arrays for fare-deducted entry without physical credential presentation. The technology is migrating from security-centric applications to friction-reduction use cases, compressing dwell times below 200 milliseconds and eliminating card-tap failure modes.
GDPR Article 25 data-protection-by-design mandates constrain how European transit authorities store passenger journey histories. Operators must implement pseudonymization and purpose-limitation protocols before cloud migration. Regional rail consortia in Germany and France respond by segmenting payment processing from analytics warehousing across separate vendor contracts.
Agency procurement teams now unbundle hardware purchase from software licensing and ongoing maintenance. Chicago Transit Authority and Transport for New South Wales structure 10-year agreements with per-transaction SaaS fees replacing upfront capital outlays. This shift concentrates vendor selection on API interoperability and uptime SLA performance rather than terminal unit cost.
Contactless Ticketing Solutions Market Segmentation
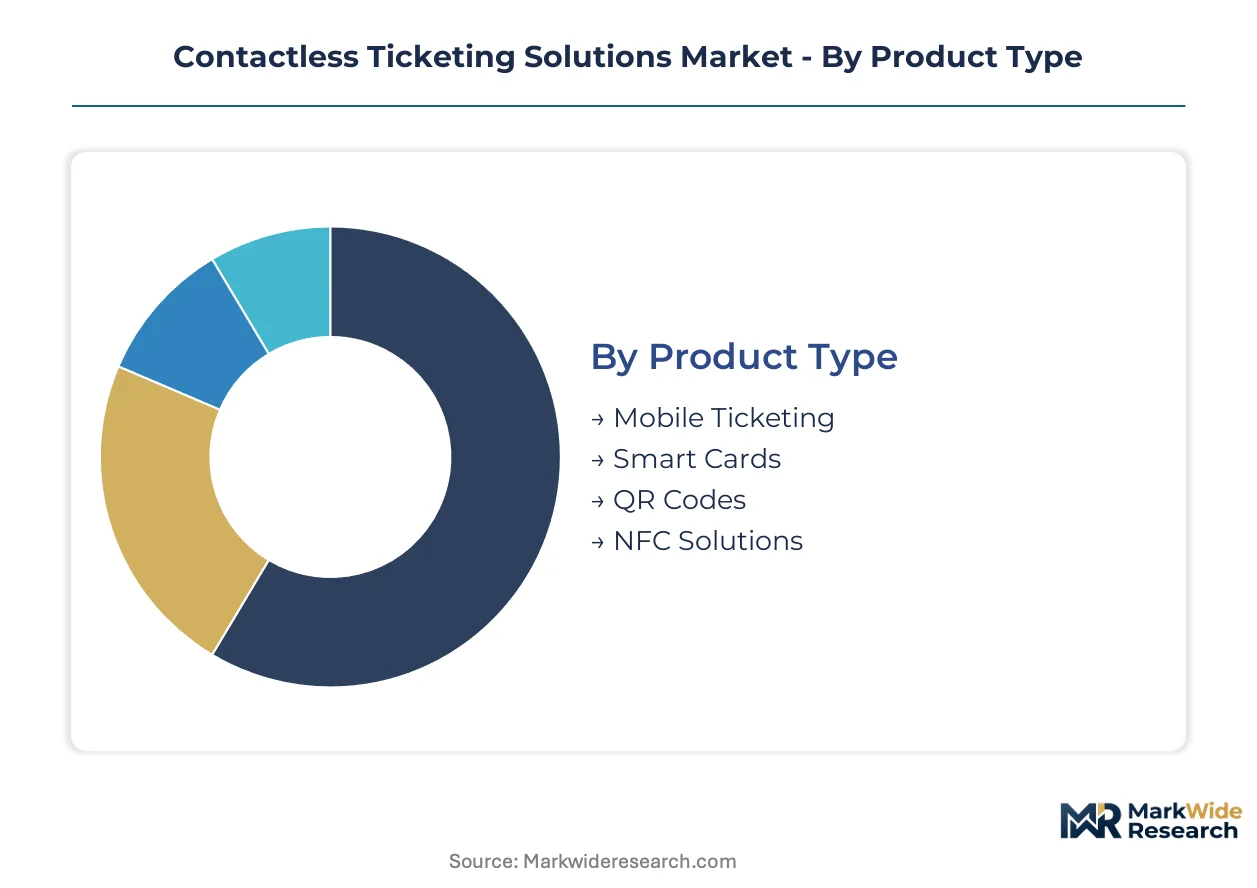
Transit agencies structure procurement around lifecycle cost models where hardware durability, firmware update cadence, and field service response times determine total cost of ownership. Segmentation reveals how vendor specialization maps to operator risk tolerance and infrastructure maturity.
Product Type:
After-sales service intensity varies sharply across credential formats, with terminal hardware demanding preventive maintenance contracts and mobile platforms requiring continuous app store compliance updates.
- Mobile Ticketing:Smartphone-based credential delivery via native apps or digital wallets eliminates physical card distribution logistics. Demand concentrates in urban metro systems across Germany and the Netherlands where smartphone penetration exceeds threshold levels for viable deployment. Operators favor this format for reduced issuance costs and real-time fare policy adjustments.
- NFC Solutions:Proximity-based 13.56 MHz credential exchange operates at sub-300 millisecond transaction speeds with EMV compliance for open-loop bank card acceptance. Deployment clusters in London, New York, and Singapore corridors where interoperability with existing payment infrastructure justifies terminal upgrade investments. Visa and Mastercard contactless mandates accelerate replacement cycles.
- Smart Cards:Dual-interface plastic credentials with embedded secure elements remain standard for closed-loop proprietary systems requiring offline validation capability.
- QR Codes:Optical scanning-based credentials enable low-cost smartphone acceptance without specialized NFC hardware at fare gates.
NFC Solutions holds the largest share; momentum sits with Mobile Ticketing.
End User:
Application context dictates security architecture, with high-throughput transit corridors requiring sub-200 millisecond validation against stadium entry tolerating longer processing windows.
- Transportation:Metro, bus, and rail networks demand hardened terminals with IP65 environmental ratings and 99.99% uptime SLAs. Ridership density in Tokyo, Paris, and São Paulo systems justifies redundant server infrastructure and 24/7 network operations centers. Fare evasion pressure drives investment in gate-mounted sensors and back-office analytics.
- Events:Temporary credential issuance for music festivals and conferences prioritizes rapid deployment speed over durability, with cloud-based validation reducing on-site hardware requirements.
- Sports:Season ticket integration with team mobile apps creates recurring engagement touchpoints beyond match-day entry.
- Entertainment:Cinema and theater operators favor low-friction entry experiences with minimal staff intervention at access points.
Transportation dominates volume; Events shows the steepest expansion trajectory as post-pandemic attendance rebounds.
Technology:
Margin pools concentrate in recurring SaaS arrangements where operators shift capital expenditure to subscription models with embedded software maintenance.
- Cloud-Based Systems:Centralized fare processing platforms enable real-time dynamic pricing and reduce on-premise server maintenance burdens. Adoption concentrates among mid-sized North American transit agencies lacking dedicated IT infrastructure. The Federal Transit Administration capital grant conditions favor open-architecture procurement compatible with cloud migration.
- RFID:Radio-frequency identification at 125 kHz and 13.56 MHz frequencies supports legacy closed-loop systems with offline validation capability in tunnel environments lacking cellular coverage.
- Biometric Verification:Facial recognition and palm-vein scanning eliminate physical credential presentation, compressing dwell times below 200 milliseconds at fare gates.
- Blockchain:Distributed ledger credential verification remains experimental, with pilot programs in Nordic markets testing interoperability across municipal boundaries.
Cloud-Based Systems commands the largest installed base; Biometric Verification gains share fastest as Transport for London and Moscow Metro advance production deployments.
Distribution Channel:
Channel selection reflects operator procurement maturity, with established agencies favoring direct vendor relationships and emerging systems defaulting to integrator-mediated purchases.
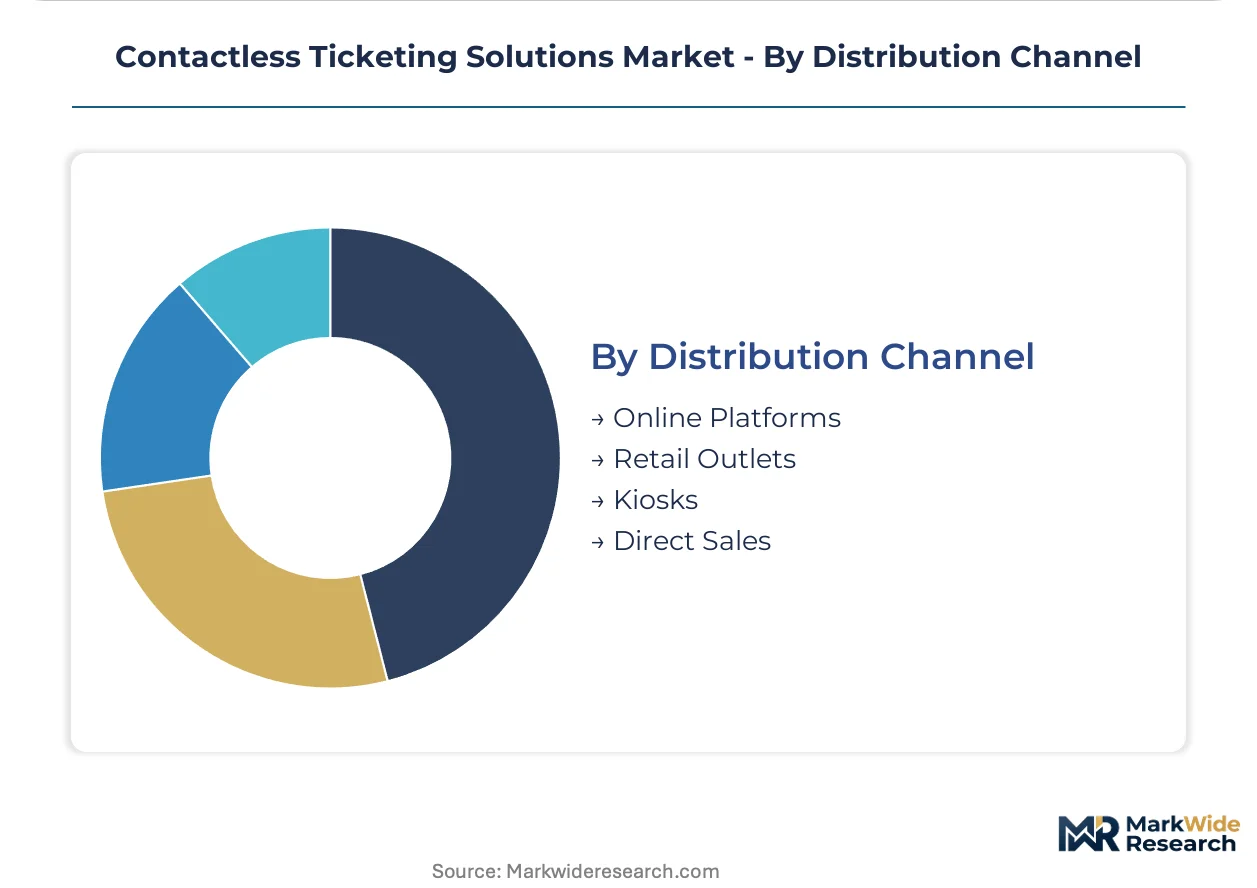
- Direct Sales:Manufacturer-led contracting enables customization of terminal firmware and integration with legacy back-office revenue management platforms. Large urban agencies in Chicago and Sydney structure 10-year agreements with per-transaction SaaS fees replacing upfront capital outlays.
- Online Platforms:Digital procurement portals streamline specification comparison for smaller operators with standardized requirements and limited technical evaluation capacity.
- Retail Outlets:Physical credential sales through convenience store networks support closed-loop systems requiring anonymous card purchase options.
- Kiosks:Self-service vending machines at transit stations enable immediate credential replacement for lost or damaged cards.
Direct Sales retains the largest contract value; Online Platforms expands most quickly as procurement digitization accelerates among secondary urban systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German terminal manufacturers export contactless validation hardware to transit agencies across the United States, United Kingdom, and Singapore, establishing a dominant trade corridor in high-throughput fare gate systems.
United States
The Federal Transit Administration conditions capital grants on open-architecture procurement standards, accelerating cloud-based fare collection migration among mid-sized agencies. Chicago Transit Authority structures 10-year agreements with per-transaction SaaS fees replacing upfront capital outlays. New York Metropolitan Transportation Authority operates the largest open-loop contactless deployment in North America.
Germany
German regional rail consortia segment payment processing from analytics warehousing across separate vendor contracts to satisfy GDPR Article 25 data-protection-by-design mandates. Berlin-Brandenburg transit authorities pilot biometric face-and-gate validation systems for sub-200 millisecond dwell times. Bavarian semiconductor clusters supply secure elements to terminal manufacturers across European deployments.
United Kingdom
Transport for London deploys camera arrays for fare-deducted entry without physical credential presentation, advancing production biometric corridors. The Information Commissioner's Office enforces purpose-limitation protocols on passenger journey data storage. Manchester and Birmingham metro expansions drive terminal procurement for multimodal integration with bus and bike-share networks.
India
Metro construction in Bangalore, Hyderabad, and Pune creates greenfield contactless deployment opportunities without legacy migration burdens. The Ministry of Housing and Urban Affairs mandates interoperable fare collection standards across urban rail projects. Delhi Metro Rail Corporation operates integrated NFC and QR code acceptance across the world's third-largest urban rail network.
Singapore
The Land Transport Authority enforces EMV contactless specifications for seamless tourist payment experience alongside domestic transit card systems. Downtown Line and Thomson-East Coast Line extensions incorporate cloud-based validation infrastructure. Singapore's position as a regional financial hub attracts fintech partnerships for account-based ticketing convergence.
Contactless Ticketing Solutions Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hardware procurement and software licensing segments. The vendor base concentrates among semiconductor manufacturers with secure-element portfolios and systems integrators with municipal back-office relationships. Three archetypes dominate: chip-level credential providers, end-to-end platform vendors, and cloud-native fare engine specialists. Strategic moves center on API interoperability investments and 10-year SaaS contract structures replacing capital sale models.
Within the semiconductor tier, NXP Semiconductors and Infineon Technologies occupy positions as secure-element anchors for transit credential programs. Cubic Transportation Systems exemplifies the integrated platform archetype through deep municipal revenue management relationships. Thales Group sits within the dual-capability segment combining card production with cloud validation services for regional rail operators.
| Leading Market Players |
|---|
| Giesecke+Devrient |
| HID Global |
| Cubic Transportation Systems |
| Siemens Mobility |
| Conduent Incorporated |
| Thales Group |
| Infineon Technologies |
| Confidex Ltd. |
| NXP Semiconductors |
| Others |
Value Network & Pricing Analysis
Bavarian semiconductor clusters anchor NFC controller and secure-element production, feeding terminal manufacturers across European and Asian deployments. This geographic concentration grants NXP Semiconductors and Infineon Technologies substantial pricing leverage over downstream fare gate integrators facing EMV compliance deadlines.
Pricing Analysis
Next-generation biometric validation systems command substantial premiums over incumbent NFC terminal hardware, while legacy RFID infrastructure faces accelerated depreciation. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and after-sales service bundling. Cost compression in standard-tier hardware is intensifying because Chinese terminal manufacturers are expanding export capacity. Rural transit districts with limited passenger density exhibit highest price sensitivity; London and Singapore operators prioritize uptime SLAs over unit cost.
Supply Chain Analysis
Flex and Jabil hold contract manufacturing capacity for transit terminal assembly, with Foxconn expanding into fare gate enclosure production. Component sourcing draws from Taiwan for NFC controllers, South Korea for memory modules, and Germany for precision mechanical assemblies. Supply chain risk centers on single-source vulnerability for EMV-certified secure elements. Distribution runs through direct vendor relationships with large urban agencies and integrator-mediated channels for secondary systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across multimodal integration requirements creates specialist opportunities as transit agencies unbundle hardware procurement from SaaS licensing. Account-based ticketing convergence with banking apps is fragmenting vendor competitive boundaries.
For Market Incumbents: Harden API interoperability investments to defend against cloud-native fare engine specialists encroaching on municipal relationships. Secure long-term secure-element supply agreements to mitigate NXP Semiconductors concentration risk. Expand biometric validation R&D to maintain technology leadership against emerging computer-vision entrants.
For New Entrants and Emerging Players: Indian metro construction in Bangalore, Hyderabad, and Pune offers greenfield deployment opportunities without legacy migration burdens. Target mid-sized North American agencies seeking cloud-based alternatives to Cubic Transportation Systems dominance. Pursue white-label SaaS partnerships with existing municipal IT providers as lower-friction market entry.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cloud-native fare engine specialists with proven API interoperability. Five-to-ten-year viability hinges on account-based ticketing convergence momentum. Monitor EMVCo specification evolution as inflection indicator for terminal hardware refresh cycles and incumbent defensibility.
| Strategic Initiative | Industry Significance |
|---|---|
| API Interoperability Investment | Enables integration with Whim and Citymapper mobility-as-a-service platforms across multimodal networks. |
| Biometric Validation Deployment | Transport for London camera arrays demonstrate sub-200 millisecond dwell time compression at production scale. |
| Cloud Migration Partnership | Chicago Transit Authority per-transaction SaaS model reduces upfront capital barriers for mid-sized agencies. |
| Secure Element Supply Agreement | Mitigates single-source vulnerability from NXP Semiconductors concentration in NFC controller production. |
| Account-Based Ticketing Convergence | Interchange revenue sharing with Visa and Mastercard transforms transit agencies into financial services participants. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EMVCo specifications, Federal Transit Administration capital grant disclosures, and European national data-protection authority rulings. Interviews with transit agency procurement officers, fare collection systems integrators, and semiconductor vendor account managers informed demand-side and supply-side assessments. Secondary validation drew from vendor contract announcements, regulatory filing databases, and municipal budget documents. Bottom-up terminal deployment estimates triangulated against top-down market value reconstruction.
Forecast inputs incorporate ridership density projections, EMV mandate implementation timelines, and cloud migration adoption curves across the analysis window. Segmentation modeling spans product type, end-use application, technology architecture, and distribution channel. CAGRs derive from logistic diffusion curves fitted to observed deployment patterns. Industry-specific inputs include smartphone penetration thresholds for mobile ticketing viability and secure-element production capacity constraints.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by semiconductor manufacturers into terminal assembly would shift outcomes. Quarterly review of EMVCo specification updates and municipal procurement award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Onboarding Market
Digital Solutions
Global Online Reputation Management Software Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
Key Management As a Service (Kmaas) Market
Digital Solutions
Weather Forecasting Systems and Solutions Market
Digital Solutions
Service Orchestration Market
Digital Solutions
Global Digital Experience Platform Market
Digital Solutions
Chile ICT Market
Digital Solutions
Online Home Service Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
Cheque Scanner Market
Digital Solutions
China Digital Twin Market
Digital Solutions
Data Pipeline Tools Market
Digital Solutions
Demand Side Platform (DSP) Market
Digital Solutions
Asia-Pacific Digital Pen Market
Digital Solutions
US Digital Twin Market