
 Global Commerce Cloud Solution Market | 2026-2036
Global Commerce Cloud Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Global Commerce Cloud Solution Market Foresight
Buyer fragmentation across mid-market digital marketplaces and subscription services is expanding the addressable base beyond traditional enterprise accounts. Salesforce.com, Inc. leverages its Einstein AI layer to anchor high-complexity omnichannel deployments. SAP SE competes through deep ERP integration that sustains renewal rates among Tier-1 suppliers. Shopify Inc. specializes in direct-to-consumer velocity, dominating merchant onboarding velocity in North America and Western Europe.
Commerce cloud solutions deliver multi-tenant software architectures with API-first headless commerce engines, real-time inventory synchronization, and edge-cached storefront rendering to enable sub-100 millisecond page loads across distributed fulfillment networks. Public cloud deployment leads volume due to elastic scaling economics, while hybrid cloud configurations capture margin pools from automotive and wholesale distributors with data residency constraints. Software as a Service remains the dominant solution offering, though integration platforms are gaining traction as enterprises stitch together fragmented order management and payment systems.
The EU AI Act, GDPR, and ISO 27001 standards collectively shape product roadmaps by mandating algorithmic transparency for recommendation engines and encrypted data residency for cross-border transactions. The Federal Trade Commission and state-level privacy statutes in the United States add compliance layers that favor vendors with pre-certified security postures. Stakeholders must monitor regulatory divergence between jurisdictions to avoid architecture lock-in that limits geographic expansion.
Market Dynamics
The EU AI Act and GDPR are forcing commerce cloud vendors to rebuild algorithmic transparency and encrypted data residency into core architectures, reshaping how automotive suppliers and specialty retailers consolidate vendor relationships across Germany and adjacent markets.
Growth Catalysts
- EU AI Act compliance mandates:Cross-border retailers must deploy explainable recommendation engines and audit trails, accelerating replacement of legacy black-box systems with certified cloud stacks.
- Headless commerce API architectures:Real-time inventory synchronization and edge-cached storefront rendering enable sub-100 millisecond page loads that automotive distributors require for distributed fulfillment networks.
- Germany's unified commerce consolidation:Automotive suppliers and specialty retailers are collapsing fragmented point solutions into single-vendor relationships to reduce integration overhead and audit complexity.
Market Restraints
- Hybrid cloud infrastructure costs:Automotive and wholesale distributors with data residency constraints face 40-60% higher total cost of ownership versus public cloud equivalents due to dedicated hardware and compliance tooling.
- ISO 27001 certification bottlenecks:Pre-certified security postures require 12-18 month audit cycles that delay vendor onboarding for mid-market digital marketplaces with compressed procurement timelines.
- Payment system fragmentation:Enterprises stitching together order management and payment systems encounter API versioning conflicts that increase integration labor by 25-35% versus unified native stacks.
Strategic Opportunities
- Subscription commerce underpenetration:Direct-to-consumer velocity platforms in France and Italy lag Germany's consolidation pace, creating whitespace for unified commerce stacks with embedded subscription billing.
- FTC state-level privacy patchwork:California, Virginia, and Colorado divergent statutes favor vendors with pre-certified multi-jurisdictional compliance modules, creating switching costs for single-state certified competitors.
- Edge computing and 5G convergence:Warehouse robotics and autonomous mobile robots demand millisecond-latency inventory updates that hybrid edge-cloud architectures can capture at automotive supplier campuses.
Industry Challenges
- API-first engineering talent scarcity:Headless commerce deployments require specialized integration architects that mid-market retailers cannot recruit at competitive rates against enterprise cloud vendors.
- Legacy ERP migration friction:Tier-1 suppliers with decades of SAP or Oracle on-premise installations face data model incompatibilities that extend cloud migration timelines by 8-14 months.
- Algorithmic audit documentation:GDPR Article 22 and EU AI Act conformity assessments demand technical documentation that product teams lack institutional knowledge to generate without external legal-technical consultants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Commerce Cloud Solution Market |
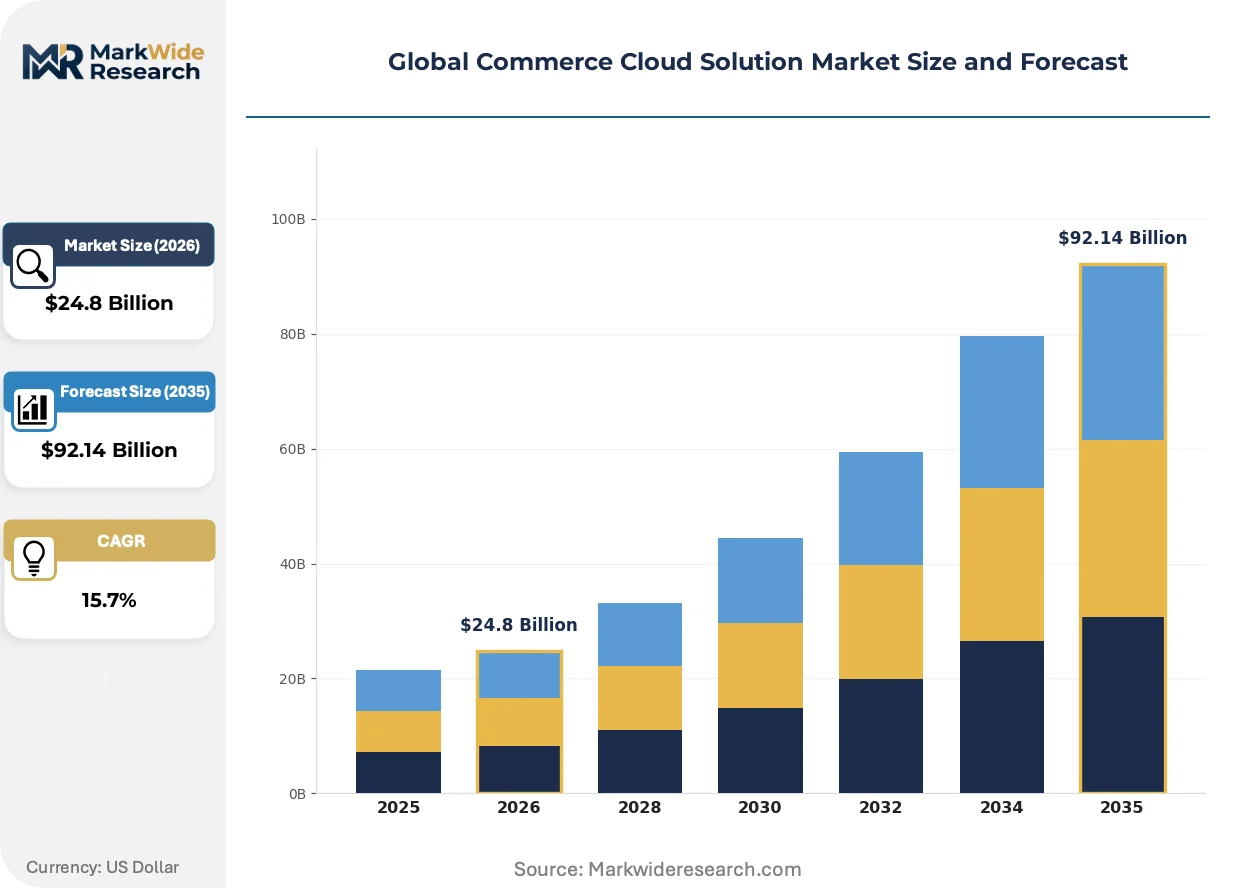
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $92.14 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Mode: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution Offering: Platform as a Service, Software as a Service, Infrastructure as a Service, Integration Platform, Managed Services Use Case: Omnichannel Retail, Digital Marketplaces, Subscription Services, Direct to Consumer, Wholesale Distribution End User Segment: Tier-1 Suppliers, Dealerships, Aftermarket Providers, Specialty Retailers |
| Companies Covered | Salesforce.com, Inc., Oracle Corporation, SAP SE, Shopify Inc., BigCommerce Pty. Ltd., Adobe, Inc., IBM Corporation, Amazon Web Services, Inc., Optimizely, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Commerce Cloud Solution Market Shifts & Advancements
Commerce cloud architectures are compressing toward composable, API-first stacks that separate frontend experience from backend fulfillment logic, enabling retailers to swap components without platform lock-in.
Headless commerce engines with GraphQL API layers is overtaking monolithic storefront architectures in complexity-driven deployments. Automotive suppliers in Germany and specialty retailers in the Netherlands are adopting these stacks within 6-9 month procurement cycles. The technology is compressing vendor consolidation timelines by eliminating frontend-backend dependencies that previously anchored multi-year platform commitments.
The EU AI Act's algorithmic transparency requirements are mandating explainable recommendation engines and automated decision documentation for cross-border transactions. Industrial consequence includes mandatory human-in-the-loop overrides for pricing algorithms above defined risk thresholds. German automotive suppliers and French luxury retailers are most affected, responding by embedding compliance telemetry directly into commerce cloud data pipelines.
Merchant onboarding velocity now determines platform selection for direct-to-consumer brands with seasonal launch windows. Shopify's standardized templates and pre-integrated payment rails are displacing custom development cycles in North American and Western European markets. This pattern is most visible in subscription box and flash sale verticals where 30-day launch timelines render traditional 90-day implementations commercially unviable.
Global Commerce Cloud Solution Market Segmentation
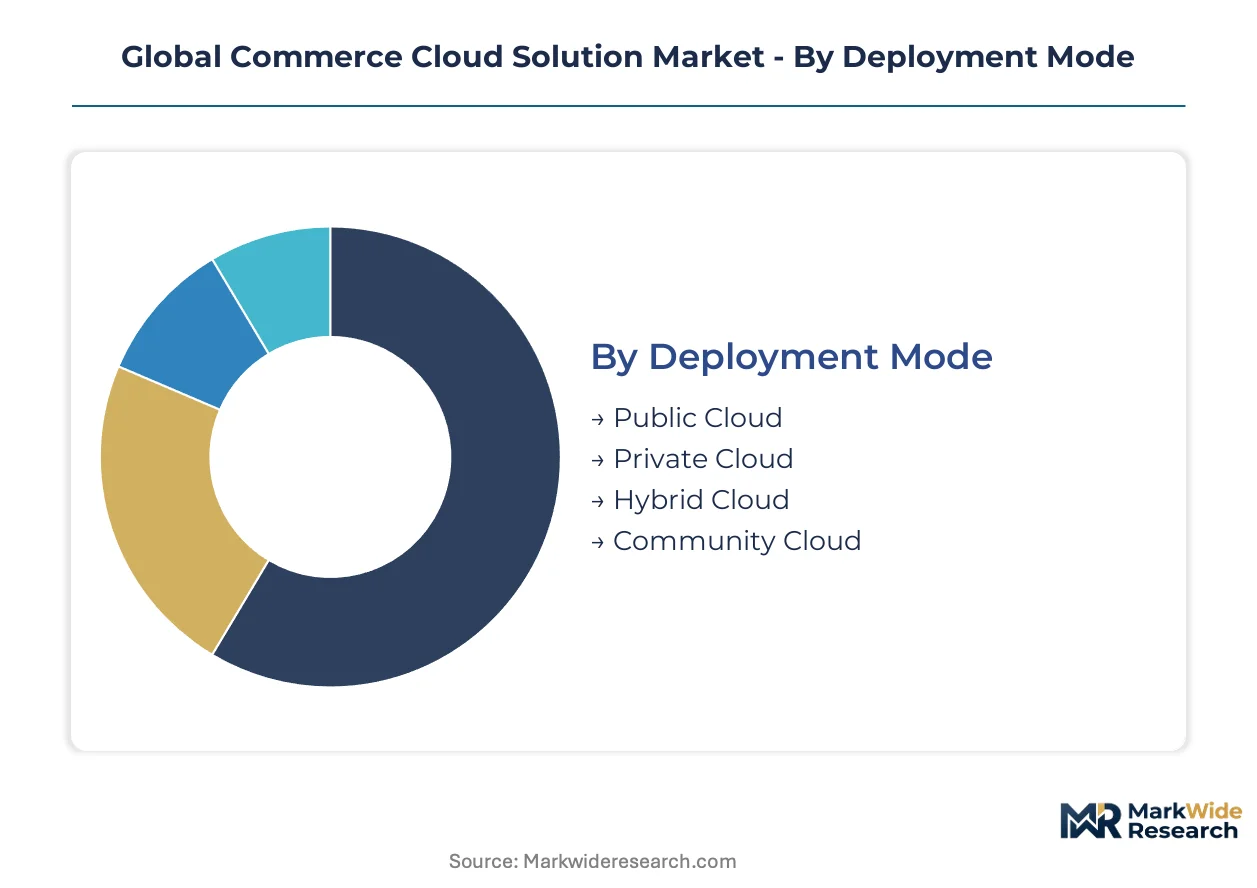
Commerce cloud procurement decisions hinge on data residency mandates, integration complexity, and launch velocity requirements that vary sharply across automotive supply chains and direct-to-consumer brands. Segment-level positioning determines whether vendors capture unified commerce consolidation in Germany or mid-market subscription growth in France and Italy.
Deployment Mode:
Cost elasticity versus compliance rigidity drives deployment selection, with automotive suppliers weighing dedicated infrastructure against public cloud economics.
- Public Cloud:Multi-tenant architectures deliver elastic scaling for flash-sale retailers and seasonal subscription box launches. Shopify merchants in North America and Western Europe default here for sub-30-day onboarding timelines that match inventory arrival schedules.
- Hybrid Cloud:Split workloads separate customer-facing storefronts from encrypted ERP data residing on German or French sovereign infrastructure. Tier-1 automotive suppliers adopt this configuration to satisfy GDPR Article 44 cross-border transfer rules while maintaining millisecond-latency inventory APIs for warehouse robotics.
- Private Cloud:Single-tenant dedicated stacks serve aftermarket providers with ISO 27001 pre-certification requirements that public environments cannot accommodate within compressed procurement cycles.
- Community Cloud:Shared infrastructure among non-competing specialty retailers in the Netherlands reduces compliance audit duplication through pooled GDPR documentation.
Public Cloud leads on scale; Hybrid Cloud leads on momentum as EU AI Act data residency rules harden.
Solution Offering:
Integration burden determines whether buyers favor native unified stacks or composable best-of-breed assembly.
- Software as a Service:Pre-configured storefront templates with embedded payment rails dominate merchant onboarding velocity for direct-to-consumer brands. Standardized checkout flows and tax calculation engines eliminate 60-70% of custom development labor versus on-premise alternatives.
- Integration Platform:API orchestration layers stitch fragmented order management systems with warehouse management and payment processors. Mid-market digital marketplaces in France deploy these to bridge legacy ERP investments with headless commerce frontends.
- Platform as a Service:Developer-centric environments enable custom storefront builds for luxury retailers requiring unique brand expression that template constraints prohibit.
- Infrastructure as a Service:Bare-metal compute and storage provisioning supports wholesale distributors with existing DevOps capabilities seeking granular cost control.
- Managed Services:Outsourced infrastructure monitoring and security patching appeals to specialty retailers lacking internal cloud engineering benches.
Software as a Service dominates current revenue; Integration Platform is climbing fastest as API fragmentation deepens.
Use Case:
Channel complexity and transaction frequency shape architectural requirements across retail verticals.
- Omnichannel Retail:Unified inventory visibility across physical stores, mobile apps, and marketplaces demands real-time synchronization engines. German automotive suppliers consolidate here to collapse fragmented point solutions into single-vendor relationships.
- Direct to Consumer:Velocity-focused brands prioritize merchant onboarding speed over customization depth. Subscription services and flash sale operators select platforms with pre-integrated payment rails and templated storefronts.
- Digital Marketplaces:Multi-seller platforms require sophisticated commission engines, seller onboarding workflows, and dispute resolution systems that standard retail stacks lack.
- Subscription Services:Recurring billing logic with dunning management and usage-based pricing appeals to software and physical goods subscription operators in underpenetrated French and Italian markets.
- Wholesale Distribution:Bulk pricing tiers, quote-to-order workflows, and EDI integration dominate B2B procurement requirements for automotive parts distributors.
Omnichannel Retail commands the largest installed base; Direct to Consumer shows the steepest expansion trajectory among new platform commitments.
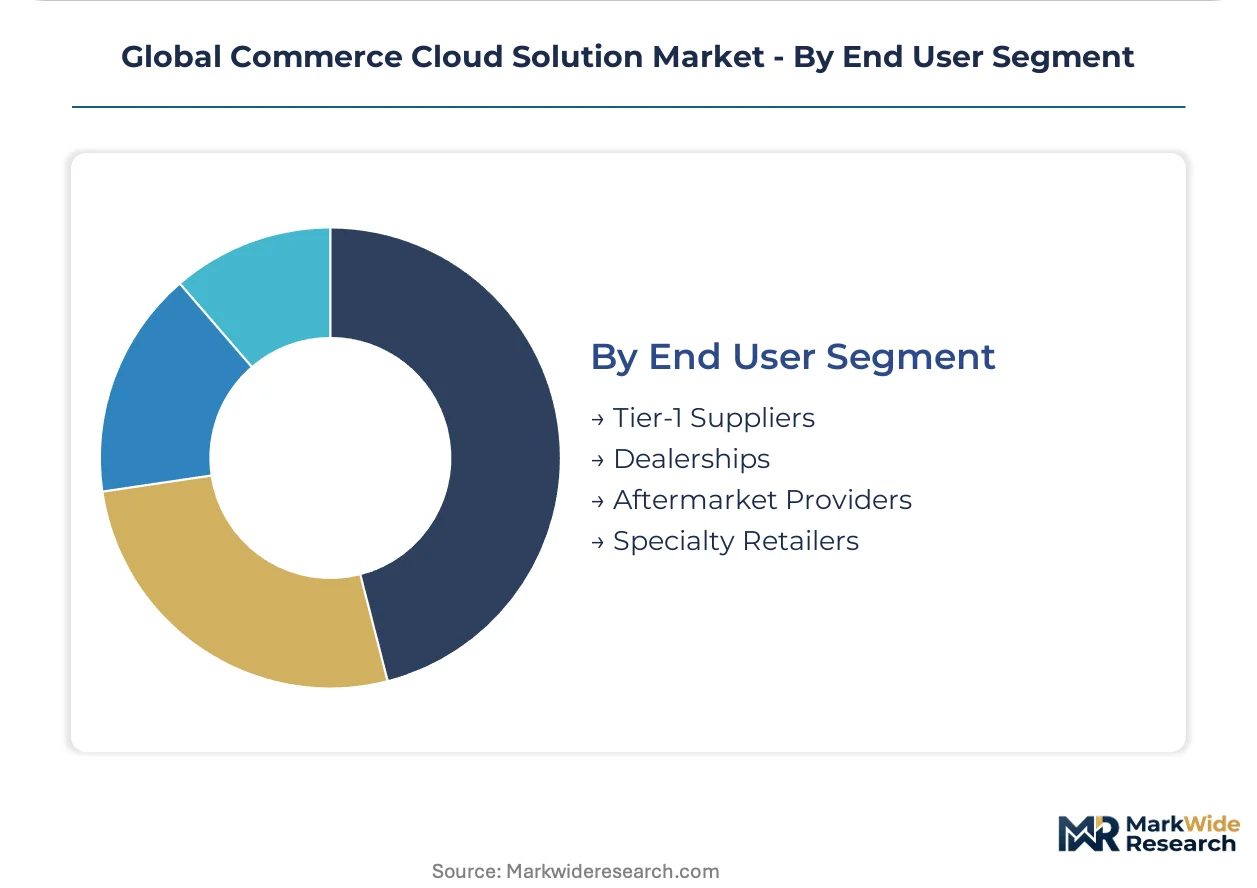
End User Segment:
Procurement sophistication and compliance exposure vary sharply across automotive supply chain tiers.
- Tier-1 Suppliers:Deep ERP integration requirements and decades of SAP or Oracle on-premise investment create migration friction extending 8-14 months. These buyers prioritize vendors with certified SAP connector ecosystems.
- Specialty Retailers:Niche product focus with lower transaction volumes enables faster cloud adoption. Dutch specialty retailers adopt headless commerce within 6-9 month cycles versus Tier-1 supplier timelines.
- Dealerships:Franchise network coordination demands multi-location inventory pooling and manufacturer-compliant branding constraints that limit platform flexibility.
- Aftermarket Providers:Parts catalog complexity with fitment data and cross-reference requirements drives specialized commerce implementations distinct from standard retail configurations.
Tier-1 Suppliers anchor contract value; Specialty Retailers are gaining share fastest through compressed procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud-native engineering talent pools in the United States, Germany, and India anchor platform development capacity for commerce cloud vendors serving cross-border retail networks.
United States
Direct-to-consumer brands and flash-sale retailers drive platform selection based on merchant onboarding velocity. The FTC and state-level privacy statutes in California, Virginia, and Colorado create compliance complexity that favors vendors with pre-certified multi-jurisdictional modules. Seattle and San Francisco Bay Area engineering clusters concentrate headless commerce API development for seasonal subscription box launches.
Germany
Automotive suppliers and specialty retailers consolidate fragmented point solutions into unified commerce stacks to reduce integration overhead. The EU AI Act and GDPR mandate algorithmic transparency and encrypted data residency, forcing rebuilds of recommendation engine architectures. Stuttgart and Munich industrial corridors host Tier-1 supplier campuses where hybrid edge-cloud deployments serve warehouse robotics with millisecond-latency inventory updates.
France
Luxury retailers and underpenetrated subscription services lag Germany's consolidation pace, creating whitespace for unified commerce stacks with embedded recurring billing. CNIL enforcement of GDPR Article 22 drives demand for explainable pricing algorithms with human-in-the-loop overrides. Paris and Lyon fashion houses adopt compliance telemetry embedded directly into commerce cloud data pipelines.
United Kingdom
Mid-market digital marketplaces expand the addressable base beyond traditional enterprise accounts with compressed procurement timelines. Post-Brexit data transfer rules complicate cross-border transaction architectures for retailers serving EU customers. London fintech clusters integrate payment orchestration layers with headless commerce frontends for multi-seller platforms.
India
Integration platform demand climbs as enterprises stitch fragmented order management systems with API-first headless commerce engines. The Digital Personal Data Protection Act shapes vendor roadmaps for data localization in cross-border retail transactions. Bengaluru and Hyderabad SaaS engineering hubs develop composable commerce stacks for mid-market merchants seeking sub-90-day implementation cycles.
Global Commerce Cloud Solution Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across deployment modes and solution layers. Enterprise software incumbents leverage deep ERP connector ecosystems to sustain renewal rates among Tier-1 suppliers with decades of on-premise investment. Three archetypes dominate: full-suite platform vendors, API-first headless specialists, and infrastructure-as-a-service providers. Competitive moves concentrate on strategic partnerships for pre-certified compliance modules and portfolio diversification into subscription billing and edge computing capabilities.
Within the full-suite platform tier, Salesforce.com, Inc. and SAP SE occupy anchor positions representing divergent integration strategies. Salesforce anchors high-complexity omnichannel deployments through AI-layer differentiation, while SAP exemplifies ERP-native consolidation that extends migration timelines but reduces long-term integration overhead. Shopify Inc. sits within the velocity-focused pure-play archetype, dominating merchant onboarding speed for direct-to-consumer brands with seasonal launch windows in North America and Western Europe.
| Leading Market Players |
|---|
| Salesforce.com, Inc. |
| Oracle Corporation |
| SAP SE |
| Shopify Inc. |
| BigCommerce Pty. Ltd. |
| Adobe, Inc. |
| IBM Corporation |
| Amazon Web Services, Inc. |
| Optimizely |
| Others |
Supply & Pricing Matrix
API-first engineering talent concentration in Bengaluru and Hyderabad anchors labor-cost differentials that separate premium-tier custom implementations from standardized SaaS subscriptions. These regional wage spreads directly determine pricing-tier stratification across deployment modes.
Pricing Analysis
Bundled SaaS subscriptions dominate the lower tier while unbundled integration platform services capture premium pricing. Pricing stratifies across enterprise-grade compliance certification, customization depth, and embedded AI capabilities. Cost compression in mid-market SaaS tiers intensifies as Shopify and BigCommerce standardize onboarding templates. Tier-1 automotive suppliers show lowest price sensitivity due to ERP migration friction and compliance mandates, while flash-sale retailers prioritize velocity over cost optimization.
Supply Chain Analysis
Single-source vulnerability sits with hyperscale cloud infrastructure concentrated in the United States, Germany, and Ireland. Commerce cloud architectures draw from GPU compute clusters, API gateway services, and encryption key management hardware. Regulatory restriction risk looms as GDPR Article 44 cross-border transfer rules harden data residency requirements. Distribution runs through direct vendor sales organizations for enterprise accounts and self-service portals for mid-market merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU AI Act compliance costs in Germany create margin pools that Indian engineering hubs can capture through ISO 27001 pre-certified delivery centers.
For Market Incumbents: Acquire headless commerce API specialist firms to neutralize composable stack disruption from emerging pure-play vendors. Deepen SAP and Oracle connector ecosystems to extend renewal rates among Tier-1 suppliers facing 8-14 month migration timelines. Invest in pre-certified multi-jurisdictional compliance modules to exploit FTC state-level privacy patchwork complexity.
For New Entrants and Emerging Players: The premium-economy pricing gap in subscription commerce billing creates entry whitespace in underpenetrated French and Italian markets. Target mid-market digital marketplaces with compressed 6-9 month procurement cycles that incumbent enterprise sales motions cannot serve. Lead with embedded recurring billing and dunning management as differentiated native capabilities.
For Investors and Strategic Acquirers: Enterprise software conglomerates with ERP connector portfolios are the most active acquirer in this space. Long-term viability hinges on API-first engineering talent retention and compliance telemetry IP accumulation. Watch for EU AI Act conformity assessment bottlenecks as inflection signals for vendor consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Headless commerce API layers compress vendor consolidation timelines by eliminating frontend-backend dependencies. |
| Acquisition of Specialist Firm | Edge computing capabilities for warehouse robotics demand millisecond-latency inventory updates at automotive campuses. |
| Strategic Partnership | Pre-certified compliance modules with GDPR and EU AI Act telemetry reduce 12-18 month audit cycles. |
| Geographic Expansion | Indian engineering hubs deliver sub-90-day implementation cycles for mid-market merchants. |
| Product Launch | Embedded subscription billing captures whitespace in French and Italian recurring commerce markets. |
Research Methodology
Multiple input streams — primary interviews with CTOs and IT procurement officers, hyperscaler capex disclosures, and SEC filings — were reconciled against bottom-up and top-down triangulation. Stakeholder conversations encompassed platform engineers, integration specialists, and channel partners across automotive supply chains and direct-to-consumer verticals. Secondary validation drew from App Annie mobile commerce metrics, EU regulatory submission databases, and customs records for cloud infrastructure equipment.
Data-stream reconciliation anchored analytical frameworks across deployment mode, organization size, vertical integration complexity, and regional adoption patterns. CAGRs were derived from modeled segment trajectories over the projection horizon. Forecast inputs incorporated API versioning conflict rates, ISO 27001 certification cycle durations, and merchant onboarding velocity benchmarks.
Caveats apply where EU AI Act enforcement timing or FTC state-level privacy rule divergence could materially shift the outlook. Forecasts reflect assumptions about compliance cost pass-through and engineering talent availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Connected Workplace Market
Digital Solutions
Manufacturing Execution System Market
Digital Solutions
Image Recognition in Retail Market
Digital Solutions
Global Autonomous Data Platform Market
Digital Solutions
North America API Management Market
Digital Solutions
Computerized Maintenance Management System Market
Digital Solutions
Condition Monitoring Software Market
Digital Solutions
North America 3D Rendering Services Market
Digital Solutions
Cloud-Based Product Lifecycle Management (PLM) Market
Digital Solutions
Mobile Resource Management Solutions Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Latin America Digital Signage Market
Digital Solutions
Global Digital Assurance Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
US Transcription Market