
 Landing Page Builders Market | 2026-2036
Landing Page Builders Market Size, Share, and Industry Trends Forecast 2026-2036
Landing Page Builders Market Foresight
Modular bundling of landing page tools with adjacent marketing automation is pivoting buyer choice away from standalone point solutions. Unbounce leverages deep specialization in conversion intelligence to sustain premium positioning among mid-market agencies. HubSpot anchors its ecosystem play by embedding page builders within broader CRM workflows. Wix competes through aggressive freemium distribution and vertical template libraries for service-sector micro-businesses.
A landing page builder is a software application that generates standalone web pages optimized for single-action conversion goals, typically incorporating drag-and-drop visual editors, A/B testing engines, and responsive CSS frameworks without requiring manual code deployment. Its primary commercial purpose is to reduce customer acquisition costs by collapsing the technical distance between campaign conception and live deployment. Cloud-based SaaS deployment models now capture the dominant share of new subscriptions, while self-service configurations with pre-built templates represent the fastest-growing service tier as solopreneurs and lean marketing teams bypass agency intermediaries. Enterprise-grade API integration capabilities concentrate margin pools, since large organizations pay premiums for CRM and ad-platform connectivity rather than base editor functionality.
GDPR enforcement by European data protection authorities and the EU AI Act's risk-classification rules shape how landing page builders handle lead data and algorithmic personalization across European deployments. The Federal Trade Commission in the United States scrutinizes deceptive design patterns in conversion interfaces, pressuring vendors to distinguish persuasive optimization from manipulative dark-pattern tactics. Stakeholders must monitor whether emerging privacy legislation fragments template personalization capabilities or consolidates compliance tooling as a bundled premium feature.
Market Dynamics
Modular bundling of landing page tools with adjacent marketing automation is pivoting buyer choice away from standalone point solutions, compressing margins for pure-play vendors while rewarding ecosystem orchestrators.
Growth Catalysts
- EU AI Act Risk Classification:Compliance mandates for algorithmic transparency in customer-facing tools are creating demand for built-in audit trails and explainable personalization engines.
- E-commerce Retailer Expansion:Digital storefront operators seeking conversion-optimized pages are driving subscription volume for drag-and-drop builders with native A/B testing.
- Cloud SaaS Deployment:Self-service configurations with pre-built templates are accelerating adoption among solopreneurs and lean marketing teams bypassing agency intermediaries.
Market Restraints
- GDPR Enforcement Complexity:European data protection authorities are imposing fines that increase operational overhead for lead data handling and cross-border transfers.
- Input Cost Volatility:Cloud infrastructure pricing from hyperscale providers creates margin pressure for vendors offering unlimited bandwidth tiers.
- Template Saturation:Homogenized design libraries reduce differentiation, forcing continuous creative production costs without commensurate pricing power.
Strategic Opportunities
- API-First Enterprise Integration:CRM and ad-platform connectivity capabilities command premium pricing from large organizations seeking workflow consolidation.
- Vertical Template Specialization:Service-sector micro-businesses in healthcare, legal, and real estate represent underpenetrated segments requiring industry-specific compliance features.
- CSRD Reporting Alignment:The EU Corporate Sustainability Reporting Directive creates demand for carbon-footprint dashboards embedded within marketing operations platforms.
Industry Challenges
- Conversion Optimization Talent Scarcity:Shortage of practitioners skilled in statistical experimental design limits customer success and expansion revenue.
- Dark Pattern Regulatory Scrutiny:FTC enforcement against deceptive interface design requires legal review cycles that slow product release velocity.
- Legacy CMS Migration Friction:Enterprises face integration complexity when replacing entrenched content management systems with specialized landing page infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Landing Page Builders Market |
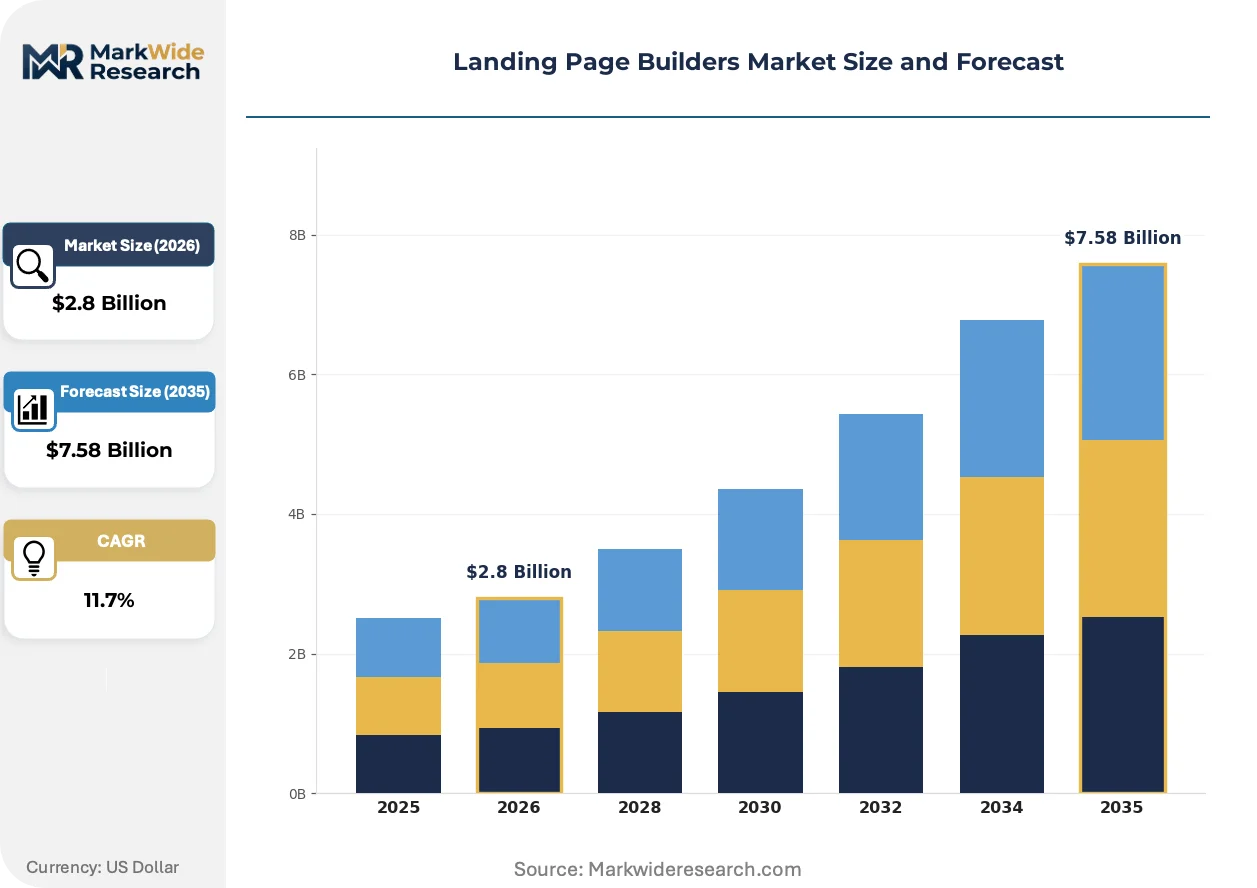
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Self-Service, Full-Service, Hybrid, Template-Based Deployment Model: Cloud, On-Premises, SaaS, CMS Integration Customer Type: Small Businesses, Enterprises, Marketing Agencies, Freelancers Integration Level: API Integration, Plug-In Support, Third-Party Compatibility, Webhooks |
| Companies Covered | Landingi, ClickFunnels, Unbounce, Swipe Pages, GetResponse, Leadpages, HubSpot, Wix, Instapage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Landing Page Builders Market Shifts & Advancements
Generative AI is compressing the production timeline between campaign conception and live deployment, while regulatory pressure on algorithmic decision-making is reshaping how personalization engines operate.
Natural language generation is automating copy production for variant testing at scale. Mid-market agencies are adopting these tools fastest, collapsing the hours required to launch multi-cell experiments from days to minutes. This capability is automating the traditional copywriter role and shifting vendor value toward orchestration rather than content creation.
The EU AI Act's risk-classification framework is mandating human oversight for high-risk automated decision systems. Landing page builders deploying algorithmic personalization must now implement audit logging and explainability features. European deployments face the strictest compliance timelines, with vendors racing to embed governance tooling before enforcement escalates.
Subscription fatigue among lean marketing teams is compressing switching cycles and favoring usage-based pricing over fixed-seat models. Self-service buyers are abandoning annual contracts for monthly flexibility, forcing vendors to front-load value demonstration. This pattern is most visible in the United States, where SaaS saturation has trained buyers to expect frictionless onboarding and immediate ROI validation.
Landing Page Builders Market Segmentation
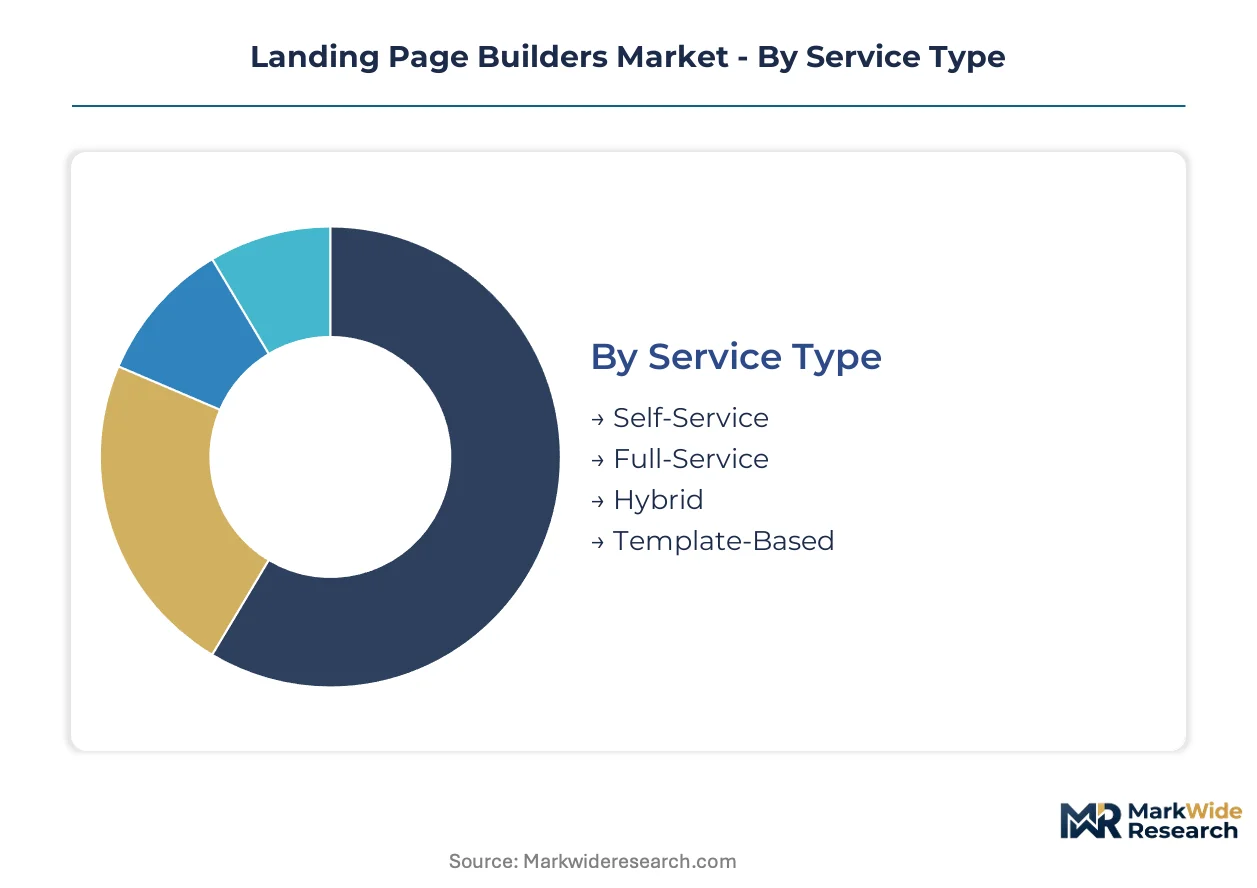
Segmentation in landing page builders reveals how compliance burdens, integration complexity, and buyer sophistication stratify purchasing patterns. Vendors must align certification requirements and deployment architectures with the operational maturity of each buyer cohort.
Service Type:
GDPR and EU AI Act obligations concentrate most heavily on full-service and hybrid offerings, where vendors control data processing pipelines and algorithmic personalization engines. Self-service tiers shift liability to end-users but impose lighter audit requirements.
- Self-Service:Drag-and-drop interfaces with pre-built templates enable solopreneurs and lean marketing teams to deploy pages without agency intermediaries. Demand clusters among US-based micro-businesses seeking monthly billing flexibility and immediate ROI validation.
- Full-Service:Managed deployments include compliance consulting, custom development, and dedicated support infrastructure. European enterprises facing GDPR enforcement complexity and FTC scrutiny of dark patterns drive premium subscriptions for legal review cycles and audit documentation.
- Hybrid:Blends self-service tooling with on-demand professional services for campaign optimization. Healthcare and legal verticals in Germany and France require this model for industry-specific consent management.
- Template-Based:Pre-designed libraries with limited customization suit cost-conscious freelancers and early-stage ventures. Template saturation pressures margins without commensurate pricing power.
Self-Service sits at the top of the volume ranking, with Hybrid climbing the fastest.
Deployment Model:
Cost tiering separates cloud and SaaS offerings—operating on usage-based or seat-based subscriptions—from capital-intensive on-premises installations requiring dedicated infrastructure teams.
- Cloud:Hyperscale-hosted deployments with elastic bandwidth scaling dominate new subscriptions. US SaaS adoption rates and digital marketing spend sustain structural demand elevation.
- On-Premises:Air-gapped installations serving financial services and government contractors in Switzerland and Germany with data sovereignty mandates. High upfront licensing and maintenance contracts compress addressable market.
- SaaS:Multi-tenant architectures with automatic updates and shared compliance tooling. E-commerce retailers across the United Kingdom and Netherlands favor this model for conversion-optimized storefront deployment speed.
- CMS Integration:Embedded modules within WordPress, Drupal, or proprietary enterprise content systems. Legacy CMS migration friction limits expansion among entrenched Fortune 500 installations.
SaaS sits at the top of the volume ranking, with CMS Integration expanding most quickly as enterprises seek workflow consolidation.
Customer Type:
Margin pools concentrate where procurement sophistication meets integration complexity—enterprises and agencies pay premiums for API connectivity rather than base editor functionality.
- Small Businesses:Price-sensitive operators prioritizing freemium entry points and vertical template libraries. Wix and similar platforms compete aggressively for this cohort through aggressive distribution.
- Enterprises:Large organizations requiring CRM and ad-platform connectivity, governance tooling, and dedicated customer success. API-first integration capabilities command substantial pricing premiums.
- Marketing Agencies:Mid-market service providers managing multi-client campaigns with white-label requirements. Conversion optimization talent scarcity limits customer success and expansion revenue in this segment.
- Freelancers:Independent practitioners seeking project-based billing and rapid deployment without long-term commitments. Subscription fatigue compresses switching cycles toward monthly flexibility.
Small Businesses sit at the top of the volume ranking, with Enterprises gaining share fastest on integration premiums.
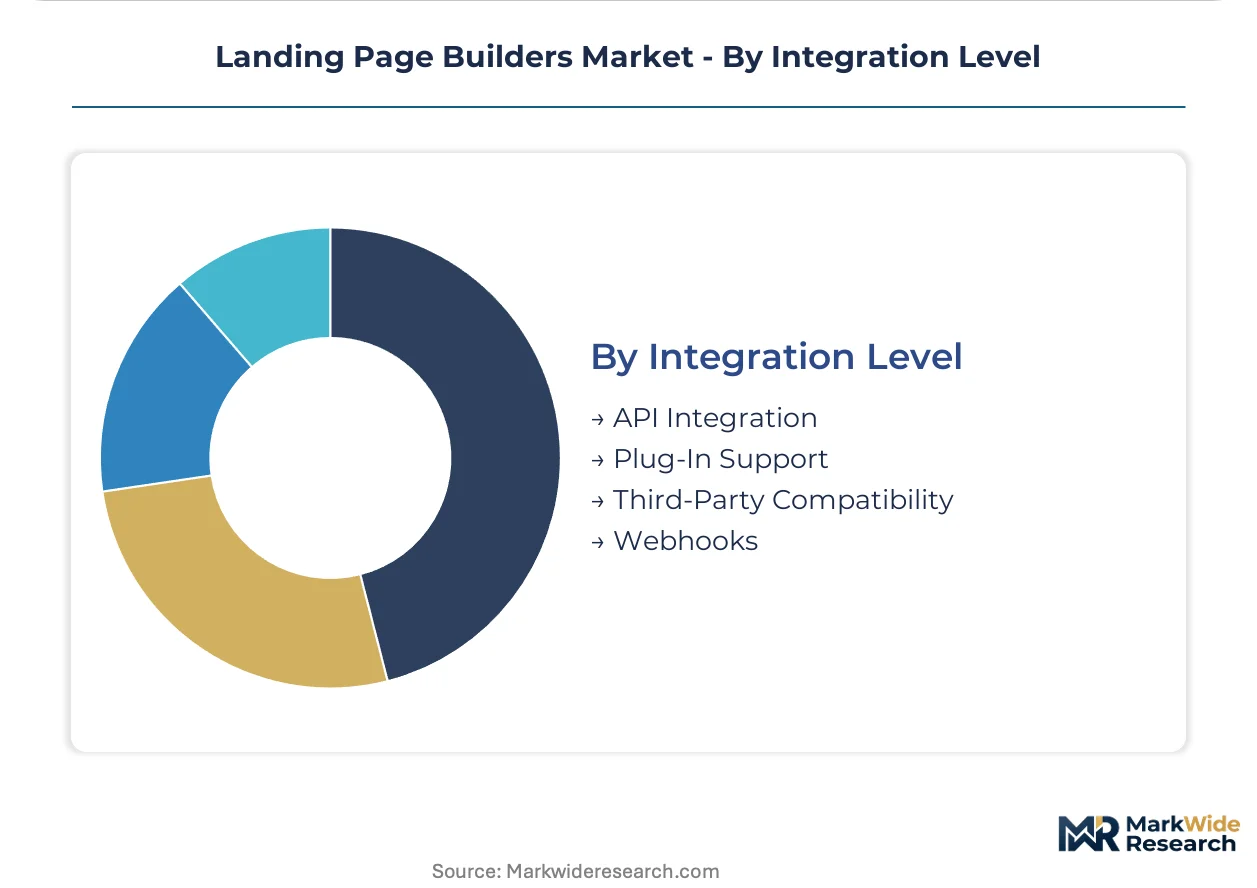
Integration Level:
Technical maturity determines which connectivity architectures buyers can operationalize—simpler plug-in support serves resource-constrained teams while API and webhook implementations demand engineering investment.
- API Integration:RESTful and GraphQL endpoints enabling bidirectional data flow with Salesforce, HubSpot, and ad platforms. Enterprise-grade implementations require explainable personalization engines under EU AI Act risk classification.
- Plug-In Support:Pre-built connectors for email marketing, analytics, and payment processors. Small business adoption concentrates in the United States where SaaS saturation trains buyers toward frictionless onboarding.
- Third-Party Compatibility:Certification against interoperability standards including OAuth 2.0 and SCIM provisioning. Marketing agencies in the United Kingdom and Canada prioritize this for multi-tool stacks.
- Webhooks:Event-driven callbacks triggering external workflows and real-time lead routing. E-commerce operators leverage these for inventory-synced promotional page deployment.
Plug-In Support sits at the top of the volume ranking, with API Integration climbing the fastest on enterprise workflow consolidation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The landing page builder industry traces its commercial origins to North American software incubators in the early 2010s, where conversion-rate optimization methodologies first merged with cloud-hosted visual editing interfaces.
United States
SaaS adoption rates and digital marketing expenditure sustain the deepest subscription base worldwide. FTC enforcement against deceptive design patterns pressures vendors to distinguish persuasive optimization from manipulative dark-pattern tactics. Silicon Valley and New York City host the densest concentration of mid-market agencies deploying multi-client campaign infrastructure.
Germany
Data sovereignty mandates and industrial B2B marketing sophistication drive demand for GDPR-compliant deployment architectures. The national data protection regulator imposes strict audit requirements for algorithmic personalization engines under EU AI Act risk classification. Berlin and Munich anchor the largest clusters of marketing technology consultancies serving DAX-listed enterprises.
United Kingdom
E-commerce retailer expansion and fintech marketing operations generate substantial drag-and-drop builder subscriptions. The Information Commissioner's Office enforces lead data handling standards that elevate compliance tooling premiums. London's Shoreditch and Manchester's Northern Quarter concentrate venture-backed SaaS procurement teams.
France
Healthcare and legal verticals require hybrid service models combining self-service tooling with on-demand professional support. CNIL enforcement of consent management protocols shapes product roadmaps for European deployments. Paris and Lyon host specialized agencies serving regulated industries with industry-specific template libraries.
India
Lean marketing teams and solopreneur expansion accelerate freemium adoption among price-sensitive operators. The country's central bank guidelines on digital payment integration influence checkout-page builder specifications. Bangalore and Mumbai concentrate the fastest-growing cohort of independent practitioners seeking monthly billing flexibility.
Landing Page Builders Market Competitive Landscape
The competitive structure tilts toward ecosystem orchestrators over standalone point solutions. Consolidation pressure compresses margins for pure-play vendors while rewarding platforms with adjacent marketing automation bundling. Three archetypes dominate: conversion intelligence specialists, freemium distribution platforms, and CRM-embedded ecosystem players. Strategic moves concentrate on API-first integration capabilities and vertical template specialization rather than base editor functionality expansion.
Within the conversion intelligence tier, Unbounce and Instapage exemplify premium positioning through deep specialization in A/B testing infrastructure. HubSpot anchors the ecosystem-play archetype by embedding page builders within broader CRM workflow orchestration. Wix occupies a position at the scale-driven freemium end, competing through aggressive distribution and vertical template libraries for service-sector micro-businesses.
| Leading Market Players |
|---|
| Landingi |
| ClickFunnels |
| Unbounce |
| Swipe Pages |
| GetResponse |
| Leadpages |
| HubSpot |
| Wix |
| Instapage |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up specialists controlling mid-market agency portfolios enforce pricing discipline through centralized procurement of cloud infrastructure and shared compliance tooling. Their ownership concentration compresses vendor margins while amplifying buyer leverage across pooled subscription negotiations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates API-first enterprise suites from self-service monthly subscriptions and freemium entry points. Price differentiation hinges on integration complexity and GDPR certification tier. Pricing pressure stems from hyperscale cloud bandwidth volatility forcing unlimited-tier vendors toward usage-based metering. Small businesses exhibit acute price sensitivity, while enterprises absorb premiums for CRM connectivity and audit documentation.
Supply Chain Analysis
Returns and refurbishment flows are minimal in pure software delivery, though customer churn generates re-engagement costs that vendors treat as reverse-logistics overhead. Supply concentrates in United States hyperscale cloud regions, Ireland GDPR-compliant data centers, and Singapore Asia-Pacific nodes. Raw material dependencies include compute silicon from Taiwan, storage components from South Korea, and undersea cable bandwidth from Japan. Single-source vulnerability in hyperscale provider concentration threatens margin stability. Distribution runs through direct self-service portals and agency channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds steadily as digital storefront expansion sustains recurring subscription demand across e-commerce verticals.
For Market Incumbents: Acquire conversion optimization talent pools to offset practitioner scarcity limiting customer success revenue. Consolidate API-first integration capabilities to defend against CRM-embedded ecosystem players. Capacity addition in Germany and France addresses GDPR enforcement complexity elevating compliance premiums. Certification investment in EU AI Act audit tooling creates switching costs against point-solution competitors. For New Entrants and Emerging Players: EU AI Act risk classification in Germany and France opens a window for explainable personalization engines with built-in governance tooling. Target healthcare and legal verticals requiring hybrid service models with industry-specific consent management. White-space exists in carbon-footprint dashboards aligned with CSRD reporting obligations. Go-to-market through specialized marketing technology consultancies serving DAX-listed enterprises accelerates trust formation. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play conversion intelligence specialists facing ecosystem bundling pressure. Long-term viability favors platforms with backward integration into adjacent marketing automation rather than standalone page builders. Acquisition target archetype: mid-market agencies with white-label infrastructure and multi-client campaign orchestration. Signal to watch: FTC enforcement escalation against dark-pattern tactics forcing legal review cycle investments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding page builders within HubSpot CRM workflows consolidates vendor ecosystems and raises switching costs. |
| Acquisition of Specialist Firm | Purchasing A/B testing boutiques addresses conversion optimization talent scarcity constraining agency expansion revenue. |
| Geographic Expansion | Establishing GDPR-compliant data centers in Ireland and Germany captures European enterprise procurement mandates. |
| Product Launch | Introducing explainable personalization engines satisfies EU AI Act audit trail requirements before enforcement escalates. |
| Strategic Partnership | Alliances with hyperscale cloud providers stabilize bandwidth pricing for unlimited-tier subscription offerings. |
Research Methodology
Direct dialogue with CMOs at mid-market agencies, SaaS procurement officers at e-commerce retailers, compliance leads at European enterprises, and integration specialists at CRM platforms grounded qualitative insights. Secondary validation drew from SEC filings of publicly traded marketing technology vendors, hyperscaler capex disclosures, GDPR enforcement action databases, and EU AI Act implementation guidance documents. Bottom-up subscription volume estimates and top-down digital marketing spend allocations were triangulated for cross-verification.
Segmented outputs across deployment models, service tiers, customer types, and integration levels were generated across the analysis window. CAGRs were derived from elasticity modeling against digital storefront expansion rates and SaaS adoption curves. Industry-specific inputs included FTC dark-pattern enforcement velocity, EU AI Act compliance timeline assumptions, and cloud infrastructure pricing trajectories from hyperscale provider announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated GDPR fine escalation or hyperscale bandwidth price shocks. Practitioners should monitor FTC guidance releases and EU AI Act delegated act publications for early signals of regulatory trajectory shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Web Real Time Communication Solution Market
Digital Solutions
Global Advocacy Software Market
Digital Solutions
Foot Traffic and Customer Location Intelligence Solution Market
Digital Solutions
Mainframe Modernization Services Market
Digital Solutions
Europe Warranty Management System Market
Digital Solutions
Video Management System Market
Digital Solutions
India PLM Market
Digital Solutions
Container Management Software Market
Digital Solutions
Community Engagement Software Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Asia Pacific Smart Card Market
Digital Solutions
Workspace As a Service Market
Digital Solutions
Digital Dispenser Systems Market
Digital Solutions
Asia-Pacific API Management Market