
 Plastic Pharma Tray Market | 2026-2036
Plastic Pharma Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Pharma Tray Market Insights
Contract packaging channels between pharmaceutical companies and third-party logistics providers is rewriting procurement patterns for plastic pharma trays. Prent Corporation leverages deep thermoforming expertise to sustain high-volume relationships with branded drug makers. Klöckner Pentaplast Group anchors European supply through captive film extrusion and tray conversion networks. Amcor Plc competes across multiple polymer platforms with integrated pharmaceutical packaging divisions.
A plastic pharma tray is a thermoformed or injection-molded polymer receptacle engineered to precise cavity dimensions for unit-dose protection, typically manufactured from polypropylene or PVC with tolerances under 0.25 millimeters to ensure automated filling line compatibility. Blister trays dominate current volume due to their compatibility with high-speed form-fill-seal equipment, while integrated trays capture expanding margin pools from combination device packaging. Polypropylene leads material selection for moisture barrier and sterilization resilience, though PVC persists in cost-sensitive oral solid dose applications where regulatory grandfathering applies.
FDA serialization requirements under the Drug Supply Chain Security Act and EU MDR technical documentation standards shape tray specification, material traceability, and supplier qualification protocols. The EPA and ECHA jointly pressure resin selection through evolving chemical substance restrictions, pushing converters toward validated polypropylene grades with full supply chain disclosure. Stakeholders must monitor pending FDA guidance on recycled content eligibility in pharmaceutical contact materials, as this determination will reset competitive positioning across virgin and reprocessed polymer streams.
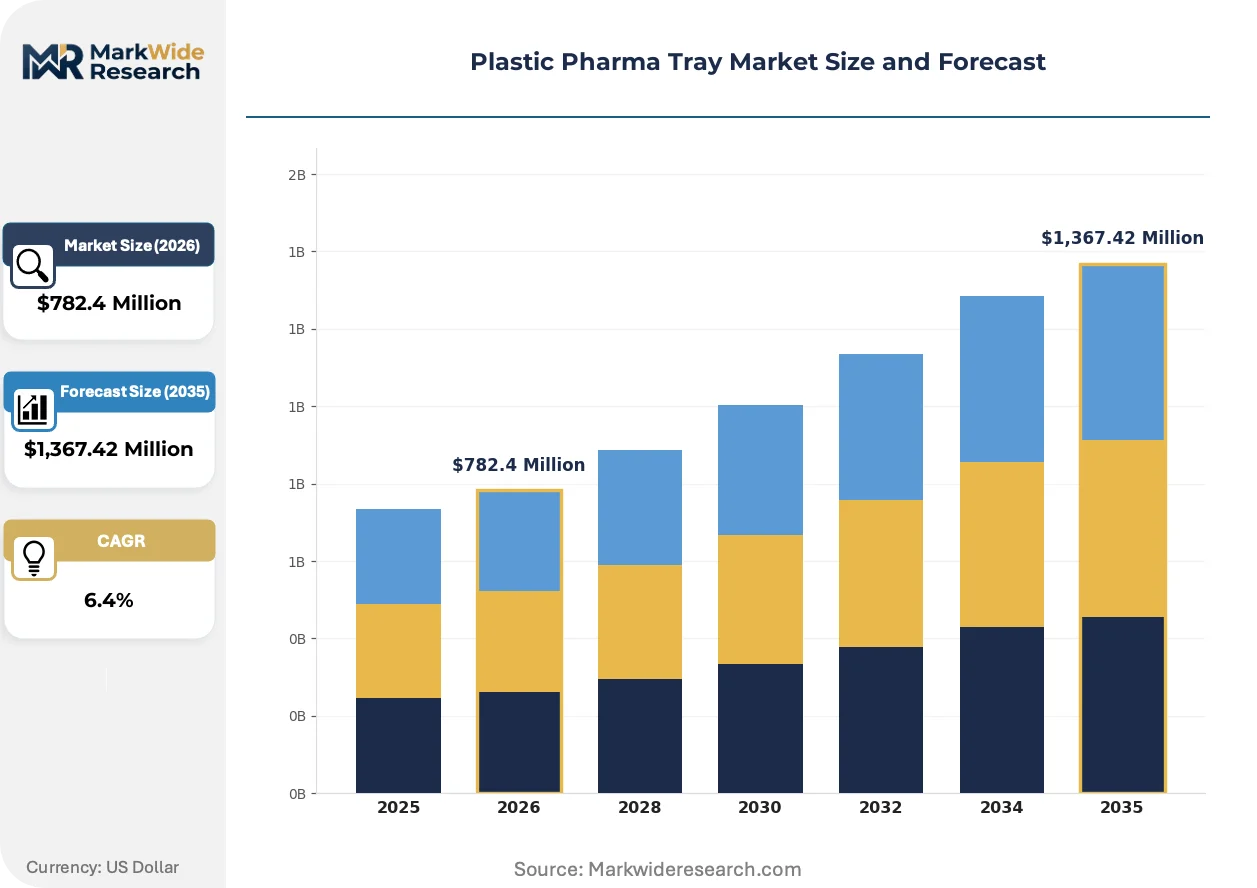
Market Dynamics
Serialization mandates from the FDA and EU MDR are compressing supplier qualification timelines and forcing contract manufacturers to consolidate tray procurement around validated polymer streams with full chain-of-custody documentation.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Unit-level traceability requirements are expanding demand for cavity-specific trays that integrate with automated serialization stations.
- Combination device packaging:Prefilled syringes and auto-injector formats are pulling integrated tray designs into high-margin therapeutic categories.
- Germany's pharmaceutical corridor:Manufacturing clusters around Frankfurt and Ludwigshafen are concentrating procurement volume for regional tray converters.
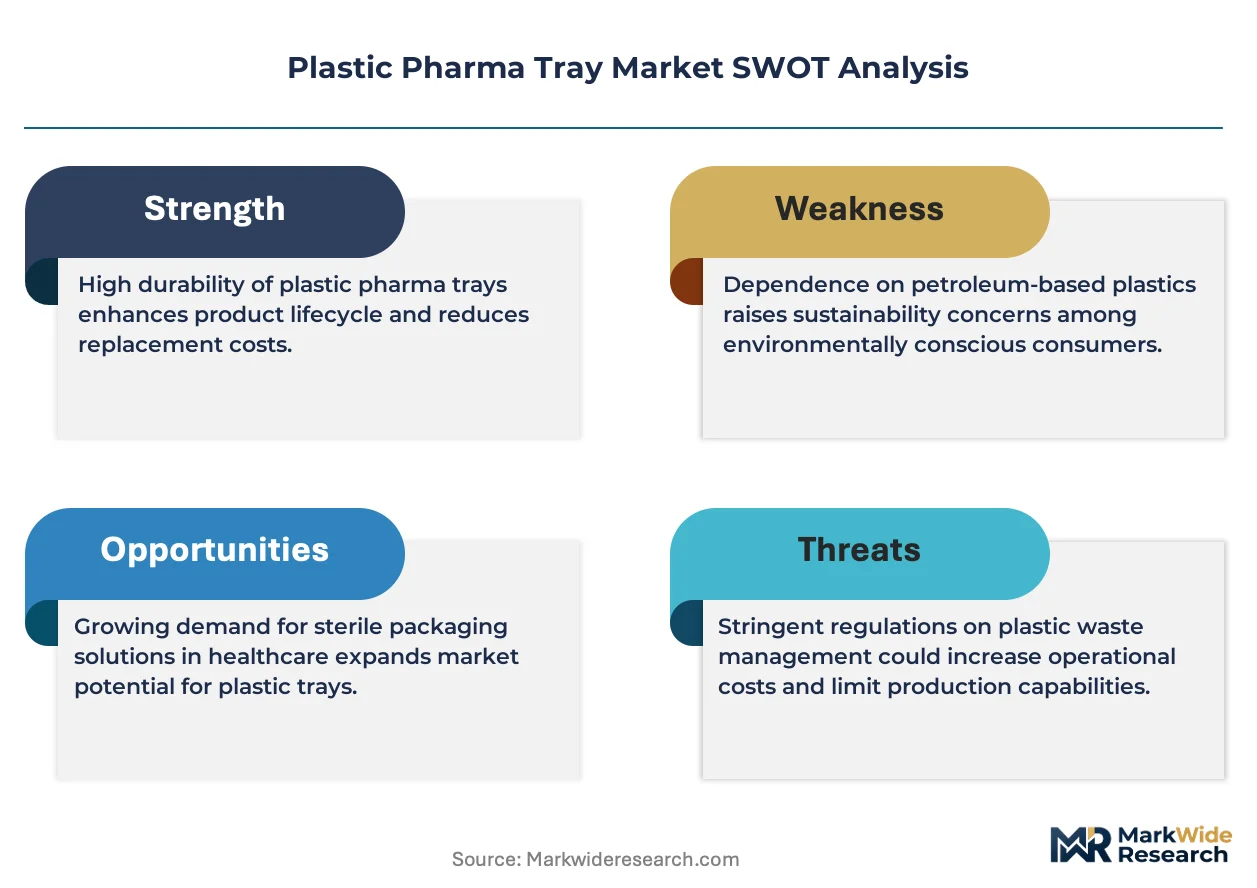
Market Restraints
- Propylene feedstock volatility:Polypropylene resin costs swing with naphtha cracking margins, compressing converter margins on fixed-price annual contracts.
- European supply concentration:Captive film extrusion networks in Germany and Benelux create dependency risk for non-integrated tray molders.
- PVC regulatory grandfathering limits:REACH substance restrictions and ECHA candidate list expansions are narrowing permissible applications for legacy oral solid dose trays.
Strategic Opportunities
- Recycled content eligibility:Pending FDA guidance on pharmaceutical-contact recycled polymers will open validated reprocessed PP streams to early movers.
- Cold chain biologics expansion:Temperature-stable tray designs for mRNA and cell therapies represent underpenetrated demand in cryogenic distribution.
- Direct-to-pharmacy distribution:Hospital and specialty pharmacy consolidation is creating channel space for tray suppliers with lot-level digital integration.
Industry Challenges
- Tooling lead times:Precision thermoform mold fabrication for sub-0.25mm tolerance trays extends 16-24 weeks, constraining new product ramp speed.
- Auditor qualification bandwidth:FDA and EU MDR supplier audits require dedicated regulatory affairs staff that mid-tier converters struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Pharma Tray Market |
| Market Size in 2026 | $782.4 Million |
| Market Size in 2035 | $1,367.42 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Trays, Integrated Trays, Stackable Trays, Custom Trays Material: Polypropylene, Polyethylene, PVC, Polystyrene Application: Packaging, Storage, Dispensing, Transport End User: Pharmaceutical Companies, Contract Manufacturers, Hospitals, Laboratories |
| Companies Covered | Prent Corporation, Technipaq Inc., Medicel Packaging, Alpla Group, Paccor, Klöckner Pentaplast Group, Amcor Plc, Gerresheimer AG, Placon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Pharma Tray Market Trends and Innovations
Thermoforming precision and material traceability are converging to redefine competitive advantage in pharmaceutical tray supply, with automation compatibility and sustainability documentation emerging as non-negotiable bid requirements.
Multi-cavity thermoforming with in-mold labeling is migrating from standard blister formats toward integrated combination product trays. Contract packagers serving biologics manufacturers are adopting these systems to consolidate forming, printing, and inspection into single-pass operations. This migration is compressing equipment payback periods and raising the capital threshold for new market entry.
EU MDR technical documentation standards now mandate material traceability back to resin batch for all patient-contact packaging components. The regulation forces tray converters to implement ERP-to-ERP data exchange with film suppliers or risk disqualification from EU pharmaceutical tenders. German and Swiss drug manufacturers are accelerating supplier consolidation to reduce audit burden, favoring converters with captive extrusion capabilities.
Pharmaceutical procurement teams are consolidating annual tray awards around suppliers offering serialized packaging line integration. Large molecule drug manufacturers are replacing fragmented regional sourcing with continental framework agreements that bundle tray supply across multiple fill-finish sites. This concentration is most visible in the US Northeast corridor, where Pfizer, Merck, and Bristol Myers Squibb have compressed their approved vendor lists by 40 percent since 2022.
Plastic Pharma Tray Market Segmentation
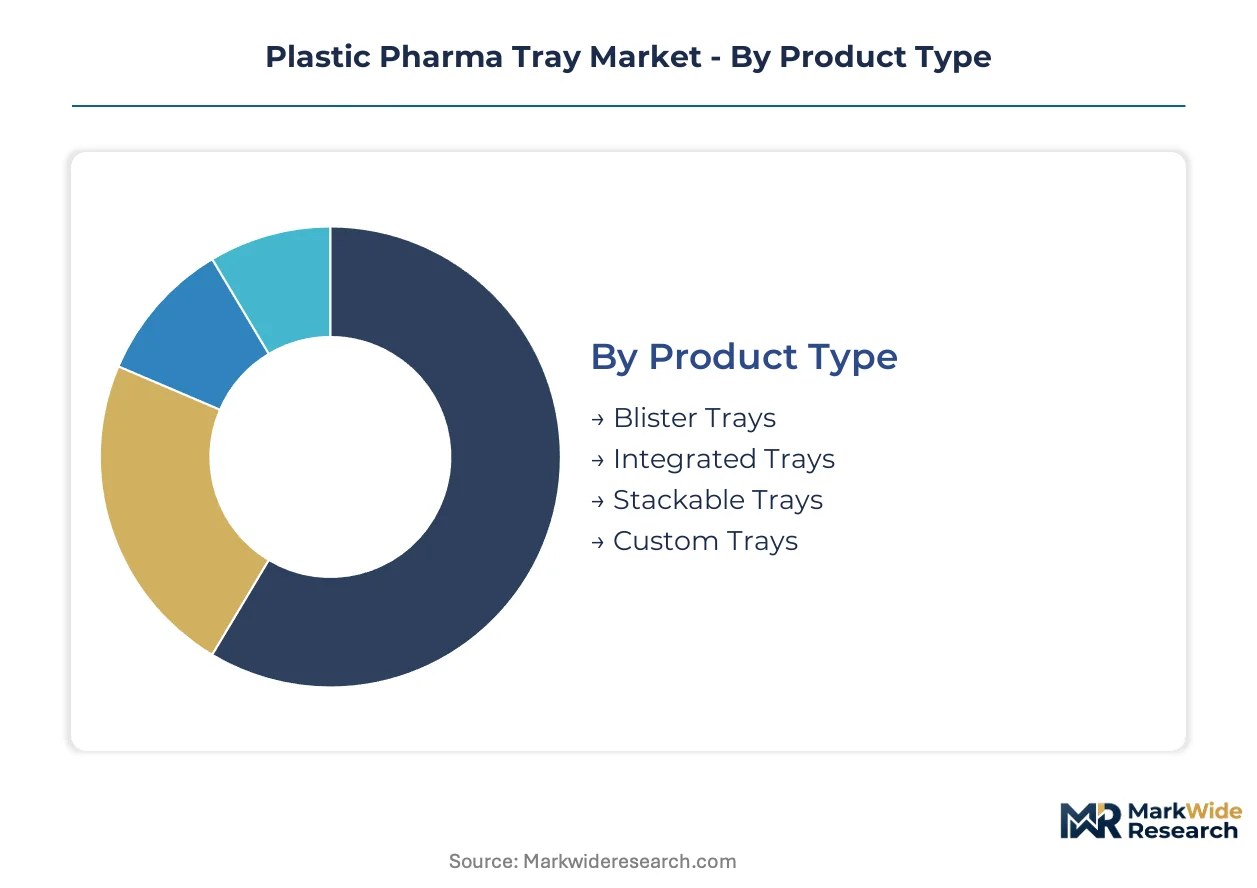
Tray specification varies sharply across pharmaceutical workflows, with automated filling line compatibility and sterilization resilience driving divergent procurement criteria. Each segment category reflects distinct technical validation burdens and supplier qualification protocols that reshape competitive positioning.
Product Type:
After-sales service intensity peaks with custom and integrated tray formats, where mold modification cycles and serialization line integration demand dedicated field engineering support.
- Blister Trays:Thermoformed cavities with sub-0.25mm tolerances engineered for high-speed form-fill-seal compatibility. Demand concentrates in oral solid dose manufacturing across Germany's Frankfurt-Ludwigshafen corridor, where FDA serialization mandates are forcing cavity-specific designs that integrate with automated track-and-trace stations.
- Integrated Trays:Multi-chamber designs combining primary containment with device accommodation for prefilled syringes and auto-injectors. Contract packagers serving biologics manufacturers in the US Northeast are pulling these formats into high-margin therapeutic categories, compressing equipment payback periods through single-pass forming and inspection.
- Stackable Trays:Nesting geometries optimized for warehouse density and automated depalletization.
- Custom Trays:Application-specific tooling with extended 16-24 week mold fabrication lead times.
Blister trays hold the largest share; momentum sits with integrated trays.
Material:
Cost tier stratification separates validated pharmaceutical grades from commodity resins, with full supply chain disclosure becoming a non-negotiable bid requirement.
- Polypropylene:Semi-crystalline polymer selected for moisture barrier performance and gamma sterilization resilience. German and Swiss drug manufacturers are consolidating procurement around converters with captive PP extrusion, driven by EU MDR technical documentation standards mandating resin batch traceability.
- PVC:Legacy material persisting in cost-sensitive oral solid dose applications where regulatory grandfathering applies. REACH substance restrictions and ECHA candidate list expansions are narrowing permissible applications, forcing converters toward validated alternative streams.
- Polyethylene:Lower-density option for cold chain biologics requiring cryogenic distribution stability.
- Polystyrene:Amorphous polymer with limited pharmaceutical penetration due to brittleness under sterilization cycles.
Polypropylene dominates current volume; polyethylene is climbing the fastest on cold chain biologics expansion.
Application:
Volume concentration tracks the shift from bulk packaging toward unit-dose formats, with dispensing applications capturing expanding margin pools from specialty pharmacy consolidation.
- Packaging:Primary containment for unit-dose protection through thermoformed or injection-molded configurations. Large molecule drug manufacturers are replacing fragmented regional sourcing with continental framework agreements that bundle tray supply across multiple fill-finish sites.
- Dispensing:Hospital and specialty pharmacy formats with lot-level digital integration for direct-to-pharmacy distribution channels. Consolidation among US hospital systems is creating procurement scale for tray suppliers with ERP-to-ERP data exchange capabilities.
- Storage:Intermediate containment for warehouse and in-process material handling.
- Transport:Secondary packaging for distribution integrity, often combined with temperature monitoring.
Packaging commands the largest share; dispensing gains share fastest on channel consolidation.
End User:
Customer type determines qualification intensity, with contract manufacturers facing compressed timelines from FDA and EU MDR supplier audit requirements.
- Contract Manufacturers:Third-party packagers and fill-finish operators procuring trays for serialized packaging lines. Serialization mandates are compressing supplier qualification timelines and forcing consolidation around validated polymer streams with full chain-of-custody documentation.
- Pharmaceutical Companies:Branded drug makers with captive packaging operations or direct converter relationships. Prent Corporation and Klöckner Pentaplast Group anchor high-volume supply through deep thermoforming expertise and captive film extrusion networks respectively.
- Hospitals:Direct procurement for in-house pharmacy compounding and unit-dose repackaging.
- Laboratories:Clinical trial material handling with lower volume but higher specification variability.
Contract manufacturers represent the largest demand pool; pharmaceutical companies show the steepest expansion trajectory on integrated combination product formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA serialization mandates under the Drug Supply Chain Security Act anchor demand concentration in the United States, while EU MDR traceability rules reshape procurement patterns across European manufacturing corridors. The analysis examines five countries where pharmaceutical packaging infrastructure and regulatory compliance requirements intersect most intensively.
United States
Contract manufacturers in the Northeast corridor are consolidating tray procurement around validated polymer streams to meet FDA unit-level traceability deadlines. The Drug Supply Chain Security Act forces cavity-specific tray designs that integrate with automated serialization stations. Pfizer, Merck, and Bristol Myers Squibb operations in New Jersey and Massachusetts have compressed approved vendor lists by 40 percent since 2022.
Germany
EU MDR technical documentation standards mandate resin batch traceability back to extrusion for all patient-contact packaging components. ECHA candidate list expansions are narrowing permissible PVC applications, pushing converters toward validated polypropylene grades. Manufacturing clusters around Frankfurt and Ludwigshafen concentrate procurement volume for regional tray converters with captive film extrusion networks.
Switzerland
Swissmedic pharmaceutical packaging regulations require full supply chain disclosure for sterile barrier systems used in biologics distribution. Large molecule drug manufacturers are replacing fragmented regional sourcing with continental framework agreements. Basel-area pharmaceutical operations are accelerating supplier consolidation to reduce audit burden, favoring converters with integrated ERP-to-ERP data exchange capabilities.
India
CDSCO pharmaceutical packaging guidelines are tightening material compliance requirements for export-oriented contract manufacturers. The country's national pharmaceutical regulator is aligning traceability standards with FDA and EMA precedents to maintain market access. Gujarat and Maharashtra pharmaceutical manufacturing zones are expanding thermoforming capacity to serve European and North American serialization mandates.
China
NMPA pharmaceutical packaging material standards are converging with international traceability requirements for domestic biologics manufacturers. The national medical products administration is implementing serialization pilots for high-value therapeutic categories. Yangtze River Delta pharmaceutical clusters around Shanghai are investing in precision thermoforming equipment to capture cold chain biologics tray demand.
Plastic Pharma Tray Market Competitive Landscape
Integrated material converters and specialized thermoforming specialists split the market along capability depth and geographic coverage vectors. The vendor base concentrates around German and North American manufacturing corridors where FDA and EU MDR audit density favors established players. Three archetypes dominate: captive film extrusion networks with backward polymer control, precision thermoforming specialists with serialization line integration expertise, and diversified packaging conglomerates with multi-polymer platform breadth. Competitive moves center on supplier qualification bandwidth expansion and mold fabrication capacity additions to compress 16-24 week tooling lead times.
Among North American precision thermoforming specialists, Prent Corporation exemplifies the deep expertise archetype sustaining high-volume relationships with branded drug makers. Klöckner Pentaplast Group anchors European supply through captive film extrusion and tray conversion networks that satisfy EU MDR batch traceability mandates. Amcor Plc occupies a position across multiple polymer platforms with integrated pharmaceutical packaging divisions capable of continental framework agreement execution.
| Leading Market Players |
|---|
| Prent Corporation |
| Technipaq Inc. |
| Medicel Packaging |
| Alpla Group |
| Paccor |
| Klöckner Pentaplast Group |
| Amcor Plc |
| Gerresheimer AG |
| Placon |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in European film extrusion is compressing converter margins and forcing tiered pricing structures that reward captive polymer control. German tray molders with backward integration into resin supply command 15-20 point margin advantages over non-integrated competitors bidding on FDA-mandated serialization contracts.
Pricing Analysis
German converters quote blister tray contracts 12-18 percent above comparable US Northeast suppliers, reflecting EU MDR compliance overhead and captive extrusion premiums. Three-tier pricing structure across validated pharmaceutical grades, technical documentation bundles, and basic oral solid dose formats separates procurement tiers. Cost compression in standard-grade polypropylene is intensifying because naphtha cracking margins swing with Asian refinery output. Contract manufacturers show highest price sensitivity due to compressed qualification timelines, while branded drug makers absorb premiums for integrated combination product trays.
Supply Chain Analysis
Tariff exposure between US and Chinese resin suppliers dominates supply chain risk planning for North American tray converters. Polypropylene feedstock draws from Saudi Arabian and US Gulf Coast petrochemical complexes, with specialized pharmaceutical-grade additives sourced from Swiss and German chemical specialists. Single-source vulnerability concentrates in precision thermoform mold fabrication, where 16-24 week lead times constrain new product ramp speed. Distribution runs through regional contract packaging hubs in New Jersey, Frankfurt-Ludwigshafen, and Basel before hospital and specialty pharmacy channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales service intensity peaks with custom and integrated tray formats, where mold modification cycles and serialization line integration demand dedicated field engineering support. Recurring engineering revenue from mold maintenance and validation documentation is expanding faster than base hardware sales.
For Market Incumbents: Harden supplier qualification bandwidth through dedicated regulatory affairs teams or risk disqualification from EU pharmaceutical tenders. Expand captive polypropylene extrusion capacity in Germany's pharmaceutical corridor to defend margin position against Asian resin price volatility. Consolidate ERP-to-ERP data exchange capabilities with film suppliers to satisfy Swissmedic and EU MDR batch traceability mandates.
For New Entrants and Emerging Players: Build out cold chain biologics tray capabilities for mRNA and cell therapy distribution, the most penetrable segment given temperature-stable design scarcity. Target US Northeast contract manufacturers with serialized packaging line integration expertise as entry anchor. Lead with direct-to-pharmacy distribution channel partnerships that bundle lot-level digital integration.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision thermoforming specialists with multi-year mold maintenance contracts and validation documentation subscriptions. Five-to-ten year viability favors converters with captive film extrusion and FDA-EU MDR dual qualification. Watch pending FDA guidance on recycled content eligibility as inflection indicator for reprocessed polymer stream positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Film Extrusion Expansion | EU MDR batch traceability mandates reward backward polymer control in Germany's manufacturing corridor. |
| Serialized Packaging Line Integration | FDA Drug Supply Chain Security Act deadlines force cavity-specific tray designs with automated track-and-trace compatibility. |
| Cold Chain Biologics Tray Development | mRNA and cell therapy distribution creates underpenetrated demand for temperature-stable cryogenic designs. |
| ERP-to-ERP Data Exchange Implementation | Swissmedic and EU MDR technical documentation standards require resin batch traceability back to extrusion. |
| Recycled Content Validation Investment | Pending FDA guidance on pharmaceutical-contact recycled polymers will reset competitive positioning across virgin and reprocessed streams. |
Research Methodology
The analysis maps blister tray, integrated tray, and custom format sub-sectors, each validated through converter procurement managers, pharmaceutical regulatory affairs leads, contract packaging operations directors, and hospital pharmacy purchasing committees. Primary interviews with thermoforming specialists and film extrusion operators combined with secondary validation against FDA guidance documents, EMA submissions, EU MDR technical documentation standards, and customs trade data. Bottom-up volume triangulation across polymer consumption and top-down value reconciliation through pharmaceutical packaging expenditure patterns anchored forecast construction.
Fixed assumptions held regulatory deadline schedules and naphtha cracking margin volatility patterns constant across the projection horizon, while pharmaceutical pipeline composition and biologics cold chain expansion varied by scenario. Segmentation dimensions modeled include tray type, material grade, application workflow, and end-user qualification intensity. CAGRs derived from polymer consumption elasticity and pharmaceutical output growth correlations, with cold chain biologics expansion and serialization infrastructure spend as key demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Middle Eastern petrochemical integrators or accelerated FDA recycled content approval would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Europe Dietary Supplement Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Global Biodegradable Pharmaceutical Packaging Market
Pharmaceutical Packaging
Latin America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Pharmaceutical Unit Dose Packaging Market
Pharmaceutical Packaging
Medical Flexible Packaging Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Vials Market
Pharmaceutical Packaging
Corrugated Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market
Pharmaceutical Packaging
Saudi Arabia Pharmaceutical Packaging Market