
 Global Elispot and Fluorospot Assay Market | 2026-2036
Global Elispot and Fluorospot Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Elispot and Fluorospot Assay Market Foresight
EU MDR and FDA guidance on cell-based potency assays is shifting procurement standards across immunotherapy development pipelines. Oxford Immunotec leverages its T-SPOT technology platform to anchor clinical diagnostics demand in tuberculosis and transplant monitoring. Cellular Technology Limited sustains competitive positioning through specialized ELISpot analysis software and contract research services. Mabtech dominates fluorescent detection substrate supply, extending its reach into multiplex cytokine profiling workflows.
ELISpot and FluoroSpot assays are solid-phase immunoassays that capture secreted proteins from individual cells on membrane-backed plates, with FluoroSpot enabling simultaneous detection of multiple analytes through spectrally distinct fluorophores. These technologies serve primary commercial purposes in vaccine efficacy validation, adoptive cell therapy potency assessment, and infectious disease immune response characterization. Elispot kits and Fluorospot kits occupy the core revenue pool due to recurring consumable demand, while digital imaging systems represent the fastest-growing technology segment as laboratories automate plate reading and colony enumeration. Infectious disease applications maintain mature volume leadership, though immunotherapy monitoring commands premium pricing from pharmaceutical and biotechnology firms.
FDA, EMA, and ISO 13485 frameworks govern assay validation, manufacturing quality, and diagnostic device registration across this market. These bodies shape demand by mandating traceable cytokine quantification methods for clinical trial endpoints and commercial release testing. Stakeholders must monitor evolving multiplex assay guidance from regulators to align R&D investment with compliant product roadmaps.
Market Dynamics
Pharmaceutical contract manufacturing organizations are consolidating cytokine detection workflows into centralized bioanalytical hubs, compressing vendor relationships and favoring assay platforms with integrated software and automated imaging capabilities.
Growth Catalysts
- Immunotherapy pipeline expansion:CAR-T and TIL therapy developers require validated potency assays for FDA and EMA submission packages, creating recurring kit demand from contract research organizations.
- EU MDR Article 10 technical documentation:In vitro diagnostic manufacturers must demonstrate analytical performance through cell-based methods, tightening procurement standards for validated ELISpot substrates.
- Multiplexing capabilities:FluoroSpot's simultaneous detection of four or more analytes per well reduces sample volume requirements and accelerates vaccine immunogenicity studies.
Market Restraints
- Fluorophore supply concentration:German and Dutch chemical suppliers dominate high-purity detection substrates, exposing assay manufacturers to euro-denominated input volatility.
- Specialized technician scarcity:Cell culture expertise for primary PBMC handling remains concentrated in academic medical centers, limiting assay standardization across decentralized testing sites.
- Flow cytometry substitution:Single-cell RNA sequencing and mass cytometry platforms capture secretory profiles with higher resolution, capturing budget allocations from exploratory research segments.
Strategic Opportunities
- China NMPA diagnostic reagent registration pathway:Streamlined Class II approval for imported immunological kits opens commercialization for tuberculosis and tumor immunology applications.
- Point-of-care infectious disease testing:Miniaturized ELISpot readers with cloud-connected enumeration algorithms address decentralized TB screening in India and Southeast Asia.
- ISO 13485 contract manufacturing:Diagnostic kit producers can outsource GMP-compliant membrane plate production to specialized converters, reducing capital intensity for market entry.
Industry Challenges
- Inter-laboratory variability control:Subjective spot enumeration across manual readers undermines clinical trial data integrity, demanding AI-assisted image analysis validation.
- Legacy LIMS integration:Proprietary data formats from competing imaging systems fragment workflow automation in multi-vendor laboratory environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Elispot and Fluorospot Assay Market |
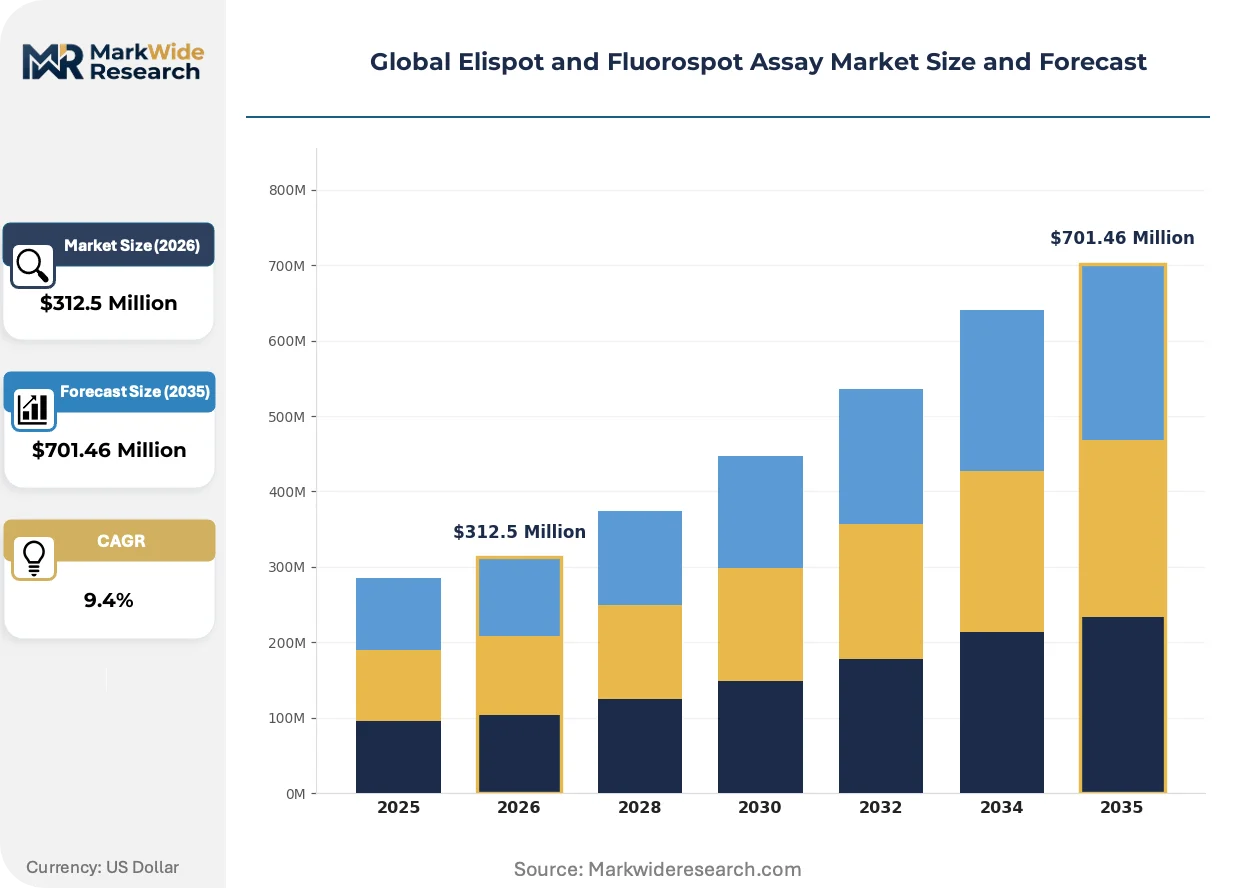
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $701.46 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elispot Kits, Fluorospot Kits, Reader Equipment, Reagents Application: Infectious Disease, Vaccine Development, Immunotherapy Monitoring, Allergy Research, Autoimmune Disorder Analysis End User: Research Institutes, Clinical Laboratories, Pharmaceutical Companies, Biotechnology Firms Technology: Chromogenic Detection, Fluorescent Detection, Multiplex Assay, Digital Imaging Systems |
| Companies Covered | Oxford Immunotec, Cellular Technology Limited, Mabtech, Becton Dickinson and Company, Abcam, Bio-Techne Corporation, U-CyTech, Autoimmun Diagnostika, Lophius Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Elispot and Fluorospot Assay Market Shifts & Advancements
Automation is compressing assay turnaround times while spectral multiplexing expands analyte throughput per sample. These developments are reshaping capital allocation priorities across diagnostic and pharmaceutical end-uses.
FluoroSpot systems are integrating artificial intelligence-based spot classification algorithms that distinguish true cytokine secretion from artifact. Large pharmaceutical sponsors now mandate AI-validated enumeration for Phase II/III immunotherapy trials. This capability is integrating manual microscopy out of regulated workflows, consolidating demand with vendors offering validated software modules.
EMA's 2024 reflection paper on cell-based potency assays tightens acceptance criteria for assay precision and robustness. Contract development and manufacturing organizations must revalidate legacy ELISpot methods against revised guidelines. European biologics developers are responding by consolidating supplier relationships with kit manufacturers holding documented ISO 13485 quality management systems.
Academic research laboratories are unbundling after-sales service contracts from instrument purchases, favoring third-party maintenance providers and open-source analysis software. This pattern compresses recurring revenue for original equipment manufacturers while expanding the installed base of compatible third-party substrates and reagents. The shift is most visible in German and US university hospital research cores operating under fixed annual capital budgets.
Global Elispot and Fluorospot Assay Market Segmentation
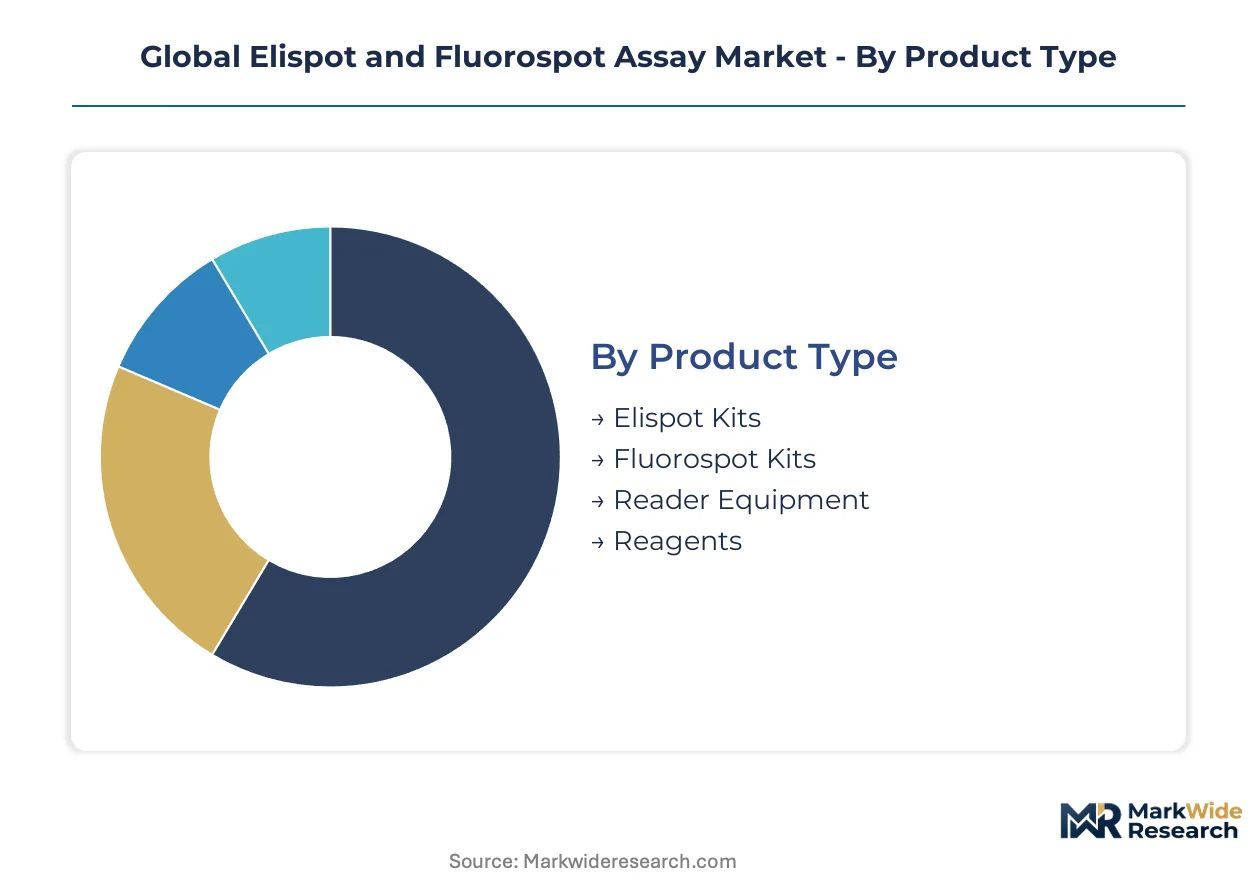
Segmentation in the Elispot and Fluorospot assay market reflects divergent upgrade cycles across consumables, instrumentation, and software. Procurement patterns vary sharply between research laboratories prioritizing reagent flexibility and pharmaceutical quality control departments demanding validated, GMP-compliant workflows.
Product Type:
Replacement cycles differ fundamentally between recurring consumable purchases and capital equipment investments, with membrane plate durability and detection chemistry stability driving reorder timing.
- Elispot Kits:These membrane-based assay plates with pre-coated capture antibodies form the foundational consumable for single-analyte cytokine detection. Demand clusters in tuberculosis diagnostic laboratories across India and South Africa where national screening programs sustain high-throughput consumption.
- Fluorospot Kits:Spectrally multiplexed detection substrates enable simultaneous quantification of four or more secreted analytes per well. CAR-T therapy developers in Boston and San Diego purchase these kits for potency assay panels supporting FDA IND submissions.
- Reader Equipment:Automated imaging systems with AI-assisted enumeration replace manual microscopy in regulated environments.
- Reagents:Detection antibodies, substrates, and blocking buffers constitute recurring ancillary purchases tied to kit consumption patterns.
Volume placements concentrate in Elispot Kits; the faster expansion belongs to Fluorospot Kits.
Application:
Application demand stratifies by regulatory intensity, with clinical trial endpoints commanding premium pricing over exploratory research.
- Infectious Disease:TB-specific interferon-gamma release assays dominate installed base, particularly in European reference laboratories performing latent infection screening for immunocompromised patients.
- Vaccine Development:Immunogenicity studies for novel adjuvants and mRNA platforms require standardized T-cell response quantification across Phase I/II cohorts.
- Immunotherapy Monitoring:Adoptive cell therapy potency validation represents the highest-value segment, with CD19 CAR-T manufacturers mandating IFN-γ and IL-2 dual detection for lot release.
- Allergy Research:Basophil activation and cytokine profiling studies utilize specialized ELISpot configurations for allergen-specific IgE characterization.
- Autoimmune Disorder Analysis:T-cell autoreactivity assessment in multiple sclerosis and type 1 diabetes research employs customized peptide libraries.
Commercial maturity sits with Infectious Disease; Immunotherapy Monitoring claims the steepest expansion trajectory.
End User:
Customer procurement authority varies by organizational scale, with centralized pharmaceutical quality departments consolidating vendor relationships differently than distributed academic cores.
- Research Institutes:University hospital cores prioritize reagent flexibility and open-source analysis tools over validated workflows. German Max Planck institutes and US NIH intramural programs represent significant installed base for basic immunology applications.
- Clinical Laboratories:Accredited diagnostic facilities require CE-IVD or FDA-cleared kits with documented traceability for patient reporting.
- Pharmaceutical Companies:GMP-compliant potency assay development drives kit standardization and software validation investments.
- Biotechnology Firms:Emerging cell therapy developers balance cost sensitivity against rapid assay qualification needs for early-phase trials.
Procurement scale peaks with Pharmaceutical Companies; Biotechnology Firms are gaining share fastest.
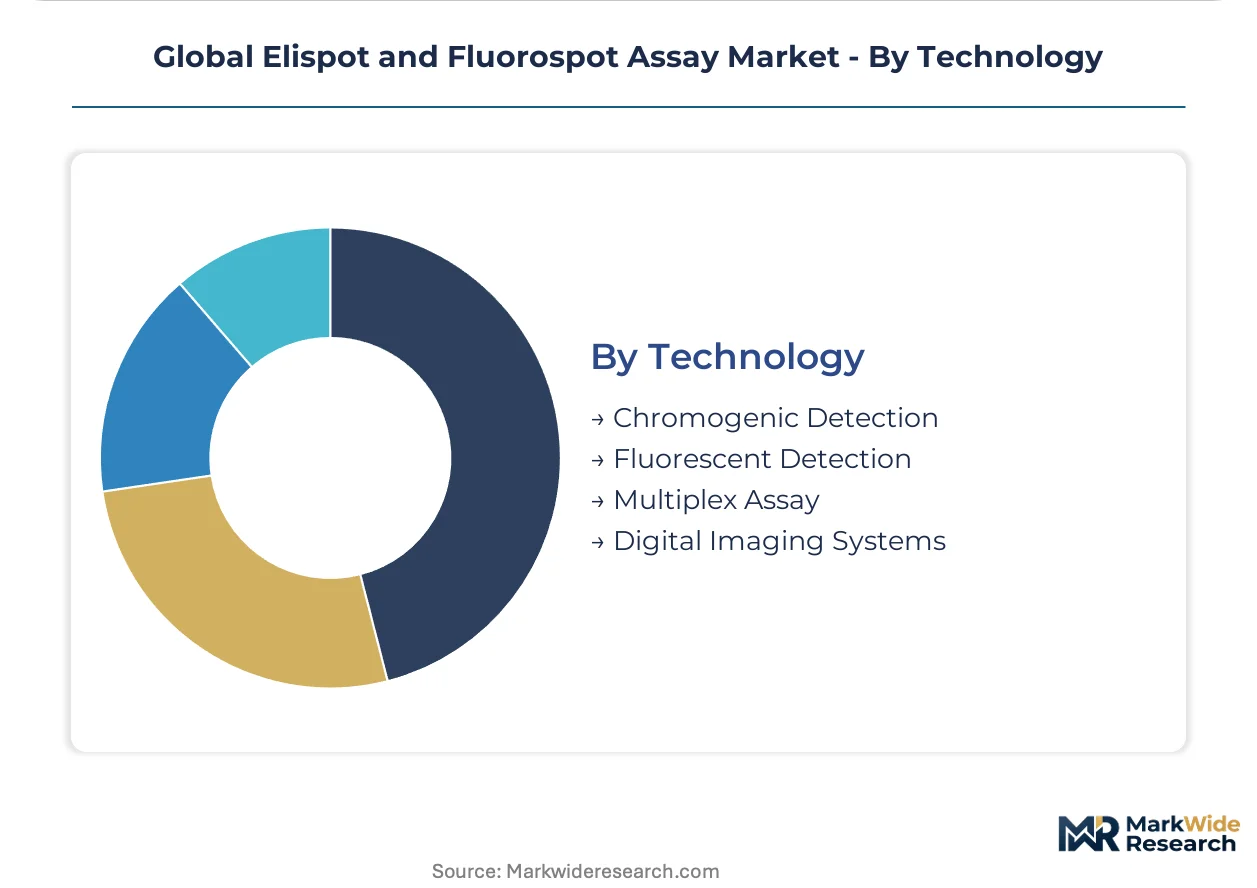
Technology:
Technology selection hinges on resolution requirements versus throughput constraints, with spectral multiplexing displacing sequential single-analyte workflows in high-complexity environments.
- Chromogenic Detection:Enzymatic substrate conversion producing visible precipitates remains the cost-optimized standard for single cytokine quantification. Indian and Southeast Asian TB screening programs rely on this established chemistry for decentralized laboratory networks.
- Fluorescent Detection:Spectrally resolved fluorophore emission enables multiplexed analyte discrimination without physical well subdivision. Swiss and Dutch contract research organizations have standardized FluoroSpot platforms for vaccine immunogenicity panels.
- Multiplex Assay:Integration of cytokine, chemokine, and cytotoxic marker detection expands information density per patient sample.
- Digital Imaging Systems:Automated plate scanning with machine learning spot classification reduces inter-operator variability in regulated studies.
Installed base dominance rests with Chromogenic Detection; Digital Imaging Systems show the fastest technology substitution rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of ELISpot membrane plates and detection substrates concentrates in Germany and the Netherlands, while consumption clusters in United States pharmaceutical hubs and Chinese diagnostic networks. This geographic split creates currency-exposed supply chains and regulatory complexity for kit manufacturers.
United States
CAR-T therapy developers in Boston and San Diego drive premium kit demand for FDA-mandated potency assays. The FDA's 2023 cell-based potency assay guidance tightens validation requirements for IND submissions. Massachusetts biotech clusters anchor immunotherapy monitoring workflows, with contract research organizations consolidating vendor relationships around automated imaging platforms.
Germany
High-purity fluorophore substrate production dominates in Baden-Württemberg chemical manufacturing zones. EU MDR Article 10 technical documentation requirements reshape procurement standards for IVD manufacturers. The Tübingen-Stuttgart corridor houses specialized membrane plate converters serving ISO 13485 contract manufacturing demand.
China
NMPA Class II diagnostic reagent registration streamlines import pathways for tuberculosis screening kits. The Yangtze River Delta biotech corridor in Shanghai and Suzhou expands cell therapy manufacturing capacity. Local CDMOs adopt ELISpot platforms for lot release testing of domestically produced CAR-T therapies.
India
National tuberculosis elimination programs sustain high-throughput ELISpot consumption in public health laboratories. CDSCO diagnostic kit registration timelines compress for WHO-prequalified immunological assays. Hyderabad and Bangalore research institutes deploy miniaturized readers for decentralized screening in rural health networks.
Switzerland
Swissmedic oversight of cell-based potency assays aligns with EMA reflection paper standards for biologics release testing. Basel pharmaceutical headquarters mandate traceable cytokine quantification for clinical trial endpoints. Geneva contract research organizations standardize FluoroSpot platforms for vaccine immunogenicity panels across European sponsor networks.
Global Elispot and Fluorospot Assay Market Competitive Landscape
The competitive structure tilts toward technology-integrated solution providers over standalone reagent suppliers. Kit manufacturers with captive software and automated imaging capabilities capture expanding pharmaceutical contracts, while pure-play substrate vendors face margin compression. Two archetypes dominate: full-platform integrators bundling hardware-software-consumables, and specialized reagent houses supplying detection chemistry to third-party instrument makers. Consolidation pressure manifests through strategic partnerships between membrane plate converters and AI imaging developers, plus geographic licensing arrangements for regulatory market access.
Within the platform-integrated tier, Oxford Immunotec anchors clinical diagnostics demand through its T-SPOT technology lineage, while Cellular Technology Limited occupies a position in specialized analysis software and contract research services. Mabtech exemplifies the detection chemistry specialization archetype, extending reach into multiplex workflows without captive instrumentation. These three represent distinct strategic postures: regulated diagnostic clearance, analytical service bundling, and substrate supply concentration.
| Leading Market Players |
|---|
| Oxford Immunotec |
| Cellular Technology Limited |
| Mabtech |
| Becton Dickinson and Company |
| Abcam |
| Bio-Techne Corporation |
| U-CyTech |
| Autoimmun Diagnostika |
| Lophius Biosciences |
| Others |
Supply & Pricing Matrix
PVDF membrane spot pricing indices from German chemical suppliers cascade through three distinct procurement tiers, compressing margins for kit assemblers while amplifying bargaining power for pharmaceutical sponsors with multi-year fluorophore offtake agreements.
Pricing Analysis
Outcome-linked pricing tied to FDA submission success anchors premium tiers for GMP-validated FluoroSpot panels, while reagent-grade consumables compete on volume scale and ISO 13485 certification tier. Three-tier pricing structure across premium, standard, and economy levels separates automated imaging bundles from manual reader kits and unbranded membrane plates. Cost compression in the economy tier is intensifying because Indian and Southeast Asian TB screening programs consolidate procurement around government tenders. Biotechnology firms exhibit highest price sensitivity, whereas CAR-T developers prioritize validation documentation over per-kit expenditure.
Supply Chain Analysis
Air freight and cold-chain logistics costs from Baden-Württemberg to Boston and San Diego biotech clusters amplify landed costs for temperature-sensitive detection substrates. Manufacturing concentrates in Germany, the Netherlands, and China, with high-purity fluorophore production drawing from specialized chemical synthesis capabilities in Basel and Rotterdam. Single-source vulnerability permeates PVDF membrane supply, as two specialized converters dominate ISO 13485-certified plate production. Distribution runs through authorized distributors for clinical laboratories and direct sales teams for pharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market is becoming a vertical-integration race, with captive fluorophore production and proprietary AI enumeration software emerging as the decisive levers for margin defense.
For Market Incumbents: Cement platform stickiness by bundling GMP-compliant kit validation with automated imaging hardware and cloud-based spot enumeration subscriptions. Single-cell RNA sequencing platforms threaten exploratory research budgets, demanding counter-investment in multiplex cytokine panel expansion. Backward integration into membrane plate conversion secures supply continuity against German chemical supplier concentration. For New Entrants and Emerging Players: Enter via the China NMPA Class II diagnostic reagent registration pathway for tuberculosis screening kits, where streamlined import procedures lower regulatory barriers. White-space concentrates in point-of-care miniaturized readers for decentralized Indian and Southeast Asian health networks. Partner with local CDMOs for membrane plate assembly to bypass capital-intensive captive manufacturing. For Investors and Strategic Acquirers: Distressed-cycle entries favor AI imaging software specialists with validated FDA submission support modules in the United States and Switzerland. Long-term viability hinges on regulatory compliance automation capabilities across EMA and FDA guidance evolution. Watch for EMA reflection paper implementation deadlines as inflection indicators for CDMO consolidation demand.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Assisted Enumeration Validation | FDA-mandated spot classification algorithms displace manual microscopy in Phase II/III immunotherapy trials. |
| ISO 13485 Contract Manufacturing | Outsourced membrane plate production reduces capital intensity for kit market entry in China and India. |
| Multiplex Cytokine Panel Expansion | Simultaneous detection of four or more analytes accelerates vaccine immunogenicity study throughput. |
| Point-of-Care Reader Miniaturization | Cloud-connected enumeration algorithms address decentralized TB screening in rural Indian health networks. |
| EMA Compliance Revalidation Services | CDMOs demand legacy ELISpot method updates against tightened cell-based potency assay acceptance criteria. |
Research Methodology
Multi-period observation of kit procurement volumes, fluorophore price indices, and regulatory submission timelines anchored the trend analysis, supplemented by interviews with diagnostic kit product managers, pharmaceutical quality control directors, contract research organization assay scientists, and hospital laboratory procurement officers. Secondary validation drew from FDA 510(k) filings, EMA scientific advice letters, NMPA registration databases, and ISO 13485 audit records. Bottom-up segment sizing triangulated against top-down pharmaceutical R&D expenditure allocation patterns.
Segment-weighting across product type, application, end user, and technology dimensions informed the analytical framework, with immunotherapy monitoring and infectious disease applications receiving distinct growth trajectory assumptions. CAGRs were derived from regression analysis of historical kit shipment data and sponsor pipeline expansion rates. Forecast inputs incorporated CAR-T therapy approval momentum and EU MDR implementation pace across member states.
Revisions become necessary when NMPA regulatory timelines extend, fluorophore supply disruptions materialize, or flow cytometry substitution accelerates beyond exploratory research segments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Services
Nigeria Clinical Laboratory Services Market
Laboratory Services
Frozen Tissues Samples Market
Laboratory Services
Hematocrit Tests Market
Laboratory Services
Middle East and Africa Clinical Laboratory Services Market
Laboratory Services
Clinical Laboratory Services Market
Laboratory Services
Biomarker Clinical Phase Outsourcing Services Market
Laboratory Services
Global Lab Consumables Market
Laboratory Services
Histopathology Services Market
Laboratory Services
AI in Laboratory Solution Market
Laboratory Services
Global Virology Specimen Collection Market
Laboratory Services
Clinical Laboratory Tests Market
Laboratory Services
Pathology Services Market
Laboratory Services
Assessment Services Market
Laboratory Services
Myoglobin Reagents Market
Laboratory Services
Preeclampsia Laboratory Testing Market
Laboratory Services
Global Clinical Reference Laboratory Market