
 Mitochondrial DNA Market | 2026-2036
Mitochondrial DNA Market Size, Share, and Industry Trends Forecast 2026-2036
Mitochondrial DNA Market Foresight
Biotech manufacturing clusters in Massachusetts and California are pivoting toward GMP-grade mitochondrial DNA production for cell therapy supply chains. Thermo Fisher Scientific leverages its reagent ecosystem to anchor clinical sequencing workflows across North American reference labs. Illumina competes through instrument placement density in academic medical centers, while QIAGEN differentiates with automated extraction platforms that reduce sample-to-result time for heteroplasmy quantification.
Mitochondrial DNA comprises a 16,569-base-pair circular genome encoding 13 essential respiratory chain proteins, 22 tRNAs, and 2 rRNAs, with copy number varying from hundreds to thousands per cell depending on tissue metabolic demand. The molecule serves as a critical biomarker for maternal lineage tracing, heteroplasmy detection, and mitochondrial disease diagnosis in clinical and forensic settings. Kits and reagents capture the dominant revenue share due to recurring consumable demand in high-throughput labs, while NGS technology leads instrument-based spending because of its superior resolution for detecting low-frequency heteroplasmic variants. Diagnostic labs represent the fastest-growing end user channel as hospital systems outsource complex mitochondrial testing to specialized reference providers.
FDA oversight of mitochondrial replacement therapies and LDT regulations shapes clinical assay validation requirements in the United States, while the EU In Vitro Diagnostic Regulation enforces stricter performance criteria for mitochondrial diagnostic kits entering European markets. ISO 15189 accreditation standards govern quality management in diagnostic laboratories processing mitochondrial DNA samples across multiple jurisdictions. Stakeholders must monitor evolving reimbursement frameworks for mitochondrial disease testing as payors develop coverage policies for heteroplasmy analysis in prenatal and oncology settings.
Market Dynamics
CRISPR-based mitochondrial editing is compressing translational timelines and forcing diagnostic labs to reconfigure heteroplasmy detection workflows around single-molecule resolution capabilities.
Growth Catalysts
- FDA LDT pathway modernization:Streamlined validation requirements for mitochondrial disease assays accelerate clinical lab adoption in the United States.
- Cell therapy manufacturing:GMP-grade mitochondrial DNA demand from CAR-T and iPSC producers creates captive supply agreements with reagent vendors.
- Germany's precision medicine clusters:Clinical heteroplasmy analysis penetration in Heidelberg and Berlin hospital networks drives reference lab outsourcing volume.
Market Restraints
- EU MDR compliance costs:Stricter performance criteria for mitochondrial diagnostic kits force smaller IVD manufacturers to abandon European market entry.
- HeLa cell line contamination risk:Cross-contamination during mitochondrial DNA extraction necessitates expensive cleanroom infrastructure for high-throughput facilities.
- Polymerase fidelity limitations:Taq enzyme error rates during long-range PCR amplification introduce false heteroplasmy calls requiring orthogonal validation.
Strategic Opportunities
- Japan's regenerative medicine framework:PMDA guidance on mitochondrial replacement compatibility creates first-mover positioning for edited mDNA suppliers.
- Liquid biopsy integration:Circulating cell-free mitochondrial DNA analysis for early cancer detection opens oncology diagnostic white space.
- ISO 15189 accreditation arbitrage:Diagnostic labs in Spain and Italy pursue cross-border certification to capture outsourced testing from Northern European hospital systems.
Industry Challenges
- Bioinformatician shortage:Specialized expertise in mitochondrial genome assembly and heteroplasmy quantification pipelines commands premium salaries that strain mid-size lab budgets.
- Multi-jurisdiction sample transport:Temperature-controlled logistics for mtDNA stability across German, French, and Swiss borders adds operational complexity to centralized testing hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mitochondrial DNA Market |
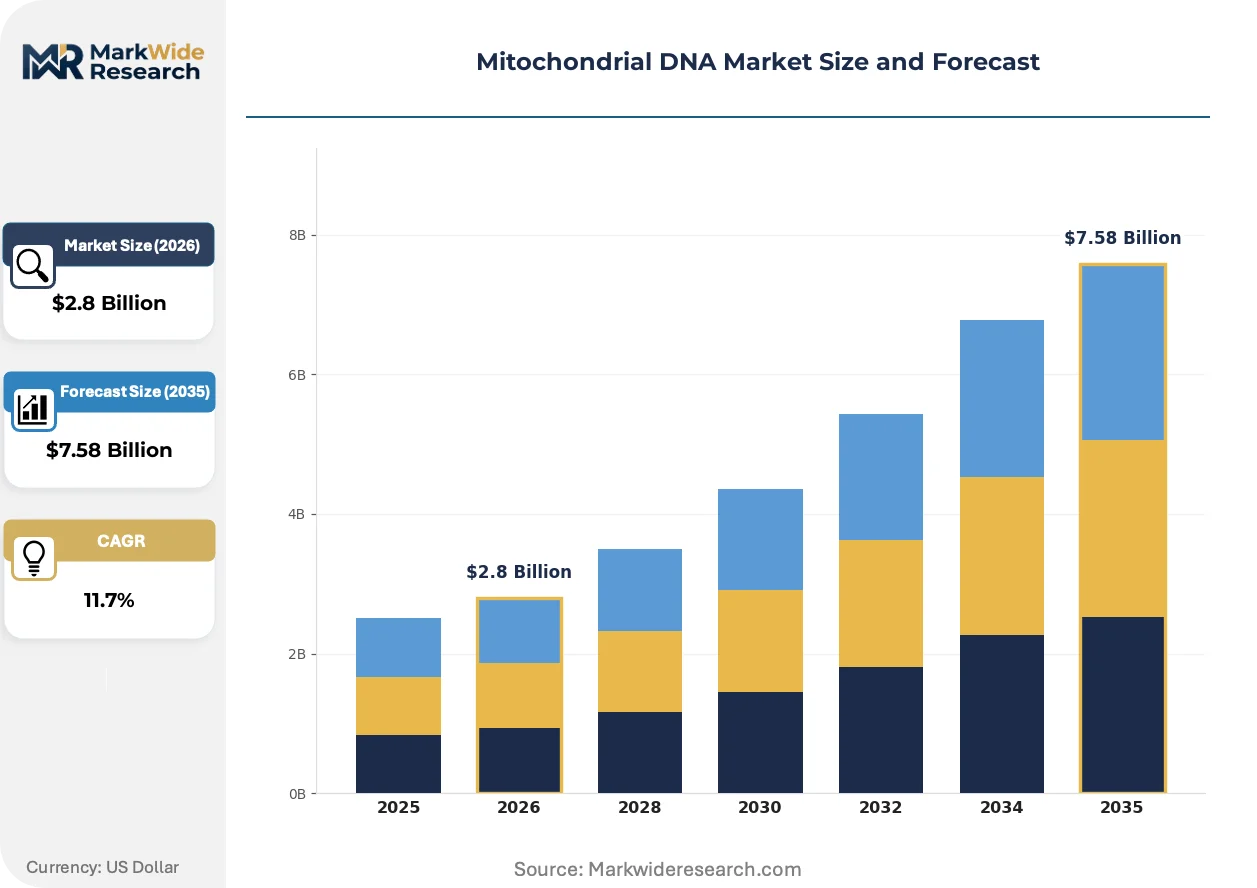
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kits, Reagents, Devices, Software Technology: NGS, PCR, SNP Analysis, Sequencing End User: Research Institutions, Hospitals, Diagnostic Labs, Pharmaceutical Companies Application: Genetic Testing, Forensic Applications, Personalized Medicine, Research |
| Companies Covered | Thermo Fisher Scientific, Illumina, Agilent Technologies, QIAGEN, Bio-Rad Laboratories, F. Hoffmann-La Roche, BGI Genomics, Oxford Nanopore Technologies, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mitochondrial DNA Market Shifts & Advancements
Workflow automation and regulatory harmonization are compressing the gap between research-grade mitochondrial analysis and clinical diagnostic deployment.
Third-generation sequencing platforms is modularizing mitochondrial genome analysis by enabling direct detection of epigenetic modifications and structural variants without PCR amplification bias. Academic medical centers in Massachusetts and California are piloting these systems for rapid mitochondrial disease diagnosis. The technology is modularizing service offerings, allowing reference labs to unbundle heteroplasmy reporting from full genome sequencing.
EU In Vitro Diagnostic Regulation enforcement is tightening performance documentation requirements for mitochondrial DNA extraction kits and quantification assays. Manufacturers must now submit clinical evidence packages demonstrating analytical sensitivity for low-frequency heteroplasmy detection. German and French notified bodies are prioritizing mDNA IVD reviews, creating regulatory backlog that favors established players with dedicated regulatory affairs teams.
Hospital systems are consolidating mitochondrial testing contracts with single reference providers capable of delivering integrated nuclear and mitochondrial genome reports. Specialized neurology and metabolic disease centers in the United States are demanding combined mtDNA deletion analysis and OXPHOS enzyme testing from one vendor. This concentration pattern is most visible in the Northeast, where Boston Children's Hospital and NewYork-Presbyterian have recently consolidated outsourced testing portfolios.
Mitochondrial DNA Market Segmentation
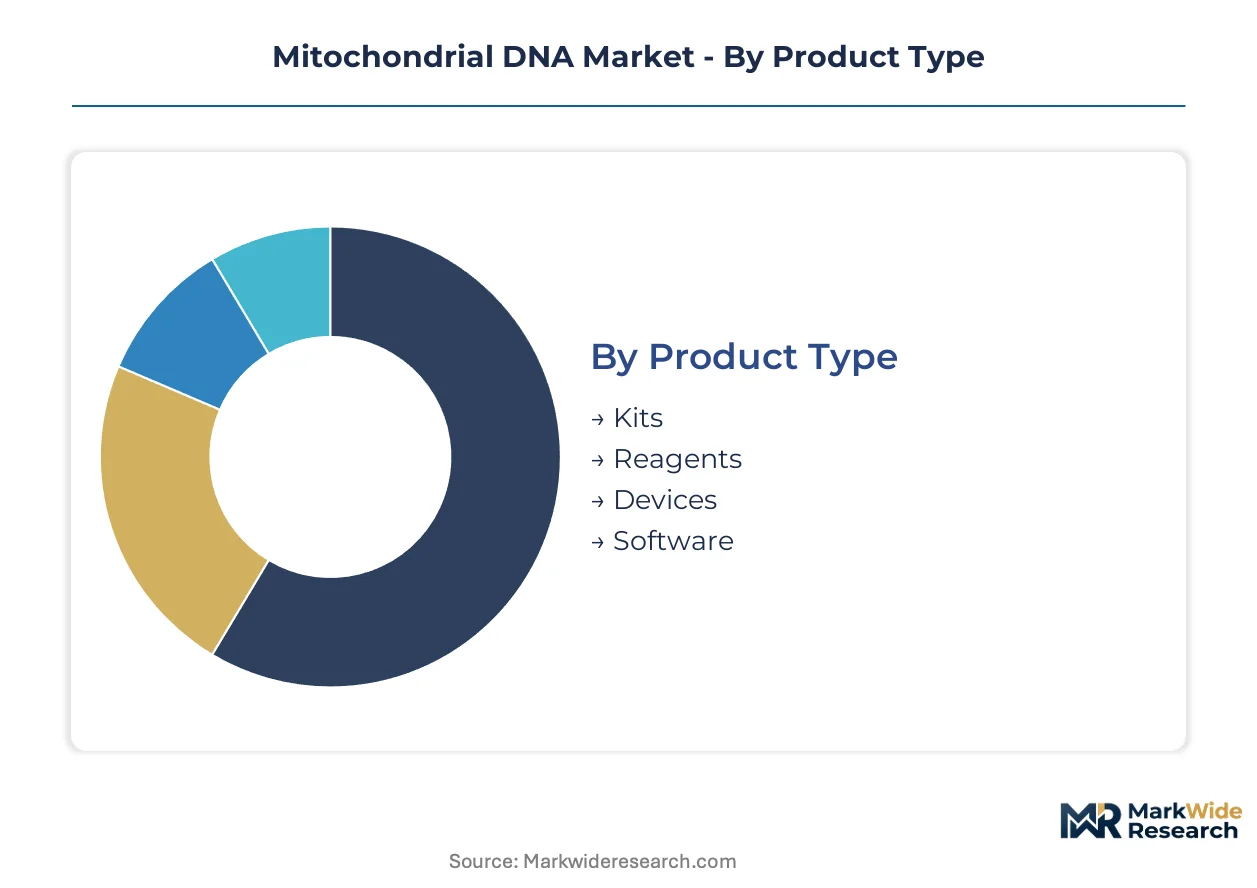
Segmentation in the mitochondrial DNA market reveals distinct capital requirements and margin profiles across product tiers. Each category shapes procurement patterns differently, with consumables-driven revenue models contrasting against instrument-heavy technology investments.
Product Type:
Kits and reagents demand lower upfront capital than devices or software platforms, yet generate recurring revenue streams that dominate manufacturer balance sheets.
- Kits:Pre-configured extraction and quantification consumables designed for heteroplasmy detection workflows. Massachusetts and California biotech clusters account for concentrated demand as CAR-T manufacturers establish GMP-grade mitochondrial DNA specifications.
- Reagents:Polymerases, primers, and fluorescent probes optimized for long-range PCR amplification of the 16,569-base-pair mitochondrial genome. Diagnostic labs in Germany's Heidelberg and Berlin hospital networks drive volume through outsourced heteroplasmy analysis contracts.
- Devices:Automated extraction platforms and capillary electrophoresis systems requiring substantial instrument placement investment.
- Software:Bioinformatics pipelines for heteroplasmy quantification and maternal lineage tracing demanding specialized computational infrastructure.
Kits absorb the bulk of installed capacity; diagnostic labs are expanding most quickly as hospital systems consolidate outsourced testing contracts.
Technology:
Technology selection determines analytical sensitivity thresholds and regulatory validation burdens for clinical deployment.
- NGS:Next-generation sequencing platforms deliver single-molecule resolution for low-frequency heteroplasmy detection without PCR amplification bias. Academic medical centers in the United States pilot third-generation systems for rapid mitochondrial disease diagnosis.
- PCR:Long-range and quantitative PCR methods remain cost-accessible for high-throughput screening despite polymerase fidelity limitations that introduce false heteroplasmy calls.
- SNP Analysis:Targeted genotyping arrays for maternal lineage tracing and ancestry applications.
- Sequencing:Sanger and emerging nanopore approaches for structural variant detection in mitochondrial DNA deletions.
NGS commands the steepest expansion trajectory as reference labs reconfigure workflows around single-molecule resolution capabilities.
End User:
End user categories reflect divergent procurement authority and technical sophistication in mitochondrial DNA applications.
- Research Institutions:Academic laboratories pursuing CRISPR-based mitochondrial editing and translational workflows. Massachusetts and California clusters anchor instrument placement density as NIH funding concentrates in these geographies.
- Diagnostic Labs:Specialized reference providers processing outsourced heteroplasmy analysis from hospital systems. Boston Children's Hospital and NewYork-Presbyterian have recently consolidated testing portfolios with single-vendor contracts.
- Hospitals:In-house neurology and metabolic disease centers requiring integrated nuclear and mitochondrial genome reporting.
- Pharmaceutical Companies:Mitochondrial genomics pipelines for rare disease therapeutics and cell therapy manufacturing quality control.
Diagnostic labs capture the majority of outsourcing volume; pharmaceutical companies are climbing the fastest as GMP-grade mitochondrial DNA demand accelerates.
Application:
Application segmentation tracks regulatory pathway complexity and reimbursement development maturity.
- Genetic Testing:Clinical heteroplasmy analysis for mitochondrial disease diagnosis and prenatal screening. FDA LDT pathway modernization accelerates assay validation in the United States.
- Personalized Medicine:Pharmacogenomic integration of mitochondrial variants into therapeutic decision support.
- Forensic Applications:Maternal lineage tracing in criminal investigations and disaster victim identification.
- Research:Basic science investigations into mitochondrial dynamics, aging, and metabolic disease mechanisms.
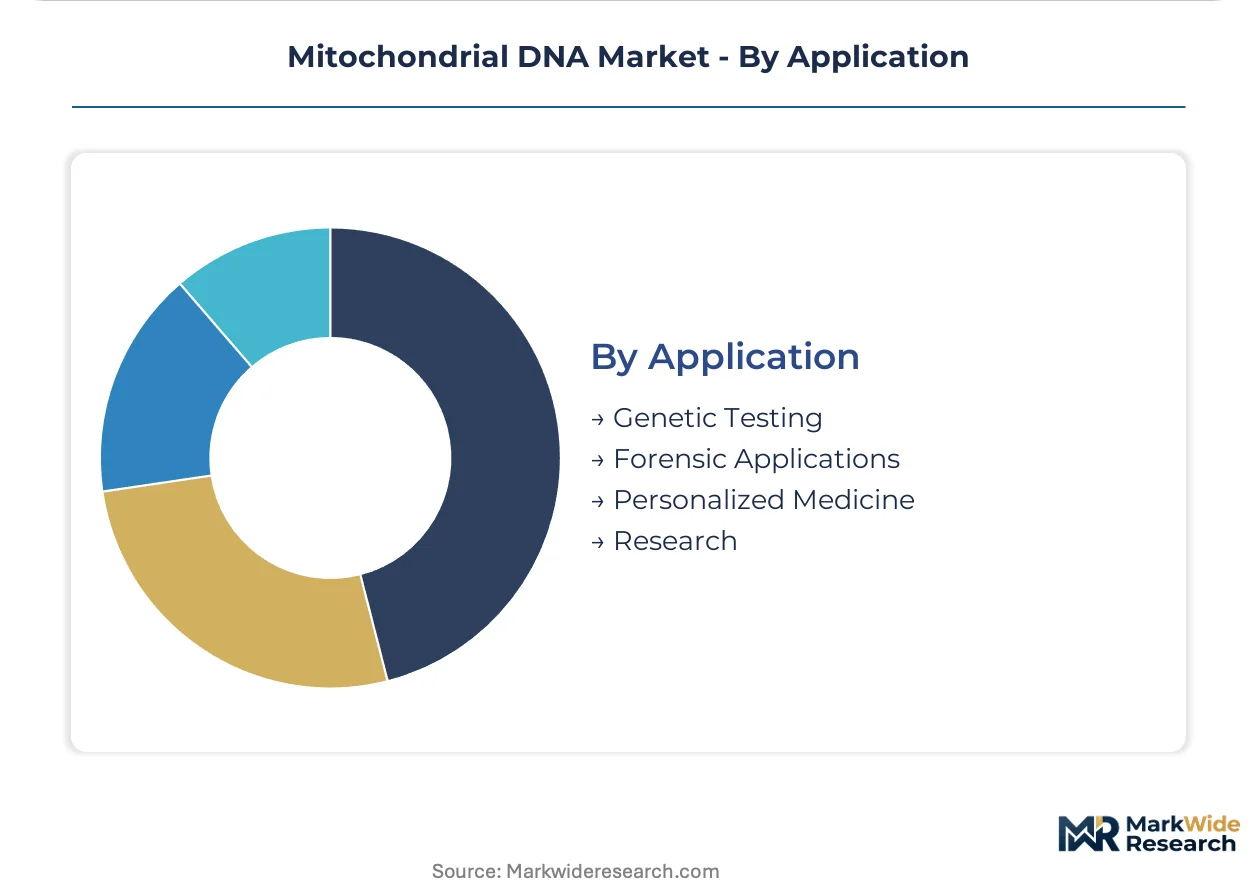
Genetic testing holds the largest share of validated assay volume; personalized medicine is gaining share fastest as payors develop coverage policies for heteroplasmy analysis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts and California biotech clusters anchor reagent manufacturing capacity for mitochondrial DNA workflows. Heidelberg and Berlin hospital networks in Germany concentrate clinical heteroplasmy analysis demand. Japan's PMDA regenerative medicine framework shapes edited mitochondrial DNA commercial pathways.
United States
FDA LDT pathway modernization accelerates mitochondrial disease assay validation timelines. The agency's oversight of mitochondrial replacement therapies shapes clinical trial design requirements. Massachusetts-based academic medical centers pilot third-generation sequencing systems for rapid diagnosis workflows.
Germany
Precision medicine clusters in Heidelberg and Berlin drive reference lab outsourcing volume for heteroplasmy analysis. EU MDR enforcement tightens performance documentation requirements for mitochondrial DNA extraction kits. Baden-Württemberg manufacturing hubs supply GMP-grade reagents to cell therapy producers.
Japan
PMDA guidance on mitochondrial replacement compatibility creates positioning opportunities for edited mDNA suppliers. METI funding for regenerative medicine infrastructure accelerates translational research pipelines. Kanto region academic hospitals integrate mitochondrial genomics into rare disease diagnostic protocols.
United Kingdom
NHS England's specialized commissioning frameworks shape reimbursement for mitochondrial disease testing. The MHRA post-Brexit regulatory pathway diverges from EU MDR for IVD kit approvals. London-Southeast research hospitals concentrate CRISPR-based mitochondrial editing pilot programs.
China
NMPA streamlined review pathways for innovative diagnostic reagents accelerate mitochondrial kit registrations. National precision medicine initiatives fund heteroplasmy analysis infrastructure in tier-one hospitals. Yangtze River Delta biotech parks attract mitochondrial genomics manufacturing investment.
Mitochondrial DNA Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue third-generation sequencing specialization. The market structures around three tiers: multinational life science conglomerates with reagent ecosystems, sequencing platform specialists with instrument placement density, and regional IVD manufacturers with cost-optimized kits. Strategic moves concentrate on regulatory capacity expansion and automated workflow integration partnerships.
Among US-based conglomerates, Thermo Fisher Scientific and Illumina occupy positions anchoring distinct competitive vectors. Thermo Fisher Scientific exemplifies the integrated reagent-provider archetype through consumable ecosystem dominance. Illumina represents the platform-specialist tier with instrument density strategies in academic medical centers. QIAGEN sits within the automated extraction segment, reducing sample-to-result intervals for heteroplasmy quantification workflows.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| Agilent Technologies |
| QIAGEN |
| Bio-Rad Laboratories |
| F. Hoffmann-La Roche |
| BGI Genomics |
| Oxford Nanopore Technologies |
| Eurofins Scientific |
| Others |
Supply & Pricing Matrix
Captive GMP-grade reagent production by Massachusetts and California biotech clusters anchors both supply security and premium pricing power for mitochondrial DNA workflows. This backward integration into high-purity consumables manufacturing insulates dominant suppliers from raw polymerase volatility while enabling service-bundling premiums for validated heteroplasmy quantification protocols.
Pricing Analysis
Extended warranty and ISO 15189 compliance documentation bundles separate premium-tier reagent contracts from unbundled economy kits. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade and heteroplasmy detection sensitivity thresholds. Pricing pressure stems from EU MDR compliance cost absorption as smaller IVD manufacturers exit, compressing mid-tier margins. Academic medical centers exhibit highest price sensitivity due to grant-funded procurement constraints, while CAR-T manufacturers prioritize specification adherence over unit cost.
Supply Chain Analysis
ISO 13485 and GMP qualification gating restricts viable reagent manufacturing to Massachusetts, California, and Baden-Württemberg production hubs. Supply chains draw from recombinant polymerase fermentation capacity, fluorophore chemical synthesis, and precision-molded consumables molding. Single-source vulnerability concentrates in Taq enzyme master cell banks held by dominant suppliers. Distribution runs through specialized life science distributors and direct reference lab contracts rather than broad-channel retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mitochondrial DNA market sits in a platform-transition phase as third-generation sequencing displaces PCR-dependent heteroplasmy workflows. Long-read technologies are rendering legacy amplification-based methods obsolete for clinical diagnostic deployment.
For Market Incumbents: Anticipate CRISPR-edited mitochondrial DNA demand acceleration by securing PMDA-compatible GMP manufacturing capacity in Japan's Kanto region. Lock in multi-year reagent supply agreements with Boston Children's Hospital and NewYork-Presbyterian before hospital consolidation patterns harden. Prioritize automated extraction platform R&D to match QIAGEN's sample-to-result interval benchmarks.
For New Entrants and Emerging Players: Reference lab partnerships offer the most penetrable channel for nanopore-based structural variant detection services. Target Spain and Italy diagnostic labs pursuing ISO 15189 cross-border accreditation arbitrage. Lead with liquid biopsy integration for circulating cell-free mitochondrial DNA oncology applications, bypassing entrenched PCR kit incumbents.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-specialist acquisitions by multinational life science conglomerates seeking third-generation sequencing capabilities. Five-to-ten year viability favors automated workflow developers with regulatory affairs infrastructure. Monitor FDA LDT pathway modernization rulings as the critical inflection signal for clinical assay validation volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Extraction Platform Deployment | QIAGEN's sample-to-result compression forces competitor workflow reinvestment in German diagnostic labs. |
| PMDA Mitochondrial Replacement Compatibility Filing | First-mover positioning in Japan's regenerative medicine framework secures edited mDNA commercial pathways. |
| ISO 15189 Cross-Border Accreditation | Spanish and Italian labs capture Northern European hospital outsourcing volume through certification arbitrage. |
| Liquid Biopsy cf-mtDNA Assay Development | Oncology diagnostic white space opens for early cancer detection beyond tissue-based heteroplasmy testing. |
| GMP-Grade Reagent Captive Manufacturing | CAR-T and iPSC producers demand supply chain control over mitochondrial DNA quality specifications. |
Research Methodology
Multi-period observation of heteroplasmy detection assay adoption rates, GMP reagent contract volumes, and CRISPR mitochondrial editing publication velocity anchored the trend analysis, supplemented by interviews with diagnostic lab directors, regulatory affairs specialists at IVD manufacturers, reference lab procurement managers, and cell therapy manufacturing quality officers. FDA 510(k) filings, EUDAMED device registrations, PMDA consultation minutes, ClinicalTrials.gov mitochondrial disease entries, and ISO certification databases provided secondary validation. Bottom-up reagent demand modeling and top-down pharmaceutical R&D spending allocation were triangulated against instrument placement tracking.
Segment-weighting applied product type, technology platform, end user category, and application area dimensions across the projection horizon. NGS versus PCR technology mix, diagnostic lab outsourcing penetration rates, and GMP-grade specification adoption curves served as core forecast inputs. CAGRs were derived from logistic diffusion modeling of platform substitution dynamics and regulatory approval timeline distributions.
Caveats apply where FDA LDT pathway modernization delays, EU MDR notified body backlog extensions, or third-generation sequencing cost curve inflections could materially shift the outlook. A model refresh is warranted upon material change in Japan's PMDA regenerative medicine guidance implementation timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Europe Epigenetics Market
Genomics
Genomic Biomarkers Market
Genomics
Genetic Testing Panels Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Latin America Gene Expression Market
Genomics
Europe Cancer Biomarkers Market
Genomics
Next-Generation Sequencing Library Preparation Market
Genomics
Glycan Sequencing Market
Genomics
Microarray Biochips Market
Genomics
Transcriptomics Technologies Market
Genomics
DNA Gene Chip Market
Genomics
Retail Genomics Market
Genomics
Apolipoprotein Test Market
Genomics
Japan Next Generation Sequencing Market
Genomics
DNA Sequencing Services Market
Genomics
Nutrigenomics Testing Market