
 Hereditary Testing Market | 2026-2036
Hereditary Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Hereditary Testing Market Intelligence
Platform licensing revenue is tilting from single-gene assays toward multi-gene panel subscriptions. Illumina, Inc. leverages its sequencing instrument installed base to anchor consumable pull-through. Myriad Genetics, Inc. competes through hereditary cancer risk specialization and accumulated clinical evidence. Invitae Corporation extends its position via transparent pricing and direct-to-patient channels.
Hereditary testing identifies germline mutations associated with inherited disease susceptibility through DNA analysis of blood or saliva specimens, typically reporting pathogenicity classifications per ACMG guidelines to inform clinical management decisions. The technology dimension shows Next-Generation Sequencing capturing the dominant share as read costs decline below Sanger thresholds. Predictive Tests represent the fastest-expanding product type as healthy populations seek polygenic risk scores for cardiovascular and oncologic conditions.
FDA oversees laboratory-developed test enforcement discretion and companion diagnostic co-approval requirements, while CMS governs reimbursement coding through molecular pathology fee schedules. The EU In Vitro Diagnostic Regulation imposes notified body conformity assessments that lengthen market access timelines for European laboratories. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled variant interpretation and its implications for test validation standards.
Market Dynamics
Next-Generation Sequencing read-cost compression below Sanger thresholds is fragmenting test economics and compressing development timelines for multi-gene panels.
Growth Catalysts
- FDA companion diagnostic co-approval pathways:Parallel review processes accelerate market entry for oncology panels, reducing time-to-reimbursement for academic medical center laboratories.
- Polygenic risk score commercialization:Cardiovascular and oncologic predictive tests attract healthy population demand through direct-to-consumer channels.
- Texas and Massachusetts cancer center clusters:Concentrated ordering volume from major academic institutions validates clinical utility and drives evidence accumulation.
Market Restraints
- EU In Vitro Diagnostic Regulation conformity assessments:Notified body bottlenecks extend European market access timelines by 12-24 months for laboratory-developed tests.
- CMS molecular pathology fee schedule compression:Reimbursement code stacking limitations constrain revenue per test for high-complexity sequencing panels.
- Variant interpretation workforce scarcity:Board-certified genetic counselors and molecular pathologists remain concentrated at top-tier academic centers.
Strategic Opportunities
- Saudi Arabia and UAE preventive health mandates:National screening programs create procurement volume for hereditary cancer panels in Gulf Cooperation Council markets.
- Artificial intelligence-enabled variant classification:Machine learning interpretation tools reduce turnaround time and labor intensity for ACMG guideline-compliant reporting.
- Employer-sponsored wellness integration:Self-insured corporations add hereditary risk screening to benefits packages as population health management tools.
Industry Challenges
- Laboratory information system interoperability:Electronic health record integration requires HL7 FHIR standardization that remains incomplete at community hospital systems.
- Reagent supply concentration:Sequencing consumable production clusters with single-source dependencies create vulnerability to geographic disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hereditary Testing Market |
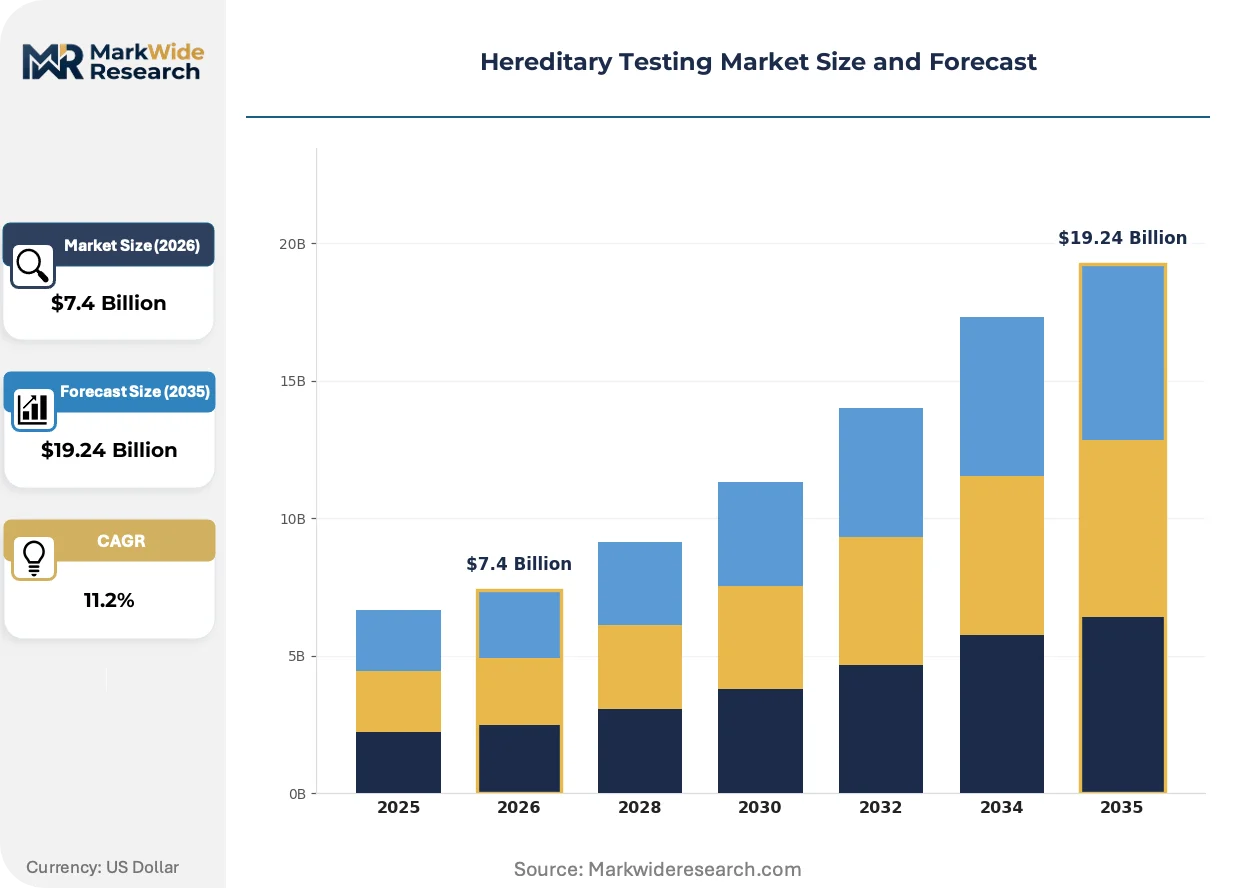
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $19.24 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetic Tests, Carrier Tests, Predictive Tests, Prenatal Tests Technology: Next-Generation Sequencing, Sanger Sequencing, Polymerase Chain Reaction, Microarrays End User: Hospitals, Laboratories, Clinics, Research Institutes Application: Cancer Screening, Cardiovascular Risk Assessment, Prenatal Screening, Rare Disease Diagnosis |
| Companies Covered | Illumina, Inc., Myriad Genetics, Inc., Invitae Corporation, Natera, Inc., Thermo Fisher Scientific Inc., F. Hoffmann-La Roche Ltd., Quest Diagnostics Incorporated, CENTOGENE N.V., Fulgent Genetics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hereditary Testing Market Strategic Shifts & Innovations
Platform economics and regulatory compression are forcing business model reinvention across specimen processing, interpretation, and results delivery.
Long-read sequencing technologies from Pacific Biosciences and Oxford Nanopore are rendering obsolete short-read assembly for complex structural variant detection in hereditary cardiovascular conditions. Pediatric cardiology departments at Boston Children's Hospital and Texas Children's Hospital are piloting these platforms for hypertrophic cardiomyopathy panel refinement. The structural consequence is rendering obsolete reimbursement codes tied to short-read methodologies, forcing payor contract renegotiation.
EMA's In Vitro Diagnostic Regulation Article 56 performance study requirements impose clinical evidence thresholds that exceed prior CE marking self-certification. European reference laboratories must now generate prospective diagnostic accuracy data for hereditary cancer panels. Germany's academic pathology institutes are responding through multicenter validation consortia to distribute study costs.
Direct-to-patient ordering portals are bypassing traditional genetics clinic referrals for BRCA1/2 and Lynch syndrome screening. Invitae and Color Genomics capture specimen collection through telehealth-integrated platforms that replace hospital-based phlebotomy. This channel shift concentrates in California and New York where state laboratory licensing permits direct consumer access without physician intermediation.
Hereditary Testing Market Segmentation
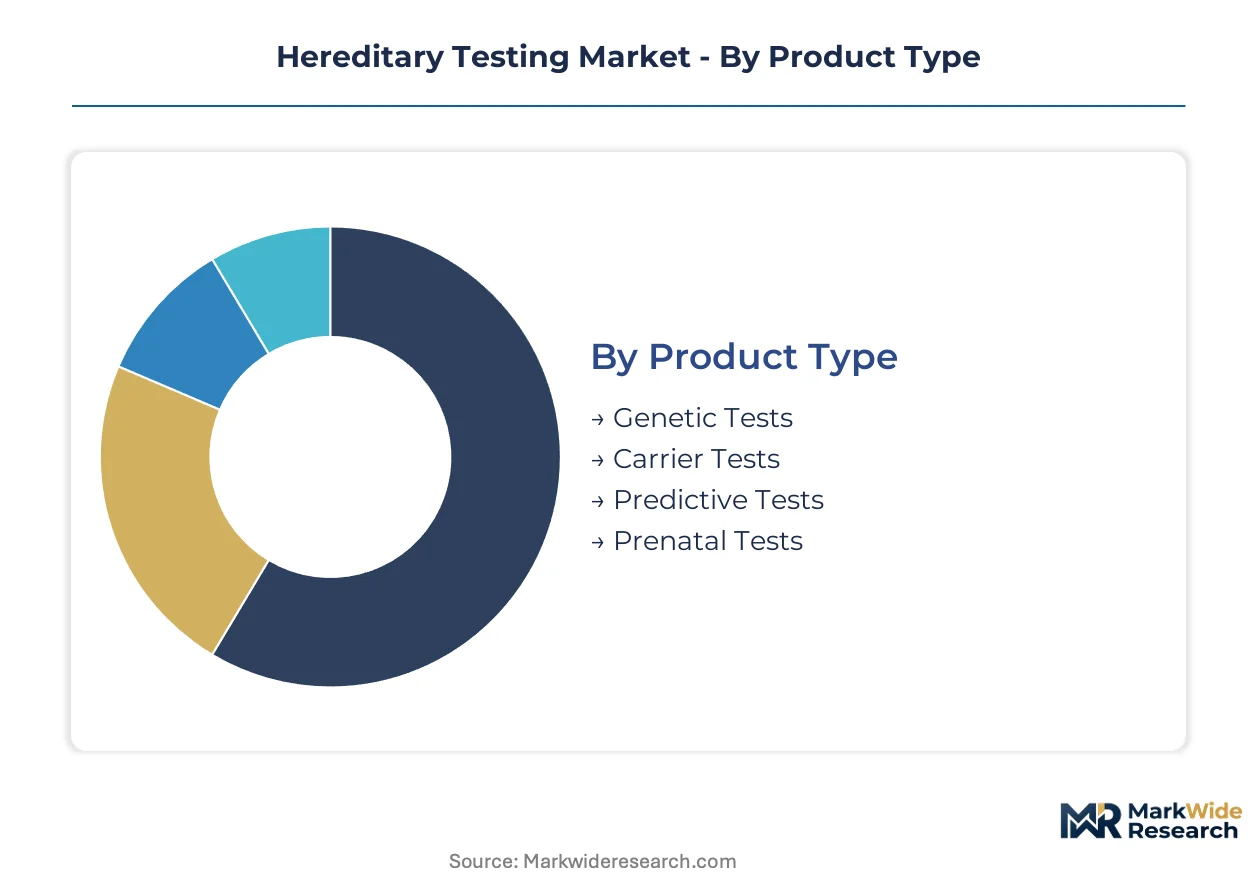
Segmentation in hereditary testing reveals how technology choices and clinical settings determine reimbursement pathways and margin structures. Product type and technology selections cascade through regulatory validation requirements and capital intensity, shaping competitive positioning across the value chain.
Product Type:
Mature diagnostic categories dominate current revenue while emerging predictive applications are reshaping volume trajectories and channel strategies.
- Genetic Tests:Broad-spectrum germline mutation panels analyze DNA from blood or saliva specimens to identify inherited pathogenic variants per ACMG guidelines. Academic medical centers in Texas and Massachusetts concentrate ordering volume for hereditary cancer panels, validating clinical utility through prospective outcome studies.
- Predictive Tests:Polygenic risk scores aggregate thousands of common variants to estimate susceptibility for cardiovascular conditions and oncologic disorders before symptom onset. Direct-to-consumer channels in California and New York attract healthy population demand through telehealth-integrated platforms that bypass traditional genetics clinic referrals.
- Carrier Tests:Targeted screening identifies autosomal recessive and X-linked mutations in prospective parents, typically ordered through obstetrics practices pre-conception or during early pregnancy.
- Prenatal Tests:Non-invasive cell-free fetal DNA analysis from maternal blood samples screens for aneuploidies and select microdeletions, concentrated at maternal-fetal medicine departments in tertiary hospitals.
Genetic Tests handles the majority of throughput; Predictive Tests is expanding most quickly on share.
Technology:
Cost tier stratification separates high-throughput platforms from legacy methodologies retained for confirmatory testing and regulatory compliance.
- Next-Generation Sequencing:Massively parallel short-read platforms sequence millions of DNA fragments simultaneously, reducing per-base costs below Sanger thresholds. The installed base at major cancer centers in Texas and Massachusetts anchors consumable pull-through and validates multi-gene panel clinical utility.
- Sanger Sequencing:First-generation capillary electrophoresis remains the gold standard for single-gene confirmatory testing and variant validation in clinical laboratories. Community hospital systems retain Sanger capacity for targeted BRCA1/2 and Lynch syndrome screening where NGS infrastructure investment is uneconomical.
- Polymerase Chain Reaction:Amplification-based detection of known pathogenic variants provides rapid turnaround for time-sensitive prenatal and neonatal screening decisions.
- Microarrays:Comparative genomic hybridization and SNP arrays detect copy number variations and large structural rearrangements in constitutional cytogenetics applications.
Next-Generation Sequencing commands the dominant capital investment; long-read platforms from Pacific Biosciences and Oxford Nanopore are gaining share fastest in structural variant detection.
End User:
Customer type determines specimen volume concentration, interpretation complexity, and integration requirements with electronic health record systems.
- Laboratories:High-complexity molecular pathology facilities process specimens from multiple ordering sites, requiring Laboratory Information System interoperability and board-certified genetic counselor staffing. Reference laboratories in Texas and Massachusetts accumulate clinical evidence for hereditary cancer panel validation.
- Hospitals:Integrated health systems manage pre-analytical workflow, specimen collection, and results delivery within oncology and cardiology service lines. Pediatric cardiology departments at Boston Children's Hospital and Texas Children's Hospital pilot long-read sequencing for hypertrophic cardiomyopathy panel refinement.
- Clinics:Community genetics and obstetrics practices order targeted panels with lower complexity interpretation requirements.
- Research Institutes:Academic centers generate prospective diagnostic accuracy data for regulatory submission and multicenter validation consortia.
Laboratories process the highest specimen volumes; direct-to-patient portals are displacing traditional clinic referrals fastest in states permitting consumer-initiated testing.
Application:
Application focus shapes reimbursement coding, evidence requirements, and competitive intensity across preventive versus diagnostic use cases.
- Cancer Screening:Hereditary breast, ovarian, colorectal, and pancreatic cancer panels identify germline mutations in BRCA1/2, Lynch syndrome genes, and CDH1. Academic medical center oncology departments expand panel ordering as FDA companion diagnostic co-approval pathways compress development timelines.
- Cardiovascular Risk Assessment:Hypertrophic cardiomyopathy, arrhythmogenic cardiomyopathy, and familial hypercholesterolemia panels detect structural variants and channelopathies. Long-read sequencing renders obsolete short-read assembly for complex structural variant detection, forcing payor contract renegotiation at Boston Children's Hospital and Texas Children's Hospital.
- Prenatal Screening:Cell-free DNA and carrier screening applications concentrate in maternal-fetal medicine and reproductive endocrinology practices.
- Rare Disease Diagnosis:Exome and genome sequencing for undiagnosed genetic disorders requires specialized interpretation and variant curation workflows.
Cancer Screening generates the majority of commercial revenue; Cardiovascular Risk Assessment is climbing the fastest as polygenic risk scores commercialize for healthy populations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: academic medical centers in the United States drive high-complexity panel volume, while Gulf Cooperation Council markets prioritize preventive screening mandates, and European laboratories navigate lengthened conformity assessments.
United States
Oncology departments at Texas and Massachusetts cancer centers concentrate hereditary cancer panel ordering, validating clinical utility through prospective outcome studies. FDA companion diagnostic co-approval pathways compress development timelines for multi-gene assays. The Texas Medical Center in Houston and Boston's Longwood Medical Area anchor reference laboratory infrastructure and board-certified genetic counselor staffing.
Germany
Academic pathology institutes respond to EMA In Vitro Diagnostic Regulation Article 56 requirements through multicenter validation consortia. Germany's national pharmaceutical regulator imposes clinical evidence thresholds exceeding prior CE marking self-certification. The Heidelberg and Berlin metropolitan areas coordinate prospective diagnostic accuracy studies to distribute regulatory compliance costs across university hospital networks.
Saudi Arabia
National preventive health mandates create procurement volume for hereditary cancer panels under Vision 2030 healthcare transformation. The country's national pharmaceutical regulator aligns Gulf Cooperation Council technical regulations with screening program requirements. Riyadh and Jeddah medical cities concentrate laboratory infrastructure deployment for population-scale germline testing.
United Kingdom
National Health Service genomic medicine service alliances consolidate hereditary testing procurement through designated genomic laboratory hubs. NHS England commissioning frameworks determine reimbursement eligibility for multi-gene panels. The Cambridge-Oxford-London triangle concentrates sequencing platform deployment and bioinformatics interpretation capacity.
Japan
PMDA regulatory pathways for companion diagnostics accelerate oncology panel approval timelines for academic hospital laboratories. METI industrial policy supports sequencing platform localization and consumable supply chain resilience. The Tokyo-Osaka corridor concentrates pharmaceutical company co-development partnerships and clinical trial enrollment for hereditary cancer indications.
Hereditary Testing Market Key Industry Players
Capability concentration sits with sequencing platform specialists; scale advantage sits with reference laboratory networks. The market structures around instrument-installed-base leverage, accumulated clinical evidence libraries, and direct-to-patient channel access. Three archetypes dominate: platform-anchored consumable suppliers, hereditary risk specialization firms, and telehealth-integrated testing portals. Competitive moves center on FDA companion diagnostic co-development partnerships and long-read sequencing platform transitions for structural variant detection.
Within the platform-anchored tier, Illumina, Inc. and Thermo Fisher Scientific Inc. represent sequencing infrastructure gatekeepers whose installed bases determine consumable pull-through economics. Myriad Genetics, Inc. occupies a specialization position in hereditary cancer risk assessment built on accumulated clinical evidence and payer contract density. Invitae Corporation exemplifies the channel-disruption archetype through transparent pricing and direct-to-patient portal strategies that bypass traditional genetics clinic referrals.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Myriad Genetics, Inc. |
| Invitae Corporation |
| Natera, Inc. |
| Thermo Fisher Scientific Inc. |
| F. Hoffmann-La Roche Ltd. |
| Quest Diagnostics Incorporated |
| CENTOGENE N.V. |
| Fulgent Genetics |
| Others |
Cost & Logistics Intelligence
Trans-Pacific air freight corridors from San Diego to Singapore carry sequencing reagents and consumables whose cost volatility feeds directly into laboratory pricing tiers and downstream test reimbursement negotiations at academic medical centers.
Pricing Analysis
Long-term offtake contracts between Illumina and major reference laboratories anchor consumable pricing, while spot-market purchases by smaller community hospitals face steeper per-run costs. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive multi-gene panels from targeted single-gene assays and basic carrier screens. Price differentiation hinges on turnaround time guarantees and genetic counselor interpretation depth. Pricing pressure stems from CMS molecular pathology fee schedule compression, with high-complexity sequencing panels experiencing the tightest margins. Community hospital laboratories exhibit the highest price sensitivity due to capital constraints, while Texas and Massachusetts cancer centers negotiate volume-based preferential rates.
Supply Chain Analysis
Export control regimes limiting next-generation sequencing instrument flows to China concentrate high-throughput platform manufacturing in the United States and Singapore. Sequencing consumable production clusters in California, Massachusetts, and South Korea supply flow cells, reagents, and library preparation kits. Raw material dependencies include semiconductor-grade silicon for flow cell manufacturing, fluorophores for signal detection, and synthetic oligonucleotides for probe synthesis. Single-source vulnerability in flow cell chemistry creates exposure to geographic disruption from seismic or trade policy events. Distribution runs through direct instrument sales teams for major platforms and third-party distributors for consumables and ancillary reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from long-read sequencing platforms that threaten to displace short-read infrastructure investments and obsolete existing reimbursement codes.
For Market Incumbents: Insulate installed-base economics by accelerating companion diagnostic co-development partnerships with oncology drug developers, locking in consumable pull-through through FDA-validated assay menus. Secure backward integration into library preparation reagent manufacturing to reduce exposure to third-party supply concentration. Counter Pacific Biosciences and Oxford Nanopore structural variant detection advantages by embedding short-read platforms into integrated health system electronic health record workflows.
For New Entrants and Emerging Players: Gulf Cooperation Council national screening programs offer procurement volume concentration with lower competitive density than United States academic medical centers. Target direct-to-patient channels in California and New York where state laboratory licensing permits consumer-initiated testing without physician intermediation. Pursue employer-sponsored wellness integration as a bypass route around hospital-based genetics clinic gatekeepers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors reference laboratory networks with accumulated clinical evidence libraries and payer contract density over pure-play platform developers. Long-term viability rests on variant interpretation workforce scaling and artificial intelligence-enabled reporting automation. Watch FDA guidance on artificial intelligence-enabled variant interpretation as the signal for regulatory validation cost inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Companion Diagnostic Co-Development | Parallel review processes with oncology drug sponsors compress time-to-reimbursement at academic medical center laboratories. |
| Long-Read Sequencing Platform Transition | Pediatric cardiology departments at Boston Children's Hospital and Texas Children's Hospital pilot structural variant detection for hypertrophic cardiomyopathy panels. |
| Direct-to-Patient Portal Expansion | Telehealth-integrated platforms in California and New York bypass traditional genetics clinic referrals for BRCA1/2 screening. |
| Artificial Intelligence Variant Classification | Machine learning interpretation tools reduce turnaround time and labor intensity for ACMG guideline-compliant reporting. |
| Gulf Cooperation Council Screening Program Entry | Saudi Arabia and UAE national preventive health mandates create procurement volume for hereditary cancer panels under Vision 2030. |
Research Approach
Two parallel data streams informed the analysis: structured interviews with laboratory directors, genetic counselors, molecular pathologists, and hospital procurement officers; and secondary validation against FDA 510(k) filings, CMS molecular pathology fee schedules, ClinicalTrials.gov hereditary testing protocols, and EMA In Vitro Diagnostic Regulation guidance documents. Bottom-up triangulation aggregated test volume estimates from state laboratory licensing databases, while top-down cross-checks applied instrument-installed-base economics to consumable pull-through assumptions.
Forecast inputs considered technology substitution curves for long-read versus short-read platforms, reimbursement code evolution under CMS, and regulatory timeline compression from FDA companion diagnostic pathways. Segmentation modeling spanned product type, technology, end user, and application dimensions across the projection horizon. CAGRs derived from logistic adoption curves for predictive test commercialization and linear extrapolation for mature diagnostic categories. Industry-specific inputs included genetic counselor workforce growth rates and artificial intelligence-enabled variant interpretation accuracy benchmarks.
The forecast holds incumbent behavior within observed patterns; aggressive moves by telehealth-integrated testing portals or long-read platform developers would shift outcomes through channel displacement or technology obsolescence. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Alagille Syndrome Market
Genomics
Genetic Testing Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Multiomics Market
Genomics
Global Nutrigenomics Market
Genomics
AI in Genomics Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Predisposition Biomarkers Market
Genomics
Next Generation Molecular Assay Market
Genomics
Microbiome Sequencing Outsourcing Services Market
Genomics
Agrigenomics Market
Genomics
RNA Transcriptome Profiling Test Market
Genomics
Transcriptomics Technologies Market
Genomics
Global Genotyping Assay Market
Genomics
Antisense Oligonucleotides Market
Genomics
Global Whole Genome Sequencing (WGS) Market