
 Next Generation Molecular Assay Market | 2026-2036
Next Generation Molecular Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Molecular Assay Market Foresight
Digital PCR chemistries are consolidating around fluorescent probe architectures that displace intercalating dye formats in high-sensitivity liquid biopsy workflows. Thermo Fisher Scientific leverages its TaqMan probe patent estate to anchor clinical assay standardization. Illumina competes through integrated sequencing-software bundles that tighten end-user switching costs. QIAGEN specializes in sample-to-insight automation that reduces hands-on time in diagnostic laboratories.
Next generation molecular assays encompass nucleic acid detection and quantification platforms employing amplification, hybridization, or sequencing chemistries with analytical sensitivity thresholds routinely reaching single-digit copies per microliter. These systems serve diagnostic, research, and therapeutic-monitoring applications where pathogen identification, mutation detection, or gene expression profiling drives clinical or developmental decisions. Real-Time PCR occupies the largest installed base and generates recurring consumable revenue streams, while CRISPR-based diagnostics represent the fastest-expanding technology segment as guide-RNA engineering matures. Oncology commands the deepest margin pools among application categories, though infectious disease testing sustains higher test volumes through seasonal respiratory panels and emerging pathogen surveillance.
FDA breakthrough device designations compress premarket review timelines for novel molecular assays, while CLIA laboratory certification requirements shape quality management investments across diagnostic laboratories. The EPA and OSHA maintain overlapping jurisdiction over chemical reagent handling in high-throughput facilities, creating compliance complexity for multi-site operators. Stakeholders must monitor evolving CMS coverage determinations for companion diagnostics, as reimbursement decisions increasingly gate commercial adoption velocity for platform launches.
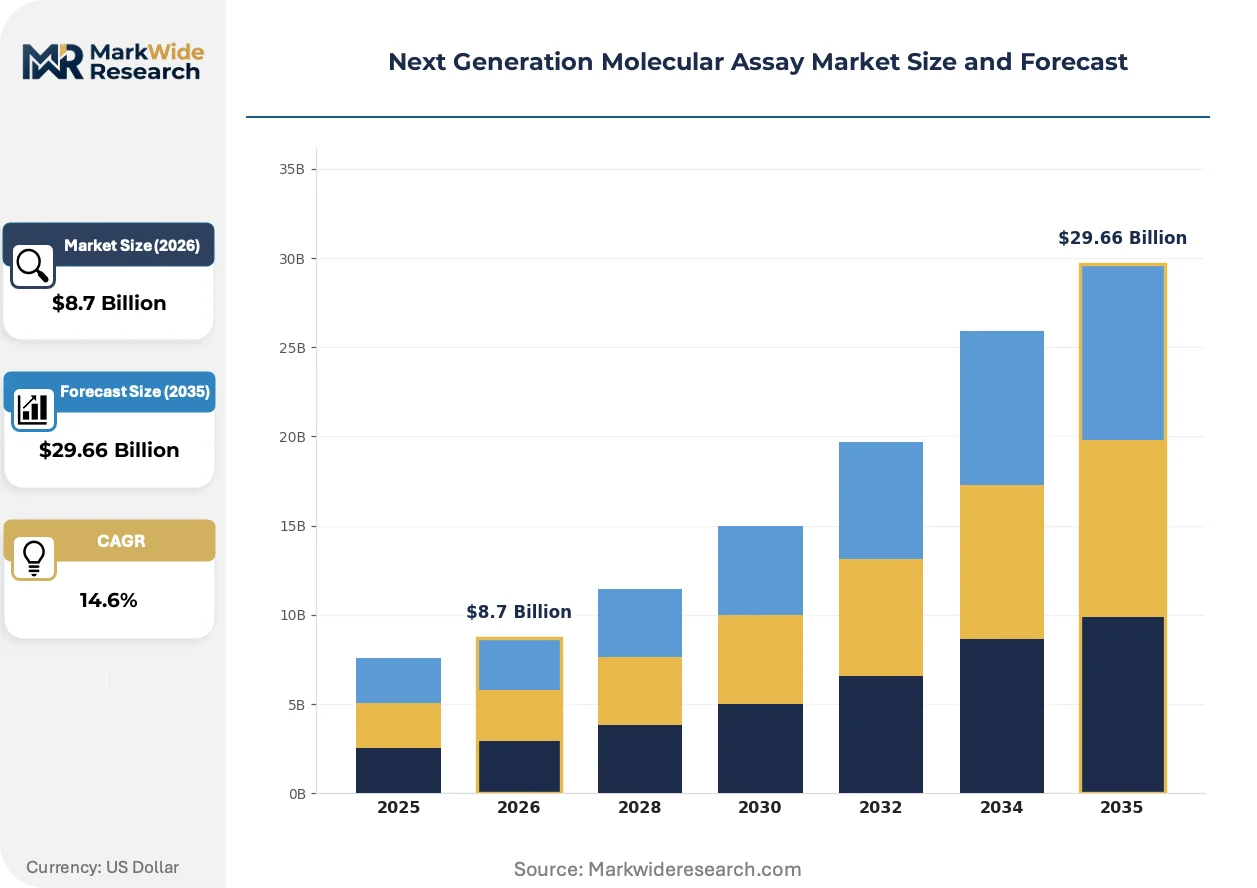
Market Dynamics
Digital PCR chemistries are consolidating around fluorescent probe architectures that displace intercalating dye formats in high-sensitivity liquid biopsy workflows. This technology shift is compressing competitive margins for legacy dye-based assay providers while concentrating purchasing power among academic medical centers expanding molecular profiling programs.
Growth Catalysts
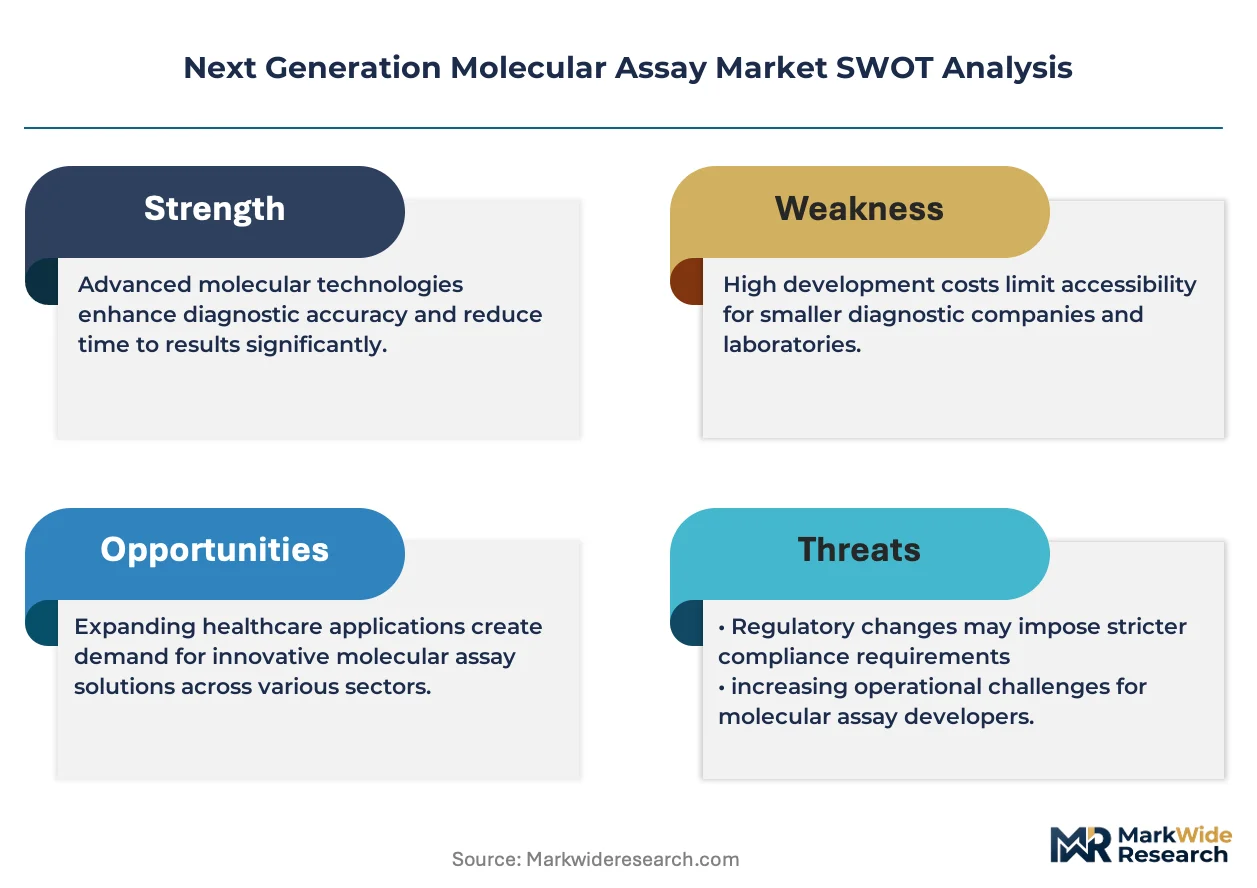
- FDA Breakthrough Device Designation:The pathway accelerates premarket review timelines for novel assay platforms, compressing commercialization cycles for developers targeting oncology companion diagnostics.
- CRISPR-based diagnostics:Guide-RNA engineering maturation is expanding the fastest-growing technology segment, enabling single-molecule detection without thermal cycling infrastructure.
- Boston-Cambridge biotech corridor:Concentrated venture deployment and academic-industry partnerships in this cluster are validating novel chemistries at scale before national rollout.
Market Restraints
- Reagent cost volatility:Fluorescent probe synthesis depends on specialty phosphoramidite chemistry supply concentrated in German and Swiss fine chemical manufacturers.
- CLIA certification complexity:Laboratory certification requirements create multi-site quality management burdens that favor large reference laboratories over independent hospital labs.
- Sequencing substitution threat:Integrated sequencing-software bundles from dominant platform providers tighten end-user switching costs and displace amplification-based workflows in research settings.
Strategic Opportunities
- Sample-to-insight automation:Pre-analytical workflow integration reduces hands-on time in diagnostic laboratories, creating white space for vendors with end-to-end platform architectures.
- Seasonal respiratory panel expansion:Infectious disease surveillance applications sustain higher test volumes than oncology, with emerging pathogen detection mandates creating recurring demand.
- CMS coverage determination alignment:Reimbursement decisions for companion diagnostics increasingly gate commercial adoption velocity, rewarding early engagement with the agency's evidence development framework.
Industry Challenges
- Bioinformatics integration complexity:Assay platforms require seamless data pipelines into electronic health records, creating implementation friction for laboratories with legacy IT infrastructure.
- Cross-jurisdictional compliance:EPA and OSHA maintain overlapping chemical reagent handling requirements, forcing multi-site operators to maintain redundant safety protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Molecular Assay Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR, NGS, Microarray, LAMP Technology: Real-Time PCR, CRISPR, Sanger Sequencing, RNA Sequencing Application: Oncology, Infectious Diseases, Genetic Testing, Personalized Medicine End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies |
| Companies Covered | Thermo Fisher Scientific, Illumina, F. Hoffmann-La Roche Ltd, Abbott, QIAGEN, Danaher, bioMérieux, Hologic, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Molecular Assay Market Shifts & Advancements
Probe-based detection architectures are absorbing market share from intercalating dye formats as sensitivity requirements intensify for circulating tumor DNA applications. This chemistry transition is reshaping competitive positioning among platform developers and reagent suppliers.
Fluorescent probe architectures are absorbing analytical workflows previously dominated by SYBR Green intercalation methods. Academic medical centers in the United States are adopting these chemistries for minimal residual disease monitoring. The technology shift is absorbing technical staff training budgets while compressing error rates in low-abundance mutation detection.
EMA's In Vitro Diagnostic Medical Devices Regulation is tightening performance evaluation requirements for companion diagnostics entering the European market. Manufacturers must now submit expanded clinical evidence packages that extend development timelines by twelve to eighteen months. Oncology assay developers are responding by front-loading European clinical validation studies to maintain parallel FDA-EMA submission strategies.
Laboratory procurement committees are consolidating vendor relationships around integrated platform-service bundles that unbundle traditional reagent-only supply contracts. Hospital systems are replacing multi-vendor fragmentation with sole-source agreements covering instrumentation, consumables, and bioinformatics support. This concentration pattern is most visible in United States academic medical centers where capital planning cycles favor five-year total cost of ownership models over per-test pricing.
Next Generation Molecular Assay Market Segmentation
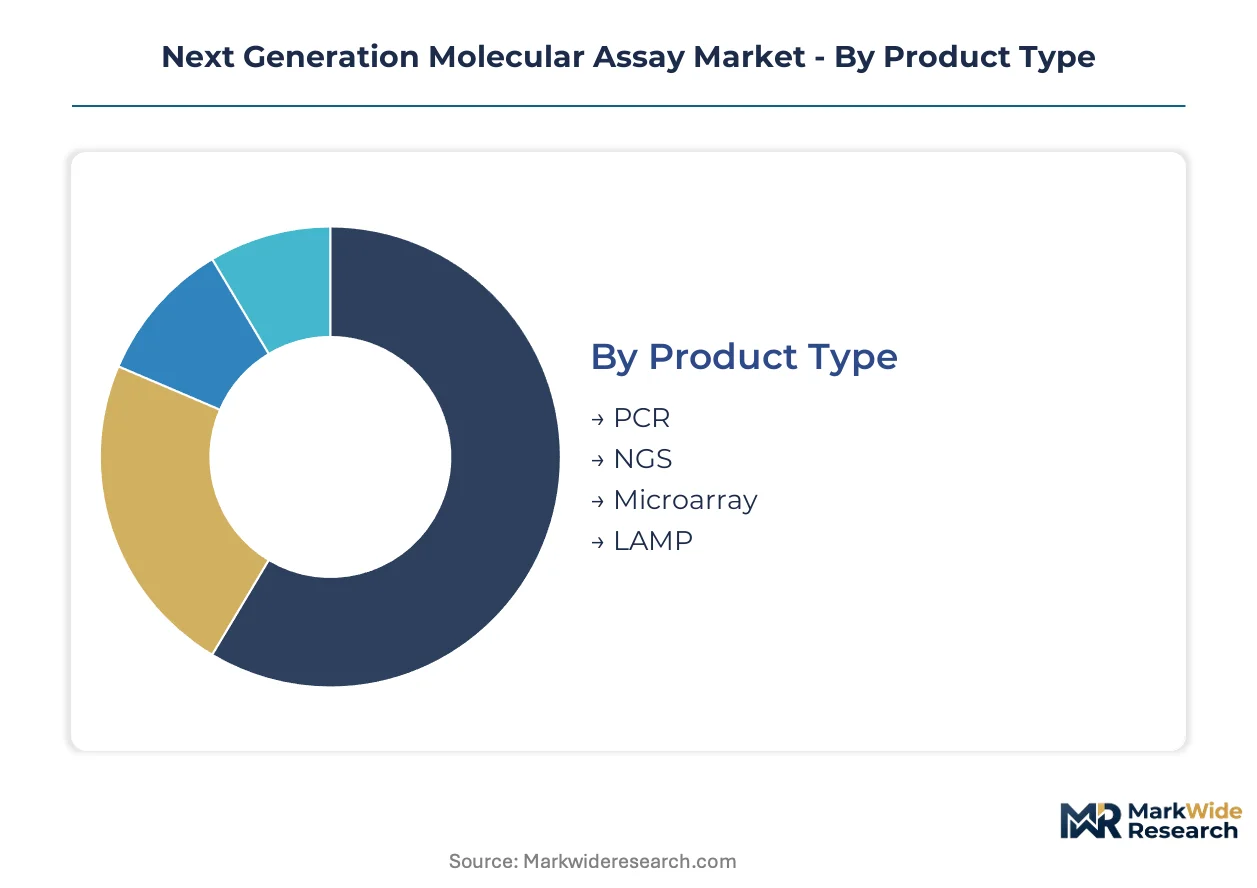
Technology heterogeneity in next generation molecular assays creates distinct purchasing patterns across clinical and research settings. Procurement committees evaluate platforms against workflow integration, regulatory clearance status, and total cost of ownership over five-year depreciation cycles.
Product Type:
PCR platforms command the largest installed base and generate recurring consumable revenue, while NGS systems capture premium pricing in comprehensive profiling applications.
- PCR:Thermal cycling instrumentation with fluorescent detection chemistries dominates infectious disease testing and oncology companion diagnostics. Demand concentrates in United States hospital laboratories seeking CLIA-certified workflows for seasonal respiratory panels.
- NGS:Massively parallel sequencing platforms enable comprehensive mutation profiling and minimal residual disease monitoring. Academic medical centers in the Boston-Cambridge corridor deploy these systems for research-to-clinic translation programs.
- Microarray:Hybridization-based detection of known variants supports pharmacogenomic screening and carrier testing applications.
- LAMP:Isothermal amplification eliminates thermal cycling infrastructure requirements, enabling point-of-care deployment in resource-limited settings.
Mature deployment sits with PCR. Newer deployment is concentrated in NGS.
Technology:
Real-Time PCR maintains workflow standardization advantages, while CRISPR-based methods are gaining share fastest in point-of-care diagnostics.
- Real-Time PCR:Quantitative amplification with probe-based detection provides gold-standard sensitivity for viral load monitoring and mutation quantification. Diagnostic laboratories in the United States standardize on this chemistry for FDA-cleared assay implementation.
- CRISPR:Guide-RNA programmable nucleic acid detection enables single-molecule sensitivity without thermal cycling. Emerging pathogen surveillance programs are validating these platforms for field-deployable testing.
- Sanger Sequencing:First-generation chain-termination chemistry remains essential for confirmatory sequencing of targeted variants.
- RNA Sequencing:Transcriptome-wide expression profiling supports biomarker discovery and immune monitoring in immuno-oncology trials.
Established regulatory pathways favor Real-Time PCR. CRISPR platforms are climbing the fastest in development pipelines.
Application:
Oncology generates the deepest margin pools per test, while infectious disease applications sustain higher annual test volumes through recurring screening mandates.
- Oncology:Companion diagnostic testing for targeted therapies and minimal residual disease monitoring commands premium reimbursement. United States academic medical centers are expanding molecular profiling programs to support precision oncology trials.
- Infectious Diseases:Syndromic respiratory panels and antimicrobial resistance profiling drive high-throughput testing in hospital core laboratories. Seasonal demand fluctuations require flexible platform capacity planning.
- Genetic Testing:Hereditary disease screening and carrier testing support reproductive health and pediatric diagnostic workflows.
- Personalized Medicine:Pharmacogenomic assay integration into electronic health records enables genotype-guided prescribing decisions.
Revenue concentration favors Oncology. Volume expansion is steepest in Infectious Diseases.
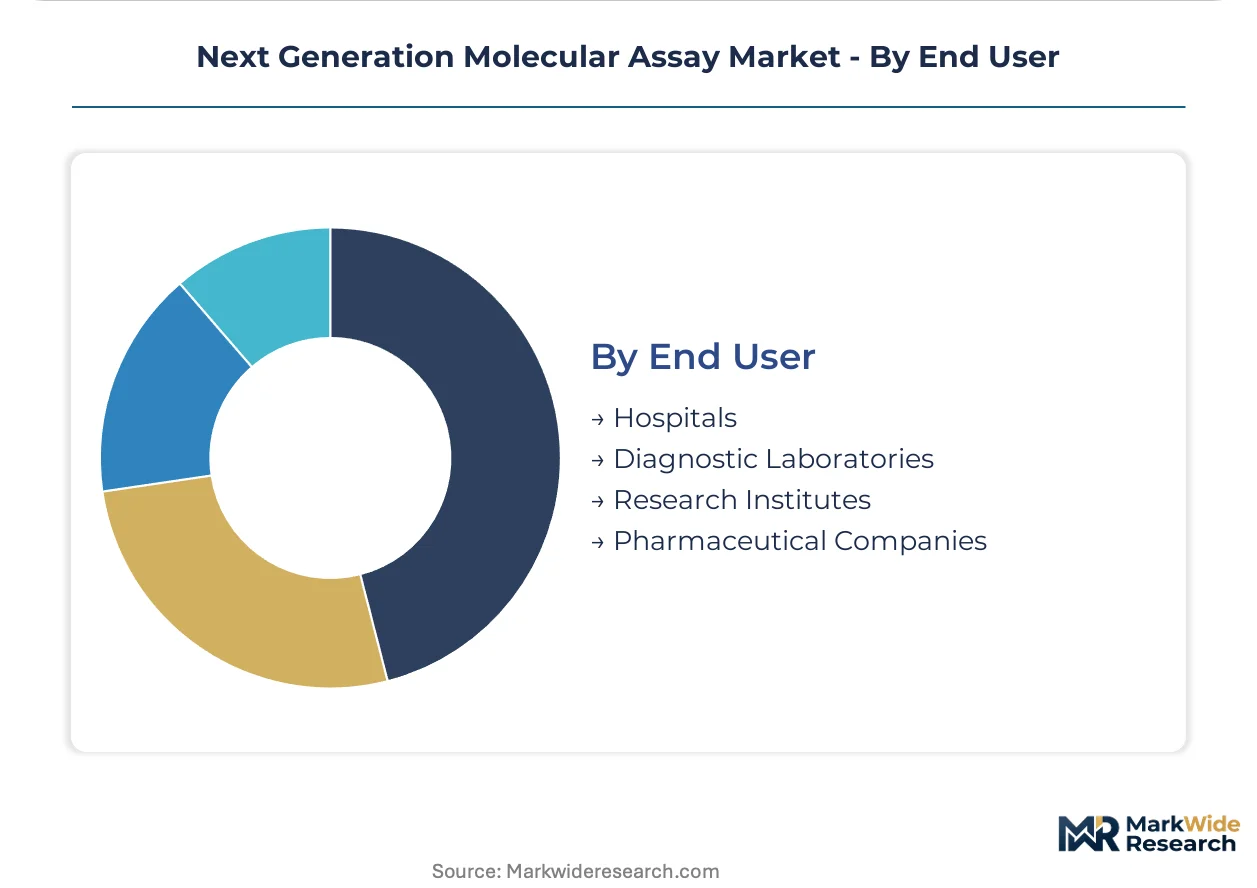
End User:
Diagnostic Laboratories consolidate purchasing power through multi-year sole-source agreements, while Research Institutes prioritize technology flexibility over regulatory clearance status.
- Hospitals:In-house molecular pathology laboratories require integrated sample-to-insight workflows with LIS connectivity. Capital planning committees in United States health systems favor vendors offering comprehensive service contracts.
- Diagnostic Laboratories:High-throughput reference laboratories achieve economies of scale through automated pre-analytical processing and batched assay runs. Multi-site quality management requirements favor large operators with dedicated compliance staff.
- Research Institutes:Academic laboratories prioritize novel chemistry access and publication support over clinical-grade validation documentation.
- Pharmaceutical Companies:Drug developers deploy molecular assays for patient stratification in clinical trials and companion diagnostic co-development programs.
Instrument purchasing authority sits with Diagnostic Laboratories. Assay development partnerships concentrate in Pharmaceutical Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States academic medical centers command the deepest concentration of molecular profiling demand, with the Boston-Cambridge corridor validating novel chemistries at scale before broader commercial deployment.
United States
FDA breakthrough device designations compress premarket review timelines for oncology companion diagnostics, while CLIA certification requirements shape multi-site quality management investments. The Boston-Cambridge biotech corridor concentrates venture deployment and academic-industry partnerships that validate novel assay platforms.
Germany
Specialty phosphoramidite chemistry supply for fluorescent probe synthesis concentrates among fine chemical manufacturers, creating reagent cost volatility for downstream assay developers. EMA's In Vitro Diagnostic Medical Devices Regulation tightens performance evaluation requirements for companion diagnostics entering the European market. The Rhine-Main cluster hosts precision medicine initiatives integrating molecular profiling into standard oncology care pathways.
Switzerland
Swissmedic maintains stringent clinical evidence standards for IVD market authorization that parallel EMA requirements. Diagnostic laboratories in the Basel-Zurich corridor achieve economies of scale through automated pre-analytical processing and batched assay runs. Pharmaceutical companies headquartered in this region deploy molecular assays for patient stratification in clinical trials.
United Kingdom
NHS England's genomic medicine service expands molecular profiling access through centralized laboratory networks. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device regulations with EU MDR frameworks to maintain market access continuity. London-Oxford-Cambridge life science clusters concentrate CRISPR-based diagnostic development programs.
China
NMPA accelerates review pathways for innovative IVD products targeting oncology and infectious disease applications. Domestic manufacturers scale production of isothermal amplification platforms for point-of-care deployment in resource-limited settings. The Yangtze River Delta biotech corridor attracts venture investment for next-generation sequencing infrastructure expansion.
Next Generation Molecular Assay Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform providers capturing premium pricing in comprehensive profiling applications while reagent suppliers defend consumable revenue streams in high-volume infectious disease testing. Market structure tilts toward consolidation among multi-technology conglomerates with end-to-end workflow capabilities. Three archetypes dominate: sequencing-software bundlers, sample-to-insight automation specialists, and probe-chemistry patent holders. Competitive dynamics center on strategic partnerships for bioinformatics integration and capacity expansion in fluorescent probe synthesis.
Among diversified life science conglomerates, Thermo Fisher Scientific anchors the probe-chemistry tier through its TaqMan patent estate, while Illumina occupies a position exemplifying sequencing-software bundling strategies. QIAGEN represents the sample-to-insight automation archetype with pre-analytical workflow integration capabilities.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Illumina |
| F. Hoffmann-La Roche Ltd |
| Abbott |
| QIAGEN |
| Danaher |
| bioMérieux |
| Hologic |
| Agilent Technologies |
| Others |
Supply & Pricing Matrix
Specialized bioinformatics workforce concentration in the Boston-Cambridge corridor widens pricing-tier spreads between premium assay platforms and commoditized reagent kits, as labor-cost differentials compound with CLIA certification overhead to stratify end-user procurement budgets.
Pricing Analysis
Volume-margin splits separate infectious disease testing from oncology companion diagnostics, with high-throughput respiratory panels commanding per-unit transactional pricing while minimal residual disease monitoring sustains subscription-based instrument-service bundles. Price differentiation hinges on FDA clearance tier and after-sales bioinformatics support depth. Cost compression in intercalating dye formats intensifies as probe-based architectures capture liquid biopsy workflows. Reference laboratories exhibit highest price sensitivity, while academic medical centers prioritize performance specifications over per-test economics.
Supply Chain Analysis
Single-source vulnerability sits with German and Swiss specialty phosphoramidite manufacturers that anchor fluorescent probe synthesis. Raw material dependencies span phosphoramidite monomers, Taq polymerase enzymes, and optical-grade fluorophores. Tariff exposure on Chinese-sourced isothermal amplification reagents compounds logistics chokepoint risks at Rotterdam and Long Beach ports. Distribution runs through authorized distributor networks serving hospital laboratories and direct-to-laboratory contracts for high-volume reference operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where FDA breakthrough device designation requirements erect barrier-to-entry moats favoring incumbent platform developers with dedicated regulatory affairs infrastructure.
For Market Incumbents: Deploy TaqMan probe patent licensing as a defensive lever against CRISPR-based diagnostic entrants, while expanding captive fluorescent probe synthesis capacity in the Rhine-Main cluster to neutralize reagent cost volatility from German fine chemical suppliers. For New Entrants and Emerging Players: Launch via LAMP-based point-of-care distribution partnerships targeting resource-limited settings in China and Southeast Asia, where isothermal amplification bypasses thermal cycling infrastructure requirements and NMPA accelerated review pathways compress regulatory timelines. For Investors and Strategic Acquirers: Re-rating potential sits with sample-to-insight automation specialists given CMS coverage determination alignment for companion diagnostics, as reimbursement velocity increasingly gates commercial adoption. Long-term viability favors platforms with end-to-end workflow integration spanning pre-analytical processing to LIS connectivity. The signal to watch is hospital system sole-source consolidation patterns in United States academic medical centers.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket review compresses commercialization cycles for oncology companion diagnostics developers. |
| Phosphoramidite Sourcing Diversification | Multi-source procurement from German and Swiss suppliers mitigates reagent cost volatility in probe synthesis. |
| Hospital System Partnership | Sole-source agreements with United States academic medical centers lock in five-year total cost of ownership contracts. |
| Software Companion Development | Seamless EHR integration reduces implementation friction for laboratories with legacy IT infrastructure. |
| Reimbursement Strategy Alignment | Early CMS engagement with evidence development frameworks gates commercial adoption velocity for platform launches. |
Research Methodology
FDA 510(k) filings, CMS coverage determination databases, and EMA In Vitro Diagnostic Medical Devices Regulation guidance documents formed the secondary backbone, cross-referenced with primary interviews involving clinical laboratory directors, diagnostic platform R&D heads, hospital procurement committee members, and GPO contracts managers. Bottom-up assay volume modeling and top-down market sizing triangulation validated segment-level outputs.
Historical trendline analysis of installed base growth and consumable pull-through rates anchored the projection framework across technology, application, and end-user dimensions. CAGRs derived from regression-adjusted growth curves incorporated regulatory approval velocity, reimbursement expansion trajectories, and chemistry transition adoption slopes. Segment-level forecasts integrated CLIA laboratory certification expansion rates and academic medical center capital planning cycle timing.
Regulatory pathway delays, reimbursement determination reversals, and phosphoramidite supply disruptions are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about chemistry transition timelines and hospital consolidation patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Metagenomics Market
Genomics
Hereditary Testing Market
Genomics
Global Immune Repertoire Sequencing Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Gene Sequencing Market
Genomics
Cytogenetic Systems Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Global Single Nucleotide Polymorphism (SNP) Genotyping Market
Genomics
Microbiome Sequencing Outsourcing Services Market
Genomics
Rare Disease Genetic Testing Market
Genomics
DNA Sequencing Market
Genomics
Genomics and Transcriptomics Market
Genomics
Immunogenetics Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Latin America Next Generation Sequencing Market
Genomics
Targeted DNA RNA Sequencing Market