
 Transcriptomics Technologies Market | 2026-2036
Transcriptomics Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Transcriptomics Technologies Market Analysis
Platform licensing revenue is reshaping competitive economics in transcriptomics, as vendors monetize recurring software access alongside consumables. Illumina leverages its installed base of sequencers to sustain high-margin reagent pull-through. Thermo Fisher Scientific anchors its position through integrated sample-to-analysis workflows spanning extraction through interpretation. QIAGEN differentiates via automated RNA purification systems that reduce hands-on time in high-throughput settings.
Transcriptomics technologies encompass methods for quantifying and analyzing RNA molecules within biological samples, employing techniques such as next-generation sequencing with read depths exceeding 100 million reads per sample to capture full transcriptome complexity. These technologies serve primary industrial purposes in drug target identification, biomarker discovery, and patient stratification for precision therapeutic development. RNA-Seq dominates technology value capture due to its unbiased detection of novel transcripts and splice variants, while qPCR retains stronghold in regulated diagnostic validation where absolute quantification standards apply. Drug discovery applications command substantial investment flows as pharmaceutical sponsors integrate transcriptomic endpoints into early-stage toxicity screening, though personalized medicine represents the fastest-expanding application segment as companion diagnostic frameworks mature.
The FDA regulates transcriptomics-based diagnostics through its in vitro diagnostic and clinical laboratory improvement amendment pathways, requiring analytical and clinical validation for RNA biomarker tests deployed in patient care decisions. The EMA's MDR framework in Europe imposes stricter performance evaluation and post-market surveillance obligations on transcriptomics device manufacturers seeking CE marking. ISO 13485 quality management standards govern manufacturing processes for reagents and instruments destined for clinical applications. Stakeholders must monitor evolving reimbursement decisions for RNA-based companion diagnostics across national health technology assessment bodies, as coverage determinations will dictate commercial viability of emerging transcriptomic tests.
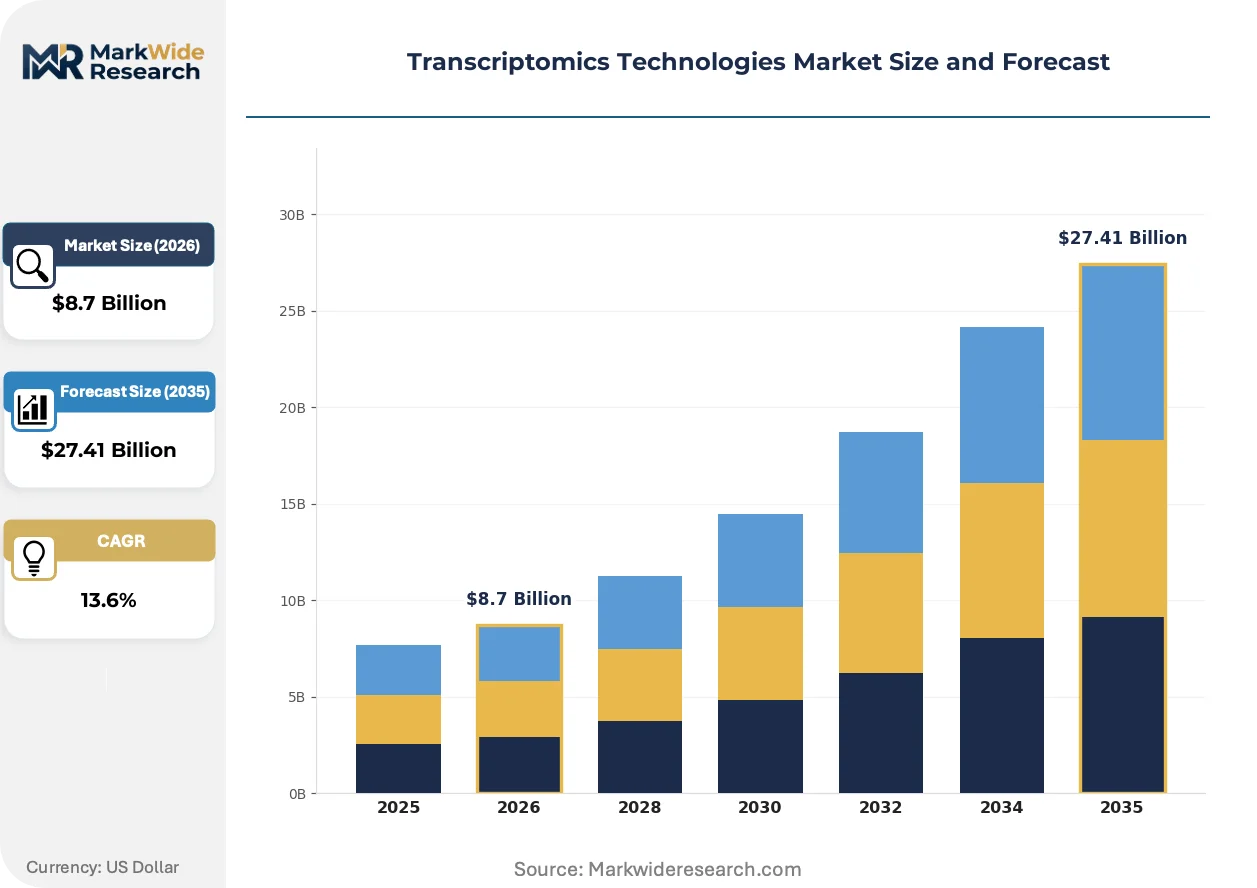
Market Dynamics
Platform licensing revenue is restructuring competitive economics in transcriptomics, as vendors monetize recurring software access alongside consumables to sustain margin profiles amid sequencing commoditization.
Growth Catalysts
- FDA Precision Medicine Guidance:The FDA's in vitro diagnostic pathway creates regulatory clarity for RNA biomarker commercialization, accelerating companion diagnostic development timelines for pharmaceutical sponsors.
- NIH Funding Concentration:Federal research allocations cluster around Boston and San Francisco biotechnology corridors, concentrating capital deployment for transcriptomics infrastructure expansion.
- RNA-Seq Technology Maturation:Next-generation sequencing platforms now deliver read depths exceeding 100 million reads per sample, enabling unbiased detection of novel transcripts and splice variants for drug target identification.
Market Restraints
- Reagent Cost Volatility:Specialized enzymes and modified nucleotides for RNA sequencing workflows face supply concentration among limited qualified suppliers, creating input cost instability.
- Analytical Validation Burden:Europe's MDR framework imposes stricter performance evaluation and post-market surveillance obligations, extending CE marking timelines for transcriptomics device manufacturers.
- qPCR Substitution Threat:Quantitative PCR retains stronghold in regulated diagnostic validation where absolute quantification standards apply, limiting RNA-Seq penetration in clinical laboratory settings.
Strategic Opportunities
- Personalized Medicine Expansion:Companion diagnostic frameworks are maturing fastest in oncology and rare disease indications, creating white space for transcriptomic patient stratification tools.
- Sample-to-Analysis Integration:Automated RNA purification systems are converging with cloud-based bioinformatics pipelines, reducing hands-on time for high-throughput pharmaceutical screening operations.
- India Biopharma Outsourcing:Contract research organizations in Hyderabad and Bangalore are building transcriptomics capabilities to serve Western pharmaceutical sponsors seeking cost-efficient target validation.
Industry Challenges
- Bioinformatics Talent Scarcity:Computational biology expertise for transcriptome interpretation remains concentrated among elite academic institutions, constraining workforce scaling for commercial operations.
- ISO 13485 Certification Timelines:Quality management system implementation for clinical-grade reagent manufacturing requires 18-24 month validation cycles, delaying market entry for emerging vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transcriptomics Technologies Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $27.41 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RNA-Seq, Microarray, qPCR, Digital Droplet PCR Application: Clinical Diagnostics, Drug Discovery, Agricultural Biotechnology, Personalized Medicine End User: Research Institutions, Pharmaceutical Companies, Academic Laboratories, Biotech Firms Delivery Mode: Cloud-Based Solutions, On-Premise Solutions, Hybrid Solutions, SaaS |
| Companies Covered | 10x Genomics, Illumina, Thermo Fisher Scientific, Agilent Technologies, Bio-Rad Laboratories, QIAGEN, Roche, BGI Genomics, NanoString Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transcriptomics Technologies Market Emerging Trajectories
Single-cell resolution capabilities are displacing bulk transcriptome analysis in pharmaceutical discovery workflows, while spatial transcriptomics adds tissue context that bulk methods cannot capture.
Spatial transcriptomics platforms are hybridizing imaging-based RNA detection with next-generation sequencing readouts, enabling researchers to map gene expression across intact tissue sections. Pharmaceutical toxicology groups adopt these hybrid systems to localize off-target drug effects within organ architecture. The technology is compressing traditional histopathology timelines by integrating molecular and morphological endpoints into single analytical workflows.
Europe's MDR framework tightens analytical validation requirements for RNA-based diagnostics, mandating clinical performance studies that exceed predecessor directive standards. Device manufacturers must now submit post-market surveillance plans as part of initial CE marking applications. Transcriptomics test developers are responding by front-loading clinical utility studies to preempt national health technology assessment rejections.
Pharmaceutical procurement departments now unbundle after-sales bioinformatics support from instrument purchases, treating computational analysis as a separate vendor category. Large-cap biopharma sponsors negotiate multi-year software access agreements independent of hardware maintenance contracts. This purchasing pattern is most visible among Boston and San Francisco headquartered companies with centralized transcriptomics operations.
Transcriptomics Technologies Market Segmentation
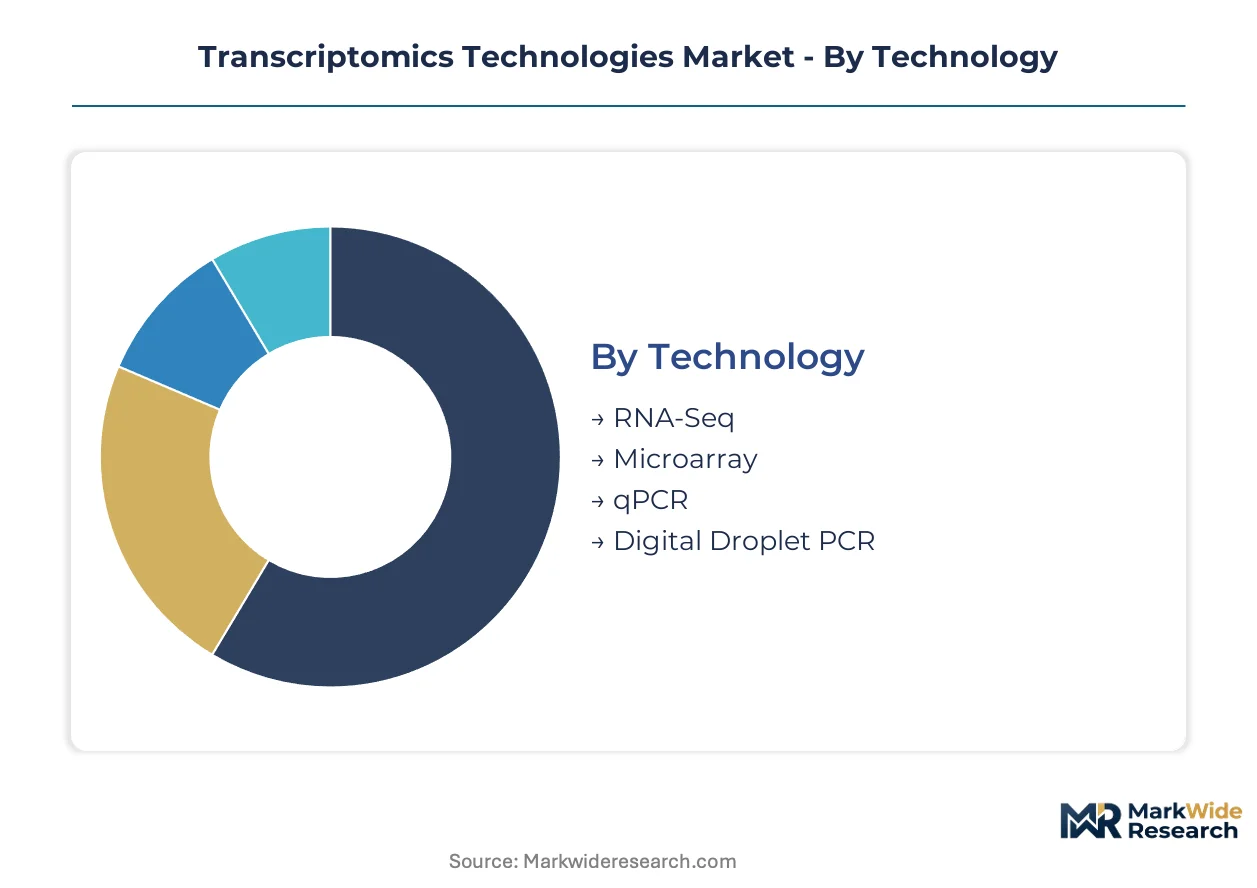
Technology heterogeneity in transcriptomics creates distinct investment profiles across platforms, with sequencing depth and regulatory compliance requirements driving divergent procurement patterns among end users.
Technology:
Mature sequencing platforms anchor commercial workflows while emerging digital PCR variants capture specialized quantification niches.
- RNA-Seq:Next-generation sequencing platforms deliver read depths exceeding 100 million reads per sample, enabling unbiased detection of novel transcripts and splice variants. Pharmaceutical sponsors in Boston and San Francisco biotechnology corridors deploy RNA-Seq for target identification workflows, though reagent cost volatility constrains budget predictability.
- qPCR:Quantitative PCR retains dominance in regulated diagnostic validation where absolute quantification standards apply under FDA in vitro diagnostic pathways. Clinical laboratories favor qPCR for companion diagnostic deployment due to established analytical validation frameworks and shorter regulatory timelines.
- Microarray:Hybridization-based expression profiling serves high-throughput screening operations with standardized probe sets.
- Digital Droplet PCR:Partitioned amplification technology enables rare transcript detection with single-molecule sensitivity.
RNA-Seq handles the majority of throughput; Digital Droplet PCR is the fastest mover on share.
Application:
Cost tiering separates capital-intensive discovery applications from reimbursement-dependent clinical deployments.
- Drug Discovery:Transcriptomic endpoints integrate into early-stage toxicity screening across pharmaceutical sponsor portfolios. RNA-Seq and spatial transcriptomics platforms command premium pricing for target validation contracts, with procurement concentrated among Boston and San Francisco headquartered companies.
- Personalized Medicine:Companion diagnostic frameworks mature fastest in oncology indications, creating demand for patient stratification tools. EMA MDR compliance requirements extend CE marking timelines for RNA biomarker tests, though coverage determinations by national health technology assessment bodies ultimately dictate commercial viability.
- Clinical Diagnostics:Regulated testing environments prioritize qPCR and ISO 13485-certified workflows.
- Agricultural Biotechnology:Crop trait discovery and livestock breeding programs adopt transcriptomics for marker-assisted selection.
Drug Discovery absorbs the largest capital allocation; Personalized Medicine is climbing the fastest on investment intensity.
End User:
Customer type determines procurement sophistication, with centralized pharmaceutical operations negotiating multi-year software access agreements independent of hardware contracts.
- Pharmaceutical Companies:Large-cap biopharma sponsors unbundle after-sales bioinformatics support from instrument purchases, treating computational analysis as a separate vendor category. Procurement departments in Boston and San Francisco headquarters centralize transcriptomics operations under dedicated infrastructure budgets.
- Research Institutions:NIH funding concentration supports infrastructure expansion across Boston and San Francisco biotechnology corridors. Federal research allocations prioritize RNA-Seq platform deployment for basic science investigations with publication-driven output metrics.
- Academic Laboratories:Grant-funded operations favor cost-efficient qPCR and microarray workflows.
- Biotech Firms:Venture-backed companies in San Francisco and Boston leverage cloud-based bioinformatics to minimize capital expenditure.
Pharmaceutical Companies dominate absolute spending; Biotech Firms are gaining share fastest on normalized R&D intensity.
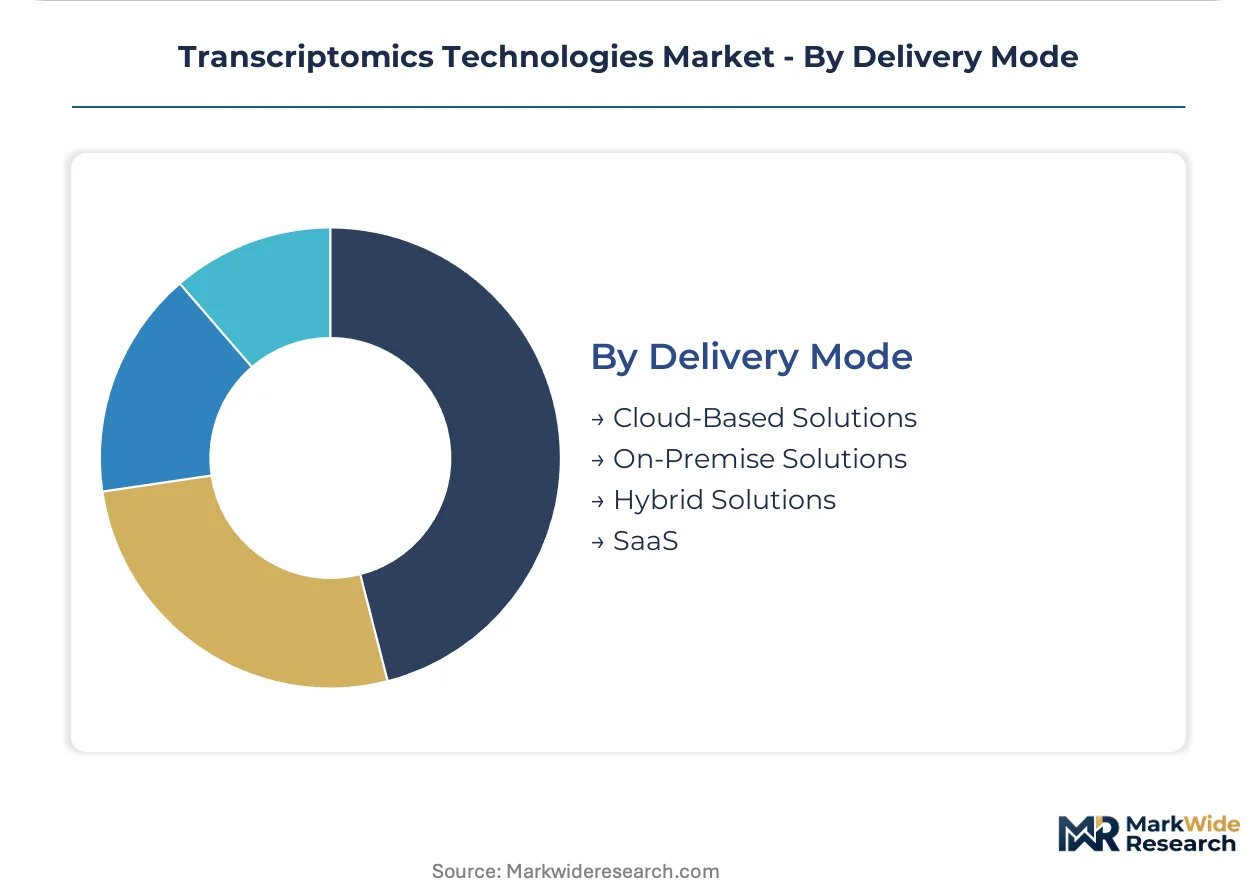
Delivery Mode:
Volume scaling favors cloud architectures for distributed research networks, while on-premise solutions retain traction in data sovereignty-sensitive environments.
- Cloud-Based Solutions:Scalable compute resources support high-throughput pharmaceutical screening operations with pay-per-analysis pricing models. Vendors monetize recurring software access alongside consumables, restructuring competitive economics toward subscription revenue streams.
- On-Premise Solutions:Local data retention addresses institutional requirements for genomic data protection in academic medical centers. Installation base concentration among Boston and San Francisco research hospitals sustains maintenance contract profitability.
- Hybrid Solutions:Mixed deployment architectures balance sensitive data local processing with elastic cloud compute for secondary analysis.
- SaaS:Software-as-a-service bioinformatics pipelines reduce hands-on time for automated RNA purification integration.
Cloud-Based Solutions carry the dominant transaction volume; SaaS is expanding most quickly on new customer acquisition.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharma procurement teams in the United States demonstrate the lowest price elasticity for transcriptomics platforms, while academic laboratories in India and contract research organizations in China operate under severe budget constraints that favor reagent rental models and shared infrastructure arrangements.
United States
NIH funding concentration drives platform deployment across Boston and San Francisco biotechnology corridors. FDA precision medicine guidance accelerates companion diagnostic development timelines for RNA biomarker commercialization. Pharmaceutical sponsors headquartered in Cambridge and South San Francisco unbundle bioinformatics support from instrument purchases, treating computational analysis as a separate vendor category.
China
National biotech industrial policy prioritizes domestic sequencing platform development to reduce import dependency. NMPA regulatory pathways for in vitro diagnostics impose clinical validation requirements on RNA-based tests. BGI Genomics anchors production capacity in Shenzhen while contract research organizations in Suzhou and Hangzhou build transcriptomics service capabilities for Western pharmaceutical sponsors.
Germany
Federal research funding through the German Research Foundation supports RNA sequencing infrastructure at Max Planck Institutes and university medical centers. EMA MDR framework extends CE marking timelines for transcriptomics device manufacturers seeking European market access. Heidelberg and Munich host concentrated pharmaceutical R&D operations integrating transcriptomic endpoints into early-stage toxicity screening.
India
CDSCO regulatory harmonization efforts align with ICH guidelines to attract multinational clinical trial investment. PLI scheme incentives for medical device manufacturing reduce landed costs for RNA purification instruments. Hyderabad and Bangalore contract research organizations build transcriptomics capabilities to serve Western pharmaceutical sponsors seeking cost-efficient target validation workflows.
United Kingdom
UK Research and Innovation funding streams prioritize single-cell and spatial transcriptomics platform access for academic consortia. MHRA post-Brexit regulatory autonomy maintains alignment with FDA and EMA standards for RNA biomarker test validation. London and Cambridge life science clusters concentrate venture-backed biotech firms leveraging cloud-based bioinformatics to minimize capital expenditure.
Transcriptomics Technologies Market Vendor Landscape
Capability concentration sits with integrated platform vendors; scale advantage sits with consumables-led business models. The market structures around three tiers: sequencing instrument manufacturers capturing high-margin reagent pull-through, sample preparation specialists automating RNA purification workflows, and bioinformatics providers monetizing recurring software access. Strategic moves center on unbundling after-sales support from hardware contracts and consolidating cloud-based analysis pipelines.
Within the integrated platform tier, Illumina and Thermo Fisher Scientific exemplify divergent approaches to sustaining margin profiles amid sequencing commoditization. QIAGEN occupies a position among sample-to-analysis workflow specialists. 10x Genomics sits within the emerging spatial and single-cell resolution segment. BGI Genomics represents the China-based scale-driven archetype competing on instrument cost and service throughput.
| Leading Market Players |
|---|
| 10x Genomics |
| Illumina |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Bio-Rad Laboratories |
| QIAGEN |
| Roche |
| BGI Genomics |
| NanoString Technologies |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese sequencing instrument manufacturing compresses margin structures for reagent suppliers across the United States and Germany, forcing vendors to bundle after-sales bioinformatics support as a pricing lever to sustain lifetime value capture.
Pricing Analysis
After-sales revenue tiers including multi-year software access agreements and cloud-based bioinformatics subscriptions now drive lifetime value for platform vendors. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical sponsors with dedicated infrastructure budgets from academic laboratories operating under NIH grant constraints. Price differentiation rests on ISO 13485 certification status and geographic delivery cost for clinical-grade reagents. Margins are tightening due to reagent cost volatility in specialized enzymes and modified nucleotides. Contract research organizations in India demonstrate the highest price sensitivity, while large-cap biopharma sponsors in Boston and San Francisco show the lowest elasticity.
Supply Chain Analysis
Supplier-financing facilities including extended payment terms for sequencing instruments anchor procurement relationships between vendors and capital-constrained academic laboratories. Manufacturing concentration sits in the United States for high-margin reagent production, China for instrument assembly, and Germany for precision optical components. The supply chain draws from modified nucleotides, flow cell substrates, and specialized polymerases as critical inputs. Single-source vulnerability in qualified enzyme suppliers creates structural risk for RNA-Seq workflow continuity. Distribution runs through direct sales forces for pharmaceutical accounts and authorized distributors for academic and clinical laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-cell and spatial transcriptomics capabilities are disrupting bulk analysis workflows, with FDA precision medicine guidance accelerating the regulatory inflection for companion diagnostic commercialization.
For Market Incumbents: Pre-empt emerging entrant pressure in automated RNA purification by consolidating cloud-based bioinformatics pipelines under unified subscription architectures. Deepen backward integration into flow cell manufacturing to reduce dependency on German optical component suppliers. Anchor capacity expansion in Hyderabad and Bangalore to capture cost-efficient pharmaceutical outsourcing demand. For New Entrants and Emerging Players: Build out spatial transcriptomics service capabilities for toxicology groups seeking integrated molecular-morphological endpoints. Target agricultural biotechnology applications in India and China where regulatory pathways remain less mature than clinical diagnostics. Pursue reagent rental models and shared infrastructure arrangements to penetrate budget-constrained academic segments. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sample-to-analysis workflow specialists with automated RNA purification platforms. Long-term viability favors vendors with installed base density in Boston and San Francisco biotechnology corridors. Watch for NMPA regulatory harmonization signals in China as an inflection indicator for domestic platform substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Licensing Expansion | Recurring software access agreements restructure competitive economics beyond consumables revenue. |
| Sample-to-Analysis Integration | Automated RNA purification convergence with cloud pipelines reduces pharmaceutical screening timelines. |
| Spatial Transcriptomics Development | Hybrid imaging-sequencing systems capture tissue context that bulk methods cannot deliver. |
| CE Marking Pathway Investment | EMA MDR compliance extends timelines but secures European market access for RNA diagnostics. |
| India Biopharma Outsourcing | Hyderabad and Bangalore CROs build cost-efficient target validation capabilities for Western sponsors. |
Methodological Framework
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and cloud platform engineers anchored the qualitative base for this study. Primary interviews combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and NIH funding databases. Bottom-up segment sizing triangulated against top-down macro indicators including federal research allocations and pharmaceutical R&D expenditure trends.
Scenario-bracketing framed the analytical approach across the analysis window, modeling technology adoption curves by application segment and end-user archetype. Segmentation dimensions included sequencing platform type, regulatory pathway cluster, and geographic procurement sophistication. CAGRs derived from instrument placement trajectories, reagent consumption intensity, and software subscription conversion rates. Forecast inputs incorporated spatial transcriptomics adoption velocity and MDR compliance timeline assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by China-based scale-driven instrument manufacturers would shift outcomes. Macroeconomic contraction in NIH funding, regulatory deviation in FDA precision medicine guidance, or technological disruption from digital PCR substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
North America Epigenetics Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Spatial OMICS Market
Genomics
Forensic Genomics Market
Genomics
Genome Sequencing Market
Genomics
DNA Mass Ladder Market
Genomics
Omics Lab Services Market
Genomics
North America Microarray Market
Genomics
Mitochondrial DNA Market
Genomics
Global Optical Genome Mapping Market
Genomics
DNA Diagnostics Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
Genetic Material Market
Genomics
China Genetic Testing Market
Genomics
Europe Whole Exome Sequencing Market