
 Asia-Pacific Quad-Flat-No-Lead Packaging Market | 2026-2036
Asia-Pacific Quad-Flat-No-Lead Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Quad-Flat-No-Lead Packaging Market Insights
JEDEC J-STD-020 moisture sensitivity qualification is collapsing the supplier base eligible for automotive and medical-grade contracts. ASE Group leverages its Kaohsiung mega-site to sustain captive substrate supply for high-volume consumer programs. JCET Group anchors Jiangsu province operations with government-backed advanced packaging R&D centers. Tongfu Microelectronics differentiates through thermal QFN specialization for power management ICs serving domestic smartphone OEMs.
Asia-Pacific Quad-Flat-No-Lead Packaging denotes a surface-mount integrated circuit package with copper lead-frame and exposed thermal pad, typically spanning 2x2mm to 12x12mm body sizes with 0.4mm to 0.65mm terminal pitch, designed for automated assembly and enhanced thermal dissipation in space-constrained electronics. The primary purpose is enabling high-density interconnection for power management, RF transceivers, and sensor fusion chips while eliminating gull-wing leads that obstruct miniaturization. Thermal QFN commands premium positioning as electric vehicle inverter modules and 5G base station amplifiers drive copper-heavy, multi-row configurations. RF QFN shows the steepest trajectory as mmWave antenna-in-package designs proliferate across South Korean and Taiwanese smartphone supply chains. Standard QFN remains the volume workhorse but faces margin compression from Chinese domestic suppliers.
China's MIIT enforces GB/T semiconductor reliability standards that mandate lead-free solder compatibility and halogen-free substrate materials, while Taiwan's ITRI coordinates industry roadmaps aligning local QFN producers with international automotive electronics council guidelines. Japan's METI promotes JIS-standard green procurement rules that restrict certain flame retardants in plastic-molded packages, reshaping material selection across regional substrate vendors. Stakeholders must monitor how China's dual carbon goals and Taiwan's renewable energy transition requirements reshape foundry-packaging energy cost structures and location decisions.
Market Dynamics
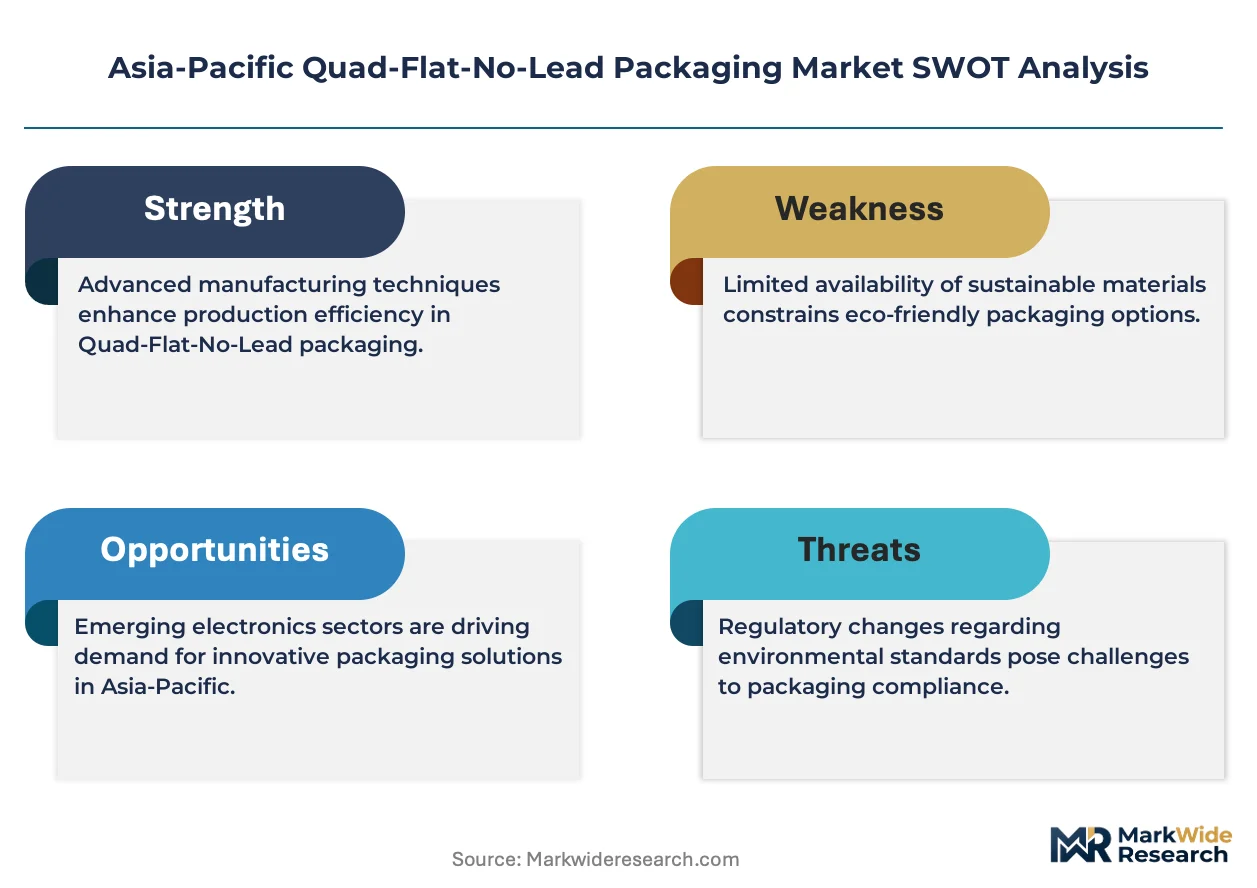
Foundry-packaging co-location in Taiwan's Hsinchu corridor is compressing cycle times and locking in regional supply dominance as Chinese substrate suppliers face MIIT-mandated process upgrades.
Growth Catalysts
- Copper-clip thermal architectures:Electric vehicle inverter modules require multi-row QFN configurations with enhanced dissipation, pulling substrate capacity toward automotive-qualified lines.
- MIIT green manufacturing mandates:China's tightening halogen-free and lead-free standards are accelerating supplier consolidation toward embedded-die and copper-heavy processes.
- mmWave antenna-in-package proliferation:South Korean and Taiwanese smartphone OEMs are expanding RF QFN orders for compact 5G transceiver integration.
Market Restraints
- Substrate material cost volatility:Copper and epoxy molding compound prices fluctuate with energy costs, squeezing margins on standard QFN volume programs.
- JEDEC qualification barriers:Moisture sensitivity level certification under J-STD-020 collapses the supplier base eligible for automotive and medical-grade contracts.
- Flip-chip BGA substitution:High-pin-count power management ICs above 100 I/O are migrating to flip-chip packages with superior electrical performance.
Strategic Opportunities
- India's electronics manufacturing clusters:PLI scheme incentives for semiconductor packaging are attracting QFN investments in Gujarat and Tamil Nadu greenfield sites.
- Medical device miniaturization:Wearable diagnostic sensors require ultra-small 2x2mm QFN formats with biocompatible molding compounds.
- Dual carbon goal alignment:China's renewable energy transition creates demand for power management ICs in solar inverters and energy storage systems.
Industry Challenges
- Automotive AEC-Q100 certification timelines:Extended qualification cycles for thermal cycling and temperature-grade testing delay revenue recognition on new product ramps.
- Packaging-fabless IP coordination:Complex die-package co-design requirements for RF QFN antenna-in-package configurations strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Quad-Flat-No-Lead Packaging Market |
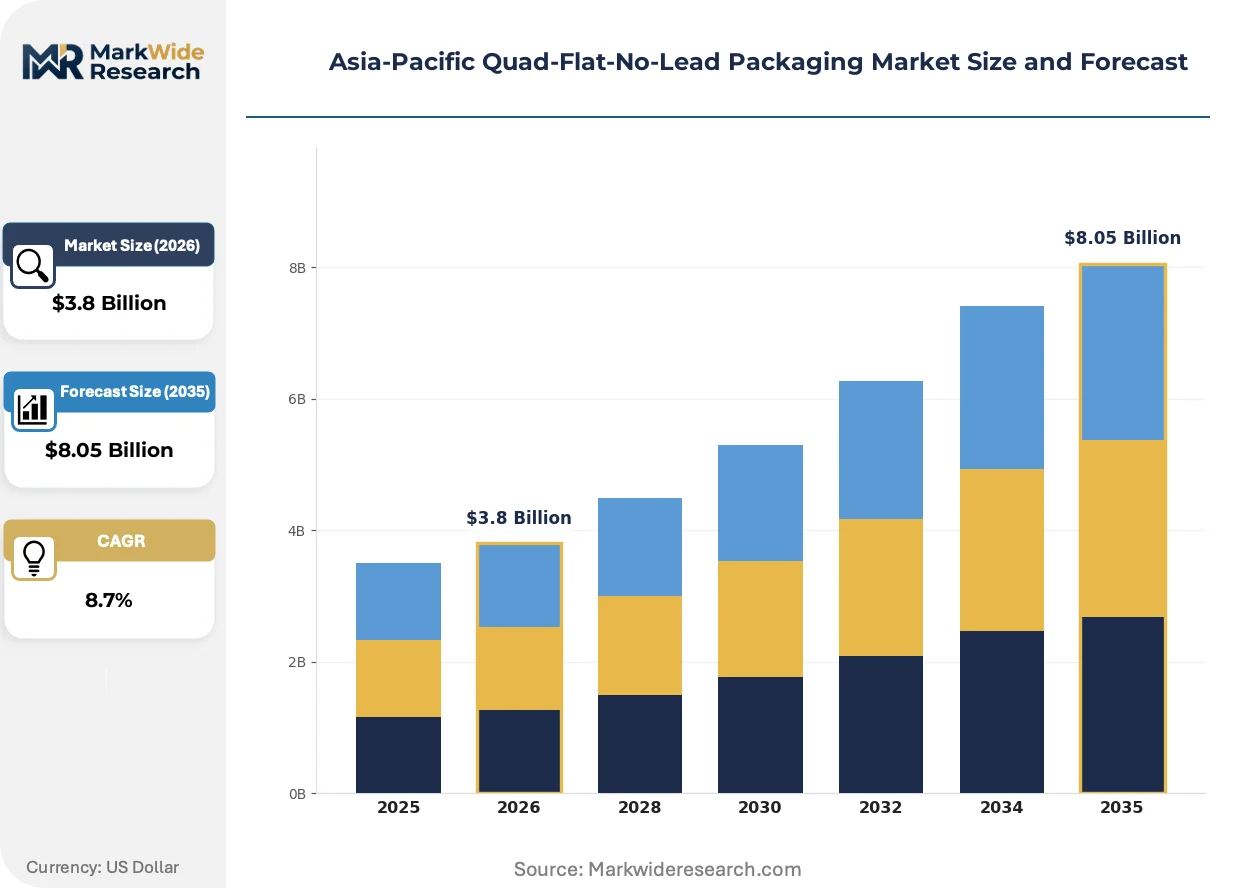
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard QFN, Thermal QFN, RF QFN, Automotive QFN End User: Consumer Electronics, Industrial Equipment, Medical Devices, Telecommunications Material: Plastic, Ceramic, Metal, Composite Application: Smartphones, Wearables, IoT Devices, Automotive Electronics |
| Companies Covered | Powertech Technology, Tongfu Microelectronics, JCET Group, STATS ChipPAC, ChipMOS TECHNOLOGIES, ASE Group, Tianshui Huatian Technology, Fujitsu, Amkor Technology, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Quad-Flat-No-Lead Packaging Market Trends and Innovations
Thermal management architectures and regulatory material bans are splitting the QFN market into premium automotive-medical tiers and cost-optimized consumer tiers.
Embedded-die QFN with active components inside the package substrate is bifurcating the competitive landscape. Electric vehicle power module suppliers are adopting these configurations for inverter integration at accelerated pace. This technology is bifurcating the supplier base into captive substrate producers and outsourced assembly houses.
METI's JIS-standard green procurement rules restrict specific flame retardants in plastic-molded packages. Japanese substrate vendors are reformulating epoxy molding compounds to eliminate brominated compounds. Medical and industrial QFN segments in Japan are absorbing premium pricing for halogen-free certified materials.
Buyer consolidation among South Korean smartphone OEMs is compressing supplier negotiation cycles. Long-term frame contracts with volume guarantees are displacing spot-market purchasing for RF QFN. This concentration is most visible in Seoul-Suwon supplier corridors serving flagship 5G handset programs.
Asia-Pacific Quad-Flat-No-Lead Packaging Market Segmentation
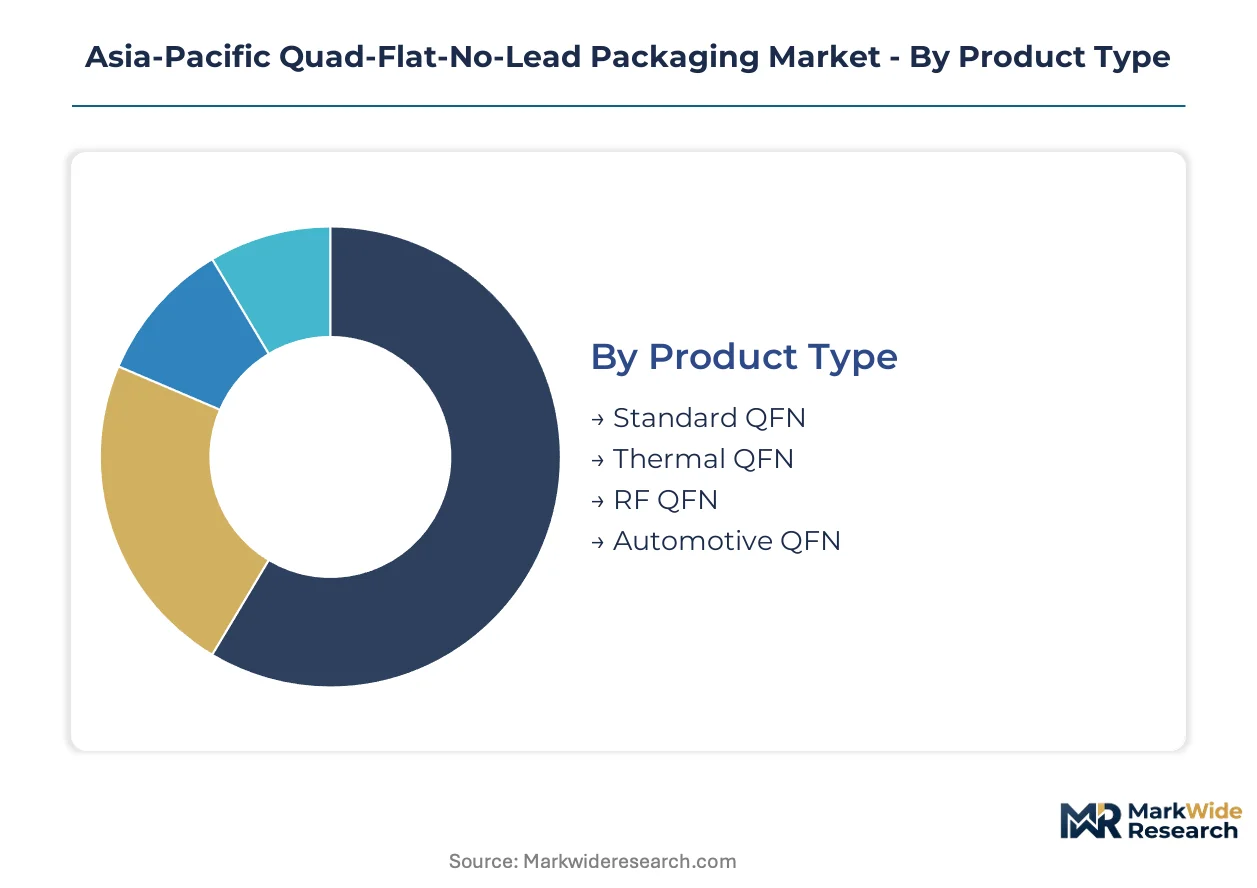
QFN packaging configurations diverge sharply across thermal performance tiers and regulatory compliance grades, with material selection and end-use certification creating distinct margin architectures. Understanding these segment boundaries exposes where substrate suppliers can defend pricing power versus where Chinese domestic competition erodes returns.
Product Type:
Premium positioning concentrates in thermally enhanced and RF-optimized variants where copper-clip architectures and antenna-in-package integration command qualification-linked pricing.
- Thermal QFN:Multi-row copper-clip configurations with exposed thermal pads enable 150W+ dissipation for electric vehicle inverter modules. ASE Group and Tongfu Microelectronics anchor capacity in Taiwan's Hsinchu corridor and Jiangsu province respectively, pulling substrate supply toward automotive-qualified lines as MIIT green standards tighten material specifications.
- RF QFN:mmWave antenna-in-package designs integrate transceiver dies with compact matching networks for 5G handset programs. South Korean smartphone OEMs in Seoul-Suwon corridors have shifted procurement to long-term frame contracts with volume guarantees, compressing supplier negotiation cycles and locking in Taiwanese and Korean substrate vendors.
- Standard QFN:Volume workhorse for consumer power management ICs with single-row leadframes and basic thermal performance. Chinese domestic suppliers dominate this tier, driving margin compression through aggressive pricing on legacy 0.5mm pitch configurations.
- Automotive QFN:AEC-Q100 qualified variants with enhanced temperature cycling resistance and JEDEC J-STD-020 Level 1 moisture sensitivity. Extended qualification timelines delay revenue recognition, restricting the supplier base to captive substrate producers with in-house reliability testing.
The dominant share belongs to Standard QFN, while RF QFN is closing the gap fastest.
End User:
Customer procurement patterns split between high-mix-low-volume medical-industrial programs and massive consumer electronics runs with stringent cost-down schedules.
- Consumer Electronics:Smartphone and tablet OEMs drive the majority of Asia-Pacific QFN demand, with South Korean and Taiwanese manufacturers specifying ultra-thin 0.55mm maximum package height for flagship handset programs. JCET Group's government-backed R&D centers in Jiangsu province target this segment with embedded-die process development.
- Automotive Electronics:Electric vehicle power module suppliers require multi-row thermal QFN with operating temperature ranges extending to 175°C. Taiwan's ITRI coordinates local producers with international automotive electronics council guidelines, creating a regional qualification pathway distinct from Chinese MIIT standards.
- Industrial Equipment:Factory automation and motor control applications favor standard QFN with extended temperature grades but less stringent thermal cycling requirements than automotive tiers.
- Medical Devices:Wearable diagnostic sensors demand 2x2mm ultra-small formats with biocompatible halogen-free molding compounds certified under Japan's METI JIS-standard green procurement rules.
Consumer Electronics captures the largest volume position, though Automotive Electronics exhibits the steepest expansion trajectory as EV inverter module demand accelerates.
Material:
Substrate material selection increasingly hinges on regulatory compliance rather than purely technical performance, with halogen-free mandates reshaping vendor qualification.
- Plastic:Epoxy molding compounds dominate standard and thermal QFN production, with Japanese substrate vendors reformulating to eliminate brominated flame retardants under METI restrictions. Medical and industrial segments in Japan absorb premium pricing for certified halogen-free materials.
- Metal:Copper leadframes with nickel-palladium-gold or silver plating enable high-current thermal QFN configurations for automotive power modules. China's MIIT tightening of green manufacturing standards pushes suppliers toward copper-clip processes with reduced plating variability.
- Ceramic:High-frequency RF QFN for mmWave applications leverages low-loss alumina or aluminum nitride substrates, though cost limits deployment to flagship 5G handset programs.
- Composite:Hybrid organic-inorganic substrates for embedded-die QFN integrate active components within the package body, bifurcating the supplier base between captive substrate producers and outsourced assembly houses.
Plastic substrates maintain overwhelming volume share, while Metal substrates gain ground fastest under automotive thermal dissipation requirements.
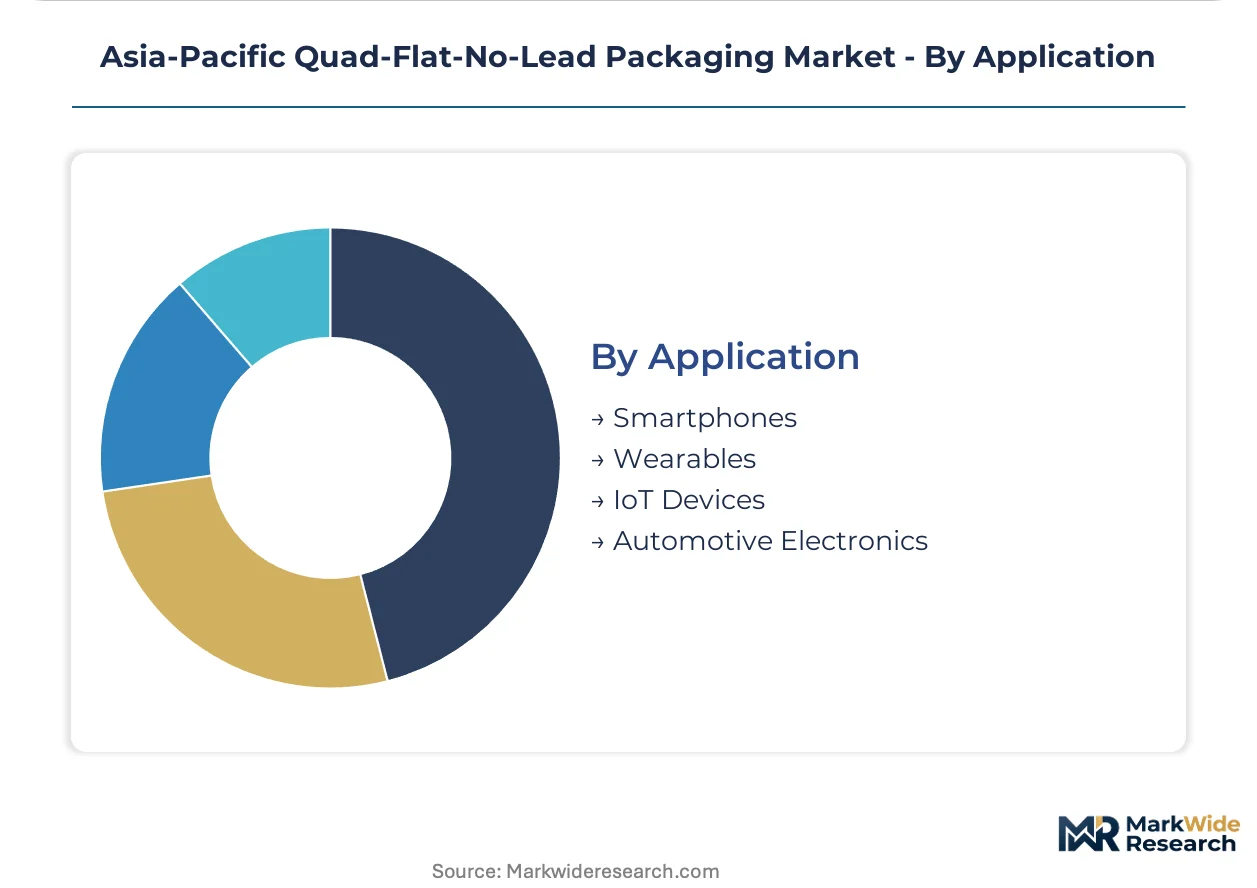
Application:
Device miniaturization trajectories and power density requirements create divergent specification clusters across portable and fixed installations.
- Smartphones:Flagship 5G handset programs in South Korea and Taiwan specify RF QFN with integrated antenna matching networks, driving mmWave antenna-in-package proliferation. Buyer consolidation among Seoul-based OEMs has compressed supplier qualification cycles to 18 months from 24.
- Automotive Electronics:Electric vehicle inverter modules and onboard chargers require thermal QFN with copper-clip architectures and operating junction temperatures to 175°C. Taiwan's foundry-packaging co-location in Hsinchu shortens cycle times for these high-reliability programs.
- Wearables:Ultra-small 2x2mm and 3x3mm formats with sub-0.5mm total thickness serve hearable and fitness tracker applications. Biocompatible molding compound certification under Japanese green procurement rules adds 15-20% material cost premium.
- IoT Devices:Industrial sensor nodes and smart home controllers favor cost-optimized standard QFN with basic thermal performance, exposing this segment to Chinese domestic supplier competition.
Smartphones retain the leading application position, while Automotive Electronics is expanding most quickly as EV power module demand reshapes substrate capacity allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smartphone OEM procurement teams in Seoul and Taipei dominate RF QFN contract volumes, while automotive power module suppliers in Shanghai and Nagoya pull substrate capacity toward thermal-grade lines. Foundry-packaging co-location advantages concentrate demand in specific industrial corridors.
China
MIIT's tightening GB/T reliability standards for halogen-free substrates are accelerating supplier consolidation toward embedded-die processes. The dual carbon goals mandate energy efficiency audits for packaging facilities in Jiangsu and Guangdong provinces. JCET Group anchors government-backed R&D centers in Jiangsu, pulling domestic smartphone OEM supply chains toward advanced packaging capabilities.
Taiwan
ITRI coordinates local QFN producers with international automotive electronics council guidelines, creating a distinct qualification pathway from mainland standards. The Hsinchu Science Park corridor hosts foundry-packaging co-location that compresses cycle times for high-reliability programs. ASE Group leverages its Kaohsiung mega-site to sustain captive substrate supply for consumer electronics volume.
South Korea
Seoul-based smartphone OEMs have compressed supplier qualification cycles to 18 months while shifting procurement to long-term frame contracts with volume guarantees. MFDS medical device regulations are creating demand for biocompatible molding compounds in wearable diagnostic applications. The Seoul-Suwon supplier corridor serves flagship 5G handset programs with concentrated RF QFN orders.
Japan
METI's JIS-standard green procurement rules restrict brominated flame retardants in plastic-molded packages, forcing substrate vendors to reformulate epoxy molding compounds. Medical and industrial QFN segments absorb premium pricing for certified halogen-free materials. Fujitsu maintains positioning in the Nagoya-Tokyo corridor for high-reliability industrial applications.
India
PLI scheme incentives for semiconductor packaging are attracting QFN investments in Gujarat and Tamil Nadu greenfield sites. The country's national electronics manufacturing clusters offer tax holidays for packaging facilities serving export markets. Domestic smartphone assembly growth is creating pull for standard QFN formats in Noida and Sri City industrial zones.
Asia-Pacific Quad-Flat-No-Lead Packaging Market Competitive Landscape
Player mix skews toward diversified packaging houses with captive substrate capabilities and government-backed domestic champions. The supplier base bifurcates between premium-tier automotive-medical specialists and volume-focused consumer electronics assemblers. Three archetypes dominate: integrated IDM-packaging hybrids, outsourced semiconductor assembly and test providers, and state-supported national champions. Competitive moves center on foundry co-location investments and qualification-linked customer lock-ins.
Among Taiwan-based packaging specialists, ASE Group and Powertech Technology exemplify the integrated model with captive substrate supply and foundry proximity advantages. Chinese state-supported players occupy a distinct tier, with Tongfu Microelectronics representing domestic champions specializing in thermal architectures for power management applications. JCET Group anchors government-backed R&D positioning in Jiangsu province. These three archetypes illustrate how geographic industrial policy and customer concentration shape competitive positioning.
| Leading Market Players |
|---|
| Powertech Technology |
| Tongfu Microelectronics |
| JCET Group |
| STATS ChipPAC |
| ChipMOS TECHNOLOGIES |
| ASE Group |
| Tianshui Huatian Technology |
| Fujitsu |
| Amkor Technology |
| Others |
Pricing and Supply Chain Analysis
Forty-five-day substrate lead times in Taiwan's Hsinchu corridor compress procurement cycles for automotive-qualified QFN lines while locking in premium pricing power for captive producers, whereas Chinese domestic suppliers face margin erosion from MIIT-mandated halogen-free material conversions.
Pricing Analysis
Copper-plus-epoxy compound contracts with London Metal Exchange indexation dominate thermal QFN procurement for electric vehicle power modules. Three-tier pricing structure across automotive-certified, RF-optimized, and standard consumer tiers separates AEC-Q100 qualified lines from mmWave antenna-in-package configurations and legacy 0.5mm pitch volume programs. Cost compression in standard QFN intensifies because Chinese domestic suppliers flood consumer electronics segments with aggressive spot-market pricing. Smartphone OEM procurement teams in Seoul exhibit lowest price sensitivity for RF QFN given antenna-in-package co-design lock-ins, while industrial sensor manufacturers represent the most price-sensitive buyer archetype.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication and advanced packaging capacity, while China's Jiangsu and Guangdong provinces concentrate legacy QFN assembly and substrate production. Copper leadframes, epoxy molding compounds, and ceramic substrates for mmWave applications constitute critical input dependencies. Single-source vulnerability concentrates in Taiwan's Hsinchu corridor where foundry-packaging co-location creates geographic chokepoints for automotive-grade thermal QFN. Distribution runs through direct long-term frame contracts with Seoul-based smartphone OEMs and Shanghai-based automotive tier-one suppliers, displacing spot-market purchasing for premium-tier programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat structure where JEDEC qualification entrenchment creates switching costs that lock automotive and medical OEMs into validated supplier relationships spanning multiple product generations.
For Market Incumbents: Compound captive substrate advantages by deepening foundry co-location in Taiwan's Hsinchu corridor and accelerating AEC-Q100 qualification pipelines before MIIT green standards fully phase in. ASE Group and Powertech Technology should expand automotive-qualified thermal QFN capacity to capture EV inverter module demand, while defending against flip-chip BGA substitution in high-pin-count power management applications through antenna-in-package integration lock-ins. For New Entrants and Emerging Players: Differentiate on embedded-die QFN architectures for electric vehicle power module integration, targeting the penetrable white space in India's Gujarat and Tamil Nadu greenfield clusters where PLI scheme incentives offset capital barriers. Medical device miniaturization in Japan's wearable diagnostic segment offers second entry vector through biocompatible halogen-free molding compound certification under METI JIS standards, with go-to-market leverage through Nagoya-Tokyo industrial corridor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automotive-certified QFN sub-segments as AEC-Q100 testing infrastructure and copper-clip thermal architecture R&D absorb disproportionate capital deployment. Long-term viability favors vertically integrated packaging houses with captive substrate supply and foundry proximity, positioning Taiwan-based integrated IDM-packaging hybrids as prime acquisition targets. Watch for MIIT dual carbon goal enforcement tightening as inflection signal for Chinese supplier consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry-Packaging Co-location Investment | Compresses cycle times for automotive QFN programs in Taiwan's Hsinchu corridor. |
| AEC-Q100 Certification Pipeline Expansion | Locks in automotive OEM relationships ahead of EV inverter module demand acceleration. |
| Embedded-Die Process Development | Enables electric vehicle power module integration bifurcating supplier competitive tiers. |
| Halogen-Free Material Conversion | Aligns substrate supply with MIIT green standards and METI JIS procurement restrictions. |
| India Greenfield Capacity Buildout | Captures PLI scheme incentives for semiconductor packaging in Gujarat and Tamil Nadu clusters. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with packaging engineering directors, substrate procurement managers at smartphone OEMs, automotive tier-one supplier quality assurance leads, and foundry business development executives. Secondary validation drew from MIIT GB standard filings, Taiwan ITRI industry roadmap publications, JEDEC J-STD-020 qualification registries, and customs data on epoxy molding compound trade flows. Bottom-up capacity modeling across individual packaging facilities triangulated against top-down semiconductor assembly market estimates.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type tier, end-use certification grade, material compliance category, and application power density requirement. CAGRs were derived from segment-level growth rate synthesis anchored to electric vehicle production forecasts and 5G handset shipment patterns. Forecast inputs incorporated foundry capacity expansion timelines, MIIT dual carbon enforcement schedules, and RF front-end module integration roadmaps from South Korean smartphone OEMs.
Material uncertainties — abrupt copper price volatility, automotive qualification timeline extensions, and MIIT green standard acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions on substrate capacity utilization and regulatory phase-in schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Packaging
Semiconductor and IC Packaging Materials Market
Semiconductor Packaging
3D IC and 2.5D IC Packaging Market
Semiconductor Packaging
Embedded Die Packaging Technology Market
Semiconductor Packaging
Global MEMS Packaging Market
Semiconductor Packaging
Fan Out Packaging Market
Semiconductor Packaging
Semiconductor Packaging Material Market
Semiconductor Packaging
Semiconductor Chip Handler Market
Semiconductor Packaging
Advanced Semiconductor Packaging Market
Semiconductor Packaging
Semiconductor Wafer Tape Market
Semiconductor Packaging
Electronic Board Level Underfill and Encapsulation Material Market
Semiconductor Packaging
3D IC Packaging Market
Semiconductor Packaging
Epoxy Potting Market
Semiconductor Packaging
3D TSV Packages Market
Semiconductor Packaging
Global Semiconductor Packaging and Assembly Equipment Market
Semiconductor Packaging
Asia Pacific LED Packaging Market
Semiconductor Packaging
Global Interposer and Fan-Out WLP Market