
 Vacuum Ovens Market | 2026-2036
Vacuum Ovens Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Ovens Market Intelligence
REACH compliance is rebalancing the cost-of-entry calculus for European vacuum oven suppliers by mandating material traceability and restricted substance documentation across supply chains. Memmert GmbH leverages its German manufacturing base to sustain domestic certification advantages. Thermo Fisher Scientific anchors North American laboratory demand through extensive service networks. Across International competes on custom chamber configurations for specialized research applications.
A vacuum oven is a sealed thermal processing chamber that operates below atmospheric pressure, typically achieving temperatures from ambient to 300°C while maintaining vacuum levels down to 0.01 mbar, designed to remove moisture or volatile compounds without oxidation. Its primary industrial purpose centers on heat-sensitive material processing where atmospheric oxygen would degrade product integrity. Laboratory ovens dominate unit shipments across the product type dimension, though industrial ovens capture disproportionate margin pools in semiconductor and aerospace curing applications. Among end users, pharmaceuticals drives replacement demand while electronics represents the fastest-growing installation base for precision dehydration protocols.
EMA sterilization guidelines, EPA emissions standards for industrial thermal equipment, and ISO 9001 quality management frameworks collectively shape product design specifications and market access requirements across target geographies. FDA validation protocols for pharmaceutical manufacturing equipment create additional compliance layers that favor established suppliers with documented quality systems. Stakeholders must monitor evolving heat pump efficiency standards and regional energy transition policies as these will determine which technology configurations retain competitive viability in procurement decisions.
Market Dynamics
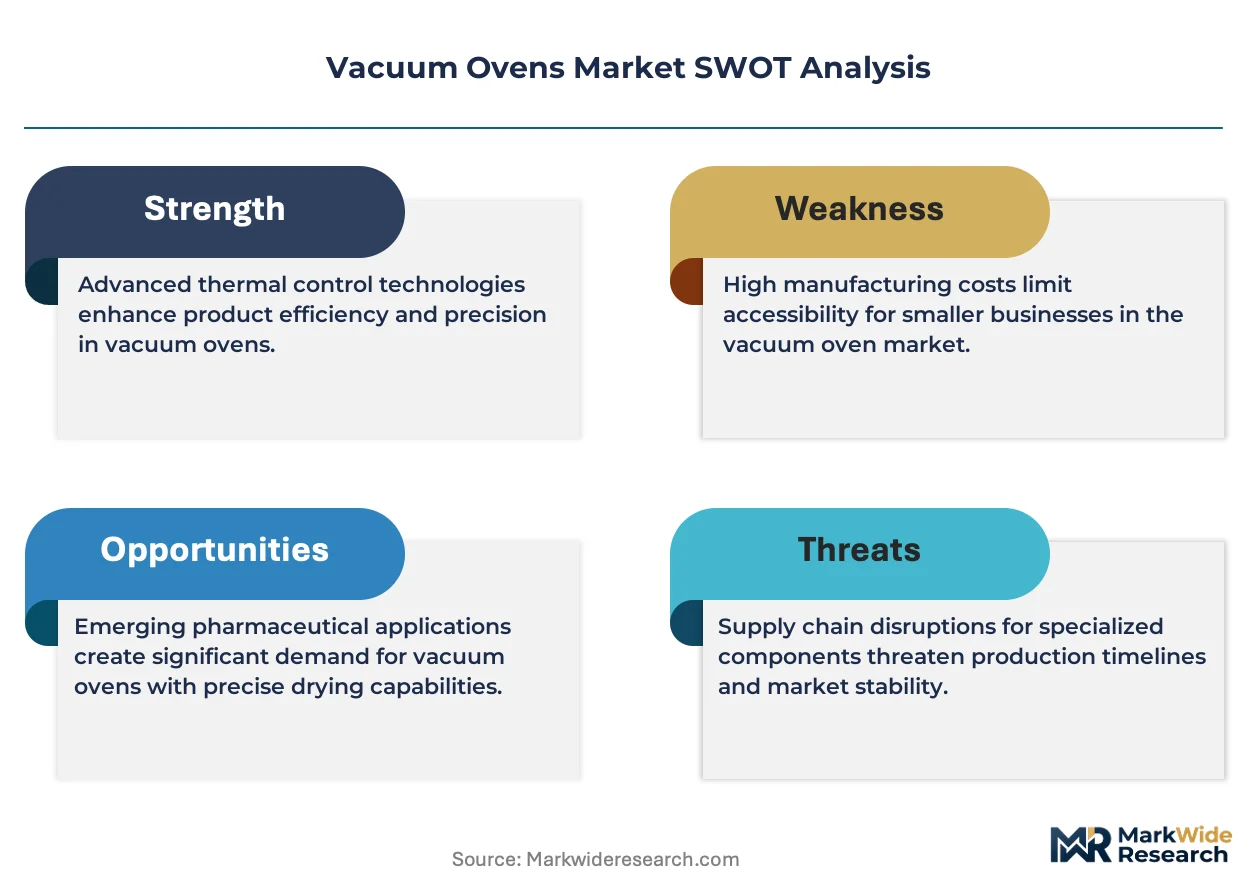
Heat pump technology is displacing conventional resistive heating elements in vacuum oven installations, compressing energy consumption profiles and forcing incumbent suppliers to retool thermal architectures or cede efficiency-sensitive procurement contests.
Growth Catalysts
- EMA Sterilization Validation:Pharmaceutical manufacturers in Germany are expanding vacuum oven fleets to meet European Medicines Agency documentation requirements for terminal sterilization processes, creating replacement demand across Central European manufacturing clusters.
- Laboratory Refurbishment Cycles:United States academic and contract research organizations are executing decade-overdue equipment modernization programs, concentrating unit shipments in the Northeast and California research corridors.
- REACH Compliance:Material traceability mandates across European supply chains are favoring domestic manufacturers with established restricted substance documentation systems, tilting procurement toward certified regional suppliers.
Market Restraints
- Stainless Steel Input Volatility:Chamber fabrication depends on 316L and 304-grade stainless supply chains concentrated in Chinese and Indian mill complexes, exposing European and North American oven builders to alloy price swings and tariff exposure.
- Vacuum Pump Supplier Concentration:Dry scroll and turbomolecular pump sourcing narrows to German and Japanese specialty manufacturers, creating single-source vulnerability for mid-tier oven assemblers without captive pump production.
- Temperature Uniformity Ceiling:Convective heat transfer limitations in vacuum environments constrain maximum achievable uniformity across large-format chambers, disqualifying standard designs from certain aerospace composite curing specifications.
Strategic Opportunities
- Semiconductor Dehydration Protocols:Advanced packaging foundries in South Korea and Taiwan are qualifying vacuum ovens for low-temperature dielectric removal, opening precision thermal processing contracts previously served by lyophilization equipment.
- EU Green Deal Heat Pump Incentives:Energy transition subsidies for industrial thermal equipment retrofits are accelerating heat pump vacuum oven adoption in Benelux and Nordic pharmaceutical manufacturing facilities.
- Service Network Unbundling:Independent calibration and validation service providers are capturing aftermarket revenue streams from capital-constrained laboratories, creating channel partnerships that bypass traditional OEM service monopolies.
Industry Challenges
- FDA 21 CFR Part 11 Validation:Pharmaceutical buyers demand electronic record and signature compliance documentation that extends equipment qualification timelines by four to six months, straining supplier engineering bandwidth.
- Legacy Control System Integration:Facilities with 1990s-era building management systems face protocol incompatibility when installing modern vacuum ovens with Ethernet-based data logging, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Ovens Market |
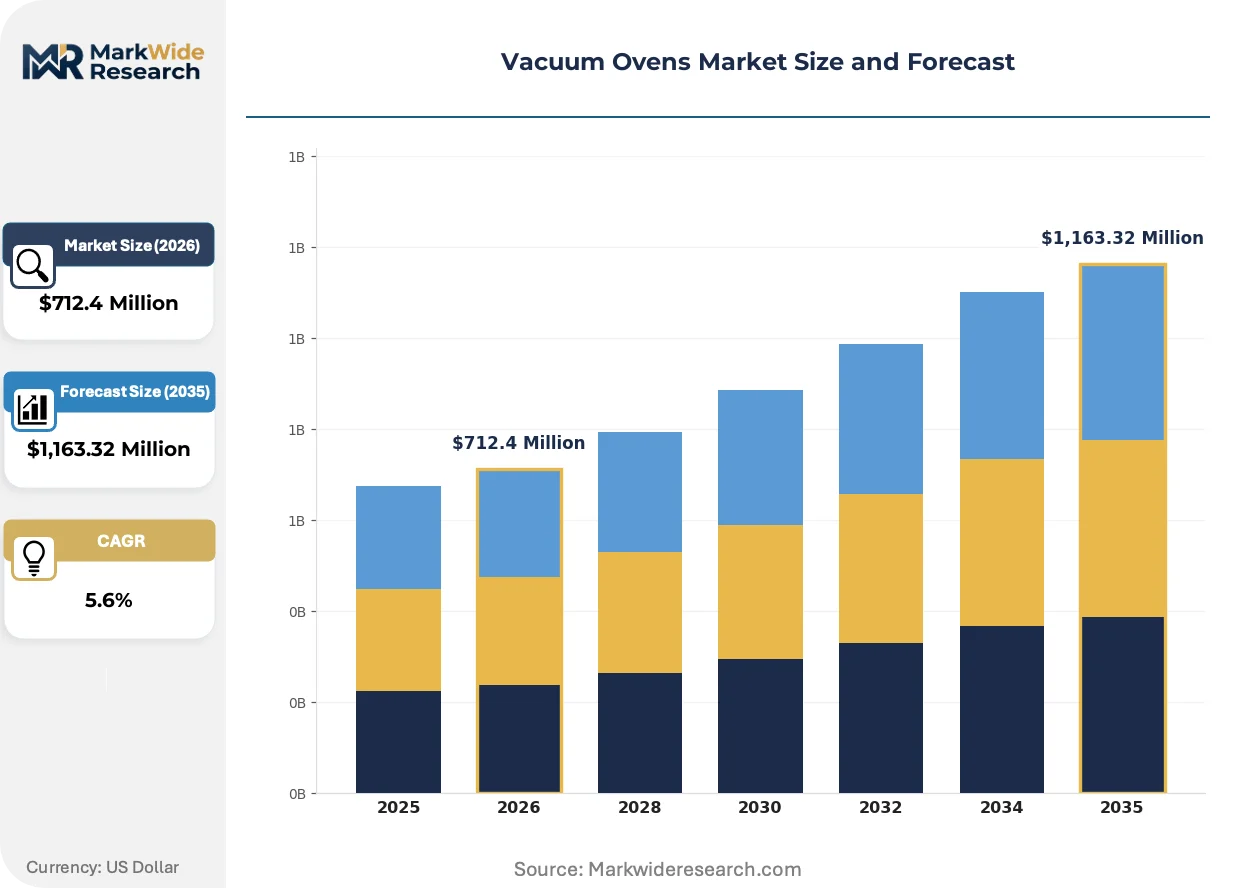
| Market Size in 2026 | $712.4 Million |
| Market Size in 2035 | $1,163.32 Million |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Ovens, Industrial Ovens, Drying Ovens, Custom Ovens End User: Pharmaceuticals, Electronics, Materials Science, Food Processing Technology: Infrared, Convection, Microwave, Heat Pump Application: Dehydration, Sterilization, Testing, Drying |
| Companies Covered | Memmert GmbH, Across International, Thermo Fisher Scientific, BOXUN, Nabertherm, Binder GmbH, Carbolite Gero, Yiheng Scientific Instruments, Yamato Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Ovens Market Strategic Shifts & Innovations
Digital control architectures and predictive maintenance capabilities are transforming vacuum oven competitive dynamics, compressing the service interval economics that previously sustained incumbent suppliers.
Programmable logic controllers with integrated IoT connectivity are automating temperature ramp profiling and vacuum level modulation in pharmaceutical manufacturing environments. Contract development and manufacturing organizations are adopting these systems to reduce batch-to-batch variability and compress validation documentation burdens. The technology is automating routine operator interventions that previously required manual datalogger transcription, enabling single-operator oversight of multiple oven suites.
REACH substance restrictions and F-Gas Regulation phase-down schedules are forcing refrigerant transitions in heat pump vacuum oven designs across European installations. Industrial thermal equipment suppliers must now document hydrofluoroolefin alternative compatibility and global warming potential calculations to maintain market access. German and Swiss pharmaceutical manufacturers are responding by specifying heat pump configurations with natural refrigerant circuits in new capital expenditure requests.
Consolidated procurement through group purchasing organizations is concentrating laboratory equipment buying power in United States academic medical centers and multi-site research institutes. Traditional distributor relationships are yielding to direct manufacturer contracts with standardized specifications and volume pricing tiers. This concentration is most visible in the Boston-Cambridge and Research Triangle Park clusters, where shared service organizations negotiate enterprise-wide thermal equipment frameworks.
Vacuum Ovens Market Segmentation
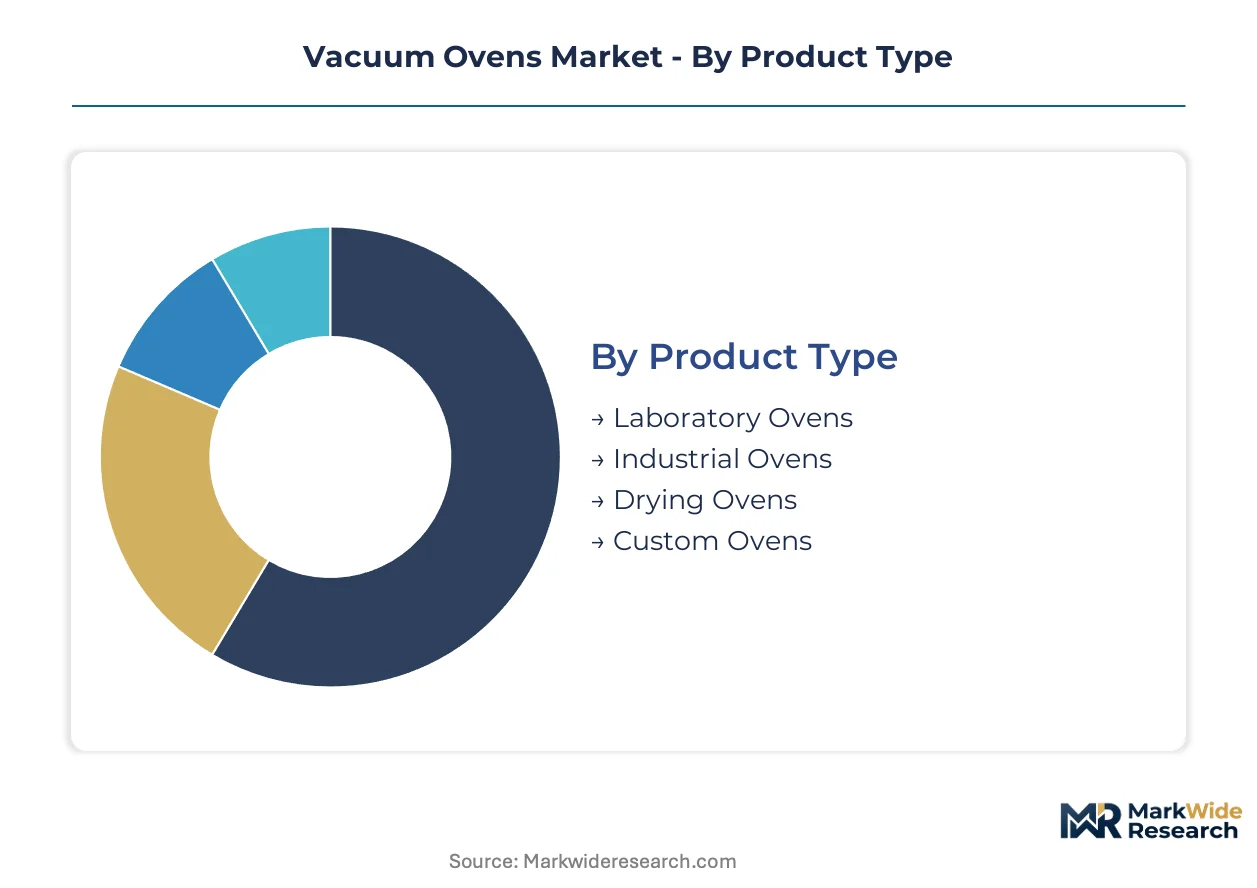
Vacuum oven procurement decisions split across performance specifications, regulatory compliance burdens, and thermal processing protocols. Each segmentation dimension carries distinct margin structures and supplier qualification requirements that reshape competitive positioning.
Product Type:
Capital allocation intensity varies sharply across installation scales, with facility footprint and batch volume requirements driving configuration selection.
- Laboratory Ovens:Compact benchtop and floor-standing units with chamber volumes under 500 liters dominate unit shipments across academic and contract research settings. Demand concentrates in United States Northeast and California research corridors where decade-overdue modernization cycles are replacing 1990s-era equipment. FDA 21 CFR Part 11 validation requirements compress supplier pools to established OEMs with documented quality systems.
- Industrial Ovens:Large-format chambers exceeding 2000 liters serve semiconductor foundries and aerospace composite curing operations where temperature uniformity specifications exceed standard convective limits. Heat pump retrofits in European pharmaceutical manufacturing are accelerating displacement of conventional resistive heating architectures in this tier.
- Drying Ovens:Purpose-built configurations for moisture removal in heat-sensitive agricultural and chemical processing applications.
- Custom Ovens:Specialized chamber geometries and vacuum level specifications for unique research protocols or proprietary manufacturing processes.
Laboratory ovens lead on scale; industrial ovens lead on momentum as heat pump retrofits accelerate across European manufacturing.
End User:
Regulatory exposure and thermal protocol precision create divergent procurement priorities across buyer categories.
- Pharmaceuticals:Terminal sterilization and API drying operations demand vacuum levels down to 0.01 mbar with full batch traceability. German manufacturers are expanding fleet capacity to satisfy EMA sterilization validation documentation requirements.
- Electronics:Advanced packaging foundries in South Korea and Taiwan are qualifying low-temperature dielectric removal protocols previously served by lyophilization equipment, opening precision thermal processing contracts.
- Materials Science:Research institutions and specialty chemical producers requiring controlled atmosphere processing for novel compound synthesis.
- Food Processing:Gentle dehydration applications for temperature-sensitive nutritional and flavor compound preservation.
Pharmaceuticals leads on scale; electronics leads on momentum as semiconductor packaging complexity intensifies.
Technology:
Energy transition policies and efficiency standards are reconfiguring technology adoption curves across installation bases.
- Heat Pump:Refrigerant-based thermal compression systems achieving 40-60% energy consumption reduction versus resistive heating. EU Green Deal subsidies are accelerating adoption in Benelux and Nordic pharmaceutical facilities; REACH F-Gas Regulation is forcing hydrofluoroolefin transitions in new equipment specifications.
- Infrared:Radiant heating elements for rapid thermal response in small-batch research applications where uniformity requirements permit localized heating profiles.
- Convection:Traditional forced-air circulation limited by vacuum environment constraints on heat transfer coefficients.
- Microwave:Dielectric heating for specialized applications requiring volumetric energy deposition rather than surface-conduction thermal transfer.
Convection retains installed base scale; heat pump claims the steepest expansion trajectory as carbon accounting enters procurement scorecards.
Application:
Process validation requirements and contamination risk profiles segment equipment specifications across use cases.
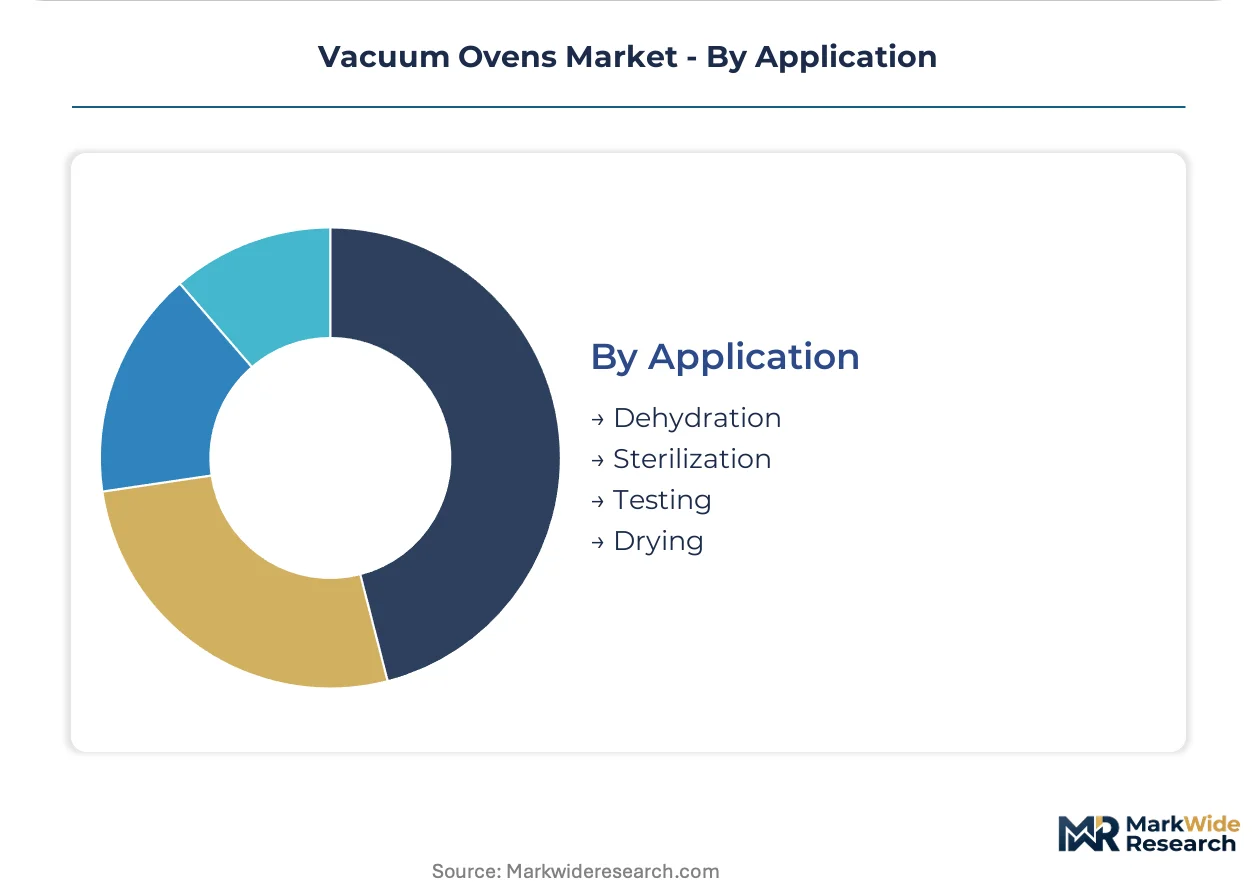
- Sterilization:Terminal sterilization of pharmaceutical products and medical devices under vacuum to prevent oxidation, requiring EMA and FDA validation documentation that extends equipment qualification timelines.
- Dehydration:Precision moisture removal for semiconductor dielectric materials and heat-sensitive chemical intermediates where atmospheric oxygen would degrade product integrity.
- Drying:General-purpose moisture elimination across agricultural, chemical, and industrial feedstock processing.
- Testing:Accelerated aging, outgassing characterization, and thermal stability validation for quality control protocols.
Dehydration leads on scale; sterilization leads on momentum as biologics manufacturing expands validation-intensive thermal processing requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent concentration anchors European vacuum oven innovation, while South Korean semiconductor process engineers and United States pharmaceutical manufacturing specialists drive distinct regional demand profiles across three continents.
United States
Academic medical centers and contract research organizations in the Northeast and California corridors execute decade-overdue laboratory refurbishment cycles. FDA 21 CFR Part 11 validation requirements compress supplier pools to established OEMs with documented quality systems. Boston-Cambridge and Research Triangle Park clusters concentrate procurement through consolidated group purchasing organizations.
Germany
Pharmaceutical manufacturers expand vacuum oven fleets to satisfy EMA sterilization validation documentation requirements for terminal sterilization processes. REACH compliance mandates material traceability across supply chains, favoring domestic manufacturers with established restricted substance documentation. Bavarian and Baden-Württemberg manufacturing clusters drive Central European replacement demand.
South Korea
Advanced packaging foundries qualify vacuum ovens for low-temperature dielectric removal protocols previously served by lyophilization equipment. MFDS pharmaceutical manufacturing standards shape equipment validation requirements for domestic biologics producers. Seoul Capital Area and Busan-Ulsan industrial corridors concentrate precision thermal processing demand.
China
Domestic laboratory equipment modernization programs accelerate across state-funded research institutes and university hospital networks. NMPA medical device manufacturing regulations elevate documentation requirements for sterilization equipment procurement. Yangtze River Delta and Pearl River Delta manufacturing zones concentrate both production capacity and end-user demand.
Japan
Materials science research institutions and specialty chemical producers maintain steady replacement demand for controlled atmosphere processing equipment. METI industrial energy efficiency standards accelerate heat pump technology evaluation in pharmaceutical manufacturing facilities. Kanto and Kansai metropolitan areas anchor domestic installation and service networks.
Vacuum Ovens Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market strata. Laboratory equipment divisions of multinational life science groups leverage service network density against regional fabricators competing on custom chamber geometries. Three archetypes dominate: German-engineered premium specialists, North American laboratory equipment conglomerates, and Asian cost-optimized volume producers. Strategic moves center on heat pump technology licensing partnerships and aftermarket service network unbundling.
Within the German-engineered tier, Memmert GmbH and Nabertherm occupy positions exemplifying domestic certification advantages under REACH and EMA frameworks. Among North American laboratory equipment groups, Thermo Fisher Scientific anchors enterprise-scale procurement relationships through extensive service infrastructure. Across International represents the specialist archetype competing on configurable chamber specifications for non-standard research protocols.
| Leading Market Players |
|---|
| Memmert GmbH |
| Across International |
| Thermo Fisher Scientific |
| BOXUN |
| Nabertherm |
| Binder GmbH |
| Carbolite Gero |
| Yiheng Scientific Instruments |
| Yamato Scientific |
| Others |
Cost & Logistics Intelligence
Stainless steel alloy costs cascade from Chinese and Indian mill complexes through European and North American oven builders, compressing margins at mid-tier suppliers while premium German manufacturers pass through material premiums via extended validation documentation.
Pricing Analysis
The bundled-versus-unbundled service split separates premium German OEMs from value-oriented competitors. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service intensity. Pricing pressure stems from heat pump technology licensing costs and energy efficiency retrofit subsidies redirecting procurement budgets. Academic medical centers exhibit highest price sensitivity due to consolidated group purchasing organization negotiations, while semiconductor foundries prioritize temperature uniformity specifications over unit cost.
Supply Chain Analysis
Reverse-logistics flows for vacuum pump refurbishment and chamber recertification extend equipment lifecycles and compress new unit demand. Manufacturing concentrates in Germany, China, and the United States. Chamber fabrication draws from 316L and 304-grade stainless supply chains, while vacuum pump sourcing narrows to German and Japanese specialty producers. Single-source vulnerability for dry scroll and turbomolecular pumps exposes mid-tier assemblers. Distribution runs through direct manufacturer contracts with multi-site research institutes and traditional laboratory equipment distributors serving smaller facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vacuum ovens market compounds steadily as pharmaceutical sterilization validation requirements and semiconductor packaging complexity create durable replacement cycles across laboratory and industrial installation bases.
For Market Incumbents: Acquire captive vacuum pump production capabilities to neutralize single-source supplier concentration risk. Defensive consolidation should target heat pump technology licensing portfolios and EMA-validated service documentation systems. Incumbents must counter emerging Asian cost-optimized entrants by embedding predictive maintenance software into control architectures. For New Entrants and Emerging Players: Digital-channel routes through independent calibration and validation service providers bypass entrenched OEM service monopolies. White-space exists in custom chamber configurations for materials science research protocols and heat pump retrofits for European pharmaceutical facilities. Target South Korean and Taiwanese semiconductor foundries with low-temperature dielectric removal specifications previously served by lyophilization equipment. For Investors and Strategic Acquirers: Consolidation pressure builds where service network density determines procurement decisions in United States academic medical centers. Long-term viability favors suppliers with documented FDA 21 CFR Part 11 and EMA sterilization validation systems. Monitor heat pump efficiency standard adoption and F-Gas Regulation refrigerant transition timelines as inflection indicators for technology displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Technology Licensing | EU Green Deal subsidies accelerate energy-efficient thermal equipment retrofits across Benelux pharmaceutical manufacturing. |
| Service Network Expansion | Direct manufacturer contracts with Boston-Cambridge research clusters bypass traditional distributor relationships. |
| EMA Validation Documentation Investment | German pharmaceutical manufacturers expand fleet capacity to satisfy European Medicines Agency sterilization requirements. |
| Custom Chamber Configuration Development | Specialized geometries capture materials science research protocols outside standard product specifications. |
| Predictive Maintenance Platform Integration | IoT-enabled control architectures compress service interval economics and sustain aftermarket revenue streams. |
Research Approach
Bottom-up laboratory and industrial end-use modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with pharmaceutical manufacturing engineers, laboratory equipment procurement managers, vacuum pump specialists, and thermal processing consultants combined with secondary validation from FDA 510(k) filings, EMA sterilization guidance documents, EPA emissions standards, and ISO 9001 certification databases. Trade data from German, Chinese, and United States customs authorities provided import-export flow triangulation against manufacturer reported volumes.
Historical trendline analysis across equipment replacement cycles and technology adoption curves informed projection parameters. The analytical framework spans product type, end-user industry, heating technology, and application dimensions throughout the forecast period. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated heat pump efficiency standard evolution, REACH substance restriction timelines, and semiconductor packaging complexity indices.
The model assumes a particular technology adoption path; alternative pathways for heat pump displacement of resistive heating would alter the outlook if refrigerant transition costs exceed subsidy offsets. Forecasts reflect documented assumptions regarding EMA validation timeline compression and laboratory refurbishment cycle concentration. Practitioners should monitor F-Gas Regulation phase-down schedules and stainless steel alloy price volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Global Tamping Machine Market
Semiconductor Equipment
Die Attach Equipment Market
Semiconductor Equipment
Solar Module Production Equipment Market
Semiconductor Equipment
Global Microelectronics Cleaning Equipment Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
Middle East and Africa Semiconductor Manufacturing Equipment Market
Semiconductor Equipment
Pulse Tube and Gifford-Mcmahon Cryocoolers Market
Semiconductor Equipment
Automatic Laser PCB Depaneling Machines Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
North America Semiconductor Etch Equipment Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
Partition Inserter Machines Market
Semiconductor Equipment
Wire Bonder Equipment Market
Semiconductor Equipment
Wet Based Wafer Cleaning Equipment Market
Semiconductor Equipment
FOUP Load Port Market