
 Vacuum Coating Equipment Market | 2026-2036
Vacuum Coating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Vacuum Coating Equipment Market Analysis
Software-defined process control is expanding as a monetizable layer atop hardware sales, with recipe optimization and predictive maintenance modules now bundled into long-term service contracts. Applied Materials leverages its installed base to anchor recurring revenue through digital retrofit programs. Bühler Group sustains competitiveness in decorative and functional coating lines through deep vertical integration in process development. ULVAC dominates Asia-Pacific supply chains for display manufacturing equipment with localized service networks.
Vacuum coating equipment encompasses systems that deposit thin-film layers onto substrates under controlled sub-atmospheric pressure, typically operating in the range of 10⁻³ to 10⁻⁹ torr depending on the deposition method and material purity requirements. These systems serve industrial applications spanning electronics, optics, energy, and surface engineering by enabling precise control over film thickness, uniformity, and adhesion at nanometer scales. Sputtering systems command the largest share of product-type revenue due to their versatility across metal, dielectric, and compound target materials. Atomic layer deposition represents the fastest-expanding technology segment as semiconductor manufacturers pursue angstrom-level thickness control for high-aspect-ratio structures. Functional coatings applications generate premium pricing relative to decorative segments because optical, thermal, and electrical performance specifications demand tighter process tolerances and qualification cycles.
The EPA enforces hazardous air pollutant standards under the National Emission Standards for Hazardous Air Pollutants that constrain solvent-based coating alternatives and indirectly boost vacuum deposition adoption. REACH registration requirements in Europe compel equipment suppliers to document chemical safety profiles for precursor materials used in CVD and ALD processes. Japan's METI coordinates industrial standards through JIS frameworks that specify vacuum performance benchmarks and safety interlocks for production-scale systems. Stakeholders must monitor evolving precursor chemistry regulations and substrate size transitions as determinants of equipment replacement cycles and retrofit investment priorities.
Market Dynamics
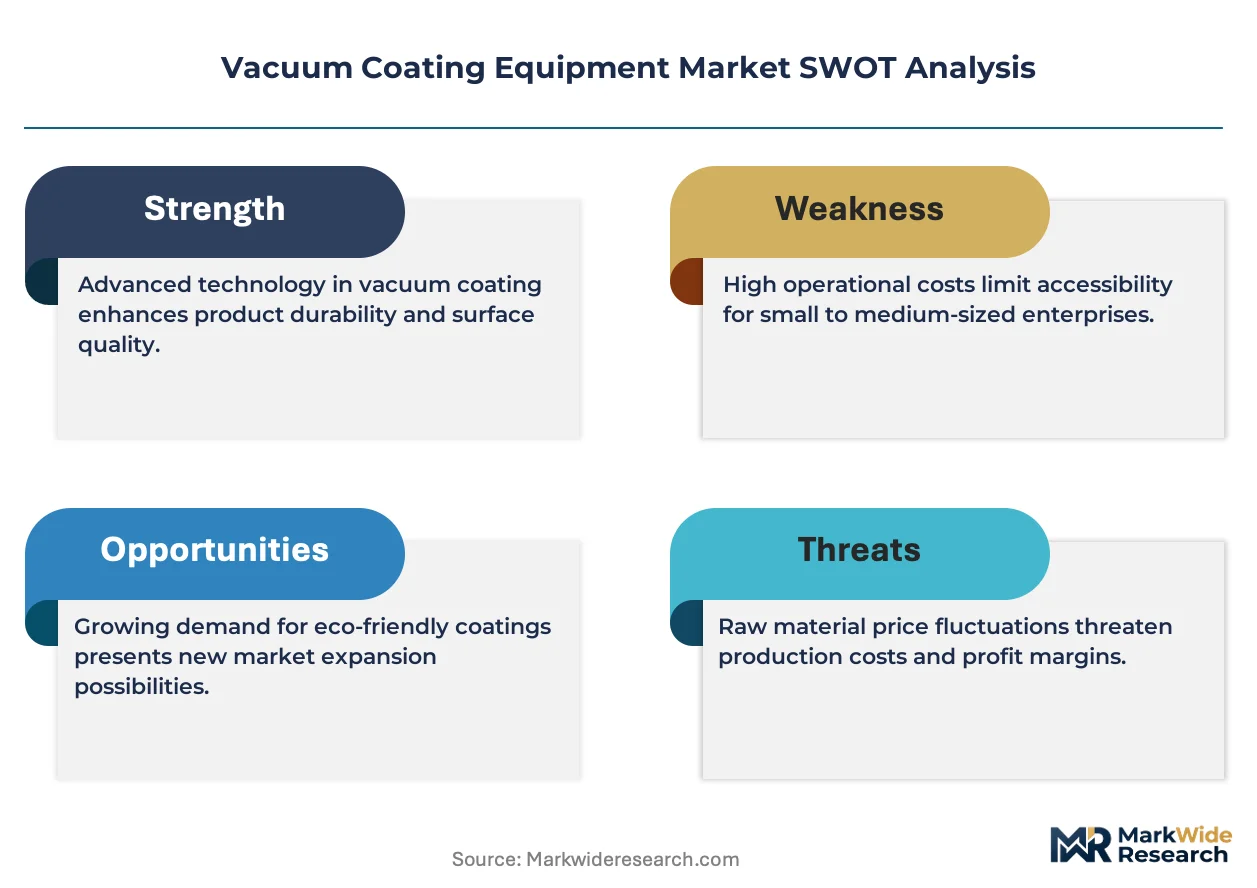
Semiconductor manufacturers are compressing deposition tool replacement cycles as angstrom-level thickness control becomes non-negotiable for gate-all-around transistor architectures. This technical inflection is restructuring equipment procurement priorities across fabrication ecosystems.
Growth Catalysts
- Advanced node semiconductor production:Logic chip manufacturers in Taiwan and South Korea are expanding sputtering and ALD capacity to support 2nm process ramps. Tool vendors capture follow-on service contracts from this installed base expansion.
- EU REACH framework:Chemical safety documentation requirements for precursor materials are accelerating closed-loop vacuum system adoption as solvent-based alternatives face compliance headwinds.
- Display manufacturing scale-up:OLED and micro-LED panel production in China is driving synchronized procurement of large-area deposition equipment with localized service support.
Market Restraints
- High-purity gas supply concentration:Specialty precursor production concentrates among a limited set of chemical suppliers, creating input cost volatility and qualification bottlenecks for equipment operators.
- Technical limitation in high-aspect-ratio coverage:Conventional PVD methods struggle with conformal coating of 3D NAND and finFET structures, forcing premature technology obsolescence for installed base owners.
- EPA NESHAP compliance friction:Hazardous air pollutant standards impose capital-intensive abatement retrofits on older open-loop systems, compressing margins for mid-tier equipment operators.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and display fabrication are creating greenfield equipment demand as the country builds domestic deposition capacity.
- Energy storage coating applications:Solid-state battery manufacturers are qualifying ALD and CVD systems for ceramic electrolyte deposition, opening a new vertical with distinct performance specifications.
- Software-defined process control convergence:Recipe optimization platforms bundled with hardware sales are transforming transactional equipment purchases into recurring revenue relationships.
Industry Challenges
- Vacuum technology specialist shortage:The shallow talent pool for sub-atmospheric process engineering is elongating commissioning timelines and inflating field service costs for equipment vendors.
- Legacy system integration complexity:Retrofitting 300mm wafer handling and advanced process control onto 200mm-era deposition tools requires custom mechanical and software engineering that strains project budgets.
- Multi-jurisdictional certification timelines:Parallel CE marking, SEMI S2/S8 safety reviews, and country-specific electrical inspections are extending order-to-revenue cycles for export-bound equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vacuum Coating Equipment Market |
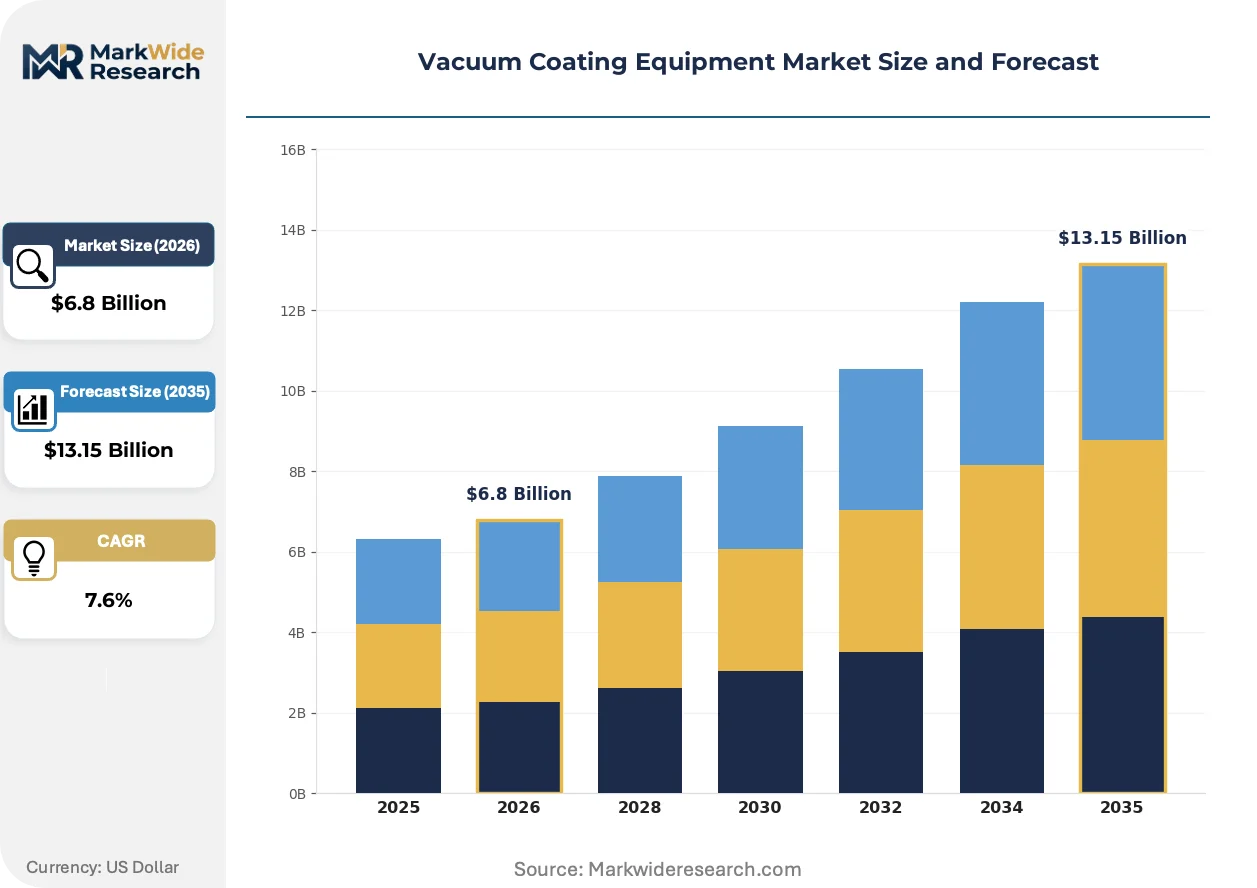
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sputtering Systems, Thermal Evaporation, Atomic Layer Deposition, Chemical Vapor Deposition End User: Electronics, Automotive, Aerospace, Healthcare Technology: Plasma Enhanced CVD, Pulsed Laser Deposition, Magnetron Sputtering, Vacuum Thermal Evaporation Application: Optical Coatings, Decorative Coatings, Functional Coatings, Barrier Coatings |
| Companies Covered | Bühler Group, AIXTRON, Applied Materials, Von Ardenne, Veeco Instruments, ULVAC, IHI Corporation, Tokyo Electron, Oerlikon Balzers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vacuum Coating Equipment Market Emerging Trajectories
Deposition technology is bifurcating between precision-extreme systems for logic semiconductors and throughput-optimized platforms for energy and display applications. This divergence is fragmenting vendor R&D priorities and reshaping competitive positioning.
Atomic layer deposition is electrifying process control capabilities by delivering single-atomic-layer thickness precision through sequential self-limiting surface reactions. Memory and logic chip manufacturers in South Korea and Taiwan are adopting ALD for high-aspect-ratio capacitor and gate stack formation at accelerated qualification paces. The technology is compressing acceptable thickness variation windows from nanometers to angstroms, rendering older CVD methods inadequate for leading-edge nodes.
Japan's METI is coordinating updated JIS standards for vacuum equipment safety interlocks and performance benchmarking that align with international SEMI guidelines. These industrial standards are mandating unified documentation for precursor handling and emergency shutdown protocols across production-scale systems. Domestic equipment manufacturers are responding by pre-integrating compliant control architectures to accelerate export certification timelines.
Equipment buyers are consolidating vendor relationships around integrated hardware-service-software bundles rather than discrete tool purchases. Semiconductor foundries in Taiwan are negotiating long-term service contracts with predictive maintenance modules and cloud-connected recipe libraries as standard inclusions. This behavioral shift is most visible in East Asia, where display and logic chip manufacturers possess sufficient procurement scale to dictate contractual terms.
Vacuum Coating Equipment Market Segmentation
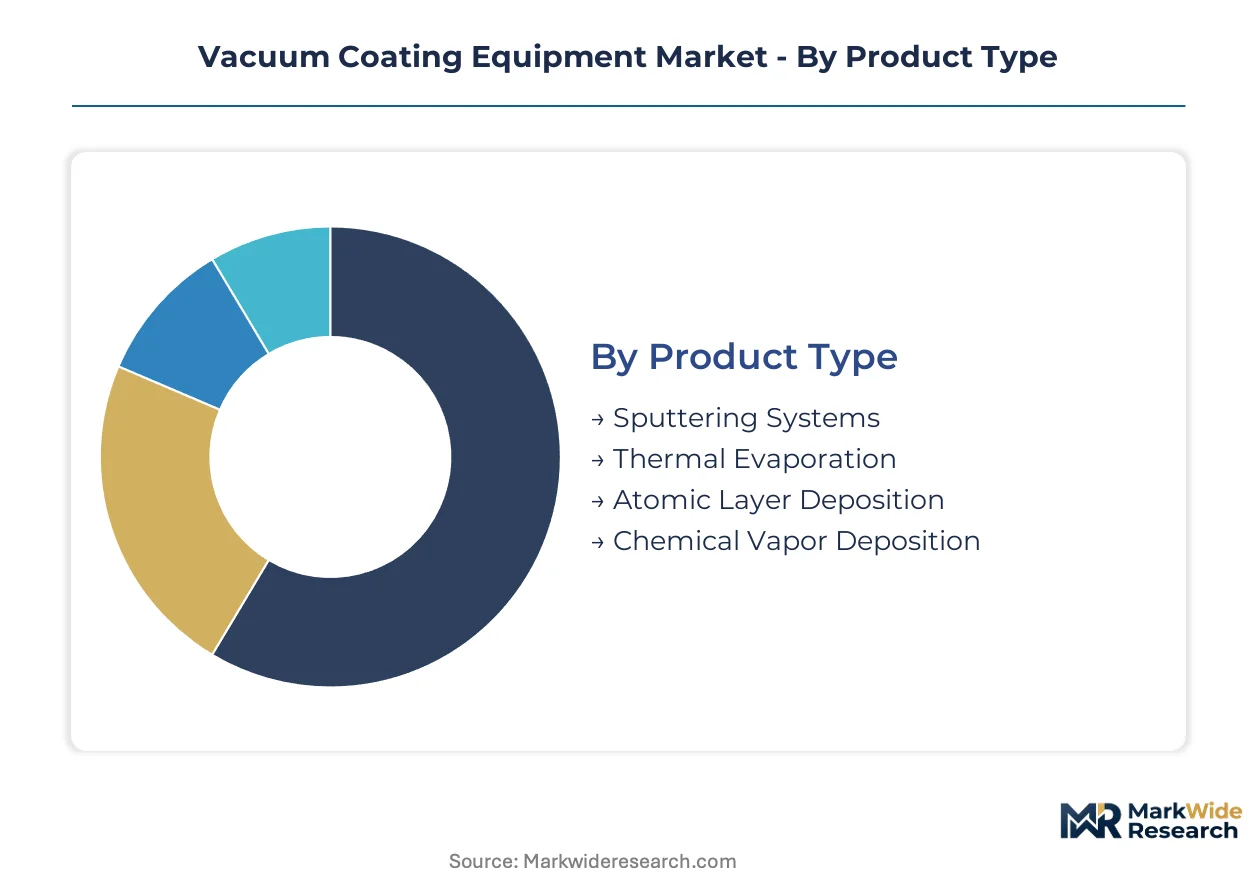
Equipment buyers in vacuum coating prioritize deposition precision, throughput requirements, and substrate compatibility differently across semiconductor, display, and industrial surface engineering applications. Segmentation reveals how technical specifications and end-use performance demands fragment procurement patterns and vendor specialization.
Product Type:
Buyers differentiate primarily by film thickness control requirements and material versatility rather than capital cost alone.
- Sputtering Systems:These systems deposit thin films by ejecting material from a target through ion bombardment, enabling deposition of metals, dielectrics, and compound materials from a single platform. Demand concentrates in Taiwan and South Korea for logic chip metallization and display electrode formation, driven by the need for alloy composition control in copper barrier seed layers. Volume sits with sputtering systems; growth tilts toward atomic layer deposition.
- Atomic Layer Deposition:Sequential self-limiting surface reactions deliver angstrom-level thickness precision through alternating precursor pulses. Semiconductor manufacturers in South Korea and Taiwan are expanding ALD capacity for gate-all-around transistor architectures and 3D NAND charge trap layers, where conformal coverage of high-aspect-ratio structures is non-negotiable.
- Thermal Evaporation:Resistive heating vaporizes source material for deposition onto substrates, offering simplicity for single-element coatings. Optical component manufacturers and decorative finishing operations favor this method for cost-sensitive applications with modest thickness uniformity requirements.
- Chemical Vapor Deposition:Thermally activated gas-phase reactions form solid films on heated substrates, excelling in high-rate dielectric and semiconductor deposition. Solar cell and power electronics manufacturers deploy CVD for silicon nitride passivation and wide-bandgap epitaxial layers.
Revenue concentration follows semiconductor capital intensity; technology transitions accelerate replacement cycles for precision-critical segments.
End User:
Application maturity and performance certification requirements create distinct customer archetypes with diverging procurement timelines.
- Electronics:Semiconductor foundries and display panel manufacturers demand sub-nanometer thickness control, particle-free processing, and seamless fab integration. Procurement in Taiwan, South Korea, and China dominates this segment, with tool qualification cycles extending 18-24 months for leading-edge nodes.
- Functional Coatings:Optical, thermal, and electrical performance specifications command premium pricing and tighter process tolerances. Aerospace and defense contractors in the US and Germany drive demand for infrared optical coatings and electromagnetic shielding layers with extended qualification protocols.
- Automotive:Interior trim, lighting reflectors, and sensor window coatings require decorative durability and functional reliability under thermal cycling. German and Japanese automotive suppliers prioritize PVD alternatives to electroplating for regulatory compliance with EU REACH substance restrictions.
- Healthcare:Implantable device manufacturers and diagnostic instrument producers apply biocompatible coatings for corrosion resistance and surface functionalization. FDA and EMA regulatory pathways for medical device coatings elongate vendor approval timelines relative to industrial applications.
Electronics commands the largest equipment spend; healthcare offers the steepest expansion trajectory as implantable device coatings proliferate.
Technology:
Process selection hinges on substrate temperature tolerance, film stress requirements, and deposition rate trade-offs.
- Magnetron Sputtering:Confined plasma near the target surface increases ionization efficiency and deposition rate compared to conventional diode configurations. Display manufacturing in China relies on large-area magnetron systems for transparent conductive oxide deposition on Gen 10.5 substrates.
- Plasma Enhanced CVD:Plasma activation enables film formation at reduced substrate temperatures, expanding compatible substrate materials. Flexible electronics manufacturers in Japan and South Korea deploy PECVD for barrier layer deposition on polymer substrates vulnerable to thermal damage.
- Pulsed Laser Deposition:High-energy laser ablation transfers stoichiometric material from target to substrate, preserving complex oxide compositions. Research institutions and specialized ceramic coating operations favor PLD for piezoelectric and superconducting film development where composition fidelity outweighs throughput concerns.
- Vacuum Thermal Evaporation:Direct resistive or electron beam heating of source material produces high-purity coatings with minimal contamination. OLED stack deposition in South Korea and China employs thermal evaporation for organic emissive layer patterning through fine metal mask shadowing.
Magnetron sputtering anchors installed base volume; plasma enhanced CVD is gaining share fastest in flexible substrate applications.
Application:
Performance specifications and aesthetic requirements partition the market between commodity finishing and precision engineering.
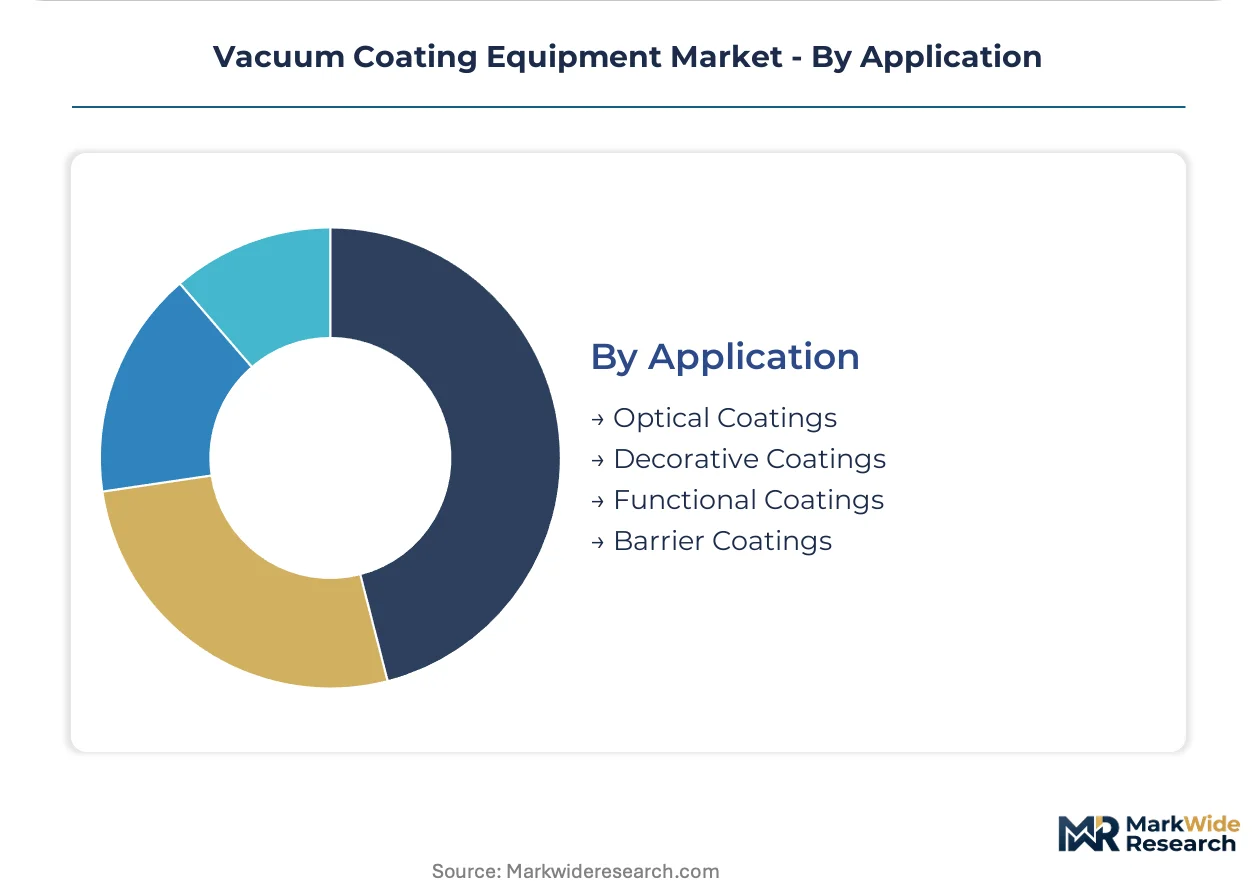
- Functional Coatings:Electrical conductivity, thermal management, and optical interference properties demand angstrom-level thickness control and interface engineering. Semiconductor and optical communications industries in Taiwan and Germany specify these coatings for device performance-critical layers.
- Optical Coatings:Anti-reflection, high-reflection, and filter designs rely on precise refractive index matching and layer stack optimization. Telescope mirror manufacturers and laser system builders in the US and Japan specify ion-assisted deposition for dense, environmentally stable coatings.
- Barrier Coatings:Permeation resistance against moisture and oxygen protects sensitive electronics and food packaging contents. Flexible display and photovoltaic manufacturers in China and South Korea adopt multi-layer barrier stacks for encapsulation of air-sensitive devices.
- Decorative Coatings:Color, gloss, and wear resistance specifications dominate jewelry, watch, and architectural hardware applications. Italian and Swiss luxury goods manufacturers sustain demand for PVD titanium nitride and carbon nitride finishes as chrome plating alternatives.
Functional coatings generate the highest average selling prices; barrier coatings are expanding most quickly with flexible electronics proliferation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment consumption concentrates in East Asian fabrication hubs while specialized coating demand clusters in European automotive and North American defense optics. Production of deposition systems remains concentrated among Japanese, German, and American capital goods manufacturers.
China
Display panel manufacturers in Hefei and Chengdu are scaling Gen 10.5 OLED lines requiring large-area sputtering platforms. MIIT's industrial upgrading directives prioritize domestic equipment procurement for semiconductor fabrication. Yangtze River Delta clusters around Shanghai and Suzhou host the densest concentration of new ALD tool installations for logic chip production.
South Korea
Samsung and SK Hynix are compressing deposition tool replacement cycles for 3nm gate-all-around transistor ramps. MFDS precursor chemical registration requirements align with REACH-equivalent safety documentation standards. Seoul Capital Area fabrication complexes in Pyeongtaek and Yongin anchor regional demand for angstrom-precision coating systems.
Taiwan
TSMC's expansion at the Southern Taiwan Science Park is driving synchronized procurement of CVD and ALD equipment for advanced node production. The island's EPA enforces hazardous air pollutant standards that accelerate closed-loop vacuum system adoption. Hsinchu Science Park remains the densest cluster of semiconductor coating equipment in operation worldwide.
United States
Defense contractors and aerospace optics manufacturers in California and Arizona sustain demand for ion-assisted deposition systems. EPA NESHAP standards constrain solvent-based coating alternatives in industrial finishing applications. Greater Boston's photonics corridor and Southern California's aerospace cluster represent distinct high-specification equipment demand pockets.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg are substituting PVD coatings for REACH-restricted chrome plating on interior trim components. KBA vehicle component regulations indirectly specify coating durability standards for exterior applications. Stuttgart and Munich industrial zones concentrate decorative and functional coating line investments.
Vacuum Coating Equipment Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across distinct technology tiers. The market structures around three concentration layers: integrated process solution providers, specialized deposition technology houses, and regional equipment fabricators. Strategic differentiation runs through software-defined service bundling, geographic proximity to Asian fabrication clusters, and vertical control over precursor supply chains. Consolidation pressure intensifies as semiconductor foundries reduce vendor counts to simplify qualification overhead.
Among Japanese capital goods houses, ULVAC and Tokyo Electron exemplify the Asia-Pacific anchored archetype with localized service networks. Applied Materials represents the integrated process platform model with recurring revenue architectures. Bühler Group occupies a position within European industrial coating specialization. Von Ardenne and Veeco Instruments sit within the precision optics and display equipment tier. IHI Corporation and Oerlikon Balzers exemplify diversified industrial conglomerates with deposition technology divisions. AIXTRON represents the compound semiconductor and specialty materials equipment archetype.
| Leading Market Players |
|---|
| Bühler Group |
| AIXTRON |
| Applied Materials |
| Von Ardenne |
| Veeco Instruments |
| ULVAC |
| IHI Corporation |
| Tokyo Electron |
| Oerlikon Balzers |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists concentrated in Germany and Japan anchor deposition chamber fabrication, their conservative balance sheet discipline limiting capacity expansion even as semiconductor foundry demand surges. This ownership structure tightens supply availability and transfers pricing power toward equipment vendors with captive precursor chemistry operations.
Pricing Analysis
Margin tightening in standard sputtering systems reflects aggressive quoting from Chinese equipment fabricators targeting display manufacturing procurement. Three-tier pricing structure across precision-critical, performance-optimized, and economy-level configurations dominates contract negotiations. Cost-down pressure accelerates because foundries bundle long-term service contracts as mandatory inclusions rather than optional add-ons. Display panel manufacturers in China exhibit highest price sensitivity; semiconductor logic chip producers in Taiwan and South Korea prioritize thickness precision over capital cost.
Supply Chain Analysis
Workforce availability constraints in Nagano prefecture and Bavaria elongate lead times for high-vacuum chamber welding and precision machining. Component fabrication concentrates in Japan, Germany, and South Korea, with specialty pump and gauge sourcing tethered to Tokyo and Stuttgart industrial clusters. Raw material dependencies include high-purity aluminum alloys, borosilicate glass viewports, and rare-earth magnetic targets for magnetron configurations. Single-source vulnerability around turbo molecular pump bearings from Swiss manufacturers exposes delivery schedules to geopolitical friction. Distribution runs through direct sales engineering teams co-located with Hsinchu, Pyeongtaek, and Shanghai fabrication clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over precursor chemical supply chains determines service contract profitability and customer lock-in duration.
For Market Incumbents: Extend software-defined process control architectures into predictive maintenance platforms with cloud-connected recipe libraries. Anchor recurring revenue through digital retrofit programs targeting Applied Materials' installed base. Defend against atomic layer deposition specialists by pre-integrating angstrom-precision metrology into legacy sputtering platforms. Deepen backward integration into specialty gas distribution infrastructure to capture margin from precursor logistics.
For New Entrants and Emerging Players: Launch via equipment-as-a-service models targeting India's PLI-subsidized semiconductor greenfield projects with localized technical support partnerships. Penetrate solid-state battery ceramic electrolyte deposition as equipment buyers qualify ALD systems outside semiconductor applications. Exploit vacuum technology specialist shortages by building training academy partnerships with South Korean technical universities. White-space concentrates in energy storage coating verticals where performance specifications diverge from electronics industry norms.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap deposition technology houses with established JIS or SEMI S2/S8 certification portfolios and service networks in East Asia. Long-term viability hinges on software attach rates and recurring service contract penetration rather than transactional equipment sales alone. Target acquisition archetype: regional equipment fabricators with captive precursor handling expertise and localized installation teams. Watch semiconductor node transition announcements from TSMC and Samsung as inflection indicators for replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Chemistry | Captive supply of ALD and CVD precursor materials locks in margin from consumables recurring revenue. |
| Software-Defined Process Control Platform | Recipe optimization modules bundled with hardware transform transactional sales into long-term service relationships. |
| Geographic Expansion to India | PLI scheme incentives for semiconductor fabrication create greenfield equipment demand with localized service requirements. |
| Joint Venture with Display Panel Manufacturer | Co-development of large-area sputtering platforms for Gen 10.5 OLED lines secures volume commitments. |
| Green Manufacturing Transition | Closed-loop vacuum system designs satisfy EPA NESHAP and EU REACH compliance mandates for hazardous emission reduction. |
Methodological Framework
SEC 10-K filings, customs and trade data from Japan and South Korea, and SEMI industry association reports formed the secondary backbone for equipment shipment and revenue estimation. Primary interviews with deposition process engineers, semiconductor fab procurement directors, vacuum technology service technicians, and specialty gas supply managers validated secondary findings against operational realities. Bottom-up and top-down triangulation reconciled vendor-reported bookings with end-user capital expenditure disclosures.
Bottom-up modeling aggregated individual equipment line forecasts across sputtering, atomic layer deposition, chemical vapor deposition, and thermal evaporation platforms. Segmentation dimensions included product type, end-user industry, deposition technology, and application specification. CAGRs derived from regression analysis against semiconductor capital intensity indices and display panel area expansion rates. Forecast inputs incorporated foundry node transition timelines and OLED substrate generation upgrades without year-specific milestones.
Semiconductor demand cyclicality, regulatory acceleration of precursor chemical restrictions, and workforce availability for vacuum technology specialization are the dominant revision risks across the projection horizon. Forecasts reflect documented assumptions regarding equipment replacement cycle compression and service contract bundling penetration. Material deviation in foundry capital expenditure announcements or REACH chemical registration enforcement timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Equipment
Wet Station Market
Semiconductor Equipment
Automatic Mounter Wafer Equipment Market
Semiconductor Equipment
Thin Film Deposition Equipment Market
Semiconductor Equipment
Ion Milling System Market
Semiconductor Equipment
China Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
North America Battery Manufacturing Equipment Market
Semiconductor Equipment
300 Mm Front Opening Unified Pods (Foups) Market
Semiconductor Equipment
Wafer Back-Grinding Machine Market
Semiconductor Equipment
Semiconductor Bonding Equipment Market
Semiconductor Equipment
Dry Reactor Market
Semiconductor Equipment
Semiconductor Laser Equipment Market
Semiconductor Equipment
Asia-Pacific Extreme Ultraviolet Lithography (EUVL) Systems Market
Semiconductor Equipment
DUV Lithography Systems Market
Semiconductor Equipment
Vacuum Ovens Market
Semiconductor Equipment
Epitaxy Equipment Market
Semiconductor Equipment
United States Chip Mounter Market