
 Electronic Manufacturing Services (EMS) Market | 2026-2036
Electronic Manufacturing Services (EMS) Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Manufacturing Services (EMS) Market Analysis
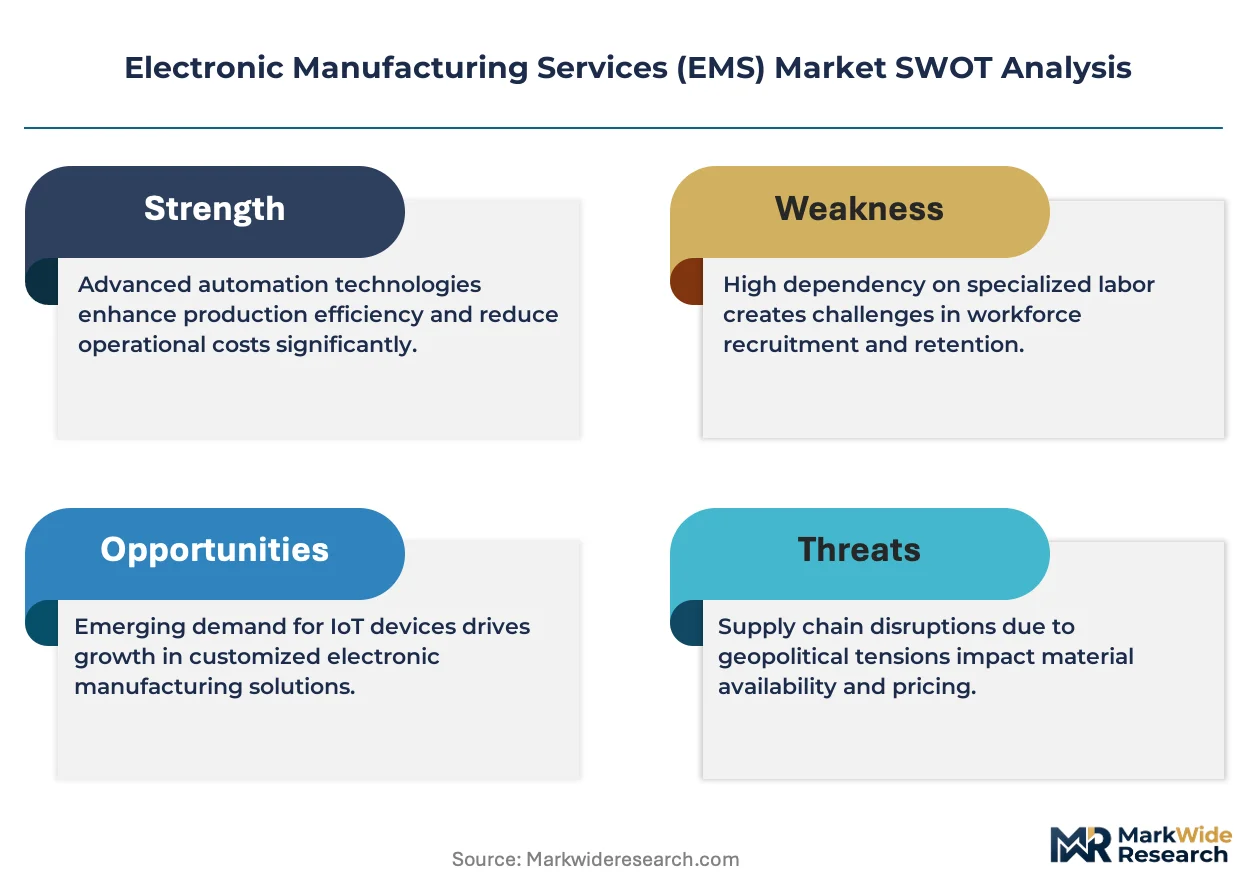
Modular box-build configurations is hardening as the dominant procurement pattern, letting OEMs mix PCB assembly, connector assembly, and final integration from different suppliers. Foxconn leverages its captive component ecosystem to control cost structures across smartphone and server programs. Jabil Inc anchors North American medical device and automotive programs with FDA-registered cleanroom capacity. Benchmark Electronics Inc specializes in low-volume, high-complexity industrial and aerospace programs where traceability requirements exceed consumer-grade standards.
Electronic Manufacturing Services encompasses the outsourced design, assembly, testing, and fulfillment of electronic products, typically involving surface mount technology placement accuracy below 50 microns and mixed-technology boards combining rigid-flex substrates. EMS providers serve industrial and commercial buyers seeking capital-efficient production without owning fixed fabrication assets. PCB Assembly and Box Build Assembly command the largest revenue pools where scale economies and inventory velocity determine margin capture. Test Services represents the fastest-expanding segment as automotive OEMs and medical device makers impose zero-defect protocols and in-circuit validation requirements. Surface Mount Technology dominates technology mix while Nano-coating adoption accelerates in medical and marine applications demanding moisture and corrosion resistance.
FCC equipment authorization rules shape product access for US-bound IoT devices and telecommunications hardware, while FDA quality system regulation governs medical device contract manufacturing site qualifications. RoHS substance restrictions and REACH SVHC disclosure obligations in Europe compel material composition tracking across multi-tier supplier networks. Stakeholders must monitor how EPA per- and polyfluoroalkyl substance rules and evolving EU Green Deal due diligence frameworks redirect sourcing for coated and encapsulated electronics.
Market Dynamics
Automotive electrification is forcing EMS providers to requalify production lines for high-voltage battery systems and power electronics, compressing traditional consumer-electronics margins while opening industrial-scale contract volumes.
Growth Catalysts
- EV Powertrain Outsourcing:Automotive OEMs are transferring electric motor controller and battery management system production to contract manufacturers, eliminating captive assembly investments.
- REACH SVHC Tracking Mandates:European material disclosure rules are compelling tier-n supplier audits, creating demand for EMS providers with embedded compliance infrastructure.
- Surface Mount Precision Thresholds:Sub-50-micron placement accuracy requirements in medical implants and aerospace avionics are filtering out mid-tier assembly houses.
Market Restraints
- Rare Earth Magnet Concentration:Permanent magnet supply chains cluster in Chinese processing facilities, exposing motor and sensor programs to export restriction volatility.
- RoHS Exemption Expirations:European substance restrictions on leaded solders in high-reliability applications are forcing costly alloy substitutions without performance parity.
- Cleanroom Capex Barriers:FDA-registered medical device assembly requires ISO 14644 Class 7 infrastructure that locks out smaller regional competitors.
Strategic Opportunities
- Vietnam Electronics Corridors:Northern industrial zones around Bac Ninh and Hai Phong are attracting box-build investments from manufacturers diversifying beyond Chinese assembly concentration.
- US IRA Clean Energy Credits:Domestic content bonuses for battery energy storage systems are incentivizing reshoring of power electronics assembly to Texas and Arizona.
- Nano-Coating Medical Adoption:Parylene and plasma-applied barrier films are penetrating implantable device segments where moisture ingress failure rates must approach zero.
Industry Challenges
- IPC-Certified Technician Scarcity:J-STD-001 and IPC-A-610 specialist credentials lag program ramp rates in Vietnam and Mexico expansion sites.
- Multi-Site Quality Harmonization:Aerospace prime contractors demand identical process control documentation across geographically dispersed EMS facilities, complicating audit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Manufacturing Services (EMS) Market |
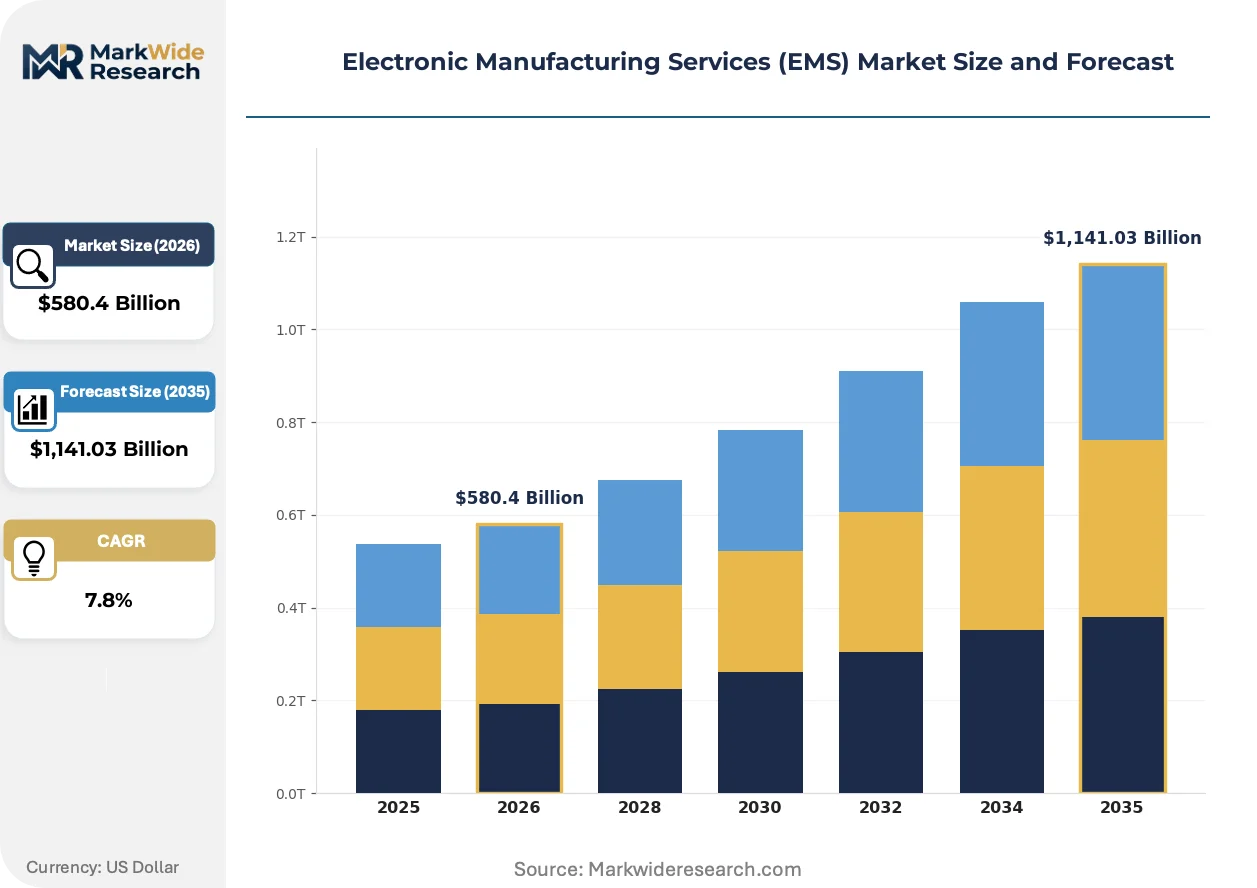
| Market Size in 2026 | $580.4 Billion |
| Market Size in 2035 | $1,141.03 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: PCB Assembly, Connector Assembly, Box Build Assembly, Test Services Industry Vertical: Telecommunications, Automotive OEMs, Consumer Electronics, Medical Devices Technology: Surface Mount Technology, Through-Hole Technology, Mixed Technology, Nano-coating Product Type: Smartphones, Wearables, Industrial Equipment, IoT Devices |
| Companies Covered | Pegatron Corporation, Celestica Inc, Foxconn, Plexus Corp, Benchmark Electronics Inc, Flex Ltd, Sanmina Corporation, Wistron Corporation, Jabil Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Manufacturing Services (EMS) Market Emerging Trajectories
Process automation and material traceability systems are converging to enable zero-defect manufacturing protocols that medical and automotive buyers now mandate in contract specifications.
Artificial intelligence-driven optical inspection is overtaking rule-based automated optical inspection in PCB assembly lines. Medical device and automotive Tier-1 suppliers are adopting deep-learning defect classification to compress false-positive rates below two percent. This displacement is reducing manual rework stations and reshaping quality engineering staffing models across high-mix facilities.
EU Green Deal due diligence frameworks are extending supply chain accountability to Scope 3 emissions disclosure for electronics contract manufacturers. EMS providers must now document carbon intensity across component sourcing, freight modes, and facility energy mix. Automotive and industrial OEMs with net-zero commitments are prioritizing providers with verified renewable power contracts.
Modular procurement architectures are fragmentating traditional single-source box-build relationships. OEMs now disaggregate PCB assembly, cable harness fabrication, and final system integration across specialized providers, compressing contract durations and intensifying price transparency. This pattern is most pronounced in industrial automation and telecommunications infrastructure verticals where product lifecycles exceed five years.
Electronic Manufacturing Services (EMS) Market Segmentation
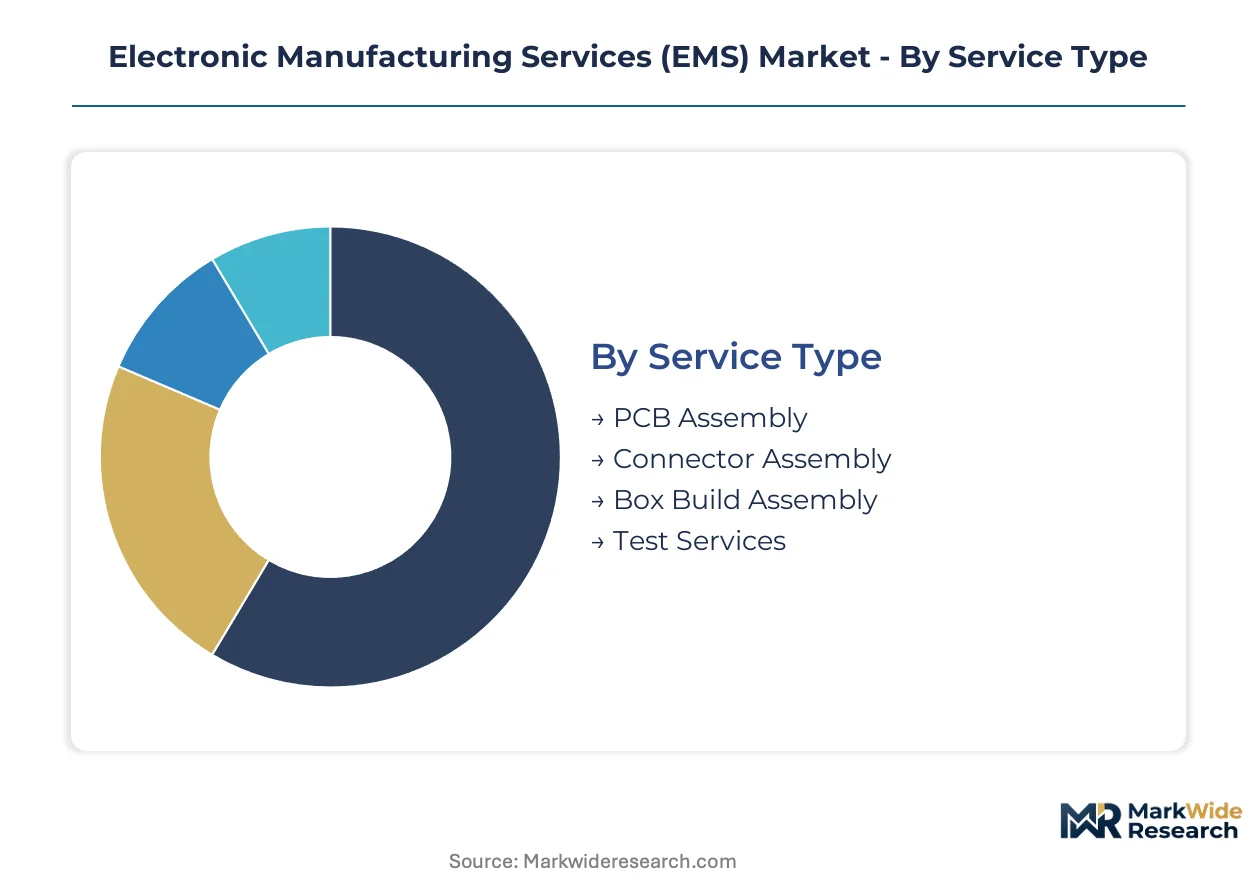
EMS procurement patterns fragment across service capabilities, end-use reliability requirements, and technology precision thresholds. Contract specifications diverge sharply between high-volume consumer programs and low-volume medical or aerospace work.
Service Type:
Volume-heavy assembly commands the largest contract values, while specialized testing and integration services capture premium margins.
- PCB Assembly:Surface mount and through-hole component mounting on rigid, flex, and rigid-flex substrates with placement accuracy below 50 microns for medical implant applications. Automotive powertrain controllers and smartphone motherboards concentrate demand in Vietnam and Mexico as manufacturers diversify beyond Chinese assembly concentration.
- Box Build Assembly:Final system integration combining PCB assemblies, cable harnesses, enclosures, and firmware loading into finished products. Industrial automation and telecommunications infrastructure OEMs favor modular procurement, disaggregating subassembly sourcing across specialized providers.
- Connector Assembly:Precision crimping and soldering of interconnect systems for high-reliability signal integrity.
- Test Services:In-circuit validation, functional testing, and environmental stress screening with zero-defect protocols mandated by automotive Tier-1 suppliers.
Mature deployment sits with PCB Assembly. Newer deployment is concentrated in Test Services.
Industry Vertical:
Regulatory intensity and traceability requirements create tiered pricing structures across end-use applications.
- Automotive OEMs:Electric vehicle powertrain outsourcing is eliminating captive assembly investments for battery management systems and motor controllers. REACH SVHC tracking mandates and zero-defect protocols imposed by European and North American vehicle manufacturers are filtering out mid-tier assembly houses lacking embedded compliance infrastructure.
- Medical Devices:FDA-registered cleanroom assembly for implantable and diagnostic equipment with ISO 14644 Class 7 infrastructure requirements. FDA quality system regulation governs site qualifications, locking out smaller regional competitors from high-margin programs.
- Telecommunications:FCC equipment authorization shapes product access for US-bound IoT and networking hardware.
- Consumer Electronics:High-volume smartphone and wearable production with compressed margins and rapid product cycles.
Automotive OEMs are climbing the fastest as electrification forces production line requalification for high-voltage systems.
Technology:
Precision thresholds and material protection requirements segment providers by capital investment and process capability.
- Surface Mount Technology:Dominant placement method for miniaturized components on high-density interconnect boards with sub-50-micron accuracy requirements in aerospace avionics. Sub-50-micron placement precision is filtering out mid-tier assembly houses as medical implant and aerospace specifications tighten.
- Nano-coating:Parylene and plasma-applied barrier films for moisture and corrosion resistance in implantable devices and marine electronics. Medical device segments demanding near-zero moisture ingress failure rates are accelerating adoption of plasma-applied barrier films.
- Mixed Technology:Combining surface mount and through-hole components on rigid-flex substrates for complex industrial applications.
- Through-Hole Technology:Manual and selective soldering for high-power components and legacy system sustainment.
Process maturity centers on Surface Mount Technology. Capability expansion is concentrated in Nano-coating.
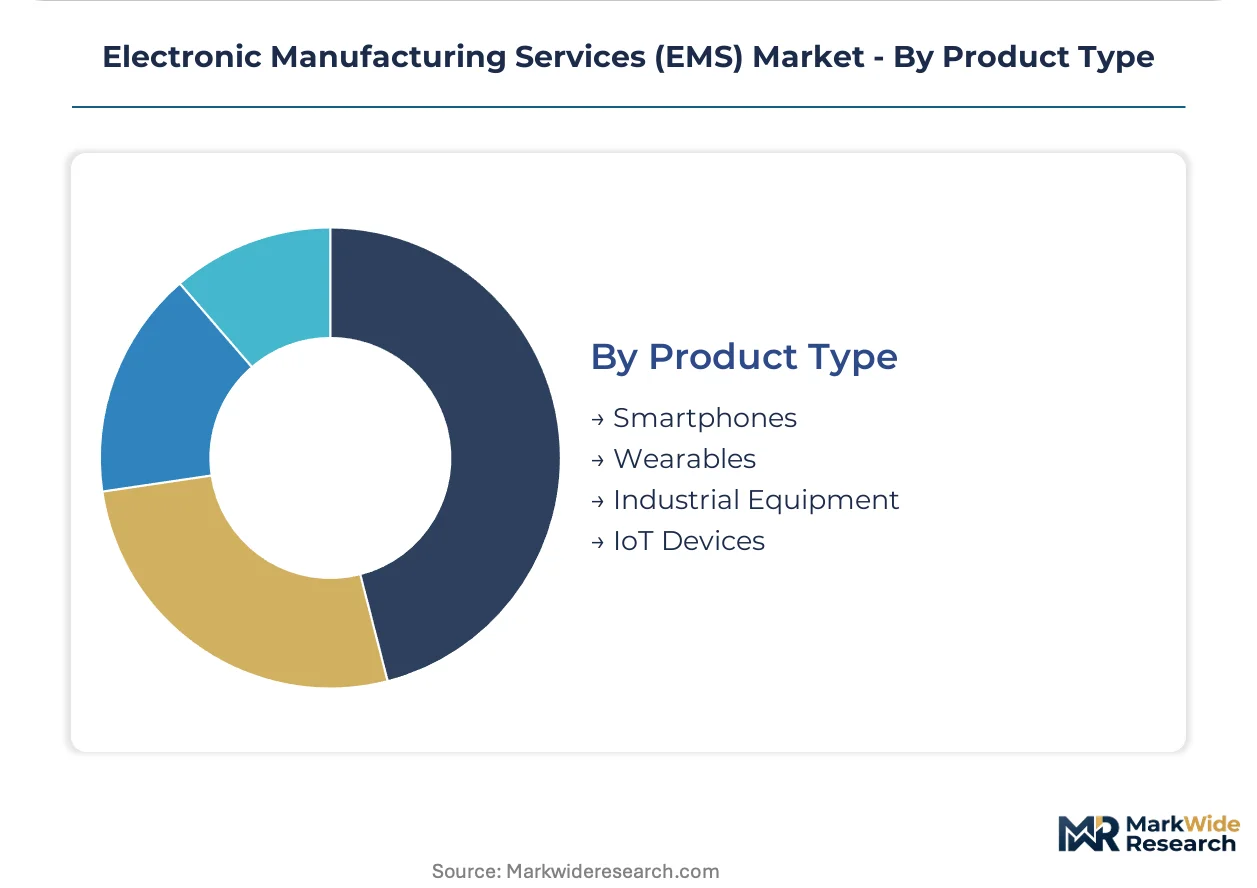
Product Type:
Lifecycle duration and volume predictability determine contract structure and supplier selection criteria.
- Industrial Equipment:Low-volume, high-complexity programs with traceability requirements exceeding consumer-grade standards and product lifecycles exceeding five years. Modular procurement architectures are fragmenting traditional single-source relationships as OEMs disaggregate PCB assembly, cable harness fabrication, and final integration.
- IoT Devices:Connected sensor and edge computing hardware with FCC equipment authorization requirements for US market access. FCC equipment authorization rules and EU Green Deal due diligence frameworks are redirecting sourcing for coated and encapsulated electronics.
- Smartphones:High-volume flagship and mid-tier handset assembly with compressed development cycles.
- Wearables:Miniaturized health and fitness devices with stringent moisture protection requirements.
Established production patterns dominate Industrial Equipment. Fastest capacity buildup is occurring in IoT Devices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China retains the dominant share of electronics assembly capacity while consumption pulls toward North American and European automotive and medical device OEMs. Contract manufacturers are diversifying final assembly and box-build operations across Vietnam, Mexico, and India to reduce geographic concentration risk. Regulatory divergence between REACH-driven European material rules and IRA-linked US domestic content incentives is fragmenting supplier qualification requirements.
United States
Automotive OEMs are reshoring power electronics assembly for battery energy storage systems to capture IRA clean energy credits. FDA quality system regulation governs medical device contract manufacturing site qualifications, filtering out non-registered competitors. Texas and Arizona industrial corridors are attracting box-build investments from manufacturers seeking proximity to North American EV supply chains.
China
Domestic EV powertrain demand and smartphone production sustain the largest PCB assembly volumes globally. MIIT standards and dual carbon goals are tightening energy efficiency and emissions disclosure requirements for electronics manufacturers. Shenzhen and Dongguan manufacturing clusters retain surface mount technology dominance despite outward investment diversification.
Vietnam
Northern industrial zones around Bac Ninh and Hai Phong are absorbing box-build capacity shifts from Chinese assembly concentration. The country's national trade regulator facilitates electronics export processing zone incentives. Samsung and Apple supplier ecosystems are deepening local PCB assembly and connector assembly capabilities.
Germany
Automotive electrification is driving contract manufacturing demand for high-voltage battery management systems and motor controllers. REACH SVHC tracking mandates and RoHS substance restrictions compel tier-n supplier audits across multi-tier networks. Bavaria and Baden-Württemberg host precision assembly operations serving automotive Tier-1 suppliers with zero-defect protocols.
Mexico
Nearshoring demand from US medical device and industrial automation OEMs is expanding FDA-registered cleanroom capacity. The central bank monitors inflationary pressure on electronics import component costs. Baja California and Chihuahua border states concentrate box-build operations benefiting from USMCA tariff preferences and logistics proximity.
Electronic Manufacturing Services (EMS) Market Vendor Landscape
The competitive structure tilts toward diversified global scale players with captive component ecosystems. Tier-one providers command automotive and medical device programs requiring FDA-registered infrastructure and REACH compliance systems. Mid-tier specialists occupy low-volume, high-complexity aerospace and industrial niches where traceability requirements exceed consumer-grade standards. Capacity expansion and strategic partnerships represent the dominant competitive moves as providers establish multi-site quality harmonization across Vietnam and Mexico expansion locations.
Among Taiwan-based fabricators, Foxconn and Wistron Corporation exemplify scale-driven archetypes leveraging integrated component supply chains for smartphone and server programs. Celestica Inc and Jabil Inc represent North American-anchored providers with FDA-registered cleanroom capacity serving medical device and automotive electrification programs. Benchmark Electronics Inc occupies a position within the low-volume, high-complexity specialist tier where aerospace traceability requirements filter out mass-market competitors.
| Leading Market Players |
|---|
| Pegatron Corporation |
| Celestica Inc |
| Foxconn |
| Plexus Corp |
| Benchmark Electronics Inc |
| Flex Ltd |
| Sanmina Corporation |
| Wistron Corporation |
| Jabil Inc |
| Others |
Supply Flow & Price Mechanics
Copper and rare earth price indices cascade through EMS contract tiers, compressing margins in high-volume consumer assembly while insulating premium medical and automotive programs where zero-defect protocols command cost pass-through.
Pricing Analysis
Margin tightening in smartphone and consumer electronics assembly reflects compressed product cycles and OEM dual-sourcing mandates. Three-tier pricing structure across FDA-registered medical, automotive-qualified industrial, and standard consumer grades separates providers by certification burden and traceability infrastructure. Cost-down pressure on box-build services accelerates because modular procurement lets OEMs disaggregate subassembly sourcing across Vietnam and Mexico corridors. Consumer OEMs exhibit acute price sensitivity, while medical device and aerospace buyers prioritize defect-rate performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth processing facilities that concentrate permanent magnet supply for motor and sensor programs. Component sourcing draws from China, Vietnam, and Mexico for PCB assembly, with connector and cable harness dependencies anchored in Taiwan and Japan. Tariff exposure on US-bound electronics from Chinese assembly sites is redirecting box-build investment toward Bac Ninh and Hai Phong industrial zones. Distribution runs through direct OEM contracts with tier-n supplier qualification managed by EMS providers rather than component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive electrification and REACH compliance mandates are forcing consolidation among mid-tier assembly houses lacking cleanroom infrastructure or embedded material tracking systems.
For Market Incumbents: Acquire ISO 14644 Class 7 cleanroom assets in Mexico and Vietnam to defend automotive and medical programs against regional specialists. Jabil and Celestica anchor North American FDA-registered capacity; Foxconn leverages captive component ecosystems. Threats from modular procurement architectures disaggregating traditional box-build relationships intensify price transparency. Backward integration into PCB fabrication and connector supply secures margin control across high-mix, low-volume aerospace contracts. For New Entrants and Emerging Players: Capture nano-coating service gaps in implantable medical devices where Parylene barrier film demand outpaces qualified provider capacity. Vietnam's northern electronics corridors around Hai Phong offer the most penetrable geography for box-build investments diversifying beyond Chinese concentration. A go-to-market angle targeting industrial automation OEMs with five-year-plus lifecycles favors modular subassembly partnerships over single-source integration contracts. For Investors and Strategic Acquirers: The window for entry favors vertically integrated specialists with FDA-registered infrastructure and REACH SVHC tracking systems over pure-play assembly houses. Long-term viability hinges on multi-site quality harmonization capabilities across geographically dispersed facilities. Watch IPC-Certified technician scarcity in Vietnam and Mexico expansion sites as the inflection signal for operational execution risk.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Site Quality Harmonization | Aerospace prime contractors demand identical process control documentation across Vietnam, Mexico, and US facilities. |
| Cleanroom Capacity Expansion | FDA-registered ISO 14644 Class 7 infrastructure locks in medical device programs with margins exceeding consumer assembly. |
| REACH Compliance Infrastructure | Embedded SVHC tracking systems filter out mid-tier competitors from European automotive electrification contracts. |
| AI-Driven Optical Inspection Deployment | Deep-learning defect classification compresses false-positive rates below two percent for zero-defect automotive protocols. |
| Rare Earth Magnet Supply Diversification | Non-Chinese processing alternatives reduce export restriction exposure for motor controller and sensor programs. |
Methodological Framework
Document review covered SEC filings from Foxconn, Jabil, and Celestica, complemented by interviews with EMS procurement directors, automotive Tier 1 supplier quality engineers, FDA regulatory affairs leads, and medical device GPO contracts managers. Secondary validation drew from FCC equipment authorization databases, ECHA REACH SVHC candidate lists, EPA PFAS regulatory dockets, and customs trade data on electronics component flows. Bottom-up facility capacity estimates triangulated against top-down OEM contract value allocations.
Segment-level revenue outputs trace to modeled splits across PCB assembly, box-build, and test services, further disaggregated by automotive electrification, medical device, and industrial automation verticals. Placement accuracy thresholds and cleanroom certification tiers introduced technology and regulatory dimensions. CAGRs derive from production line requalification timelines for high-voltage battery systems and nano-coating adoption curves in implantable devices.
The model holds under stable trade policy and sustained automotive electrification investment; deviation in rare earth export restrictions or RoHS exemption timelines would shift provider competitiveness rankings. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Manufacturing
Stencil Lithography Market
Semiconductor Manufacturing
Europe Electronic Manufacturing Services Market
Semiconductor Manufacturing
Surface Mount Technology (SMT) Market
Semiconductor Manufacturing
United States Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
Europe Photoresist and Photoresist Ancillaries Market
Semiconductor Manufacturing
China Electronic Design Automation (EDA) Tools Market
Semiconductor Manufacturing
Solar Laser Drilling Market
Semiconductor Manufacturing
Malaysia and Thailand Precession Cleaning for Electronic Market
Semiconductor Manufacturing
Semiconductor and Circuit Manufacturing Market
Semiconductor Manufacturing
IC CMP Slurries and Pads Market
Semiconductor Manufacturing
PCB Photoresist Market
Semiconductor Manufacturing
High Purity Process Systems for Semiconductor Market
Semiconductor Manufacturing
Battery Manufacturing Machines Market
Semiconductor Manufacturing
Global EUV Lithography Market
Semiconductor Manufacturing
Photoresist Stripper Market
Semiconductor Manufacturing
Silicon Wafer Reclaim Market