
 United Kingdom Barbeque Grill Market | 2026-2036
United Kingdom Barbeque Grill Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Barbeque Grill Market Outlook
CE marking under the UKCA regime is redrawing competitive boundaries for grill importers and domestic manufacturers. Weber-Stephen Products LLC leverages its brand heritage to sustain premium positioning across garden centres and specialty retailers. Napoleon Grills anchors its UK presence through robust dealer networks and stainless-steel construction credentials. Landmann competes aggressively in the mid-range gas segment with German-engineered burner systems adapted for British weather conditions.
A barbeque grill is a cooking appliance designed for outdoor use, typically comprising a firebox, cooking grate, and lid assembly with temperature control mechanisms ranging from direct charcoal combustion to precision gas valve regulation or electric resistance heating. The primary commercial purpose centres on preparing food through radiant and convective heat transfer in residential gardens, commercial hospitality terraces, and recreational camping settings. Gas grills occupy the largest volume share among product types due to convenience and regulatory tolerance in smoke-controlled zones, while pellet grills represent the fastest-expanding category as wood-fired flavour profiles gain traction among enthusiasts seeking automated temperature management. The premium price tier captures disproportionate margin pools as British consumers trade up toward ceramic kamado constructions and Wi-Fi-enabled smart controls.
The UK's Office for Product Safety and Standards enforces stringent construction and stability requirements under the General Product Safety Regulations, while local authority environmental health departments administer Clean Air Act provisions that restrict charcoal combustion in designated smoke control areas. These frameworks compel manufacturers to engineer cleaner-burning alternatives and clearer fuel labelling. Stakeholders must monitor evolving UKCA transition timelines and potential divergence from EU harmonised standards when allocating certification budgets and product development resources.
Market Dynamics
The UKCA regime's divergence from CE marking standards is fragmenting supplier compliance pathways and forcing recertification investments across the import base.
Growth Catalysts
- Clean Air Act enforcement:Local authority smoke control designations are accelerating gas grill substitution in Greater London and Birmingham corridors where charcoal combustion faces outright bans.
- Garden room construction:The surge in residential outdoor living spaces across Surrey and Hertfordshire is creating dedicated cooking zones requiring permanent appliance installations.
- Pellet automation:Wood-fired flavor profiles combined with PID temperature controllers are converting traditionalist charcoal users in the enthusiast segment.
Market Restraints
- Stainless steel volatility:Grade 304 sheet input costs swing with nickel futures, compressing margin stability for mid-range gas grill assemblers.
- East Asian supply concentration:Cast iron grates and burner assemblies concentrate in Zhejiang and Guangdong manufacturing clusters, exposing importers to shipping rate spikes.
- UKCA transition friction:The delayed full enforcement timeline creates inventory stranding risk for products certified only under legacy CE frameworks.
Strategic Opportunities
- Scottish Highlands penetration:Rural properties outside smoke control zones retain charcoal freedom, creating underserved demand for premium kamado constructions.
- Commercial hospitality terraces:Pub and restaurant outdoor dining investments in Manchester and Bristol require NSF-rated equipment with rapid recovery burners.
- Smart home convergence:Wi-Fi-enabled temperature probes integrated with Alexa and Google Home ecosystems are opening premium price tiers among tech-forward homeowners.
Industry Challenges
- Gas Safe Register compliance:Technician certification requirements for LPG connection work lengthen installation timelines and inflate after-sales costs.
- UKCA testing backlog:Notified body capacity constraints delay product launch windows, particularly for novel electric grill architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Barbeque Grill Market |
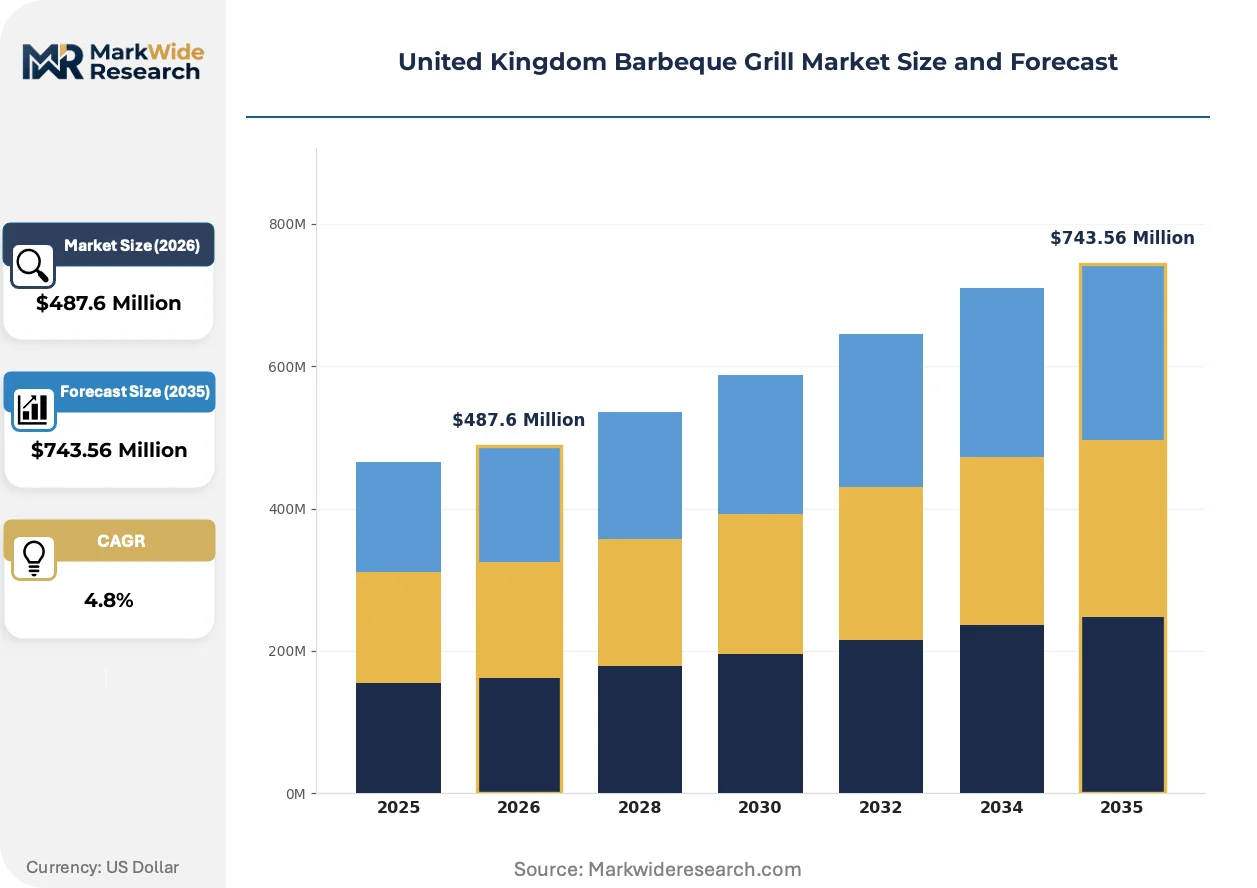
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Grill, Charcoal Grill, Electric Grill, Pellet Grill Fuel Type: Charcoal, Gas, Wood, Electricity End User: Homeowners, Restaurants, Camping Enthusiasts, Event Planners Price Tier: Premium, Mid-Range, Budget, Luxury |
| Companies Covered | Weber-Stephen Products LLC, Char-Broil, Napoleon Grills, Big Green Egg, Traeger Grills, The Middleby Corporation, Landmann, Outback International UK, Pit Boss Grills, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Barbeque Grill Market Strategic Shifts
Connected cooking systems and emissions-compliant fuel alternatives are restructuring how British households approach outdoor meal preparation and appliance selection.
Ceramic kamado construction is decomposing the traditional price-performance tradeoff in high-heat retention cooking. Affluent suburban buyers in Buckinghamshire and Cheshire are specifying these units for year-round use, collapsing the seasonal demand trough that historically constrained grill utilization rates and accessory sales cycles.
UKCA marking requirements under the Office for Product Safety and Standards are redirecting importer sourcing toward domestic assembly partnerships. The construction and stability testing mandates compress profit pools on entry-level imports while rewarding UK-based fabricators with faster certification turnaround and reduced customs friction.
Alfresco dining's normalization is shortening replacement cycles for built-in outdoor kitchen modules. Homeowners in Essex and Kent are treating grills as depreciating appliances rather than durable goods, favoring modular systems with swappable burner configurations over welded fixed designs. This behavioral pivot concentrates volume in garden centre channels offering installation and financing bundles.
United Kingdom Barbeque Grill Market Segmentation
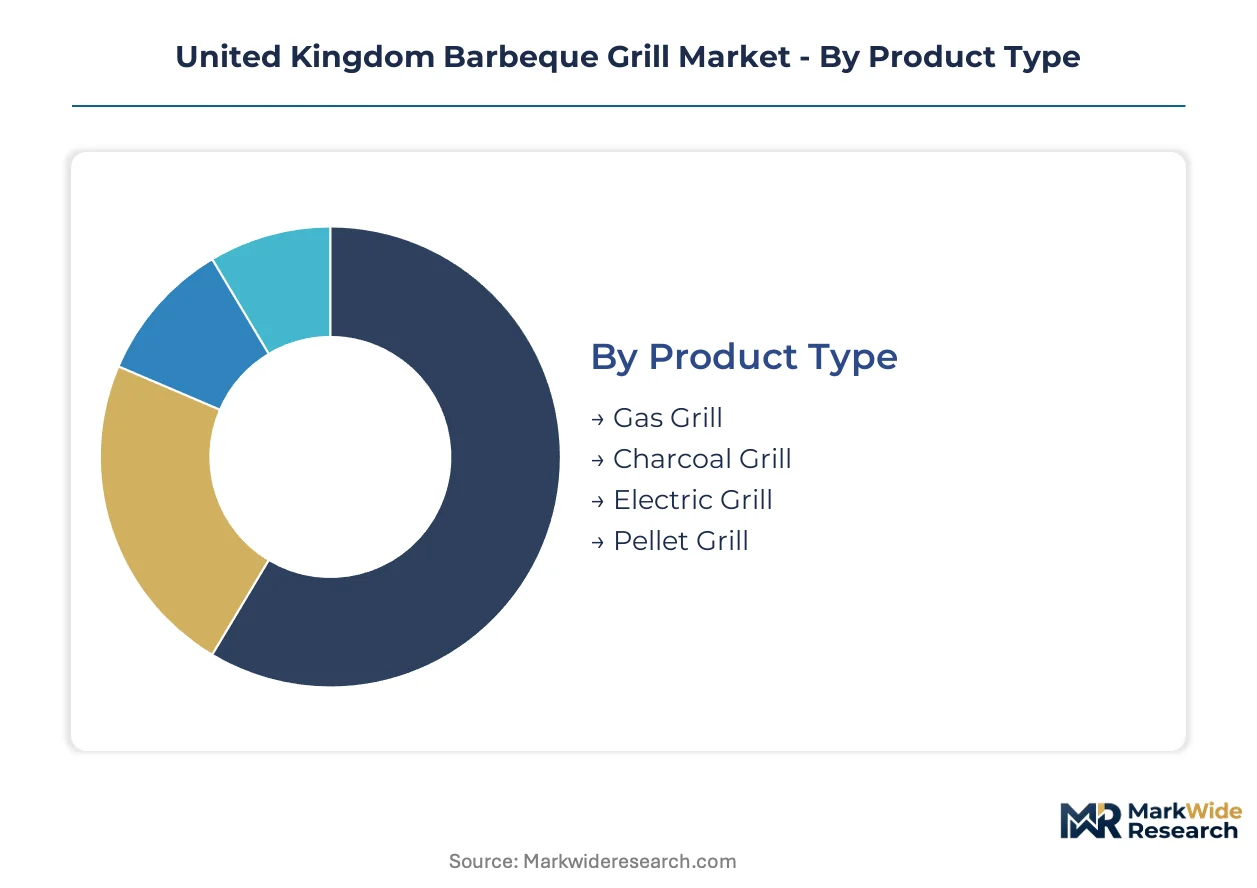
Grill segmentation in the United Kingdom reflects divergent compliance burdens, fuel access restrictions, and outdoor living investment patterns across suburban England and rural peripheries. Category boundaries are hardening as UKCA certification costs and Clean Air Act enforcement reshape viable product configurations for importers and domestic fabricators.
Product Type:
Margin pools concentrate in automated fuel delivery systems that command premium positioning through precision temperature control and reduced operator attention.
- Gas Grill:These units deploy propane or natural gas through brass or cast-aluminum burner manifolds with piezoelectric ignition. Demand clusters in Greater London and Birmingham smoke control zones where charcoal combustion faces prohibition, driving replacement cycles among compliance-conscious homeowners.
- Pellet Grill:Auger-fed hardwood pellet systems with PID controllers automate wood-fired flavor delivery. Enthusiasts in Surrey and Hertfordshire garden room installations are adopting these for year-round cooking without charcoal's regulatory exposure.
- Charcoal Grill:Traditional kettle and kamado constructions using lump charcoal or briquettes retain dominance in rural Scottish Highlands and Welsh counties outside designated smoke control areas.
- Electric Grill:Resistance-heated cooking surfaces suit apartment terraces and balcony installations where open flame restrictions apply across Manchester and Bristol high-density housing.
Gas Grill holds installed capacity. Pellet Grill is rotating up the share rankings.
Fuel Type:
Volume distribution tracks regulatory geography more closely than consumer preference, with fuel legality determining addressable market boundaries.
- Gas:LPG and natural gas systems dominate suburban corridors where pipeline infrastructure or cylinder exchange networks are mature, particularly across England's southeast commuter belt.
- Charcoal:Lump hardwood and compressed briquette combustion retains enthusiast loyalty in smoke-control-exempt zones, though Clean Air Act expansion is compressing this segment's geographic footprint.
- Wood:Hardwood pellets and chunks serve the automation-seeking segment seeking smoke profiles without manual fire management, climbing fastest among Buckinghamshire and Cheshire affluent households.
- Electricity:Resistance heating elements capture balcony and terrace installations where leasehold restrictions prohibit combustible fuels, concentrated in London apartment stock.
Gas retains volume leadership. Wood is gaining share fastest through pellet system adoption.
End User:
Application requirements diverge sharply between residential convenience priorities and commercial durability specifications.
- Homeowners:Suburban garden culture in Kent and Essex drives replacement-cycle compression as outdoor kitchens become standard new-build features rather than discretionary additions.
- Restaurants:Pub and hospitality terrace operations in Manchester and Bristol demand NSF-rated stainless construction with rapid recovery burners for high-throughput service periods.
- Camping Enthusiasts:Portable charcoal and gas systems serve recreational vehicle and tent-based outdoor cooking, with demand peaking in Lake District and Peak District corridor retail.
- Event Planners:Rental and catering operations require modular equipment with rapid deployment and breakdown capabilities for wedding and festival temporary installations.
Homeowners anchor volume. Restaurants are expanding fastest through outdoor dining infrastructure investment.
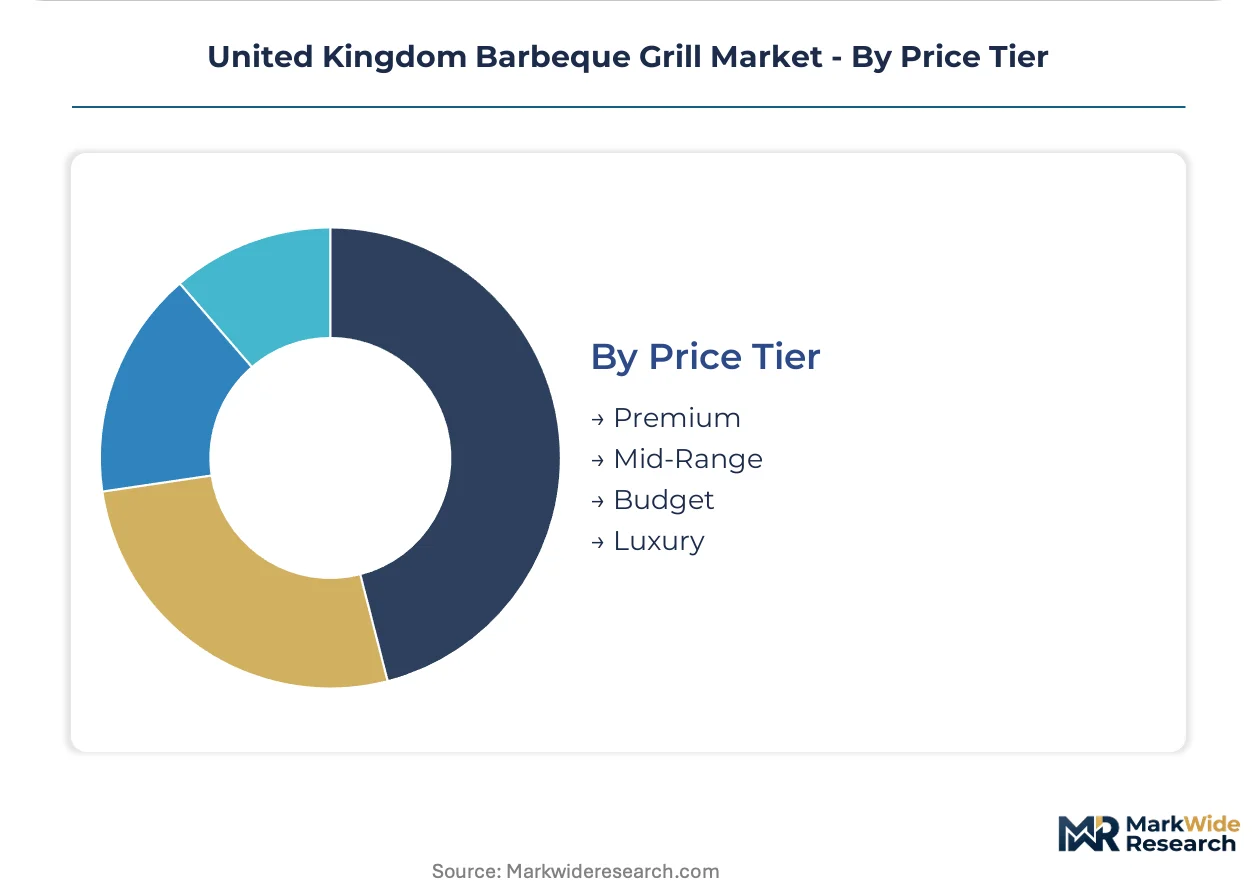
Price Tier:
Certification cost absorption and material specification thresholds stratify the market into distinct procurement channels.
- Premium:Ceramic kamado and thick-gauge stainless gas systems with Wi-Fi connectivity target affluent suburban buyers in Cheshire and Buckinghamshire seeking year-round outdoor cooking capability.
- Mid-Range:Porcelain-enameled steel and standard-grade stainless constructions balance durability against cost, capturing garden centre volume across England's suburban corridors.
- Budget:Thin-gauge steel and basic aluminum imports serve price-sensitive seasonal users, though UKCA transition costs are compressing this tier's supplier base and retail presence.
- Luxury:Built-in outdoor kitchen modules with integrated refrigeration and storage command project-based specification through landscape architects and high-end residential developers.
Premium captures margin concentration. Mid-Range rotates up through trade-up behavior from Budget tier compression.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The M6 motorway corridor and Felixstowe container port throughput underwrite England's dominance in grill import logistics and distribution reach into suburban markets.
London and Southeast England
Smoke control zone enforcement across Greater London and commuter belt counties accelerates gas grill replacement cycles among compliance-conscious homeowners. Local authority environmental health departments administer Clean Air Act provisions that restrict charcoal combustion in designated areas. Garden room construction in Surrey and Hertfordshire creates dedicated outdoor cooking zones requiring permanent appliance installations.
Midlands
Birmingham's smoke control designation and surrounding West Midlands urban corridors drive demand for pellet and electric alternatives to traditional charcoal. The Office for Product Safety and Standards enforces UKCA marking requirements that redirect importer sourcing toward domestic assembly partnerships. Retail concentration in Solihull and Coventry garden centres channels mid-range gas volume through installation and financing bundles.
North England
Manchester and Bristol hospitality terrace investments require NSF-rated equipment with rapid recovery burners for high-throughput service periods. Local authority smoke control designations vary by metropolitan borough, creating patchwork regulatory geography that favors flexible fuel-switching appliances. Sheffield and Leeds distribution hubs aggregate pellet supply for enthusiast segments seeking automated temperature management.
Scotland
Rural properties outside smoke control zones retain charcoal freedom, creating underserved demand for premium kamado constructions in Highland and Aberdeenshire markets. The Scottish Environment Protection Agency coordinates with local authorities on air quality management but exempts extensive rural territories from combustion restrictions. Edinburgh and Glasgow retail corridors concentrate mid-range gas volume while Highland specialty dealers serve enthusiast niches.
Wales
Coastal counties and rural interior zones outside designated smoke control areas sustain charcoal grill demand among traditionalist users. Natural Resources Wales administers air quality regulations with lighter enforcement touch than English metropolitan authorities. Cardiff and Newport retail clusters import entry-level gas systems through Bristol distribution channels while rural dealers serve camping and recreational vehicle segments.
United Kingdom Barbeque Grill Market Competitive Environment
Listed leaders compete with private specialists across certification compliance and channel access dimensions. The vendor base stratifies between heritage brands with garden centre penetration and direct-to-consumer entrants leveraging online review aggregation. Three archetypes dominate: premium heritage specialists, mid-range European fabricators, and pellet automation technology vendors. Capacity expansion and UKCA certification partnerships constitute the dominant competitive moves as transition timelines compress launch windows.
Within the premium heritage tier, Weber-Stephen Products LLC and Napoleon Grills anchor positioning through dealer network density and stainless-steel construction credentials. Landmann occupies a position among mid-range European fabricators with German-engineered burner systems adapted for British weather conditions. These three exemplify how geographic origin and corporate structure map onto certification burden absorption and channel access strategies.
| Leading Market Players |
|---|
| Weber-Stephen Products LLC |
| Char-Broil |
| Napoleon Grills |
| Big Green Egg |
| Traeger Grills |
| The Middleby Corporation |
| Landmann |
| Outback International UK |
| Pit Boss Grills |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for Zhejiang-sourced cast iron grates compress pricing power for mid-range gas grill assemblers while amplifying margin volatility across UKCA certification tiers. This lead-time exposure concentrates cost pass-through capacity among domestic fabricators with faster UKCA turnaround and reduced customs friction.
Pricing Analysis
Volume-discount tiering structures separate premium ceramic kamado constructions from mid-range porcelain-enameled steel units from budget thin-gauge aluminum imports. Price differentiation hinges on UKCA certification grade and stainless-steel gauge specification, with Grade 304 input cost swings compressing margin stability for mid-tier assemblers. Cost compression in the budget tier is intensifying because UKCA transition expenses strand legacy CE-certified inventory. Homeowners in Kent and Essex exhibit lowest price sensitivity for built-in outdoor kitchen modules, while seasonal users drive volume in entry-level channels.
Supply Chain Analysis
China and Taiwan anchor cast iron grate and burner manifold fabrication, with Zhejiang and Guangdong manufacturing clusters feeding component streams into UK assembly partnerships. Raw material dependencies center on nickel-priced Grade 304 stainless sheet, brass valve castings, and hardwood pellet feedstock. Single-source vulnerability concentrates in East Asian casting capacity, exposing importers to shipping rate spikes through Felixstowe port congestion. Distribution runs through garden centre installation bundles in Surrey and Hertfordshire, with specialist dealers serving enthusiast segments in Highland Scotland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK barbeque grill market sits at a platform-economics inflection as Wi-Fi-enabled temperature probes integrate with Alexa and Google Home ecosystems, collapsing hardware margins into recurring service-layer value pools.
For Market Incumbents: Consolidate dealer network density in Greater London smoke control corridors to defend against pellet automation entrants converting traditionalist charcoal users. Prioritize backward integration into UK-based stainless fabrication to compress UKCA certification timelines and neutralize import cost volatility from Zhejiang supply concentration. For New Entrants and Emerging Players: Post-installation calibration services for smart grill ecosystems represent an underserved service layer where incumbents under-serve. Target Scottish Highlands rural properties outside smoke control zones with premium kamado constructions through specialty dealer partnerships rather than garden centre mass retail. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-arbitrage play because UKCA divergence from CE standards creates captive domestic assembly value pools that compound as enforcement timelines compress. Monitor UKCA notified body capacity constraints as the inflection signal for certification bottleneck severity and domestic fabricator pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| UKCA Certification Partnership | Domestic assembly partnerships accelerate product launch windows amid notified body capacity constraints. |
| Smart Home Platform Integration | Alexa and Google Home ecosystem connectivity opens premium price tiers among tech-forward Buckinghamshire homeowners. |
| Pellet Supply Chain Localization | Hardwood pellet sourcing partnerships reduce exposure to transatlantic shipping rate volatility. |
| Commercial Hospitality Specification | NSF-rated equipment certification captures Manchester and Bristol pub terrace replacement cycles. |
| Scottish Highlands Distribution Expansion | Specialty dealer networks in Highland and Aberdeenshire access smoke-control-exempt charcoal demand. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs import records, garden centre sales audits, and Office for Product Safety and Standards certification databases. Interviews with product safety compliance officers, garden centre category buyers, stainless steel procurement managers, and outdoor kitchen installation contractors informed demand-side assumptions. Bottom-up volume builds triangulate against top-down macroeconomic consumption indicators across the UK household durables sector.
Segmentation dimensions modeled include fuel type, product architecture, end-user application, and price tier across the projection horizon. CAGRs derive from regression analysis against housing construction permits, smoke control zone expansion timelines, and alfresco dining frequency indices. Pellet grill automation adoption curves and UKCA transition cost absorption rates constitute industry-specific forecast inputs.
Forecasts assume regulatory continuity in UKCA marking requirements and Clean Air Act enforcement regimes; material policy shifts would require re-modeling. Stainless steel commodity volatility and East Asian supply chain disruption represent specific revision triggers. Recalibration cycles align with material shifts in notified body capacity, smoke control designation expansions, and smart home platform penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Food and Grocery Retail Market
Food Service
Nigeria Food Service Market
Food Service
United States Cafes & Bars Market
Food Service
India Quick Service Restaurant Market
Food Service
Global Cafe and Bars Market
Food Service
Contract Catering Market
Food Service
Breakfast Takeout Market
Food Service
Global Digital Food Delivery Market
Food Service
Chinese Takeout Market
Food Service
Limited-Service Restaurants Market
Food Service
Commercial Tandoor Oven Market
Food Service
North America Smokeless Indoor Grills Market
Food Service
North America Food Platform-To-Consumer Delivery Market
Food Service
Smart Food Logistics Market
Food Service
Gas Floor Fryers Market
Food Service
Commercial Restaurant Rangers Market