
 Brazil Foodservice Market | 2026-2036
Brazil Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Foodservice Market Outlook
Short-order cook availability is unwinding expansion plans across Brazil's foodservice sector, forcing chains to redesign kitchen workflows and automate prep stations. Arcos Dorados Holdings Inc. dominates the quick-service landscape through its McDonald's franchise network spanning Brazilian urban centers. Grupo Madero leverages its steakhouse expertise to anchor the premium casual segment with disciplined unit economics. Fogo de Chão sustains its competitive edge by controlling the churrascaria experience through specialized gaucho-trained service teams.
Brazil foodservice encompasses commercial establishments preparing and serving meals for immediate consumption, ranging from standardized quick-service formats to experiential full-service operations requiring cold-chain integrity and HACCP-compliant preparation protocols. The sector functions as a critical employment engine and cultural exchange platform, processing perishable proteins and regional produce through charcoal grilling, buffet assembly, and made-to-order stations. Full-Service Restaurants capture margin-rich occasions while Fast Casual segments attract weekday traffic from time-constrained business professionals. Catering Services occupy institutional channels including corporate campuses and event venues, though Cafés compete aggressively for morning commuter spending through beverage-led daypart strategies.
ANVISA enforces sanitary surveillance standards that dictate food handler certification, facility inspection frequencies, and traceability documentation across all licensed establishments. The country's national labor regulator mandates consolidated overtime calculations and social contribution schedules that directly shape staffing models and operating hour decisions. Municipal health surveillance agencies in Rio de Janeiro and Belo Horizonte layer additional permitting requirements onto federal baselines. Stakeholders must monitor how pending tax reform discussions around service sector levies could alter franchise royalty structures and location profitability thresholds.
Market Dynamics
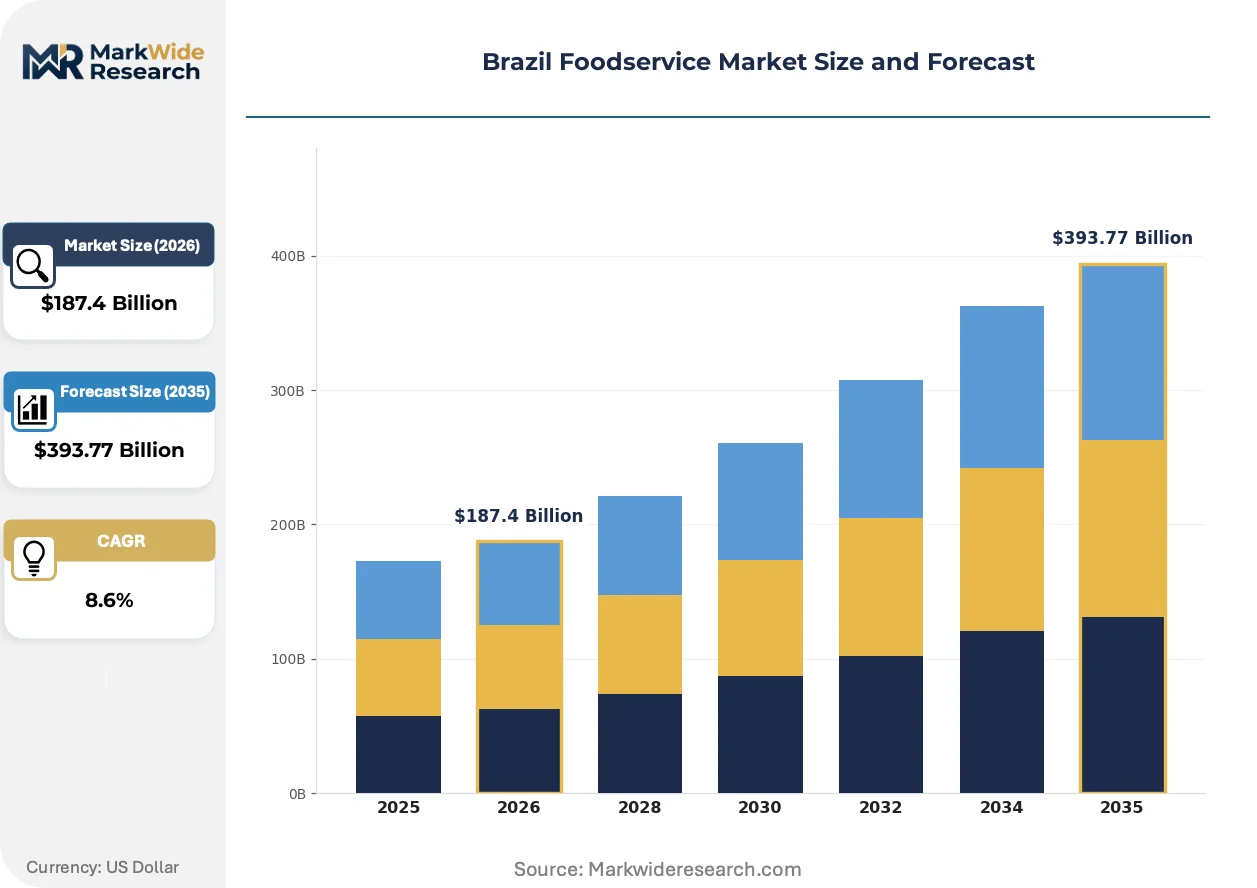
Labor scarcity in Brazil's metropolitan kitchens is forcing automation investment and workflow redesign across quick-service and full-service formats, compressing operating margins while elevating capital intensity for equipment upgrades.
Growth Catalysts
- ANVISA Sanitary Modernization:Updated food safety protocols mandate cold-chain traceability systems, driving equipment replacement cycles and certified supplier consolidation among protein distributors.
- São Paulo Premium Corridor:Concentrated high-income households sustain demand for experiential dining concepts, anchoring expansion capital toward Brazilian cuisine and churrascaria formats.
- Cloud Kitchen Infrastructure:Delivery-optimized ghost kitchens reduce real estate costs for emerging brands, enabling rapid market testing without traditional storefront investment.
Market Restraints
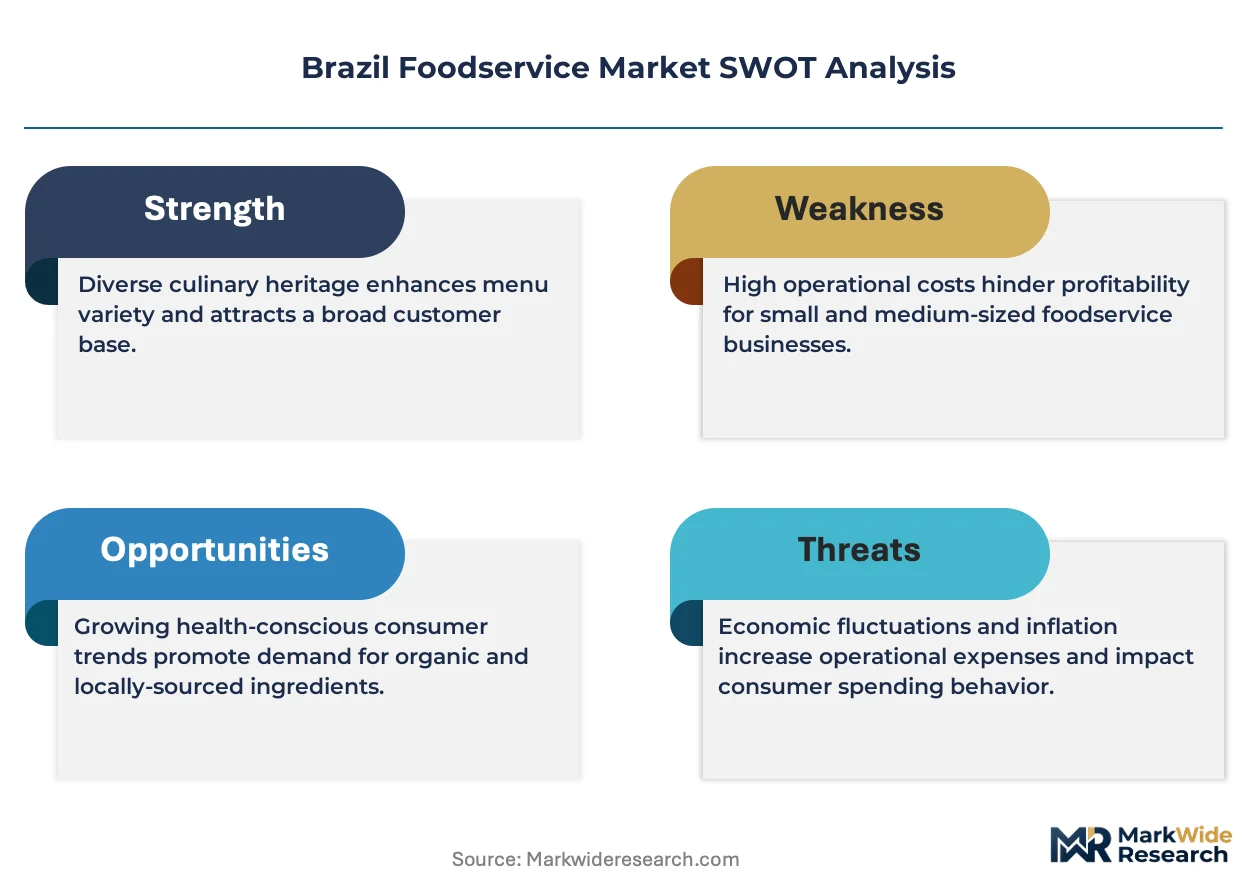
- Beef Price Volatility:Input cost swings for Brazil's signature protein strain margin predictability, particularly for steakhouse and churrascaria operators locked into fixed-menu pricing.
- Short-Order Cook Scarcity:Trained kitchen labor availability constrains unit expansion velocity, forcing chains to limit operating hours or delay new location openings.
- Municipal Permitting Layering:Rio de Janeiro and Belo Horizonte health surveillance agencies impose supplemental inspection regimes atop federal ANVISA baselines, extending pre-opening timelines.
Strategic Opportunities
- Northeast Urban Expansion:Salvador and Recife metropolitan areas show underpenetrated full-service density relative to per-capita income growth, offering first-mover positioning for premium casual entrants.
- Plant-Based Menu Integration:ANVISA's novel food ingredient approval pathway enables regulated introduction of alternative proteins, creating differentiation vectors for health-positioned chains.
- Corporate Catering Channels:Institutional meal contracts for São Paulo financial district campuses remain fragmented, presenting consolidation potential for operators with HACCP-certified central kitchens.
Industry Challenges
- Gaucho-Trained Service Pipeline:Specialized churrascaria staffing requires months of rotational training, creating bottlenecked expansion capacity for authentic format replication.
- Franchisee Capital Access:Brazilian credit conditions and collateral requirements limit qualified franchise operator pool, constraining brand growth through proven unit economics.
- Tax Reform Uncertainty:Pending federal discussions on service sector levy restructuring create location profitability ambiguity, freezing some development commitments until legislative clarity emerges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Foodservice Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $393.77 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Fast Casual, Cafés, Catering Services Customer Type: Families, Young Adults, Business Professionals, Tourists Food Type: Italian, Brazilian, Asian, Vegetarian Dining Experience: Casual Dining, Fine Dining, Buffet, Food Trucks |
| Companies Covered | Grupo Madero, Yum! Brands, Inc., Arcos Dorados Holdings Inc., Giraffas, Habib's S.A., McDonald's Brasil, Restaurant Brands International Inc., Fogo de Chão, ZAMP, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Foodservice Market Strategic Shifts
Digital ordering infrastructure and back-of-house automation are compressing traditional labor models while regulatory pressure on food safety documentation accelerates technology adoption across format types.
Automated prep stations with integrated portion control and inventory tracking are bifurcating kitchen operations between high-touch service roles and capital-intensive equipment management. Quick-service chains in São Paulo and Rio de Janeiro deploy these systems fastest, attracted by wage cost containment and ANVISA-compliant batch consistency. The technology is bifurcating competitive position between operators who can amortize equipment costs across multi-unit networks and smaller independents facing stranded asset risk.
ANVISA's 2023 updated sanitary surveillance standards mandate digital traceability documentation for temperature-controlled proteins, requiring cloud-connected cold-chain monitoring. Full-service restaurants and institutional caterers face the steepest compliance retrofit costs, driving consolidation toward suppliers with integrated documentation platforms. Chains are responding by vertically integrating into certified distribution partnerships or acquiring cold-storage capabilities directly.
Commuter breakfast occasions are rotating toward beverage-led café formats, compressing traditional full-service morning traffic. São Paulo's central business district sees rapid kiosk and grab-and-go density expansion, displacing seated service for time-constrained professionals. This pattern concentrates most visibly among financial services and technology sector employment clusters, where meeting schedules eliminate extended meal windows.
Brazil Foodservice Market Segmentation
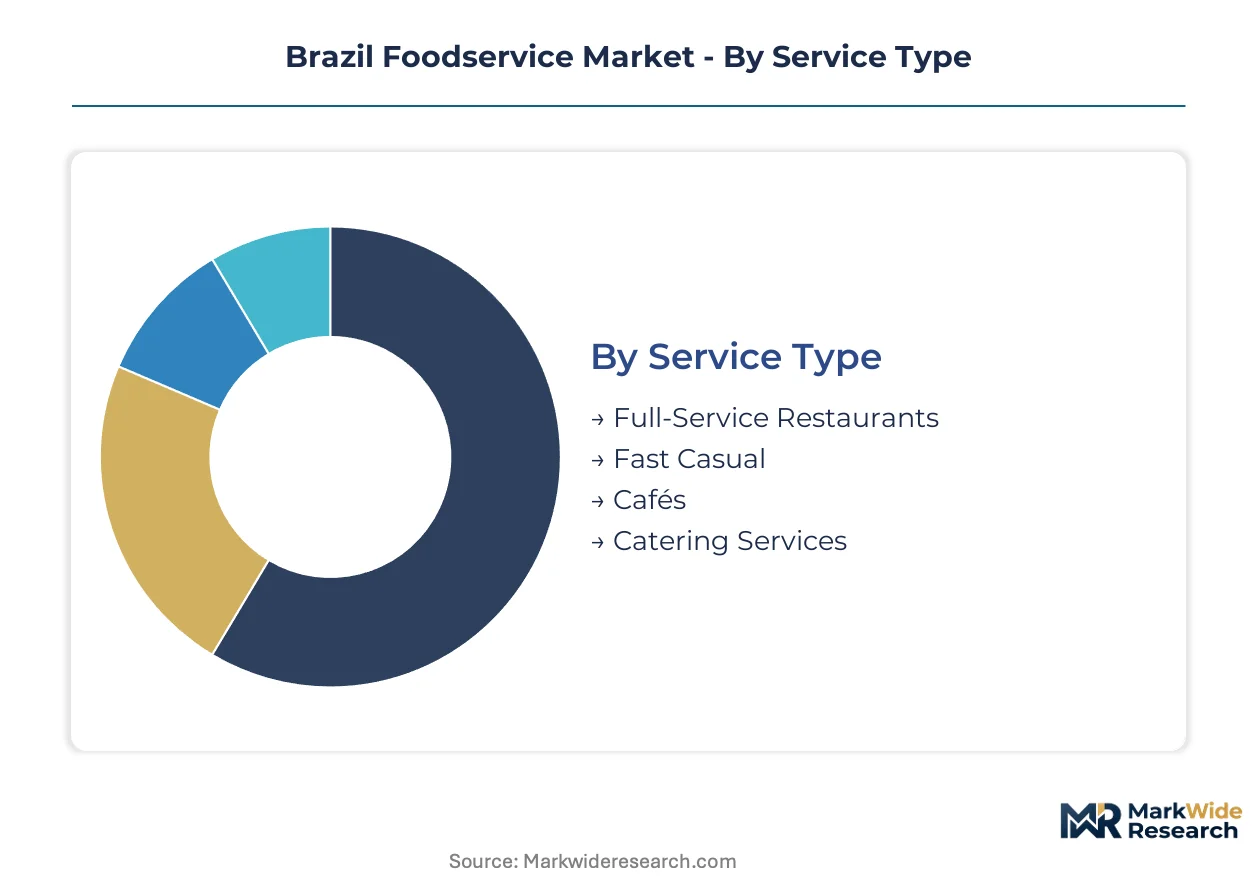
Brazil's foodservice segmentation reflects distinct operational models and capital intensity requirements. Format selection dictates real estate footprints, labor structures, and regulatory compliance burdens across metropolitan corridors.
Service Type:
Channel-mix dynamics determine which formats capture occasion-based spending versus habitual traffic across São Paulo and Rio de Janeiro.
- Full-Service Restaurants:Table-service operations with dedicated floor staff and kitchen brigades. São Paulo's premium corridor sustains experiential dining demand for Brazilian cuisine and churrascaria concepts, though gaucho-trained service pipelines constrain authentic format replication.
- Fast Casual:Counter-service formats with elevated ingredient positioning and limited table service. Business professionals in financial district clusters drive weekday lunch velocity, compressing traditional full-service capture during compressed meal windows.
- Cafés:Beverage-led daypart operations with grab-and-go food attachments. Morning commuter traffic concentrates in São Paulo CBD kiosks, displacing seated breakfast occasions.
- Catering Services:Institutional meal contracts requiring HACCP-certified central kitchens. Corporate campuses and event venues demand batch consistency with ANVISA traceability documentation.
By volume, Full-Service Restaurants lead. By growth pace, Fast Casual is climbing the fastest.
Customer Type:
Spending patterns vary sharply by demographic, with occasion frequency and check average diverging across family units versus individual professionals.
- Families:Multi-generational dining occasions favoring buffet and casual formats with portion flexibility. Weekend traffic concentrates in shopping mall food courts and churrascaria destinations.
- Young Adults:Digital-native consumers driving delivery-optimized ghost kitchen adoption and social-media-responsive menu innovation. Price sensitivity elevates fast casual and food truck trial rates.
- Business Professionals:Time-constrained weekday demand for speed and consistency. São Paulo's financial district sees premium casual penetration during lunch dayparts.
- Tourists:Experience-seeking visitors prioritizing authentic Brazilian cuisine and churrascaria theater. Seasonal concentration strains Rio de Janeiro and Salvador service capacity.
Business Professionals generate highest per-capita spend. Young Adults are expanding most quickly as a share of traffic.
Food Type:
Menu positioning determines supply chain complexity and ANVISA compliance pathways for ingredient sourcing.
- Italian:Pasta and pizza formats with standardized preparation protocols. São Paulo's Italian-heritage neighborhoods sustain family-owned trattoria density alongside chain expansion.
- Brazilian:Indigenous ingredient portfolios including açaí, tapioca, and regional protein preparations. Churrascaria and moqueira specialists command loyalty through authentic technique demonstration.
- Asian:Japanese and Chinese formats with cold-chain intensive seafood requirements. ANVISA's updated traceability mandates elevate compliance costs for raw fish handling.
- Vegetarian:Plant-forward menus leveraging ANVISA's novel food ingredient approval pathway for alternative protein integration. Health-positioned chains differentiate through regulated ingredient introductions.
Brazilian cuisine dominates check averages. Vegetarian options are gaining share fastest among metropolitan millennials.
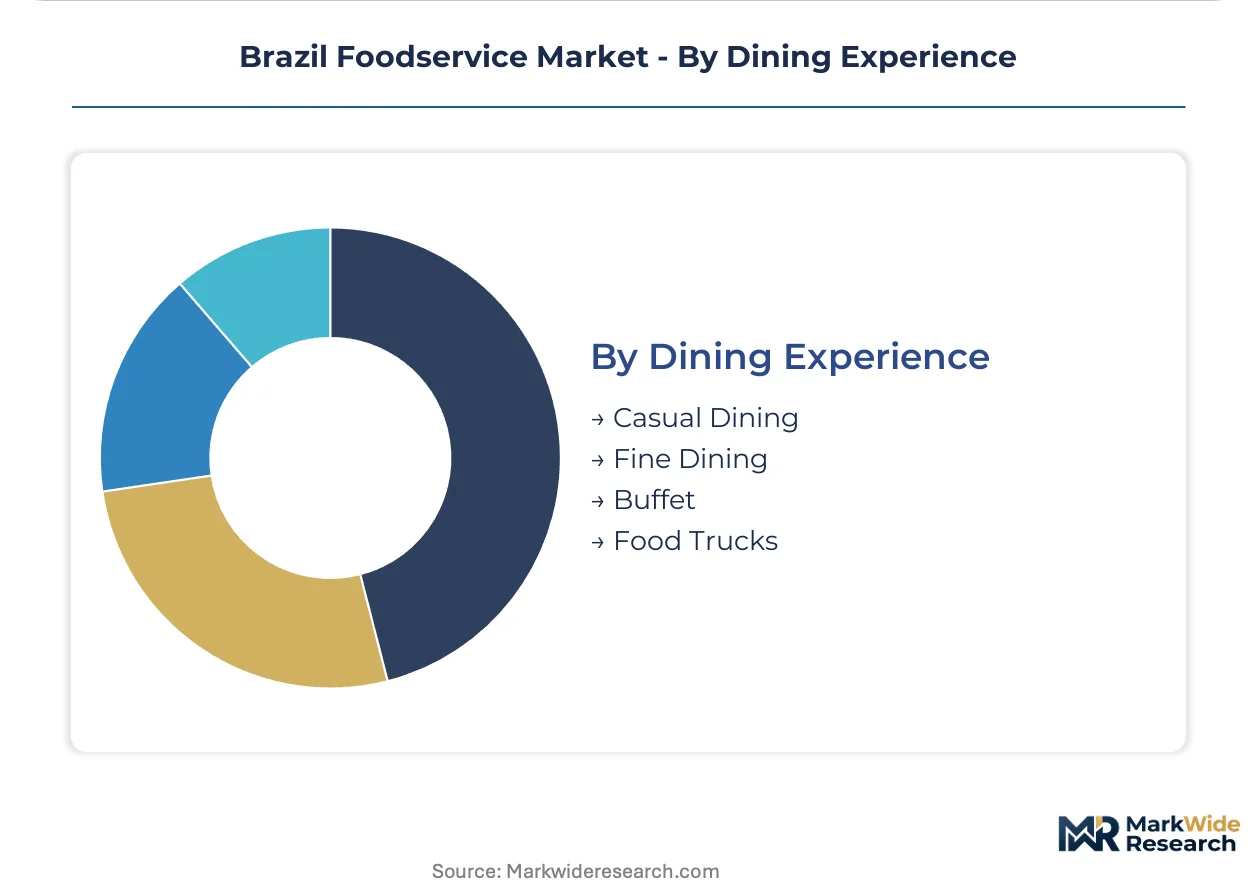
Dining Experience:
Capital deployment and labor models diverge across experience tiers, with real estate costs and table turns determining unit economics.
- Casual Dining:Mid-market table service with standardized menus and moderate price positioning. Suburban São Paulo corridors sustain family-oriented expansion.
- Fine Dining:Chef-driven tasting menus and wine programs with extended service rituals. Limited to high-income pockets in São Paulo and Rio de Janeiro.
- Buffet:Self-service formats with protein-forward Brazilian offerings. Churrascaria rodízio models require specialized carving stations and gaucho-trained floor teams.
- Food Trucks:Mobile operations with lower permitting barriers and flexible location testing. Municipal health surveillance layering in Belo Horizonte and Rio de Janeiro extends compliance timelines.
Casual Dining holds widest geographic footprint. Food Trucks are expanding most quickly as cloud kitchen infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's sanitary surveillance standards anchor Brazil's foodservice regulatory framework, with enforcement intensity varying across metropolitan health surveillance jurisdictions. São Paulo's state-level sanitary agency layers additional inspection protocols atop federal baselines.
São Paulo
High-income household concentration sustains experiential dining demand for churrascaria and Brazilian cuisine concepts. The state's sanitary surveillance agency mandates supplemental facility inspections beyond ANVISA federal requirements. São Paulo's metropolitan corridor anchors premium casual expansion capital, with disciplined unit economics attracting franchise investment.
Rio de Janeiro
Tourism-driven seasonal traffic strains service capacity for authentic Brazilian format operators. Municipal health surveillance layering extends pre-opening timelines through supplemental permitting regimes. The city's South Zone concentrates fine dining and beachfront casual concepts, while suburban corridors sustain family-oriented buffet formats.
Minas Gerais
Belo Horizonte's metropolitan health surveillance agency imposes inspection frequencies that compress new location velocity. Traditional mineiro cuisine specialists leverage regional ingredient sourcing for differentiation. The state's interior cities show underpenetrated fast casual density relative to per-capita income trajectories.
Rio Grande do Sul
Gaucho-trained service team pipelines originate here, creating specialized labor supply for churrascaria format replication. State-level vocational programs feed rotational training capacity into national expansion networks. Porto Alegre's metropolitan area sustains steakhouse concept incubation before national rollout.
Bahia
Salvador's metropolitan corridor shows underpenetrated full-service restaurant density relative to income growth curves. Regional seafood supply chains require ANVISA-compliant cold-chain documentation for distributor certification. Northeast urban expansion attracts first-mover positioning from premium casual entrants seeking early market share establishment.
Brazil Foodservice Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with franchise-heavy quick-service networks dominating volume and experiential full-service operators capturing margin-rich occasions. The structure bifurcates between capital-intensive multi-unit platforms and single-concept specialists. Two strategic archetypes define competitive positioning: integrated franchise systems with captive supply chains, and experiential format specialists with proprietary service rituals. Dominant competitive moves include backward integration into certified distribution partnerships and geographic expansion through ghost kitchen infrastructure.
Within the integrated franchise tier, Arcos Dorados Holdings Inc. and McDonald's Brasil exemplify capital-intensive multi-unit platforms with standardized operational protocols. Grupo Madero anchors the premium casual segment through disciplined steakhouse unit economics. Fogo de Chão occupies a specialized position within experiential churrascaria formats, with gaucho-trained service teams representing a differentiated labor model that constrains rapid replication. These three companies collectively illustrate the competitive spectrum from volume-driven quick-service scale to margin-focused experiential positioning.
| Leading Market Players |
|---|
| Grupo Madero |
| Yum! Brands, Inc. |
| Arcos Dorados Holdings Inc. |
| Giraffas |
| Habib's S.A. |
| McDonald's Brasil |
| Restaurant Brands International Inc. |
| Fogo de Chão |
| ZAMP |
| Others |
Value Chain & Pricing Dynamics
Multi-unit network scale in Brazil's foodservice sector compresses per-unit procurement costs while elevating price floors for independent operators lacking volume leverage. ANVISA-mandated cold-chain compliance and gaucho-trained labor scarcity concentrate negotiating power among integrated chains with captive distribution partnerships.
Pricing Analysis
São Paulo's premium corridor commands 15-25% menu premiums over Belo Horizonte and Salvador for identical churrascaria formats. Three-tier pricing structure across experiential, casual, and quick-service levels differentiates check averages by service intensity and protein grade. Cost compression in mid-market steakhouse tiers is intensifying because beef price volatility strains fixed-menu commitments. Young adult delivery customers exhibit highest price sensitivity, while business professionals in financial districts show lowest elasticity for weekday lunch occasions.
Supply Chain Analysis
Perishable protein inventory cycles of 48-72 hours dominate cold-chain logistics, compressing lead-time tolerance for temperature-controlled distribution. Brazil's domestic beef and poultry production anchors protein supply, with specialized gaucho labor pools concentrated in Rio Grande do Sul. Supply chain risk centers on single-source vulnerability for certified ANVISA-compliant distributors serving multi-unit chains. Distribution runs through vertically integrated cold-storage networks or third-party logistics partnerships with traceability documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's foodservice market rewards service-attach revenue models, with ghost kitchen infrastructure and corporate catering contracts expanding faster than traditional storefront development. Recurring institutional meal agreements and delivery platform optimization layers outpace capital-intensive full-service unit economics.
For Market Incumbents: Compound defensive positioning through backward integration into ANVISA-certified protein distribution, locking in supply security against beef price volatility. Acquire cold-storage capabilities in São Paulo's metropolitan corridor to capture margin from traceability-mandated supplier consolidation. Channel control through exclusive ghost kitchen infrastructure partnerships limits emerging brand market testing velocity.
For New Entrants and Emerging Players: Lead with cloud kitchen deployment in Salvador and Recife's underpenetrated corridors, avoiding capital-heavy storefront requirements. Target corporate catering channels in São Paulo's financial district, where fragmented institutional contracts favor HACCP-certified central kitchen operators. Go-to-market positioning should emphasize plant-based menu differentiation through ANVISA's novel ingredient approval pathway.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with integrated digital ordering infrastructure and automated prep station deployment. Long-term viability over the next decade hinges on labor substitution capabilities and multi-unit scalability rather than single-location experiential concepts. Acquisition target archetype: fast casual chains with proven unit economics in secondary metropolitan markets. Signal to watch: municipal permitting streamlining in Rio de Janeiro and Belo Horizonte that accelerates new location velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Ghost Kitchen Infrastructure Expansion | Reduces real estate costs for emerging brands testing Salvador and Recife markets. |
| ANVISA-Certified Cold-Chain Integration | Captures margin from traceability-mandated supplier consolidation toward integrated distributors. |
| Corporate Catering Channel Development | Secures recurring revenue from fragmented São Paulo financial district institutional contracts. |
| Automated Prep Station Deployment | Substitutes scarce short-order cook labor with capital equipment across multi-unit networks. |
| Plant-Based Menu Certification | Differentiates health-positioned chains through ANVISA's novel ingredient approval pathway. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with restaurant chain executives, ANVISA regulatory affairs specialists, foodservice equipment distributors, and ghost kitchen operators; and secondary validation through ANVISA sanitary surveillance filings, municipal health agency permitting databases, beef futures pricing data, and foodservice trade association membership records. Bottom-up location-level unit economics triangulated against top-down metropolitan corridor spending estimates.
Across the projection horizon, the analytical framework modeled segmentation dimensions including service type, customer demographic, cuisine category, and dining experience tier. CAGRs derived from historical location expansion velocity, per-capita foodservice spending elasticity, and regulatory compliance cost trajectories. Industry-specific forecast inputs incorporated gaucho-trained labor pipeline constraints and cloud kitchen infrastructure penetration curves.
The analysis sits within stated boundaries; outcomes outside ANVISA regulatory stability, beef commodity price bands, or municipal permitting timelines would require recalibration. Forecasts reflect documented assumptions about labor substitution technology adoption and delivery platform commission structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Cafes & Bars Market
Food Service
Thailand Food Service Market
Food Service
China Inflight Catering Market
Food Service
Middle East Smokeless Indoor Grills Market
Food Service
Australia Foodservice Market
Food Service
Beverage Napkins Market
Food Service
Fast Food Market
Food Service
Smokeless Grill Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
Latin America Online Grocery Delivery Market
Food Service
United States Foodservice Market
Food Service
Global Vending Machine Market
Food Service
International Food Subscription Box Service Market
Food Service
Full-Service Restaurants Market
Food Service
China Food Service Market
Food Service
Global Online Food Delivery Services Market