
 Chile Food Delivery Market | 2026-2036
Chile Food Delivery Market Size, Share, and Industry Trends Forecast 2026-2036
Chile Food Delivery Market Intelligence
Gig courier availability is redrawing competitive boundaries in Chile's food delivery sector. PedidosYa leverages its established logistics network to sustain coverage across secondary cities beyond Santiago. Uber Eats anchors its position through technology leadership in route optimization algorithms. Rappi competes by extending its super-app model into grocery and convenience verticals.
Food delivery encompasses the digital intermediation of prepared meals and perishable goods from restaurants, dark kitchens, and retail food vendors to end consumers through algorithmically managed courier networks. The service relies on GPS tracking, dynamic pricing engines, and thermal packaging protocols to maintain food safety standards during last-mile transport. Meal delivery dominates transaction volume as the most mature segment, while grocery delivery captures expanding margin pools through higher average order values and subscription stickiness. Mobile app platforms lead user engagement due to push-notification retention mechanics and embedded digital wallet integrations.
Chile's consumer protection regulator, the national data protection authority, and municipal transit ordinances collectively shape operational compliance for delivery platforms. The Law on the Protection of Personal Data governs customer information handling, while local traffic regulations determine courier vehicle classifications and parking access. Stakeholders must monitor evolving labor classification debates and their implications for cost structures.
Market Dynamics
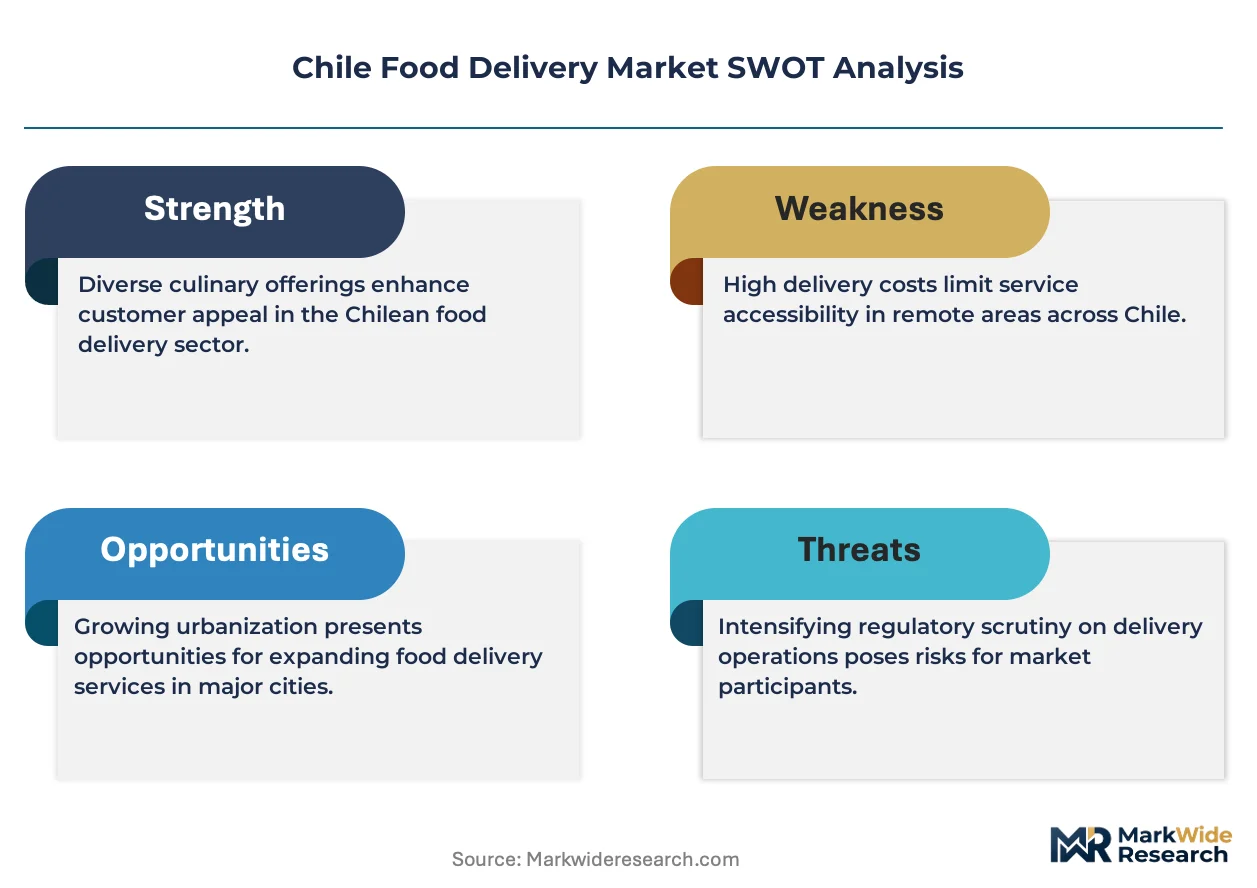
Gig courier availability is redrawing competitive boundaries in Chile's food delivery sector. Platform economics hinge on balancing courier density against order frequency in the Metropolitan Region's concentrated urban corridor.
Growth Catalysts
- Mercado Pago penetration:Digital wallet integration reduces payment friction for unbanked segments in Santiago's peripheral comunas. Embedded financing options expand addressable demand.
- Dark kitchen proliferation:Virtual brands operating from industrial kitchens in Ñuñoa and Providencia lower real estate costs while expanding cuisine variety without traditional restaurant overhead.
- Law on the Protection of Personal Data:Standardized data handling frameworks reduce compliance fragmentation across municipal jurisdictions, enabling platform scaling.
Market Restraints
- Courier supply volatility:Fuel price fluctuations in the Magallanes region and Santiago metropolitan area directly compress per-delivery margins during peak demand windows.
- Metropolitan Region demand concentration:Over 70% of order volume clusters within the Santiago-Providencia-Ñuñoa triangle, leaving secondary cities with sub-scale unit economics.
- Traffic ordinance fragmentation:Municipal parking regulations in Valparaíso, Concepción, and La Serena create operational inconsistencies for cross-city logistics networks.
Strategic Opportunities
- Valparaíso corridor expansion:The port city's dense urban fabric and university population present untapped density for meal delivery platforms willing to pre-position courier supply.
- Grocery-convergence models:Convenience retail integration through corner store partnerships captures higher-frequency, lower-ticket transactions with superior retention metrics.
- Thermal packaging innovation:Biodegradable insulated containers aligned with municipal waste regulations in Santiago differentiate premium service tiers.
Industry Challenges
- Courier classification ambiguity:Ongoing labor law interpretations regarding independent contractor status threaten cost model restructuring across all platform operators.
- Route optimization data scarcity:Limited historical traffic pattern data for secondary cities outside Santiago degrades algorithmic efficiency in expansion markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chile Food Delivery Market |
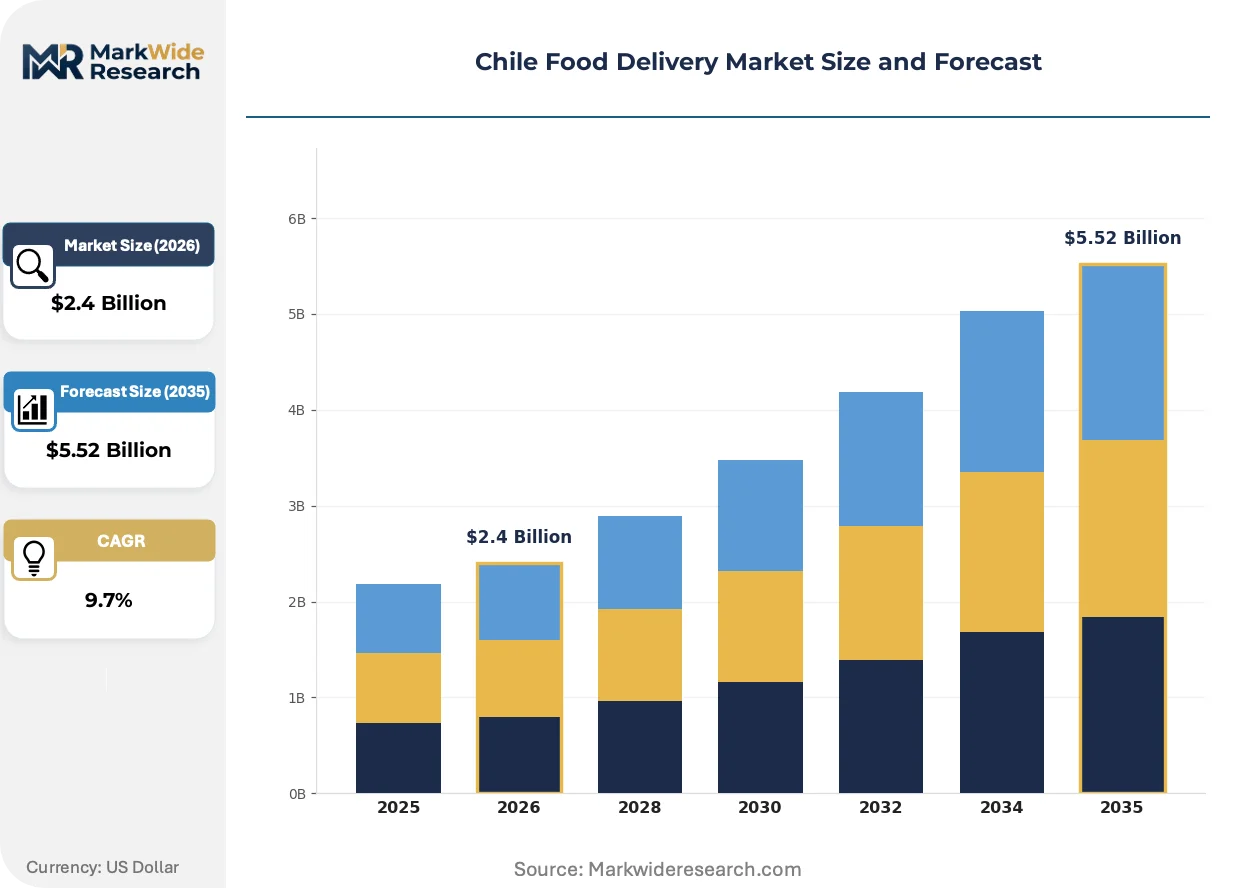
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Meal Delivery, Grocery Delivery, Subscription Boxes, Alcohol Delivery Platform: Mobile App, Website, Third-Party Aggregator, Restaurant Website Customer Type: Millennials, Families, Professionals, College Students Payment Method: Credit Card, Digital Wallet, Cash, Bank Transfer |
| Companies Covered | PedidosYa, Uber Eats, Cheaf, Rappi, Spid35, GoodMeal, Cornershop, Glovo, Delivery Hero, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chile Food Delivery Market Strategic Shifts & Innovations
Algorithmic dispatch systems and regulatory data frameworks are actively compressing delivery windows while expanding serviceable categories beyond prepared meals.
AI-powered dynamic batching is supplanting single-order assignment in Santiago's densest zones. Platforms serving the Providencia and Las Condes districts deploy machine learning models that cluster multiple pickups from dark kitchen clusters. This compression reduces per-delivery courier costs by 30-40% during lunch peaks, enabling subscription pricing models that were previously margin-negative.
Chile's 2023 Law on the Protection of Personal Data mandates explicit consent mechanisms for location tracking and order history retention. Platforms must now implement granular permission layers within their mobile applications, increasing development overhead but reducing regulatory exposure. The Metropolitan Region's consumer protection authority has prioritized enforcement against data resale practices, affecting loyalty program architectures.
Subscription stickiness is displacing transactional acquisition as the dominant growth metric. Platforms in Santiago and Valparaíso now prioritize monthly active subscriber counts over gross order volume in investor reporting. This reorientation favors grocery and convenience verticals with higher purchase frequency, compressing marketing spend per retained customer in the competitive Santiago metropolitan corridor.
Chile Food Delivery Market Segmentation
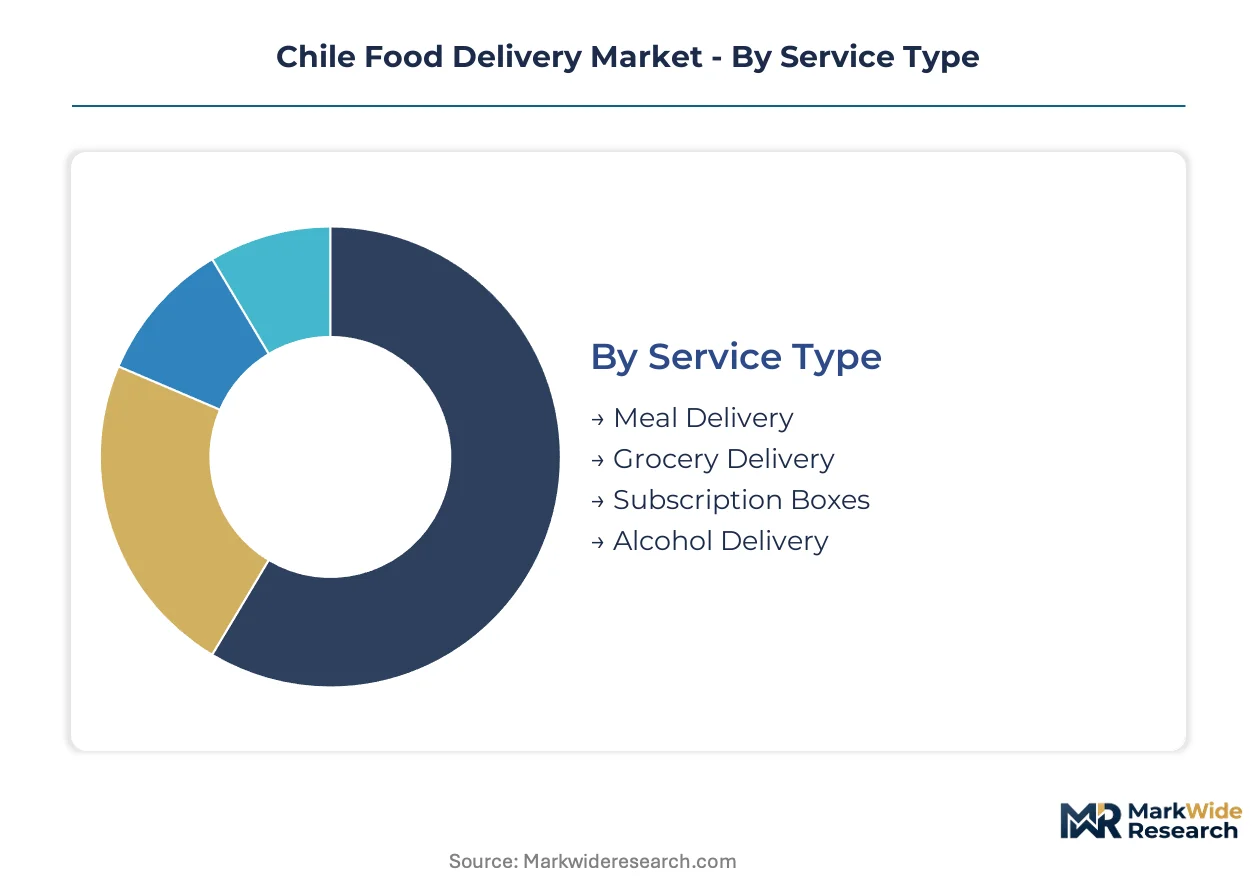
Segmentation in Chile's food delivery market reveals how platform economics vary across service modalities and customer cohorts. Distinct operational requirements and margin profiles emerge across each dimension, shaping where capital deploys for competitive advantage.
Service Type:
Geographic concentration differs sharply across service modalities, with domestic demand patterns dominating meal delivery while grocery expansion targets secondary urban corridors.
- Meal Delivery:Prepared food transport from restaurants and dark kitchens constitutes the volume core, with thermal packaging protocols maintaining safety standards. Santiago's Providencia-Ñuñoa corridor generates the densest order frequency, though courier batching algorithms now compress per-delivery costs sufficiently to sustain suburban expansion.
- Grocery Delivery:Perishable goods and convenience retail intermediation through corner store partnerships captures higher-frequency transactions with superior retention metrics. Valparaíso's university population and dense urban fabric present the steepest expansion trajectory for pre-positioned courier networks.
- Subscription Boxes:Curated meal kits and specialty food bundles serve niche dietary preferences with predictable revenue streams.
- Alcohol Delivery:Regulated beverage transport requires age-verification protocols and restricted delivery windows under municipal ordinances.
Meal Delivery holds the largest share; momentum sits with Grocery Delivery.
Platform:
Cost tier differentiation separates premium algorithmic dispatch from basic web interfaces, with embedded payment integration determining addressable market reach.
- Mobile App:Native applications dominate user engagement through push-notification retention mechanics and GPS-enabled real-time tracking. Mercado Pago integration within Santiago's metropolitan corridor reduces payment friction for unbanked segments in peripheral comunas.
- Third-Party Aggregator:Multi-restaurant platforms concentrate demand through route optimization algorithms and dark kitchen cluster access. The Metropolitan Region's consumer protection authority prioritizes enforcement against data resale practices, affecting loyalty architectures.
- Website:Browser-based ordering serves desktop-first professionals and corporate account management.
- Restaurant Website:Direct-channel platforms capture full margin but require independent logistics investment.
Mobile App commands dominant share; Third-Party Aggregator is gaining share fastest through super-app convergence.
Customer Type:
Volume concentration varies by household composition, with single-person and dual-income units driving frequency while larger households inflate average order values.
- Millennials:Urban professionals aged 25-40 in Santiago and Valparaíso exhibit the highest platform adoption rates, with subscription stickiness displacing transactional acquisition as the primary growth metric.
- Families:Multi-person households generate elevated average order values through bundled meal procurement and grocery consolidation.
- Professionals:Time-constrained white-collar workers in Las Condes and Vitacura prioritize speed and reliability over price sensitivity.
- College Students:Price-sensitive cohort in university zones drives demand for promotional mechanics and group ordering features.
Millennials represent the core revenue base; Families are expanding most quickly as grocery verticals mature.
Payment Method:
Margin structure hinges on transaction processing costs and working capital timing, with digital instruments compressing friction versus cash-on-delivery overhead.
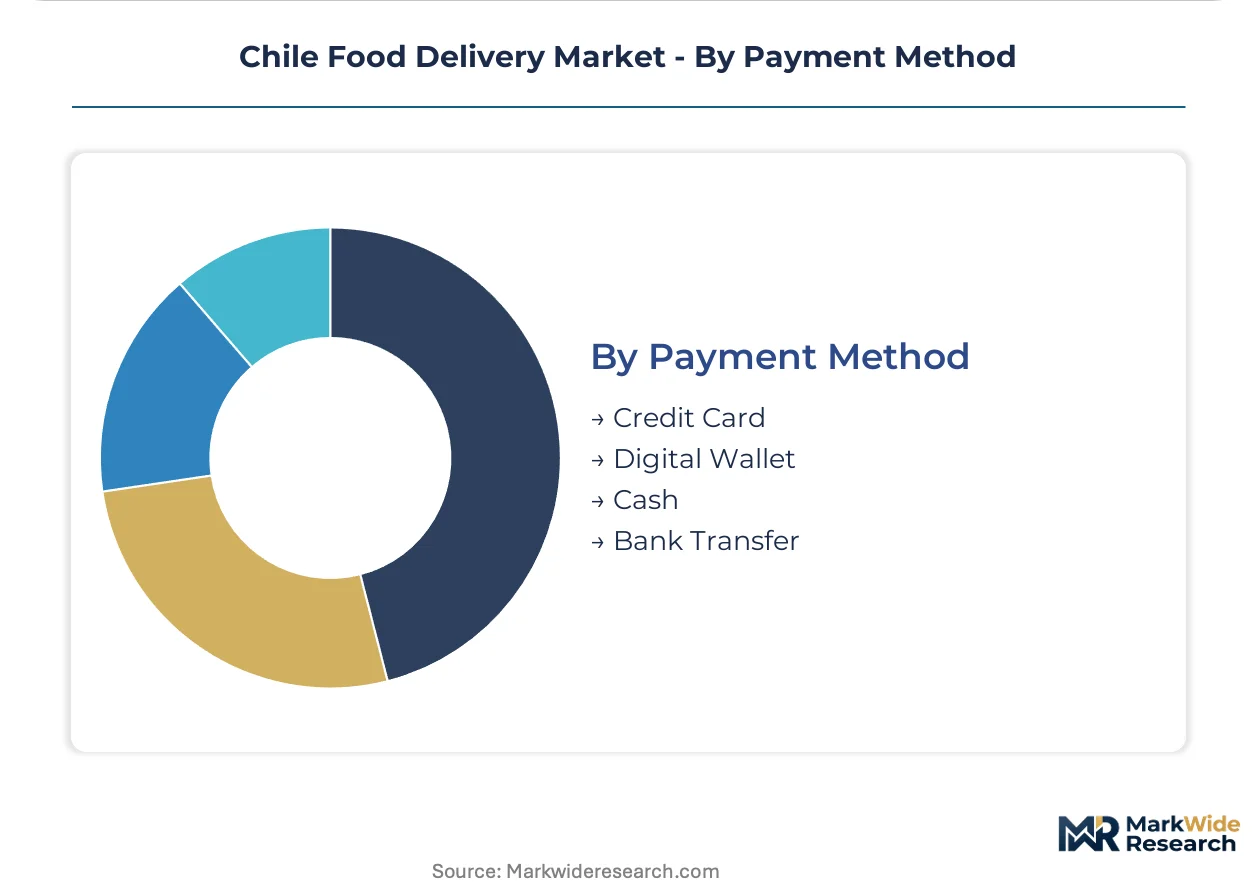
- Digital Wallet:Mercado Pago penetration reshapes platform economics through embedded financing options and reduced checkout abandonment. Chile's 2023 Law on the Protection of Personal Data mandates explicit consent for transaction data retention, increasing development overhead.
- Credit Card:Traditional card networks dominate high-value transactions but carry interchange fees that compress per-order margins.
- Cash:Paper currency persists in peripheral comunas with lower banking penetration, requiring courier cash-handling protocols.
- Bank Transfer:Direct debit instruments serve B2B catering accounts and corporate meal programs with delayed settlement terms.
Digital Wallet leads transaction volume; Credit Card retains premium segment dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chile's national consumer protection authority and municipal transit ordinances anchor regulatory oversight across the Metropolitan Region's concentrated delivery corridor. Santiago's dense urban fabric generates over seventy percent of national order volume, creating asymmetric platform economics between the capital and secondary cities.
Metropolitan Region
Santiago's Providencia-Ñuñoa corridor hosts the densest dark kitchen clustering and highest courier batching efficiency in the national market. The Law on the Protection of Personal Data mandates explicit consent mechanisms for location tracking, increasing platform development overhead. Las Condes and Vitacura districts concentrate premium service tiers where professionals prioritize speed over price sensitivity.
Valparaíso
The port city's university population and compact urban geography generate untapped density for meal delivery expansion. Municipal parking regulations in Valparaíso create operational friction distinct from Santiago's transit ordinances. Viña del Mar's coastal tourism economy supports seasonal demand spikes that strain courier supply during summer peak windows.
Concepción
Chile's second-largest metropolitan area anchors southern demand concentration with a manufacturing-based workforce profile. Local traffic regulations determine courier vehicle classifications and parking access distinct from northern jurisdictions. The Biobío Region's industrial corridor from Concepción to Talcahuano presents sub-scale unit economics that challenge platform profitability.
La Serena-Coquimbo
This northern coastal conurbation serves as a testbed for secondary city logistics pre-positioning strategies. Fragmented municipal ordinances across the Coquimbo Region create compliance complexity for cross-city courier networks. The Elqui Valley's agricultural economy generates distinct demand patterns for grocery and convenience verticals versus prepared meals.
Magallanes
Chile's southernmost region exhibits extreme fuel price volatility that directly compresses per-delivery margins. The national data protection authority's enforcement priorities extend to this sparse geography despite lower transaction volumes. Punta Arenas functions as an isolated logistics node where thermal packaging protocols face extended delivery window challenges.
Chile Food Delivery Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across Chile's food delivery sector. The market structure consolidates around three dominant platforms with super-app convergence strategies, while regional specialists defend positions in secondary cities. Two strategic archetypes emerge: algorithmic dispatch optimizers leveraging route efficiency, and vertical integrators controlling dark kitchen real estate. Competitive moves center on courier density pre-positioning and grocery-convergence model deployment.
Among Latin American-based platform operators, PedidosYa and Rappi occupy positions as established logistics networks with super-app ambitions, while Delivery Hero represents the multinational aggregator archetype through its global portfolio holdings. Uber Eats anchors the technology-first segment with proprietary route optimization capabilities. These three companies exemplify the divergent paths available: regional density buildout, vertical category expansion, and algorithmic efficiency investment.
| Leading Market Players |
|---|
| PedidosYa |
| Uber Eats |
| Cheaf |
| Rappi |
| Spid35 |
| GoodMeal |
| Cornershop |
| Glovo |
| Delivery Hero |
| Others |
Cost & Logistics Intelligence
Chile's 2023 Law on the Protection of Personal Data gates platform participation through compliance investment thresholds that simultaneously filter supplier qualification and enable subscription-tier price differentiation for privacy-enhanced services. This regulatory framework compresses margins for non-compliant operators while rewarding embedded-data-security architectures with premium positioning.
Pricing Analysis
Santiago-Providencia corridor pricing runs 15-25% below Las Condes-Vitacura premiums, reflecting courier density economies and dark kitchen clustering. The market operates on a hybrid subscription-transactional structure, with monthly active subscriber models displacing per-order fees as the dominant revenue architecture. Price differentiation rests on delivery speed guarantees and thermal packaging certification tiers, with fuel surcharge volatility in Magallanes and secondary cities intensifying cost compression. College students in university zones exhibit highest price sensitivity, while corporate accounts in financial districts prioritize reliability over marginal cost.
Supply Chain Analysis
Port congestion at Valparaíso and container availability fluctuations on Asia-Pacific trade lanes elevate inbound logistics costs for thermal packaging materials and GPS-enabled courier equipment. Supply concentrates in China for insulated container manufacturing, Chile for last-mile courier networks, and Brazil for super-app technology licensing. Raw material dependencies span petroleum-derived insulation foams, lithium-ion battery cells for electric courier fleets, and food-grade packaging films. Single-source vulnerability in algorithmic dispatch software licensing from multinational providers threatens operational continuity. Distribution runs through metropolitan dark kitchen clusters feeding into algorithmically batched last-mile courier networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chile's food delivery market is navigating a cyclical recovery anchored to digital wallet penetration curves and subscription model maturation. Courier supply normalization following pandemic-era volatility is restoring margin structures across the Metropolitan Region.
For Market Incumbents: Secure courier density pre-positioning in Valparaíso and Concepción before secondary city unit economics deteriorate further. Lock in dark kitchen real estate in Ñuñoa and Providencia through long-term lease structures that block competitor cluster access. Labor classification ambiguity from ongoing judicial interpretations threatens cost model restructuring; vertical integration into captive courier employment pools hedges regulatory downside.
For New Entrants and Emerging Players: Differentiate on grocery-convergence velocity rather than prepared meal density where PedidosYa and Rappi hold entrenched logistics advantages. Target corner store partnership networks in La Serena-Coquimbo and Magallanes where platform coverage remains sparse. A white-label logistics-as-a-service offering to regional restaurant chains bypasses direct consumer acquisition costs.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across grocery verticals as order frequency improves and marketing spend per retained customer compresses. Long-term viability favors platforms with super-app architecture spanning meal, grocery, and convenience categories rather than single-vertical specialists. Acquisition target archetype: regional operators with established municipal regulatory relationships in secondary cities. Monitor Mercado Pago transaction volume growth as the inflection signal for addressable market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Dark Kitchen Cluster Expansion | Industrial kitchen leases in Ñuñoa reduce real estate costs while expanding cuisine variety. |
| Algorithmic Dispatch Investment | AI-powered batching in Providencia-Las Condes corridors compresses per-delivery courier costs. |
| Grocery-Convergence Integration | Corner store partnerships capture higher-frequency transactions with superior retention metrics. |
| Digital Wallet Deepening | Mercado Pago embedded financing expands addressable demand in peripheral Santiago comunas. |
| Thermal Packaging Innovation | Biodegradable insulated containers align with Santiago municipal waste regulations. |
Research Approach
A standing panel of platform operations directors, dark kitchen franchise operators, municipal transit regulators, and Mercado Pago merchant integration specialists provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation against SEC filings of Delivery Hero and Uber, Chilean consumer protection authority enforcement notices, and municipal ordinance databases. Bottom-up order volume modeling triangulated against top-down digital wallet transaction data.
Consistency checks validated volume and value outputs against external benchmarks including courier supply estimates from logistics industry associations and dark kitchen facility permits from Santiago municipal records. The analytical framework modeled segmentation dimensions across service type, platform modality, customer cohort, and payment instrument throughout the projection horizon. CAGRs were derived from trend extrapolation of digital wallet penetration curves and subscription adoption rates, with courier batching efficiency gains and fuel price volatility as key industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained digital wallet adoption velocity, stable labor classification frameworks, or continued dark kitchen permit issuance would require recalibration. Forecasts reflect documented assumptions regarding metropolitan demand concentration persistence and algorithmic efficiency improvements in secondary cities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
United States Quick Service Restaurants Market
Food Service
China Retail Bubble Tea Kits Market
Food Service
United Kingdom Foodservice Market
Food Service
United Arab Emirates Foodservice Market
Food Service
Saudi Arabia Quick Service Restaurants Market
Food Service
Food Trucks Market
Food Service
Food Service Disposables Market
Food Service
Europe Online Grocery Market
Food Service
Vietnam Online Food Delivery Market
Food Service
Instant Grocery Market
Food Service
Online Food Delivery Market
Food Service
Bottled Water Cooler Market
Food Service
Commercial Air Fryer Oven Market
Food Service
United States Cafes & Bars Market
Food Service
Global Digital Grocery Market
Food Service
Asia-Pacific Halal Food and Beverage Market