
 Japan Foodservice Market | 2026-2036
Japan Foodservice Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Foodservice Market Foresight
Convenience store foodservice channels is narrowing as Seven & I Holdings Co. Ltd deepens its hot meal and fresh bento offerings against traditional quick-service formats. Yoshinoya Holdings Co. Ltd leverages its beef bowl specialization to sustain price-competitive positioning across Japan's commuter rail nodes. Zensho Holdings Co. Ltd anchors the market through Sukiya's extensive domestic footprint and centralized supply chain control.
Japan foodservice encompasses commercial establishments preparing and serving meals for immediate consumption, operating across formats from counter-service counters to full-table dining with standardized HACCP protocols and regional ingredient sourcing requirements. The sector primarily satisfies urban Japan's demand for time-efficient, socially embedded meal occasions outside the home. Full-Service Restaurants retain margin concentration in premium izakaya and kaiseki formats, while Fast Food Chains capture volume leadership through standardized production and extended operating hours. Online Delivery is expanding fastest among distribution channels as platform integration reduces per-order friction for office workers and families.
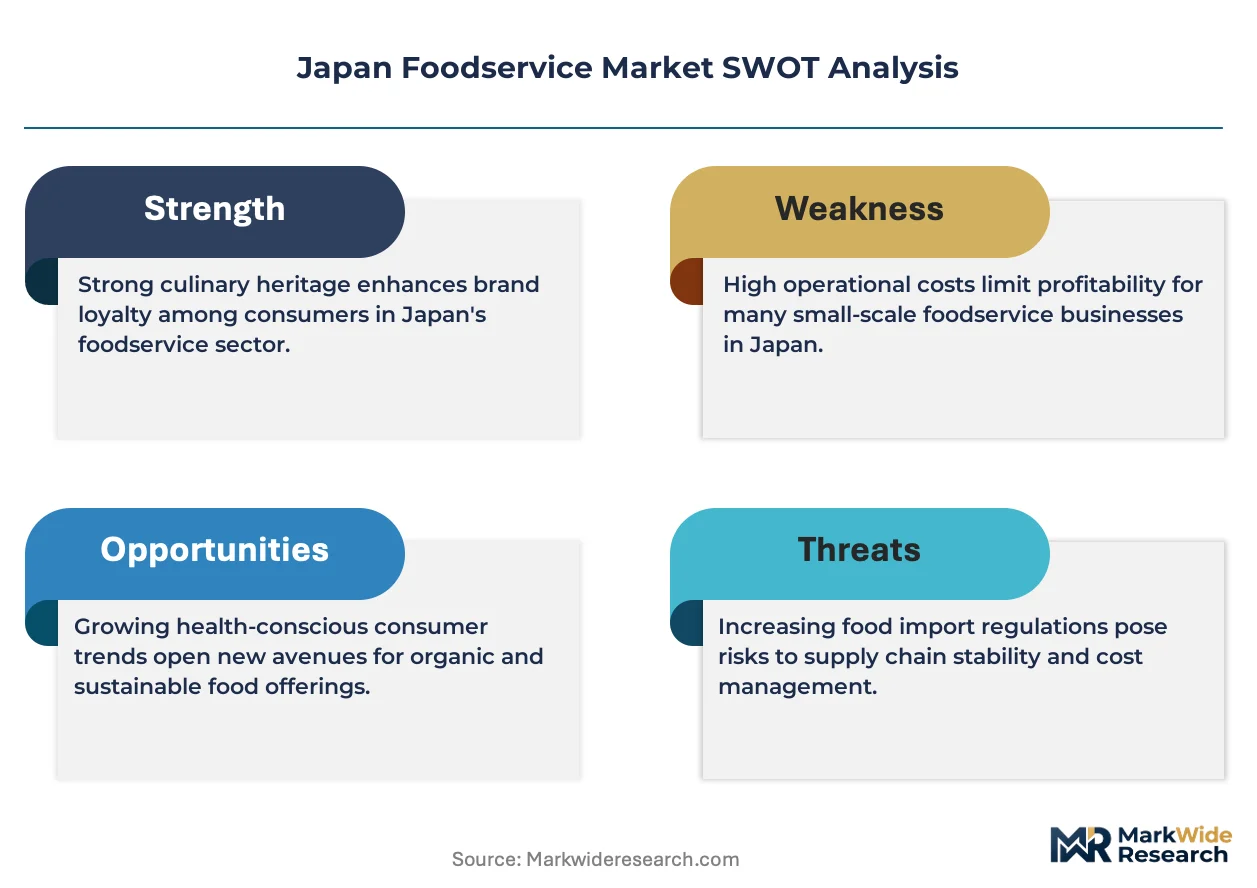
METI's Work Style Reform standards, FSSC 22000 certification requirements, and the Consumer Affairs Agency's food labeling mandates collectively elevate operational compliance costs while advantaging scaled operators with dedicated quality infrastructure. PMDA-aligned food safety audits and prefectural health department inspections further segment market access between enterprise chains and independent establishments. Stakeholders must monitor evolving platform commission structures and labor regulation enforcement as determinants of sustainable unit economics.
Market Dynamics
METI's Work Style Reform directives are compressing traditional lunch-hour peaks and extending evening dining windows, forcing operators to reconfigure labor deployment and kitchen throughput across Japan's urban corridors.
Growth Catalysts
- Platform commission structures:Aggregator fee renegotiations are improving unit economics for franchise operators in Tokyo and Osaka corridors.
- Dual-income household penetration:Time-constrained families are outsourcing meal preparation to convenience-oriented channels with standardized HACCP protocols.
- METI Work Style Reform:Extended operating hour permissions are unlocking revenue capture during previously restricted late-night and early-morning windows.
Market Restraints
- Imported protein input volatility:Beef and pork price fluctuations constrain margin predictability for gyudon and teishoku specialists.
- Prefectural health department fragmentation:Licensing reciprocity gaps between Tokyo, Osaka, and Fukuoka complicate multi-location expansion.
- Ready-to-eat retail substitution:Supermarket deli counters and convenience store hot meals capture price-sensitive commuter traffic.
Strategic Opportunities
- Hokkaido and Tohoku underpenetration:Lower chain density per capita creates whitespace for format adaptation in regional cities.
- FSSC 22000 certification arbitrage:Enterprise-scale quality infrastructure advantages independent operators lacking dedicated compliance staff.
- Ghost kitchen convergence with logistics tech:Dark kitchen real estate and route-optimization algorithms reduce last-mile delivery costs.
Industry Challenges
- Line cook and shift supervisor attrition:Demographic contraction shrinks the available labor pool for back-of-house operations.
- Legacy POS-integration complexity:Platform aggregator APIs frequently conflict with proprietary inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Foodservice Market |
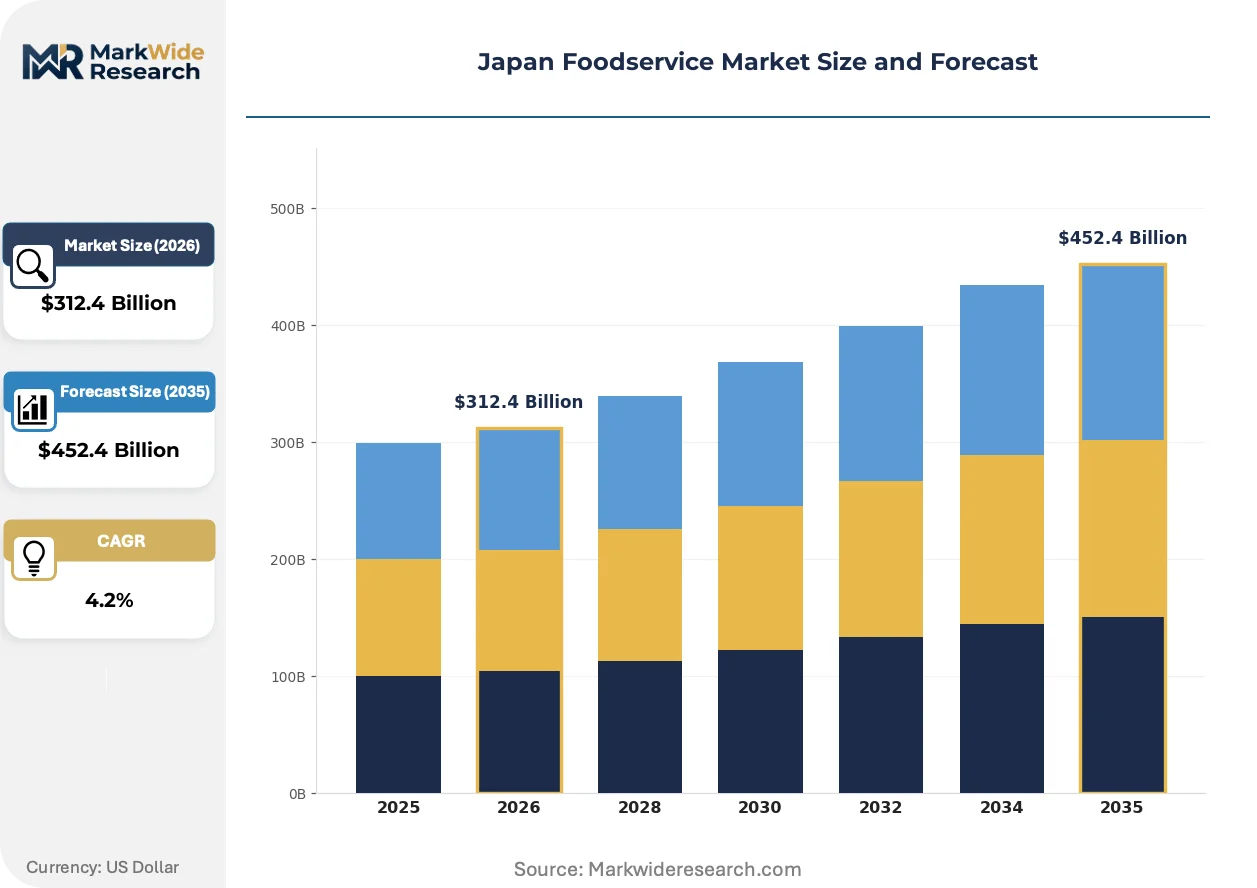
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $452.4 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Full-Service Restaurants, Fast Food Chains, Cafés, Food Trucks Cuisine Type: Japanese, Italian, American, Chinese Distribution Channel: Online Delivery, Dine-In, Takeaway, Drive-Thru Customer Segment: Families, Office Workers, Students, Tourists |
| Companies Covered | Yoshinoya Holdings Co. Ltd, Zensho Holdings Co. Ltd, McDonald's Corporation, Food & Life Companies Ltd, McDonald's Holdings Company (Japan) Ltd, Seven & I Holdings Co. Ltd, Yum! Brands Inc., Colowide Co. Ltd, Skylark Holdings Co. Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Foodservice Market Shifts & Advancements
Automation and regulatory compliance technologies are restructuring operational economics across Japan's foodservice value chain, compressing labor dependency while elevating traceability requirements.
AI-powered demand forecasting systems are rendering obsolete manual inventory planning and static production scheduling. Mid-scale izakaya chains in Tokyo's Shibuya and Shinjuku wards are deploying machine learning models to predict hourly demand fluctuations. This compression of forecast error is rendering obsolete the traditional head chef's intuitive purchasing authority.
METI's FSSC 22000 certification mandate for scaled operators is elevating capital requirements across the sector. Prefectural health departments are aligning inspection protocols with international standards, advantaging chains with dedicated quality infrastructure. Full-service restaurants in Osaka's Umeda district are restructuring supplier relationships to satisfy documentary traceability requirements.
Subscription-based meal plans are displacing transactional ordering among Tokyo office workers. Platform aggregators are bundling recurring lunch deliveries with loyalty incentives, capturing predictable revenue streams. This behavioral pivot is most visible among technology and financial services employees in the Marunouchi and Roppongi corridors.
Japan Foodservice Market Segmentation
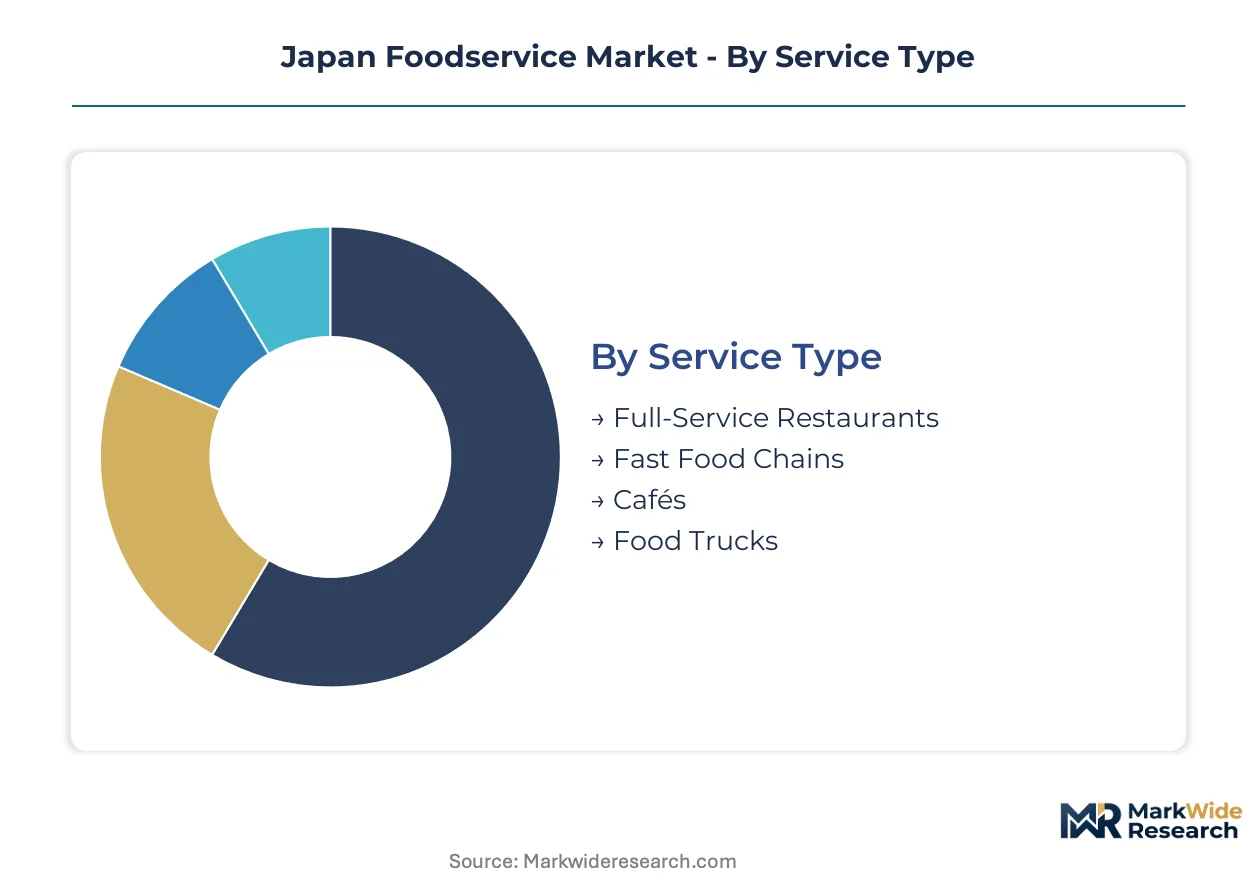
Japan's foodservice segmentation reveals how urban consumption patterns fragment across service formats, cuisine preferences, and channel behaviors. Understanding these divisions illuminates where METI's regulatory shifts and platform economics concentrate competitive pressure.
Service Type:
Mature formats dominate transaction volume while emerging concepts reshape real estate and labor deployment across Tokyo-Osaka corridors.
- Full-Service Restaurants:Table-service establishments with dedicated floor staff and kitchen brigades, spanning izakaya chains to independent kaiseki houses. Premium formats in Ginza and Kyoto's Gion district sustain margin concentration through experiential dining, though labor costs from METI Work Style Reform compliance erode mid-tier operators.
- Fast Food Chains:Standardized counter-service formats with limited menus and high throughput, led by gyudon specialists and burger chains. Yoshinoya and Sukiya anchor commuter rail nodes across the Greater Tokyo Area, capturing office worker lunch demand through price-competitive positioning and extended operating windows.
- Cafés:Beverage-forward formats with light meal attachments, including coffee chains and kissaten independents.
- Food Trucks:Mobile kitchen units serving festivals, construction sites, and event venues with lower fixed-cost structures.
Fast Food Chains retain volume leadership; Food Trucks hold the steepest expansion curve.
Cuisine Type:
Cost tier stratification separates commodity-positioned formats from premium experiential dining across Japan's urban corridors.
- Japanese:Indigenous formats spanning teishoku set meals, ramen shops, sushi counters, and kaiseki. Traditional washoku establishments in Kyoto and Kanazawa leverage UNESCO recognition and domestic ingredient sourcing to command premium positioning, while gyudon and curry chains compete on speed and price.
- Italian:Pasta and pizza formats adapted to Japanese palates, from family restaurants to chef-driven trattorias. Demand concentrates in Osaka's Umeda and Tokyo's Ebisu districts, where dual-income households seek accessible Western dining without full-service formality.
- American:Burger, fried chicken, and sandwich chains with localized menu adaptations.
- Chinese:Ramen-adjacent noodle shops and dim sum specialists, concentrated in Yokohama's Chinatown and urban Chinatowns.
Japanese cuisine retains volume leadership; Italian holds the steepest expansion curve.
Distribution Channel:
Channel selection reflects customer type and occasion urgency, with platform economics restructuring last-mile capture.
- Online Delivery:Platform-mediated ordering with third-party logistics fulfillment, dominated by Uber Eats, Demae-can, and Menu. Technology and financial services employees in Marunouchi and Roppongi corridors drive subscription-based meal plan adoption, compressing per-order friction through bundled loyalty incentives.
- Dine-In:On-premise consumption with full service or counter formats, retaining margin concentration in experiential segments.
- Takeaway:Customer-collected orders without platform intermediation, common at convenience store hot counters and railway ekiben vendors.
- Drive-Thru:Vehicle-based ordering and pickup, limited to suburban highway-adjacent locations and select fast-food chains.
Dine-In retains volume leadership; Online Delivery holds the steepest expansion curve.
Customer Segment:
Demographic targeting determines location strategy, menu engineering, and daypart configuration across Japan's metropolitan hierarchy.
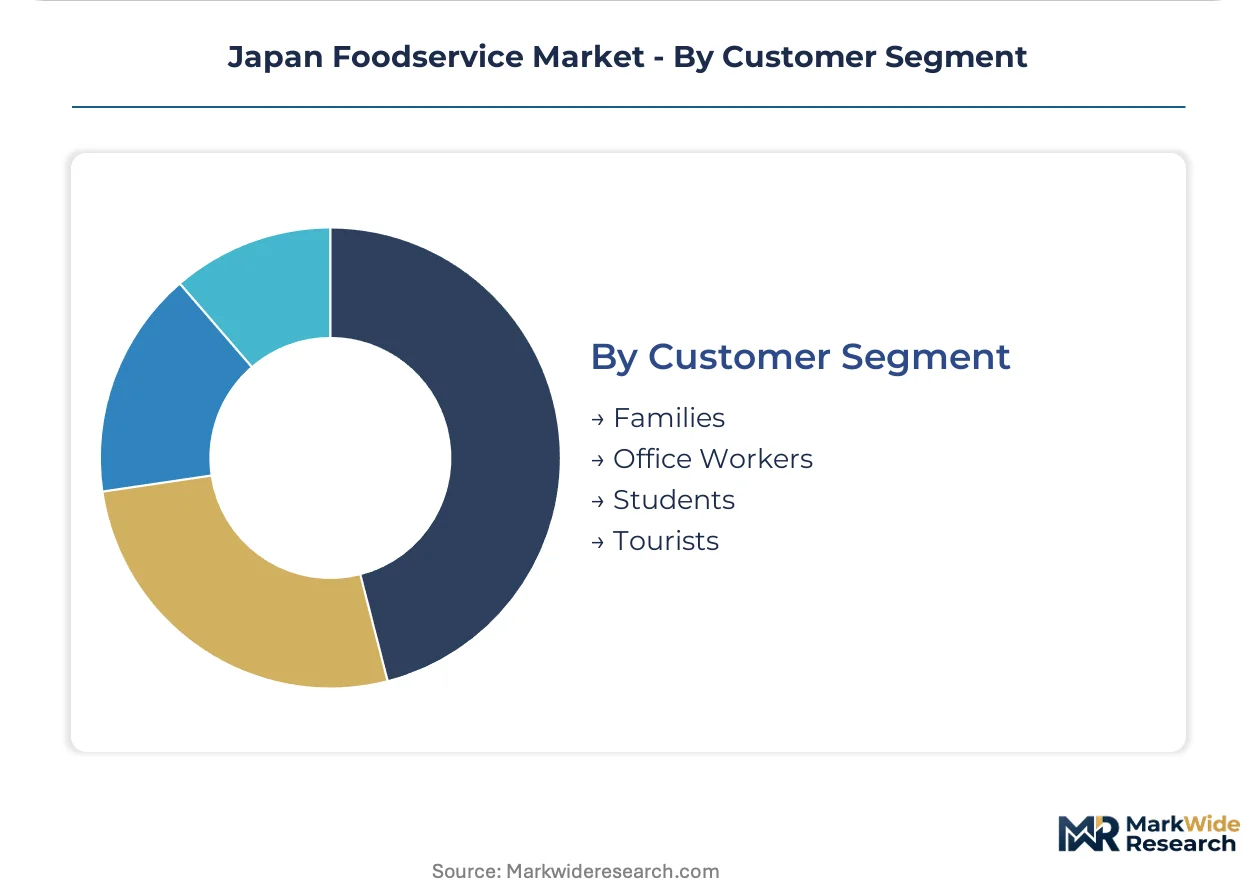
- Families:Multi-generational dining occasions prioritizing value, child accommodation, and menu breadth. Family restaurants in suburban Tokyo and Osaka prefectures configure play areas and all-you-can-drink options to extend visit duration and per-cover spending.
- Office Workers:Time-constrained professionals seeking speed, predictability, and convenience. Tokyo's Shinjuku and Osaka's Honmachi districts concentrate demand for sub-600-yen lunch sets, with platform aggregators capturing recurring orders through corporate account structures.
- Students:Price-sensitive younger consumers with flexible timing and social dining priorities.
- Tourists:Inbound visitors seeking authentic or accessible Japanese dining experiences, concentrated in Kyoto, Tokyo's Asakusa, and Osaka's Dotonbori districts.
Office Workers retain volume leadership; Tourists hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shinkansen high-speed rail network binds Japan's metropolitan foodservice clusters into a unified labor and supply corridor, compressing delivery windows between production kitchens and consumption nodes.
Kanto/Tokyo
Corporate headquarters concentration in Marunouchi and Roppongi drives premium lunch demand, with technology and financial services employees subscribing to platform-aggregated meal plans. METI's Work Style Reform directives have extended operating permissions for late-night izakaya service in Shibuya and Shinjuku wards. Ghost kitchen operators in Shinagawa and Odaiba districts exploit lower commercial rents while maintaining 30-minute delivery radii to central business districts.
Kansai/Osaka
Dual-income household density in Umeda and Honmachi corridors sustains family restaurant and teishoku chain expansion. The Consumer Affairs Agency's food labeling mandates enforce stricter allergen disclosure for independent operators in Dotonbori's tourism-heavy dining strips. Prefectural health department inspections in Osaka city align with FSSC 22000 protocols, advantaging scaled chains over traditional kissaten establishments.
Chubu/Nagoya
Automotive supplier office parks in Toyota City and central Nagoya generate concentrated weekday lunch demand for gyudon and curry specialists. JIS standards compliance for foodservice equipment procurement shapes kitchen renovation cycles across the region's manufacturing canteens. Station-front developments at Nagoya and Sakae districts concentrate fast-food and café formats targeting commuter rail traffic.
Kyushu
Lower chain density per capita in Fukuoka and Kitakyushu creates whitespace for format adaptation, particularly in suburban family dining and convenience-oriented lunch channels. Prefectural licensing reciprocity gaps with Tokyo and Osaka complicate multi-location expansion for emerging operators. Yatai street food culture in Fukuoka's Nakasu district sustains independent vendor networks alongside emerging platform delivery integration.
Hokkaido
Tourism seasonality in Sapporo and Niseko drives volatile demand patterns for full-service restaurants and ski-resort dining formats. Domestic ingredient sourcing requirements advantage local seafood and dairy suppliers in supply chain negotiations with national chains. Sapporo's Susukino entertainment district retains independent izakaya density despite metropolitan consolidation trends.
Japan Foodservice Market Competitive Landscape
On the supply side, the industry is consolidating around enterprise-scale operators with dedicated compliance infrastructure, while independent establishments face escalating regulatory burden. Three archetypes dominate: beef bowl specialists leveraging centralized supply chains, convenience store operators integrating hot meal production, and platform-dependent delivery aggregators. Competitive moves concentrate on ghost kitchen real estate acquisition and FSSC 22000 certification arbitrage against smaller competitors.
Within the beef bowl specialization tier, Yoshinoya Holdings Co. Ltd and Zensho Holdings Co. Ltd occupy positions defined by commuter rail node density and price-competitive positioning. Seven & I Holdings Co. Ltd exemplifies the convenience store convergence archetype, deepening hot meal offerings that capture office worker lunch traffic from traditional quick-service formats. These three enterprises anchor the competitive structure through distinct channel strategies rather than direct format overlap.
| Leading Market Players |
|---|
| Yoshinoya Holdings Co. Ltd |
| Zensho Holdings Co. Ltd |
| McDonald's Corporation |
| Food & Life Companies Ltd |
| McDonald's Holdings Company (Japan) Ltd |
| Seven & I Holdings Co. Ltd |
| Yum! Brands Inc. |
| Colowide Co. Ltd |
| Skylark Holdings Co. Ltd |
| Others |
Supply & Pricing Matrix
Imported protein input volatility from Australian and US beef suppliers determines both the spread between gyudon economy tiers and kaiseki premium positioning and the supply chain shape across Japan's foodservice sector. METI's FSSC 22000 certification mandate compresses margin flexibility for mid-tier operators while advantaging scaled chains with captive quality infrastructure.
Pricing Analysis
Volume-discount tiering separates enterprise gyudon chains from independent izakaya operators through procurement scale advantages. Pricing stratifies across premium kaiseki experiences, standard family restaurant formats, and economy beef bowl counters based on labor intensity and ingredient provenance. Cost compression in the economy tier intensifies as Seven & I Holdings deepens hot meal penetration at sub-500-yen price points. Office workers exhibit highest price sensitivity during weekday lunch occasions, while tourist-facing establishments in Kyoto's Gion district maintain lowest elasticity through experiential differentiation.
Supply Chain Analysis
Central kitchen concentration among Zensho Holdings, Yoshinoya Holdings, and Skylark Holdings controls nationwide bento and teishoku production capacity. Domestic rice sourcing from Niigata and Hokkaido prefectures combines with imported beef from Australia and pork from the United States to anchor protein inputs. Single-source vulnerability in Australian grass-fed beef contracts exposes margin predictability to tariff and currency fluctuations. Distribution runs through refrigerated logistics networks serving commuter rail nodes and platform-aggregator dark kitchens in Tokyo and Osaka corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as convenience store hot meals and supermarket deli counters capture price-sensitive commuter traffic from traditional quick-service formats.
For Market Incumbents: Harden supply chain resilience through backward integration into domestic rice milling and regional vegetable procurement networks. Secure FSSC 22000 certification arbitrage against independent competitors lacking dedicated compliance staff. Channel control through ghost kitchen real estate acquisition in Shinagawa and Odaiba districts protects delivery-radius economics from platform commission erosion. For New Entrants and Emerging Players: Regional cities in Hokkaido and Tohoku with lower chain density per capita represent the most penetrable entry points for format adaptation. Fukuoka's suburban family dining whitespace and Kitakyushu's convenience-oriented lunch channels offer parallel expansion vectors. Go-to-market execution through platform-aggregator partnership structures reduces upfront real estate capital requirements. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors enterprise-scale operators with dedicated quality infrastructure and centralized supply chain control. Long-term viability over the next decade hinges on regulatory compliance scalability rather than format innovation alone. Ghost kitchen convergence with logistics technology serves as the critical inflection indicator for unit economics trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| FSSC 22000 Certification Investment | METI-aligned quality infrastructure creates compliance moats against independent competitors lacking dedicated audit staff. |
| Ghost Kitchen Network Expansion | Dark kitchen real estate in Shinagawa and Odaiba reduces last-mile delivery costs while maintaining central business district radii. |
| Platform Aggregator Partnership | Corporate account structures with Uber Eats and Demae-can capture recurring office worker subscription revenue. |
| Regional Format Adaptation | Hokkaido and Tohoku whitespace penetration exploits lower chain density per capita in secondary cities. |
| Domestic Ingredient Sourcing | Hokkaido seafood and Niigata rice procurement satisfies Consumer Affairs Agency traceability mandates while reducing import tariff exposure. |
Research Methodology
Desk research of METI regulatory filings, Consumer Affairs Agency food labeling databases, and prefectural health department inspection protocols preceded structured interviews with gyudon chain procurement directors, izakaya operations managers, platform-aggregator account executives, and convenience store foodservice planners. Secondary validation drew from corporate sustainability disclosures, FSSC 22000 certification registries, and refrigerated logistics trade data. Bottom-up outlet enumeration across Tokyo, Osaka, and Fukuoka corridors combined with top-down consumer expenditure estimates to establish market sizing triangulation.
Assumptions held fixed across the modeling period include METI Work Style Reform enforcement continuity, platform commission structure stability, and Australian beef import tariff regimes. Segmentation dimensions modeled span service format, cuisine type, distribution channel, and customer segment with additional granularity on corporate versus individual account structures. CAGRs derived from trend extrapolation of historical outlet growth and per-capita foodservice expenditure elasticity. Forecast inputs incorporated office worker lunch demand intensity and dual-income household penetration patterns.
Practitioners should monitor Australian beef price volatility, platform-aggregator fee renegotiation cycles, and METI labor regulation enforcement intensity for early signals requiring forecast revision. Cross-checking against prefectural health department licensing data and corporate outlet expansion disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Europe Biodegradable Food Service Disposables Market
Food Service
Pizza Oven Market
Food Service
Cloud Kitchen Market
Food Service
Full-Service Restaurants Market
Food Service
Global Self Heating Instant Hot Pot Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Europe Food Away from Home Market
Food Service
Instant Grocery Market
Food Service
US Food Service Market
Food Service
Spain Food Service Market
Food Service
United States Food Truck Market
Food Service
Switzerland Food Service Market
Food Service
Commercial Air Fryer Oven Market
Food Service
Clear Ice Maker Market
Food Service
Belgium HRI Market
Food Service
Saudi Arabia Foodservice Market