
 Food Service Dairy Products Market | 2026-2036
Food Service Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Food Service Dairy Products Market Analysis
Multi-source procurement among institutional food buyers is expanding as operators diversify dairy supplier bases to mitigate cold-chain disruption risks. Fonterra leverages its New Zealand-origin milk powder network to anchor bulk supply contracts across Asia-Pacific food manufacturers. Lactalis competes through vertically integrated cheese production that controls whey processing and aging facilities. Nestlé differentiates via extended shelf-life UHT cream formulations tailored to tropical climate distribution.
Food service dairy products encompass pasteurized, ultra-heat-treated, dried, and cultured milk derivatives formulated for commercial kitchen and away-from-home consumption, typically requiring minimum protein thresholds of 3.2% for fluid milk and specific butterfat grades for culinary applications. These products serve as foundational ingredients in recipe-standardized environments where consistency, yield, and labor efficiency determine procurement decisions. Cheese commands the largest margin pool among product type segments due to aged-variant premiums and portion-controlled shredding formats. Bulk containers dominate packaging type demand within high-volume restaurant chains where automated dispensing reduces per-unit handling costs. Direct sales channels are capturing share from traditional wholesale distributors as national café operators negotiate private-label supply agreements.
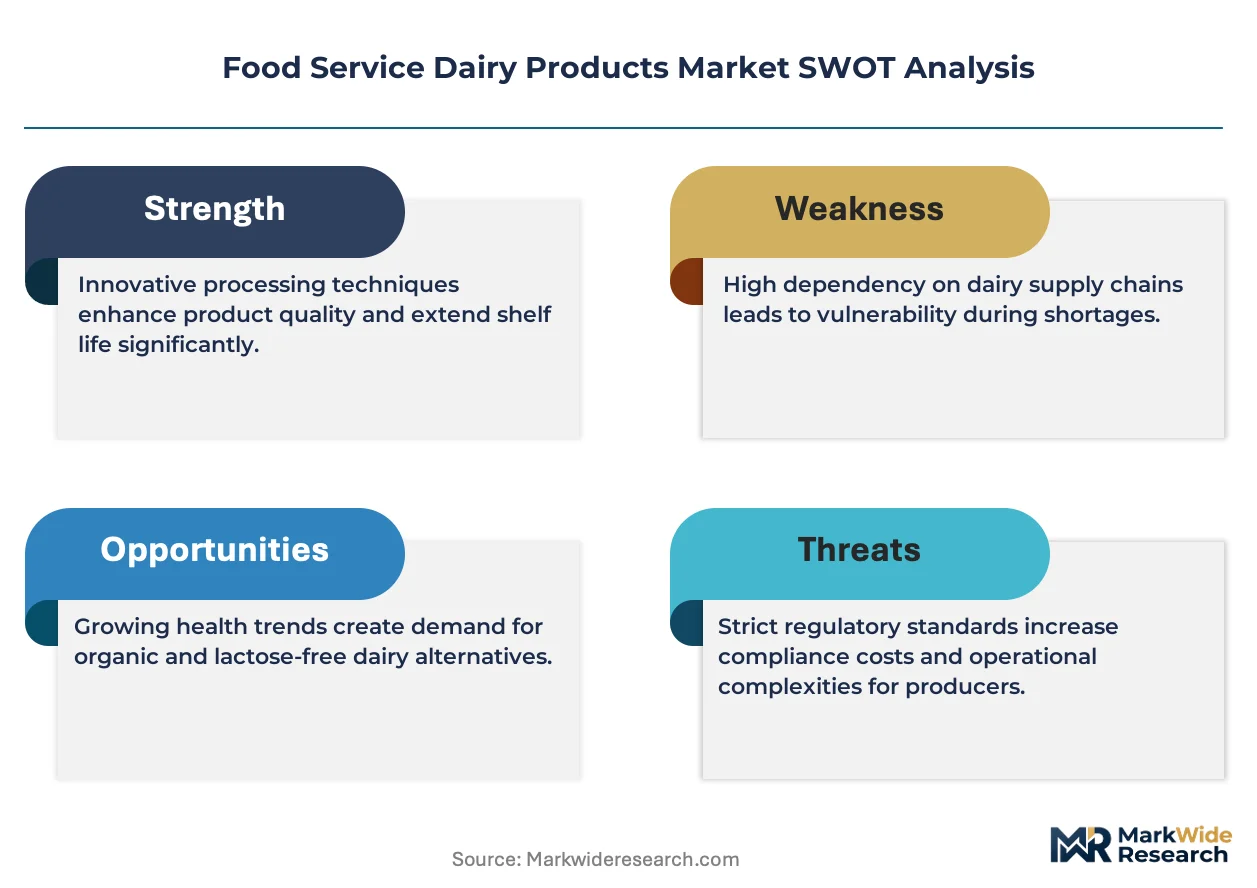
The USDA's Grade A Pasteurized Milk Ordinance governs interstate fluid milk safety standards, while FDA enforcement of the Food Safety Modernization Act mandates hazard analysis for refrigerated dairy throughout distribution. EU EFSA hygiene criteria for unpasteurized milk derivatives restrict market access for non-compliant exporters. Stakeholders must monitor evolving cold-chain traceability requirements as regulatory bodies tighten temperature documentation protocols without specifying implementation timelines.
Market Dynamics
EU Green Deal sustainability mandates are compressing supplier certification timelines while Southeast Asian quick-service restaurant chains accelerate refrigerated dairy procurement, creating simultaneous compliance pressure and demand pull across the value chain.
Growth Catalysts
- EU Green Deal compliance mandates:Foodservice operators across Germany and France now require verified carbon footprint documentation for butter and cream suppliers, redirecting procurement toward certified sustainable sources.
- Urban foodservice corridor expansion:Indonesia's Jakarta-Bandung-Surabaya corridor is driving concentrated demand for UHT milk and processed cheese formats suited to tropical distribution infrastructure.
- Cold-chain infrastructure modernization:Refrigerated logistics networks in Vietnam and Thailand now support extended shelf-life dairy delivery to remote restaurant locations previously unreachable.
Market Restraints
- Feed cost volatility:New Zealand and Australian pasture-based dairy systems face margin compression from fluctuating grain and fertilizer input prices that transfer unpredictably into bulk milk powder contracts.
- Supplier concentration risk:A limited number of cooperatives control whey protein concentrate output for Southeast Asian food manufacturers, creating single-source vulnerability for industrial cheese production.
- Regulatory friction from unpasteurized restrictions:EU EFSA hygiene criteria for raw milk derivatives block market access for traditional cheese exporters from non-compliant third countries.
Strategic Opportunities
- Underpenetrated Philippine foodservice:Manila's expanding café and bakery segment lacks consistent aged cheese supply, presenting white space for portion-controlled shredding format entry.
- Plant-dairy hybrid formulations:Convergence of enzymatic processing and fermentation technology enables reduced-dairy cream alternatives that meet EU sustainability thresholds without full substitution.
- Direct private-label channels:National coffeehouse chains in Malaysia and Singapore now negotiate bypass agreements with processors, disintermediating traditional wholesale distributors.
Industry Challenges
- Cold-chain traceability documentation:FDA Food Safety Modernization Act enforcement demands continuous temperature logging across distribution, requiring capital investment in IoT sensor deployment.
- Specialized dairy technologist scarcity:Industrial cheesemaking and UHT formulation expertise concentrates in European and Oceania labor pools, constraining facility expansion in emerging production regions.
- Legacy system integration friction:ERP platforms at institutional food buyers resist seamless data exchange with supplier traceability databases, delaying real-time compliance verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Service Dairy Products Market |
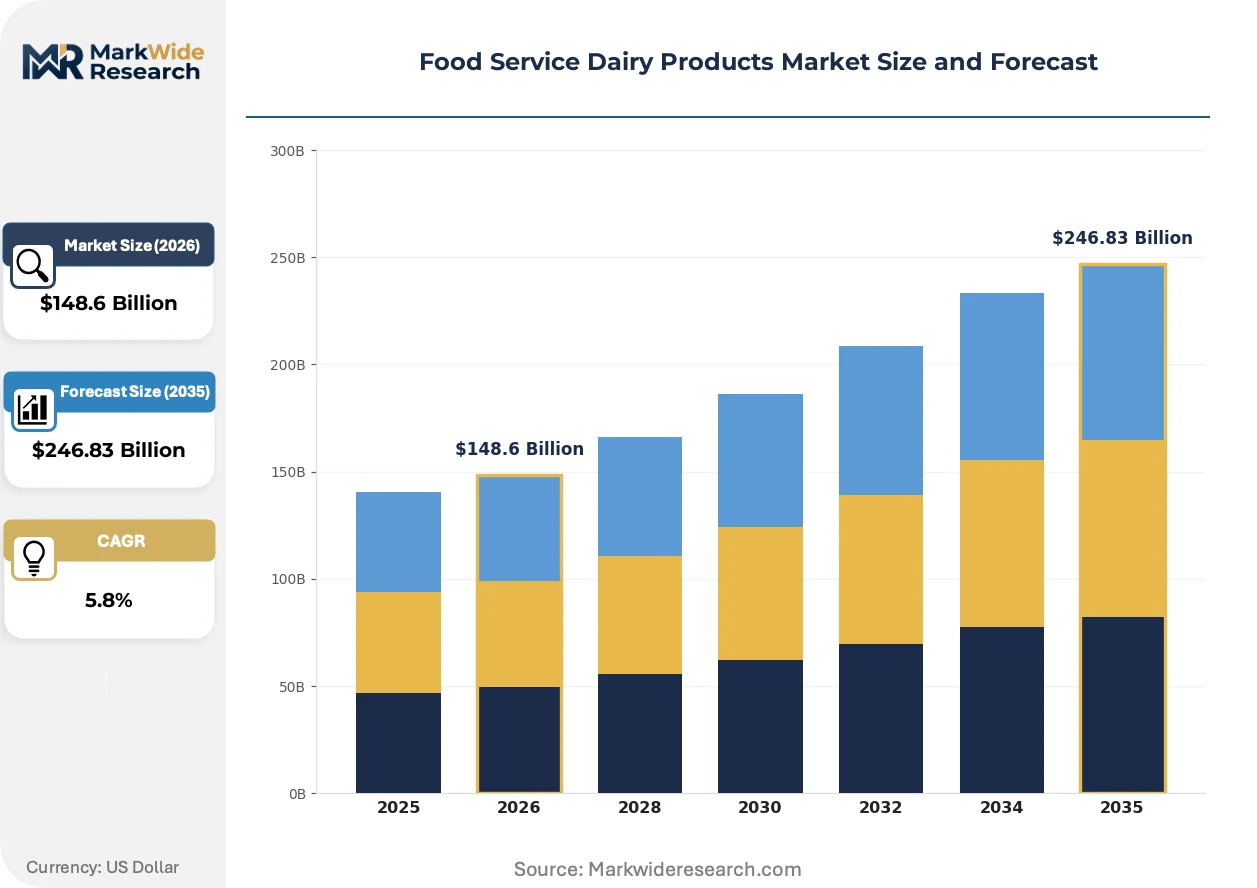
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $246.83 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Yogurt, Cheese, Butter End User: Restaurants, Cafés, Catering Services, Hotels Packaging Type: Bottles, Tetra Packs, Pouches, Bulk Containers Distribution Channel: Direct Sales, Wholesale, Online Retail, Distributors |
| Companies Covered | Danone, Fonterra, Lactalis, Mengniu Dairy, FrieslandCampina, Nestlé, Arla Foods, Saputo Inc., Dairy Farmers of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Service Dairy Products Market Emerging Trajectories
Automation in dairy processing and distribution is compressing operational timelines while regulatory frameworks harden documentation requirements. Three distinct shifts are restructuring competitive positioning across production, compliance, and procurement.
Aseptic filling and packaging technology is consolidating fragmented regional supply into centralized production hubs. Southeast Asian dairy processors adopt closed-system UHT lines to reduce contamination risk during tropical monsoon seasons. This consolidation enables single-facility supply to multiple countries, compressing the number of viable suppliers per market.
CSRD corporate sustainability reporting obligations are mandating scope-three emissions disclosure for EU-based foodservice operators. Dairy suppliers must now provide farm-level methane and energy-use data to maintain contract eligibility. French and Italian restaurant groups are responding by consolidating procurement around processors with verified lifecycle assessment capabilities.
Buyer concentration among multinational café chains is displacing fragmented wholesale distribution with direct processor relationships. Singapore-based operators now negotiate specification-grade milk contracts that bypass traditional dairy cooperatives. This pattern is most visible in ASEAN urban centers where chain penetration exceeds independent foodservice density.
Food Service Dairy Products Market Segmentation
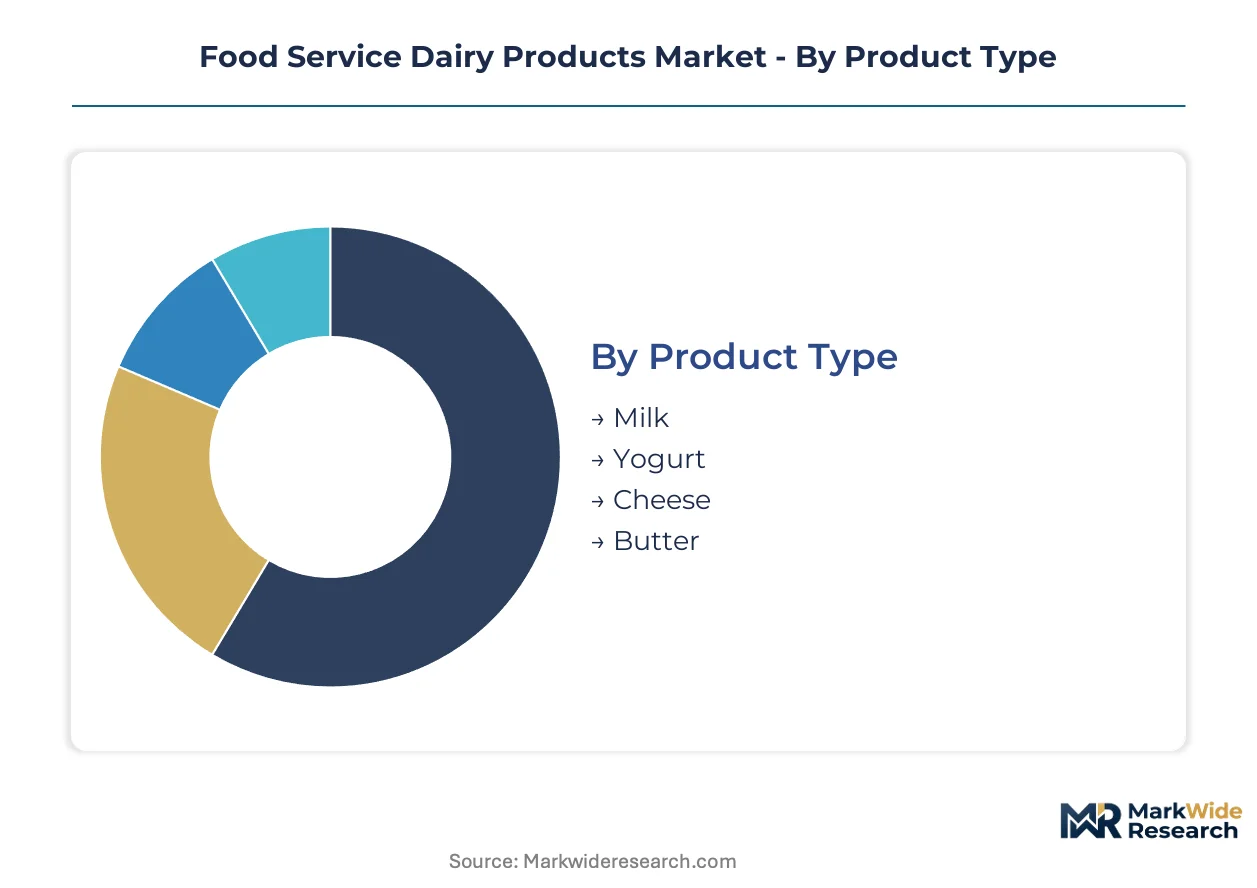
Food service dairy procurement decisions pivot on yield consistency, labor efficiency, and cold-chain reliability. Segmentation reveals where margin pools concentrate and how operator scale dictates format preferences across institutional kitchens and away-from-home channels.
Product Type:
Volume throughput dominates milk and butter procurement, while aged variants and portion-controlled formats command premium positioning in cheese and yogurt segments.
- Cheese:Aged variants with controlled moisture content and standardized melt profiles anchor recipe-standardized kitchens. Demand concentrates in quick-service chains across Indonesia's urban corridor, where portion-controlled shredding reduces labor cost per serving.
- Milk:Fluid milk meeting minimum 3.2% protein thresholds serves as foundational input for beverage and sauce applications. High-volume restaurant chains in Vietnam and Thailand drive procurement of extended shelf-life UHT formulations suited to tropical distribution infrastructure.
- Yogurt:Cultured derivatives with defined viscosity specifications support both standalone service and ingredient applications in bakery and smoothie operations.
- Butter:Specified butterfat grades for culinary applications, with EU Green Deal carbon footprint documentation now required by French and German operators.
Mature deployment sits with cheese portion-control formats. Newer deployment is concentrated in UHT milk tailored to monsoon-season distribution.
End User:
Operator scale determines procurement sophistication, with national chains negotiating direct processor agreements while independent venues rely on wholesale intermediation.
- Restaurants:Quick-service chains across Southeast Asia scale refrigerated dairy procurement through centralized specification contracts. Cold-chain modernization in Vietnam and Thailand now extends supply to remote locations previously unreachable.
- Cafés:National coffeehouse chains in Malaysia and Singapore negotiate bypass agreements with processors, disintermediating traditional dairy cooperatives. Specification-grade milk contracts dominate procurement.
- Catering Services:Institutional buyers diversify supplier bases to mitigate cold-chain disruption risks, expanding multi-source procurement strategies.
- Hotels:Full-service properties demand consistent butterfat grades for culinary applications across banquet and à la carte operations.
Procurement sophistication concentrates in café direct-channel negotiations. Volume scaling is accelerating most quickly in quick-service restaurant chains.
Packaging Type:
Automation compatibility and per-unit handling cost drive format selection, with bulk solutions favored by high-volume operators and portion-controlled formats serving precision kitchens.
- Bulk Containers:Automated dispensing systems in high-volume restaurant chains reduce per-unit handling costs. These formats dominate procurement where labor efficiency determines operational margins.
- Tetra Packs:Aseptic filling technology enables centralized production hubs to supply multiple Southeast Asian markets from single facilities, compressing viable supplier counts per geography.
- Bottles:Standard fluid milk delivery for traditional foodservice operations with established refrigerated logistics networks.
- Pouches:Flexible formats for portion-controlled and single-serve applications in limited-service environments.
Established infrastructure supports bottle and bulk container deployment. Tetra Pack aseptic systems represent the steepest expansion trajectory for tropical climate distribution.
Distribution Channel:
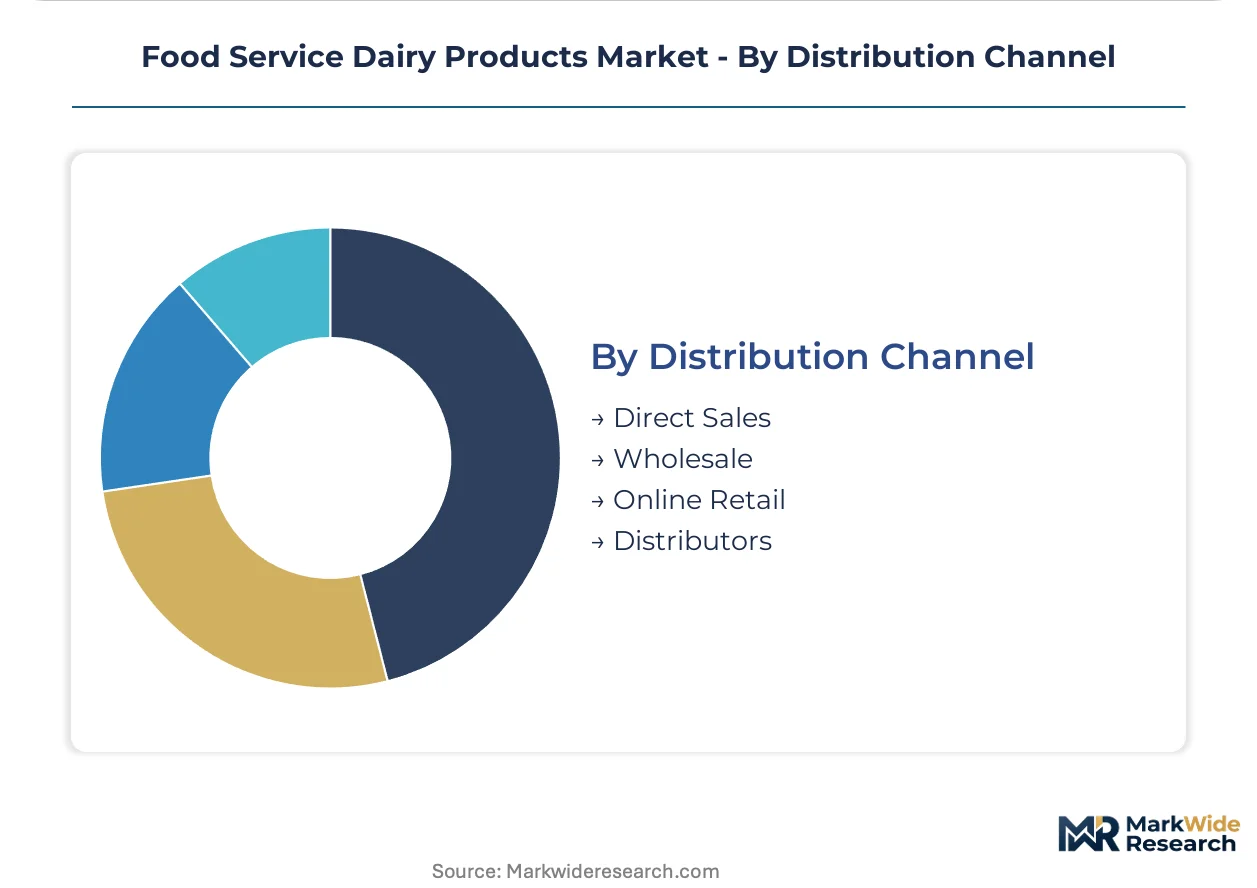
Channel selection reflects buyer concentration and specification complexity, with direct relationships displacing fragmented wholesale where scale permits.
- Direct Sales:National café operators negotiate private-label supply agreements that bypass traditional wholesale distributors. Singapore-based processors now contract directly with multinational chains for specification-grade products.
- Wholesale:Traditional dairy cooperatives serve fragmented independent foodservice density where chain penetration remains limited.
- Distributors:Regional intermediaries maintain cold-chain integrity for operators lacking direct processor relationships.
- Online Retail:Digital procurement channels emerging for specialty and smaller-format dairy derivatives in urban foodservice corridors.
Channel maturity rests with wholesale cooperative structures. Direct sales deployment is concentrating fastest among ASEAN café chains with scale sufficient to justify bypass agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Southeast Asia's urban foodservice corridors where quick-service restaurant chains scale refrigerated dairy procurement. Indonesia's Jakarta-Bandung-Surabaya axis anchors volume growth, while EU sustainability mandates reshape supplier certification requirements across European procurement networks.
Indonesia
Quick-service chains drive UHT milk and processed cheese procurement across the Jakarta-Bandung-Surabaya corridor. BIS certification requirements govern imported dairy derivatives entering institutional foodservice channels. Surabaya's port infrastructure expansion enables direct bulk container receipt from New Zealand-origin suppliers, bypassing traditional Singapore transshipment.
United States
Institutional buyers diversify supplier bases to mitigate cold-chain disruption risks across multi-state restaurant operations. FDA enforcement of the Food Safety Modernization Act mandates hazard analysis for refrigerated dairy throughout distribution. California's Central Valley processing cluster supplies extended shelf-life cream formulations to national café chains negotiating direct procurement agreements.
Germany
Foodservice operators require verified carbon footprint documentation for butter and cream suppliers under EU Green Deal compliance mandates. EFSA hygiene criteria restrict market access for non-compliant raw milk derivative exporters. Bavaria's dairy processing corridor consolidates procurement around processors with verified lifecycle assessment capabilities.
Vietnam
Refrigerated logistics networks now support extended shelf-life dairy delivery to remote restaurant locations previously unreachable. The country's national food safety regulator tightens cold-chain documentation protocols without specifying implementation timelines. Ho Chi Minh City's urban foodservice density attracts direct processor relationships from multinational café chains.
France
Restaurant groups consolidate procurement around processors with verified lifecycle assessment capabilities under CSRD corporate sustainability reporting obligations. EU EFSA hygiene criteria for unpasteurized milk derivatives block traditional cheese exporters from non-compliant third countries. The Île-de-France region's institutional catering sector demands specified butterfat grades for culinary applications across banquet operations.
Food Service Dairy Products Market Vendor Landscape
Direct private-label negotiations dominate the current landscape as national café chains disintermediate traditional wholesale distributors. The vendor base clusters around three archetypes: Oceania-origin cooperatives controlling bulk milk powder networks, European processors with vertically integrated cheese production, and diversified multinationals offering tropical-formulation UHT derivatives. M&A activity concentrates in Southeast Asian processing assets, while capacity expansion targets aseptic filling technology for monsoon-season distribution resilience.
Within the cooperative archetype, Fonterra anchors bulk supply relationships across Asia-Pacific food manufacturers. Lactalis occupies a position exemplifying vertically integrated cheese production with controlled whey processing. Nestlé sits within the diversified multinational tier, representing extended shelf-life formulation capabilities tailored to tropical climate distribution infrastructure.
| Leading Market Players |
|---|
| Danone |
| Fonterra |
| Lactalis |
| Mengniu Dairy |
| FrieslandCampina |
| Nestlé |
| Arla Foods |
| Saputo Inc. |
| Dairy Farmers of America |
| Others |
Supply Flow & Price Mechanics
Global Dairy Trade auction prices for whole milk powder serve as the primary reference point cascading through Southeast Asian procurement contracts, compressing margins for processors unable to pass through commodity volatility into fixed-price foodservice agreements.
Pricing Analysis
Volume throughput commands thin margins in fluid milk and bulk butter contracts, while aged cheese variants and portion-controlled shredding formats capture premium positioning through labor-efficiency value propositions. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified sustainable dairy from conventional supply and commodity-grade alternatives. Pricing pressure stems from New Zealand and Australian feed cost volatility transferring unpredictably into bulk milk powder contracts. Quick-service restaurant chains exhibit highest price sensitivity due to recipe-standardized cost targets, while national café operators prioritize specification consistency over per-unit savings.
Supply Chain Analysis
Raw milk supply rests on pasture-based systems in New Zealand, grain-fed operations in the United States, and mixed farming across the European Union. Whey protein concentrate draws from a limited cooperative base, while specialized cultures and enzymes feed from European biotechnology suppliers. Single-source vulnerability concentrates in Southeast Asian whey procurement for industrial cheese production. Distribution runs through refrigerated logistics networks with direct private-label channels displacing traditional wholesale cooperatives among scaled buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aseptic filling capacity scarcity in Southeast Asia props pricing power for processors with monsoon-season distribution capabilities, constraining supply response to quick-service chain procurement scaling.
For Market Incumbents: Extend certification investments to capture EU Green Deal compliance premiums before mandatory scope-three disclosure deadlines harden procurement requirements. Anchor supply relationships through backward integration into New Zealand-origin milk powder networks to defend against emerging Oceania cooperative entrants. Prioritize IoT sensor deployment across cold-chain assets to meet FDA Food Safety Modernization Act documentation mandates.
For New Entrants and Emerging Players: Independent bakery and café operators in Manila's expanding foodservice corridor represent the most penetrable buyer archetype, lacking consistent aged cheese supply and receptive to portion-controlled shredding format entry. Target direct processor relationships bypassing traditional dairy cooperatives in Vietnam's Ho Chi Minh City cluster. Lead with specification-grade UHT formulations tailored to tropical climate distribution infrastructure.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Southeast Asian processing assets with aseptic filling technology in Indonesia and Vietnam, where cold-chain modernization lags demand growth. Long-term viability hinges on securing farm-level methane data capabilities for EU contract eligibility. Watch for consolidation signals when multinational café chains accelerate direct procurement bypass agreements.
| Strategic Initiative | Industry Significance |
|---|---|
| Aseptic Filling Capacity Expansion | Monsoon-season distribution resilience enables centralized supply to multiple Southeast Asian markets from single facilities. |
| Farm-Level Carbon Data Integration | EU CSRD scope-three disclosure mandates require verified lifecycle assessment capabilities for contract retention. |
| Direct Private-Label Agreements | Singapore-based processors bypass traditional dairy cooperatives to capture specification-grade contracts with national café chains. |
| Cold-Chain IoT Deployment | FDA enforcement of continuous temperature logging demands capital investment in sensor infrastructure across distribution networks. |
| Backward Integration into Milk Powder | New Zealand-origin supply anchors bulk procurement relationships across Asia-Pacific food manufacturers facing feed cost volatility. |
Methodological Framework
Multi-period observation of Global Dairy Trade auction prices, EU carbon certification timelines, and Southeast Asian quick-service chain procurement scaling anchored the trend analysis, supplemented by interviews with dairy processing executives, foodservice procurement directors, cold-chain logistics operators, and regulatory compliance officers. Primary fieldwork combined with secondary validation through USDA Grade A Pasteurized Milk Ordinance filings, EU EFSA hygiene criteria documentation, FDA Food Safety Modernization Act enforcement records, and BIS certification requirement publications. Bottom-up volume modeling across product type, end user, packaging format, and distribution channel segments triangulated against top-down macroeconomic drivers.
Input-output matrices mapped raw milk supply from New Zealand, Australia, the United States, and the European Union through processing stages into foodservice channel demand across Indonesia, Vietnam, Thailand, Malaysia, Singapore, Germany, France, and the United States. Segmentation dimensions modeled include product type, end user scale, packaging automation compatibility, and channel directness. CAGRs were derived from regression analysis of historical procurement volumes against quick-service restaurant chain expansion, cold-chain infrastructure investment, and regulatory compliance cost absorption across the projection horizon. Forecast inputs incorporated pasture-based versus grain-fed milk production cost structures and tropical climate distribution infrastructure availability.
Revisions become necessary when EU Green Deal implementation timelines accelerate, Southeast Asian cold-chain modernization stalls, or New Zealand-Australian feed cost volatility disrupts bulk milk powder contract pricing. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and buyer concentration trajectories. A small set of triggers—FDA temperature documentation mandate expansion, CSRD scope-three disclosure hardening, and multinational café chain procurement bypass acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service
Commercial Charbroiler Market
Food Service
Train Catering Service Market
Food Service
United States Biodegradable Food Service Disposables Market
Food Service
Food Logistics Market
Food Service
Beverage Vending Machine Market
Food Service
Online Grocery Market
Food Service
Limited-Service Restaurants Market
Food Service
Bottled Water Cooler Market
Food Service
Global Virtual Restaurant and Ghost Kitchens Market
Food Service
Haute Cuisine Market
Food Service
United Kingdom Cafes & Bars Market
Food Service
Restaurant Glassware Market
Food Service
Full-Service Restaurants Market
Food Service
Kamado Grill Market
Food Service
United Kingdom Barbeque Grill Market
Food Service
Undercounter Ice Makers Market