
 Self-Checkout System Market | 2026-2036
Self-Checkout System Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Checkout System Market Analysis
Consolidation among big-box retailers is repositioning procurement power toward a handful of national chains that dictate system specifications and deployment timelines. NCR Corporation leverages its installed base of point-of-sale infrastructure to cross-sell integrated self-checkout terminals. Diebold Nixdorf sustains a strong position in financial self-service hardware, extending its engineering capabilities into retail automation. Fujitsu competes through specialized biometric authentication modules that reduce friction at payment stages.
A self-checkout system comprises hardware terminals, payment kiosks, software platforms, and integrated peripherals that enable customers to scan, bag, and pay for merchandise without cashier assistance. These systems typically incorporate barcode scanners weighing scales, touchscreen interfaces, and card readers to process transactions while maintaining loss-prevention accuracy. Terminal hardware anchors the largest revenue pool due to replacement cycles and retrofit demand across existing store footprints. Cloud-based deployment is gaining traction fastest as retailers seek centralized fleet management and real-time software updates across distributed locations. Mobile payment technology integration is reshaping competitive positioning, with vendors racing to support tap-to-pay and digital wallet protocols.
The Federal Trade Commission monitors checkout automation for its effects on employment disclosures and consumer pricing transparency, while PCI-DSS standards enforce encryption and tokenization protocols for card-present transactions. The National Institute of Standards and Technology publishes cybersecurity frameworks that self-checkout vendors must address to protect against point-of-sale malware and network intrusions. Stakeholders should monitor evolving state-level biometric privacy laws, as facial recognition and palm-scanning authentication methods spread through next-generation kiosk designs.
Market Dynamics
Consolidation among national supermarket chains is concentrating procurement power into fewer buyers who dictate terminal specifications, deployment timelines, and software integration requirements across thousands of store locations.
Growth Catalysts
- Labor Cost Pressures:Supermarket operators face mounting wage inflation in urban markets, accelerating capital allocation toward autonomous checkout infrastructure to redeploy floor staff to customer service roles.
- NIST Cybersecurity Framework:Federal guidelines for point-of-sale hardening are mandating encrypted payment architectures, creating replacement demand for legacy terminals that lack tokenization capabilities.
- Tap-to-Pay Protocols:Near-field communication standards are proliferating through smartphone ecosystems, reducing friction at payment stages and expanding addressable transaction volumes for kiosk vendors.
Market Restraints
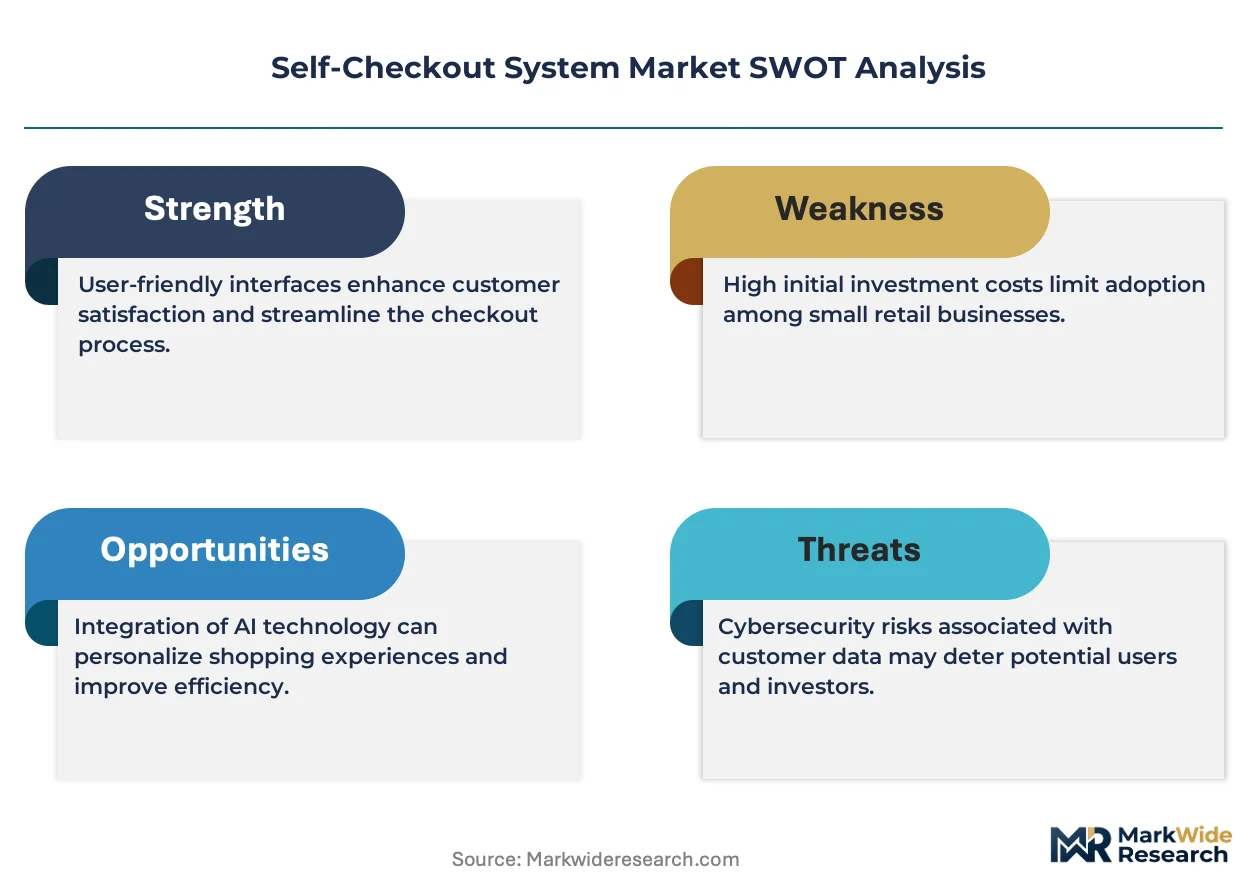
- Semiconductor Supply Concentration:Touchscreen controller chips and secure element processors source predominantly from East Asian foundries, exposing deployment timelines to geopolitical disruption risks.
- Shrinkage Detection Limitations:Current weight-sensing algorithms struggle with variable-density produce and non-barcoded bulk items, constraining rollout feasibility in grocery formats with high fresh-food penetration.
- Biometric Privacy Friction:State-level facial recognition moratoriums in Illinois, Texas, and California are blocking palm-scanning authentication pilots, forcing fallback to slower card-and-PIN workflows.
Strategic Opportunities
- Convenience Store Underpenetration:The United States hosts over 150,000 convenience locations with minimal automation deployment, presenting a greenfield segment for compact terminal form factors.
- Cloud-Native Fleet Management:Centralized software update architectures are converging with edge-computing capabilities, enabling predictive maintenance and dynamic pricing integration previously requiring on-site technical visits.
- India Retail Modernization:Organized retail penetration remains below ten percent, creating first-mover advantages for vendors establishing local assembly partnerships ahead of format standardization.
Industry Challenges
- Legacy POS Integration Complexity:Major retailers operate heterogeneous back-end systems accumulated through decades of acquisitions, requiring costly middleware development to synchronize inventory, loyalty, and payment data flows with new kiosk fleets.
- PCI-DSS Certification Timelines:Hardware validation cycles for encryption modules stretch eighteen to twenty-four months, compressing vendor development roadmaps and delaying revenue recognition for new product generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Checkout System Market |
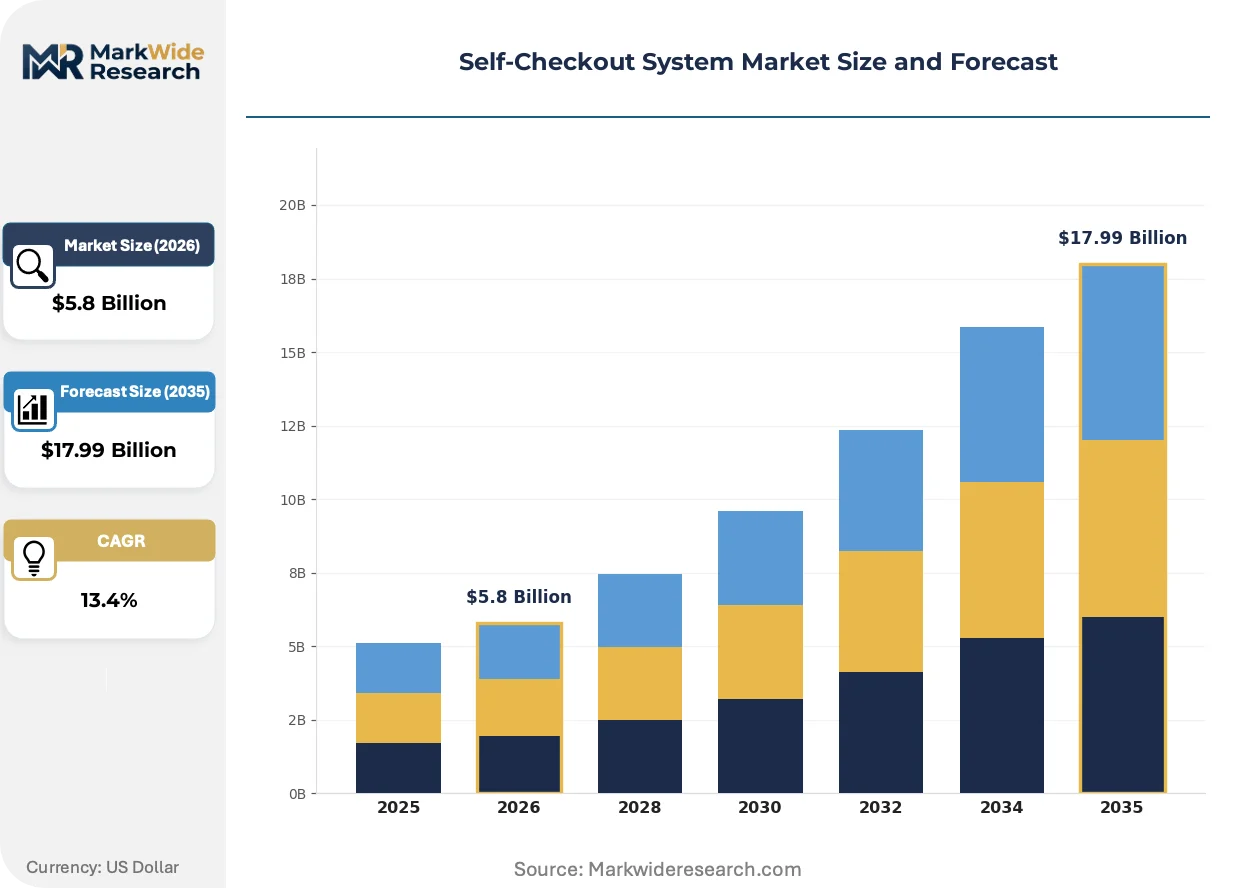
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $17.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Terminal, Kiosk, Software, Integrated System End User: Retailers, Supermarkets, Convenience Stores, Restaurants Technology: Barcode Scanning, Mobile Payment, RFID, Touchscreen Interface Deployment: On-Premise, Cloud-Based, Hybrid, Others |
| Companies Covered | NCR Corporation, Diebold Nixdorf, Acrelec, Fujitsu, Toshiba TEC Corporation, Gilbarco Veeder Root, ITAB Shop Concept, Zebra Technologies, Strongpoint, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Checkout System Market Emerging Trajectories
Computer vision and sensor fusion technologies are displacing traditional barcode-dependent workflows, enabling grab-and-go checkout experiences that eliminate scanning friction entirely.
Camera-based recognition systems are expanding into produce identification and weight estimation, eliminating manual lookup steps that previously slowed throughput in grocery environments. Albertsons and Kroger are piloting these capabilities in high-traffic urban locations, compressing average transaction times by removing barcode scanning as a mandatory step. The technology is expanding into loss-prevention applications, correlating shelf-sensor data with point-of-sale records to flag discrepancies without human monitoring.
The EU AI Act's risk classification framework is imposing documentation and audit requirements on automated decision systems used in retail payment authentication. Vendors deploying facial or gait recognition for fraud detection must now maintain algorithmic impact assessments and human oversight protocols. European supermarket operators are responding by accelerating procurement of transparent, explainable biometric alternatives that satisfy conformity assessment procedures.
Buying committees at national retail chains are unbundling hardware procurement from software licensing, favoring modular architectures that permit competitive tendering for each stack layer. This pattern displaces traditional single-vendor relationships and compresses contract values for integrated solution providers. The shift is most visible in the United States, where Target and Walmart have established separate RFP processes for terminal hardware, payment gateway software, and fleet management platforms.
Self-Checkout System Market Segmentation
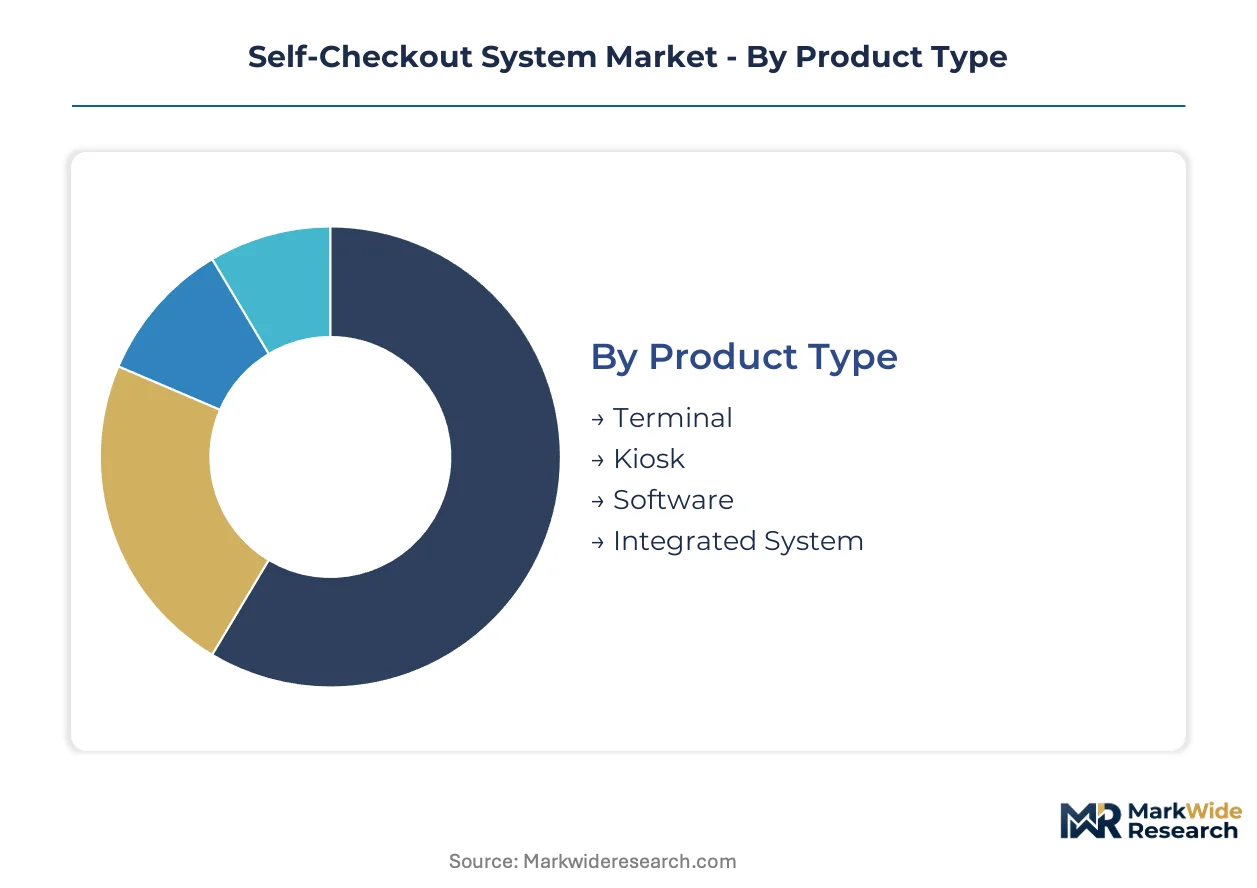
Self-checkout system segmentation reveals how procurement decisions bifurcate between capital-intensive hardware refresh cycles and recurring software subscriptions. Understanding these category boundaries clarifies where vendors can defend margin versus where price competition erodes profitability.
Product Type:
Supply concentration in touchscreen controller semiconductors and secure payment modules shapes which product categories command pricing power versus which face cost compression.
- Terminal:Freestanding units with integrated scales, scanners, and payment readers anchor retrofit demand across existing store footprints. United States supermarket chains dominate procurement volumes as wage inflation accelerates capital allocation toward autonomous checkout infrastructure.
- Kiosk:Compact wall-mounted or countertop configurations target convenience stores and quick-service restaurants with space constraints. Deployment feasibility depends on PCI-DSS certification timelines that stretch hardware validation cycles.
- Software:Fleet management platforms and transaction processing engines enable centralized updates across distributed locations.
- Integrated System:Bundled hardware-software packages with unified warranty and support terms appeal to smaller retailers lacking internal IT integration capabilities.
Today's leader: Terminal. Tomorrow's challenger: Software.
End User:
End-user concentration determines whether vendors pursue direct enterprise sales or channel partner distribution strategies.
- Retailers:Department stores and big-box chains with heterogeneous legacy POS systems accumulated through decades of acquisitions require costly middleware development for kiosk synchronization.
- Supermarkets:Grocery operators with high fresh-food penetration face shrinkage detection limitations that constrain full-format rollout feasibility.
- Convenience Stores:The United States hosts over 150,000 locations with minimal automation deployment, presenting greenfield opportunity for compact terminal form factors.
- Restaurants:Quick-service and fast-casual operators prioritize speed-of-service metrics over loss prevention, favoring payment kiosks with minimal friction.
Supermarkets absorb the heaviest investment; convenience stores offer the steepest expansion trajectory.
Technology:
Technology maturity curves determine which capabilities justify premium pricing versus which commoditize into baseline expectations.
- Barcode Scanning:Legacy laser and camera-based 1D/2D reading remains the default transaction method despite throughput friction. Retailers in the United States are piloting computer vision alternatives that eliminate mandatory scanning steps entirely.
- Mobile Payment:Near-field communication protocols embedded in smartphone ecosystems reduce payment stage friction and expand addressable transaction volumes.
- RFID:Tag-based identification enables grab-and-go checkout without individual item scanning, though tag costs limit adoption to higher-margin merchandise categories.
- Touchscreen Interface:Capacitive and projected capacitive displays constitute the primary customer interaction layer, with procurement concentrated among East Asian panel manufacturers.
Barcode scanning dominates installed base; mobile payment integration is gaining share fastest.
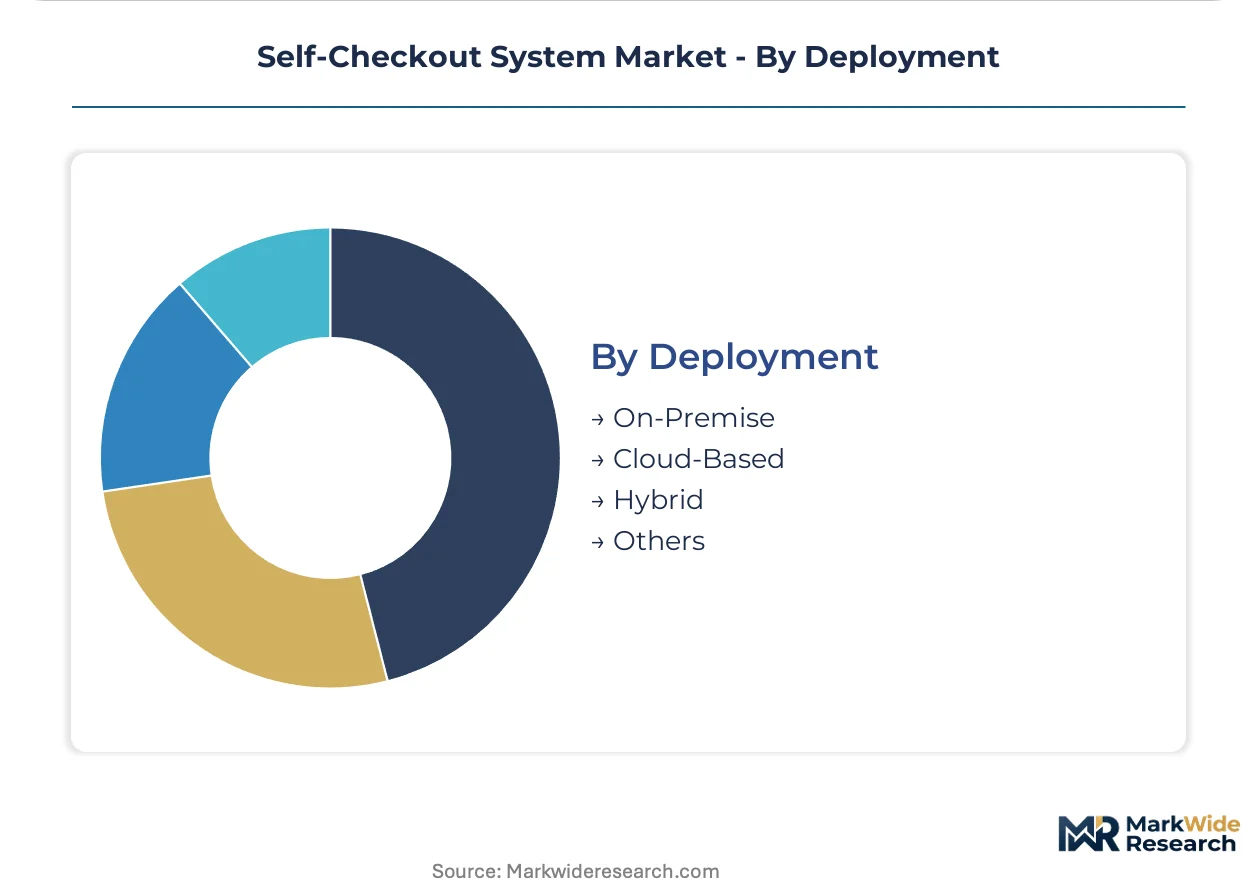
Deployment:
Deployment architecture choices reflect retailer IT maturity and appetite for operational control versus vendor-managed convenience.
- On-Premise:Local server installations with dedicated network segmentation satisfy stringent data sovereignty requirements and minimize external connectivity attack surfaces.
- Cloud-Based:Centralized software update architectures converge with edge-computing capabilities to enable predictive maintenance without on-site technical visits. United States national chains favor this model for fleet-wide pricing integration.
- Hybrid:Mixed configurations process sensitive payment data locally while pushing analytics and inventory synchronization to cloud endpoints.
- Others:Containerized and serverless deployments emerging for retailers with cloud-native infrastructure investments.
Cloud-based deployment is climbing the fastest; hybrid architectures retain appeal among risk-averse operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized retail technology talent clusters in the United States, Germany, and Japan anchor global self-checkout system development, with engineering concentrations in Boston, Stuttgart, and Tokyo driving hardware-software integration capabilities.
United States
National supermarket chains and big-box retailers dominate procurement volumes as wage inflation accelerates capital allocation toward autonomous checkout infrastructure. The Federal Trade Commission monitors checkout automation for employment disclosure effects and consumer pricing transparency requirements. Engineering talent concentrates in the Greater Boston corridor, where computer vision startups and legacy POS vendors collaborate on next-generation kiosk platforms.
Germany
Discount grocery operators and automotive retail chains drive demand for compact terminal form factors with robust loss-prevention capabilities. The EU AI Act's risk classification framework imposes documentation requirements on automated decision systems used in payment authentication. Industrial design expertise clusters in Stuttgart and Munich, where precision engineering traditions translate into durable hardware specifications for high-traffic retail environments.
Japan
Convenience store operators with over 50,000 locations seek frictionless payment integration as labor shortages intensify. METI guidelines on retail automation standardization influence procurement specifications across the sector. Tokyo-based engineering teams specialize in biometric authentication modules and compact touchscreen interfaces optimized for space-constrained urban retail formats.
United Kingdom
Grocery cooperatives and department store chains pursue cloud-native fleet management to synchronize pricing across distributed locations. GDPR compliance requirements shape data handling protocols for customer-facing payment terminals. London fintech clusters collaborate with retail technology vendors on tap-to-pay integration and digital wallet protocol development.
India
Organized retail penetration below ten percent creates first-mover opportunities for vendors establishing local assembly partnerships ahead of format standardization. RBI payment security guidelines and BIS certification requirements govern terminal deployment specifications. Karnataka and Maharashtra host emerging technology partnerships between domestic retailers and international kiosk manufacturers seeking cost-optimized production configurations.
Self-Checkout System Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across hardware manufacturing, payment software, and fleet management services. The vendor base spans three tiers: integrated solution providers with end-to-end portfolios, component specialists concentrating on biometric modules or secure payment elements, and regional fabricators serving localized retail formats. Consolidation among national retail chains concentrates procurement power into fewer buyers who dictate terminal specifications and deployment timelines. Dominant competitive moves include strategic partnerships between hardware manufacturers and cloud platform providers, plus backward integration into secure element semiconductor sourcing.
Within the integrated solution tier, NCR Corporation and Diebold Nixdorf occupy positions that exemplify cross-sector diversification from financial self-service into retail automation. Fujitsu represents the specialized component archetype through its concentrated focus on biometric authentication modules. These three companies anchor the competitive structure while smaller specialists compete on compact form factors and regional customization capabilities.
| Leading Market Players |
|---|
| NCR Corporation |
| Diebold Nixdorf |
| Acrelec |
| Fujitsu |
| Toshiba TEC Corporation |
| Gilbarco Veeder Root |
| ITAB Shop Concept |
| Zebra Technologies |
| Strongpoint |
| Others |
Supply Flow & Price Mechanics
Computer vision engineering talent concentration in the Greater Boston corridor widens pricing-tier spreads between premium AI-enabled terminals and standard barcode-dependent units as labor-cost differentials between US and East Asian manufacturing feed into procurement decisions.
Pricing Analysis
The bundled-vs-unbundled service split now defines competitive positioning as buying committees at national chains separate hardware procurement from software licensing. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with PCI-DSS validated modules commanding substantial premiums over uncertified alternatives. Cost compression in the standard tier is intensifying because semiconductor supply constraints force vendors to absorb margin erosion. Convenience store operators exhibit highest price sensitivity due to thin merchandise margins, while supermarket chains prioritize total cost of ownership over upfront capital expenditure.
Supply Chain Analysis
Warehouse-distribution layer configurations favor hub-and-spoke patterns anchored in regional distribution centers near major retail clusters in Texas, Ohio, and California. Manufacturing draws from Taiwan for touchscreen controllers, South Korea for secure element processors, and China for structural enclosures. Touchscreen controller semiconductors, secure payment modules, and weighing scale load cells constitute critical input dependencies. Single-source vulnerability in East Asian foundry capacity exposes deployment timelines to geopolitical disruption. Distribution runs through direct OEM relationships with national retail chains, supplemented by value-added resellers serving mid-market independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as supermarket operators shift procurement criteria toward hardened payment architectures and computer vision capabilities that command premium positioning.
For Market Incumbents: Anchor defensive positioning through backward integration into secure element semiconductor sourcing and captive production of biometric authentication modules. NIST cybersecurity framework mandates and PCI-DSS certification timelines create replacement demand that favors vendors with pre-validated encryption architectures. Cloud-native fleet management platforms represent the critical R&D lever for sustaining recurring revenue streams against hardware commoditization.
For New Entrants and Emerging Players: Begin with convenience store automation as the most penetrable segment, where over 150,000 US locations remain minimally automated and procurement committees lack technical integration capabilities. Compact terminal form factors with plug-and-play deployment satisfy space constraints and limited IT staffing. A channel partner go-to-market angle through petroleum equipment distributors bypasses direct competition with entrenched supermarket vendors.
For Investors and Strategic Acquirers: Cloud platform providers represent the most active acquirer category in this space as they seek edge-computing deployment footprints in physical retail. The long-term viability window favors vendors with software recurring revenue exceeding fifty percent of total mix. Acquisition target archetypes include computer vision startups with produce recognition IP and regional fabricators with established convenience store channel relationships. The signal to watch as inflection indicator is unbundled RFP proliferation separating hardware, payment gateway, and fleet management procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Biometric Authentication Module Development | Fujitsu's specialized capabilities demonstrate premium pricing power in friction-reduction applications. |
| Cloud-Native Fleet Management Platform Launch | Centralized update architectures enable predictive maintenance without on-site technical visits across distributed retail locations. |
| Convenience Store Channel Partnership | Petroleum equipment distributors provide established routes to 150,000 underpenetrated US locations. |
| Secure Element Backward Integration | Captive sourcing of payment processors mitigates East Asian foundry concentration risks. |
| Computer Vision Produce Recognition Acquisition | Albertsons and Kroger pilot deployments validate grab-and-go checkout as format-standardizing technology. |
Methodological Framework
Multiple input streams — executive interviews with retail technology procurement officers, technical discussions with POS integration specialists, and validation sessions with cloud platform engineering leads — were reconciled against secondary sources including SEC 10-K filings, FTC regulatory dockets, and PCI-DSS certification databases. Bottom-up terminal deployment tallies by retail chain were cross-referenced with top-down market sizing derived from semiconductor shipment data and payment processor volume disclosures.
Historical deployment trajectories were cross-referenced against panel input from supermarket operators and convenience store franchise systems across the analysis window. Segmentation dimensions modeled include terminal form factor, deployment architecture, end-user format, and technology maturity tier. CAGRs were derived from regression analysis of capital expenditure patterns correlated with wage inflation indices and regulatory compliance deadlines. Industry-specific forecast inputs encompass NIST framework adoption timelines and state-level biometric privacy legislation progression.
Several conditions sit outside the modeled scope, including speculative breakthroughs in RFID tag economics and unannounced merger activity among national retail chains. Forecasts reflect documented assumptions regarding semiconductor supply normalization and PCI-DSS certification cycle durations. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Alternative Retailing Technologies Market
Retail Technology
Ticket Machine Market
Retail Technology
Smart Shelf Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Global Kiosk Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Digital Kiosk Market
Retail Technology
America's AI in the Retail Market