
 Self-Checkout in Retail Market | 2026-2036
Self-Checkout in Retail Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Checkout in Retail Market Analytics
China is fragmenting as domestic kiosk manufacturers scale production for both local hypermarkets and export markets. NCR Corporation leverages its software-hardware integration to sustain recurring revenue streams across North American grocery chains. Toshiba Global Commerce Solutions anchors its position through deep relationships with Japanese convenience store operators, while Fujitsu competes on computer vision accuracy for high-theft retail environments.
Self-checkout in retail encompasses automated point-of-sale terminals that integrate barcode scanning, weight verification sensors, and payment processing modules to enable customer-initiated transactions without cashier assistance. These systems typically operate on embedded Linux or Windows IoT platforms with touchscreen interfaces ranging from 15 to 22 inches, designed to reduce labor expenditure and queue times in high-volume retail settings. Standalone Units dominate current installation bases due to lower capital requirements and retrofit compatibility, though Hybrid Systems represent the fastest-growing category as retailers blend fixed kiosks with mobile app workflows. Computer Vision technology commands premium positioning as it enables scan-free item recognition, while Barcode Scanners remain the margin-dense workhorse across price-sensitive deployments.
FDA guidelines on payment security intersect with PCI DSS standards to shape hardware certification requirements for pharmacy self-checkout terminals in the United States. The EU AI Act imposes risk-classification obligations on automated decision systems, compelling European retailers to document algorithmic transparency for their computer vision loss-prevention modules. Stakeholders must weigh capital deployment timing against evolving biometric consent frameworks and emerging state-level privacy statutes that could restrict facial recognition integration in retail settings.
Market Dynamics
The retail self-checkout sector is undergoing a fundamental restructuring as computer vision systems displace legacy barcode infrastructure, forcing hardware vendors to reconfigure their product architectures around AI-enabled loss prevention and frictionless item recognition.
Growth Catalysts
- EU AI Act compliance mandates:European retailers are accelerating deployment of auditable computer vision modules to meet risk-classification obligations for automated decision systems in loss prevention.
- Grocery chain labor optimization:US hypermarket operators are expanding kiosk footprints to reduce cashier headcount and compress checkout queue times during peak traffic periods.
- Weight-verification sensor advances:Improved load-cell precision is reducing shrinkage incidents and enabling broader adoption across high-theft merchandise categories.
Market Restraints
- Semiconductor supply concentration:Embedded processor shortages concentrated in Taiwanese fabrication facilities are extending lead times for kiosk motherboard production.
- PCI DSS certification friction:Payment terminal hardware must undergo multi-quarter validation cycles, delaying deployment timelines for new market entrants.
- Mobile wallet substitution:Smartphone-based scan-and-go applications are capturing transaction volume in urban retail environments with high digital-native customer bases.
Strategic Opportunities
- Japanese convenience store automation:Dense urban retail networks in Tokyo and Osaka present untapped demand for compact footprint hybrid checkout systems.
- GDPR-aligned biometric consent frameworks:Retailers implementing opt-in facial recognition for loyalty programs can access premium customer analytics while maintaining regulatory defensibility.
- Convergence of RFID and computer vision:Dual-technology authentication architectures are opening high-value apparel and electronics verticals previously resistant to self-checkout adoption.
Industry Challenges
- Embedded Linux firmware expertise scarcity:Kiosk manufacturers face recruitment bottlenecks for engineers capable of hardening IoT platforms against payment card industry intrusion vectors.
- Legacy POS integration complexity:Retailers with decades-old enterprise resource planning systems encounter data synchronization failures when bridging mainframe inventory databases to cloud-connected self-checkout terminals.
- ISO 9001 quality management recertification:Hardware vendors expanding production lines must navigate extended audit timelines that constrain capacity scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Checkout in Retail Market |
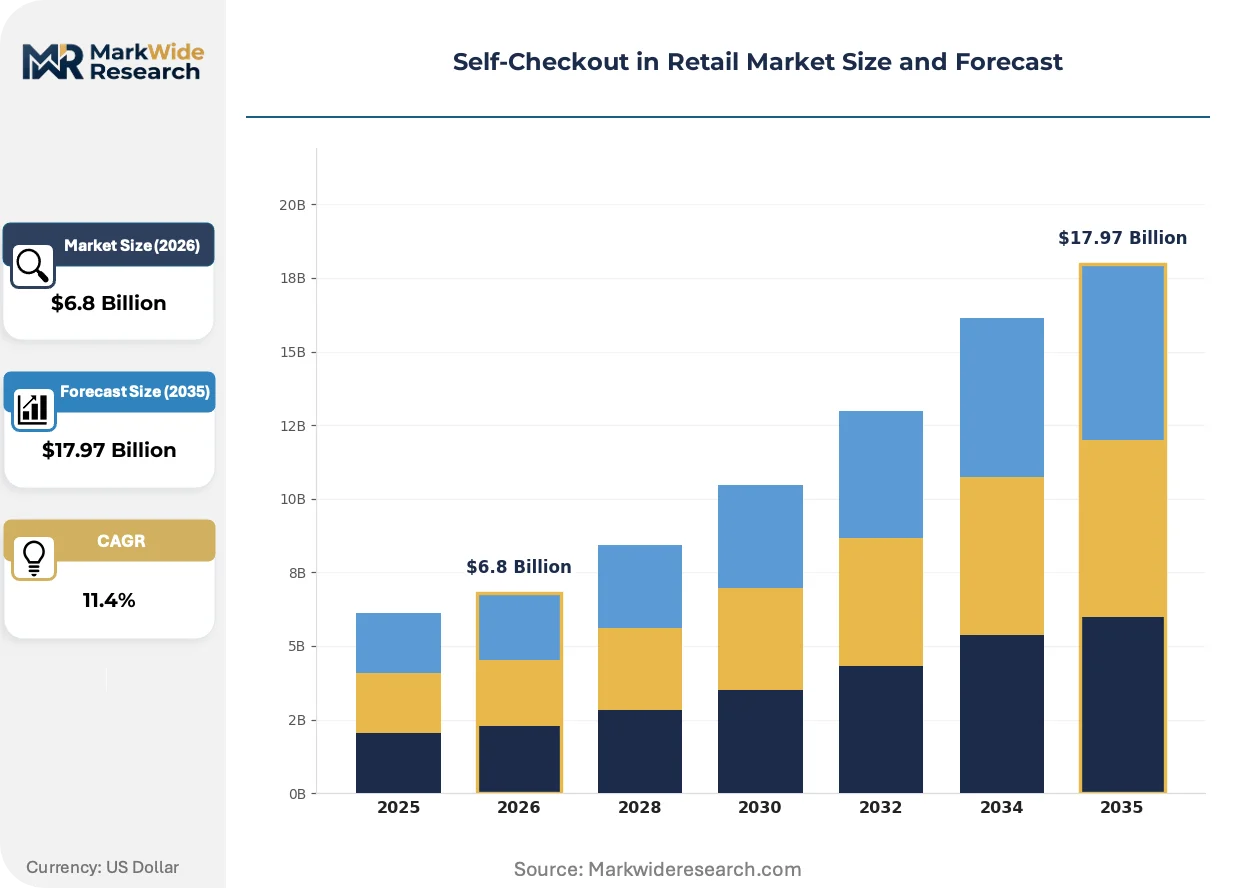
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Units, Integrated Kiosks, Mobile Apps, Hybrid Systems Technology: RFID, Computer Vision, Barcode Scanners, Machine Learning End User: Grocery Stores, Hypermarkets, Pharmacies, Convenience Stores Deployment: In-Store, Online, Mixed Use, Pilot Programs |
| Companies Covered | NCR Corporation, Diebold Nixdorf, Toshiba Global Commerce Solutions, Fujitsu, ITAB Group, StrongPoint, Pan Ostan, Gilbarco Veeder-Root, Pyramid Computer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Checkout in Retail Market Evolving Landscape
Retail checkout infrastructure is pivoting from transaction processing toward customer intelligence capture, with sensor fusion and edge computing architectures enabling real-time behavioral analytics that reshape loss prevention and merchandising workflows.
Computer vision-based item recognition is digitizing product identification workflows by eliminating manual barcode scanning through neural network-trained camera arrays. Grocery chains in the United States are deploying these systems at scale to reduce friction in produce and bulk goods transactions. The technology is digitizing inventory tracking accuracy while compressing transaction times for irregular-shaped merchandise categories previously resistant to automation.
The EU AI Act risk-classification framework is imposing documentation burdens on algorithmic transparency for automated decision systems deployed in European retail environments. Retailers must now maintain technical files demonstrating human oversight capabilities for computer vision modules used in theft detection. German and French supermarket operators are responding by segregating AI-enabled checkout lanes from standard kiosks to simplify compliance scope and audit trails.
Buyer procurement patterns are consolidating around integrated hardware-software contracts that bundle kiosk hardware with multi-year SaaS maintenance agreements. Independent grocery cooperatives and mid-size regional chains are displacing fragmented point-solution purchasing in favor of single-vendor partnerships covering deployment, training, and remote diagnostics. This concentration is most visible in the US Midwest, where buying groups are negotiating enterprise-wide rollouts across hundreds of affiliated store locations.
Self-Checkout in Retail Market Segmentation
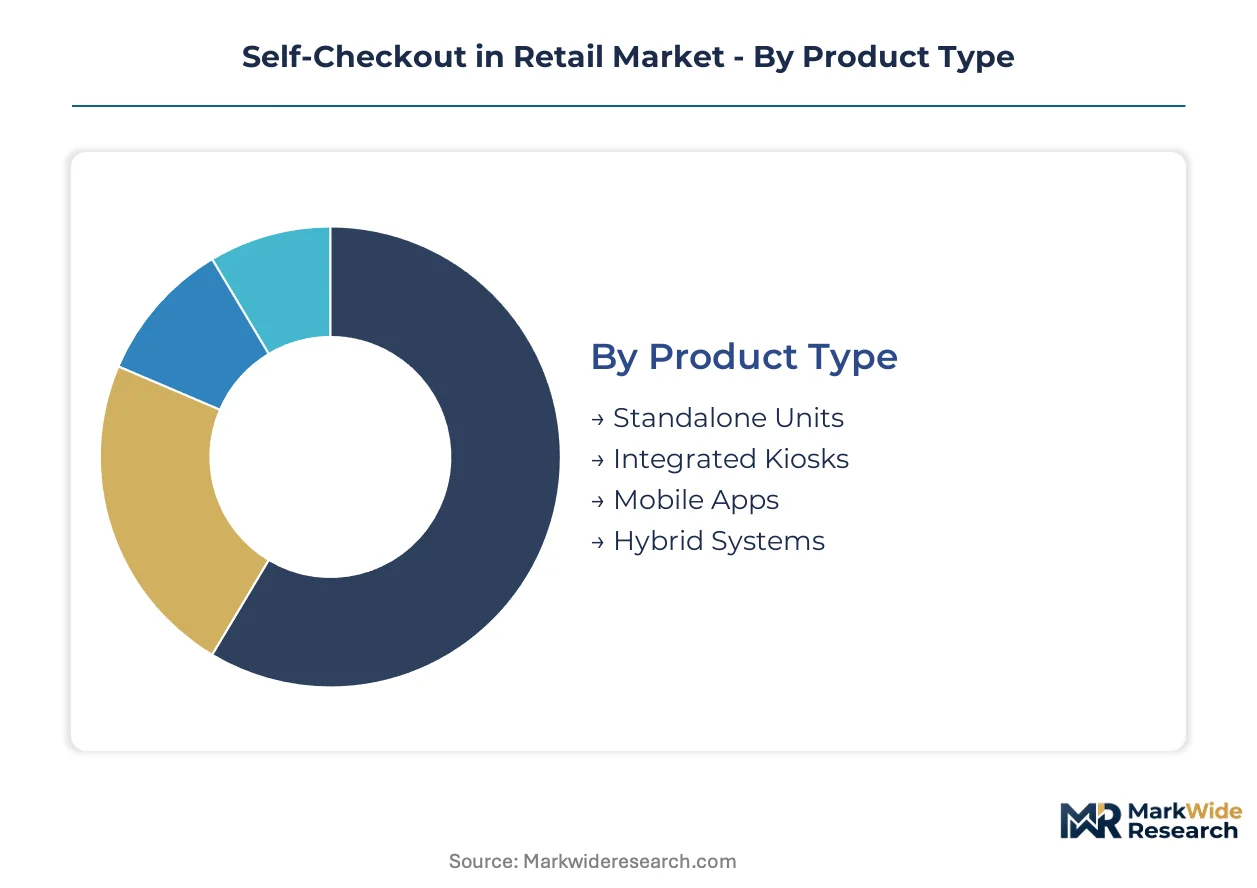
Self-checkout segmentation determines service contract structures and replacement cycle timing. Hardware-software bundles require distinct maintenance protocols versus standalone kiosk deployments. Retailers align procurement decisions with traffic density, merchandise theft risk, and existing POS infrastructure age.
Product Type:
After-sales-service intensity varies sharply across product architectures, with integrated systems demanding multi-year technical support contracts and standalone units operating on break-fix models.
- Standalone Units:Modular kiosk enclosures housing payment terminals, receipt printers, and weight scales in self-contained footprints. US grocery chains favor these for rapid retrofit of legacy checkout lanes without structural modifications. Service intensity concentrates on card reader replacement and touchscreen calibration cycles.
- Hybrid Systems:Architectures blending fixed kiosk hardware with smartphone-enabled scan-and-go workflows through cloud-synchronized inventory databases. German hypermarket operators deploy these to capture loyalty program data while reducing capital expenditure per transaction point. These configurations generate recurring SaaS revenue streams that alter vendor-customer contracting dynamics.
- Integrated Kiosks:Custom-fabricated terminals embedded directly into store fixtures with dedicated power and network infrastructure.
- Mobile Apps:Smartphone-based checkout workflows bypassing dedicated hardware entirely.
Standalone Units hold the largest share; momentum sits with Hybrid Systems.
Technology:
Technology selection drives sensor replacement schedules and firmware update frequencies, with vision-based systems requiring more intensive field calibration than legacy scanning approaches.
- Computer Vision:Neural network-trained camera arrays performing real-time item recognition without barcode scanning, deployed primarily in produce and bulk goods departments. French retailers accelerate adoption under EU AI Act documentation requirements for algorithmic transparency in automated decision systems. The technology commands premium hardware pricing but reduces shrinkage in high-theft categories through behavioral anomaly detection.
- Barcode Scanners:Laser or imager-based modules reading UPC and EAN symbologies with millisecond response times. Japanese convenience store operators standardize on these for reliability in high-volume, low-margin environments where capital constraints limit AI infrastructure investment. Margin density remains superior due to mature supply chains and minimal firmware complexity.
- RFID:Radio-frequency identification tags enabling bulk scanning of entire shopping baskets.
- Machine Learning:Algorithmic modules optimizing transaction flow and fraud detection through pattern recognition.
Barcode Scanners dominate installed base; Computer Vision is climbing the fastest.
End User:
End-user verticals dictate loss-prevention sensitivity and checkout throughput requirements, with pharmacies facing stricter payment security protocols than general merchandise retailers.
- Grocery Stores:High-frequency, low-margin environments with diverse product formats including weighted produce and alcohol age-verification workflows. US regional chains prioritize these deployments for labor cost reduction during peak evening traffic periods.
- Hypermarkets:Large-format retailers combining grocery, general merchandise, and apparel under single roofs. Walmart and Target in the United States anchor demand here, driving thousand-unit rollout contracts that reshape vendor capacity planning.
- Convenience Stores:Compact-footprint urban locations with space constraints and 24-hour operation requirements.
- Pharmacies:Healthcare-adjacent retail subject to FDA payment security guidelines and HIPAA-adjacent privacy considerations.
Grocery Stores command the greatest deployment volume; Convenience Stores present the steepest expansion trajectory.
Deployment:
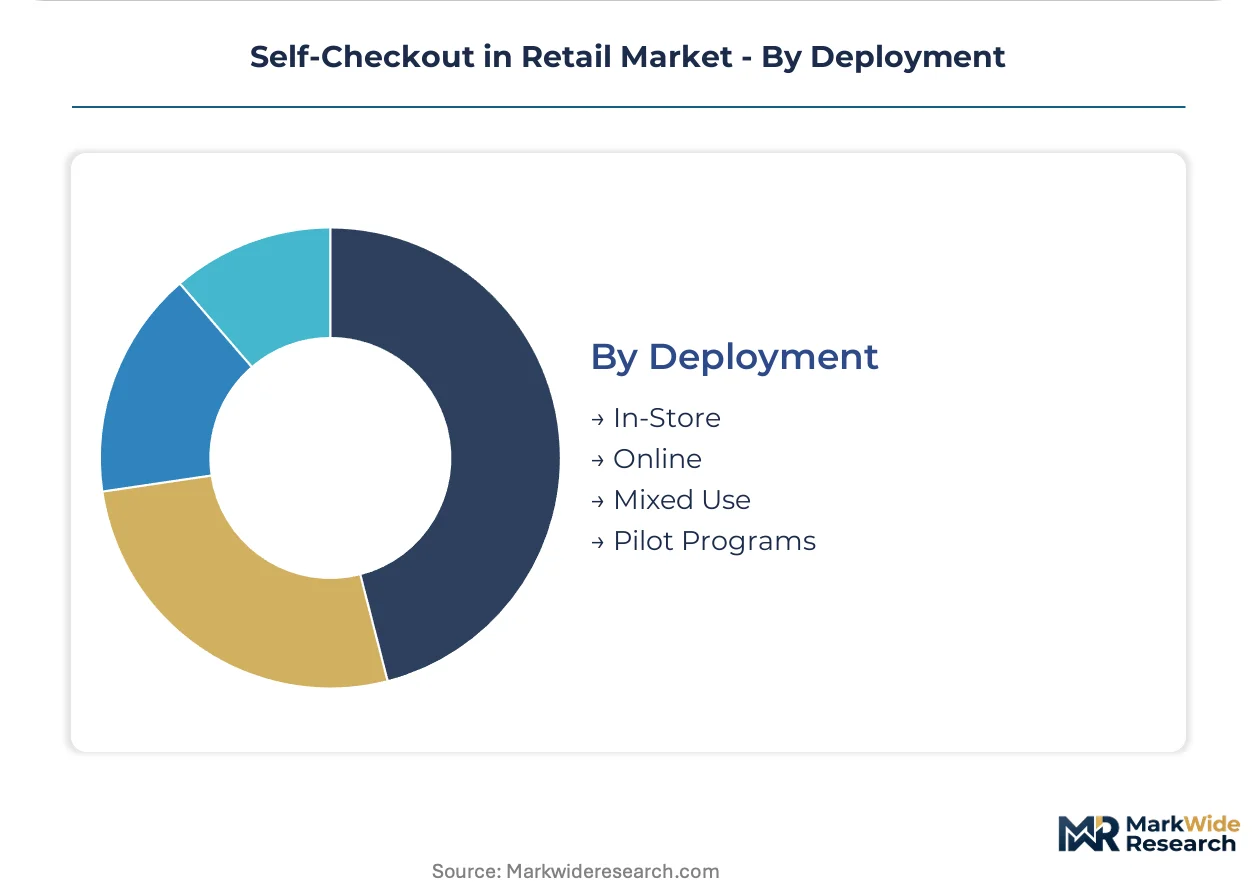
Deployment modality determines capital recognition timing and pilot-to-production conversion rates, with mixed-use architectures complicating ROI measurement.
- In-Store:Permanent fixture installations with multi-year depreciation schedules and dedicated electrical infrastructure. US big-box retailers standardize on this approach for predictable throughput gains and centralized loss prevention monitoring.
- Pilot Programs:Limited-scale trials in 5-15 location cohorts testing technology fit before enterprise commitment. UK grocery cooperatives favor these for risk mitigation when evaluating computer vision modules under evolving GDPR biometric consent frameworks.
- Mixed Use:Configurations alternating between staffed and self-service lanes based on traffic patterns.
- Online:E-commerce-integrated pickup and return processing through automated lockers or curbside terminals.
In-Store captures the dominant investment share; Pilot Programs are gaining share fastest as retailers delay full commitments amid regulatory uncertainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded processor fabrication concentrates in Taiwanese facilities, extending lead times for kiosk motherboard production across all major retail markets. Vendors navigate divergent regulatory frameworks as the EU AI Act imposes algorithmic transparency mandates while the United States prioritizes PCI DSS payment security certification.
United States
Walmart and Target drive thousand-unit rollout contracts across hypermarket formats, compressing checkout queue times during peak evening traffic. FDA guidelines intersect with PCI DSS standards to shape hardware certification requirements for pharmacy self-checkout terminals. Retail technology clusters concentrate in the Midwest, where buying groups negotiate enterprise-wide deployments across hundreds of affiliated store locations.
Germany
Hypermarket operators deploy hybrid systems to capture loyalty program data while reducing capital expenditure per transaction point. The EU AI Act compels retailers to document algorithmic transparency for computer vision loss-prevention modules, with German operators segregating AI-enabled checkout lanes to simplify compliance scope. Industrial automation expertise concentrates in Bavaria, where kiosk manufacturers integrate sensor fusion architectures for real-time behavioral analytics.
China
Domestic kiosk manufacturers scale production for both local hypermarkets and export markets, fragmenting supply-side concentration. The country's national standards regulator imposes GB certification requirements on payment terminal hardware entering commercial deployment. Production gravity clusters in the Yangtze River Delta, where fabricators source embedded Linux platforms and touchscreen assemblies for cost-optimized standalone units.
Japan
Convenience store operators standardize on barcode scanner reliability in high-volume, low-margin environments where capital constraints limit AI infrastructure investment. METI guidelines shape quality management expectations for IoT platform hardening against payment card industry intrusion vectors. Dense urban retail networks in Tokyo and Osaka present untapped demand for compact footprint hybrid checkout systems with 24-hour operation capability.
United Kingdom
Grocery cooperatives favor pilot programs in 5-15 location cohorts for risk mitigation when evaluating computer vision modules under evolving GDPR biometric consent frameworks. The national data protection regulator enforces strict documentation requirements for automated decision systems processing customer behavioral data. Technology procurement clusters in London and the Southeast, where retailers test convergence architectures blending RFID and computer vision for high-value apparel verticals.
Self-Checkout in Retail Market Competitive Landscape
Integrated hardware-software providers and modular component specialists split the market into distinct contracting ecosystems. Procurement patterns consolidate around bundled maintenance agreements, displacing fragmented point-solution purchasing among mid-size regional chains. Three archetypes dominate: full-stack platform vendors capturing enterprise rollouts, component-focused fabricators serving retrofit installations, and SaaS-anchored specialists monetizing recurring diagnostics revenue. Competitive intensity centers on M&A activity consolidating regional service networks and strategic partnerships bridging legacy POS integration gaps.
Within the full-stack platform tier, NCR Corporation and Toshiba Global Commerce Solutions occupy positions exemplifying software-hardware integration strategies. Diebold Nixdorf anchors the financial services-adjacent segment with payment terminal heritage. Fujitsu represents the computer vision accuracy specialization targeting high-theft retail environments. These three companies collectively illustrate how vendor origin—Atlanta-based, Tokyo-based, and Kawasaki-based respectively—correlates with regional customer relationship density and service network configuration.
| Leading Market Players |
|---|
| NCR Corporation |
| Diebold Nixdorf |
| Toshiba Global Commerce Solutions |
| Fujitsu |
| ITAB Group |
| StrongPoint |
| Pan Ostan |
| Gilbarco Veeder-Root |
| Pyramid Computer |
| Others |
Value Network & Pricing Analysis
Tariff exposure on Taiwanese semiconductor imports determines both pricing tier spreads and supply chain shape in the self-checkout hardware sector, compressing margins on computer vision-enabled systems while forcing vendors toward dual-sourcing strategies for embedded Linux motherboards.
Pricing Analysis
The EU AI Act dictates the pricing tier structure across European deployments, mandating algorithmic transparency documentation that adds compliance costs to computer vision modules. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because grocery cooperatives are consolidating procurement around integrated hardware-software contracts. Independent regional chains exhibit the highest price sensitivity, while Walmart-scale hypermarket operators prioritize throughput metrics over unit cost.
Supply Chain Analysis
Hon Hai Precision Industry and Pegatron hold dominant contract manufacturing capacity for kiosk enclosures and touchscreen assemblies. Production gravity clusters in China, Taiwan, and Vietnam, with embedded processor fabrication drawing from TSMC facilities in Hsinchu. Supply chain risk centers on single-source vulnerability for neural network accelerators used in computer vision modules. Distribution runs through OEM direct sales for enterprise rollouts and regional systems integrators for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
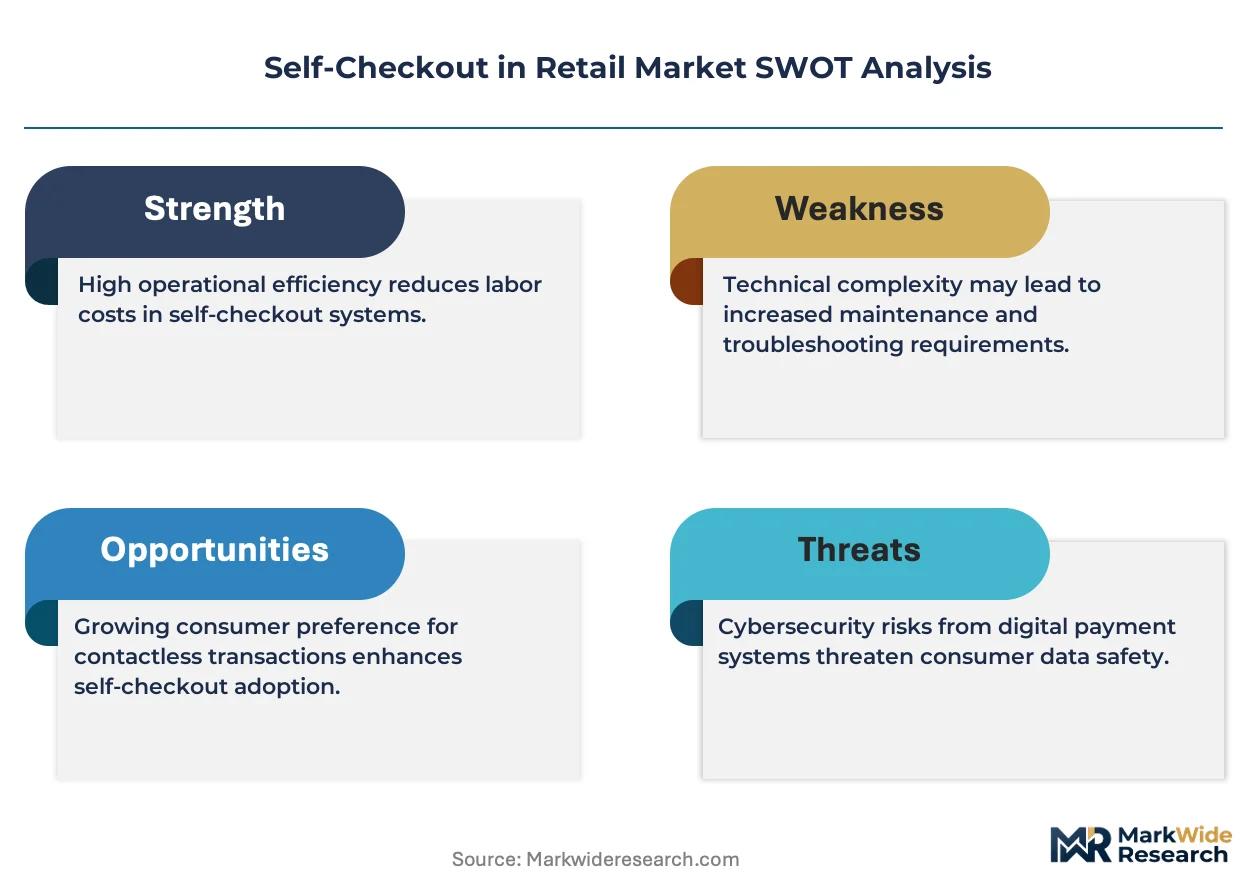
Mobile wallet substitution threatens dedicated kiosk demand, requiring incumbents to defend installed base through software-hardware integration moats while new entrants exploit white-space in Japanese convenience store automation.
For Market Incumbents: Build switching-cost moats through multi-year SaaS maintenance agreements that embed remote diagnostics and firmware update pipelines. Consolidate regional service networks to reduce break-fix response times below four hours for grocery chain SLAs. Counter mobile wallet substitution by anchoring computer vision modules as loss-prevention infrastructure rather than pure transaction processing. For New Entrants and Emerging Players: Build out compact-footprint hybrid systems targeting Tokyo and Osaka convenience store operators, where 24-hour operation requirements and space constraints have delayed automation adoption. Penetrate the UK grocery cooperative segment through pilot program partnerships that demonstrate GDPR-compliant biometric consent frameworks. Lead with RFID-computer vision convergence architectures to differentiate from barcode-dominated incumbent offerings. For Investors and Strategic Acquirers: Computer vision software specialists with proven algorithmic accuracy in high-theft retail environments represent the most defensible acquisition profile. Long-term viability hinges on regulatory compliance capabilities as the EU AI Act risk-classification framework expands to additional member states. Monitor PCI DSS certification queue lengths as an inflection indicator for hardware vendor capacity constraints and pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Documentation capabilities unlock German and French hypermarket procurement pipelines. |
| Hybrid System Platform Launch | Smartphone integration captures loyalty data while reducing capital per transaction point. |
| Computer Vision Accuracy Investment | Neural network training reduces shrinkage in produce departments for US grocery chains. |
| Regional Service Network Acquisition | Midwest US coverage density secures buying group enterprise rollout contracts. |
| RFID-Vision Convergence Partnership | Dual-technology authentication opens apparel and electronics verticals previously resistant to automation. |
Research Methodology
A standing panel of kiosk hardware procurement managers, grocery chain IT directors, computer vision engineering leads, and payment security compliance officers provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against PCI DSS certification databases, EU AI Act implementation guidance, and SEC filings from publicly traded retail technology vendors. Bottom-up unit deployment tallies triangulated against top-down grocery industry capital expenditure surveys.
Scenario bracketing anchored the analytical framework across the projection horizon, modeling adoption curves by product type, technology tier, end-user vertical, and deployment modality. CAGRs derived from logistic diffusion curves fitted to historical kiosk installation data, with neural network training cost trajectories and semiconductor supply elasticity as key industry-specific inputs.
Sensitivities concentrate around EU AI Act enforcement timelines and Taiwanese fab capacity allocation decisions. Forecasts reflect documented assumptions on labor cost inflation trajectories and mobile wallet substitution rates. Quarterly review of PCI DSS certification queue lengths and German hypermarket pilot-to-production conversion rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Cash Register Machines Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Self-Checkout System Market
Retail Technology
US Self-Checkout Systems Market
Retail Technology
Global Kiosk Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Self-Service Market
Retail Technology
Smart Shelves Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
AR in Retail Market
Retail Technology
Smart Shopping Cart Market
Retail Technology
Connected Retail Market
Retail Technology
Digital Kiosk Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Smart Retail Systems Market