
 Smart Grocery Cart Market | 2026-2036
Smart Grocery Cart Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Grocery Cart Market Insights
GDPR enforcement in Europe is pivoting the cost-of-entry calculus for smart cart vendors that process biometric and behavioral data at scale. Amazon leverages its cloud infrastructure to sustain edge-computing deployments across grocery footprints. Walmart anchors North American rollout velocity through its captive store network and direct supplier relationships.
Smart grocery carts integrate sensor arrays, onboard weighing systems, and real-time payment terminals to automate item recognition and checkout within retail environments. RFID-enabled product identification and IoT connectivity constitute core technical architectures, with mobile app integration serving as the dominant consumer-facing interface layer. Self-checkout carts occupy the largest installed base among product types, while smart carts with personalization engines capture the fastest expansion trajectory as retailers prioritize basket-size optimization. Supermarkets dominate end-user deployment, though convenience stores represent an emerging margin pool due to smaller-format automation economics.
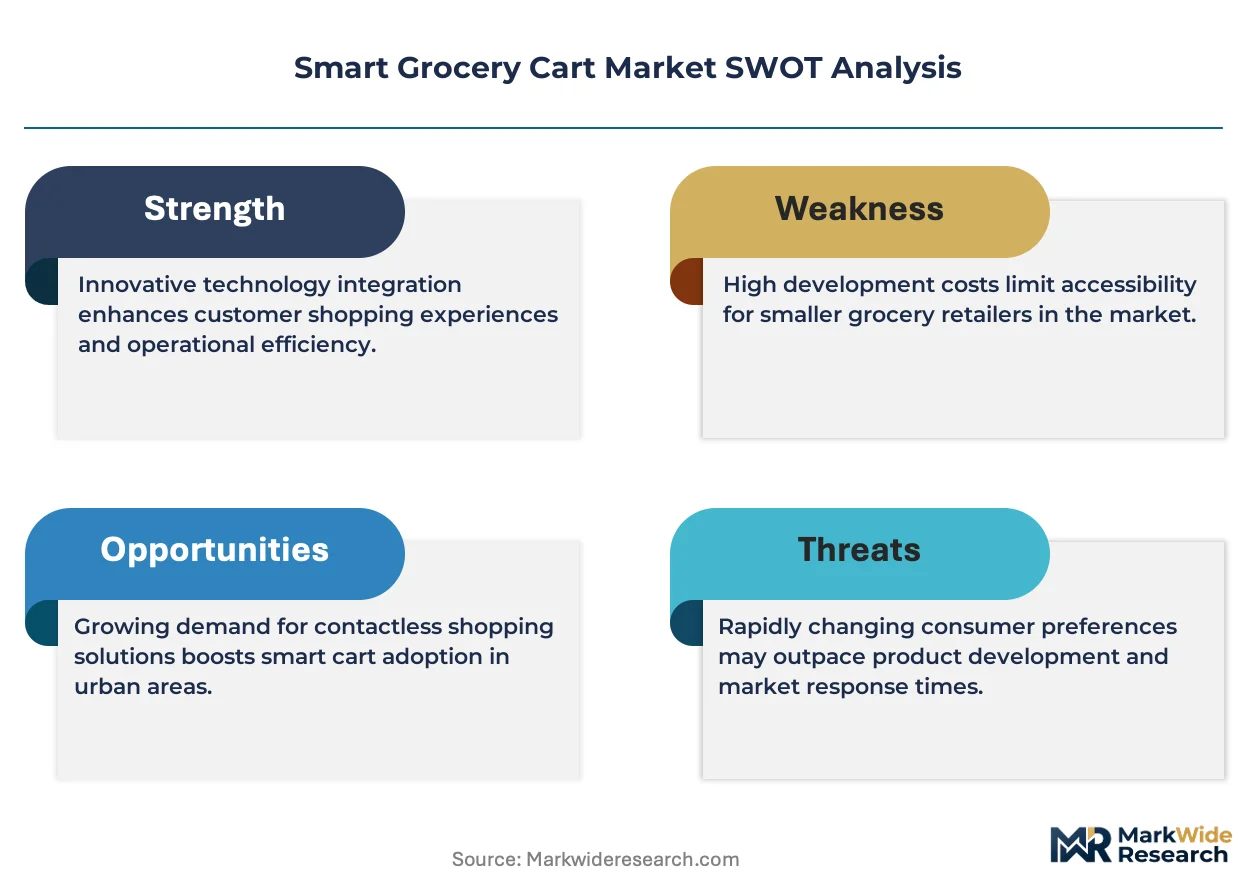
FDA guidelines on consumer-facing biometric data collection, FCC rules governing IoT device spectrum allocation, and the EU AI Act's risk-classification framework collectively shape product standards and market access conditions for smart cart manufacturers. Retailers must navigate divergent compliance obligations across jurisdictions where data governance and device certification requirements lack harmonization. Stakeholders should monitor regulatory convergence dynamics between data privacy mandates and retail automation incentives to anticipate deployment timeline shifts.
Market Dynamics
EU AI Act risk-classification rules are forcing smart cart vendors to reengineer computer vision architectures before 2026 deployment windows close. Retailers now face parallel compliance tracks across biometric data handling, edge computing certification, and cross-border data transfer protocols.
Growth Catalysts
- Labor Cost Compression:US supermarket chains deploy automated checkout carts to offset wage inflation in high-turnover frontline roles.
- GDPR-Driven Vendor Consolidation:European retailers favor established players with certified data governance frameworks over unproven entrants.
- RFID Infrastructure Maturation:Item-level tagging economics in apparel and grocery categories enable seamless cart-based recognition without computer vision dependency.
Market Restraints
- Semiconductor Supply Concentration:Edge AI chip fabrication relies on Taiwan-based foundry capacity subject to geopolitical disruption.
- FCC Spectrum Allocation Uncertainty:IoT device certification delays in the 6 GHz band stall nationwide rollout timelines for connected cart fleets.
- Mechanical Durability Thresholds:Onboard weighing systems fail calibration standards in high-humidity environments, limiting tropical market viability.
Strategic Opportunities
- Convenience Store Automation:Smaller-format retailers in Japan and South Korea pilot compact cart systems for 24-hour unmanned operations.
- EU Green Deal Procurement Incentives:Member state retailers gain preferential financing for energy-efficient cart fleets meeting Ecodesign criteria.
- Mobile Wallet Convergence:Integration with super-app payment ecosystems in Southeast Asia bypasses legacy POS infrastructure entirely.
Industry Challenges
- Embedded Systems Talent Scarcity:Firmware engineering for real-time sensor fusion commands premium compensation beyond mid-tier vendor budgets.
- Retrofit Integration Complexity:Legacy store layouts require structural modifications to accommodate cart charging stations and lane width requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Grocery Cart Market |
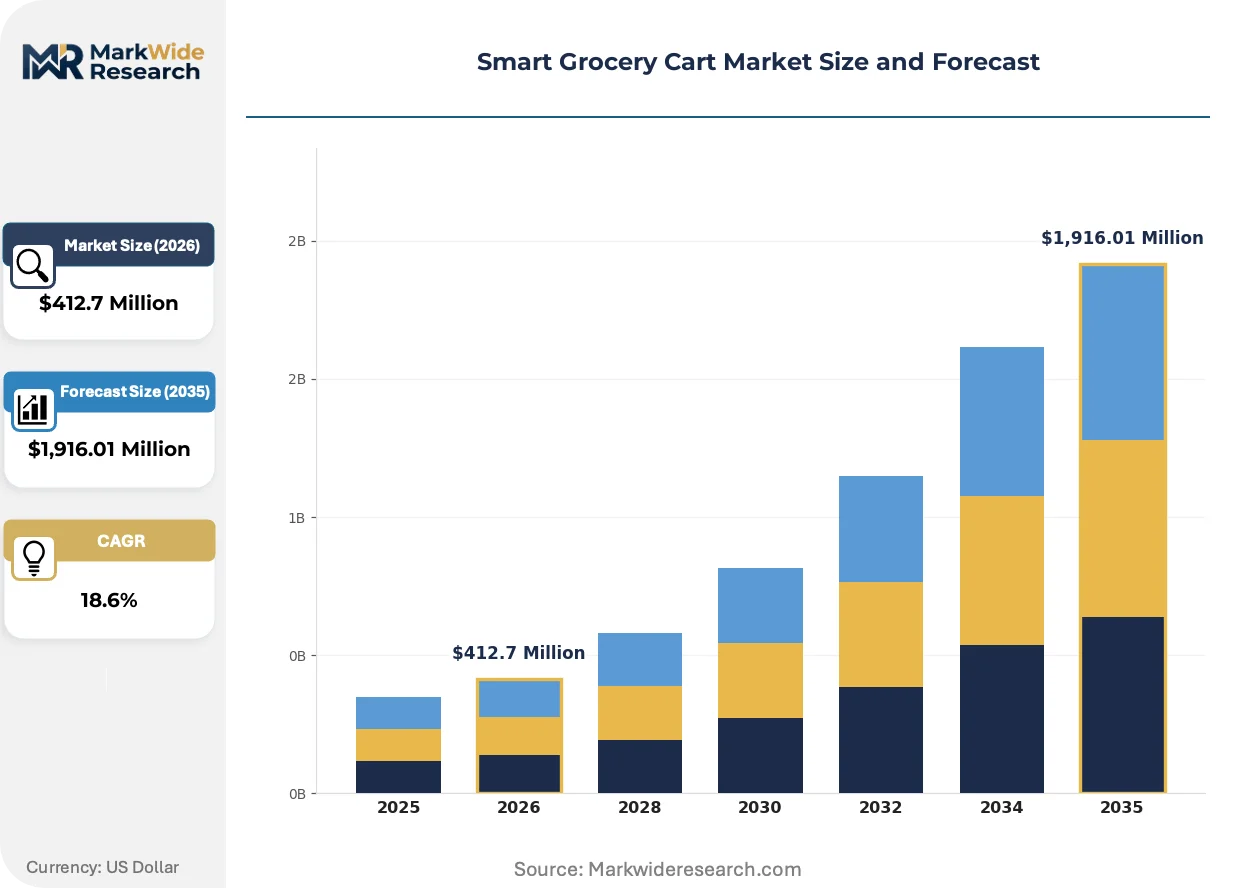
| Market Size in 2026 | $412.7 Million |
| Market Size in 2035 | $1,916.01 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Checkout Carts, Smart Carts, Standard Carts, Mobile Carts Technology: RFID, IoT, Barcode Scanning, Mobile App Integration End User: Supermarkets, Hypermarkets, Convenience Stores, Online Retailers Feature: Cart Tracking, Smart Checkout, Personalization, Inventory Management |
| Companies Covered | Retail AI, Walmart, Amazon, IBM, Panasonic, Caper, Shopic, Fujitsu, SuperHii, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Grocery Cart Market Trends and Innovations
Computer vision architectures are migrating from cloud-dependent processing to edge-native inference, compressing latency and data transfer costs simultaneously. This shift reconfigures vendor competitive moats around silicon efficiency rather than cloud scale.
Edge-native inference chips are overtaking GPU-based cloud processing as the dominant compute paradigm in smart cart deployments. Mid-size supermarket chains in Germany and France now specify onboard inference as a procurement requirement. This compression of data gravity is overtaking Amazon Web Services' early architectural advantage in retail edge computing.
EU AI Act high-risk system obligations trigger mandatory conformity assessments for biometric identification functions in retail environments. Manufacturers must document algorithmic accuracy benchmarks and human oversight protocols before CE marking. French and Italian retailers delay pilot programs pending notified body certification timelines.
Friction-reduction mandates from US grocery headquarters are compressing traditional RFP cycles from eighteen months to ninety days. Category managers now prioritize vendors with pre-certified hardware platforms over custom development proposals. This acceleration is most visible in California and Texas metropolitan markets where labor arbitrage pressures peak.
Smart Grocery Cart Market Segmentation
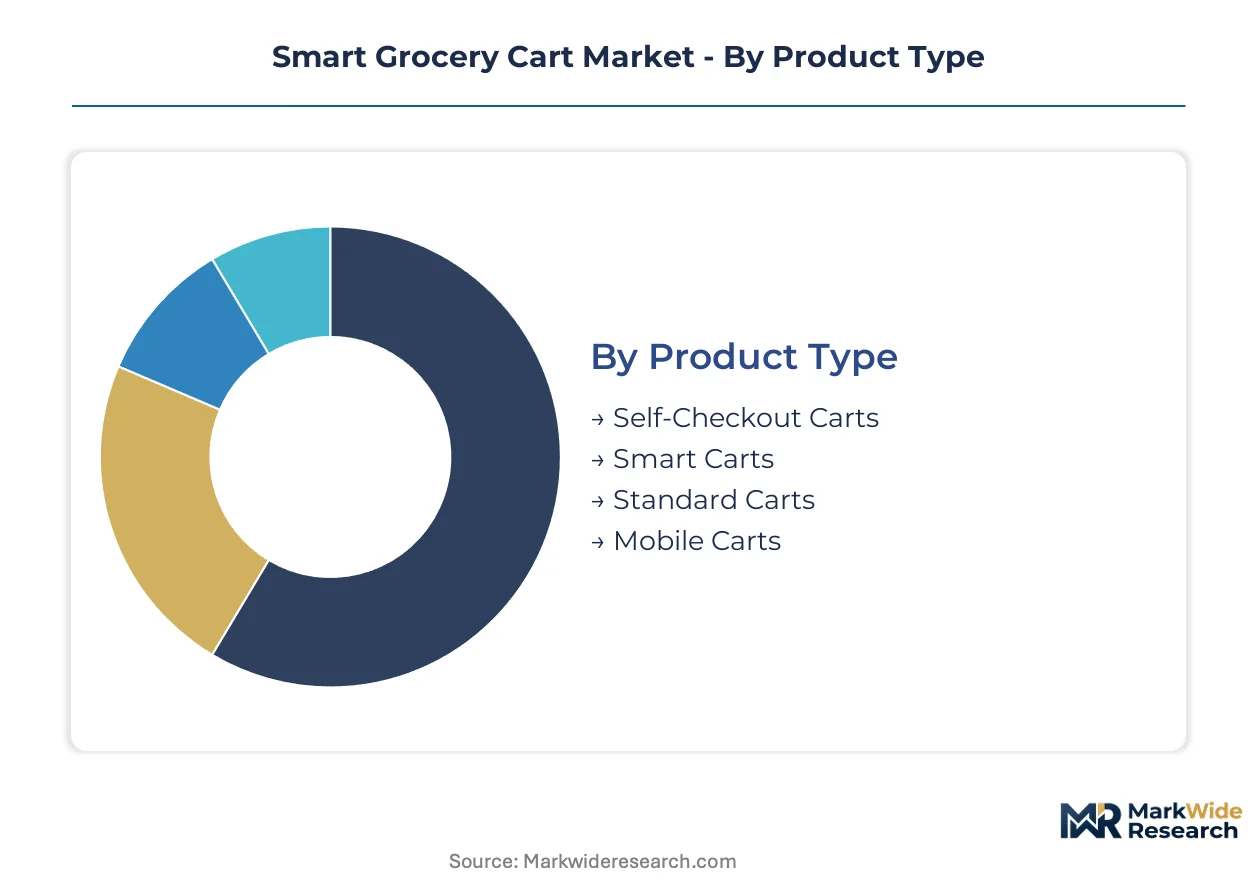
Smart grocery cart architectures fragment across hardware configurations, data protocols, and retail workflow integrations. Procurement committees weight total cost of ownership against checkout throughput gains and data monetization potential when mapping vendor capabilities to format requirements.
Product Type:
Standardization dominates basic cart fleets while sensor-embedded variants demand bespoke integration engineering.
- Self-Checkout Carts:Embedded payment terminals and weighing scales automate transaction completion without lane queuing. US supermarket chains in California and Texas deploy these units to compress labor hours at front-end operations.
- Smart Carts:Sensor arrays enable real-time item recognition, basket tracking, and personalized recommendation delivery. Personalization engines within this segment capture the steepest expansion trajectory as retailers prioritize basket-size optimization.
- Standard Carts:Unmodified utility carts serve cost-sensitive retrofit environments and secondary store formats. Budget-constrained regional grocers in the Midwest specify these for phased automation rollouts.
- Mobile Carts:Compact, battery-powered units target convenience store footprints and temporary retail installations. Japanese 24-hour unmanned operations pilot these for space-constrained urban locations.
Leading the category by volume: Self-Checkout Carts. Expanding most quickly: Smart Carts.
Technology:
Protocol selection determines hardware BOM costs, cloud dependency, and FCC certification complexity.
- RFID:Item-level tag reading enables seamless product identification without line-of-sight constraints. Apparel and grocery tagging economics in France and Germany now support cart-based recognition without computer vision dependency.
- IoT:Connected sensor networks transmit inventory and location data to store operations centers. FCC spectrum allocation uncertainty in the 6 GHz band stalls nationwide fleet certification timelines.
- Barcode Scanning:Legacy optical recognition requires consumer activation and maintains higher friction profiles. Discount chains leverage existing UPC infrastructure for lowest-cost deployment paths.
- Mobile App Integration:Smartphone tethering serves as the dominant consumer-facing interface layer across all cart categories. Southeast Asian super-app payment ecosystems bypass legacy POS infrastructure entirely.
Dominant by installed base: Mobile App Integration. Gaining share fastest: RFID.
End User:
Format scale dictates automation ROI thresholds and capital allocation urgency.
- Supermarkets:Full-format grocers anchor deployment velocity through captive supplier networks and direct technology vendor relationships. Walmart's North American rollout pace sets procurement benchmarks for mid-tier chains.
- Hypermarkets:Mass-merchandise hybrids require extended battery ranges and multi-zone navigation capabilities. Big-box footprints in Texas metropolitan markets stress-test mechanical durability thresholds.
- Convenience Stores:Smaller-format automation economics unlock 24-hour unmanned operations in Japan and South Korea. Compact cart systems address labor scarcity in high-rent urban districts.
- Online Retailers:Dark store fulfillment operations deploy modified carts for picker guidance and order consolidation. Last-mile grocery platforms in California pilot these for micro-fulfillment center efficiency.
Commanding largest deployment share: Supermarkets. Emerging as margin pool: Convenience Stores.
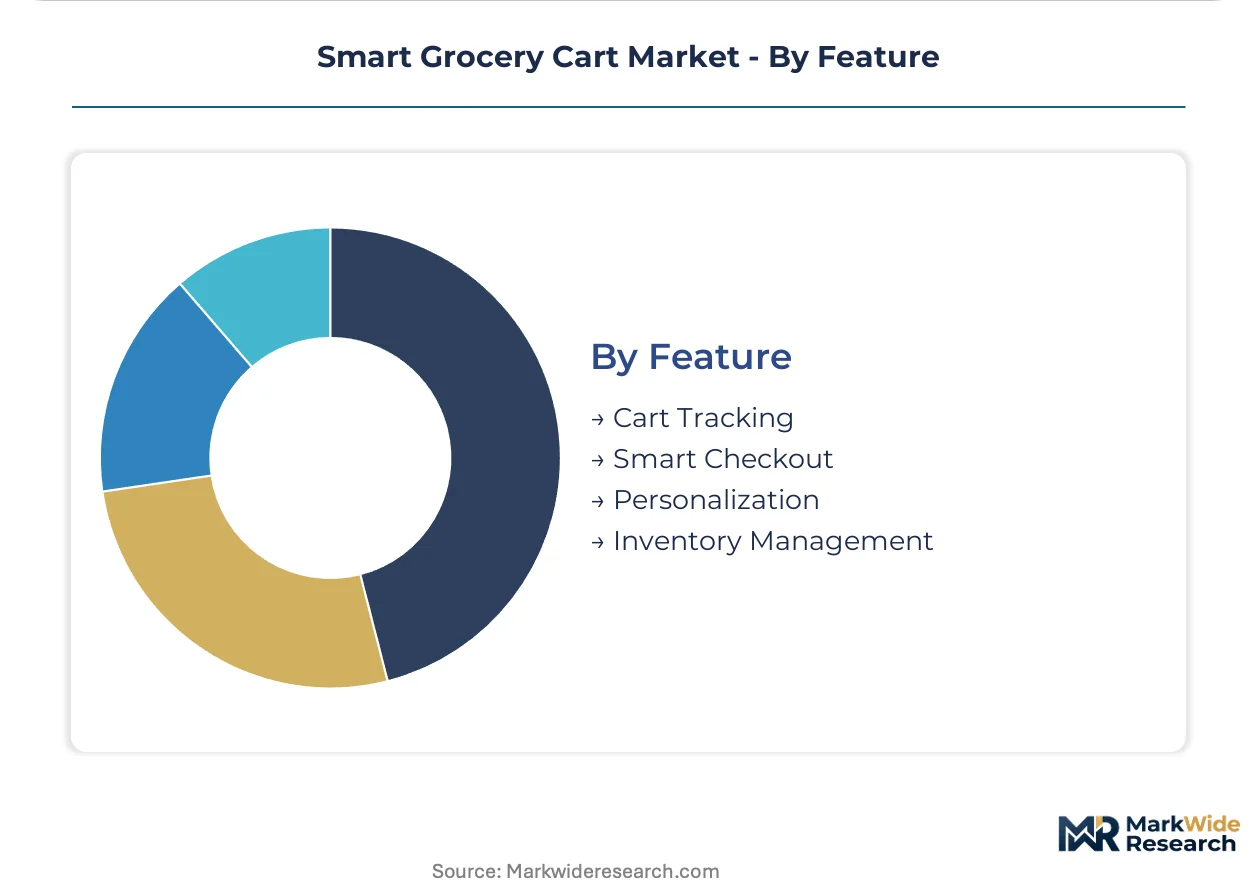
Feature:
Capability bundling separates premium vendor tiers from hardware commodity suppliers.
- Smart Checkout:Integrated payment and recognition systems eliminate traditional POS terminal dependency. EU AI Act biometric data obligations trigger mandatory conformity assessments for facial recognition functions.
- Personalization:Behavioral analytics engines deliver real-time promotions based on basket composition and dwell patterns. French and Italian retailers delay pilot programs pending notified body certification timelines.
- Cart Tracking:Location services prevent loss and optimize fleet utilization across multi-level store layouts. RFID-enabled tracking dominates European deployments due to GDPR-compliant data minimization.
- Inventory Management:Shelf-edge sensors and weight detection trigger automatic replenishment workflows. Real-time stock visibility commands premium pricing from vendors with certified data governance frameworks.
Highest procurement priority: Smart Checkout. Steepest capability investment: Personalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's Opportunity Zone tax incentives and Texas enterprise zone credits are concentrating smart cart pilot deployments along the US Sun Belt corridor. Retail automation vendors establish technical support hubs in these zones to service expanding supermarket footprints.
United States
Wage inflation in California and Texas frontline retail roles accelerates automated checkout cart procurement cycles. FCC spectrum allocation uncertainty in the 6 GHz band stalls nationwide IoT certification timelines for connected cart fleets. Dallas-Fort Worth metropolitan supermarkets stress-test mechanical durability thresholds for edge-native inference hardware.
Germany
GDPR-certified data governance frameworks favor established vendors over unproven market entrants in supermarket procurement committees. EU AI Act high-risk system obligations trigger mandatory conformity assessments for biometric identification functions before CE marking. Bavarian retail cooperatives pilot RFID-enabled cart systems to bypass computer vision compliance complexity.
France
French retailers delay personalization engine deployments pending notified body certification timelines under EU AI Act risk-classification rules. ANSM and CNIL joint guidance on consumer-facing biometric data collection shapes product standards for computer vision architectures. Île-de-France supermarket chains specify onboard inference chips as mandatory procurement requirements.
Japan
Compact cart systems address labor scarcity in Tokyo's high-rent urban convenience store districts. METI standards for IoT device interoperability guide edge computing certification protocols for retail automation equipment. Osaka-Kansai metropolitan retailers pilot 24-hour unmanned operations using battery-powered mobile cart units.
South Korea
Seoul Capital Area convenience store automation economics unlock round-the-clock unmanned retail operations. MFDS guidelines on embedded systems safety intersect with retail automation procurement standards for sensor-equipped cart fleets. Busan-Ulsan industrial corridor manufacturers supply edge AI chipsets for regional smart cart assembly.
Smart Grocery Cart Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement cycles that compress from eighteen months to ninety days. Tiered vendor segmentation separates cloud-scale platform operators from hardware-commodity suppliers. Three archetypes dominate: captive retail technology divisions, independent automation vendors, and component-integrated systems integrators. M&A activity concentrates around edge AI chip capabilities, while strategic partnerships lock in exclusive supermarket rollout rights.
Within the independent automation tier, Caper and Shopic exemplify pure-play specialists that anchor competitive positioning through pre-certified hardware platforms. Retail AI occupies a position among emerging vendors targeting mid-tier supermarket chains with rapid-deployment value propositions. Panasonic represents diversified conglomerate participation, leveraging existing retail equipment distribution networks to accelerate geographic penetration.
| Leading Market Players |
|---|
| Retail AI |
| Walmart |
| Amazon |
| IBM |
| Panasonic |
| Caper |
| Shopic |
| Fujitsu |
| SuperHii |
| Others |
Pricing and Supply Chain Analysis
Firmware engineering talent concentration in Taiwan and South Korea feeds labor-cost differentials that widen pricing-tier spreads between premium edge-AI cart systems and commodity barcode-scanning alternatives.
Pricing Analysis
Short lead-time premiums for EU AI Act pre-certified hardware platforms command pricing spreads against spot inventory from uncertified vendors awaiting notified body timelines. Three-tier pricing structure across premium, standard, and economy levels stratifies by edge inference capability, GDPR certification grade, and after-sales service bundling. Pricing pressure stems from semiconductor supply concentration and FCC certification delays that compress margins for IoT-dependent cart fleets. Mid-tier supermarket chains in the US Midwest exhibit highest price sensitivity, while California and Texas metropolitan retailers prioritize throughput gains over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Walmart and Amazon procurement committees mandate multi-supplier qualification for edge AI chipsets across Taiwan, South Korea, and Japan. Component dependencies center on TSMC-fabricated inference processors, RFID inlays from NXP and Impinj, and lithium-ion battery cells from CATL and LG Energy Solution. Single-source vulnerability in Taiwan-based foundry capacity exposes rollout timelines to geopolitical disruption. Distribution runs through captive retail technology divisions and systems integrators with certified installation networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into edge AI silicon design and captive cloud infrastructure anchors competitive positioning as vendors race to compress data gravity and bypass third-party foundry constraints.
For Market Incumbents: Anticipate EU AI Act conformity assessment bottlenecks by pre-positioning notified body relationships and dual-track certification for biometric and non-biometric cart architectures. Lock in exclusive supermarket rollout rights through revenue-sharing models that align capital deployment with throughput-based payment structures. Deepen backward integration into sensor fusion firmware to offset embedded systems talent scarcity.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in convenience store automation creates entry space for compact cart systems targeting Japan and South Korea's 24-hour unmanned format. White-space concentration sits with RFID-first architectures that bypass computer vision compliance complexity in European procurement cycles. Pursue super-app payment ecosystem partnerships in Southeast Asia to bypass legacy POS infrastructure entirely.
For Investors and Strategic Acquirers: Re-rating potential sits with pure-play specialists possessing pre-certified hardware platforms given procurement cycle compression from eighteen months to ninety days. Long-term viability favors vendors with demonstrated EU AI Act compliance pathways and captive edge computing IP. Monitor FCC 6 GHz spectrum allocation rulings as inflection indicator for nationwide IoT fleet certification velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Inference Chip Development | Onboard processing reduces cloud dependency and GDPR data transfer exposure. |
| EU AI Act Pre-Certification Investment | Notified body relationships accelerate CE marking for biometric identification functions. |
| RFID Infrastructure Partnership | Item-level tagging economics enable computer vision bypass in French and German deployments. |
| Super-App Payment Integration | Southeast Asian mobile wallet convergence eliminates legacy POS terminal dependency. |
| Convenience Store Format Miniaturization | Compact battery-powered units address Tokyo labor scarcity in high-rent districts. |
Research Methodology
SEC filings from Amazon and Walmart, EU AI Act implementation guidance from notified bodies, and FCC spectrum allocation dockets formed the secondary backbone for supply-side and regulatory trajectory assessment. Primary interviews with supermarket category managers, edge AI hardware procurement leads, and retail technology integration specialists combined with customs data on RFID inlay imports and hyperscaler capex disclosures. Bottom-up unit economics modeling triangulated against top-down market sizing from supermarket chain automation budget disclosures.
Historical trendline analysis of self-checkout cart deployment velocities across California, Texas, and German metropolitan markets anchored the projection framework. Segmentation dimensions spanned product type, recognition technology protocol, retail format scale, and regional regulatory cluster. CAGRs were derived from installed base ramp rates and replacement cycle assumptions, with edge inference adoption curves and labor cost inflation differentials as primary forecast inputs.
Inputs from notified body certification timelines and FCC ruling dockets were available through the study window; gaps in supermarket chain specific automation budget commitments introduce uncertainty bands around deployment velocity assumptions. Deviation in EU AI Act enforcement stringency or Taiwan foundry capacity availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
Alternative Retailing Technologies Market
Retail Technology
Global Restaurant Point of Sale (POS) Terminals Market
Retail Technology
Global Kiosk Market
Retail Technology
America's AI in the Retail Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Smart Shopping Cart Market
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Smart Retail Systems Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
Smart Shelf Market
Retail Technology
E-Retail Market