
 United States Grocery and Pharmacy Point of Sale (POS) Terminal Market | 2026-2036
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market Size, Share, and Industry Trends Forecast 2026-2036
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market Analytics
EMV Level 3 certification requirements for grocery and pharmacy environments is unwinding legacy terminal deployments across independent and mid-size retail chains. Block, Inc. leverages its integrated hardware-software ecosystem to anchor SMB pharmacy accounts with subscription-based POS services. NCR Voyix Corporation dominates enterprise supermarket installations through its Aloha and Emerald platforms, while Toast, Inc. competes aggressively in urban grocery formats with kitchen-display-integrated checkout workflows.
United States Grocery and Pharmacy Point of Sale (POS) Terminal systems comprise hardware terminals, payment processing software, and peripheral integrations designed to process transactions, manage inventory, and enforce regulatory compliance in retail food and drug environments. These systems typically integrate barcode scanners, weight scales, prescription verification modules, and dual-screen customer displays to support high-volume, regulated transactions. Terminal POS hardware retains the largest installed base across supermarket chains due to durability requirements and multi-lane throughput demands, though mobile POS is gaining fastest in convenience stores and curbside pharmacy pickup. Cloud-based deployment models now capture margin pools from SaaS recurring revenue, displacing capital-heavy on-premise legacy systems.
FDA traceability rules under the Food Safety Modernization Act, PCI-DSS payment security standards, and state-level pharmacy board prescription data retention requirements collectively shape product specifications and procurement timelines for POS vendors. NHTSA indirectly influences pharmacy drive-through lane designs where POS terminals must integrate with vehicle queue management. Retailers and system integrators must monitor evolving state privacy legislation and real-time payment network mandates to avoid stranded infrastructure investments.
Market Dynamics
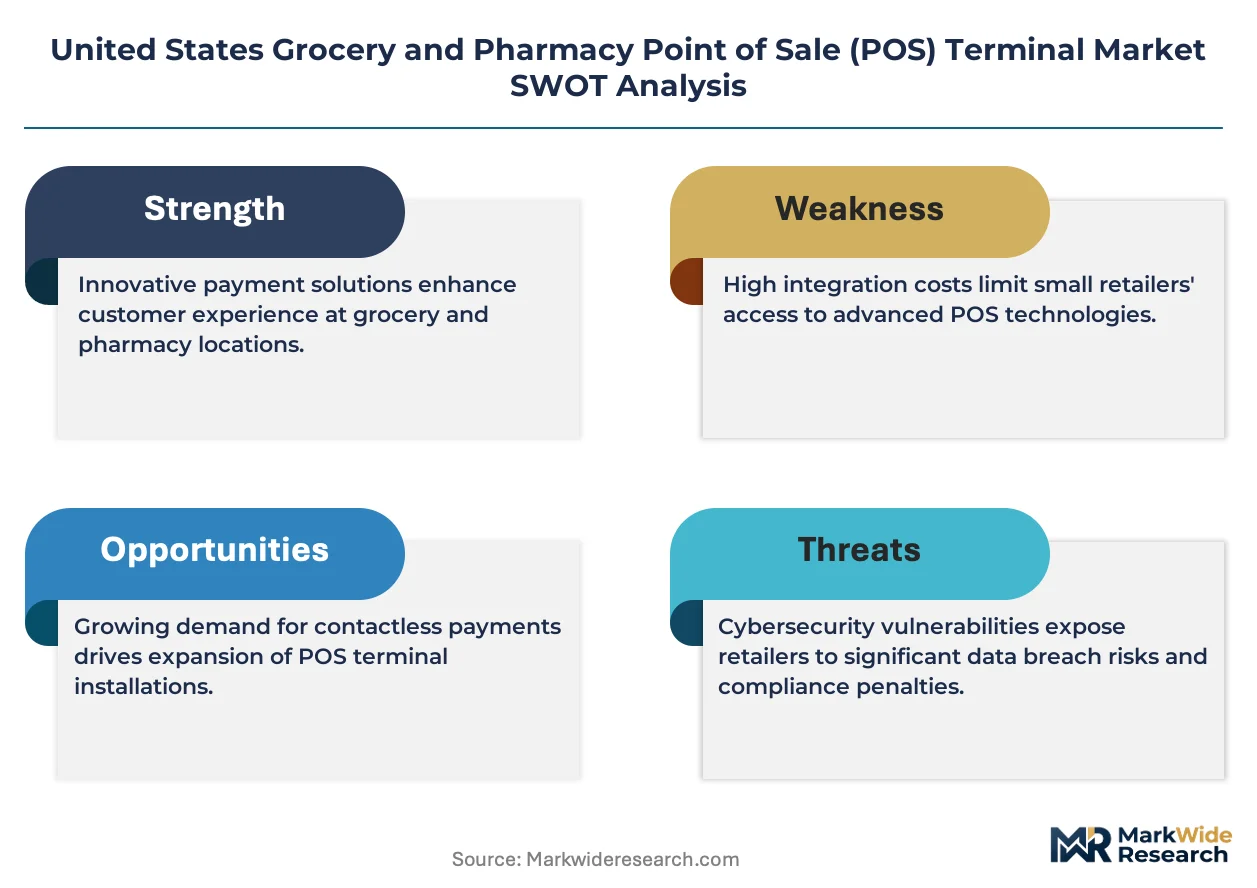
EMV Level 3 certification deadlines are forcing independent grocers and regional pharmacy chains to replace legacy countertop terminals with integrated payment ecosystems, compressing replacement cycles from seven years to four.
Growth Catalysts
- FDA Food Safety Modernization Act traceability mandates:Grocery retailers must deploy POS systems capable of capturing lot-level data at checkout, driving hardware refresh cycles.
- California pharmacy board prescription data retention rules:Dual-screen customer displays with signature capture modules are becoming standard equipment in West Coast drugstore chains.
- Supermarket digitization in Texas:Self-checkout lane expansion across H-E-B and regional competitors is accelerating demand for weight-integrated POS terminals.
Market Restraints
- Semiconductor supply concentration:Payment terminal processors rely on Taiwanese foundry capacity, creating 16-24 week lead time volatility for new deployments.
- PCI-DSS compliance cost structure:Annual certification audits for Level 1 merchants exceed $50,000 per location, squeezing independent pharmacy margins.
- Technical limitation in legacy integration:IBM 4690 and NCR 7456 terminal protocols resist cloud-native middleware, trapping mid-market grocers on end-of-life platforms.
Strategic Opportunities
- Curbside pharmacy pickup in Florida:Mobile POS with Bluetooth prescription scanners enables vehicle-side checkout without lane infrastructure investment.
- Cloud-native SaaS migration:Subscription-based terminal management displaces capital-heavy on-premise server closets for 50-200 location grocery chains.
- Kitchen-display integration:Urban grocery formats with hot food service are converging FOH and BOH workflows on unified Toast and NCR platforms.
Industry Challenges
- EMV Level 3 certification timelines:Independent software vendors face 8-12 month laboratory testing queues, delaying product launches and freezing procurement decisions.
- Legacy system integration complexity:Pharmacy management systems from McKesson and Cardinal Health require custom middleware development for modern POS APIs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Grocery and Pharmacy Point of Sale (POS) Terminal Market |
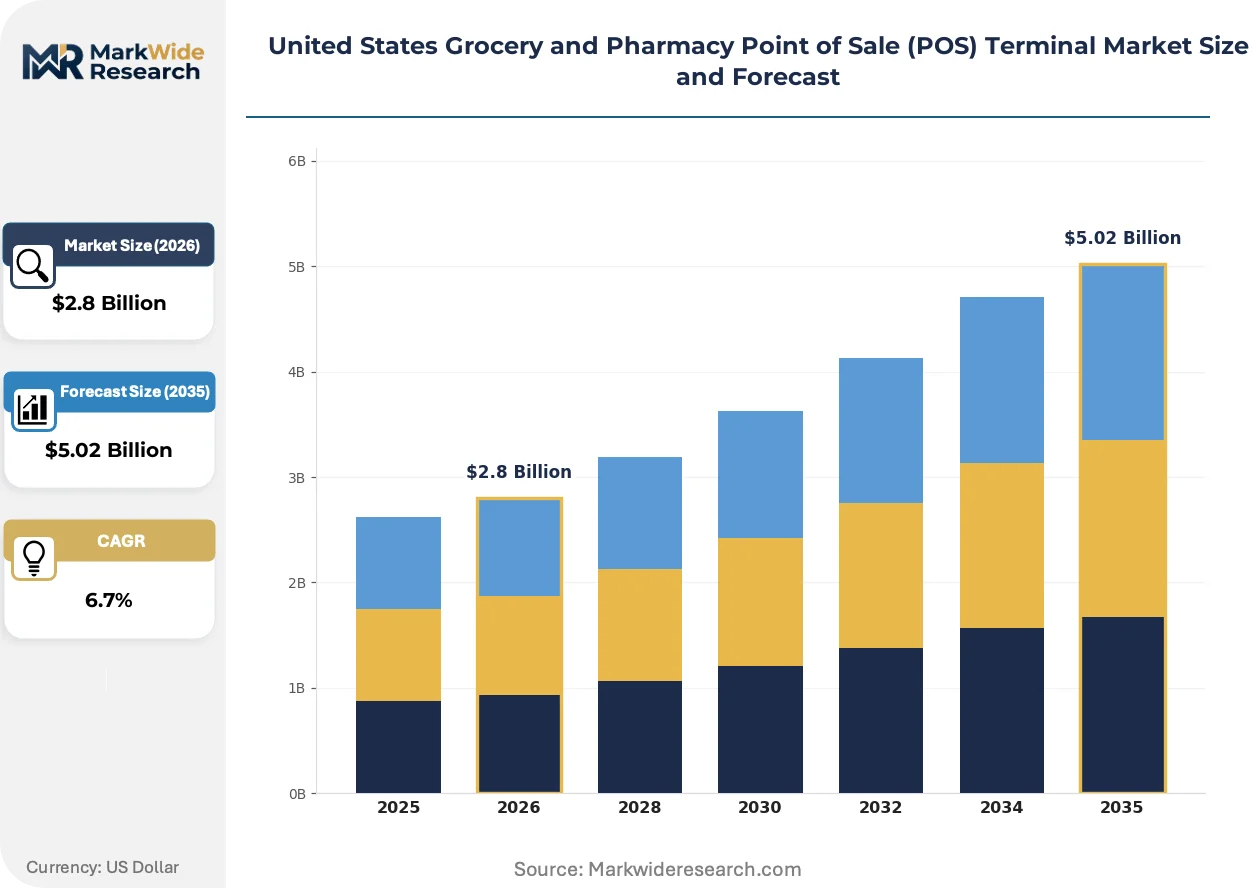
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile POS, Terminal POS, Self-Service Kiosks, Integrated Payment Systems Technology: Cloud-Based, On-Premise, Hybrid Systems, Contactless Payment Solutions End User: Supermarkets, Pharmacies, Convenience Stores, Specialty Retailers Deployment: On-Site, Remote Support, SaaS, PaaS |
| Companies Covered | PayPal Holdings, Inc., Lightspeed Commerce Inc., Block, Inc., Clover Network, LLC, PAX Technology, Toast, Inc., Verifone, Inc., NCR Voyix Corporation, Fiserv, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market Evolving Landscape
Payment terminal architecture is fragmenting across three vectors simultaneously: hardware form factors, software deployment models, and peripheral integration depth. Each vector carries distinct implications for vendor competitive position.
Biometric authentication modules are fragmenting traditional card-present transaction flows. Large-format grocery chains in California and Texas are piloting palm-vein scanners at self-checkout lanes to reduce friction for loyalty program linkage. The technology is fragmenting PCI-DSS scope definitions, forcing acquirers to reassess liability models for biometric data storage.
FDA traceability rules under the Food Safety Modernization Act are mandating lot-level data capture at point of sale. Grocery retailers must now integrate produce scale systems with inventory management APIs, creating new specification requirements for terminal software stacks. California and Florida chains are responding fastest, embedding GS1 barcode scanners directly into checkout lanes.
Subscription-based terminal management is displacing perpetual license purchases among 20-100 location grocery chains. Hardware-as-a-service bundles from payment facilitators are compressing traditional POS vendor margins while capturing recurring revenue pools. This shift is most visible in Texas and Arizona, where regional chains prioritize operational flexibility over capital ownership.
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market Segmentation
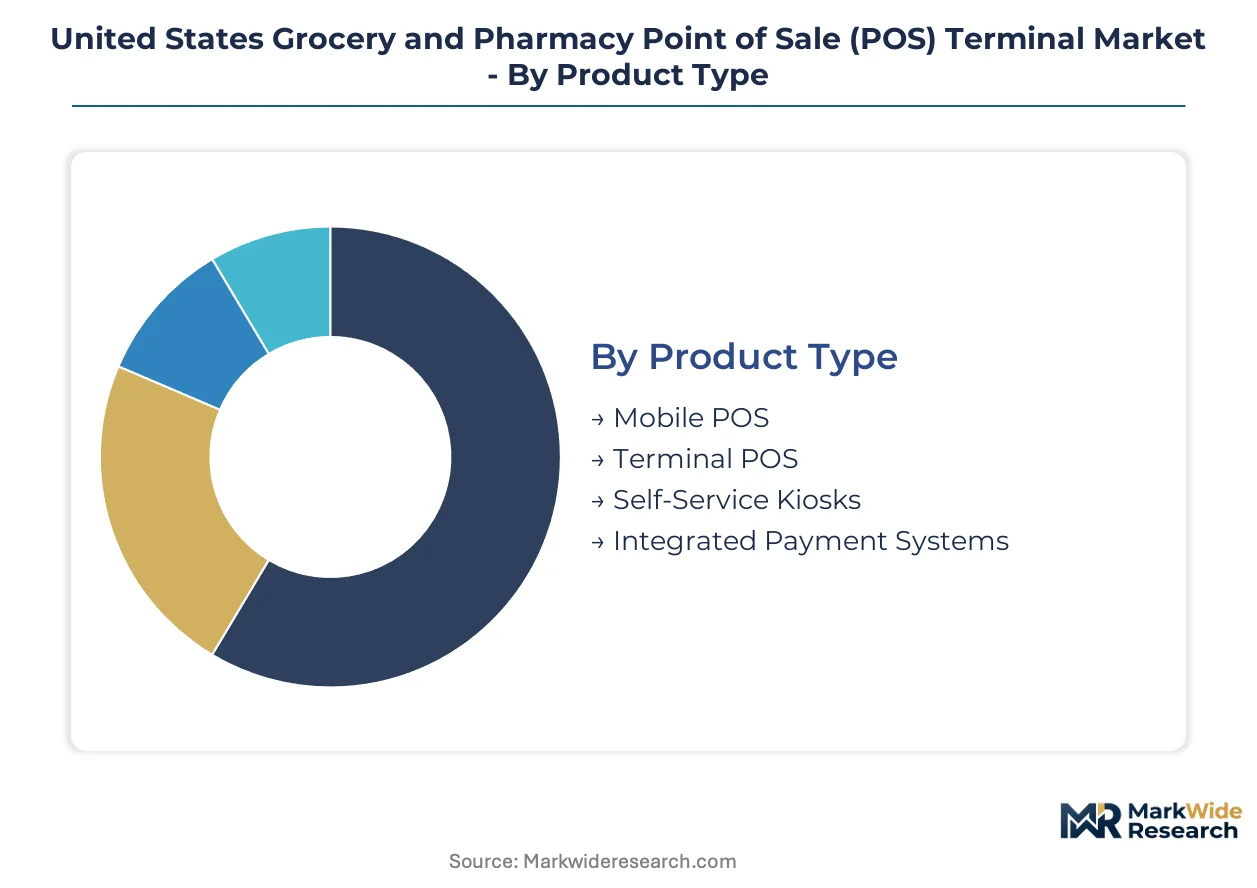
POS terminal procurement in US grocery and pharmacy environments follows distinct channel patterns. Product type and deployment model decisions cascade through technology selection and end-user requirements.
Product Type:
Channel mix varies sharply by format: supermarket chains favor terminal POS through direct vendor relationships, while independent pharmacies acquire mobile POS through payment facilitator channels.
- Terminal POS:Fixed countertop units with integrated payment processing, barcode scanning, and customer-facing displays. Demand concentrates in California and Texas supermarket chains where multi-lane throughput requirements and FDA traceability data capture drive hardware refresh cycles.
- Mobile POS:Handheld tablets with Bluetooth peripheral connectivity enabling curbside and aisle checkout. Florida pharmacy chains and urban convenience stores are expanding vehicle-side prescription pickup workflows, compressing deployment timelines from lane infrastructure builds.
- Self-Service Kiosks:Freestanding checkout terminals with weight-integrated bagging areas. H-E-B and regional Texas competitors are scaling lane conversions.
- Integrated Payment Systems:All-in-one terminals combining hardware, processing software, and merchant services in subscription bundles. Mid-market grocery chains in Arizona prioritize operational flexibility.
By volume, Terminal POS leads. By growth pace, Mobile POS is expanding most quickly.
Technology:
Cost tier separation is pronounced: cloud-native stacks command premium SaaS pricing while on-premise systems retain installed base through compliance latency.
- Cloud-Based:Fully hosted software with browser-based terminal management and automatic security patching. California pharmacy boards mandate real-time prescription data sync, accelerating West Coast migration from legacy server closets.
- Hybrid Systems:Split architecture keeping payment processing on-premise while routing inventory and analytics to cloud endpoints. PCI-DSS scope reduction drives adoption among 50-200 location grocery chains.
- On-Premise:Local server installations with perpetual software licenses. IBM 4690 protocol dependencies trap some independent grocers on end-of-life platforms.
- Contactless Payment Solutions:NFC-enabled terminals supporting tap-to-pay and mobile wallet acceptance. Texas supermarket digitization mandates are accelerating lane upgrades.
Cloud-Based deployments capture the highest-margin recurring revenue. Hybrid Systems are climbing fastest among compliance-constrained mid-market operators.
End User:
Application requirements diverge: supermarkets need weight-scale integration and high-volume throughput, while pharmacies require prescription verification modules and signature capture.
- Supermarkets:Full-service grocery chains with 20+ checkout lanes and hot food service integration. Self-checkout expansion across Texas H-E-B locations is driving integrated terminal demand.
- Pharmacies:Drugstore chains and independent dispensaries with prescription data retention requirements. California board mandates for dual-screen signature capture are standardizing equipment specifications.
- Convenience Stores:Small-format retailers with limited counter space and rapid transaction requirements. Mobile POS adoption is outpacing terminal deployments in this segment.
- Specialty Retailers:Organic grocers, ethnic food markets, and health-focused chains with niche inventory management needs. FDA traceability compliance is forcing hardware upgrades.
Supermarkets generate the largest absolute volume. Pharmacies are gaining share fastest due to consolidation and regulatory pressure.
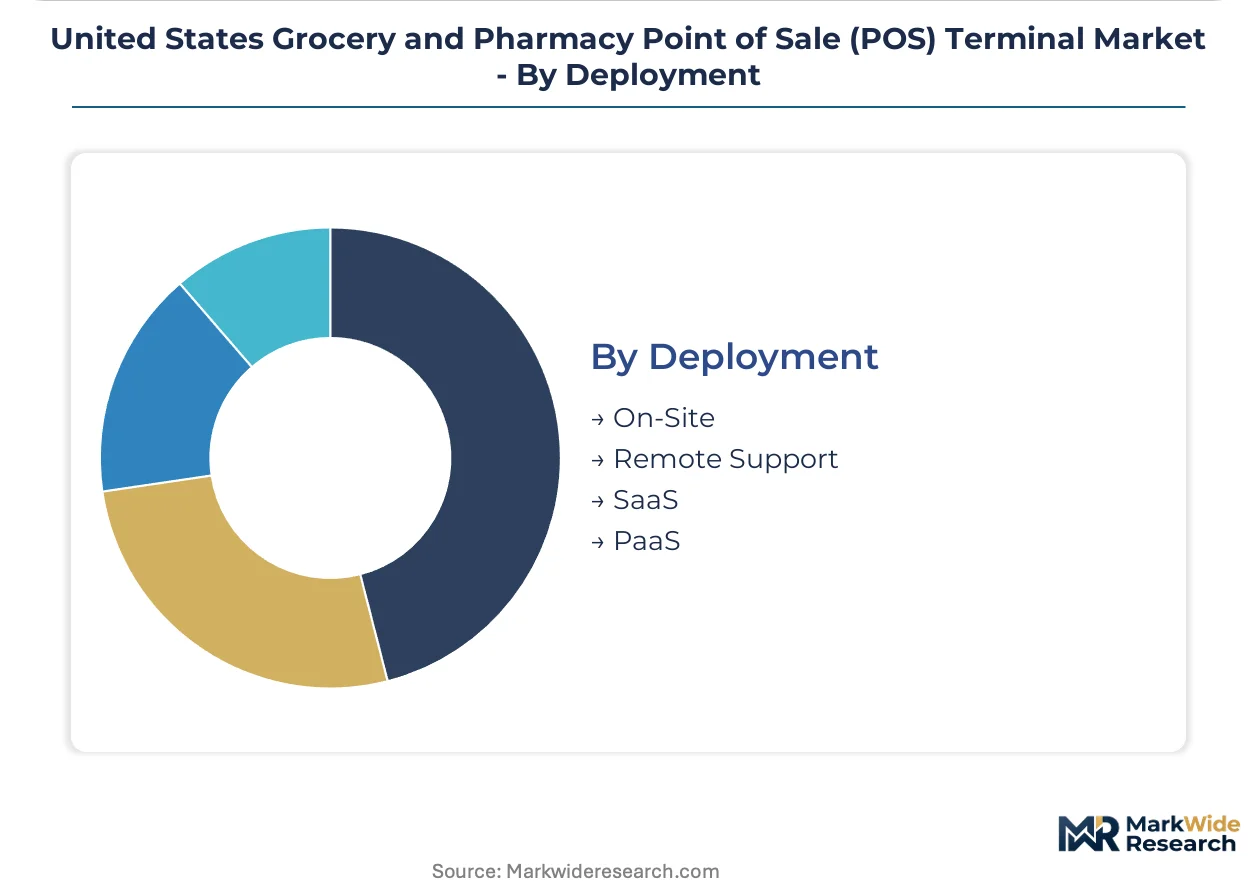
Deployment:
Customer type stratification is evident: enterprise chains negotiate SaaS contracts with dedicated account management, while independents purchase through payment facilitator marketplaces.
- SaaS:Subscription-based terminal management with bundled hardware, software, and support. Regional grocery chains in Texas and Arizona prioritize operational flexibility over capital ownership.
- On-Site:Traditional capital purchase with local IT maintenance and periodic upgrade cycles. Some legacy-dependent operators retain this model.
- PaaS:Platform-as-a-service offerings enabling custom application development on terminal hardware. Pharmacy management system integrators are leveraging this for McKesson and Cardinal Health middleware.
- Remote Support:Cloud-managed terminals with offsite technical assistance and over-the-air updates. Post-pandemic labor constraints are accelerating adoption.
SaaS leads by new contract value. PaaS is expanding most quickly among system integrators serving pharmacy chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a POS terminal trade deficit, importing payment hardware assemblies from Asian manufacturing clusters while exporting cloud-native software platforms to Canadian and Mexican retail chains. Regional procurement patterns diverge sharply between FDA-regulated grocery environments and state-board-governed pharmacy operations.
California
California pharmacy board mandates for dual-screen signature capture and prescription data retention are standardizing terminal specifications across CVS, Walgreens, and independent drugstore networks. FDA Food Safety Modernization Act traceability rules force grocery chains to deploy GS1-capable scanners at checkout. Los Angeles and San Francisco Bay Area clusters anchor West Coast demand for integrated payment ecosystems.
Texas
H-E-B and regional supermarket competitors are scaling self-checkout lane conversions, driving weight-integrated terminal demand across Dallas-Fort Worth and Houston metros. State-level pharmacy consolidation accelerates mobile POS adoption for curbside prescription pickup. Texas retailers prioritize operational flexibility, favoring subscription-based terminal management over capital purchases.
Florida
Pharmacy drive-through expansion and vehicle-side checkout workflows are compressing deployment timelines for Bluetooth-enabled mobile POS systems. CVS and Walgreens are retrofitting lanes across Miami-Dade, Tampa Bay, and Orlando corridors. Florida's elderly population density intensifies demand for prescription verification modules with large-format customer displays.
Northeast Corridor
New York and Massachusetts supermarket chains face compressed EMV Level 3 certification deadlines, forcing replacement of legacy IBM 4690 protocol systems. PCI-DSS compliance costs exceed $50,000 per location for Level 1 merchants, squeezing independent grocers in Connecticut and New Jersey. Boston and New York City clusters concentrate cloud-native SaaS migration among 50-200 location regional chains.
Pacific Northwest
Seattle and Portland grocery cooperatives are piloting biometric palm-vein scanners at self-checkout lanes, fragmenting traditional card-present transaction flows. Washington state privacy legislation shapes procurement timelines for facial recognition-capable terminals. Regional pharmacy chains prioritize hybrid cloud deployments to reduce PCI-DSS audit scope.
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market Competitive Landscape
Listed leaders compete with private specialists across payment facilitator channels and enterprise direct sales. The market structure tiers into three distinct competitive bands: cloud-native SaaS platforms, legacy hardware-software integrators, and payment facilitator bundles. Strategic archetypes include integrated hardware-software ecosystems, kitchen-display-integrated checkout workflows, and subscription-based terminal management services. Dominant competitive moves center on SaaS recurring revenue capture and EMV certification acceleration.
Within the integrated ecosystem tier, Block, Inc. and Toast, Inc. exemplify hardware-software convergence strategies. NCR Voyix Corporation anchors enterprise supermarket installations through direct vendor relationships. Among payment facilitator channels, PayPal Holdings, Inc. and Fiserv, Inc. occupy positions bundling merchant services with terminal hardware. These five entities represent the competitive spectrum from SMB pharmacy accounts to multi-lane grocery chain deployments.
| Leading Market Players |
|---|
| PayPal Holdings, Inc. |
| Lightspeed Commerce Inc. |
| Block, Inc. |
| Clover Network, LLC |
| PAX Technology |
| Toast, Inc. |
| Verifone, Inc. |
| NCR Voyix Corporation |
| Fiserv, Inc. |
| Others |
Value Network & Pricing Analysis
Sixteen-to-twenty-four week lead times for payment terminal processors compress procurement flexibility and anchor pricing power with Taiwanese foundry operators serving US grocery and pharmacy chains. Inventory buffers at distributor hubs in California and Texas rarely exceed thirty days, forcing retailers into expedited freight premiums when semiconductor wafer allocation tightens.
Pricing Analysis
Regional grocery chains anchor subscription-based pricing structures across SaaS-tiered terminal management bundles, with PCI-DSS certification grade and volume scale driving differentiation between premium EMV Level 3 certified systems and standard countertop replacements. Pricing pressure stems from payment facilitator channel compression, squeezing traditional POS vendor margins while hardware-as-a-service models capture recurring revenue pools. Independent pharmacies exhibit highest price sensitivity due to annual compliance audit burdens exceeding fifty thousand dollars per location, while enterprise supermarket chains leverage multi-lane procurement scale for least-sensitive contract negotiations.
Supply Chain Analysis
Port congestion at Los Angeles-Long Beach and container availability constraints on transpacific trade lanes disrupt inbound logistics for terminal hardware assemblies manufactured in Taiwan, China, and Vietnam. Payment terminal production draws from Taiwanese semiconductor foundries, Chinese printed circuit board fabricators, and Mexican final assembly operations. Single-source vulnerability concentrates in advanced payment security chip fabrication. Distribution runs through payment facilitator marketplaces for independent pharmacies and direct vendor relationships for enterprise supermarket chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where EMV certification interoperability and cloud-native middleware convergence determine competitive survival. The shift from perpetual license purchases to subscription-based terminal management restructures vendor economics toward recurring revenue capture.
For Market Incumbents: Compound defensive moats by deepening backward integration into payment security chip supply and accelerating EMV Level 3 certification pre-clearance programs for independent software vendors. Cloud-native entrants threaten legacy hardware-software integrators through kitchen-display-integrated checkout workflows; counter by embedding prescription verification modules directly into terminal firmware to raise switching costs for pharmacy chains.
For New Entrants and Emerging Players: EMV Level 3 laboratory fast-track partnerships with certified testing facilities unlock procurement windows frozen by eight-to-twelve month certification queues. Curbside pharmacy pickup in Florida presents the most penetrable white-space target, with vehicle-side mobile POS deployment compressing infrastructure timelines against lane-based competitors. Target payment facilitator channel partnerships rather than direct enterprise sales to bypass incumbent account control.
For Investors and Strategic Acquirers: Carve-out targets emerge from legacy hardware-software conglomerates divesting non-core POS terminal divisions amid cloud-native SaaS migration. Long-term viability over the next decade hinges on recurring revenue share and certification asset ownership. Watch FDA Food Safety Modernization Act enforcement acceleration as the signal indicating hardware refresh cycle inflection for grocery chains.
| Strategic Initiative | Industry Significance |
|---|---|
| EMV Level 3 Certification Fast-Track | Pre-cleared laboratory partnerships compress eight-to-twelve month testing queues for independent software vendors. |
| Cloud-Native SaaS Migration | Subscription-based terminal management displaces capital-heavy on-premise server closets for mid-market grocery chains. |
| Biometric Authentication Integration | Palm-vein scanner pilots at California and Texas self-checkout lanes fragment PCI-DSS liability models for acquirers. |
| Curbside Pharmacy Mobile POS Deployment | Bluetooth prescription scanners enable vehicle-side checkout without lane infrastructure investment in Florida markets. |
| Kitchen-Display System Convergence | Urban grocery hot food service integration unifies FOH and BOH workflows on unified hardware-software platforms. |
Research Methodology
Operator-level perspectives from supermarket IT directors, pharmacy chain procurement managers, payment facilitator channel partners, and EMV certification laboratory engineers anchored the qualitative base. Primary interviews with POS terminal deployment specialists and grocery technology consultants combined with secondary validation from FDA Food Safety Modernization Act guidance documents, PCI-DSS compliance bulletins, state pharmacy board regulations, and SEC filings from publicly traded payment hardware vendors. Bottom-up terminal deployment counts across California, Texas, and Florida triangulated against top-down market size estimates from recurring revenue disclosures.
Sensitivity analysis around semiconductor lead time volatility and EMV certification timeline compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, deployment model, end-user format, and regional regulatory cluster. CAGRs derived from hardware refresh cycle compression analysis and SaaS subscription attach rate trajectories. Forecast inputs incorporated FDA traceability mandate enforcement schedules and state-level pharmacy board prescription data retention rule adoption curves.
Underlying assumptions cover stable transpacific logistics capacity and PCI-DSS audit cost structures, with deviation risk concentrated in Taiwanese foundry allocation disruptions and EMV laboratory testing queue extensions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Smart Shelf Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
AR in Retail Market
Retail Technology
Smart Shopping Cart Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
Smart Retail Systems Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Digital Kiosk Market
Retail Technology
Self-Checkout System Market
Retail Technology
E-Retail Market
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
Data-Driven Retail Solution Market
Retail Technology
Global Smart Retail Market