
 Omni-Channel Retail Solutions Market | 2026-2036
Omni-Channel Retail Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Omni-Channel Retail Solutions Market Intelligence
Specialty apparel retail is restructuring fulfillment expectations around buy-online-pickup-in-store and ship-from-store capabilities. NCR Corporation dominates legacy point-of-sale infrastructure while extending into cloud-native architectures. Shopify Plus anchors small-to-mid-market merchant adoption through native e-commerce and POS convergence. Manhattan Associates specializes in warehouse management and distributed order orchestration for enterprise-scale inventory visibility.
Omni-channel retail solutions integrate point-of-sale terminals, customer relationship management software, e-commerce platforms, and inventory management systems through APIs and unified data layers to synchronize stock, pricing, and customer profiles across physical and digital touchpoints. Cloud-based and SaaS deployment models are capturing margin pools as retailers abandon capital-intensive on-premises infrastructure for elastic, subscription-priced architectures. Integration services represent the fastest-growing service type because fragmented legacy stacks require middleware and API governance to achieve real-time synchronization between ERP, POS, and marketplace channels.
The Federal Trade Commission scrutinizes data aggregation practices in retail loyalty programs, while the EU AI Act imposes algorithmic transparency requirements on automated pricing and recommendation engines deployed in European markets. State-level frameworks such as the California Consumer Privacy Act compel retailers to reconstruct customer data architectures for consent management and deletion portability. Stakeholders must monitor regulatory divergence between federal privacy preemption debates and proliferating state statutes when selecting deployment regions and data residency strategies.
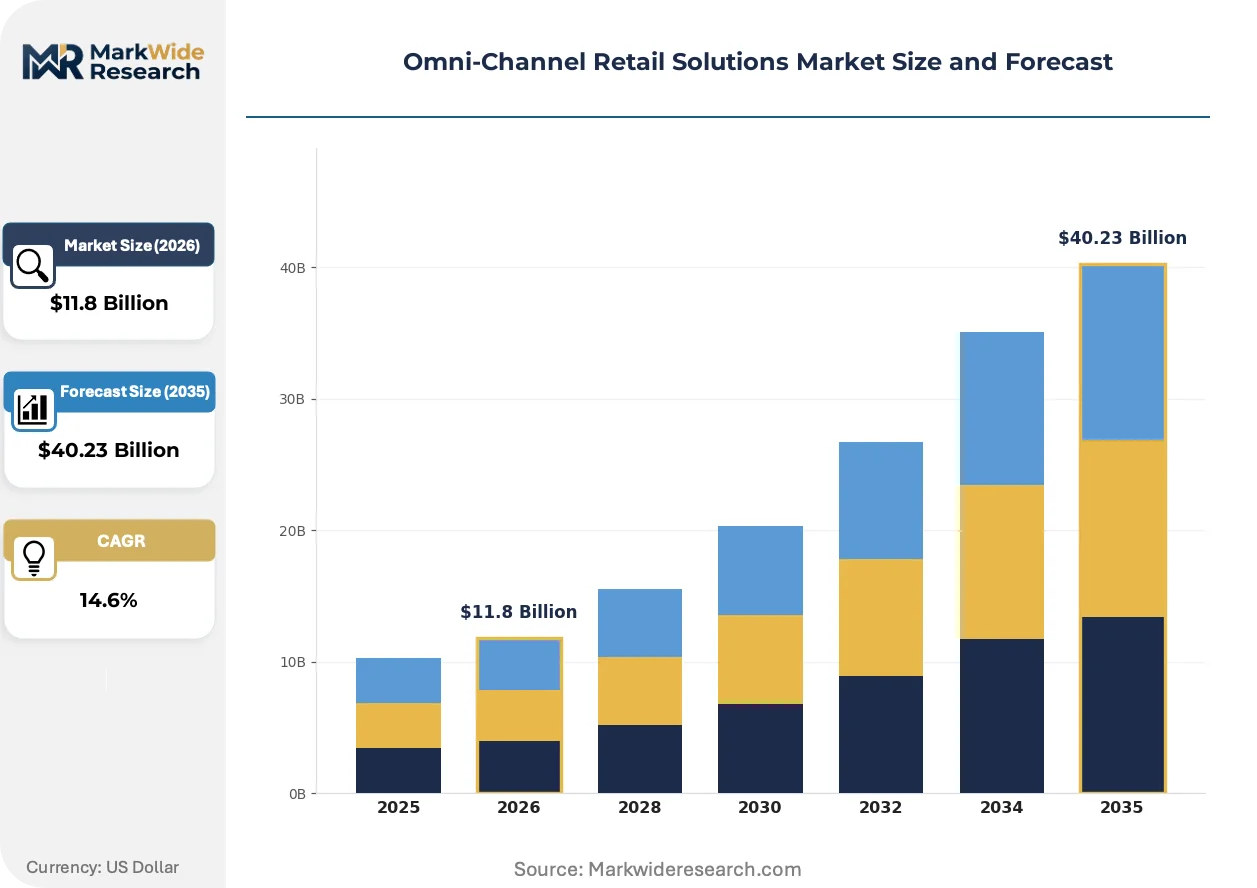
Market Dynamics
Unified commerce platforms are compressing fulfillment architecture decisions as specialty apparel retailers abandon channel-siloed inventory management for single-view stock orchestration. Real-time synchronization between POS, e-commerce, and marketplace channels now determines working capital efficiency and customer promise reliability.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for automated pricing engines are forcing platform upgrades across European operations, accelerating cloud-native architecture adoption.
- Ship-from-store capabilities:Specialty apparel retailers are retrofitting physical locations as distributed fulfillment nodes to reduce last-mile delivery costs and inventory carrying requirements.
- California Consumer Privacy Act enforcement:Consent management and data deletion portability requirements are driving replacement of legacy customer data architectures with compliant unified data layers.
Market Restraints
- Legacy ERP integration costs:Middleware development for real-time API governance between on-premises ERP systems and cloud-native platforms requires substantial professional services expenditure.
- Cloud concentration risk:Elastic compute dependency on hyperscale providers creates vulnerability to egress pricing volatility and regional availability zone disruptions.
- Data residency fragmentation:Divergent state-level privacy statutes in the United States complicate single-tenant deployment strategies and inflate compliance architecture costs.
Strategic Opportunities
- Mid-market hybrid deployment:United States retailers with 50-200 locations seek unified commerce platforms combining cloud elasticity with on-premises POS resilience.
- Buy-online-pickup-in-store convergence:Real-time inventory visibility and curbside orchestration capabilities open white space in grocery and home improvement verticals.
- FTC loyalty program scrutiny:Data aggregation transparency requirements create competitive opening for privacy-forward customer data platforms with built-in consent audit trails.
Industry Challenges
- API governance talent scarcity:Retailers struggle to hire integration architects capable of designing fault-tolerant middleware between fragmented legacy stacks and modern commerce platforms.
- Real-time synchronization complexity:Achieving sub-second inventory accuracy across distributed order management systems requires substantial network infrastructure investment and edge computing deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Omni-Channel Retail Solutions Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $40.23 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point of Sale, CRM Software, E-commerce Platform, Inventory Management Customer Type: Small Businesses, Large Enterprises, Franchises, Startups Service Type: Consulting Services, Integration Services, Support Services, Maintenance Services Deployment Model: Cloud-Based, On-Premises, Hybrid, SaaS |
| Companies Covered | NCR Corporation, Shopify Plus, Kibo Commerce, Oracle Corporation, Salesforce, IBM Corporation, SAP SE, Adobe, Manhattan Associates, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Omni-Channel Retail Solutions Market Strategic Shifts & Innovations
Headless commerce architectures are decoupling frontend presentation layers from backend fulfillment systems, enabling retailers to experiment with customer experience without disrupting core inventory operations. This separation is accelerating vendor specialization and API-first platform design.
Composable commerce platforms are consolidating point-of-sale, order management, and customer data functions into modular microservices architectures. Mid-market retailers in the United States are adopting these stacks fastest, replacing monolithic legacy suites with best-of-breed components connected through unified APIs. This consolidation is compressing vendor switching costs and enabling faster feature deployment cycles.
The EU AI Act is imposing documentation requirements on automated pricing and recommendation systems deployed in European markets. Retailers must maintain algorithmic audit trails and human oversight mechanisms for dynamic pricing engines. Enterprise-scale merchants with cross-border operations are responding by establishing dedicated AI governance functions and regional model deployment strategies.
Curbside and locker-based fulfillment options are displacing traditional home delivery as the default customer expectation in urban United States markets. Grocery and big-box retailers are retrofitting parking infrastructure and partnering with third-party locker networks to accommodate this shift. This behavioral change is most visible in California and Texas metropolitan corridors where delivery density and labor costs have compressed traditional last-mile economics.
Omni-Channel Retail Solutions Market Segmentation
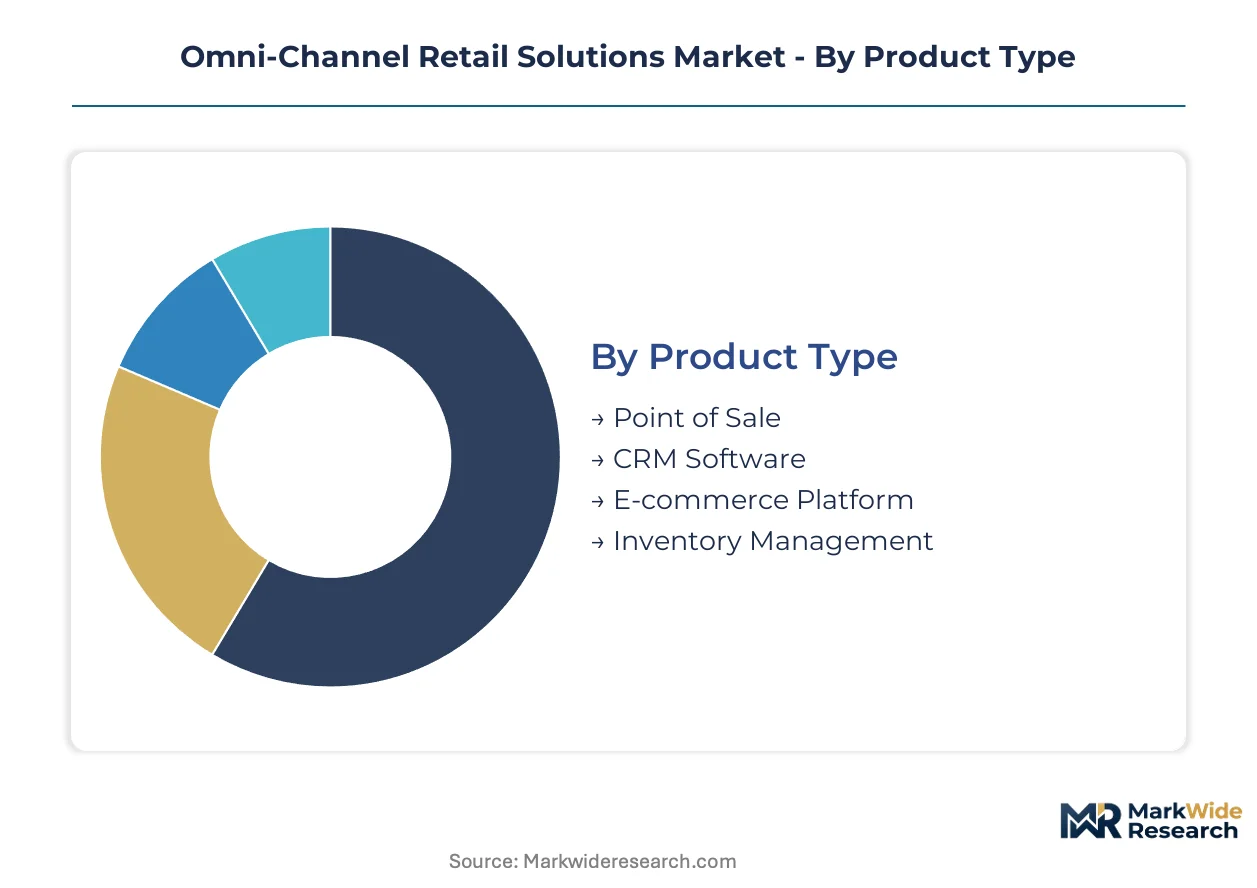
Retailers select omni-channel platforms based on technical debt exposure, compliance burden, and fulfillment complexity rather than feature checklists alone. Segmentation reveals where capital allocation concentrates and which deployment models capture margin as channel integration deepens.
Product Type:
Integration complexity with legacy infrastructure drives platform selection more than standalone capability ratings.
- Point of Sale:Terminal hardware and software stacks process transactions while synchronizing inventory deductions across channels in real time. Specialty apparel retailers in the United States prioritize POS resilience during cloud outages, driving hybrid architecture demand.
- Inventory Management:Distributed order orchestration engines maintain single-view stock accuracy across warehouses, stores, and third-party fulfillment nodes. Ship-from-store mandates are compressing deployment timelines as retailers retrofit physical locations as fulfillment endpoints.
- CRM Software:Unified customer data layers consolidate profiles across touchpoints for consent management and personalization.
- E-commerce Platform:Headless architectures decouple frontend experience from backend fulfillment systems.
Volume sits with Point of Sale; growth tilts toward Inventory Management.
Customer Type:
Scale determines whether retailers build in-house integration teams or outsource middleware development entirely.
- Large Enterprises:Multi-brand retailers operate fragmented legacy stacks requiring extensive API governance and dedicated integration architects. California Consumer Privacy Act compliance is forcing reconstruction of customer data architectures with audit-ready consent trails.
- Franchises:Distributed ownership structures demand centralized platform governance with localized execution flexibility. Franchise operators in Texas and Florida metropolitan corridors are adopting unified commerce platforms to standardize curbside fulfillment across independently owned locations.
- Small Businesses:Native SaaS adoption accelerates as merchant acquirers bundle payments with commerce platforms.
- Startups:API-first composable stacks enable rapid channel experimentation without monolithic suite commitments.
Franchise deployments are expanding most quickly; Large Enterprises anchor current revenue concentration.
Service Type:
Professional services intensity correlates directly with legacy system fragmentation and regulatory jurisdiction count.
- Integration Services:Middleware architects design fault-tolerant APIs connecting ERP, POS, and marketplace channels with sub-second synchronization requirements. EU AI Act algorithmic transparency mandates are accelerating demand for documentation-heavy deployment projects across European operations.
- Consulting Services:Strategic advisors map cloud migration pathways and data residency strategies for multi-jurisdiction retailers. Mid-market United States merchants with 50-200 locations seek guidance on hybrid deployment architectures balancing elasticity with on-premises resilience.
- Support Services:Technical assistance maintains platform uptime during peak transaction periods.
- Maintenance Services:Patch management and security updates preserve compliance posture.
Integration Services command premium pricing; Consulting Services are gaining share fastest.
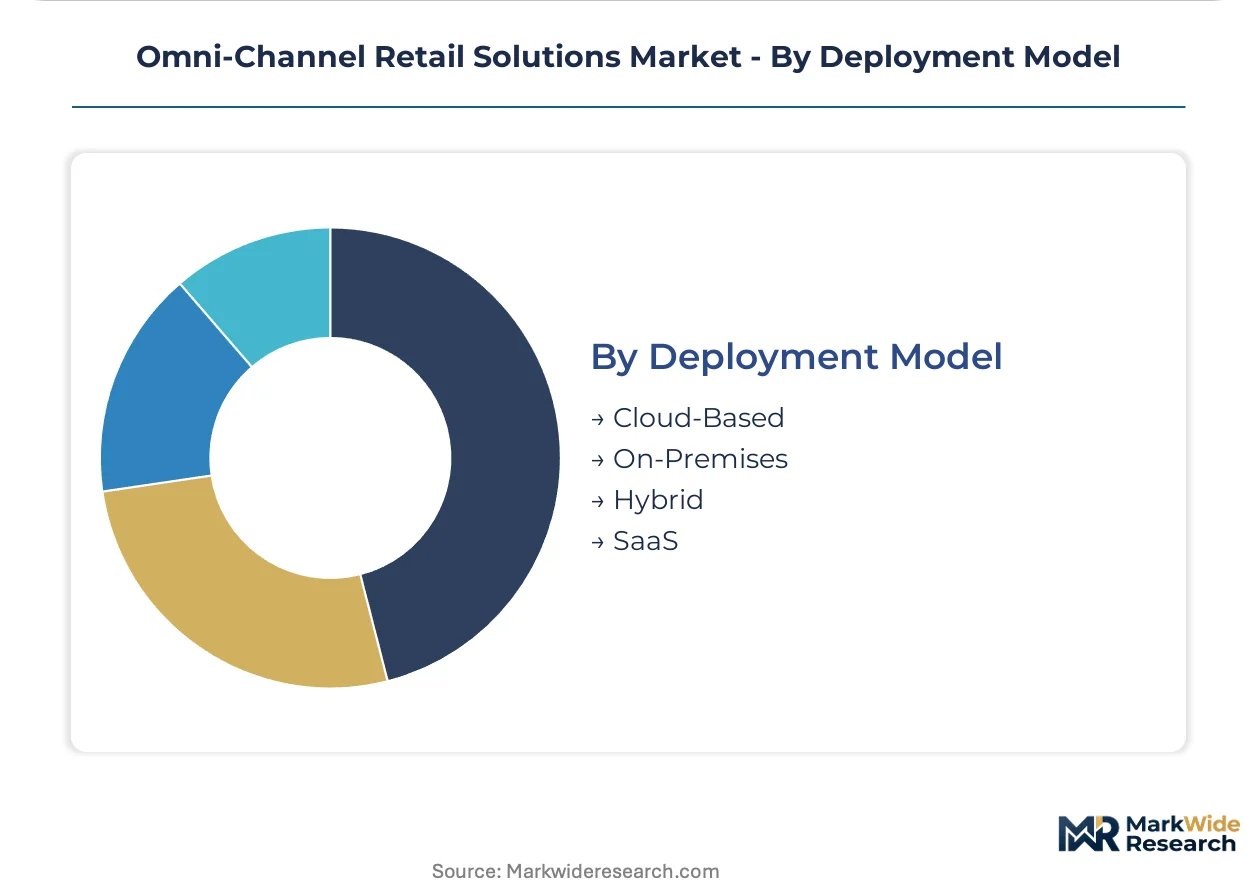
Deployment Model:
Data residency requirements and egress cost volatility shape architecture decisions more than pure technical preference.
- Cloud-Based:Elastic compute and storage resources scale with transaction volume without capital-intensive infrastructure investment. State-level privacy statute proliferation in the United States is complicating single-tenant strategies and inflating compliance architecture costs.
- Hybrid:On-premises POS resilience combines with cloud-native analytics and inventory orchestration. United States mid-market retailers facing FTC loyalty program scrutiny favor hybrid models for customer data custody control.
- SaaS:Subscription-priced platforms reduce upfront capital requirements and accelerate feature deployment cycles.
- On-Premises:Self-managed infrastructure persists in highly regulated verticals with strict data localization mandates.
Hybrid architectures anchor current deployments; Cloud-Based models are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Shenzhen and Dubai Internet City are concentrating omni-channel platform development through tax-advantaged R&D facilities and data residency incentives.
United States
Mid-market retailers with 50-200 locations are driving hybrid deployment demand, combining cloud elasticity with on-premises POS resilience. The FTC scrutinizes data aggregation in loyalty programs, compelling consent management upgrades. California's CCPA enforcement is accelerating customer data architecture reconstruction across Los Angeles and San Francisco Bay Area retail clusters.
Germany
Enterprise-scale merchants prioritize algorithmic transparency for automated pricing engines under EU AI Act mandates. The ECHA and national data protection authorities enforce strict audit trail requirements. Berlin and Munich retail technology corridors host concentrated platform development for cross-border compliance architectures.
United Kingdom
Post-Brexit data residency requirements are fragmenting deployment strategies for cross-channel inventory synchronization. The Information Commissioner's Office enforces GDPR-aligned consent frameworks. London's fintech-retail convergence zone drives headless commerce adoption among digitally native merchant segments.
China
Domestic platform ecosystems are decoupling from Western cloud infrastructure amid data localization mandates. MIIT and SAMR impose algorithmic recommendation system regulations. Shenzhen's special economic zone anchors hardware-POS integration manufacturing for Asia-Pacific distribution networks.
United Arab Emirates
Dubai Internet City's free zone incentives attract regional headquarters for Middle East omni-channel expansion. The UAE's data protection law and central bank digital commerce guidelines shape platform selection. Abu Dhabi's retail-tech cluster concentrates luxury merchant adoption of unified commerce stacks.
Omni-Channel Retail Solutions Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with legacy infrastructure vendors defending installed bases while cloud-native challengers capture greenfield deployments. The vendor landscape organizes around three archetypes: full-suite platform consolidators, best-of-breed component specialists, and hybrid middleware integrators. Competitive dynamics center on M&A-driven capability expansion and strategic partnerships bridging legacy-to-cloud migration pathways.
Within the legacy-to-cloud transition archetype, NCR Corporation, Oracle Corporation, and Manhattan Associates occupy anchor positions. NCR Corporation exemplifies the point-of-sale infrastructure incumbent extending into cloud-native architectures. Oracle Corporation represents the enterprise database and ERP giant consolidating commerce functions into integrated cloud stacks. Manhattan Associates anchors the distributed order management specialization tier, with warehouse orchestration capabilities converging toward unified inventory visibility platforms.
| Leading Market Players |
|---|
| NCR Corporation |
| Shopify Plus |
| Kibo Commerce |
| Oracle Corporation |
| Salesforce |
| IBM Corporation |
| SAP SE |
| Adobe |
| Manhattan Associates |
| Others |
Cost & Logistics Intelligence
Elastic compute egress fees from hyperscale providers cascade through SaaS subscription tiers, compressing margins for cloud-native platform vendors while forcing mid-market retailers toward hybrid architectures that retain on-premises POS resilience.
Pricing Analysis
Short lead-time deployment premiums command pricing separation from standard implementation cycles in the integration services tier. Three-tier pricing structure across premium, standard, and economy levels segments by customization depth and API governance complexity. Pricing pressure stems from merchant acquirer bundling of payments with baseline commerce platforms. Small businesses exhibit highest price sensitivity; large enterprises with fragmented legacy stacks absorb premium professional services rates.
Supply Chain Analysis
EU AI Act domestic-content documentation mandates are reshaping sourcing for algorithmic audit trail components deployed in European operations. Hardware manufacturing concentrates in China, software development clusters in the United States, and integration talent pools in Germany and the United Kingdom. Cloud infrastructure draws from hyperscale provider networks spanning regional availability zones. Single-source vulnerability sits with concentrated hyperscale dependency. Distribution runs through direct enterprise sales, systems integrator channels, and merchant acquirer bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
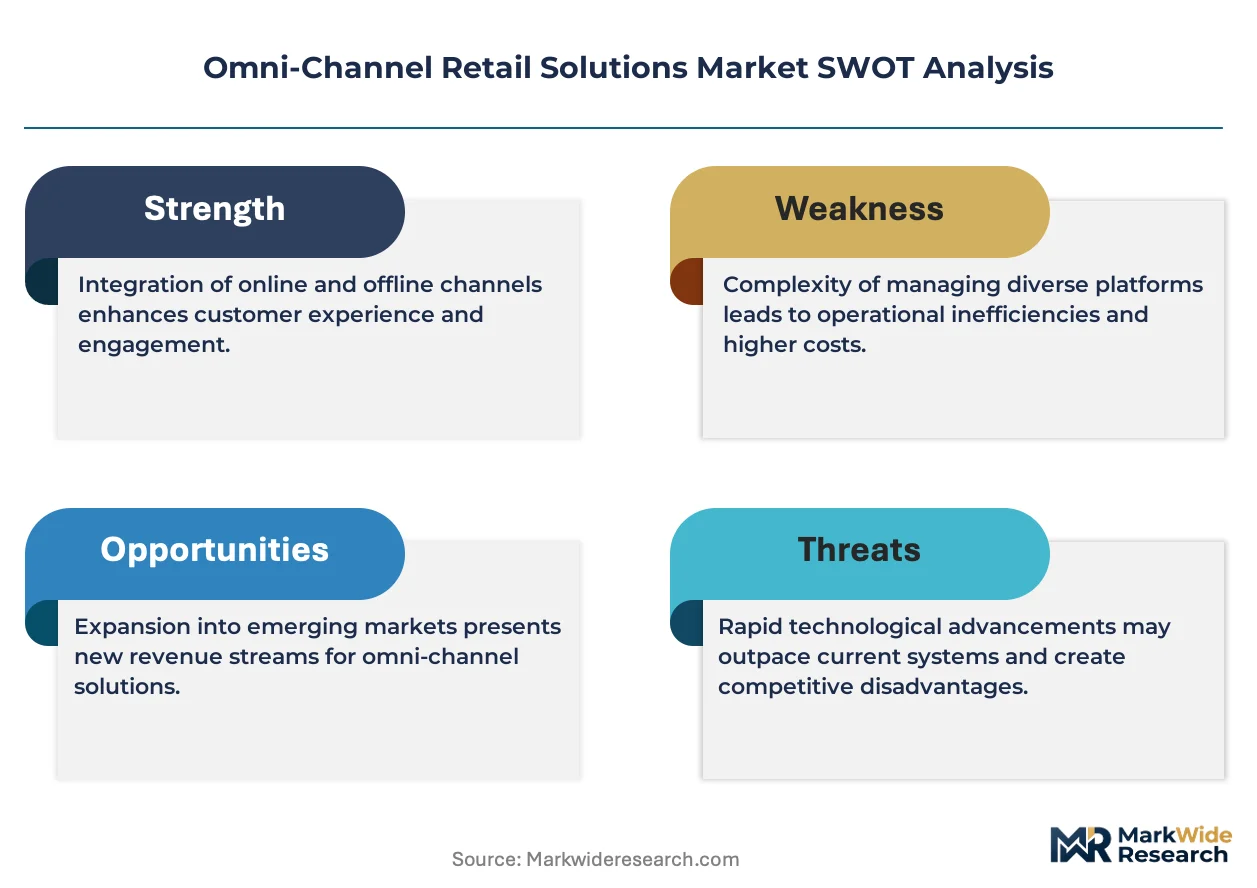
The EU AI Act's algorithmic transparency requirements have erected a compliance moat that favors incumbent platform vendors with dedicated governance functions and documentation infrastructure.
For Market Incumbents: Deepen vertical integration into middleware and API governance capabilities to defend against cloud-native challengers eroding the integration services tier. Fortify hybrid deployment architectures for United States mid-market retailers seeking on-premises POS resilience alongside cloud elasticity. Prioritize certification investment for EU AI Act audit-ready algorithmic documentation. For New Entrants and Emerging Players: Capture white space in privacy-forward customer data platforms with built-in consent audit trails responding to FTC loyalty program scrutiny. Target franchise operators in Texas and Florida metropolitan corridors standardizing curbside fulfillment across independently owned locations. Lead with API-first composable stacks enabling rapid channel experimentation without monolithic suite commitments. For Investors and Strategic Acquirers: Mid-market hybrid deployment acceleration across 50-200 location retailers is the leading indicator that consolidation momentum will concentrate among vendors bridging legacy-to-cloud migration pathways. Five-to-ten year viability favors acquisition targets with distributed order management specialization and warehouse orchestration convergence capabilities. Monitor hyperscale egress pricing volatility as an inflection signal for margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| API Governance Platform Acquisition | Consolidates middleware capabilities for real-time ERP-POS synchronization demanded by specialty apparel retailers. |
| Hybrid Deployment Architecture Launch | Addresses United States mid-market demand combining cloud elasticity with on-premises POS resilience. |
| EU AI Act Compliance Certification | Creates algorithmic audit trail differentiation for automated pricing engines in European markets. |
| Franchise Operator Channel Partnership | Standardizes curbside fulfillment orchestration across distributed ownership structures in Texas and Florida. |
| Headless Commerce Platform Integration | Decouples frontend experience from backend fulfillment for faster merchant experimentation cycles. |
Research Approach
Document review covered SEC filings from NCR Corporation, Oracle Corporation, and Manhattan Associates, complemented by interviews with retail technology executives, integration architects, franchise operations directors, and merchant acquirer product managers. Secondary validation drew from FTC enforcement actions, EU AI Act implementation guidance, California Attorney General CCPA opinions, and hyperscale provider capex disclosures. Bottom-up merchant deployment estimates triangulated against top-down platform vendor revenue segmentation.
Market size and growth trajectory outputs reflect analytical framework segmentation across deployment model, customer scale tier, service type intensity, and regional regulatory cluster complexity. CAGRs were derived from elasticity-adjusted adoption curves incorporating compliance mandate acceleration effects. Forecast inputs included ship-from-store retrofit timelines, API governance talent availability constraints, and state-level privacy statute proliferation patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hyperscale pricing volatility, federal privacy preemption debates, and algorithmic transparency enforcement divergence between EU and United States jurisdictions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Global Advanced Shopping Technology Market
Retail Technology
Smart Shelves Market
Retail Technology
Global Kiosk Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
America's AI in the Retail Market
Retail Technology
Digital Kiosk Market
Retail Technology
Global Smart Retail Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Smart Retail Systems Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
North America Automation in Retail Market
Retail Technology
Smart Shopping Cart Market