
 America's AI in the Retail Market | 2026-2036
America's AI in the Retail Market Size, Share, and Industry Trends Forecast 2026-2036
America's AI in the Retail Market Outlook
The capability gap between cloud-native AI infrastructure and legacy retail IT systems is collapsing. Amazon Web Services leverages its vertically integrated chip-to-software stack to dominate enterprise-grade retail AI deployments. Microsoft Azure sustains competitive positioning through deep ERP integration capabilities that anchor mid-market grocery and apparel chains. NVIDIA specializes in GPU-accelerated inference architectures that extend real-time demand forecasting to edge locations.
America's AI in the Retail encompasses machine learning algorithms, natural language processing engines, computer vision systems, and predictive analytics platforms deployed across digital and physical retail channels to automate merchandising, personalize consumer engagement, and optimize supply chain decisions. These technologies process transaction data, visual shelf imagery, and conversational inputs through cloud-based, on-premises, hybrid, or edge computing architectures to generate actionable intelligence within sub-second latency thresholds. Cloud-based deployment leads current adoption due to elastic scaling during peak retail seasons, while edge computing represents the fastest-growing segment as retailers seek to reduce bandwidth costs and enable real-time inventory tracking in distributed store networks. Machine learning occupies the largest technology share by revenue, though computer vision commands premium pricing in automated checkout and loss-prevention applications.
The National Institute of Standards and Technology AI Risk Management Framework and the Federal Trade Commission's guidance on algorithmic fairness shape vendor compliance requirements and procurement standards for retail AI systems. State-level privacy laws, including the California Consumer Privacy Act and emerging biometric regulations in Illinois and Texas, constrain how retailers deploy facial recognition and behavioral analytics in physical stores. Stakeholders must monitor evolving patchworks of federal and state AI governance to anticipate compliance costs and deployment restrictions that will determine competitive access across American retail markets.
Market Dynamics
The Federal Trade Commission's algorithmic fairness guidance and state biometric laws are compressing deployment timelines for computer vision systems in physical retail environments across American stores.
Growth Catalysts
- Computer vision adoption:Grocery chains in California and Texas deploy automated checkout systems to reduce labor costs and shrinkage rates in high-traffic store formats.
- NIST AI Risk Management Framework:Federal procurement standards create compliance roadmaps that accelerate enterprise vendor qualification cycles for retail AI platforms.
- Predictive analytics integration:E-commerce platforms anchor inventory forecasting demand, pulling cloud-native machine learning infrastructure into mid-market retail operations.
Market Restraints
- GPU supply concentration:NVIDIA's dominance in AI inference accelerators creates single-source dependency risks for retailers scaling edge computing deployments.
- Biometric regulatory friction:Illinois Biometric Information Privacy Act and Texas biometric laws constrain facial recognition deployment in loss-prevention applications.
- Legacy IT integration costs:Mainframe-era inventory systems in established retail chains require expensive middleware layers to interface with cloud AI platforms.
Strategic Opportunities
- Edge computing expansion:Bandwidth cost reduction incentives drive real-time inventory tracking deployments in distributed store networks across the American Midwest.
- Natural language processing convergence:Voice-enabled customer service interfaces merge with recommendation engines to capture conversational commerce transactions.
- California Consumer Privacy Act tailwinds:Compliance tooling demand creates adjacent revenue streams for AI governance and data lineage software vendors serving retail clients.
Industry Challenges
- MLOps talent scarcity:Retailers struggle to hire machine learning operations specialists capable of maintaining production inference pipelines across hybrid cloud-edge architectures.
- Algorithmic audit complexity:Third-party fairness certification timelines stretch 12-18 months, delaying rollout of pricing optimization models in regulated jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | America's AI in the Retail Market |
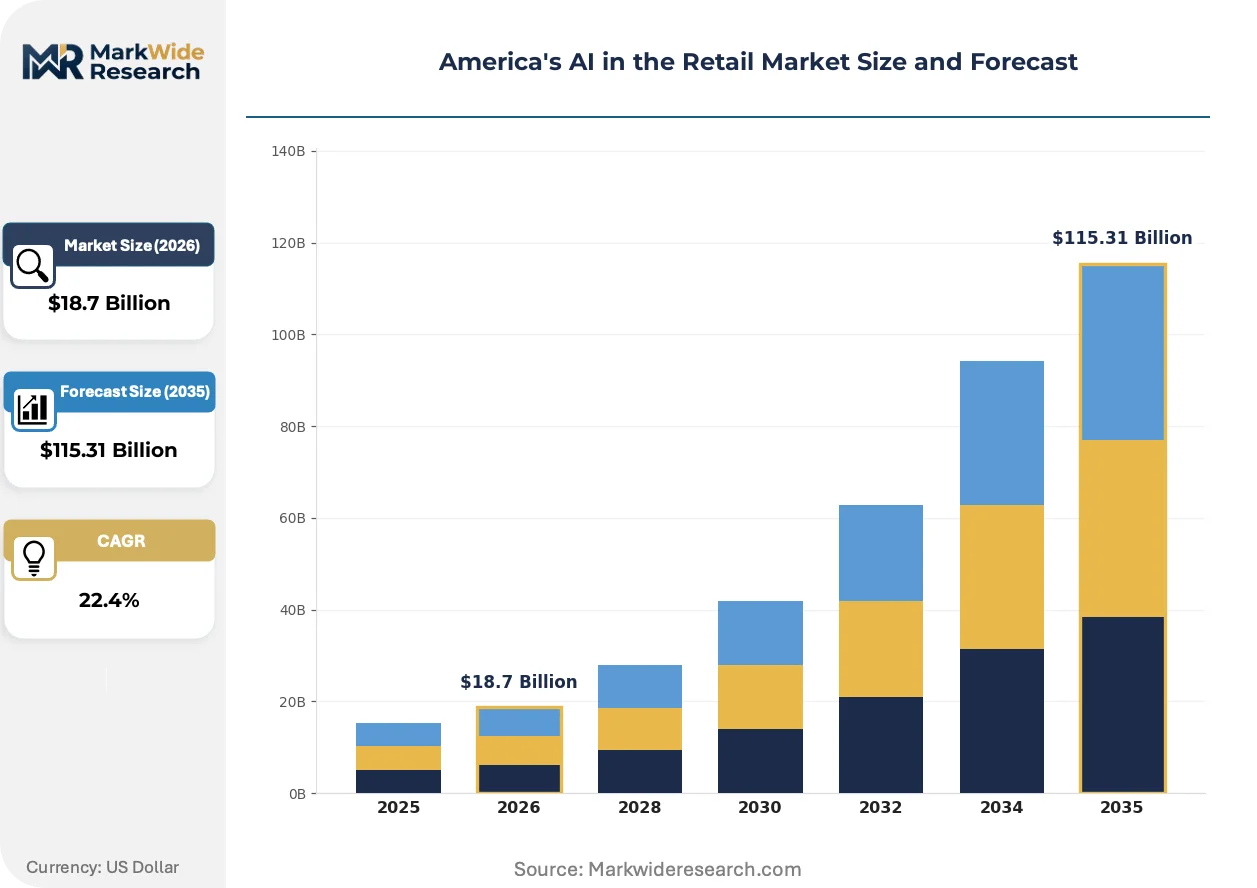
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Customer Service, Inventory Management, Personalized Marketing, Fraud Detection Technology: Machine Learning, Natural Language Processing, Predictive Analytics, Computer Vision Deployment: Cloud-based, On-premises, Hybrid, Edge Computing End User: E-commerce, Brick-and-Mortar Stores, Wholesalers, Distributors |
| Companies Covered | Amazon Web Services (AWS), Microsoft Azure, Google Cloud, IBM Corporation, Salesforce, Oracle, NVIDIA, Intel, ServiceNow, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
America's AI in the Retail Market Strategic Shifts
Retail AI infrastructure is splitting between hyperscale cloud deployments and localized edge inference, with regulatory pressure and latency requirements driving divergent technical architectures.
Multimodal AI systems combining computer vision with natural language processing are bifurcating merchandising workflows. Apparel retailers adopt these platforms for automated product tagging and visual search. The technology is compressing content production cycles from weeks to hours, forcing traditional studio photography vendors into defensive repositioning.
The Federal Trade Commission's guidance on algorithmic fairness imposes documentation burdens on pricing and recommendation systems. Retailers must maintain audit trails for model training data and decision logic. Mid-market grocery chains face the steepest compliance costs, as they lack dedicated AI governance functions present at larger competitors.
Buying patterns for retail AI are fragmenting between centralized procurement through cloud marketplaces and direct vendor relationships for specialized computer vision applications. Department stores favor marketplace consolidation for generic analytics, while loss-prevention teams maintain separate vendor contracts for biometric systems. This bifurcation is most pronounced in Texas and Florida, where retail footprints span hundreds of locations with heterogeneous IT estates.
America's AI in the Retail Market Segmentation
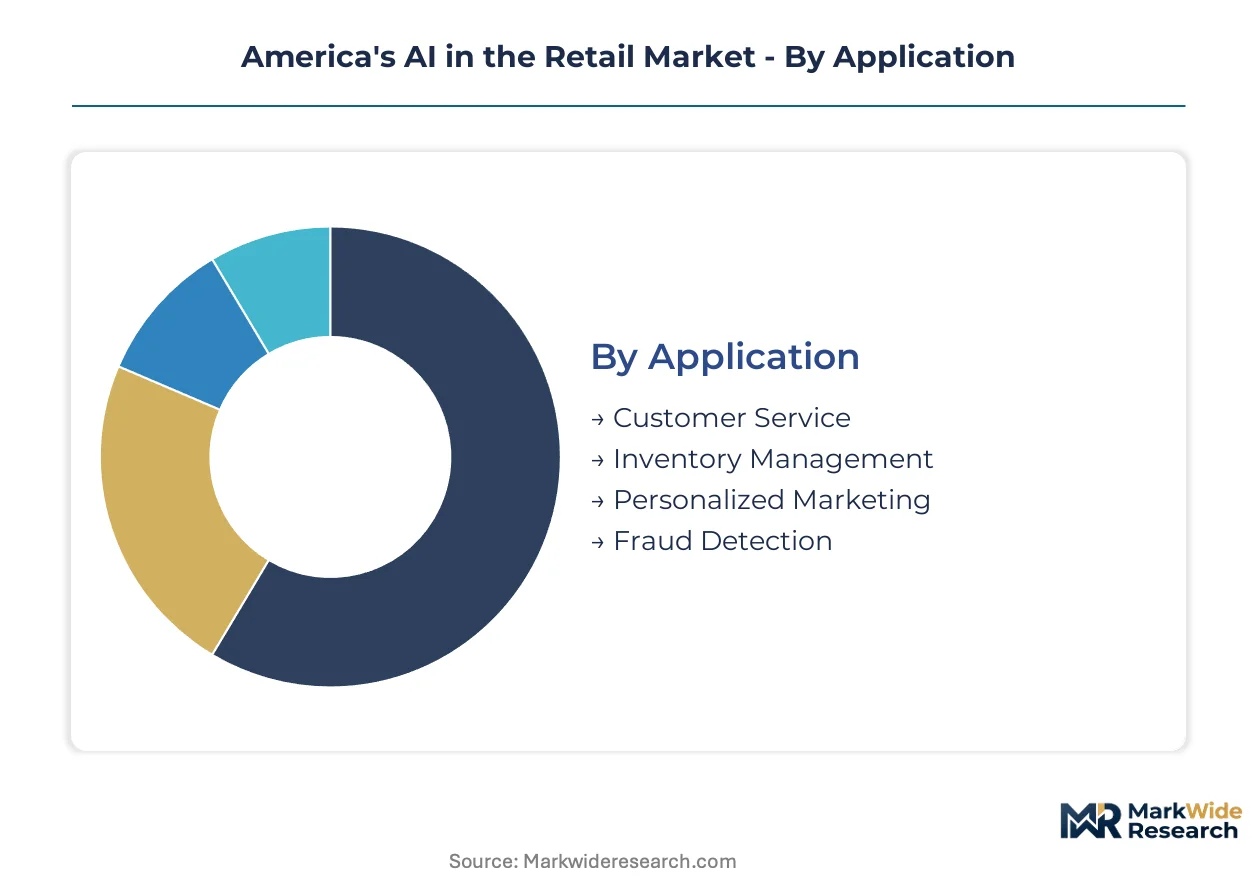
Retail AI segmentation reveals how regulatory pressure and infrastructure economics reshape technology procurement across American retail channels. Deployment choices increasingly hinge on state biometric laws and federal procurement standards rather than pure technical performance.
Application:
The Federal Trade Commission's algorithmic fairness guidance and Illinois Biometric Information Privacy Act create divergent compliance burdens across use cases, forcing retailers to segment investments by audit complexity.
- Customer Service:Natural language processing engines power chatbots and voice assistants that handle order inquiries and returns. E-commerce platforms in California concentrate demand here, driven by California Consumer Privacy Act requirements for transparent automated decision-making.
- Inventory Management:Predictive models forecast stock levels across distributed fulfillment networks. Midwest grocery chains anchor adoption, seeking to reduce carrying costs while maintaining availability through machine learning demand sensing.
- Personalized Marketing:Recommendation algorithms segment consumers based on behavioral signals and transaction history.
- Fraud Detection:Anomaly detection systems flag suspicious payment patterns and account behaviors in real-time transaction streams.
Inventory Management handles the majority of throughput; Customer Service is expanding most quickly on share.
Technology:
Cost tier differentiation separates commodity analytics infrastructure from premium computer vision systems commanding specialized hardware premiums.
- Machine Learning:Supervised and unsupervised algorithms form the foundational layer for demand forecasting, pricing optimization, and customer segmentation. Cloud-native deployments dominate, with elastic scaling during holiday retail peaks driving hyperscale provider preference.
- Computer Vision:GPU-accelerated inference architectures process visual shelf imagery and enable automated checkout. Texas and California grocery chains concentrate demand, constrained by state biometric regulations that lengthen deployment timelines.
- Natural Language Processing:Text and speech analysis engines extract intent from customer service interactions and product reviews.
- Predictive Analytics:Statistical models project future demand patterns and operational outcomes from historical data.
Machine Learning captures the largest revenue base; Computer Vision is climbing the fastest on pricing premium.
Deployment:
Volume concentration in cloud infrastructure is shifting as bandwidth economics and latency requirements pull inference workloads toward distributed architectures.
- Cloud-based:Elastic compute resources scale dynamically with transaction volumes and seasonal demand fluctuations. E-commerce platforms anchor adoption, prioritizing capital efficiency over data locality.
- Edge Computing:Localized inference nodes process data within store premises to minimize latency and network transit costs. American Midwest retail networks drive expansion, seeking real-time inventory tracking without cloud dependency.
- Hybrid:Split architectures route sensitive data to on-premises systems while leveraging cloud burst capacity.
- On-premises:Dedicated infrastructure maintains full data sovereignty for high-security retail environments.
Cloud-based deployment retains volume leadership; Edge Computing is gaining share fastest on infrastructure investment.
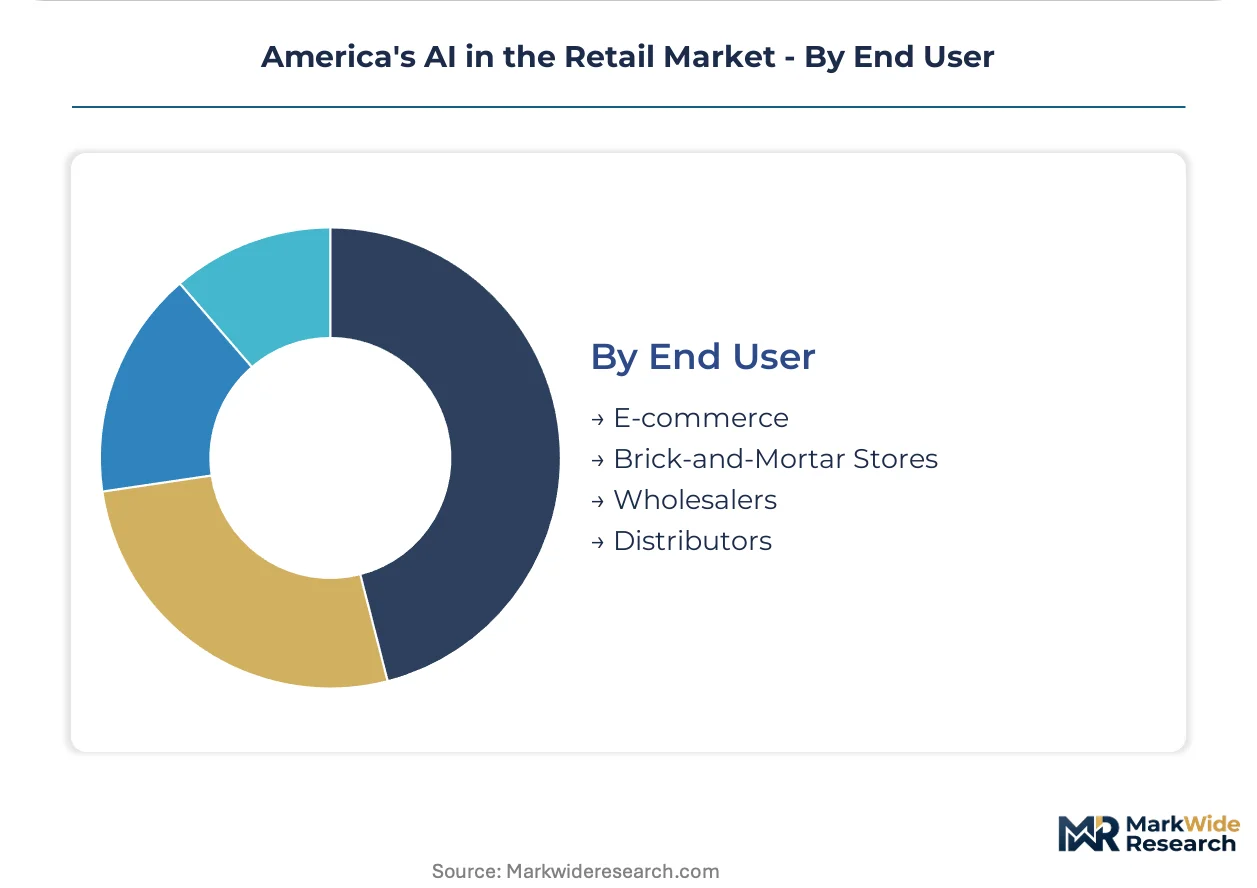
End User:
Customer type maturity determines procurement sophistication, with digital-native retailers advancing faster on AI integration than physical-format incumbents.
- E-commerce:Digital-first retailers deploy comprehensive AI stacks across recommendation, logistics, and customer service functions. Predictive analytics for inventory forecasting anchors technology spend, pulling cloud-native infrastructure investment.
- Brick-and-Mortar Stores:Physical retailers concentrate computer vision investment in automated checkout and loss prevention. California and Texas grocery chains lead deployment, navigating biometric regulatory complexity.
- Wholesalers:B2B distributors apply demand forecasting to optimize procurement and warehouse operations.
- Distributors:Supply chain intermediaries leverage route optimization and inventory positioning algorithms.
E-commerce commands the technology investment lead; Brick-and-Mortar Stores show the steepest expansion trajectory on computer vision adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in California and Texas, where grocery chains absorb premium computer vision costs, while Midwest retailers face margin compression from legacy IT integration burdens.
California
E-commerce platforms anchor predictive analytics demand, pulling cloud-native machine learning infrastructure into Los Angeles and San Francisco Bay Area operations. The California Consumer Privacy Act imposes transparent automated decision-making requirements on customer service AI deployments. Computer vision adoption clusters in San Diego and Central Valley grocery chains deploying automated checkout systems.
Texas
Grocery chains in Dallas-Fort Worth and Houston metro areas drive automated checkout expansion to reduce labor costs and shrinkage rates. The Texas Capture or Use of Biometric Identifier Act constrains facial recognition deployment timelines for loss-prevention applications. Austin's technology corridor hosts edge computing pilot programs for real-time inventory tracking in distributed store networks.
Illinois
Midwest grocery and apparel chains concentrate inventory management investment, seeking demand forecasting to optimize carrying costs across Chicago and Peoria distribution networks. The Illinois Biometric Information Privacy Act creates compliance friction for computer vision deployment in physical retail environments. Rockford and Springfield retail networks face extended vendor qualification cycles under federal procurement standards.
New York
Manhattan and Brooklyn e-commerce operations sustain natural language processing investment for voice-enabled customer service interfaces. State-level privacy legislation shapes algorithmic audit requirements for pricing optimization models. Buffalo and Rochester retail networks pursue hybrid cloud-edge architectures to balance data sovereignty with burst capacity needs.
Florida
Miami and Tampa retail footprints spanning heterogeneous IT estates fragment procurement between cloud marketplaces and direct vendor relationships. Biometric regulatory gaps relative to Illinois and Texas accelerate computer vision pilot programs in loss-prevention applications. Orlando's tourism-adjacent retail clusters experiment with conversational commerce transactions through merged recommendation engines.
America's AI in the Retail Market Competitive Environment
Concentration sits with hyperscale cloud providers commanding enterprise-grade retail AI deployments through vertically integrated infrastructure stacks. The vendor base splits between full-stack platform operators and specialized hardware accelerators. Three archetypes dominate: cloud-native platform providers with ERP integration capabilities, GPU-accelerated inference specialists, and enterprise software vendors with pre-built retail modules. Competitive moves center on strategic partnerships with grocery chains and technology licensing arrangements for edge computing architectures.
Within the hyperscale tier, Amazon Web Services, Microsoft Azure, and NVIDIA occupy distinct positioning. Amazon Web Services exemplifies the vertically integrated archetype through chip-to-software stack control. Microsoft Azure represents ERP-anchored competitive positioning that sustains mid-market grocery and apparel chain relationships. NVIDIA occupies the specialized hardware accelerator position, with GPU architectures extending real-time demand forecasting to distributed edge locations.
| Leading Market Players |
|---|
| Amazon Web Services (AWS) |
| Microsoft Azure |
| Google Cloud |
| IBM Corporation |
| Salesforce |
| Oracle |
| NVIDIA |
| Intel |
| ServiceNow |
| Others |
Value Chain & Pricing Dynamics
Ninety-day GPU lead times for NVIDIA inference accelerators compress margins across edge-computing deployments while amplifying pricing power for cloud-native platform providers with captive silicon supply. This inventory bottleneck reshapes procurement hierarchies, forcing Midwest grocery chains toward hybrid architectures and concentrating premium pricing among vertically integrated hyperscalers.
Pricing Analysis
The customization-premium spread between configured-to-order edge inference nodes and standard cloud API pricing spans subscription SaaS tiers for machine learning platforms, per-unit transactional licensing for computer vision modules, and project-based professional services for legacy ERP integration. Price differentiation rests on certification level under NIST AI Risk Management Framework compliance tiers and volume scale commitments across multi-year enterprise agreements. Pricing pressure intensifies downward through commodity analytics tiers as open-source frameworks erode baseline machine learning infrastructure margins. E-commerce platforms exhibit lowest price sensitivity due to elastic scaling demands during peak retail seasons, while mid-market brick-and-mortar chains face acute cost compression from biometric regulatory compliance overhead.
Supply Chain Analysis
Inbound logistics costs through Los Angeles and Long Beach port congestion elevate landed costs for GPU hardware destined to Texas and California edge-computing deployments. Supply concentrates in Taiwan for advanced semiconductor fabrication, South Korea for memory components, and domestic U.S. facilities for final system integration and NIST compliance certification. Raw material dependencies span silicon wafers, specialized cooling substrates, and high-bandwidth memory modules. Single-source vulnerability risks concentrate around NVIDIA's dominance in AI inference accelerators. Distribution runs through hyperscale cloud marketplaces for standardized analytics infrastructure and direct vendor relationships for specialized computer vision hardware.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
America's AI in the Retail Market sits in cyclical recovery as post-pandemic inventory destocking concludes and retailers reinvest in automation infrastructure. Federal procurement standardization under NIST frameworks accelerates enterprise qualification cycles.
For Market Incumbents: Secure backward integration into specialized AI chip design or captive cloud infrastructure to defend margin position against hyperscale commoditization pressure. Anchor ERP integration capabilities deeper into mid-market grocery and apparel chain workflows to create switching cost moats. Prioritize MLOps talent acquisition in Chicago and Austin corridors where machine learning operations specialist scarcity threatens production pipeline reliability.
For New Entrants and Emerging Players: Anchor in Illinois and Florida biometric regulatory gaps where computer vision deployment timelines lag California and Texas, creating white-space for loss-prevention applications. Target conversational commerce convergence between natural language processing and recommendation engines as the most penetrable application layer. Pursue channel partnerships with existing POS system integrators rather than direct enterprise sales to accelerate grocery chain access.
For Investors and Strategic Acquirers: Long-term, this sits as a infrastructure consolidation play because edge-computing hardware deployment scales create natural monopoly economics across distributed store networks. Target acquisition archetypes include specialized computer vision vendors with Illinois BIPA compliance tooling and MLOps platforms with production-grade retail inference pipelines. Watch federal procurement standardization velocity as the critical inflection signal determining competitive access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| NIST AI Risk Management Framework Certification | Federal procurement standards accelerate enterprise vendor qualification cycles for retail AI platforms. |
| Edge Computing Architecture Deployment | Real-time inventory tracking in Midwest distributed store networks reduces bandwidth costs and cloud dependency. |
| Computer Vision Hardware Partnership | Automated checkout systems in California and Texas grocery chains compress labor costs and shrinkage rates. |
| MLOps Platform Acquisition | Production inference pipeline maintenance capabilities address talent scarcity constraining hybrid cloud-edge architectures. |
| Biometric Compliance Tooling Development | Illinois BIPA and Texas biometric law adherence creates adjacent revenue streams for governance software vendors. |
Study Parameters
A spread of perspectives from retail technology procurement officers, grocery chain operations executives, cloud platform solution architects, computer vision hardware vendors, and federal compliance consultants converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings from hyperscale providers, NIST AI Risk Management Framework documentation, state biometric law legislative records, and hyperscaler capital expenditure disclosures. Bottom-up demand modeling triangulated against top-down market sizing across deployment mode, technology type, and end-user segment dimensions.
Segmentation dimensions modeled encompass application layer (customer service, inventory management, personalized marketing, fraud detection), technology stack (machine learning, computer vision, natural language processing, predictive analytics), deployment architecture (cloud-based, edge computing, hybrid, on-premises), and end-user category (e-commerce, brick-and-mortar stores, wholesalers, distributors). CAGRs were derived through regression analysis of historical adoption curves and forward projection of regulatory compliance cost trajectories. Industry-specific forecast inputs included GPU supply availability constraints and state-level biometric legislation implementation timelines.
Underlying assumptions cover sustained federal procurement standardization momentum and stable hyperscale cloud pricing elasticity, with deviation risk concentrated in export control restrictions affecting semiconductor supply chains and accelerated state privacy law fragmentation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Customer-Facing Technology Market
Retail Technology
Global Kiosk Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
US Retail Recon Software Market
Retail Technology
Smart Shelf Market
Retail Technology
E-Retail Market
Retail Technology
US Self-Checkout Systems Market
Retail Technology
Digital Kiosk Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
Enterprise Mobility in Retail Market
Retail Technology
Self-Service Market
Retail Technology
Smart Shelves Market
Retail Technology
Cash Register Machines Market
Retail Technology
Retail Inventory Software Market
Retail Technology
Global Restaurant Point of Sale (POS) Terminals Market
Retail Technology
Ticket Machine Market