
 Global Kiosk Market | 2026-2036
Global Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Global Kiosk Market Outlook
Aluminum alloy enclosures are replacing stamped steel chassis across outdoor and high-traffic kiosk installations, expanding unit margins through reduced corrosion maintenance and lighter freight costs. NCR Corporation leverages its integrated payments stack to anchor self-service banking and retail contracts across North America. Diebold Nixdorf competes through ATM-to-kiosk conversion programs that sustain installed-base revenue. Fujitsu dominates transit gate integrations in East Asian metro systems.
A kiosk is a freestanding, interactive terminal combining an embedded computing module, hardened display, and peripheral integration bay for printers, card readers, or biometric sensors, typically housed in steel or aluminum with IP54 minimum ingress protection for public environments. Interactive kiosks lead product type revenue as retailers replace legacy POS with self-checkout stations, while digital signage kiosks represent the fastest-growing category as DOOH networks adopt programmatic ad insertion. Cloud-based deployment is displacing on-premises management in healthcare and education, concentrating margin pools with SaaS operators.
The FDA governs kiosk-collected biometric data in US healthcare settings, while the EU Accessibility Act mandates EN 301 549-compliant interfaces for public terminals across member states. Japan's METI enforces JIS standards for outdoor terminal durability in rail and municipal applications. Stakeholders must monitor evolving cybersecurity certification requirements for payment-enabled terminals.
Market Dynamics
Self-checkout hardware refresh cycles in grocery retail are compressing replacement timelines from seven-year cycles to four-year cycles, forcing enclosure manufacturers and payment integrators to synchronize production ramps with seasonal deployment windows.
Growth Catalysts
- EU Accessibility Act mandates:EN 301 549-compliant multimodal interfaces for public terminals across member states compel interface redesigns that expand addressable user bases.
- India urban transit digitization:Metro authorities in Delhi, Mumbai, and Bengaluru are replacing legacy token systems with QR-NFC integrated gate platforms, driving hardware procurement volumes.
- Aluminum alloy substitution:Transit operators and outdoor retail deployers specify corrosion-resistant enclosures to reduce lifecycle maintenance expenditures and freight logistics costs.
Market Restraints
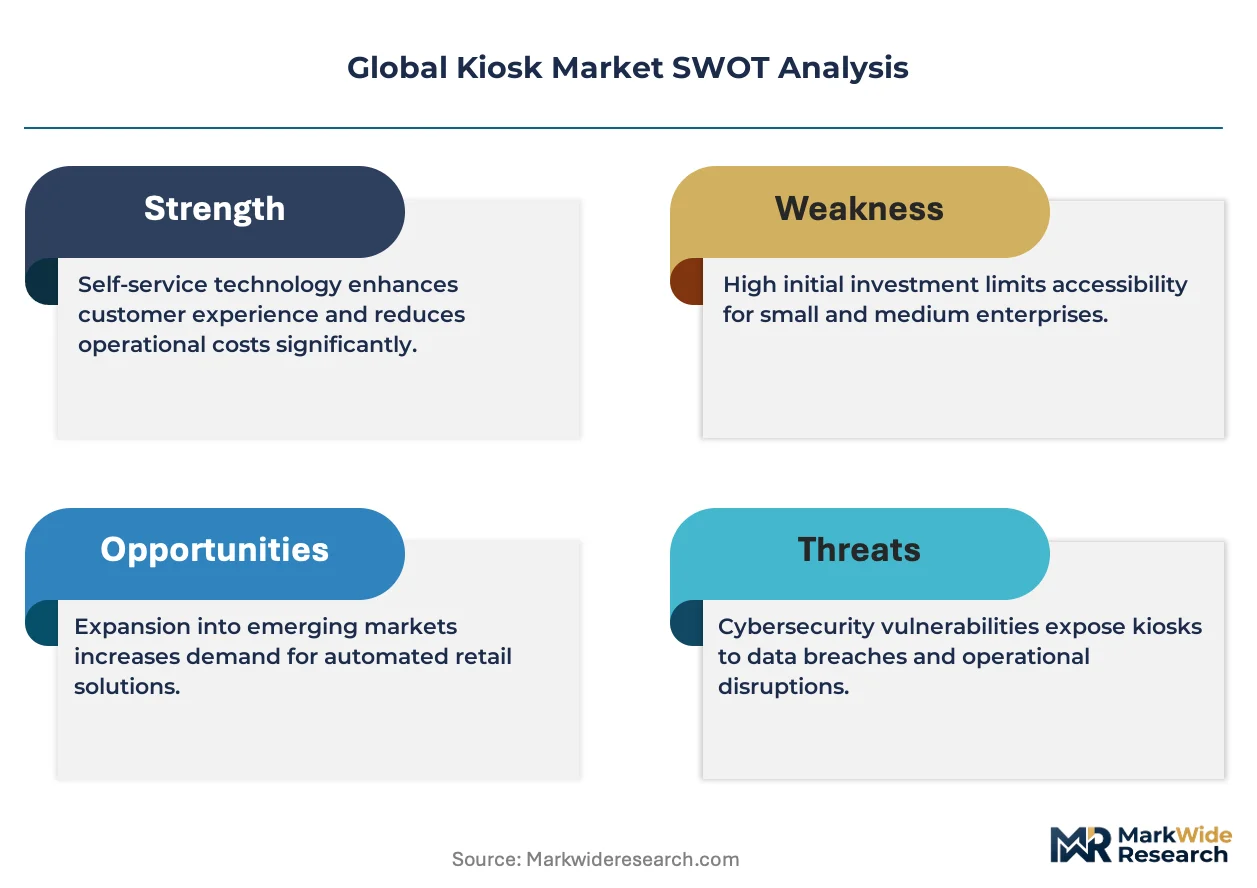
- Semiconductor supply concentration:Touch controller and secure element chip fabrication concentrates in Taiwan and South Korea, exposing kiosk OEMs to single-source disruption risk.
- Payment certification friction:PCI DSS compliance timelines for biometric-enabled terminals extend eighteen to twenty-four months, delaying product launches in healthcare and banking.
- LCD panel input volatility:Industrial-grade display glass pricing fluctuates with photovoltaic demand cycles, compressing hardware margins unpredictably.
Strategic Opportunities
- Brazil underpenetrated retail:Convenience store chains in São Paulo and Rio de Janeiro lack self-checkout density compared to North American benchmarks, creating first-mover installation potential.
- SaaS management convergence:Cloud-based kiosk fleet orchestration is overtaking on-premises server deployments in North American healthcare systems, concentrating recurring revenue with platform operators.
- Japan METI durability standards:JIS-certified outdoor terminal requirements for rail applications create specification barriers that favor suppliers with proven environmental testing capabilities.
Industry Challenges
- Cybersecurity certification complexity:Payment-enabled terminals must satisfy evolving PCI PTS and country-specific financial regulator standards simultaneously, stretching engineering validation resources.
- Legacy POS integration:Retailers operating mixed estates of traditional checkout and self-service hardware require middleware development that extends deployment timelines and inflates professional services costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Kiosk Market |
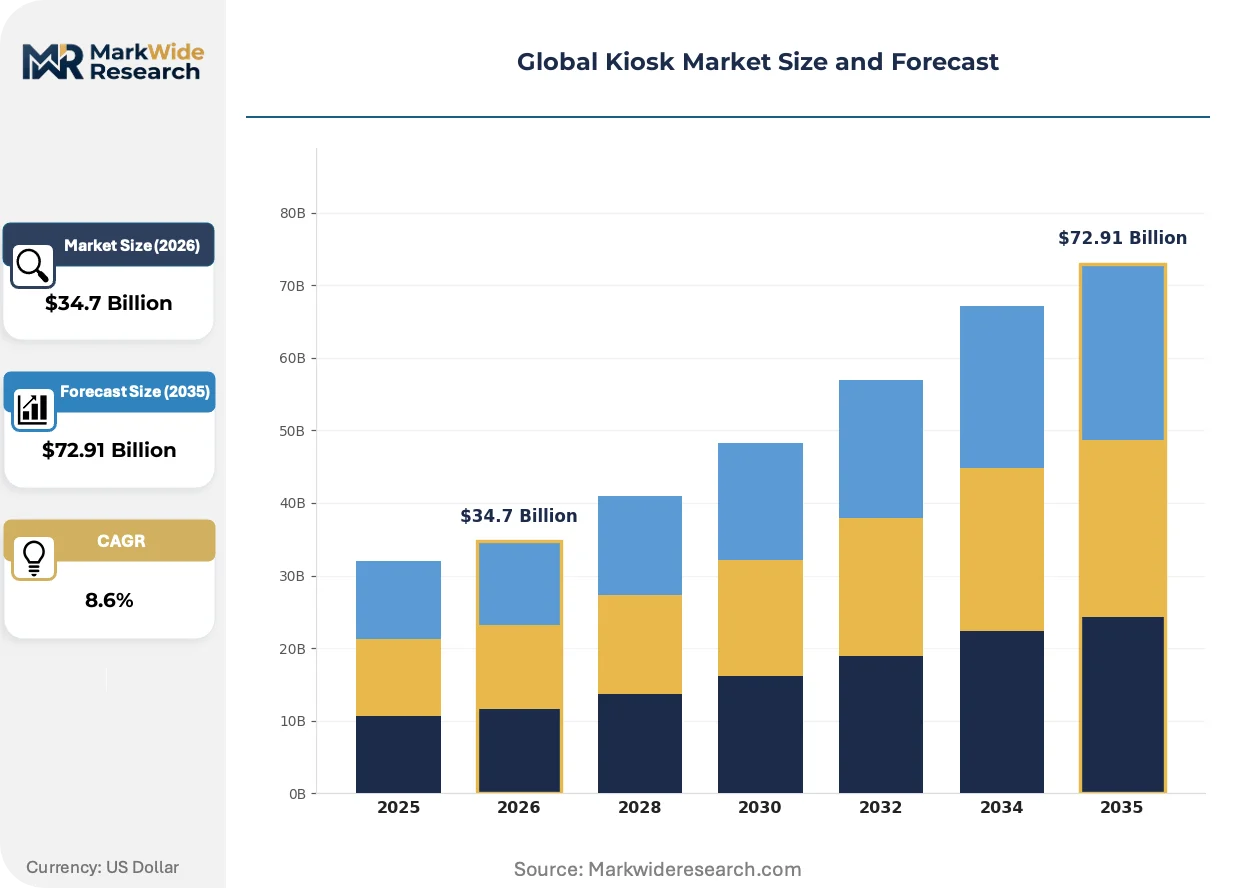
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $72.91 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interactive Kiosks, Vending Kiosks, Digital Signage Kiosks, Ticketing Kiosks End User: Retail, Healthcare, Transportation, Education Deployment: On-Premises, Cloud-Based, Self-Service, Managed Services Technology: Touchscreen, QR Code Scanning, NFC, Cloud Connectivity |
| Companies Covered | NCR Corporation, Diebold Nixdorf, Incorporated, KIOSK Information Systems, Meridian Kiosks, Advantech Co., Ltd., Zebra Technologies Corporation, Glory Ltd., Olea Kiosks Inc., Fujitsu Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Kiosk Market Strategic Shifts
Embedded biometric authentication and edge AI processing are redefining kiosk interaction paradigms, shifting competitive advantage from hardware durability to software-defined experience personalization and real-time inference capabilities.
Capacitive fingerprint and palm-vein sensors are overtaking magnetic stripe and chip-card readers as the primary authentication modality in healthcare and banking kiosks. Hospital networks in the United States deploy FDA-governed biometric data collection terminals to streamline patient check-in workflows. This authentication shift compresses transaction times while elevating cybersecurity liability exposure for terminal operators.
Japan's METI enforces JIS standards for outdoor terminal durability in rail and municipal applications, mandating vibration resistance and temperature operating ranges that exceed typical commercial specifications. East Asian metro system procurements now require demonstrated compliance with these environmental benchmarks. Fujitsu and domestic competitors anchor transit gate integration contracts through pre-certified platform architectures.
Buyer procurement patterns in North American quick-service restaurant chains favor outcome-based service contracts over capital purchase models, transferring uptime risk to kiosk fleet operators. Equipment vendors respond by embedding predictive maintenance algorithms and remote diagnostics capabilities into standard service agreements. This contractual evolution concentrates margin pools with vertically integrated providers capable of guaranteeing availability metrics.
Global Kiosk Market Segmentation
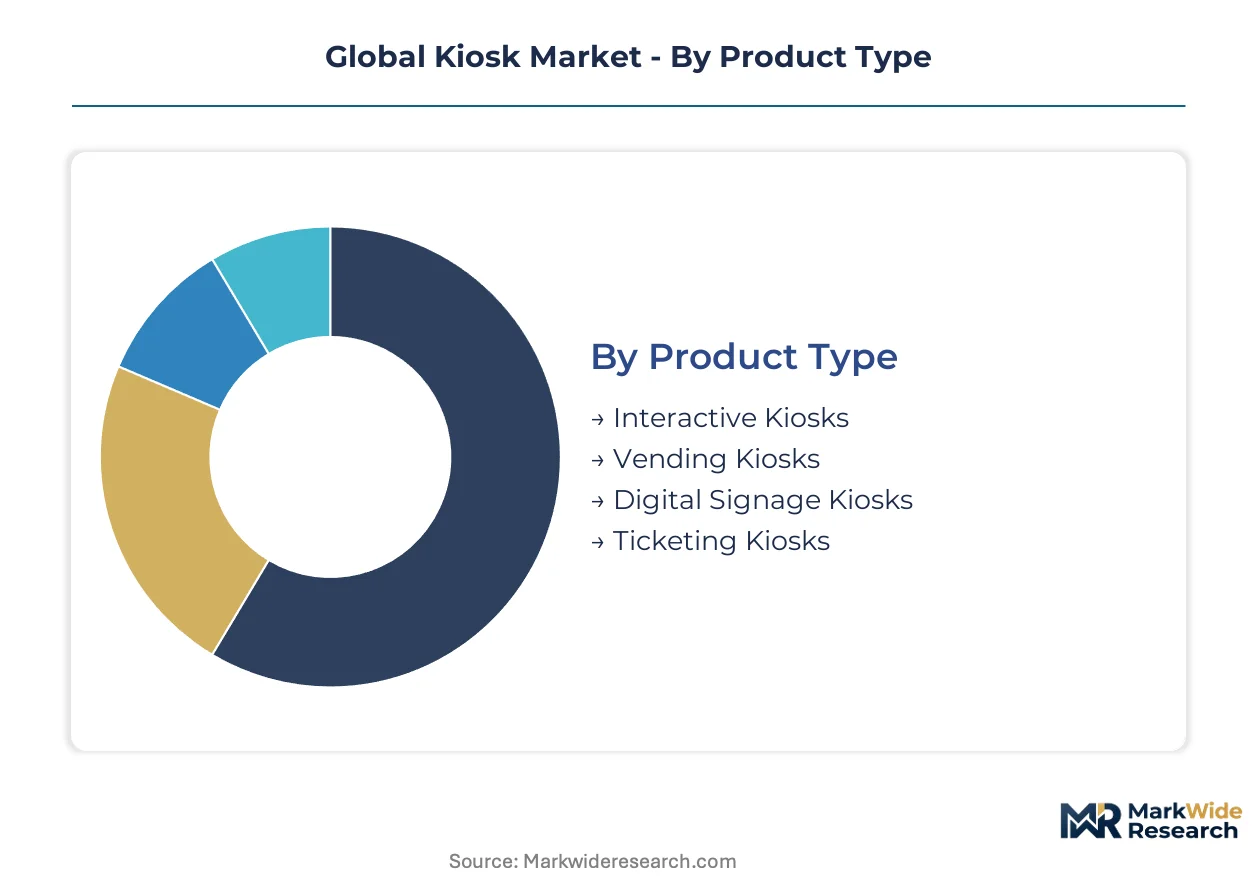
Kiosk market segmentation reveals divergent margin profiles across hardware categories, deployment architectures, and authentication technologies. Understanding these splits enables suppliers to align R&D investment with procurement patterns shifting toward software-defined service models and multimodal interfaces.
Product Type:
Interactive kiosks command premium pricing through payment integration complexity, while digital signage units scale through volume deployment in advertising networks.
- Interactive Kiosks:These terminals combine hardened displays with peripheral bays for card readers, biometric sensors, and receipt printers, typically housed in aluminum enclosures with IP54 ingress protection. Grocery chains in the United States and Germany are compressing hardware refresh cycles from seven years to four years, forcing enclosure manufacturers to synchronize production with seasonal deployment windows.
- Digital Signage Kiosks:Programmatic ad insertion capabilities and DOOH network expansion distinguish this category from passive displays. Transit authorities in India and Brazil are installing these units in metro corridors to monetize passenger dwell time through targeted advertising, though LCD panel pricing volatility tied to photovoltaic demand cycles compresses hardware margins unpredictably.
- Vending Kiosks:Automated retail terminals with integrated payment stacks and inventory management sensors.
- Ticketing Kiosks:QR-NFC integrated gate platforms replacing legacy token systems in urban transit environments.
Today's leader: Interactive Kiosks. Tomorrow's challenger: Digital Signage Kiosks.
End User:
Retail procurement concentrates in self-checkout hardware, while healthcare and transportation segments drive biometric authentication integration.
- Retail:Self-checkout stations dominate capital expenditure as convenience chains replace legacy POS terminals. Quick-service restaurant operators in North America are shifting toward outcome-based service contracts that transfer uptime risk to fleet operators, embedding predictive maintenance into standard agreements.
- Transportation:Metro authorities in Delhi, Mumbai, and Bengaluru are deploying QR-NFC integrated gate platforms at scale. Japan's METI enforces JIS durability standards for outdoor terminals that exceed commercial specifications, creating specification barriers favoring suppliers with proven environmental testing capabilities.
- Healthcare:FDA-governed biometric data collection terminals streamline patient check-in workflows in United States hospital networks.
- Education:Campus credential verification and wayfinding installations are migrating toward cloud-based fleet management.
Retail anchors current procurement volumes; transportation infrastructure projects are climbing the fastest.
Deployment:
Cloud-based architectures are displacing on-premises management in institutional settings, concentrating recurring revenue with SaaS platform operators.
- Cloud-Based:Centralized fleet orchestration enables remote diagnostics, predictive maintenance algorithms, and over-the-air security updates. Healthcare systems across North America are overtaking on-premises server deployments, though PCI DSS compliance timelines for biometric-enabled terminals extend eighteen to twenty-four months.
- Managed Services:Vertically integrated providers guarantee availability metrics through embedded remote monitoring and field service networks. This model transfers capital expenditure to operational expenditure, appealing to retail chains with distributed estate management complexity.
- On-Premises:Legacy server-based management retains foothold in security-sensitive banking and government installations.
- Self-Service:Buyer-operated maintenance models persist in simple digital signage and wayfinding applications.
Cloud-Based deployment is gaining share fastest; Managed Services represents the adjacent expansion vector for hardware vendors seeking recurring revenue.
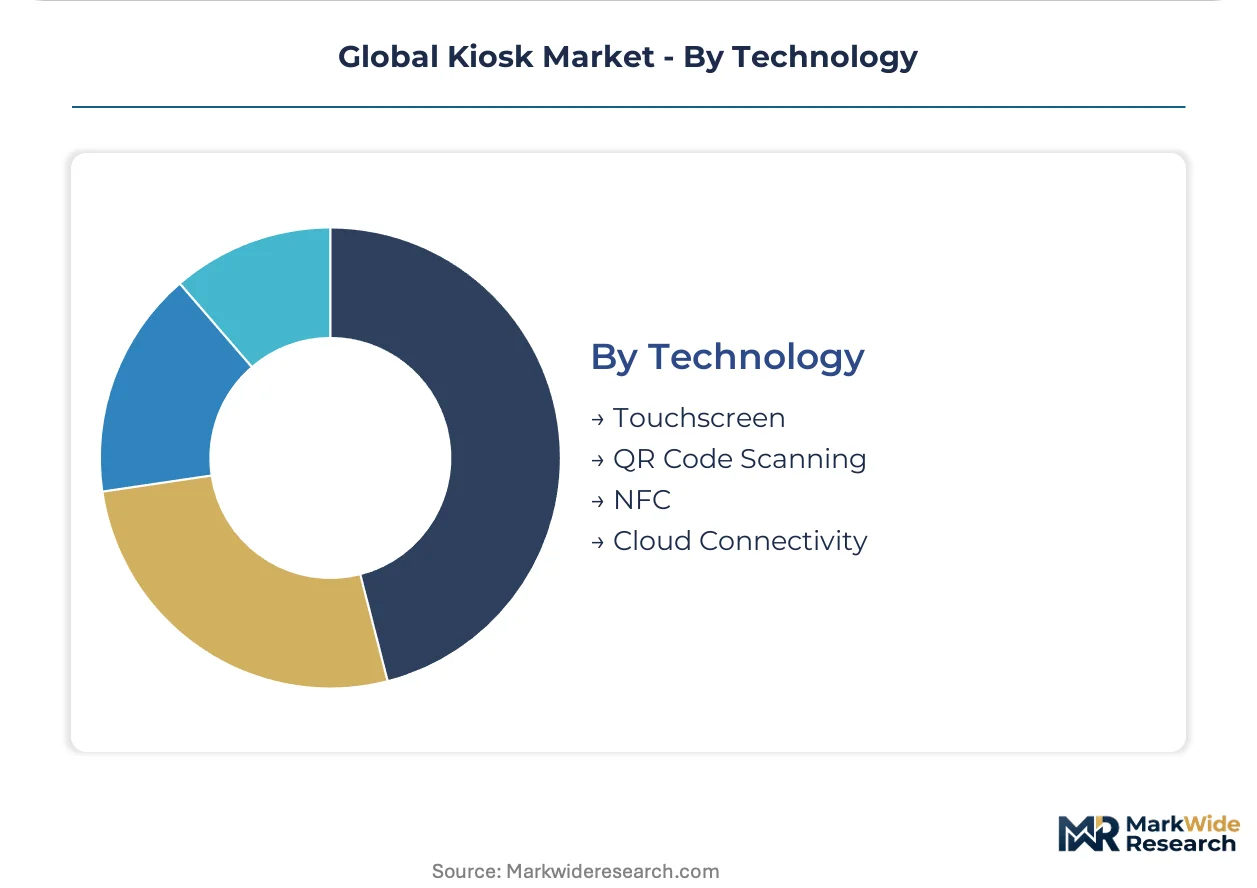
Technology:
Authentication modalities are shifting from physical card interaction toward contactless and biometric methods, elevating cybersecurity liability exposure.
- Touchscreen:Projected capacitive and infrared frame technologies remain baseline for information and transaction terminals. Industrial-grade display glass pricing fluctuates with photovoltaic manufacturing cycles, creating margin compression for hardware OEMs.
- NFC:Near-field communication enables tap-to-pay and transit credential verification with sub-second transaction times. The EU Accessibility Act mandates multimodal interfaces that incorporate NFC alongside visual and audio feedback, expanding addressable user bases.
- QR Code Scanning:Camera-based authentication dominates in transit and ticketing applications where smartphone penetration is high.
- Cloud Connectivity:Persistent network links enable real-time inventory, advertising content rotation, and security patch distribution.
NFC leads transaction authentication; touchscreen remains the foundational interaction layer across all terminal categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Delhi's metro infrastructure replacement programs anchor procurement volumes across the Global Kiosk Market. Transit digitization in India, self-checkout deployment in Germany, and outdoor terminal specifications in Japan collectively reshape regional demand patterns.
United States
FDA-governed biometric data collection terminals streamline patient check-in across hospital networks in Texas and California. Quick-service restaurant chains in the Southeast favor outcome-based service contracts over capital purchases. Chicago and Atlanta clusters concentrate fleet management platform development for healthcare systems.
Germany
Grocery retail chains compress hardware refresh cycles from seven years to four years, forcing enclosure manufacturers to synchronize production with seasonal windows. The EU Accessibility Act mandates EN 301 549-compliant multimodal interfaces for public terminals. Munich and Frankfurt transit authorities specify corrosion-resistant aluminum enclosures for outdoor installations.
India
Metro authorities in Delhi, Mumbai, and Bengaluru replace legacy token systems with QR-NFC integrated gate platforms at scale. BIS certification requirements govern payment terminal security specifications for transit applications. The Delhi-NCR corridor anchors procurement volumes for integrated transit gate hardware.
Japan
METI enforces JIS standards for outdoor terminal durability in rail and municipal applications, mandating vibration resistance and temperature ranges exceeding commercial specifications. Kanto and Kansai metro systems require demonstrated compliance with environmental benchmarks. Tokyo-based suppliers anchor transit gate integration contracts through pre-certified architectures.
Brazil
Convenience store chains in São Paulo and Rio de Janeiro lack self-checkout density compared to North American benchmarks, creating first-mover installation potential. ANVISA regulations govern biometric data collection in healthcare settings. The São Paulo industrial corridor concentrates enclosure fabrication for South American deployment.
Global Kiosk Market Competitive Environment
Portfolio diversification dominates the current landscape as incumbent payment hardware vendors extend into adjacent self-service verticals. The vendor base concentrates around three strategic archetypes: integrated payments stack operators, transit-specialized system integrators, and enclosure-focused fabricators. M&A activity and cloud-based service model transitions represent the dominant competitive vectors reshaping margin pools.
Within the integrated payments tier, NCR Corporation and Diebold Nixdorf exemplify archetypes leveraging financial services heritage to anchor retail and banking contracts. Fujitsu occupies a position representing transit-specialized system integration, particularly across East Asian metro procurement cycles. Advantech Co., Ltd. sits within the industrial computing fabricator tier, supplying embedded modules to downstream kiosk assemblers.
| Leading Market Players |
|---|
| NCR Corporation |
| Diebold Nixdorf, Incorporated |
| KIOSK Information Systems |
| Meridian Kiosks |
| Advantech Co., Ltd. |
| Zebra Technologies Corporation |
| Glory Ltd. |
| Olea Kiosks Inc. |
| Fujitsu Limited |
| Others |
Value Chain & Pricing Dynamics
Transit authorities in Delhi, Mumbai, and Bengaluru anchor procurement volumes through centralized tender programs that compress vendor margins while demanding EN 301 549-compliant multimodal interfaces. Their consolidated buying power enforces outcome-based service contracts over capital purchases, transferring hardware depreciation risk to kiosk fleet operators.
Pricing Analysis
Input-cost pass-through from industrial-grade LCD panels and secure element chips governs hardware pricing trajectories. Three-tier pricing structure across premium, standard, and economy levels separates JIS-certified outdoor terminals from indoor commercial units and basic digital signage kiosks. Pricing pressure stems from photovoltaic demand cycles that spike display glass costs unpredictably. Quick-service restaurant chains exhibit highest price sensitivity due to distributed estate management complexity, while healthcare systems prioritize FDA-compliant biometric authentication over unit economics.
Supply Chain Analysis
Reverse-logistics networks for enclosure refurbishment and component recovery are emerging as margin preservation tools as hardware refresh cycles compress from seven years to four years. Touch controller fabrication concentrates in Taiwan and South Korea, while aluminum alloy enclosure stamping feeds from China and domestic fabrication clusters in Brazil and Germany. Single-source vulnerability in secure element chip supply exposes kiosk OEMs to disruption risk. Distribution runs through vertically integrated fleet operators in North American healthcare and systems integrators in East Asian transit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS certification requirements impose eighteen-to-twenty-four-month compliance timelines that deter rapid market entry, while Brazil's ANVISA regulations on biometric data collection create comparable friction—presenting arbitrage opportunities for suppliers with pre-certified platform architectures in either jurisdiction.
For Market Incumbents: Cement dominance in transit gate integration through JIS pre-certification investments that lock out competitors from Tokyo and Osaka metro procurements. Deepen backward integration into aluminum alloy enclosure fabrication to capture freight cost advantages and corrosion-resistance specifications. Counter emerging cloud-based SaaS operators by embedding predictive maintenance algorithms into standard hardware service agreements. For New Entrants and Emerging Players: Launch via outcome-based service contracts targeting São Paulo convenience store chains where self-checkout density lags North American benchmarks. Exploit white-space in Brazilian retail automation and Indian campus credential verification systems migrating toward cloud-based fleet management. Pursue channel partnerships with regional systems integrators possessing established field service networks rather than direct OEM competition. For Investors and Strategic Acquirers: Payment hardware vendors with integrated software stacks are the most active acquirer in this space, consolidating kiosk fleet management platforms to capture recurring SaaS revenue. Long-term viability hinges on authentication modality transitions from card-based to biometric-enabled terminals. Monitor PCI DSS certification timeline compression for biometric-enabled healthcare terminals as an inflection indicator for vendor consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | NCR Corporation leverages payments stack integration to anchor self-service banking contracts across Texas and California hospital networks. |
| Acquisition of Specialist Firm | Diebold Nixdorf sustains installed-base revenue through ATM-to-kiosk conversion programs targeting legacy hardware estates. |
| Geographic Expansion | Fujitsu dominates East Asian transit gate procurements through METI JIS-certified outdoor terminal architectures. |
| Product Launch | QR-NFC integrated gate platforms replace legacy token systems across Delhi-NCR, Mumbai, and Bengaluru metro corridors. |
| Strategic Partnership | Cloud-based kiosk fleet orchestration partnerships concentrate recurring revenue with SaaS operators in North American healthcare systems. |
Study Parameters
Coverage spans the United States, Germany, India, Japan, and Brazil, with primary inputs from each market combining interviews with kiosk OEM procurement directors, transit authority technology officers, healthcare system biomedical engineers, and retail chain operations executives. Secondary validation draws from FDA 510(k) filings for biometric terminals, BIS certification registries for Indian payment hardware, METI JIS standard documentation, and SEC 10-K disclosures from integrated payments vendors. Bottom-up unit deployment estimates triangulate against top-down market value reconstruction across the analysis window.
Granularity-level modeling distinguishes interactive kiosks, digital signage units, vending terminals, and ticketing platforms by deployment architecture, authentication technology, and end-use vertical. The projection horizon incorporates hardware refresh cycle compression, regulatory compliance timeline extensions, and cloud-based management adoption curves. CAGRs derive from weighted scenario analysis across seasonal deployment windows and transit infrastructure procurement cycles.
Forecast precision tightens around the base case; tail outcomes carry wider variance under semiconductor supply disruption or extended PCI DSS certification delays for biometric-enabled terminals. Practitioners should monitor EU Accessibility Act enforcement patterns and India urban transit digitization budget allocations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Smart Retail Systems Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Retail-As-A-Service (Raas) Market
Retail Technology
Smart Shelf Market
Retail Technology
AR in Retail Market
Retail Technology
Smart Shopping Cart Market
Retail Technology
Cash Register Machines Market
Retail Technology
Omni-Channel Retail Solutions Market
Retail Technology
Retail Sourcing and Procurement Market
Retail Technology
E-Retail Market
Retail Technology
Smart Kitchen Solutions Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
Customer-Facing Technology Market
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
Self-Service Market
Retail Technology
Global Restaurant Point of Sale (POS) Terminals Market