
 Smart Kitchen Solutions Market | 2026-2036
Smart Kitchen Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Kitchen Solutions Market Insights
Energy Star certification and A+++ efficiency ratings are reorganizing competitive dynamics in smart kitchen appliances. Samsung Electronics leverages its proprietary SmartThings ecosystem to anchor connectivity standards across device categories. LG Electronics differentiates through AI-driven food management algorithms in its refrigerator lineup. Whirlpool Corporation sustains manufacturing scale advantages in North American built-in segments.
Smart kitchen solutions encompass internet-connected cooking, refrigeration, cleaning, and climate-control appliances that integrate sensors, embedded software, and wireless protocols to automate food preparation, inventory tracking, and energy management. These systems typically operate on dual-band Wi-Fi or Thread mesh networks with cloud-based recipe orchestration and remote diagnostics as core functional parameters. Smart refrigerators command the largest installed base among product types, though smart ovens generate disproportionate margin contributions through subscription-enabled recipe services. Wi-Fi and voice control technology segments exhibit the steepest adoption curves as interoperability standards consolidate around Matter protocol compatibility.
The U.S. Department of Energy enforces minimum efficiency standards that compel manufacturers to redesign heating elements and insulation systems in smart ovens and cooktops. The EU F-Gas Regulation and Ecodesign Directive restrict refrigerant types and standby power consumption in smart refrigeration, directly influencing R&D allocation across Electrolux, BSH, and Miele. China's GB standards for household appliance safety and network security create separate certification pathways for Haier and Midea. Stakeholders must monitor whether fragmented cybersecurity mandates across the FCC, ETSI, and MIIT converge or diverge as device connectivity becomes universal.
Market Dynamics
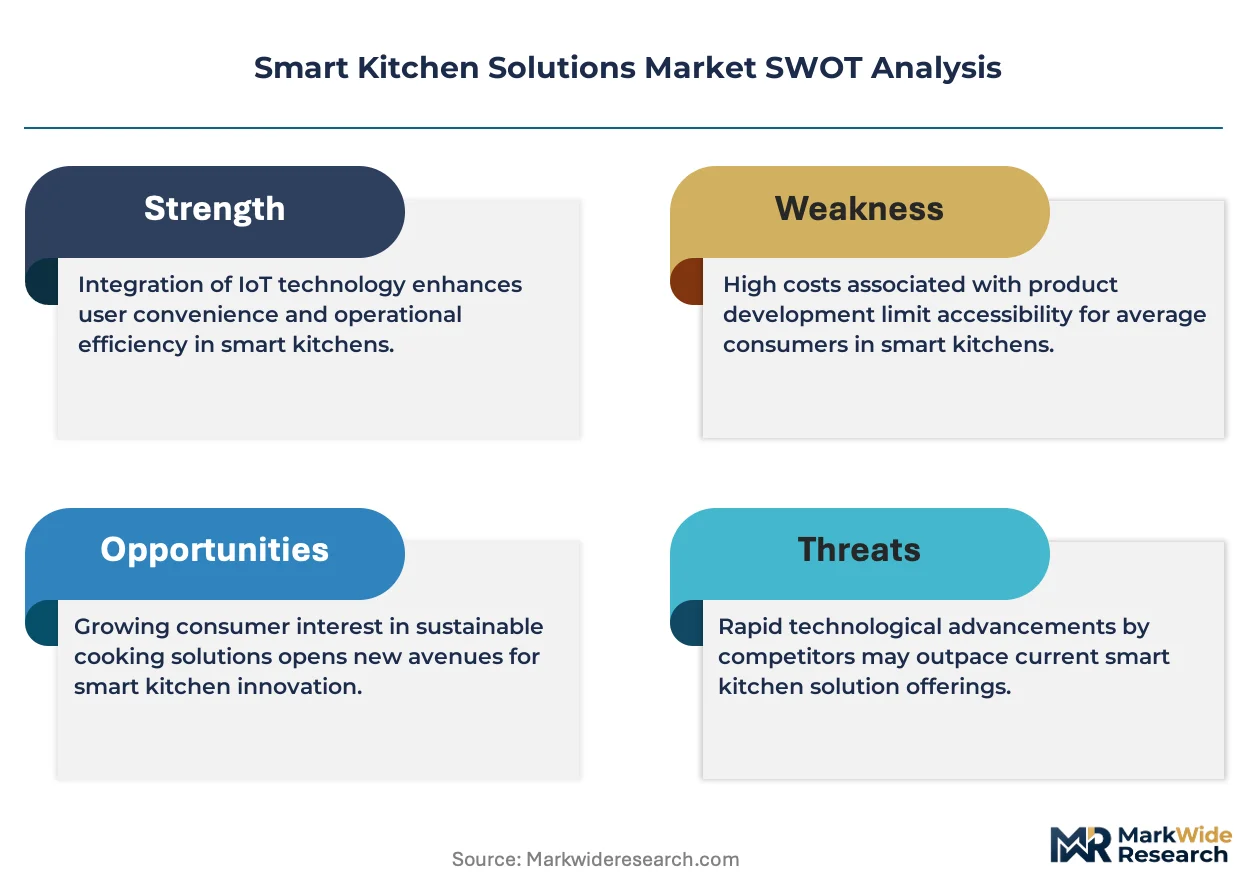
Matter protocol standardization is compressing interoperability timelines across device ecosystems, forcing manufacturers to consolidate wireless stacks and abandon proprietary connectivity layers.
Growth Catalysts
- EU Ecodesign Directive:Mandatory standby power limits and refrigerant phase-downs under F-Gas Regulation are accelerating replacement cycles in European built-in appliance segments.
- Residential electrification:Homeowners in Germany, Japan, and the United States are retrofitting kitchens with connected cooking and climate-control systems as gas-to-electric conversion subsidies expand.
- Sensor fusion architectures:Multi-modal detection combining computer vision, weight sensing, and gas detection is enabling predictive maintenance and automated recipe adjustment in premium ovens.
Market Restraints
- Semiconductor supply concentration:Wi-Fi 6 and Thread radio modules depend on TSMC and Samsung Foundry capacity allocations, creating 16-24 week lead time volatility for mid-tier manufacturers.
- Technical fragmentation:Cloud-to-cloud API inconsistencies between Amazon Alexa, Google Home, and Apple HomeKit require redundant development tracks, inflating software maintenance overhead.
- Substitution pressure:Non-connected premium appliances with mechanical durability and repairability advantages retain share among sustainability-focused buyers in Nordic markets.
Strategic Opportunities
- India kitchen modernization:Urban middle-class households in Mumbai and Bangalore are adopting compact smart cooking appliances as modular kitchen installation rates climb.
- Regulatory tailwind from IRA:US Inflation Reduction Act rebates for electric appliance upgrades are creating price parity between smart induction cooktops and conventional gas ranges.
- Retail-as-a-service:Direct-to-consumer subscription models bundling hardware, recipe content, and ingredient delivery are penetrating millennial homeowner segments in coastal US metros.
Industry Challenges
- Cybersecurity certification backlog:FCC equipment authorization and ETSI EN 303 645 compliance testing queues are extending product launch timelines by 4-6 months.
- Legacy system integration:Smart kitchen platforms must maintain backward compatibility with 2.4 GHz Wi-Fi-only appliances, fragmenting firmware development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Kitchen Solutions Market |
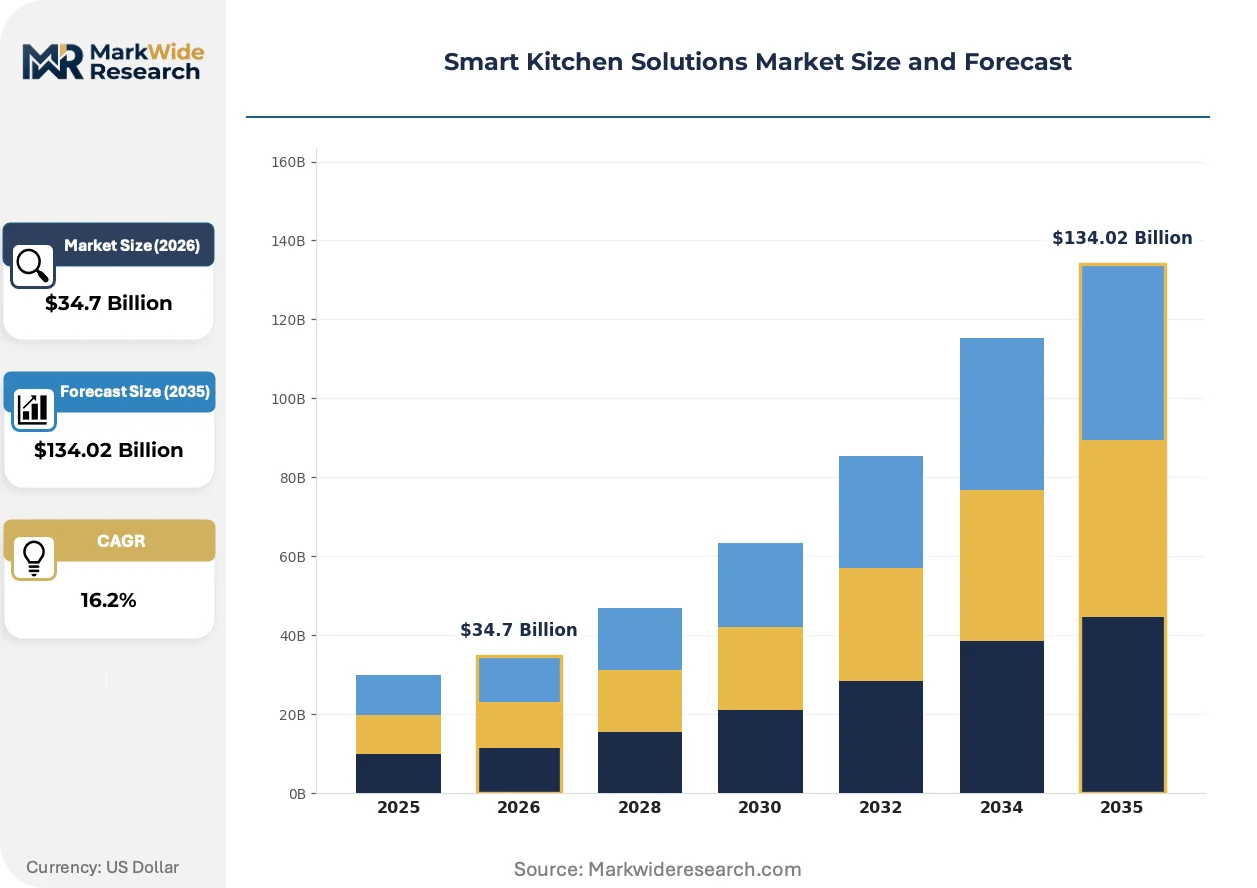
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $134.02 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Ovens, Smart Refrigerators, Smart Dishwashers, Smart Cooktops Technology: Wi-Fi, Bluetooth, Voice Control, IoT Connectivity End User: Homeowners, Chefs, Restaurants, Hospitality Installation: Built-in, Freestanding, Modular, Integrated |
| Companies Covered | Whirlpool Corporation, Samsung Electronics, LG Electronics, Electrolux, Haier, BSH, Panasonic, Miele, Midea, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Kitchen Solutions Market Trends and Innovations
Edge computing migration and on-device AI inference are redistributing processing loads away from cloud dependencies, reshaping hardware specifications and data governance architectures.
Camera-based food recognition systems are miniaturizing from refrigerator-mounted units to embedded door-sill arrays. Appliance manufacturers in Japan and South Korea are adopting these compact vision modules for real-time inventory tracking. This compression is enabling retrofit kits for existing refrigerator installed bases rather than full appliance replacement.
The EU F-Gas Regulation is banning hydrofluorocarbon refrigerants with GWP above 150 in new smart refrigeration equipment. Manufacturers are pivoting to isobutane and propane blends, requiring redesign of compressor sealing and ignition protection systems. Germany and France are experiencing the steepest compliance-driven model turnover as enforcement deadlines approach.
Builder procurement is consolidating around smart-home-ready specifications in new residential construction. Large-scale developers in Texas, Florida, and Arizona are pre-wiring kitchens for Matter-compatible device ecosystems. This specification capture is displacing retail channel influence over brand selection in suburban single-family housing.
Smart Kitchen Solutions Market Segmentation
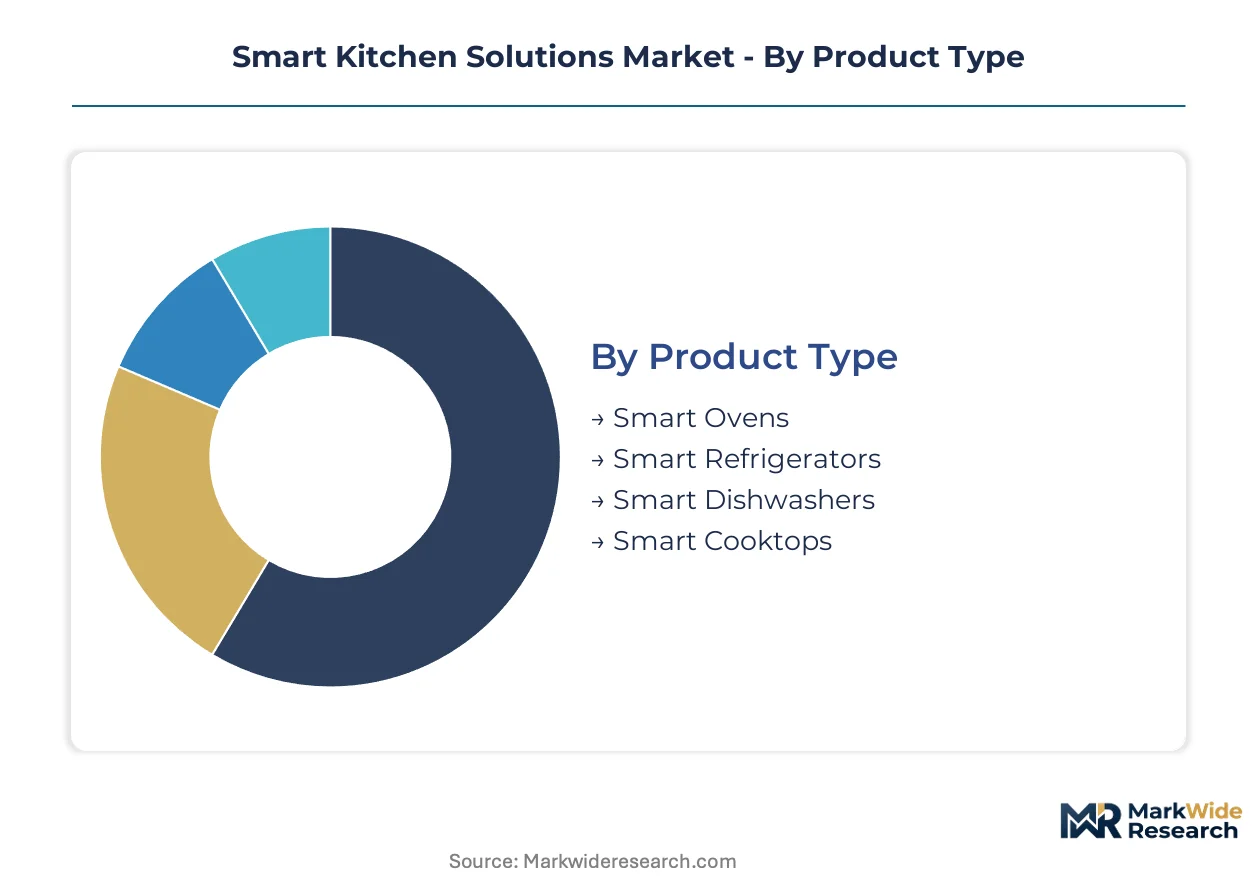
Segmentation in smart kitchen solutions reveals divergent technology adoption curves across installation contexts and user sophistication levels. Product architecture, connectivity protocol, and procurement channel each impose distinct competitive requirements on manufacturers.
Product Type:
Substitution pressure varies sharply across cooking versus preservation categories, with mechanical durability in conventional appliances threatening premium smart positioning in price-sensitive segments.
- Smart Ovens:These units integrate multi-modal sensor arrays—computer vision, weight sensing, and gas detection—for automated recipe adjustment and predictive maintenance. Demand concentrates in Germany and the United States where residential electrification subsidies accelerate gas-to-electric conversion. The EU Ecodesign Directive's standby power limits are forcing heating element redesigns that favor induction-based smart cooktops over conventional resistive alternatives.
- Smart Refrigerators:Camera-based food recognition systems and cloud-connected inventory tracking define this category. Japan and South Korea anchor installed base expansion as manufacturers miniaturize vision modules for retrofit compatibility with existing units. The EU F-Gas Regulation's hydrofluorocarbon phase-down is compressing replacement cycles in France and Germany.
- Smart Dishwashers:Connected units optimize water and energy consumption through soil-sensing algorithms and delayed-start scheduling tied to utility rate signals.
- Smart Cooktops:Induction-based systems with zoneless heating and app-controlled temperature curves serve modular kitchen configurations in urban apartments.
Smart refrigerators anchor the volume base while smart ovens gain share at the steepest rate.
Technology:
Protocol standardization is compressing development timelines, with Matter compatibility now a baseline requirement rather than a differentiator.
- Wi-Fi:Dual-band 802.11ax connectivity enables cloud-based recipe orchestration, remote diagnostics, and over-the-air firmware updates. Demand concentrates in North American suburban single-family housing where whole-home coverage is achievable. The FCC's equipment authorization queues are extending product launch timelines by 4-6 months for new entrants.
- Voice Control:Natural language interfaces for hands-free operation during food preparation. Cloud-to-cloud API inconsistencies between Amazon Alexa, Google Home, and Apple HomeKit require redundant development tracks, inflating software maintenance overhead for smaller manufacturers.
- Bluetooth:Low-energy pairing for initial device setup and proximity-based automation triggers.
- IoT Connectivity:Thread mesh networking and cloud platform integration for multi-device orchestration.
Wi-Fi carries the largest installed base while voice control is climbing the fastest as interoperability standards consolidate.
End User:
Procurement authority is fragmenting across retail, direct-to-consumer, and builder channels, each with distinct specification requirements.
- Homeowners:Residential buyers in Germany, the United States, and Japan drive premium built-in installation rates. US Inflation Reduction Act rebates for electric appliance upgrades are creating price parity between smart induction systems and conventional gas ranges.
- Restaurants:Commercial kitchens require ruggedized connectivity modules and centralized fleet management for multi-location operators.
- Chefs:Professional users demand precise temperature control and recipe programming capabilities.
- Hospitality:Hotel and serviced apartment operators prioritize remote monitoring and predictive maintenance to minimize downtime.
Homeowners dominate unit volume while hospitality is expanding most quickly through property management platform integration.
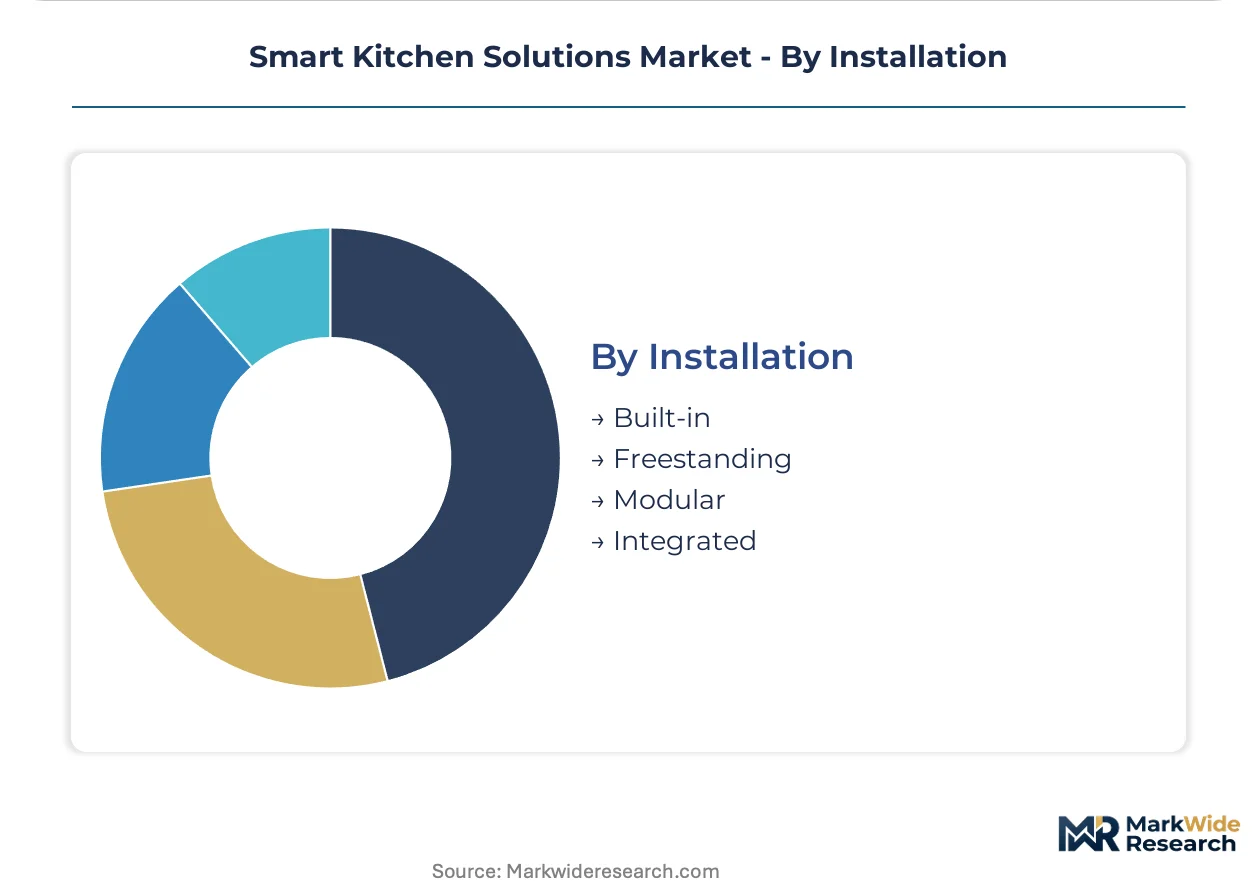
Installation:
Builder procurement consolidation is displacing retail channel influence over brand selection in new residential construction.
- Built-in:Custom panel-ready appliances integrated with cabinetry during construction or renovation. Large-scale developers in Texas, Florida, and Arizona are pre-wiring kitchens for Matter-compatible device ecosystems, capturing specification authority before retail engagement.
- Modular:Compact, freestanding units designed for urban apartments and flexible kitchen layouts. Demand concentrates in Mumbai and Bangalore as modular kitchen installation rates climb among India's urban middle class.
- Freestanding:Self-contained units requiring no custom cabinetry or electrical modifications.
- Integrated:Fully concealed appliances behind matching cabinet fronts for seamless aesthetic continuity.
Built-in installations command the revenue base while modular configurations are gaining share fastest in dense urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component manufacturing for smart kitchen solutions clusters in South Korea, Japan, and Germany, where precision sensor fabrication and wireless module assembly anchor supply chains. Demand-side expansion concentrates in North American and European residential markets where electrification subsidies and efficiency mandates accelerate replacement cycles.
United States
Residential electrification subsidies under the Inflation Reduction Act are compressing payback periods for smart induction cooktops in suburban single-family housing. The Department of Energy enforces minimum efficiency standards that compel heating element redesigns in connected ovens. Large-scale developers in Texas, Florida, and Arizona are pre-wiring kitchens for Matter-compatible device ecosystems, capturing specification authority from retail channels.
Germany
Premium built-in installation rates exceed regional averages as homeowners retrofit kitchens during energy efficiency upgrades. The EU Ecodesign Directive and F-Gas Regulation mandate standby power limits and hydrofluorocarbon phase-downs, forcing compressor redesigns in smart refrigeration. Industrial clusters in Bavaria and North Rhine-Westphalia host R&D facilities for refrigerant transition engineering and sensor fusion architectures.
Japan
Camera-based food recognition systems are miniaturizing for retrofit compatibility with existing refrigerator installed bases. METI efficiency standards and smart home infrastructure maturity support premium positioning for connected appliance portfolios. Tokyo and Osaka metropolitan areas concentrate demand for compact vision modules and edge computing-enabled cooking systems.
China
GB standards for household appliance safety and network security create separate certification pathways for domestic manufacturers. Dual carbon goals and urban kitchen modernization in tier-one cities are expanding modular smart cooking appliance adoption. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta supply Wi-Fi modules and compact induction components for export markets.
India
Urban middle-class households in Mumbai and Bangalore are adopting compact smart cooking appliances as modular kitchen installation rates climb. BIS certification requirements and import duty structures influence component sourcing strategies for international brands. The Delhi-NCR and Hyderabad corridors are emerging as service hubs for connected appliance installation and maintenance networks.
Smart Kitchen Solutions Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with ecosystem proprietors commanding connectivity standards while scale manufacturers dominate built-in segments. The market exhibits tiered consolidation: diversified electronics conglomerates anchor premium positioning, specialized appliance manufacturers sustain regional share, and emerging Asian producers capture volume in modular categories. Strategic moves concentrate on Matter protocol compliance, refrigerant transition engineering, and direct-to-consumer subscription model development.
Within the diversified electronics tier, Samsung Electronics and LG Electronics exemplify ecosystem-driven competitive positioning. Samsung leverages its SmartThings platform to anchor connectivity standards across device categories, while LG occupies a position emphasizing AI-driven food management algorithms. Whirlpool Corporation represents the scale-manufacturing archetype, sustaining manufacturing advantages in North American built-in segments through vertical integration into component supply and established builder channel relationships.
| Leading Market Players |
|---|
| Whirlpool Corporation |
| Samsung Electronics |
| LG Electronics |
| Electrolux |
| Haier |
| BSH |
| Panasonic |
| Miele |
| Midea |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation agreements with TSMC and Samsung Foundry lock in Wi-Fi 6 and Thread radio module allocations while fixing semiconductor input costs for tier-one manufacturers. These contracts insulate premium smart appliance producers from spot-market volatility that squeezes mid-tier competitors sourcing through distributors.
Pricing Analysis
The EU Ecodesign Directive dictates the pricing tier structure by mandating standby power limits and refrigerant phase-downs that increase compliance costs. Three-tier pricing structure across premium, standard, and economy levels separates Matter-certified built-in systems with edge-AI capabilities from basic Wi-Fi-connected freestanding units and non-smart mechanical alternatives. Cost compression in the standard tier is intensifying because FCC equipment authorization queues extend launch timelines and inflate certification overhead. Homeowners in Germany and Japan show the least price sensitivity for built-in installations, while India's urban middle class in Mumbai and Bangalore drives volume at economy price points.
Supply Chain Analysis
Port congestion on the Shanghai-Los Angeles trade lane and container availability constraints on Asia-Europe routes are elevating inbound logistics costs for finished appliance shipments. Component manufacturing clusters in South Korea, Japan, and Germany anchor precision sensor fabrication and wireless module assembly. Smart kitchen production draws from Taiwan and China for Wi-Fi chipsets, South Korea for OLED display panels, and Germany for compressor systems. Single-source vulnerability concentrates in TSMC's advanced node capacity for AI inference chips. Distribution runs through builder-direct channels in Texas and Arizona, retail chains in Germany, and modular kitchen installers in Bangalore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart kitchen market is exiting a cyclical trough driven by semiconductor supply normalization and Matter protocol standardization that compresses replacement cycles. Recovery velocity hinges on builder channel capture rates in US suburban housing and EU refrigerant transition deadlines.
For Market Incumbents: Compound ecosystem lock-in by deepening SmartThings, HomeKit, and Alexa integration layers while accelerating refrigerant transition engineering ahead of F-Gas Regulation enforcement. Defend against emerging Asian producers by capturing builder specification authority in Texas and Florida through pre-wiring partnerships. Prioritize backward integration into compressor sealing systems to control propane-isobutane blend transition costs.
For New Entrants and Emerging Players: Anchor in India's modular kitchen segment where BIS certification requirements create defensible moats against established Western brands. Target compact smart cooking appliances for Mumbai and Bangalore urban apartments as the most penetrable white space. Pursue direct-to-consumer subscription models bundling hardware, recipe content, and ingredient delivery to bypass retail channel concentration.
For Investors and Strategic Acquirers: Sensor fusion architecture specialists with multi-modal detection IP represent the highest-conviction acquisition archetype for long-term viability across the 5-10 year connected appliance replacement wave. Watch builder procurement consolidation rates in Arizona and Florida as the inflection signal for ecosystem winners versus retail-dependent brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Matter Protocol Certification | Enables interoperability across Samsung SmartThings, Apple HomeKit, and Google Home ecosystems. |
| Refrigerant Transition Engineering | Positions manufacturers for EU F-Gas Regulation compliance ahead of hydrofluorocarbon phase-down deadlines. |
| Builder Channel Pre-wiring Partnerships | Captures specification authority in Texas and Florida before retail engagement influences brand selection. |
| Edge AI Inference Chip Integration | Reduces cloud dependency for camera-based food recognition in Japanese refrigerator retrofit kits. |
| Direct-to-Consumer Subscription Launch | Penetrates millennial homeowner segments in coastal US metros through bundled hardware-content-delivery models. |
Research Methodology
Desk research of regulatory filings from the FCC, ETSI, and METI preceded structured interviews with smart appliance product managers, builder procurement officers, modular kitchen installers, and semiconductor supply planners. Secondary validation drew from EU Ecodesign Directive implementation reports, US Department of Energy efficiency standard updates, and customs data on Wi-Fi module trade flows. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Variance decomposition across product type, connectivity protocol, installation context, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from replacement cycle modeling tied to efficiency mandate deadlines and electrification subsidy expiration patterns. Forecast inputs included builder housing start correlations, refrigerant transition cost curves, and Matter protocol adoption velocity indices.
Material uncertainties — semiconductor capacity reallocation, cybersecurity mandate divergence between FCC and ETSI, and gas-to-electric conversion subsidy modifications — sit outside the modeled envelope. Forecasts reflect assumptions about protocol standardization timelines and regulatory enforcement consistency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Retail Technology
Internet of Things (IoT) in Retail Market
Retail Technology
America's AI in the Retail Market
Retail Technology
Smart Retail Systems Market
Retail Technology
Global Kiosk Market
Retail Technology
Self-Checkout in Retail Market
Retail Technology
Alternative Retailing Technologies Market
Retail Technology
Retail Inventory Software Market
Retail Technology
United States Grocery and Pharmacy Point of Sale (POS) Terminal Market
Retail Technology
Self-Checkout System Market
Retail Technology
E-Retail Market
Retail Technology
US Self-Checkout Systems Market
Retail Technology
Selfservice Technologies Market
Retail Technology
Smart Grocery Cart Market
Retail Technology
Digital Kiosk Market
Retail Technology
Smart Shelf Market
Retail Technology
Self-Service Market