
 Seismic Data Acquisition Equipment Market | 2026-2036
Seismic Data Acquisition Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Seismic Data Acquisition Equipment Market Insights
Subscription-based software-defined processing is shifting how vendors monetize seismic hardware deployments. Schlumberger leverages its integrated platform model to bundle acquisition systems with cloud-based imaging workflows. CGG competes through specialized high-performance computing services that extend the value chain beyond sensor sales. Sercel anchors its market position with manufacturing scale in cable-based and cableless receiver technologies.
Seismic data acquisition equipment encompasses sensors, recording systems, and telemetry infrastructure engineered to detect, amplify, and digitize elastic wave propagation through subsurface geological formations, typically operating across bandwidths from 0.1 Hz to 10 kHz depending on target depth and resolution requirements. These systems serve oil and gas explorers, mining operators, and geotechnical engineers who require quantitative subsurface property maps for resource estimation, hazard assessment, and structural design. Geophones retain the largest installed base in land surveys, though ocean-bottom node arrays are gaining share in marine environments where nodal technology eliminates towed-streamer limitations in obstructed or shallow-water zones. Passive seismic monitoring, once confined to research applications, now attracts mining firms seeking real-time microseismic tracking for rockburst prediction and tailings dam integrity verification.
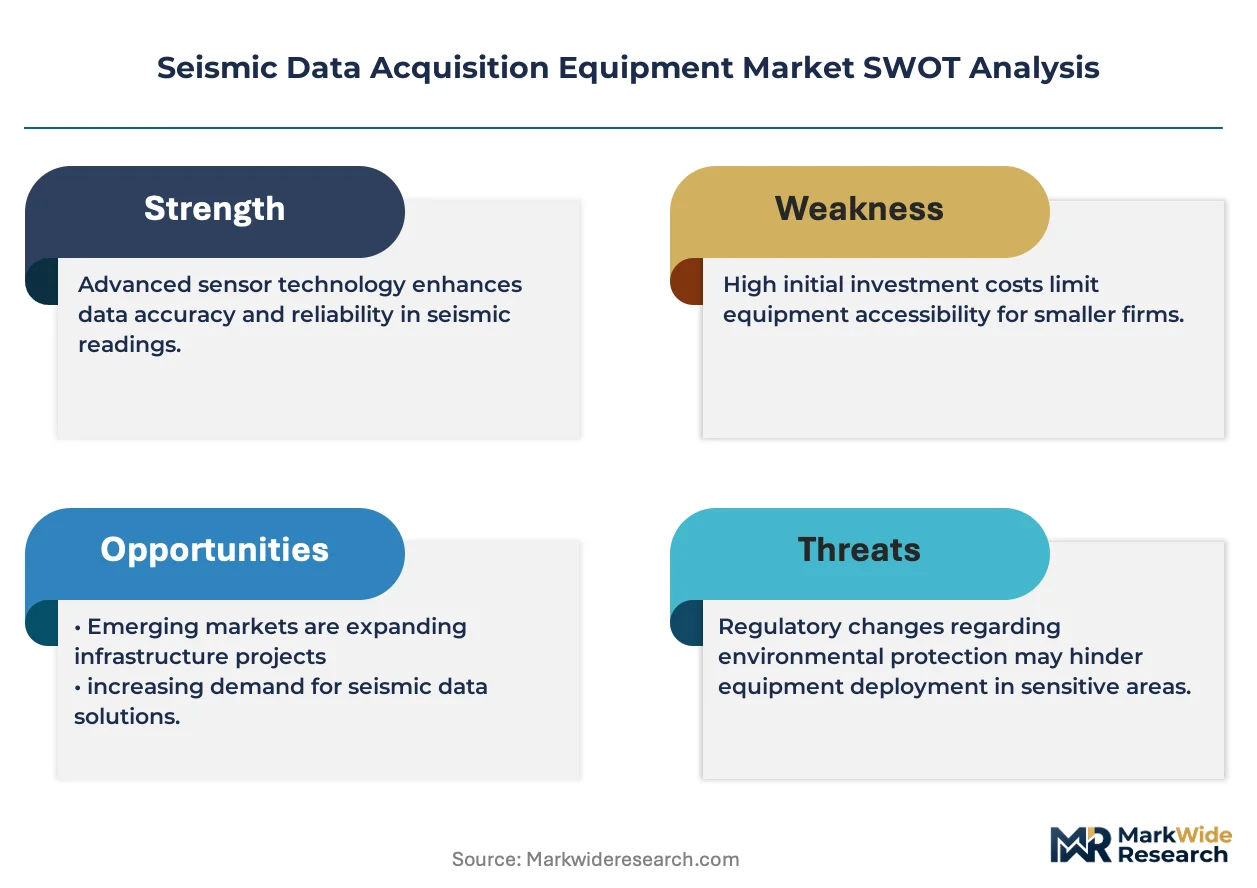
BOEM in the United States and ANP in Brazil impose environmental compliance conditions on marine seismic permits, compelling operators to demonstrate marine mammal observation protocols and reduced-source alternatives before authorization. The EU Marine Strategy Framework Directive extends similar constraints to North Sea and Atlantic frontier blocks, favoring equipment vendors with proven quiet-source or simultaneous-source methodologies. Stakeholders must weigh capital commitment timing against regulatory pathway certainty as permitting delays in multiple jurisdictions extend project development cycles beyond traditional planning horizons.
Market Dynamics
Offshore operators face a structural pivot as environmental compliance costs for marine seismic surveys compress project economics and redirect capital toward lower-impact acquisition modalities. The US Bureau of Ocean Energy Management's tightened Atlantic permitting standards exemplify this pressure, forcing equipment vendors to reengineer source arrays and telemetry systems for reduced acoustic footprint.
Growth Catalysts
- Pre-salt exploration intensity:Brazil's pre-salt polygon drives demand for ocean-bottom node arrays capable of high-resolution imaging beneath complex salt formations. Petrobras and international operators deploy these systems to optimize reservoir recovery in deepwater blocks.
- EU Marine Strategy Framework Directive:North Sea and Atlantic frontier regulations favor vendors with quiet-source or simultaneous-source methodologies. Equipment manufacturers demonstrating marine mammal observation protocols gain permit advantages.
- Passive seismic monitoring:Mining firms adopt real-time microseismic tracking for rockburst prediction and tailings dam integrity verification, expanding addressable market beyond traditional oil and gas exploration.
Market Restraints
- Permitting timeline volatility:BOEM authorization delays in US Atlantic waters extend project development cycles beyond traditional planning horizons, freezing capital commitment timing.
- Sensor manufacturing concentration:Geophone and accelerometer supply clusters in East Asian production centers create vulnerability to logistics disruptions and input cost swings.
- Optical telemetry limitation:Deepwater pressure ratings and cable fatigue constrain real-time data transmission rates, forcing redundant storage architectures that inflate system cost.
Strategic Opportunities
- Carbon capture site characterization:Subsurface monitoring requirements for CO2 storage integrity verification create demand for permanent reservoir surveillance installations using ocean-bottom node technology.
- Software-defined processing convergence:Cloud-native imaging workflows bundled with acquisition hardware enable recurring revenue streams beyond sensor sales.
- India offshore licensing rounds:The country's national petroleum regulator expands exploration acreage in frontier basins, attracting nodal array deployments where towed-streamer operations face logistical constraints.
Industry Challenges
- Marine mammal observer certification bottleneck:Qualified personnel scarcity delays survey mobilization timelines, particularly in jurisdictions with strict BOEM or EU Marine Strategy Framework Directive observation mandates.
- Multi-vendor system integration complexity:Operators combining recording systems from Sercel with processing platforms from competing vendors face data format incompatibilities and workflow fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Seismic Data Acquisition Equipment Market |
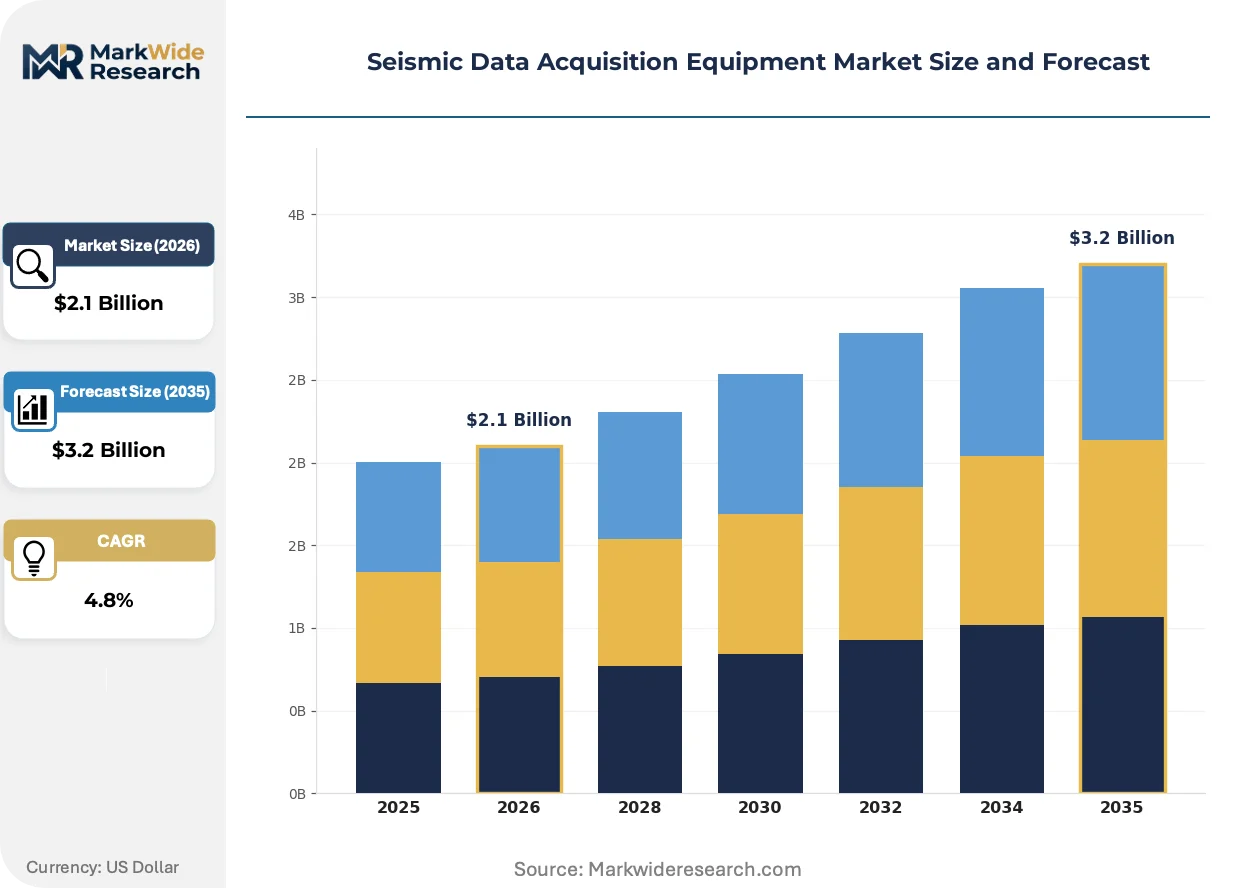
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Geophones, Accelerometers, Hydrophones, Seismographs Technology: Seismic Refraction, Seismic Reflection, Ground Penetrating Radar, Passive Seismic Application: Oil & Gas Exploration, Mining, Geotechnical Investigation, Environmental Monitoring End User: Energy Companies, Mining Firms, Environmental Agencies, Research Institutions |
| Companies Covered | Schlumberger, CGG, ION Geophysical Corporation, Kinemetrics, Sercel, Nanometrics, Geospace Technologies, BGP Inc., WesternGeco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Seismic Data Acquisition Equipment Market Trends and Innovations
Seismic acquisition technology is bifurcating between high-density nodal architectures for complex geologies and lightweight, rapidly deployable systems for frontier reconnaissance. This divergence reshapes vendor R&D allocation and operator procurement criteria.
Autonomous underwater vehicles equipped with self-contained nodal sensors are integrating continuous seismic monitoring into permanent reservoir surveillance installations. Offshore operators in Brazil's pre-salt fields deploy these systems to eliminate surface vessel dependency during 4D repeat surveys. The technology is integrating subsurface imaging with production optimization workflows, compressing the feedback loop between data acquisition and reservoir engineering decisions.
REACH chemical restrictions and EU Marine Strategy Framework Directive noise thresholds are compelling manufacturers to reformulate buoyancy materials and source energy signatures. Equipment vendors must now submit environmental impact documentation alongside technical specifications for North Sea tenders. Marine contractors respond by specifying simultaneous-source methodologies that reduce survey duration and acoustic exposure.
Subscription licensing for processing software displaces perpetual license purchases among mid-size exploration firms. Buyers in Asia-Pacific frontier markets favor bundled acquisition-to-imaging contracts that transfer computational infrastructure risk to vendors. Brazil's national petroleum agency encourages this shift by evaluating operator technical capability rather than asset ownership in bid rounds.
Seismic Data Acquisition Equipment Market Segmentation
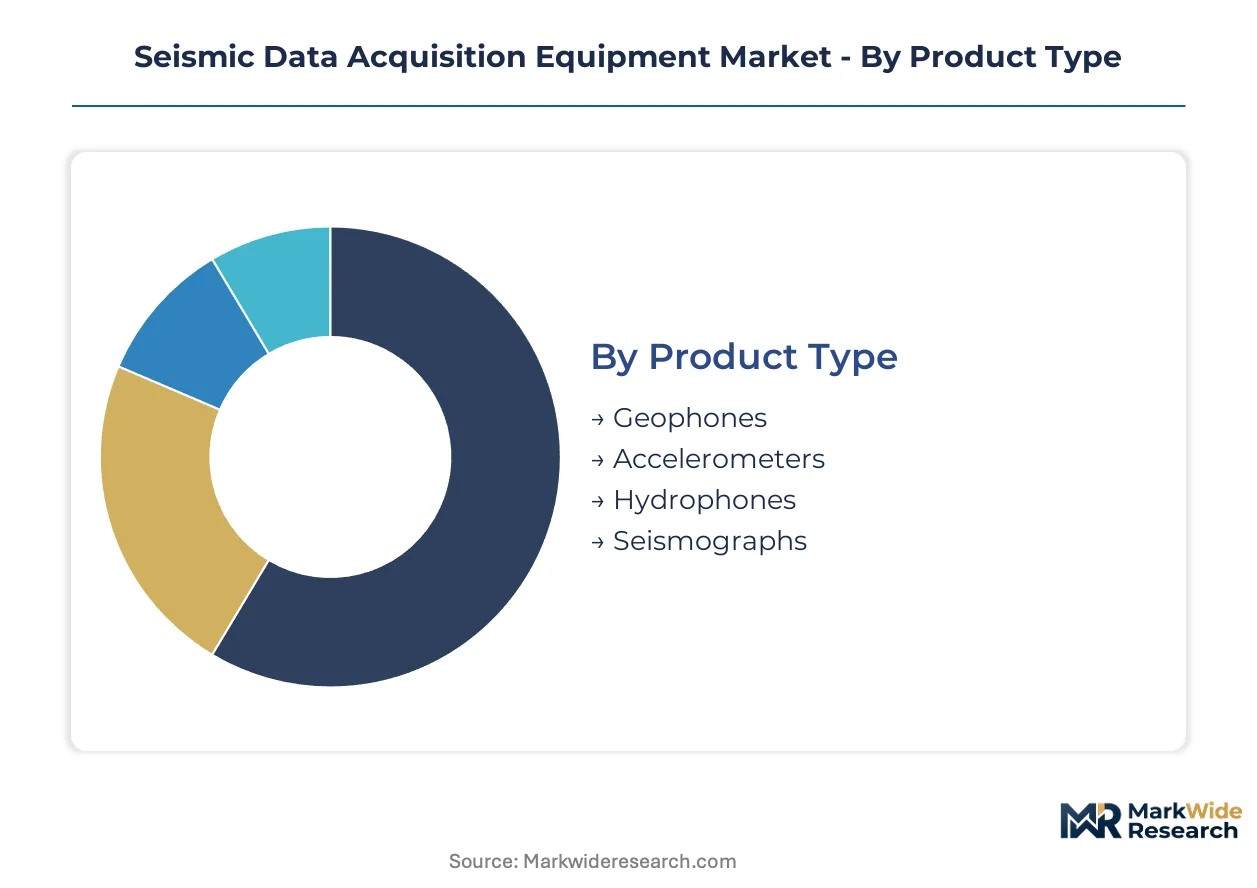
Equipment segmentation in seismic data acquisition reflects divergent capital deployment strategies across exploration verticals. Sensor technologies and recording modalities command distinct procurement cycles, with offshore energy operators prioritizing nodal arrays while mining contractors favor portable, rapidly deployable systems.
Product Type:
Capital intensity varies sharply across sensor categories, with marine-deployed hydrophone arrays requiring vessel integration and deepwater-rated housings that multiply upfront investment versus land-based alternatives.
- Geophones:Electromechanical velocity sensors utilizing moving-coil transducers to detect ground motion across 1 Hz to 100 Hz bandwidths. Brazil's pre-salt polygon and US Permian Basin operators deploy these in cable-connected arrays for 3D land surveys where manufacturing scale at Sercel and other vendors compresses unit costs.
- Accelerometers:Piezoelectric or MEMS-based devices measuring ground acceleration directly, enabling broader frequency response for near-surface high-resolution imaging. Mining firms in Australia and Canada specify these for microseismic monitoring arrays where sensitivity to low-magnitude events determines rockburst prediction efficacy.
- Hydrophones:Pressure-sensitive sensors optimized for acoustic wave detection in marine environments, typically paired with ocean-bottom node architectures.
- Seismographs:Integrated recording systems combining analog-to-digital conversion, timing synchronization, and telemetry interfaces.
Geophones absorb the bulk of installed capacity across land survey operations; accelerometers are expanding most quickly in mining safety applications.
Technology:
Survey methodology selection hinges on target depth, geological complexity, and regulatory constraints governing acoustic source energy in sensitive marine habitats.
- Seismic Reflection:Controlled-source imaging utilizing reflected wavefields to map subsurface boundaries, dominant in oil and gas exploration for reservoir delineation. Petrobras and international operators in Brazil's pre-salt polygon rely on ocean-bottom node deployments of this technology where salt canopy complexity defeats conventional streamer acquisition.
- Passive Seismic:Ambient noise and microseismic event monitoring without artificial source activation, gaining traction in mining and carbon storage verification. EU-funded research consortia and Australian tailings dam operators deploy permanent arrays for continuous integrity surveillance, circumventing source permitting constraints under the EU Marine Strategy Framework Directive.
- Seismic Refraction:First-arrival traveltime analysis for shallow crustal structure mapping, common in geotechnical site investigation.
- Ground Penetrating Radar:Electromagnetic subsurface imaging for near-surface engineering and archaeological applications.
Seismic reflection commands the largest share of contracted survey value; passive seismic is climbing the fastest as regulatory barriers restrict active-source marine operations.
Application:
End-use demand fragmentation creates divergent equipment specifications, with energy exploration prioritizing channel count and bandwidth while environmental monitoring emphasizes deployment mobility.
- Oil & Gas Exploration:High-channel-count acquisition for hydrocarbon prospect delineation and reservoir characterization, representing the dominant revenue concentration. Deepwater operators in Brazil, the US Gulf of Mexico, and emerging Indian offshore blocks specify ocean-bottom node systems for 4D time-lapse monitoring of producing fields.
- Mining:Microseismic and passive seismic systems for rock mechanics, tailings dam surveillance, and ore body delineation. Canadian and Australian hard-rock operators are the primary adopters, integrating real-time monitoring with operational safety protocols.
- Geotechnical Investigation:Shallow seismic surveys for civil engineering foundation design and tunnel route assessment.
- Environmental Monitoring:Subsurface characterization for carbon storage site selection, groundwater mapping, and contamination plume tracking.
Oil and gas exploration absorbs the bulk of high-end equipment investment; environmental monitoring is gaining share fastest as carbon capture site characterization requirements multiply.
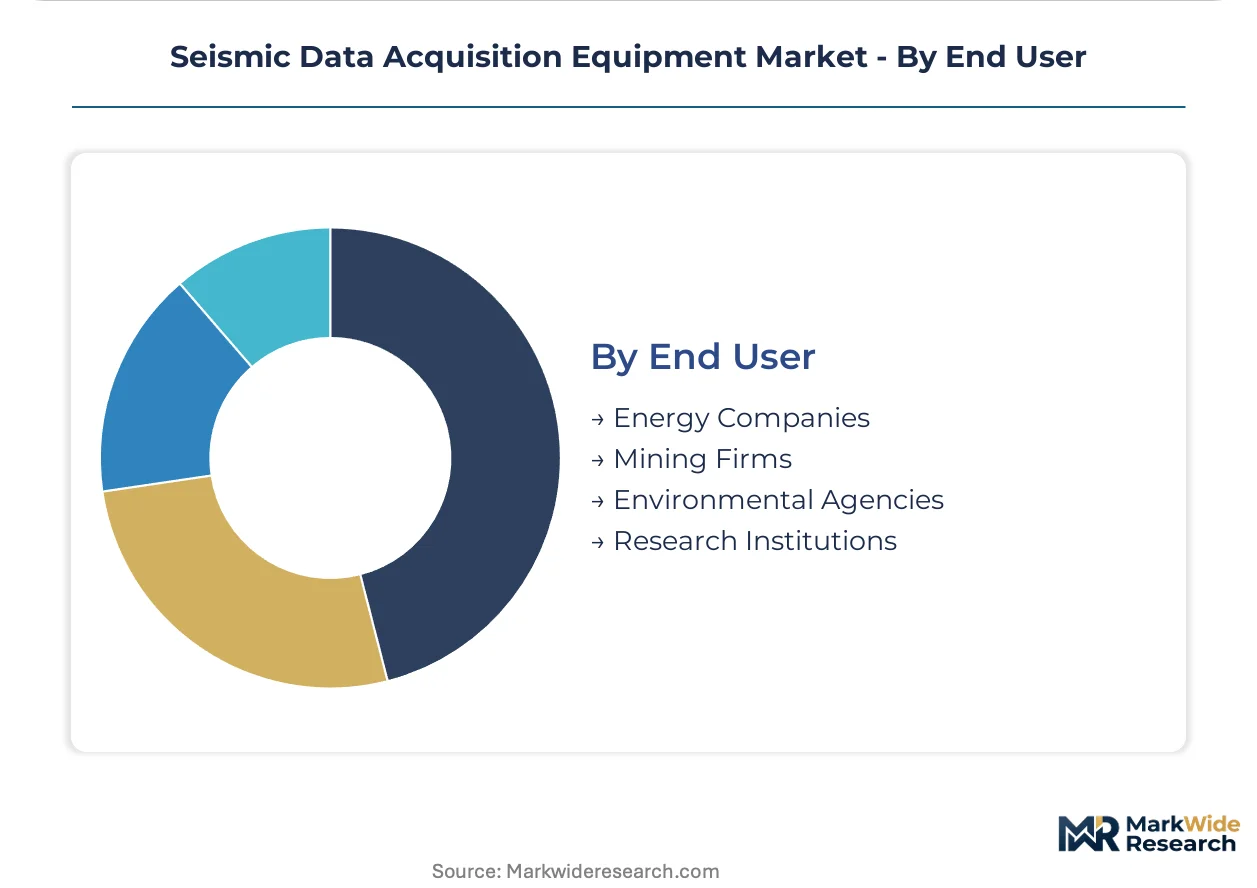
End User:
Procurement authority and technical sophistication vary across buyer categories, with integrated energy companies driving specification standards that cascade to contractor and agency purchasers.
- Energy Companies:Integrated oil and gas operators and national oil companies specifying acquisition parameters for proprietary surveys or contractor-managed programs. Petrobras, ExxonMobil, and emerging Indian operators dictate ocean-bottom node array configurations that equipment vendors must certify for deepwater deployment.
- Mining Firms:Hard-rock and coal operators procuring microseismic systems for operational safety and reserve definition. Australian and Canadian producers lead adoption, with procurement decisions increasingly centralized under corporate safety engineering functions rather than decentralized mine-site authority.
- Environmental Agencies:Government and quasi-governmental bodies conducting regulatory compliance surveys and carbon storage site certification.
- Research Institutions:Academic and governmental research programs utilizing seismic equipment for crustal studies and method development.
Energy companies command the largest equipment procurement budgets; mining firms are expanding their addressable spend fastest as passive seismic safety mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing of geophones and ocean-bottom node housings clusters in East Asian production centers, while demand concentrates in offshore basins off Brazil, the US Gulf Coast, and emerging Indian blocks. This geographic split shapes logistics costs and vendor service network placement.
United States
Deepwater operators in the Gulf of Mexico deploy ocean-bottom node arrays for 4D reservoir monitoring, with ExxonMobil and Chevron driving specification standards. BOEM tightened Atlantic seismic permitting requirements, extending environmental review timelines and favoring vendors with quiet-source methodologies. Houston hosts the primary contractor procurement and equipment staging hub for Western Hemisphere offshore programs.
Brazil
Petrobras and international operators expand pre-salt polygon exploration, specifying high-channel-count nodal systems for imaging beneath complex salt formations. ANP imposes local content requirements and environmental compliance conditions on marine seismic permits. The Santos Basin port complex serves as the deployment and maintenance center for deepwater acquisition fleets.
China
BGP Inc. anchors domestic manufacturing capacity for cable-based and cableless receiver technologies, supplying both national oil company programs and export markets. MIIT standards govern seismic equipment certification for domestic deployment. Sichuan province hosts concentrated R&D activity in MEMS-based accelerometer development for mining safety applications.
India
The Directorate General of Hydrocarbons expands offshore licensing rounds in frontier basins, attracting nodal array deployments where towed-streamer operations face logistical constraints. CEA regulations shape electrical safety standards for onshore recording equipment. Mumbai and Chennai serve as contractor mobilization points for Arabian Sea and Bay of Bengal survey programs.
Norway
North Sea operators specify simultaneous-source methodologies to comply with EU Marine Strategy Framework Directive noise thresholds and reduce marine mammal acoustic exposure. Equinor drives demand for permanent reservoir surveillance installations using autonomous nodal systems. Stavanger hosts the primary technical specification and vendor qualification center for North Atlantic offshore programs.
Seismic Data Acquisition Equipment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the seismic equipment value chain. The market structure concentrates around integrated energy service conglomerates, specialized sensor manufacturers, and national oil company-affiliated contractors. Three archetypes dominate: full-stream providers bundling hardware with processing workflows, component specialists manufacturing at scale, and regionally anchored system integrators. Competitive moves center on cloud-native imaging convergence and manufacturing capacity expansion in East Asian supply clusters.
Within the integrated service tier, Schlumberger and CGG represent contrasting platform strategies—one leveraging bundled acquisition-to-imaging contracts, the other competing through high-performance computing specialization. Sercel anchors the manufacturing-centric archetype with production scale in cable-based and cableless receiver technologies. These three companies exemplify how vendor positioning diverges between subscription-based software monetization and hardware shipment economics.
| Leading Market Players |
|---|
| Schlumberger |
| CGG |
| ION Geophysical Corporation |
| Kinemetrics |
| Sercel |
| Nanometrics |
| Geospace Technologies |
| BGP Inc. |
| WesternGeco |
| Others |
Pricing and Supply Chain Analysis
Deepwater-rated titanium alloy housings and pressure-tolerant optical transceivers cascade from East Asian precision manufacturing through Sercel and Schlumberger assembly lines into three-tier pricing structures across premium, standard, and economy levels. ANP local-content mandates in Brazil and BOEM environmental compliance costs in US Atlantic waters amplify landed costs for integrated acquisition systems.
Pricing Analysis
Margin tightening in premium ocean-bottom node arrays reflects simultaneous-source R&D amortization and extended BOEM permitting timelines that freeze capital recovery schedules. Three-tier pricing structure across premium, standard, and economy levels separates deepwater-certified systems with autonomous deployment capability from cable-based land arrays and refurbished geophone strings. Price differentiation hinges on channel density ratings and ANP local-content certification tier. Mid-size exploration contractors in Asia-Pacific frontier markets exhibit highest price sensitivity; Petrobras and ExxonMobil procurement teams prioritize technical specification compliance over unit cost.
Supply Chain Analysis
ANP local-content requirements and China's MIIT certification standards are reshaping sourcing patterns for cable-based receiver technologies. Manufacturing gravity centers on China, France, and Japan for MEMS accelerometer fabrication, piezoelectric hydrophone elements, and deepwater-rated telemetry housings. Component sourcing draws from Malaysian semiconductor packaging facilities, German precision optics suppliers, and Australian rare-earth magnet providers. Single-source vulnerability concentrates in high-pressure optical connector supply. Distribution runs through Houston, Stavanger, and Santos Basin port complexes for contractor mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where EU Marine Strategy Framework Directive noise thresholds and BOEM marine mammal observation mandates erect regulatory moats favoring vendors with proven quiet-source methodologies and certified environmental protocols.
For Market Incumbents: Acquire autonomous underwater vehicle nodal deployment capabilities to eliminate surface vessel dependency in Brazil's pre-salt 4D repeat surveys. Backward integration into MEMS accelerometer fabrication reduces exposure to East Asian supply concentration. Invest in simultaneous-source processing R&D to defend specification standards against emerging cableless competitors. For New Entrants and Emerging Players: Marine contractor procurement offices in Mumbai and Chennai represent the most penetrable channel entry point for nodal array providers lacking Petrobras qualification history. Target India's Directorate General of Hydrocarbons frontier licensing rounds where towed-streamer logistics constraints create white-space for autonomous deployment systems. Lead with bundled acquisition-to-imaging contracts that transfer computational infrastructure risk. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized high-performance computing services providers in Norway and France with permanent reservoir surveillance installation expertise. Long-term viability hinges on carbon capture site characterization demand multiplying through the projection horizon. Monitor BOEM Atlantic permitting authorization velocity as inflection indicator for US offshore capital deployment appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Quiet-Source Technology Certification | BOEM and EU Marine Strategy Framework Directive compliance unlocks Atlantic and North Sea tender participation. |
| Cloud-Native Imaging Platform Integration | Schlumberger and CGG subscription models displace perpetual licenses among mid-size exploration firms. |
| Autonomous Nodal System Deployment | Petrobras eliminates surface vessel costs in Brazil's pre-salt 4D monitoring programs. |
| Carbon Capture Site Characterization | CO2 storage integrity verification creates permanent reservoir surveillance demand beyond hydrocarbon exploration. |
| East Asian Manufacturing Scale Expansion | Sercel and BGP Inc. production capacity anchors cost compression in cable-based receiver technologies. |
Research Methodology
Independent corroboration across BOEM permit authorization databases, ANP local-content compliance filings, and EU Marine Strategy Framework Directive environmental impact assessments underwrites the qualitative findings. Primary interviews with offshore project managers at Petrobras and ExxonMobil, seismic acquisition contractors in Houston and Stavanger, and marine mammal observer certification bodies combined with secondary validation from SEC 10-K equipment revenue disclosures, customs trade data for geophone and accelerometer imports, and IHS Markit offshore project development databases. Bottom-up channel count deployment estimates triangulate against top-down exploration capital expenditure allocations.
Historical reference periods spanning pre-salt polygon development phases and US Gulf of Mexico deepwater ramp-ups anchor the forecast window across the analysis window. Segmentation dimensions modeled include sensor technology type, survey methodology, water depth rating, and regulatory compliance tier. CAGRs derive from equipment shipment volume trajectories and contracted survey value trends. Industry-specific forecast inputs incorporate ANP licensing round schedules and BOEM Atlantic permitting velocity assumptions.
Caveats apply where BOEM authorization delays, REACH chemical restriction scope expansions, or optical telemetry bandwidth breakthroughs could materially shift the outlook. Forecasts reflect documented assumptions about permitting timeline stability and marine contractor fleet utilization rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
COG Bonder Market
Industrial Equipment
Hot Runner Temperature Controller Market
Industrial Equipment
UV Conveyor Systems Market
Industrial Equipment
Pin Marking Machine Market
Industrial Equipment
Global High Power Laser Systems Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Global Industrial Dispensing System and Equipment Market
Industrial Equipment
Industrial Monitor Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Diaphragm Coupling Market
Industrial Equipment
Snowrator Market
Industrial Equipment
Latin America Explosion-Proof Equipment Market
Industrial Equipment
Industrial Magnetrons Market
Industrial Equipment
Dustless Workstations Market
Industrial Equipment
Seal Inspection Equipment Market
Industrial Equipment
Global Liquid Handling Systems Market