
 Pin Marking Machine Market | 2026-2036
Pin Marking Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Pin Marking Machine Market Analytics
Equipment leasing and managed-service contracts for marking stations is reconfiguring competitive entry barriers, allowing smaller job shops to access industrial-grade traceability without capital-heavy purchases. Gravotech Group leverages its European service network to sustain recurring revenue from installed-base retrofits. Telesis Technologies Inc. anchors its position through deep specialization in aerospace-grade deep marking for titanium and Inconel alloys. Pryor Marking Technology competes aggressively on channel control, maintaining direct distribution across British and Indian industrial clusters.
A pin marking machine drives a hardened stylus into metal surfaces to create permanent, dot-matrix indentations readable under harsh conditions, with typical pin frequencies ranging from 200 to 800 impacts per second depending on pneumatic or electric actuation. These systems serve critical traceability functions across automotive VIN stamping, aerospace part certification, and medical device serialization. Portable and handheld configurations now lead unit shipments due to flexibility in field-service and maintenance-repair environments, while electric technology segments capture expanding margin pools as factories phase out compressed-air infrastructure. Metal fabrication and automotive manufacturing applications dominate volume, though aerospace parts marking commands premium pricing through stringent NADCAP and AS9100 compliance requirements.
The FDA enforces Unique Device Identification rules that mandate permanent direct-part marking for reusable surgical instruments and implantable devices, directly shaping product development roadmaps for US-focused suppliers. In Europe, the Machinery Directive and CE marking requirements govern operator safety and electromagnetic compatibility, while REACH restrictions on hexavalent chromium coatings influence stylus material selection. China's SAMR administers GB standards for industrial equipment safety that pin marking OEMs must satisfy for domestic market access. Stakeholders should monitor evolving traceability mandates in battery supply chains and hydrogen infrastructure, as these emerging sectors will extend marking requirements beyond traditional metalworking domains.
Market Dynamics
Electric actuation systems are displacing pneumatic infrastructure across automotive and aerospace manufacturing lines, compressing operating costs while satisfying tightening energy-efficiency mandates from regulators in Germany, Japan, and the United States.
Growth Catalysts
- FDA Unique Device Identification:Permanent direct-part marking requirements for surgical instruments and implantable devices are forcing medical device manufacturers to install certified pin marking stations.
- China's eastern manufacturing corridor:Domestic machine builders are scaling production capacity to serve metal fabrication and aerospace supply chains with localized equipment sourcing.
- EU Machinery Directive:Operator safety and electromagnetic compatibility standards are accelerating replacement cycles for aging marking equipment across European automotive plants.
Market Restraints
- Compressed-air infrastructure lock-in:Pneumatic pin marking systems dominate installed bases, and factory retooling for electric alternatives demands substantial capital expenditure and production downtime.
- Stylus material constraints:REACH restrictions on hexavalent chromium coatings limit durable stylus options, forcing suppliers to qualify alternative carbide and ceramic formulations.
- Laser marking substitution:Fiber laser systems compete for high-speed, non-contact applications in electronics and consumer goods, narrowing pin marking's addressable market in speed-sensitive segments.
Strategic Opportunities
- Battery supply chain traceability:Emerging cell manufacturing and recycling regulations will extend marking requirements to lithium-ion module housings and electrode components.
- Hydrogen infrastructure components:Pressure vessels, valves, and fueling nozzles for hydrogen systems will require permanent certification marks under developing safety standards.
- Equipment-as-a-service models:Leasing and managed-service contracts for marking stations allow smaller job shops to access industrial-grade traceability without capital-heavy purchases.
Industry Challenges
- NADCAP and AS9100 certification timelines:Aerospace parts marking demands extensive supplier qualification processes that extend sales cycles and strain smaller OEMs' technical documentation capabilities.
- Legacy system integration:Pin marking stations must interface with established MES and ERP architectures, requiring customized software bridges that complicate deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pin Marking Machine Market |
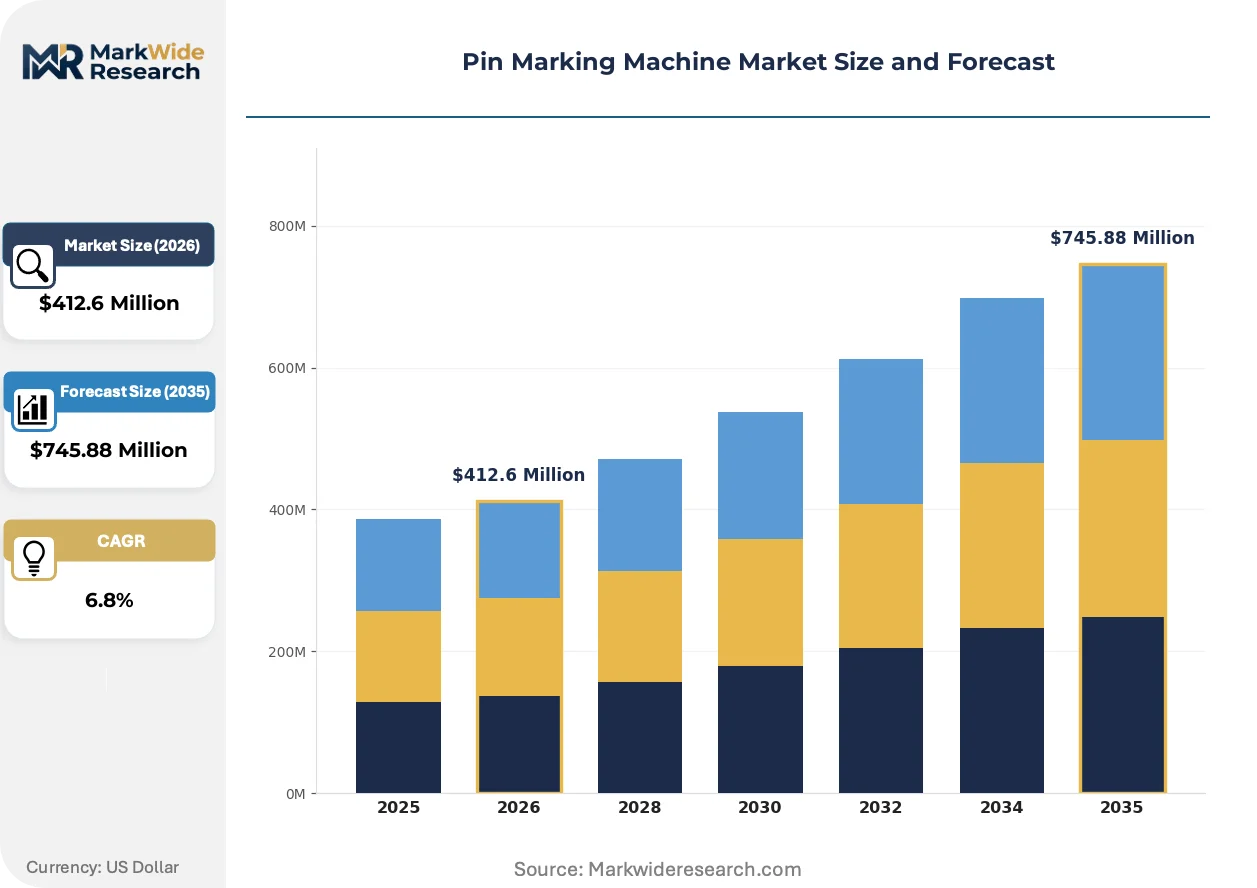
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Portable, Desktop, Industrial, Handheld Technology: Pneumatic, Electric, Laser, Mechanical Application: Metal Fabrication, Automotive Manufacturing, Aerospace Parts, Electrical Components End User: Manufacturers, Job Shops, Assemblers, Research Institutions |
| Companies Covered | SIC Marking Group, Gravotech Group, Telesis Technologies Inc., MECCO, Technifor, Pryor Marking Technology, HeatSign, Pannier Corporation, Kwik Mark Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pin Marking Machine Market Evolving Landscape
Software-defined control architectures and cloud-connected diagnostics are reconfiguring how marking equipment is operated, maintained, and monetized across industrial end-uses.
Digital twin technology is virtualizing machine commissioning and fault diagnosis for pin marking systems. Automotive tier-one suppliers in Stuttgart and Detroit are deploying virtual commissioning to reduce physical prototyping. This capability is virtualizing the traditional service technician dispatch model, compressing response times and enabling predictive maintenance contracts.
REACH regulations on hexavalent chromium are forcing stylus material transitions across European supply chains. Carbide and ceramic alternatives now dominate new equipment specifications from German and French machine builders. Medical device manufacturers sourcing from EU-based suppliers face the steepest compliance timelines as they validate alternative stylus performance for FDA-submitted processes.
After-sales service unbundling is fragmenting traditional equipment vendor revenue streams. Gravotech Group and comparable suppliers now sell maintenance modules separately from hardware, allowing buyers to self-service or contract third-party technicians. This pattern concentrates most visibly in India's industrial clusters, where cost-sensitive fabricators prioritize spare parts availability over integrated service agreements.
Pin Marking Machine Market Segmentation
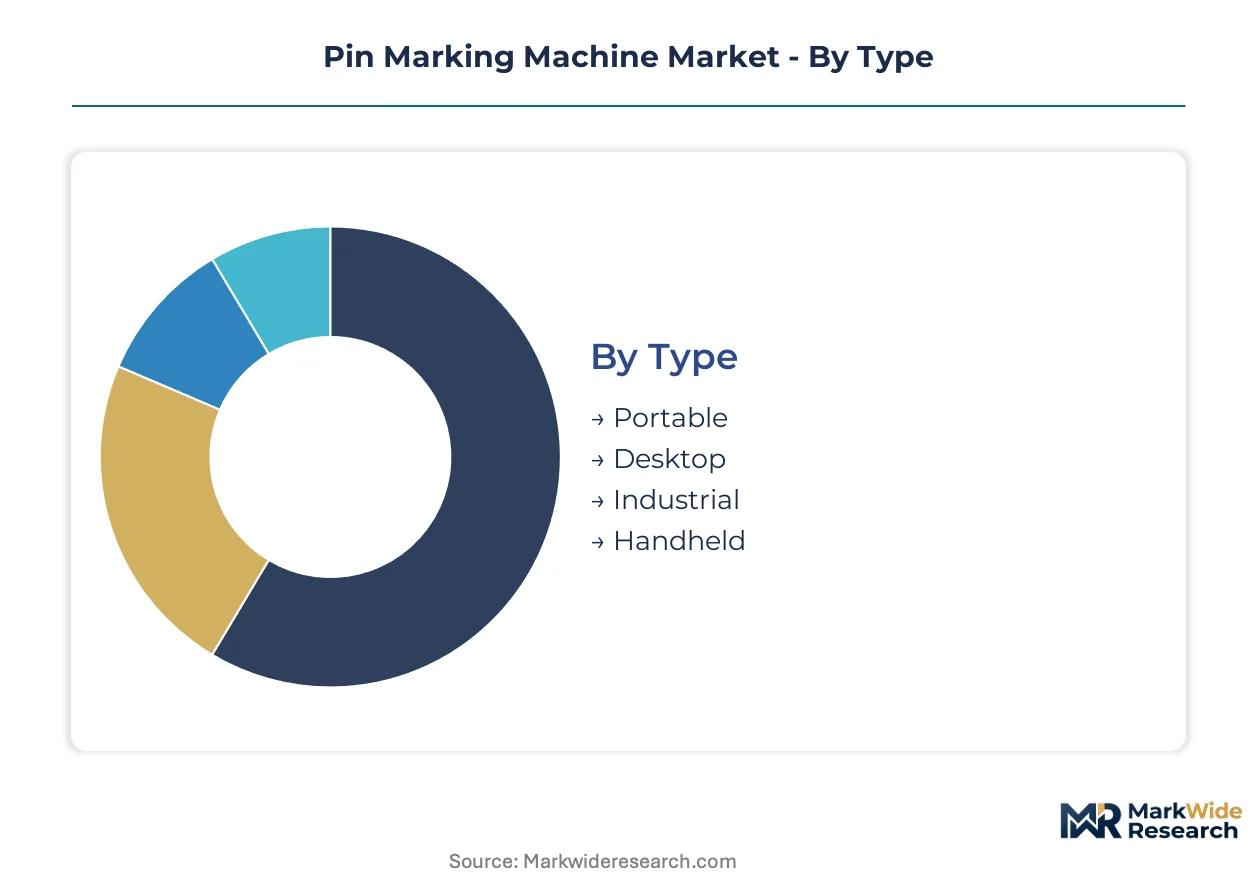
Pin marking machine procurement cycles vary sharply by configuration and end-use, with portable units turning over in 3-5 years while industrial installations persist for 12-15 years. Understanding these velocity differentials helps suppliers align inventory, service contracts, and upgrade pathways to actual replacement patterns rather than assumed uniform demand.
Type:
Cycle times diverge most dramatically in this dimension, with handheld and portable configurations replacing fastest due to field wear, while industrial platforms anchor long-horizon capital budgets.
- Portable:Battery-powered mobile stations weighing 8-15 kg dominate MRO environments and construction equipment yards. German automotive suppliers in Stuttgart and Wolfsburg deploy fleets for just-in-time VIN corrections on assembly lines. Portable units face the steepest price pressure from Asian contract manufacturers.
- Handheld:Pistol-grip form factors with integrated controllers serve aerospace line maintenance and energy infrastructure field teams. Japanese heavy equipment exporters in Osaka and Komatsu source these for dealer network support across Southeast Asian mining operations. Ergonomic redesigns for extended single-hand operation differentiate premium offerings.
- Desktop:Bench-mounted systems with fixed work envelopes target small-batch job shops and medical device prototyping labs.
- Industrial:Gantry-integrated or robotic-arm-mounted stations for high-volume automotive and aerospace production lines.
Industrial platforms anchor the volume base while handheld configurations gain share at the steepest rate.
Technology:
Cost tier stratification runs deepest here, with pneumatic systems occupying the economy position, electric capturing mid-premium positioning, and laser commanding the highest entry thresholds.
- Electric:Servo-driven pin actuation eliminates compressed-air infrastructure and delivers ±0.01 mm repeatability for aerospace-grade deep marking. US-based medical device manufacturers in Minneapolis and Warsaw, Indiana are standardizing on electric platforms to satisfy FDA process validation requirements. METI efficiency guidelines in Japan accelerate displacement of legacy pneumatic assets.
- Pneumatic:Compressed-air systems with 400-600 Hz impact rates retain installed-base dominance in metal fabrication job shops. Chinese machine builders in Suzhou and Ningbo optimize these for cost-sensitive domestic supply chains. Energy consumption penalties mount under EU Ecodesign regulations.
- Laser:Fiber and CO2 alternatives compete for speed-critical electronics marking where pin marking's mechanical cycle times prove insufficient.
- Mechanchanical:Manual or spring-actuated legacy systems persisting in artisanal and educational applications.
Pneumatic technology retains the largest installed base while electric systems climb the fastest through replacement cycles.
Application:
Volume concentration versus margin extraction splits this dimension, with automotive manufacturing driving unit scale and aerospace parts commanding pricing premiums through certification overhead.
- Automotive Manufacturing:VIN stamping, engine block serialization, and powertrain component traceability consume the highest machine counts. Tier-one suppliers in Detroit, Stuttgart, and Shanghai operate 24/7 marking stations integrated with plant MES architectures. NHTSA recall traceability mandates deepen penetration beyond final assembly into subsystem suppliers.
- Aerospace Parts:Titanium, Inconel, and aluminum alloy marking for NADCAP-accredited suppliers demands specialized stylus geometries and process documentation. French and Italian aerostructures manufacturers in Toulouse and Turin specify electric deep-marking platforms for fatigue-resistant indentations. AS9100 compliance extends sales cycles but locks in long-term service relationships.
- Metal Fabrication:General-purpose structural steel and aluminum marking for construction, agricultural, and industrial equipment.
- Electrical Components:Terminal block, connector, and enclosure marking for switchgear and control panel manufacturers.
Automotive manufacturing anchors the volume base while aerospace parts capture the steepest expansion trajectory through regulatory deepening.
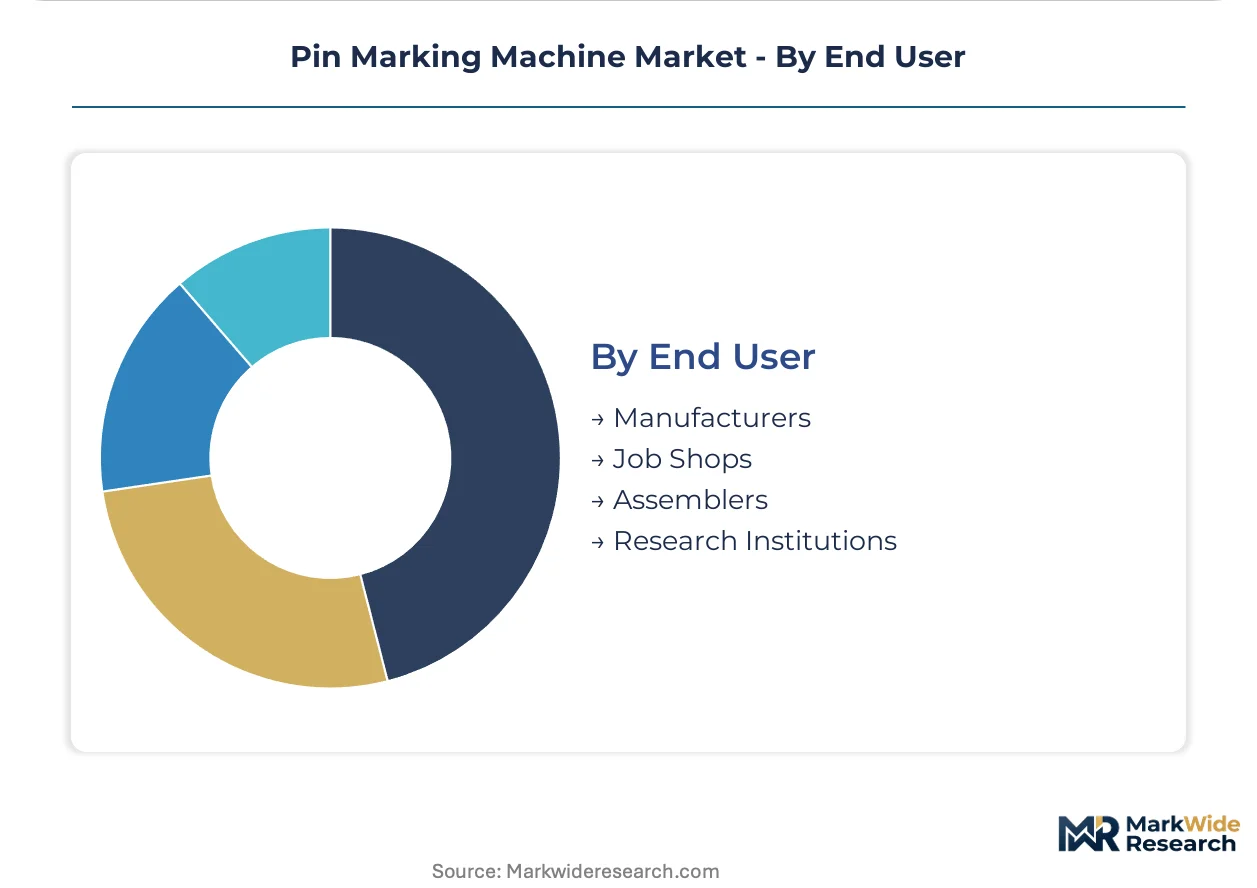
End User:
Customer type determines procurement modality, with manufacturers favoring capital purchase and job shops increasingly receptive to equipment-as-a-service structures.
- Manufacturers:OEMs and tier suppliers with captive production lines standardize on integrated marking cells with robotic handling. German white goods and automotive producers in Munich and Düsseldorf specify electric platforms with predictive maintenance contracts. Capital budgeting cycles align with plant retooling schedules.
- Job Shops:Contract fabricators and marking service bureaus prioritize equipment flexibility and rapid changeover between part families. Indian metalworking clusters in Pune and Rajkot drive demand for portable and desktop configurations with lease financing. After-sales unbundling allows self-service maintenance to control operating costs.
- Assemblers:Final assembly operations requiring late-stage serialization or rework marking capabilities.
- Research Institutions:Universities and national laboratories procuring marking equipment for materials science and prototype development.
Manufacturers anchor the volume base while job shops gain share at the steepest rate through service-model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital equipment buyers cluster around automotive manufacturing corridors and aerospace certification hubs, with procurement patterns diverging sharply between integrated OEMs and contract fabricators seeking flexible marking solutions.
United States
Medical device manufacturers in Minneapolis and Warsaw, Indiana drive electric platform standardization under FDA Unique Device Identification mandates. NHTSA recall traceability requirements deepen marking penetration into automotive subsystem suppliers. Detroit's tier-one supplier ecosystem operates 24/7 integrated marking cells with plant MES architectures.
Germany
Stuttgart and Wolfsburg automotive suppliers deploy portable marking fleets for just-in-time VIN corrections on assembly lines. EU Machinery Directive and Ecodesign regulations accelerate displacement of legacy pneumatic assets. Bavarian machine builders optimize electric servo-driven systems for aerospace-grade deep marking applications.
China
Suzhou and Ningbo machine builders scale pneumatic system production for cost-sensitive domestic supply chains. SAMR-administered GB standards govern industrial equipment safety compliance for domestic market access. Eastern manufacturing corridor demand concentrates in metal fabrication and aerospace supply chain localization.
Japan
Osaka and Komatsu heavy equipment exporters source handheld configurations for dealer network support across Southeast Asian mining operations. METI efficiency guidelines compress operating costs while phasing out compressed-air infrastructure. Kanto region medical device manufacturers validate alternative stylus performance for process documentation.
India
Pune and Rajkot metalworking clusters drive demand for portable and desktop configurations with lease financing. Cost-sensitive fabricators prioritize spare parts availability over integrated service agreements. After-sales unbundling allows self-service maintenance to control operating costs in job shop environments.
Pin Marking Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented tiers. The vendor base spans European service-network operators, aerospace-grade deep marking specialists, and Asian contract manufacturers. Three archetypes dominate: integrated solution providers with predictive maintenance contracts, component-specialist fabricators with NADCAP accreditation, and cost-optimized volume producers. Geographic expansion and technology licensing represent the dominant competitive moves as suppliers seek regulatory qualification in multiple jurisdictions.
Among European-integrated players, Gravotech Group occupies a position exemplifying service-network monetization through installed-base retrofits. Telesis Technologies Inc. sits within the aerospace-specialist tier, representing deep marking expertise for titanium and Inconel alloys. Pryor Marking Technology anchors the channel-control archetype through direct distribution across British and Indian industrial clusters.
| Leading Market Players |
|---|
| SIC Marking Group |
| Gravotech Group |
| Telesis Technologies Inc. |
| MECCO |
| Technifor |
| Pryor Marking Technology |
| HeatSign |
| Pannier Corporation |
| Kwik Mark Inc. |
| Others |
Value Network & Pricing Analysis
Overcapacity in China's eastern manufacturing corridor compresses margin buffers for pneumatic system builders while concentrating pricing power among European electric-platform specialists serving aerospace certification markets. Utilization differentials between these regional production bases directly shape supplier investment priorities and buyer negotiation leverage across procurement cycles.
Pricing Analysis
Certification level creates the primary spread between equipment tiers, with FDA-grade electric platforms commanding substantial premiums over CE-marked pneumatic alternatives. Three-tier pricing structure across premium, standard, and economy levels segments buyers by compliance burden and volume scale. Cost compression in the pneumatic tier intensifies because Chinese contract manufacturers optimize for domestic metal fabrication demand. Job shops in Indian industrial clusters exhibit the steepest price sensitivity, while aerospace tier-one suppliers prioritize stylus performance and documentation depth over unit cost.
Supply Chain Analysis
Contract manufacturing concentration rests with Suzhou and Ningbo-based machine builders for pneumatic assemblies and Bavarian fabricators for servo-driven electric platforms. Raw material sourcing draws from carbide suppliers in Germany, ceramic formulation specialists in Japan, and controller electronics from South Korean semiconductor foundries. Single-source vulnerability concentrates in aerospace-grade stylus coatings where REACH restrictions eliminated hexavalent chromium alternatives. Distribution runs through direct OEM channels for integrated automotive cells and third-party industrial distributors for portable and desktop configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
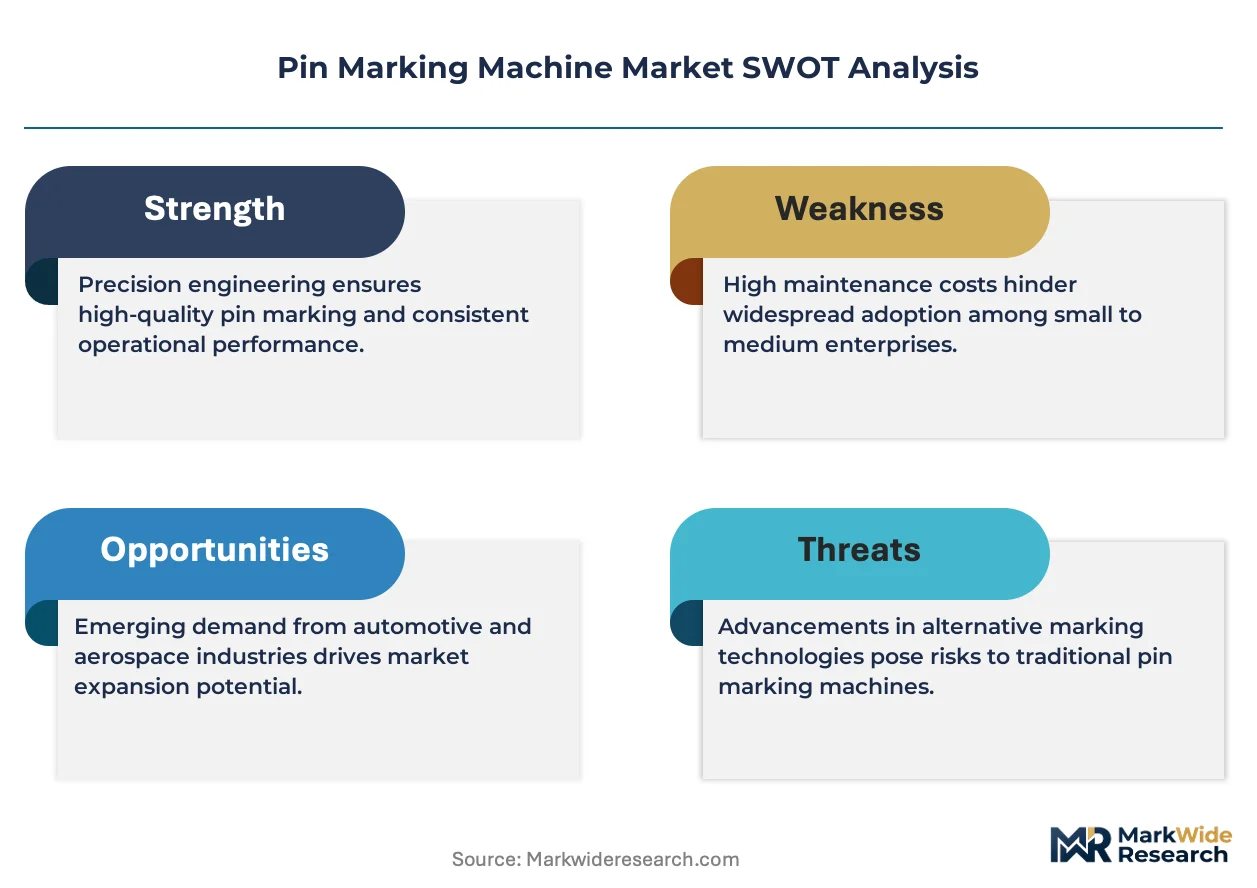
Fiber laser marking systems threaten pin marking incumbents in electronics and consumer goods applications where mechanical cycle times lag non-contact speeds. Incumbents must navigate this substitution pressure while defending aerospace and medical device strongholds where regulatory permanence requirements favor mechanical indentation.
For Market Incumbents: Harden installed-base retention through predictive maintenance contracts that lock in recurring revenue from Gravotech-style service networks. Deepen stylus material R&D to qualify REACH-compliant carbide and ceramic formulations ahead of regulatory deadlines. Defend against laser substitution by emphasizing NADCAP-compliant deep marking for titanium and Inconel alloys where fiber systems cannot achieve fatigue-resistant indentations.
For New Entrants and Emerging Players: Build out equipment-as-a-service offerings targeting Indian and Southeast Asian job shops where lease financing unlocks access to capital-constrained fabricators. Battery supply chain traceability presents the most penetrable white-space as emerging cell manufacturing regulations extend marking requirements to lithium-ion module housings. Pursue hydrogen infrastructure component certification as a first-mover angle before safety standards solidify.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among European-integrated service-network operators with installed-base retrofit capabilities. Long-term viability favors suppliers with NADCAP accreditation and FDA process validation documentation that extends customer switching costs. Watch for inflection in battery supply chain marking mandates as the signal for capacity expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Stylus Material Transition | REACH-compliant carbide and ceramic formulations secure European market access for medical device suppliers. |
| Equipment-as-a-Service Launch | Lease financing unlocks Indian job shop demand without capital-heavy purchase barriers. |
| Aerospace Certification Investment | NADCAP and AS9100 accreditation locks in long-term service relationships with Toulouse and Turin aerostructures manufacturers. |
| Battery Supply Chain Positioning | Early marking station deployment captures emerging lithium-ion module traceability requirements. |
| Cloud-Connected Diagnostics Integration | Software-defined control architectures enable predictive maintenance contracts across Stuttgart and Detroit automotive tiers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC equipment manufacturer filings, and EU regulatory directives. Interviews with maintenance directors at automotive tier-one suppliers, plant engineers in metal fabrication job shops, aftermarket service heads at marking equipment distributors, and biomedical engineers at FDA-regulated device manufacturers informed demand-side validation. Bottom-up equipment shipment analysis triangulates against top-down manufacturing value-add estimates across the projection horizon.
Forecast inputs include automotive production schedules, aerospace OEM delivery backlogs, and medical device regulatory submission pipelines. Segmentation dimensions span configuration type, actuation technology, end-use application, and customer procurement modality. CAGRs derive from replacement cycle velocity differentials between portable and industrial platforms, technology displacement curves from pneumatic to electric systems, and regulatory mandate implementation timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese pneumatic specialists or accelerated laser substitution in electronics would shift outcomes. Cross-checking against IHS Markit automotive production data and FAA aerospace certification databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
Vibration Isolation Tables Market
Industrial Equipment
Global Dicing Blades Market
Industrial Equipment
Soldering Iron Market
Industrial Equipment
Cleanroom Equipment Market
Industrial Equipment
Global Cold Plate Market
Industrial Equipment
Global Industrial Actuators Market
Industrial Equipment
Vertical Centrifugal Separator Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
South America Fans and Blowers Market
Industrial Equipment
Mounted Bearing Market
Industrial Equipment
Global Laser Material Market
Industrial Equipment
Cash Sorting Machines Market
Industrial Equipment
North America Industrial Centrifuge Market
Industrial Equipment
Europe Tempered Glass Cutting Machine Market
Industrial Equipment
China Ceramic Roller Bearings Market