
 Hot Runner Temperature Controller Market | 2026-2036
Hot Runner Temperature Controller Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Runner Temperature Controller Market Outlook
The direct-sales channel for hot runner temperature controllers is fragmenting as regional distributors and systems integrators capture mid-market accounts. Husky Injection Molding Systems leverages captive controller production to lock in mold-system bundles across North American automotive programs. Yudo Group anchors its position through integrated temperature-pid offerings bundled with manifold sales in Asian packaging hubs. Barnes Group (Synventive) differentiates via proprietary smart-control algorithms that reduce cycle-to-cycle variance for medical-device molders.
A hot runner temperature controller is an electromechanical device that regulates heat input to individual manifold zones or nozzles within an injection mold, typically maintaining setpoints within ±0.5°C through closed-loop feedback to thermocouples or RTD sensors. Its primary purpose is to prevent material degradation, reduce scrap rates, and enable synchronized filling across multi-cavity molds in high-volume polymer processing. Multi-zone controllers command premium positioning because medical-device and automotive buyers demand cavity-to-cavity consistency that single-zone units cannot deliver. Smart control technology is displacing analog and relay architectures as molders adopt Industry 4.0 protocols for remote diagnostics and predictive maintenance.
ISO 9001 quality-system certification shapes baseline supplier qualification across European and Asian procurement offices, while FDA 21 CFR Part 820 quality-system regulation governs controller validation for US medical-device molders. Germany's KBA enforces dimensional-stability requirements that cascade into tighter thermal-management specifications for automotive interior components. Buyers must weigh total cost of ownership against controller interoperability when consolidating vendor relationships across geographically dispersed mold shops.
Market Dynamics
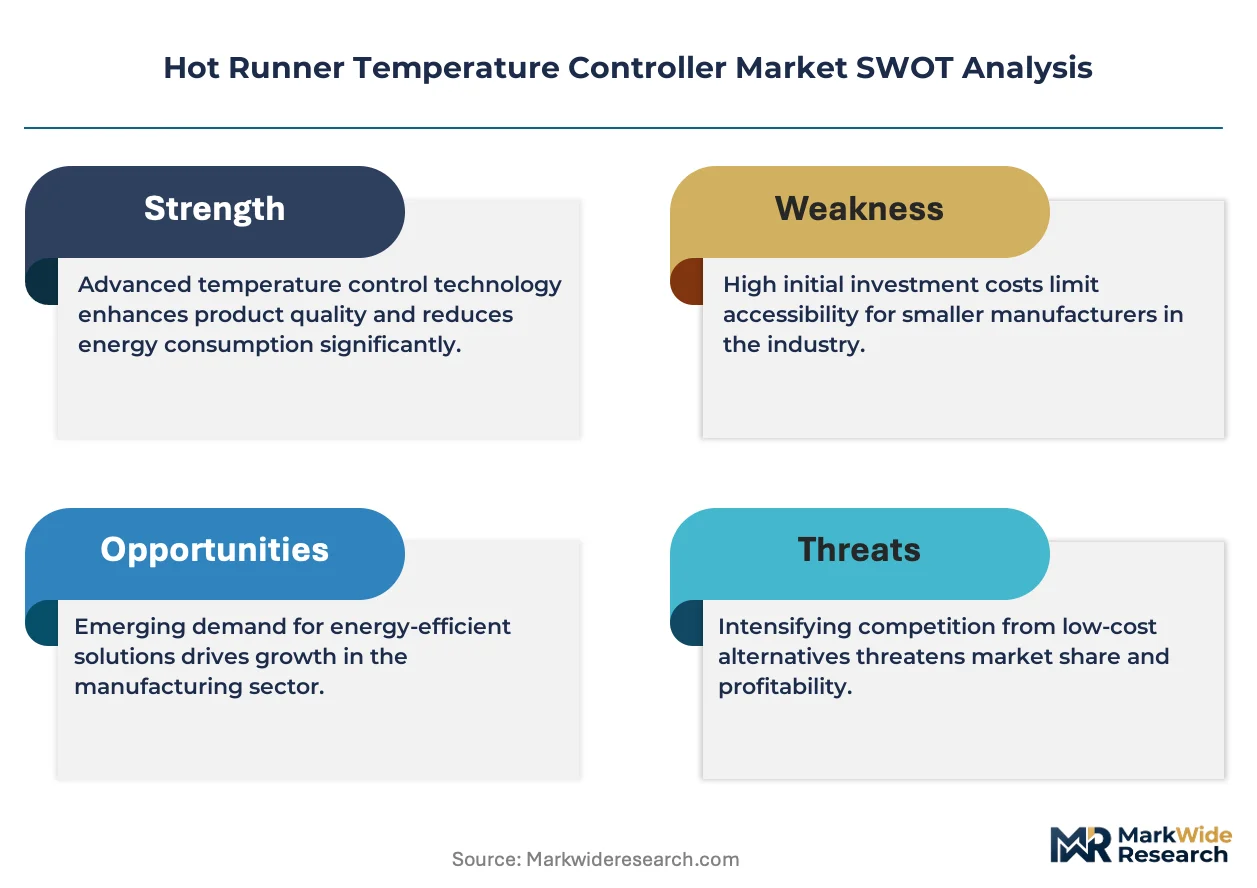
Smart control architectures are compressing replacement cycles as molders prioritize predictive maintenance over reactive thermal management, while REACH and FDA mandates tighten allowable temperature-variation tolerances across European and North American medical-device clusters.
Growth Catalysts
- Automotive precision molding:Tier-1 suppliers in Germany and Mexico are expanding multi-zone controller deployments to meet KBA dimensional-stability requirements for interior components.
- REACH compliance:ECHA enforcement of tighter thermal-management specifications is forcing molders to upgrade from analog to closed-loop PID systems.
- Industry 4.0 integration:Remote diagnostics capabilities are pulling demand from automotive and medical-device molders seeking synchronized cavity filling.
Market Restraints
- Copper and semiconductor input volatility:Controller PCB and thermocouple wiring costs fluctuate with commodity markets, squeezing margin on mid-tier units.
- Supply concentration in East Asian sensor modules:RTD and thermocouple sourcing clusters in China create vulnerability for European controller assemblers.
- Technical limitation in legacy mold retrofit:Older manifold designs lack standardized zone interfaces, complicating controller upgrades.
Strategic Opportunities
- Underpenetrated Mexican injection-molding clusters:Export-oriented automotive supply chains near Querétaro lack sufficient multi-zone controller density.
- Regulatory tailwind from FDA 21 CFR Part 820:Medical-device quality-system mandates in the United States are accelerating validation-ready controller procurement.
- Technology convergence of edge computing and thermal control:On-controller AI inference is enabling real-time cavity-pressure correlation without cloud latency.
Industry Challenges
- Control systems engineering talent scarcity:Mold shops struggle to hire technicians capable of calibrating multi-zone PID loops across heterogeneous nozzle geometries.
- ISO 9001 certification timeline compression:European procurement offices now demand twelve-week validation cycles versus historical twenty-six-week windows.
- Integration complexity with legacy SCADA:Proprietary communication protocols in aging press controllers obstruct seamless data flow from new temperature modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Runner Temperature Controller Market |
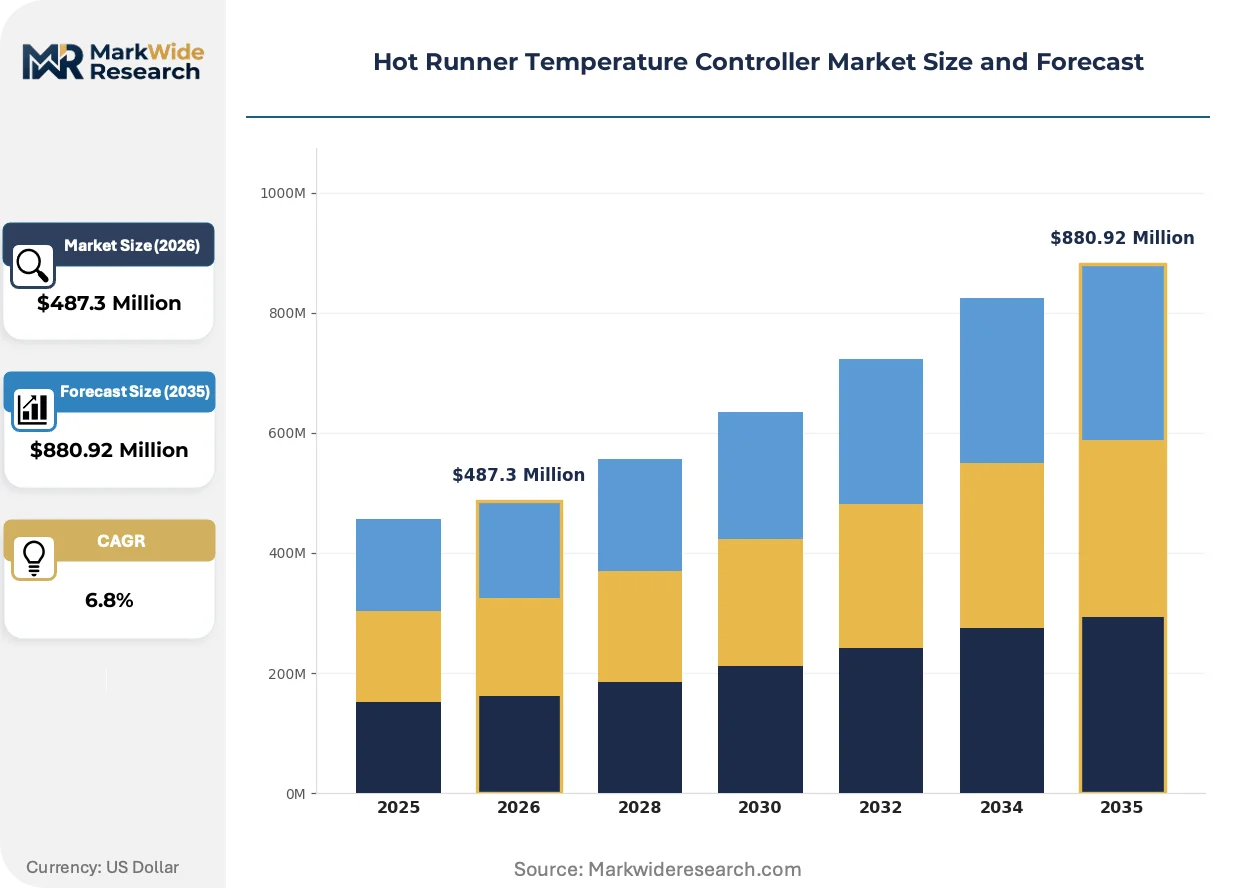
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Zone, Multi Zone, Modular, Integrated Application: Injection Molding, Blow Molding, Extrusion, Thermoforming End User: Automotive, Consumer Goods, Medical Devices, Packaging Technology: PID Control, Relay Control, Smart Control, Analog Control |
| Companies Covered | Milacron, Seiki Corporation, Husky Injection Molding Systems, GÜNTHER Heisskanaltechnik GmbH, EWIKON Heißkanalsysteme GmbH, INCOE Corporation, Barnes Group (Synventive), Gammaflux, Yudo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Runner Temperature Controller Market Strategic Shifts
Digital twin technology is collapsing the boundary between physical thermal management and simulated process optimization, while regulatory fragmentation between FDA and EMA pathways forces dual-validation strategies.
Edge-based thermal modeling software is virtualizing zone-specific heat-flow prediction, allowing automotive molders to simulate cavity filling before physical commissioning. Tier-1 suppliers in Germany are adopting these tools for complex interior trim programs. The technology is virtualizing traditional trial-and-error startup protocols that previously consumed forty-eight to seventy-two hours per mold changeover.
REACH authorization requirements for certain heat-transfer fluid chemistries are compelling controller manufacturers to certify compatibility with bio-based thermal media. ECHA's evolving substance restrictions cascade into redesign cycles for heating-element housings. Medical-device molders in Ireland and Switzerland are responding by pre-qualifying controllers against anticipated 2027 substance restrictions.
After-sales service unbundling is fragmenting the traditional controller-plus-support bundle, with molders in China's Pearl River Delta purchasing hardware through distributors while sourcing calibration services from third-party metrology labs. This bifurcation compresses vendor switching costs and pressures OEM service margins. The pattern is most visible in packaging applications where controller lifespan exceeds mold change frequency.
Hot Runner Temperature Controller Market Segmentation
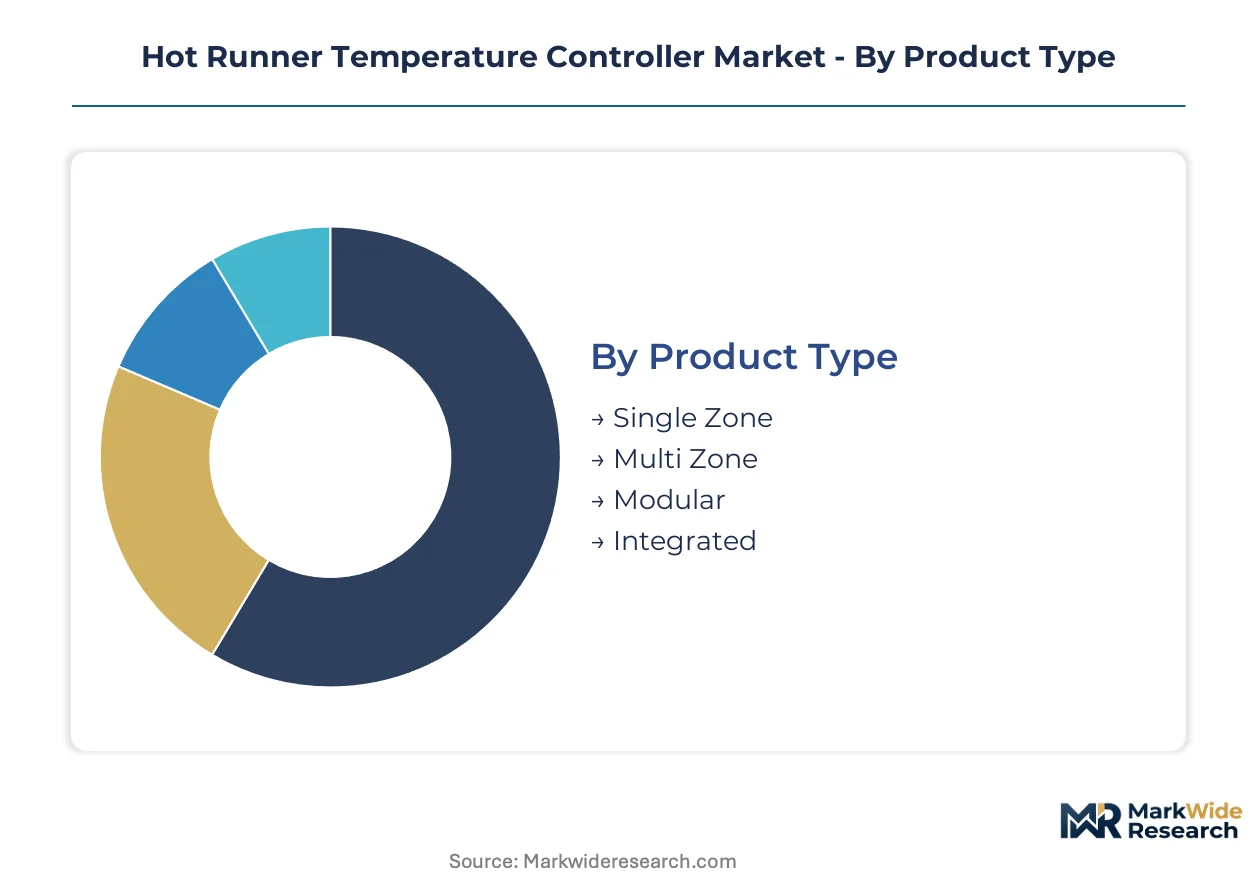
Hot runner temperature controller purchasing patterns diverge sharply by production environment. Automotive programs demand multi-zone precision for dimensional stability, while packaging operations prioritize rapid controller swap-out over calibration complexity. Segmentation reveals where technology premiums command pricing power versus where hardware commoditization dominates.
Product Type:
Multi-zone units turn over fastest in automotive retooling cycles, while modular architectures persist longest in packaging hubs running standardized molds.
- Multi Zone:These systems coordinate eight to sixty-four independent heating zones through centralized PID loops, enabling cavity-to-cavity temperature uniformity within ±0.5°C. German Tier-1 automotive suppliers deploy these for interior trim components facing KBA dimensional-stability enforcement. REACH-compliant closed-loop architectures are displacing relay-based predecessors in European medical-device clusters.
- Single Zone:Standalone controllers manage one nozzle or manifold segment through basic thermocouple feedback, dominating legacy mold retrofits where wiring harness replacement costs prohibit multi-zone upgrades. Mexican packaging molders near Querétaro favor these for short-run export contracts where mold change frequency exceeds controller amortization periods.
- Modular:Rack-mountable units allow zone-count expansion without full controller replacement, appealing to contract molders serving heterogeneous client portfolios.
- Integrated:Embedded controllers ship pre-calibrated within complete hot runner systems, locking buyers into vendor-specific maintenance protocols.
Single-zone hardware dominates installed base. Multi-zone systems are where expansion concentrates.
Application:
Injection molding commands the steepest controller specification tiers, while blow molding and extrusion operate at lower thermal-management precision thresholds.
- Injection Molding:Multi-cavity precision molding for automotive interior components and medical devices demands synchronized filling across dozens of cavities, requiring zone-specific heat input modulation. FDA 21 CFR Part 820 validation protocols in the United States mandate documented temperature traceability that analog controllers cannot provide.
- Blow Molding:Parison temperature control for packaging applications operates with wider tolerance bands, accepting simpler relay architectures where cycle consistency matters less than equipment uptime.
- Extrusion:Profile and sheet extrusion applies hot runner controllers primarily for die temperature zoning, with lower zone counts per line than injection applications.
- Thermoforming:Heater bank management for thin-gauge packaging uses modified PID controllers adapted to radiant rather than conductive heating elements.
Injection molding anchors technology premium capture. Blow molding represents volume scaling without specification escalation.
End User:
Medical-device buyers impose the longest validation timelines, while automotive procurement compresses vendor qualification into twelve-week windows.
- Automotive:Interior and under-hood component programs in Germany, Mexico, and China drive multi-zone adoption for dimensional stability across polypropylene and glass-filled nylon formulations. KBA enforcement cascades into thermal-management specifications that single-zone units cannot satisfy.
- Medical Devices:FDA-regulated molders in the United States and Swissmedic-supervised facilities in Switzerland demand documented calibration traceability, predictive maintenance capabilities, and closed-loop PID architectures that support process validation protocols.
- Packaging:High-volume thin-wall container production in China's Pearl River Delta prioritizes controller durability over precision, with hardware lifespans exceeding mold change frequencies.
- Consumer Goods:Appliance and electronics housing molders balance cost pressure against cosmetic defect prevention, often deploying mid-tier PID systems without full Industry 4.0 integration.
Automotive dominates current procurement volume. Medical devices are climbing the fastest on regulatory tailwinds.
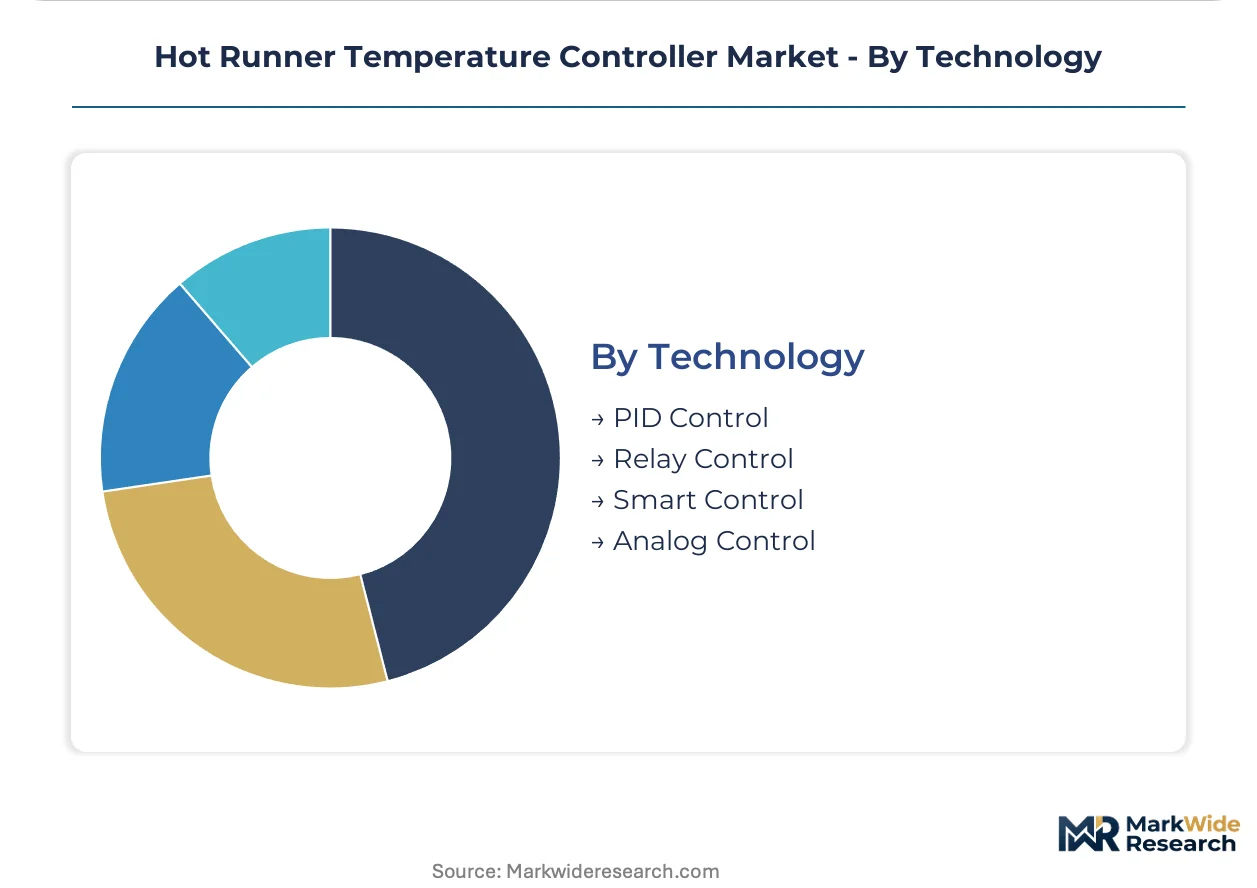
Technology:
Smart control architectures displace legacy analog systems fastest in medical-device clusters, while relay control persists in cost-sensitive packaging operations.
- Smart Control:Edge-computing-enabled controllers execute real-time cavity-pressure correlation and predictive maintenance algorithms without cloud latency. German automotive Tier-1 suppliers adopt these for complex interior programs requiring digital twin integration.
- PID Control:Proportional-integral-derivative feedback loops remain the industrial standard for closed-loop temperature regulation, with incremental software improvements replacing full hardware swaps in mid-market accounts.
- Relay Control:On-off switching architectures survive in legacy packaging installations where temperature oscillation tolerance exceeds material degradation thresholds.
- Analog Control:Potentiometer-based setpoint systems face obsolescence as ECHA REACH enforcement tightens documentation requirements for European medical-device molders.
PID control dominates installed base. Smart control is gaining share fastest on Industry 4.0 integration demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive supply chains while Mexican export clusters absorb margin pressure from rapid controller deployment cycles. This asymmetry shapes procurement patterns across the three dominant injection-molding geographies.
Germany
KBA dimensional-stability enforcement for interior components drives multi-zone controller specification. REACH authorization timelines compress vendor qualification windows to twelve weeks. Stuttgart and Wolfsburg automotive clusters demand cavity-to-cavity uniformity within ±0.5°C for polypropylene trim programs.
China
Pearl River Delta packaging hubs prioritize controller durability over precision for thin-wall container production. GB standards alignment with ISO 9001 shapes baseline supplier qualification. Shenzhen and Dongguan molders unbundle after-sales service, purchasing hardware through distributors while sourcing calibration from third-party metrology labs.
United States
FDA 21 CFR Part 820 mandates documented temperature traceability for medical-device molders. Automotive retooling in Michigan and Ohio accelerates smart-control adoption for predictive maintenance. Detroit-area Tier-1 suppliers compress vendor qualification into compressed procurement cycles.
Mexico
Export-oriented automotive supply chains near Querétaro lack sufficient multi-zone controller density. NOM standards enforcement lags REACH and FDA stringency, enabling relay-control persistence in legacy installations. Guanajuato and Nuevo León injection-molding clusters face technical limitations retrofitting older manifold designs with standardized zone interfaces.
Switzerland
Swissmedic-supervised medical-device facilities demand predictive maintenance capabilities and closed-loop PID architectures. Pre-qualification against anticipated 2027 REACH substance restrictions shapes controller procurement in Basel and Zurich clusters. Precision molding for pharmaceutical packaging commands premium positioning for validation-ready systems.
Hot Runner Temperature Controller Market Competitive Environment
Integrated hot-runner system builders and standalone controller specialists split the market between bundled solution sales and component-level procurement. The vendor base concentrates among mold-system OEMs with captive controller production and independent electronics manufacturers serving heterogeneous client portfolios. Two strategic archetypes dominate: vertically integrated mold suppliers leveraging controller bundling for account lock-in, and modular specialists capturing contract molders through interoperability claims. Competitive moves center on geographic expansion into underpenetrated Mexican clusters and technology licensing for edge-computing thermal algorithms.
Within the integrated-system tier, Husky Injection Molding Systems and Yudo Group exemplify bundling strategies that tie controller procurement to complete hot-runner packages. Barnes Group occupies a position bridging integrated and specialist archetypes through its Synventive division. Among German precision-engineering houses, GÜNTHER Heisskanaltechnik GmbH and EWIKON Heißkanalsysteme GmbH represent European-centric mold-system bundlers with strong automotive sector positioning. These five entities collectively anchor the competitive structure, with the remainder of the market fragmenting across regional distributors and mid-tier PID controller assemblers.
| Leading Market Players |
|---|
| Milacron |
| Seiki Corporation |
| Husky Injection Molding Systems |
| GÜNTHER Heisskanaltechnik GmbH |
| EWIKON Heißkanalsysteme GmbH |
| INCOE Corporation |
| Barnes Group (Synventive) |
| Gammaflux |
| Yudo Group |
| Others |
Value Chain & Pricing Dynamics
Copper and semiconductor input volatility determines both tiered pricing spreads and supply chain configuration across hot runner temperature controller manufacturing. Component cost fluctuations compress margins on mid-tier PID units while pushing automotive and medical-device buyers toward premium smart-control architectures with longer amortization horizons.
Pricing Analysis
Configured-to-order pricing for multi-zone systems with embedded edge-computing capabilities commands spreads of 40-60 percent above standard single-zone relay controllers. Pricing stratifies across premium smart-control tiers, mid-range PID architectures, and economy relay units based on zone-count scalability and FDA 21 CFR Part 820 validation documentation. Cost compression in economy relay tiers intensifies as Chinese packaging molders unbundle hardware from calibration services. Medical-device buyers in Switzerland and the United States exhibit lowest price sensitivity due to regulatory compliance mandates.
Supply Chain Analysis
Contract manufacturing capacity for controller PCB assemblies concentrates in Taiwan, South Korea, and coastal China. Thermocouple and RTD sensor sourcing draws from specialized clusters in Jiangsu province and Shenzhen SEZ. Single-source vulnerability around precision analog-to-digital converter chips creates exposure for European controller assemblers. Distribution runs through regional distributors and systems integrators capturing mid-market accounts, with direct OEM relationships reserved for automotive Tier-1 programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart control architectures are compressing replacement cycles across automotive and medical-device clusters, creating a high-growth disruption anchored by Industry 4.0 integration mandates and REACH authorization timelines.
For Market Incumbents: Insulate installed-base relationships by embedding predictive maintenance capabilities that increase switching costs for automotive Tier-1 suppliers. Deepen in-house production of edge-computing thermal algorithms to differentiate against modular specialists. Prioritize ISO 9001 certification timeline compression to match European procurement office demands for twelve-week validation windows.
For New Entrants and Emerging Players: Pursue underpenetrated Mexican automotive clusters near Querétaro where multi-zone controller density lags German and Chinese benchmarks. Target contract molders serving heterogeneous client portfolios through modular rack-mountable architectures that enable zone-count expansion without full replacement. Lead with interoperability claims against proprietary integrated systems.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors specialists with captive smart-control IP over legacy relay manufacturers. Five-to-ten year viability hinges on edge-computing thermal algorithm ownership and FDA validation-ready product pipelines. Watch for inflection signals in ECHA substance restriction pre-qualification activity among Swiss and Irish medical-device molders.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Integration | Enables real-time cavity-pressure correlation without cloud latency for German automotive Tier-1 suppliers. |
| Regulatory Pre-Qualification | Positions controllers against anticipated ECHA substance restrictions shaping 2027 procurement in Basel clusters. |
| Modular Architecture Expansion | Captures contract molders through zone-count scalability without full controller replacement across heterogeneous portfolios. |
| After-Sales Service Unbundling | Responds to Pearl River Delta molders purchasing hardware through distributors while sourcing calibration from metrology labs. |
| Mexican Cluster Penetration | Addresses density gaps in Querétaro automotive supply chains facing KBA dimensional-stability enforcement. |
Study Parameters
Cross-validation between primary interviews with hot runner system engineers, automotive Tier-1 procurement leads, and medical-device quality managers anchors the qualitative findings. Secondary validation draws from customs and trade data, SEC filings of listed industrial equipment manufacturers, ECHA REACH authorization databases, and FDA 510(k) submission records. Bottom-up demand modeling from injection-molding machine installations triangulates against top-down market sizing from hot runner system OEM revenue disclosures.
Calibration against historical replacement cycle data and regulatory enforcement timelines shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, application, end-user industry, and technology architecture. CAGRs derive from zone-count expansion rates in automotive retooling programs and medical-device validation-ready procurement acceleration. Industry-specific inputs incorporate KBA dimensional-stability enforcement cascades and FDA 21 CFR Part 820 quality-system mandate adoption curves.
Sensitivities concentrate around copper and semiconductor commodity volatility, ECHA substance restriction timeline shifts, and Mexican automotive cluster expansion velocity. Forecasts reflect documented assumptions regarding Industry 4.0 protocol adoption rates and REACH compliance cost pass-through elasticity. Quarterly review of thermocouple import volumes, ECHA authorization list updates, and German automotive interior trim program announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Press-Insertion Systems Market
Industrial Equipment
North America Rental Chillers Market
Industrial Equipment
Cartridge Heaters Market
Industrial Equipment
Laser Marking Machine Market
Industrial Equipment
Air Preparation Equipment (FRL) Market
Industrial Equipment
Portable Laser Cleaning Machine Market
Industrial Equipment
Laser Processing Market
Industrial Equipment
Thermoelectric Refrigerator Market
Industrial Equipment
Europe Industrial Centrifuge Market
Industrial Equipment
Linear Motion (LM) Shaft Market
Industrial Equipment
Industrial Vacuum Evaporation Systems Market
Industrial Equipment
Asia-Pacific Electro Hydraulic Servo Valve Market
Industrial Equipment
Air Bearing Spindle Market
Industrial Equipment
Liquid Cold Plates Market
Industrial Equipment
North America Industrial Centrifuge Market
Industrial Equipment
PCB Punching Machine Market