
 Latin America Explosion-Proof Equipment Market | 2026-2036
Latin America Explosion-Proof Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Explosion-Proof Equipment Market Foresight
Maintenance contracts bundled with hazardous-location hardware is realigning vendor-customer relationships across Latin America. ABB Ltd leverages its regional service footprint to anchor long-term agreements with Petrobras-operated facilities. R. STAHL AG specializes in IECEx-certified assemblies that sustain premium positioning despite price competition from regional distributors. Emerson Electric Co. controls aftermarket revenue streams by embedding predictive diagnostics into its flameproof instrumentation.
Explosion-proof equipment encompasses electrical apparatus engineered to contain internal ignition and prevent flame propagation into hazardous atmospheres, typically rated for gas groups IIA through IIC and temperature classes T1 through T6. Intrinsic safety technology dominates laboratory and pharmaceutical settings where minimal energy containment prevents ignition in volatile compound zones. Flameproof enclosures lead oil and gas applications across Brazilian pre-salt fields due to proven performance in hydrogen sulfide-rich environments. Cable glands represent the fastest-growing product category as brownfield retrofit projects multiply across aging Mexican refineries.
Brazil's INMETRO certification requirements and Mexico's NOM-001-SEDE electrical standards shape product design cycles and import compliance costs for foreign manufacturers. IECEx and ATEX alignment pressures from European parent companies of local subsidiaries accelerate standard harmonization but strain smaller domestic fabricators. Stakeholders must monitor regulatory divergence between Mercosur and Pacific Alliance frameworks when configuring regional supply chains and certification strategies.
Market Dynamics
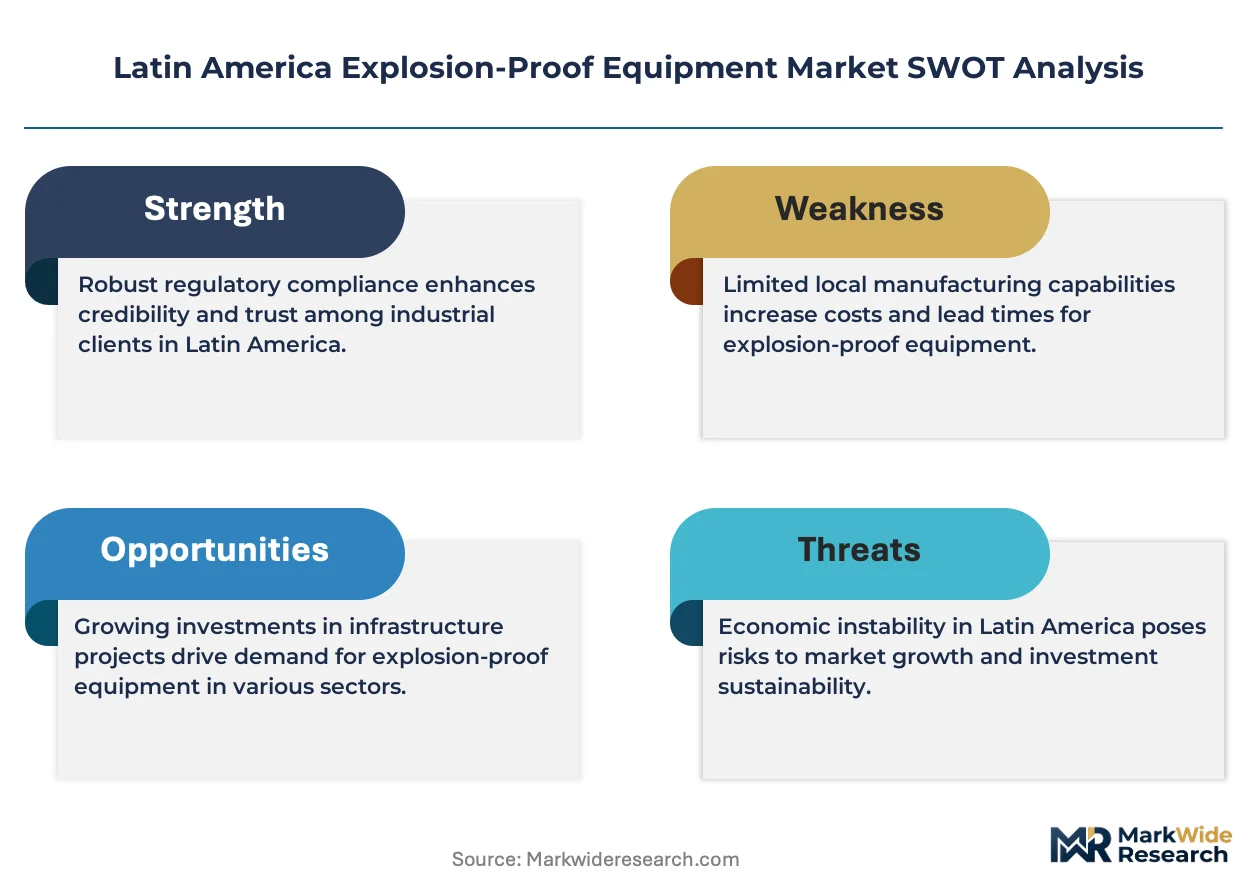
Brazil's INMETRO certification mandates and Mexico's NOM-001-SEDE electrical standards are compressing product design cycles while elevating compliance costs for foreign manufacturers. These regulatory frameworks now function as primary gatekeepers to market access, forcing suppliers to reconfigure regional supply chains around dual-certification strategies.
Growth Catalysts
- Offshore pre-salt expansion:Petrobras-operated platforms in Brazil's Santos Basin require flameproof enclosures rated for hydrogen sulfide-rich environments, sustaining equipment refresh cycles.
- NOM certification mandates:Mexico's energy reform imposes stricter hazardous location standards on downstream infrastructure, compelling refinery operators to upgrade legacy electrical systems.
- Vaca Muerta shale development:Neuquén Province concentration of drilling activity generates concentrated demand for intrinsic safety systems in wellhead automation.
Market Restraints
- Copper and aluminum price volatility:Raw material input swings compress margin stability for enclosure fabricators operating on fixed-price maintenance contracts.
- European parent-company standard alignment:IECEx and ATEX harmonization pressures strain smaller domestic fabricators lacking capital for dual-testing protocols.
- Extended INMETRO approval timelines:Bureaucratic certification queues delay product launches by 8-14 months, freezing working capital in regulatory limbo.
Strategic Opportunities
- Colombia's offshore Caribbean blocks:Underpenetrated licensing rounds create first-mover positioning for IECEx-certified cable gland suppliers.
- Predictive diagnostics integration:Convergence of flameproof instrumentation with IIoT sensor networks enables recurring revenue streams through condition-based maintenance.
- Pharmaceutical laboratory buildouts:Buenos Aires and São Paulo biotech clusters generate demand for intrinsic safety barriers in solvent handling zones.
Industry Challenges
- IECEx competency gaps:Shortage of certified hazardous area engineers delays installation commissioning and post-sale technical support.
- Legacy system interoperability:Brownfield retrofit projects in Mexican refineries require custom adapter solutions for obsolete conduit interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Explosion-Proof Equipment Market |
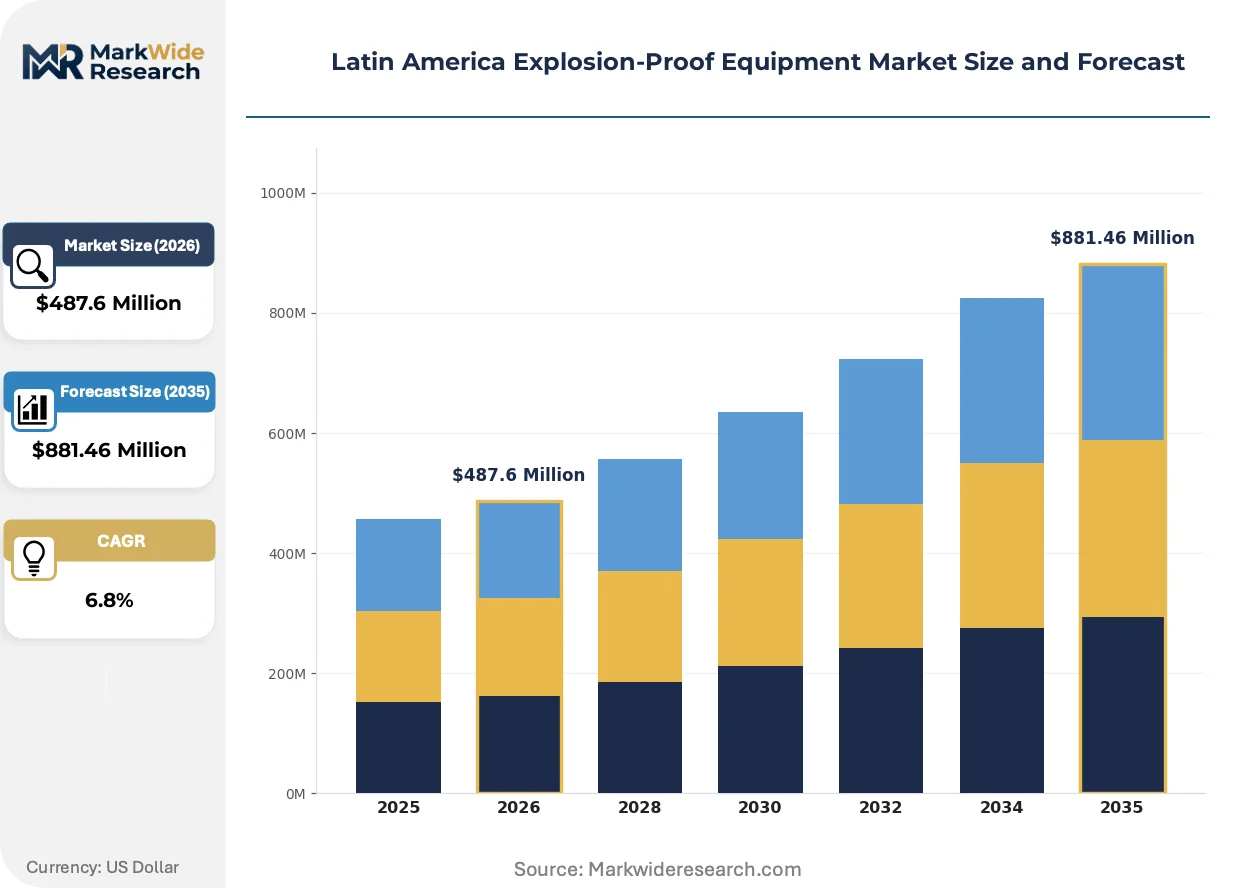
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enclosure, Cable Glands, Lighting Fixtures, Junction Boxes Technology: Flameproof, Increased Safety, Intrinsic Safety, Purged and Pressurized End User: Oil & Gas, Chemical, Mining, Pharmaceutical Application: Hazardous Locations, Industrial Facilities, Refineries, Storage Tanks |
| Companies Covered | Bartec GmbH, ABB Ltd, R. STAHL AG, Emerson Electric Co., Eaton, Marechal Electric, Pepperl+Fuchs Group, Honeywell International Inc., Adalet, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Explosion-Proof Equipment Market Shifts & Advancements
Wireless instrumentation architectures are displacing hardwired legacy systems across Latin American hazardous facilities. This shift compresses installation costs while introducing new cybersecurity vulnerabilities that vendors must address through encrypted protocol stacks.
Intrinsic safety barriers with embedded edge computing capabilities are decentralizing control architectures in Brazilian pre-salt platforms. Petrobras engineering teams specify these units for subsea distribution panels where centralized PLC access proves impractical. The technology is decentralizing maintenance workflows by enabling localized diagnostics without topside intervention.
Mercosur technical regulation revisions are tightening alignment gaps with IECEx 02 certification schemes. Argentine and Brazilian regulators coordinate mutual recognition protocols to reduce redundant testing for cross-border equipment shipments. Cable gland manufacturers with existing IECEx 02 approvals gain accelerated market entry versus competitors pursuing parallel national tracks.
Maintenance contract unbundling is fragmenting traditional hardware-plus-service bundles across Mexican energy infrastructure. Pemex-affiliated operators now separate procurement of flameproof enclosures from installation and commissioning services, opening channel entry for specialized regional integrators. This pattern concentrates in Veracruz and Tamaulipas refinery complexes where cost transparency pressures dominate sourcing decisions.
Latin America Explosion-Proof Equipment Market Segmentation
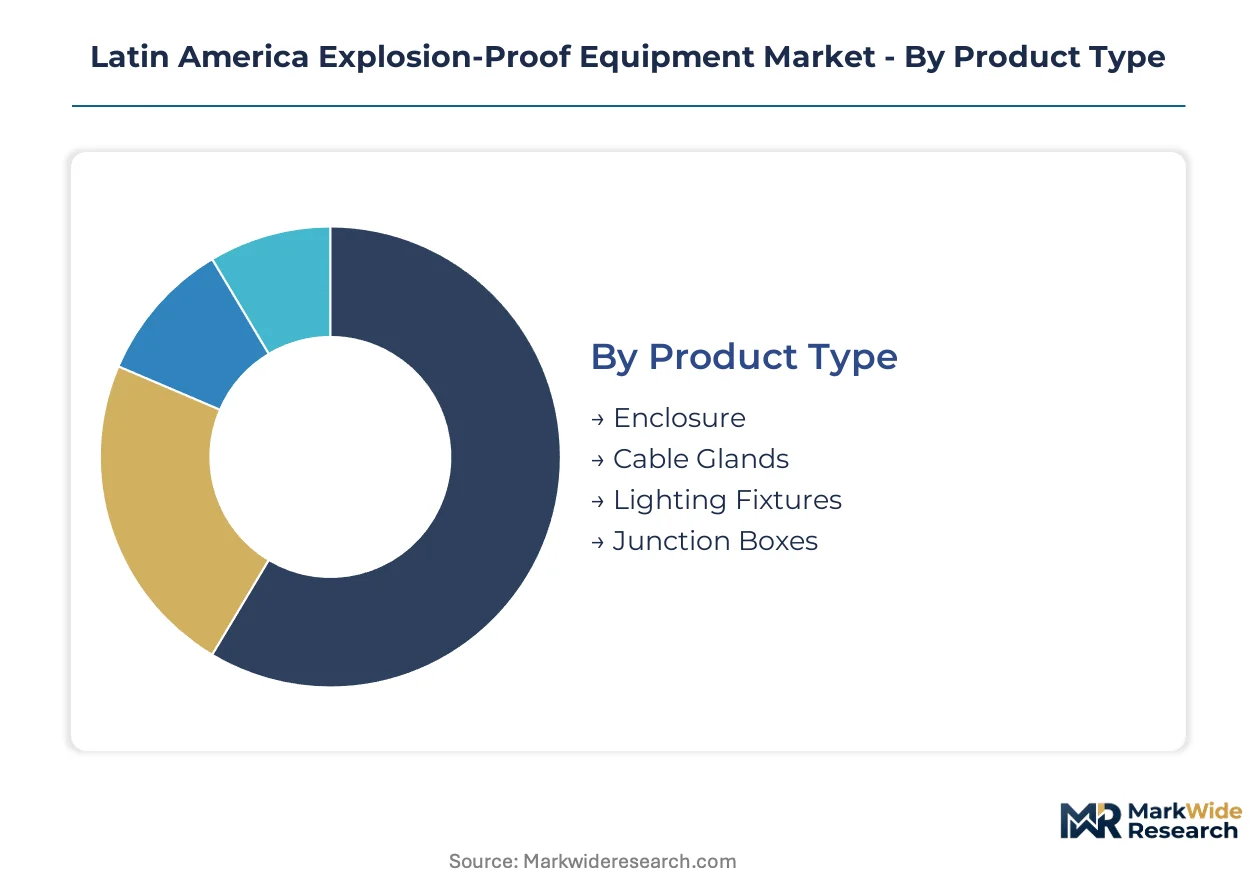
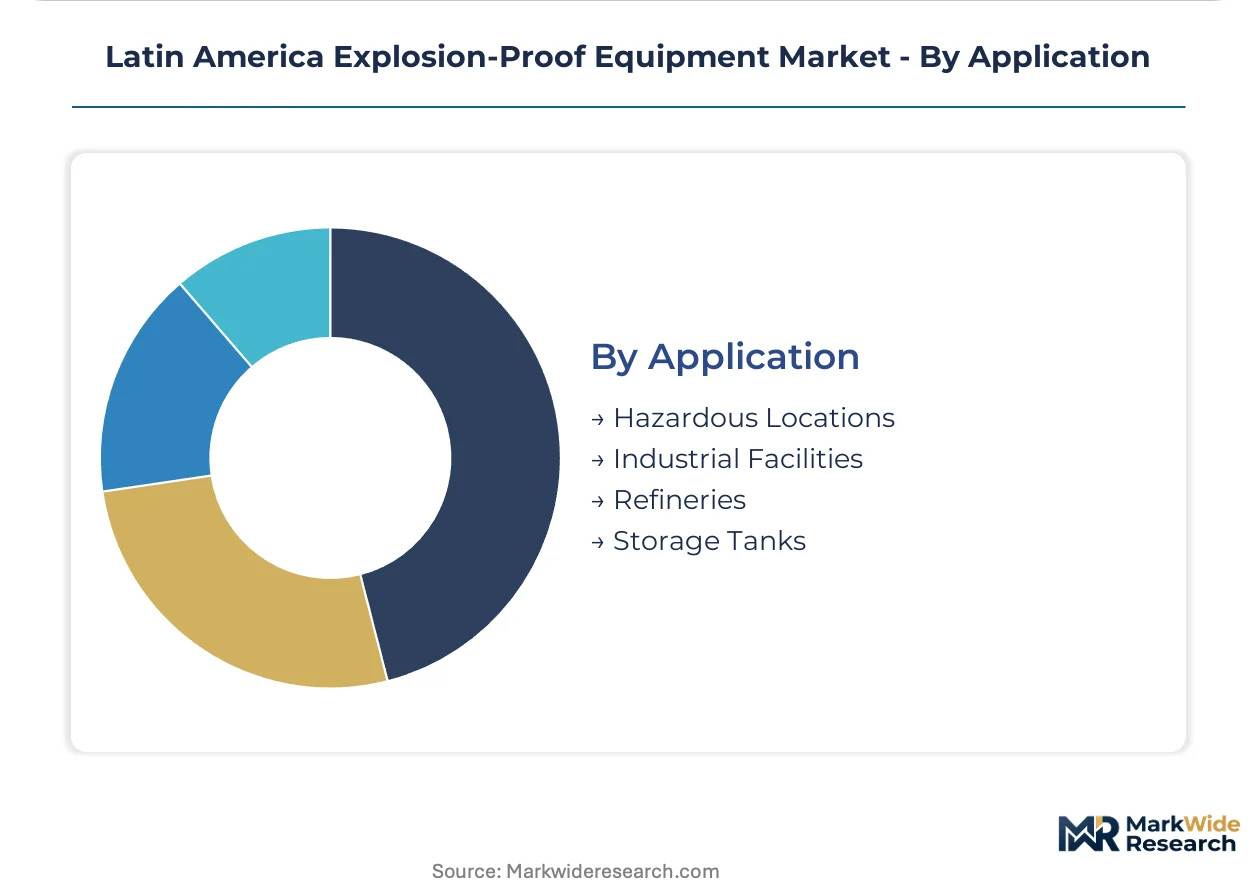
Segmentation in Latin America's explosion-proof equipment market reveals how certification requirements, environmental conditions, and operational intensity shape procurement patterns across distinct technical categories. Buyers configure portfolios around specific hazardous zone classifications rather than pursuing one-size-fits-all solutions.
Product Type:
Standardization dominates high-volume categories while custom engineering persists in project-critical applications across this spectrum.
- Enclosure:Fabricated steel or aluminum housings rated for gas groups IIA through IIC contain internal explosions and prevent flame propagation. Brazilian pre-salt platforms specify these for hydrogen sulfide-rich environments, driving demand for 316 stainless steel variants with extended corrosion warranties.
- Cable Glands:Compression and barrier-type sealing devices maintain explosion protection integrity at wiring entry points. Mexican brownfield refinery retrofits concentrate procurement here, with operators replacing obsolete conduit interfaces to meet NOM-001-SEDE electrical standards.
- Lighting Fixtures:LED-based luminaires with flameproof or increased safety ratings illuminate hazardous zones without ignition risk.
- Junction Boxes:Terminal enclosures aggregate circuit distribution in Zone 1 and Zone 2 locations.
Most installed capacity flows through Enclosure. Expansion is steepest in Cable Glands.
Technology:
Cost tiers separate proven incumbent methods from emerging architectures gaining share in specialized applications.
- Flameproof:Ex d-rated equipment contains internal ignition within robust housings that cool escaping gases below ambient ignition temperatures. Petrobras-operated Santos Basin platforms specify this technology exclusively for surface installations, prioritizing track records in hydrogen sulfide exposure.
- Intrinsic Safety:Ex i systems limit energy available to sparking or thermal effects below ignition thresholds of target gas groups. Neuquén Province shale wellhead automation concentrates demand here, where minimal energy containment prevents ignition in volatile compound zones around Vaca Muerta drilling operations.
- Increased Safety:Ex e construction prevents arcs, sparks, or excessive temperatures in normal operation.
- Purged and Pressurized:Ex p systems maintain protective gas pressure to exclude hazardous atmospheres from enclosures.
Flameproof commands the largest installed base. Intrinsic Safety is gaining share fastest in new automation deployments.
End User:
Customer type determines specification stringency, with international operators imposing parent-company standards beyond local minimums.
- Oil & Gas:Upstream, midstream, and downstream operations across Brazilian pre-salt fields, Mexican refineries, and Argentine shale formations drive specification intensity. Operators bundle maintenance contracts with hardware procurement, anchoring long-term vendor relationships.
- Chemical:Petrochemical complexes and specialty chemical plants require Zone-rated equipment for solvent handling and reactor zones. Buenos Aires industrial corridors concentrate Argentine demand here.
- Mining:Underground and surface extraction operations in Chilean copper belts and Peruvian polymetallic deposits specify explosion-proof electrical systems.
- Pharmaceutical:Biotech manufacturing clusters in São Paulo and Buenos Aires demand intrinsic safety barriers for solvent handling in laboratory and production environments.
Oil & Gas absorbs the majority of current capacity. Pharmaceutical applications are expanding most quickly as regional biotech investment accelerates.
Application:
Geography within Latin America shapes application mix, with coastal offshore operations differing materially from inland industrial corridors.
- Hazardous Locations:Zone 0, 1, and 2 classified areas under IECEx and national standards require purpose-built equipment with certified protection concepts. Brazilian INMETRO and Mexican NOM frameworks govern compliance costs and design cycles for installations across both countries.
- Refineries:Downstream processing facilities in Veracruz, Tamaulipas, and Campos Basin regions concentrate demand for flameproof instrumentation and cable management systems. Pemex-affiliated operators now unbundle procurement from installation services, opening channel entry for specialized regional integrators.
- Industrial Facilities:Manufacturing and processing plants outside core oil and gas sectors specify hazardous area equipment.
- Storage Tanks:Aboveground and underground tank farms require rated electrical systems for monitoring and safety applications.
Hazardous Locations contain the dominant share of deployed equipment. Refinery applications show the steepest retrofit-driven expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil absorbs larger equipment volumes than Mexico, yet Mexican regulatory velocity under NOM reforms is compressing foreign supplier lead times more aggressively. Argentina's shale corridor generates concentrated demand spikes that outpace national market averages.
Brazil
Petrobras-operated pre-salt platforms in the Santos Basin sustain flameproof enclosure procurement cycles rated for hydrogen sulfide-rich environments. INMETRO certification mandates function as primary gatekeepers, extending approval timelines by 8-14 months for unqualified suppliers. The Campos Basin refinery complex and São Paulo industrial corridor concentrate maintenance contract bundling with hardware procurement.
Mexico
NOM-001-SEDE electrical standards compel downstream operators to upgrade legacy systems across Veracruz and Tamaulipas refinery complexes. Pemex-affiliated operators now unbundle procurement from installation services, fragmenting traditional vendor relationships. The Mexico City Metro area anchors specialized regional integrators capturing commissioning work separated from hardware supply.
Argentina
Vaca Muerta shale development in Neuquén Province concentrates intrinsic safety system demand for wellhead automation in volatile compound zones. The national pharmaceutical regulator enforces hazardous location standards on Buenos Aires biotech laboratory buildouts. Mendoza's industrial corridor sees secondary demand from petrochemical processing adjacent to shale logistics infrastructure.
Chile
Underground copper extraction in the Atacama Desert and Central Valley polymetallic deposits specifies explosion-proof electrical systems for ventilation and hoisting operations. The national mining regulator coordinates IECEx alignment with Chilean technical standards. Antofagasta and Santiago metropolitan clusters concentrate procurement authority for multinational mining operators.
Colombia
Offshore Caribbean licensing rounds create first-mover positioning for cable gland suppliers targeting underpenetrated exploration blocks. The national hydrocarbon regulator imposes hazardous area standards on new upstream concessions. Barranquilla and Cartagena port infrastructure supports equipment import logistics for coastal drilling campaigns.
Latin America Explosion-Proof Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with maintenance contract bundling favoring established service footprints while brownfield retrofits open channel entry for regional integrators. European-headquartered groups anchor premium positioning through IECEx-certified assemblies, though price competition from regional distributors compresses margin stability. Two strategic archetypes dominate: full-service providers leveraging long-term agreements with national oil companies, and certification-focused specialists sustaining technical differentiation. Competitive moves concentrate on predictive diagnostics integration and geographic expansion into underpenetrated licensing rounds.
Among Germany-based specialists, R. STAHL AG and Bartec GmbH exemplify the certification-focused archetype, anchoring premium market positioning through IECEx and ATEX alignment pressures transmitted from European parent structures. ABB Ltd, with its broader industrial automation portfolio, occupies a position bridging full-service maintenance bundling with hardware supply across Brazilian pre-salt and Mexican refinery installations. These three entities represent distinct competitive vectors: pure-play hazardous location specialization, integrated automation platforms, and regional service density.
| Leading Market Players |
|---|
| Bartec GmbH |
| ABB Ltd |
| R. STAHL AG |
| Emerson Electric Co. |
| Eaton |
| Marechal Electric |
| Pepperl+Fuchs Group |
| Honeywell International Inc. |
| Adalet |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between IECEx-certified assemblies and non-certified commodity hardware manifests in parallel supply chain configurations across Latin America. Premium-tier flameproof enclosures command sourcing from German and Swiss fabrication facilities with captive testing laboratories, while price-competitive cable glands flow through regional distributors in São Paulo and Mexico City.
Pricing Analysis
Capacity additions in Chinese aluminum casting facilities are reshaping price floors for standard enclosure housings, compressing margins for Brazilian fabricators operating on fixed-price maintenance contracts with Petrobras. Three-tier pricing structure across premium IECEx-certified, mid-tier INMETRO-compliant, and economy non-certified levels separates procurement pools. Price differentiation hinges on certification grade and after-sales service bundling. Cost compression in the mid-tier is intensifying because Pemex-affiliated operators now unbundle hardware from installation services. State-owned oil companies prove least price-sensitive; regional pharmaceutical laboratories exhibit highest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with German specialty steel suppliers providing 316 stainless steel for hydrogen sulfide-rated enclosures. Manufacturing concentration centers on Germany, Switzerland, and Brazil for finished assemblies; China and India for raw aluminum and copper components. The supply chain draws from copper and aluminum feedstock subject to commodity price volatility. Tariff exposure runs through Mercosur-Pacific Alliance regulatory divergence. Distribution runs through authorized regional distributors holding INMETRO and NOM import licenses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Specification intensity is shifting toward IECEx-certified systems as European parent companies harmonize standards across Brazilian and Mexican subsidiaries.
For Market Incumbents: Hedge against margin erosion by anchoring long-term service contracts with Petrobras and Pemex before procurement unbundling fragments vendor relationships. Backward integration into captive stainless steel sourcing mitigates raw material volatility threatening fixed-price maintenance agreements. Certification investment in dual INMETRO-NOM approval protocols preserves access across Mercosur and Pacific Alliance regulatory zones. For New Entrants and Emerging Players: Regional integrators specializing in commissioning services capture value from Pemex procurement unbundling in Veracruz and Tamaulipas refinery complexes. Colombia's underpenetrated offshore Caribbean blocks offer first-mover positioning for IECEx-certified cable gland suppliers. Neuquén Province shale automation presents accessible entry for intrinsic safety specialists targeting Vaca Muerta wellhead deployments. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier Brazilian fabricators possessing INMETRO certification infrastructure but lacking capital for IECEx dual-testing protocols. Long-term viability favors acquisition targets with established maintenance contract anchors to national oil companies. The inflection signal to watch is Mercosur technical regulation revision accelerating IECEx alignment.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Dual-Tracking | Simultaneous INMETRO and IECEx approval reduces cross-border shipment delays between Brazil and Argentina. |
| Predictive Diagnostics Integration | Embedded IIoT sensors in flameproof instrumentation enable recurring revenue through condition-based maintenance contracts. |
| Regional Integrator Partnership | Channel alliances with Mexican commissioning specialists capture value from Pemex procurement unbundling. |
| Raw Material Backward Integration | Captive stainless steel sourcing insulates margin stability against commodity price swings. |
| Pharmaceutical Laboratory Targeting | Intrinsic safety barriers for São Paulo and Buenos Aires biotech clusters diversify beyond oil and gas concentration. |
Research Methodology
Multiple input streams — regulatory filing analysis, equipment procurement databases, and trade flow records — were reconciled against primary fieldwork. Plant engineers at Brazilian pre-salt platforms, maintenance directors at Mexican refineries, and hazardous area certification specialists provided operational validation. Secondary sources included INMETRO approval registries, NOM-001-SEDE compliance filings, IECEx certificate databases, and customs import records. Bottom-up equipment deployment estimates and top-down market sizing were cross-validated through triangulation.
Historical certification timelines were cross-referenced against panel input from regional distributors and national oil company procurement officers. Segmentation modeling covered protection concept technology, product type, end-user industry, and country-level regulatory framework across the analysis window. CAGRs were derived from equipment refresh cycle analysis and brownfield retrofit pipeline assessment. Forecast inputs incorporated Petrobras capital expenditure disclosures and Mexican energy reform implementation velocity.
Revisions become necessary when Mercosur-Pacific Alliance regulatory divergence intensifies, copper and aluminum price volatility exceeds historical bands, or INMETRO approval timelines extend beyond current bureaucratic queues. Forecasts reflect documented assumptions regarding certification harmonization progress and national oil company procurement patterns. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Equipment
Air Filters Market
Industrial Equipment
Laser Plastic Welding Market
Industrial Equipment
Laser Marking Equipment Market
Industrial Equipment
Laser Marking Market
Industrial Equipment
Dry Block Heaters Market
Industrial Equipment
Screw Air End Market
Industrial Equipment
Global Laboratory Vacuum Pumps Market
Industrial Equipment
Resistance Spot Welding Machines Market
Industrial Equipment
Laser Ablation Systems Market
Industrial Equipment
Smart Pneumatics Market
Industrial Equipment
Machine Tool Cooling System Market
Industrial Equipment
Global Industrial Weighing Machines Market
Industrial Equipment
Global Special Purpose Machines Market
Industrial Equipment
CO2 Laser Market
Industrial Equipment
High-Speed Electric Spindle Market
Industrial Equipment
Grading and Batching Systems Market