
 Europe Feed Mycotoxin Detoxifiers Market | 2026-2036
Europe Feed Mycotoxin Detoxifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Mycotoxin Detoxifiers Market Foresight
The gap between premium enzymatic detoxifiers and commodity clay adsorbents is broadening as livestock producers face stricter residue limits and traceability mandates. BASF SE leverages its polymer science capabilities to engineer modified yeast cell wall products with superior aflatoxin binding affinity. Alltech, Inc. sustains competitive separation through integrated fermentation platforms that produce proprietary glucan-based mycotoxin modifiers. Kemin Industries, Inc. differentiates via precision-delivery formulations targeting deoxynivalenol degradation in ruminant feed.
Europe feed mycotoxin detoxifiers comprise functional feed additives designed to neutralize, bind, or biotransform fungal metabolites including aflatoxins, ochratoxins, and trichothecenes in compound feeds, with enzymatic variants employing esterase and epoxidase activity to cleave toxic moieties at gastrointestinal pH ranges. Adsorbents occupy the largest revenue share due to established cost economics and broad-spectrum binding capacity, though biological detoxifiers represent the fastest-expanding category as producers seek alternatives to aluminum silicate inclusion rates that risk mineral nutrient sequestration. Enzyme formulations command premium positioning in poultry and swine applications where Fusarium mycotoxin pressure demands targeted biotransformation rather than physical adsorption alone.
EFSA maximum levels for deoxynivalenol and zearalenone in cereals and complete feeds compel compound feed manufacturers to incorporate certified detoxifiers into quality assurance protocols, while REACH registration requirements for novel biological active substances extend development timelines and elevate compliance expenditure for new market entrants. The EU Green Deal Farm to Fork strategy intensifies scrutiny on chemical additive residues, redirecting formulation investment toward microbial and enzymatic platforms with favorable toxicology profiles. Stakeholders must monitor pending revisions to Commission Regulation (EC) No 1881/2006 and assess biological detoxifier efficacy claims against emerging EFSA guidance on in vitro to in vivo translation standards.
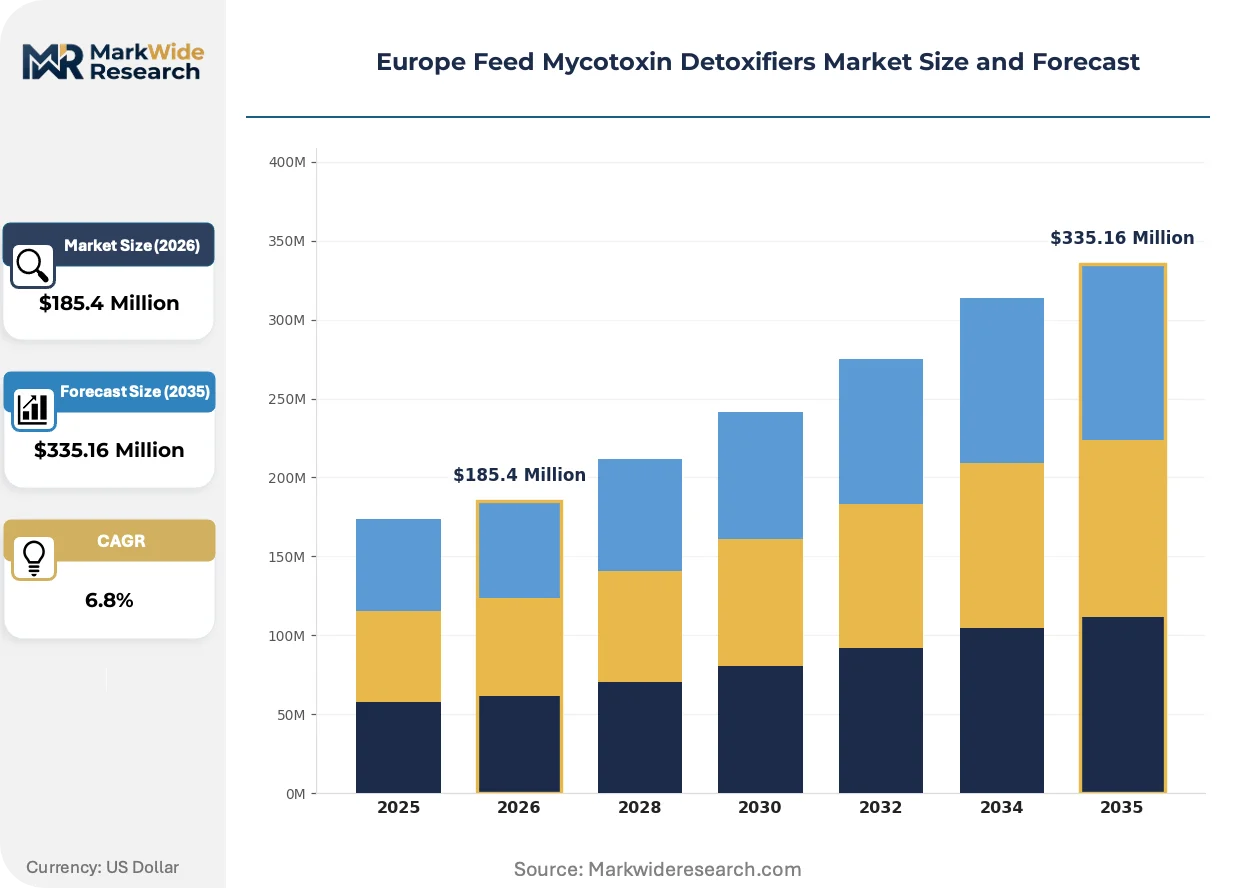
Market Dynamics
The EU Green Deal Farm to Fork strategy is compressing formulation timelines as compound feed manufacturers pivot from aluminum silicate adsorbents toward enzymatic and microbial detoxifiers that satisfy tightened EFSA residue thresholds without sequestering essential minerals.
Growth Catalysts
- EFSA threshold tightening:Maximum levels for deoxynivalenol and zearalenone in cereals and complete feeds mandate certified detoxifier inclusion in quality assurance protocols, expanding addressable volume for validated biological solutions.
- Poultry sector expansion:Intensive operations across Germany and France are accelerating adoption of esterase-based enzymatic detoxifiers to manage aflatoxin and fumonisin pressure in high-density broiler and layer systems.
- Netherlands-Denmark procurement concentration:Volume procurement hubs in these livestock-intensive markets create scale economics that subsidize biological detoxifier penetration into mid-tier feed compounders.
Market Restraints
- REACH registration timelines:Novel biological active substances face extended development cycles and elevated compliance expenditure, extending payback periods for new market entrants beyond typical venture horizons.
- Aluminum silicate cost anchoring:Commodity clay adsorbents maintain entrenched price positioning at 60-70% below enzymatic alternatives, constraining premium substitution in price-sensitive ruminant feed segments.
- Fermentation capacity concentration:Microbial detoxifier production clusters in Belgium and Germany create geographic supply vulnerability and input competition with human pharmaceutical biologics.
Strategic Opportunities
- Poland and Romania penetration:Underdeveloped mycotoxin management infrastructure in these expanding livestock markets offers first-mover positioning before EFSA-aligned national regulations fully harmonize.
- Precision-delivery formulation convergence:Encapsulation technologies enabling targeted release at ruminant rumen pH unlock deoxynivalenol degradation applications previously dominated by adsorbents.
- CSRD-aligned sustainability reporting:Biological detoxifiers' favorable carbon and toxicology profiles attract ESG-mandated procurement from integrated protein producers subject to corporate sustainability reporting requirements.
Industry Challenges
- In vivo validation expertise scarcity:EFSA guidance on in vitro to in vivo translation standards demands specialized toxicology and ruminant physiology capabilities that outstrip available talent pools in smaller member states.
- Commission Regulation (EC) No 1881/2006 revision uncertainty:Pending mycotoxin maximum level revisions create formulation freeze periods as compounders defer detoxifier specification commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Mycotoxin Detoxifiers Market |
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $335.16 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adsorbents, Enzymes, Chemical Detoxifiers, Biological Detoxifiers Application: Poultry, Swine, Ruminants, Aquaculture Formulation: Powder, Liquid, Granular, Pellet Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | DSM-Firmenich AG, Cargill, Incorporated, BASF SE, Brenntag SE, Adisseo SAS, Alltech, Inc, Kemin Industries, Inc., Biomin Holding GmbH, Impextraco N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Mycotoxin Detoxifiers Market Shifts & Advancements
Formulation science is advancing through three parallel vectors: enzymatic specificity gains, regulatory chemistry substitution mandates, and procurement model compression favoring integrated supplier relationships over transactional additive purchasing.
Modified yeast cell wall technologies are converging with precision polymer engineering to achieve superior aflatoxin binding affinity at reduced inclusion rates. Poultry integrators in France and the Netherlands are piloting these advanced adsorbents at commercial scale. The structural compression of mineral nutrient sequestration risk is enabling premium pricing that bridges the historical gap between biological and clay-based solutions.
REACH authorization requirements for novel enzyme active substances are extending development timelines by 18-24 months while elevating toxicology documentation standards. This regulatory friction is consolidating biological detoxifier development among established fermentation platforms with existing regulatory dossiers. Smaller compound feed manufacturers are responding by outsourcing detoxifier specification to premix suppliers with in-house regulatory affairs capabilities.
Integrated protein producers are consolidating additive procurement under long-term partnership frameworks that bundle mycotoxin risk assessment, detoxifier supply, and residue testing services. Traditional distributor channels in Spain and Italy are losing volume to direct manufacturer relationships with top-ten compounders. This channel compression is most visible in Denmark, where cooperative feed manufacturing structures enable collective negotiation of biological detoxifier supply agreements.
Europe Feed Mycotoxin Detoxifiers Market Segmentation
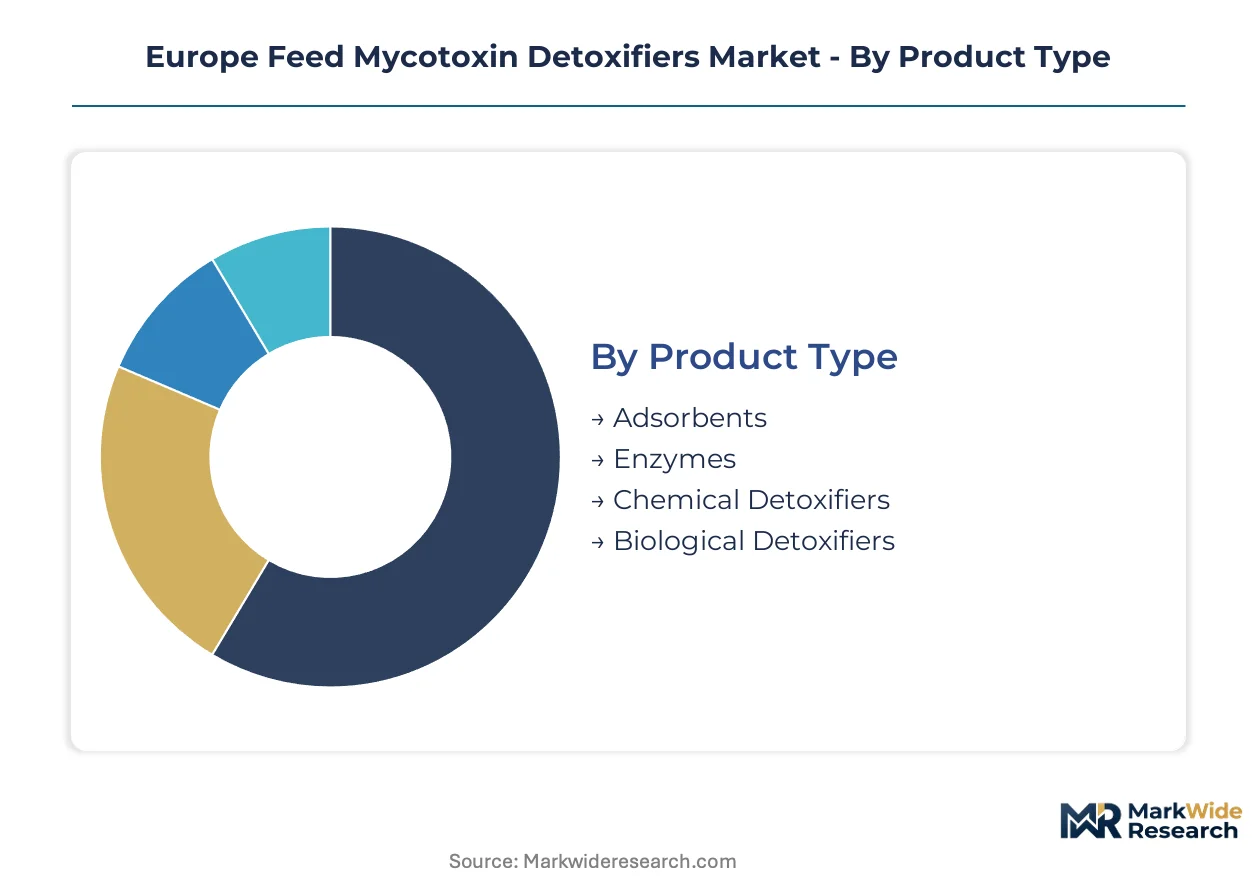
Segmentation in Europe's feed mycotoxin detoxifiers market reveals distinct capital requirements, regulatory exposure, and customer procurement behaviors across product chemistry, livestock application, and delivery format. Understanding these divisions exposes where formulation investment concentrates and which channels capture margin.
Product Type:
Capital intensity varies sharply across chemistries, with biological platforms demanding fermentation infrastructure while adsorbents leverage mineral processing assets.
- Adsorbents:Aluminum silicate clays and modified yeast cell walls constitute the incumbent volume base. Procurement concentrates among Dutch and Danish compound feed manufacturers seeking cost-certain broad-spectrum binding for aflatoxin and fumonisin management in poultry rations.
- Enzymes:Esterase and epoxidase formulations require dedicated bioreactor capacity and REACH dossier investment. German and French poultry integrators drive demand for Fusarium mycotoxin biotransformation where EFSA deoxynivalenol thresholds demand proven efficacy.
- Chemical Detoxifiers:Oxidative and reductive agents face margin compression under EU Green Deal residue scrutiny.
- Biological Detoxifiers:Microbial consortia with glucan-based modifiers attract ESG-mandated procurement from integrated protein producers.
Most installed capacity flows through Adsorbents. Expansion is steepest in Enzymes.
Application:
Species-specific metabolism and regulatory residue limits create divergent specification requirements across livestock categories.
- Poultry:High-density broiler and layer operations in Germany and France prioritize enzymatic detoxifiers for rapid growth-phase mycotoxin clearance. EFSA maximum levels for complete feeds mandate certified additive inclusion.
- Swine:Fumonisin sensitivity in piglets drives premium formulation adoption. Dutch integrators lead procurement of precision-delivery encapsulated products targeting gastrointestinal pH release.
- Ruminants:Deoxynivalenol degradation in rumen environments favors adsorbent cost economics, though biological alternatives gain traction in Denmark's cooperative dairy feed structures.
- Aquaculture:Emerging specification category with nascent EFSA guidance on marine feed mycotoxin limits.
Volume procurement concentrates in Poultry. Specification complexity climbs fastest in Swine.
Formulation:
Physical form determines blending equipment compatibility, shelf stability, and precision-delivery potential in automated feed mills.
- Powder:Dominant format for adsorbent inclusion in premix operations. Belgian and German compounders favor micronized grades for homogeneous distribution in high-volume ruminant feeds.
- Liquid:Enzymatic and biological actives concentrate here. Post-pelleting application systems in French poultry plants enable heat-sensitive additive retention.
- Granular:Intermediate flowability for mid-scale compounders with batch blending constraints.
- Pellet:Co-extruded formats for aquaculture and specialty swine feeds requiring water stability.
Processing throughput favors Powder. Technical differentiation accumulates in Liquid.
Distribution Channel:
Channel structure reflects customer scale, regulatory support needs, and inventory carrying cost tolerance across the value chain.
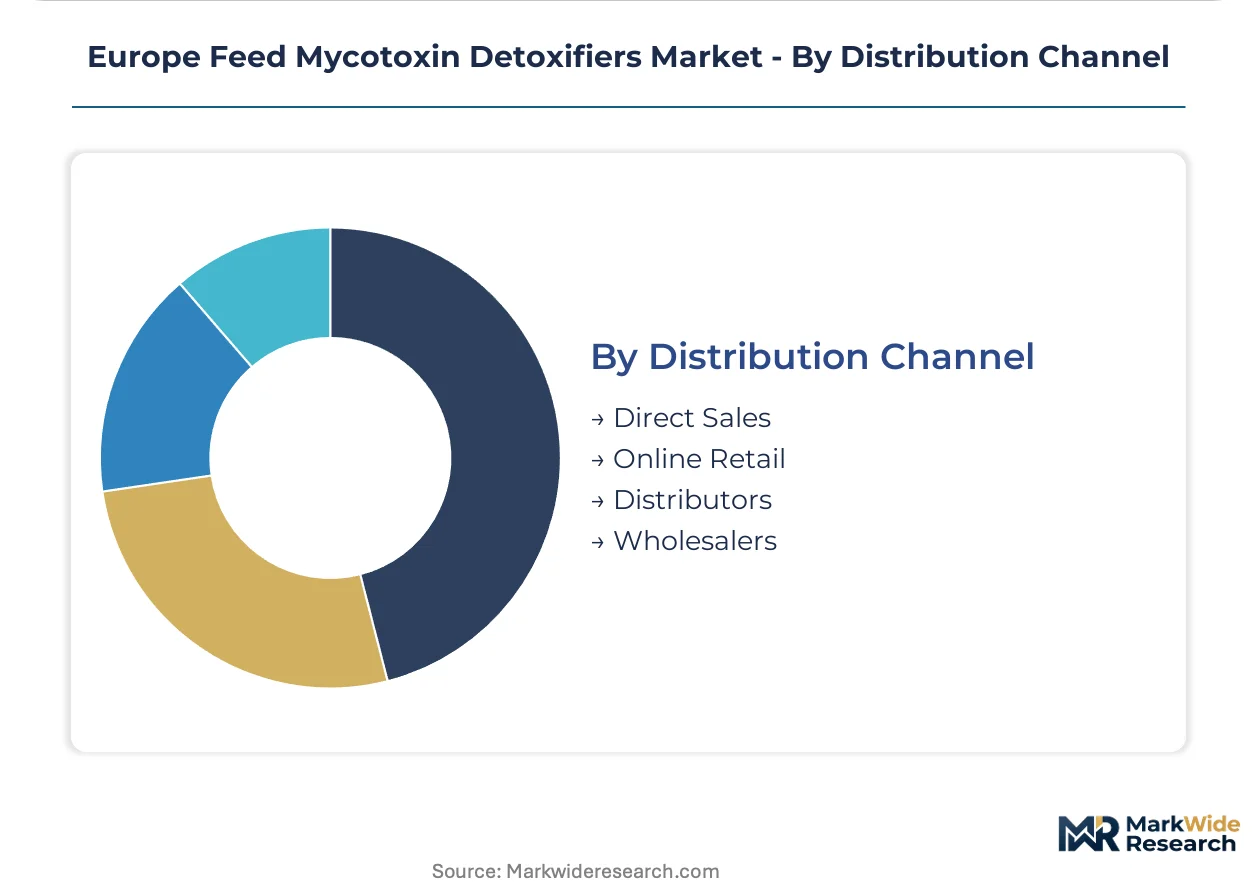
- Direct Sales:Top-ten compounders in Denmark and the Netherlands negotiate multi-year biological detoxifier supply agreements bundling risk assessment and residue testing. Manufacturer regulatory affairs capabilities substitute for distributor technical support.
- Distributors:Spanish and Italian mid-tier feed manufacturers rely on regional additive distributors for inventory pooling and formulation guidance.
- Online Retail:Limited penetration constrained by REACH documentation requirements and technical consultation needs.
- Wholesalers:Price-sensitive ruminant feed segments in Eastern Europe leverage commodity clay adsorbent volume purchasing.
Contract value concentrates in Direct Sales. Channel compression accelerates fastest in Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the Netherlands diverge in detoxifier procurement intensity despite both hosting dense livestock clusters, with Dutch compounders consolidating biological additive volumes while German integrators diversify across enzymatic platforms. This bifurcation shapes national specification patterns and channel structures across the region.
Germany
Poultry integrators in Lower Saxony and Bavaria drive esterase-based enzymatic detoxifier procurement for Fusarium mycotoxin biotransformation. REACH dossier requirements for novel biological actives extend development timelines for domestic fermentation platforms. The Rhine-Ruhr industrial corridor concentrates microbial detoxifier production capacity, creating input competition with pharmaceutical biologics manufacturers.
Netherlands
Cooperative feed manufacturing structures enable collective negotiation of biological detoxifier supply agreements bundling risk assessment and residue testing. EFSA maximum levels for deoxynivalenol in complete feeds mandate certified additive inclusion in quality assurance protocols. The Randstad region anchors volume procurement hubs that subsidize biological detoxifier penetration into mid-tier compounders.
France
High-density broiler and layer operations in Brittany and Pays de la Loire prioritize enzymatic detoxifiers for rapid growth-phase mycotoxin clearance. EU Green Deal Farm to Fork strategy redirects formulation investment toward microbial platforms with favorable toxicology profiles. Poultry integrators in the Grand Est region pilot modified yeast cell wall adsorbents at commercial scale.
Denmark
Dairy cooperative feed structures in Jutland drive biological detoxifier adoption for deoxynivalenol management in ruminant rations. CSRD-aligned sustainability reporting requirements attract ESG-mandated procurement from integrated protein producers. The Copenhagen-Aarhus corridor concentrates direct manufacturer relationships that bypass traditional distributor channels.
Poland
Expanding livestock markets in Greater Poland and Silesia offer first-mover positioning before EFSA-aligned national regulations fully harmonize. Commodity clay adsorbents maintain entrenched price positioning in price-sensitive ruminant feed segments. Warsaw-based compounders increasingly outsource detoxifier specification to premix suppliers with regulatory affairs capabilities.
Europe Feed Mycotoxin Detoxifiers Market Competitive Landscape
Top-tier vendors anchor premium enzymatic and biological platforms, while mid-scale specialists compete on regional formulation flexibility and distributor channel density. The vendor base stratifies across fermentation-integrated multinationals, mineral processing incumbents, and precision-delivery technology developers. Strategic archetypes include polymer science specialists, integrated fermentation platforms, and encapsulation technology innovators. Competitive moves concentrate on REACH dossier consolidation and long-term supply agreement bundling with residue testing services.
Among diversified chemical and nutrition conglomerates, DSM-Firmenich AG and BASF SE occupy positions representing polymer science and fermentation-integrated capabilities respectively. Cargill, Incorporated exemplifies the agricultural trading house archetype with downstream feed additive integration. Kemin Industries, Inc. and Alltech, Inc. sit within the specialty biotechnology tier, with Biomin Holding GmbH representing Austrian-anchored microbial platform development. These entities collectively illustrate the competitive tension between mineral-based incumbency and biological substitution trajectories.
| Leading Market Players |
|---|
| DSM-Firmenich AG |
| Cargill, Incorporated |
| BASF SE |
| Brenntag SE |
| Adisseo SAS |
| Alltech, Inc |
| Kemin Industries, Inc. |
| Biomin Holding GmbH |
| Impextraco N.V. |
| Others |
Supply & Pricing Matrix
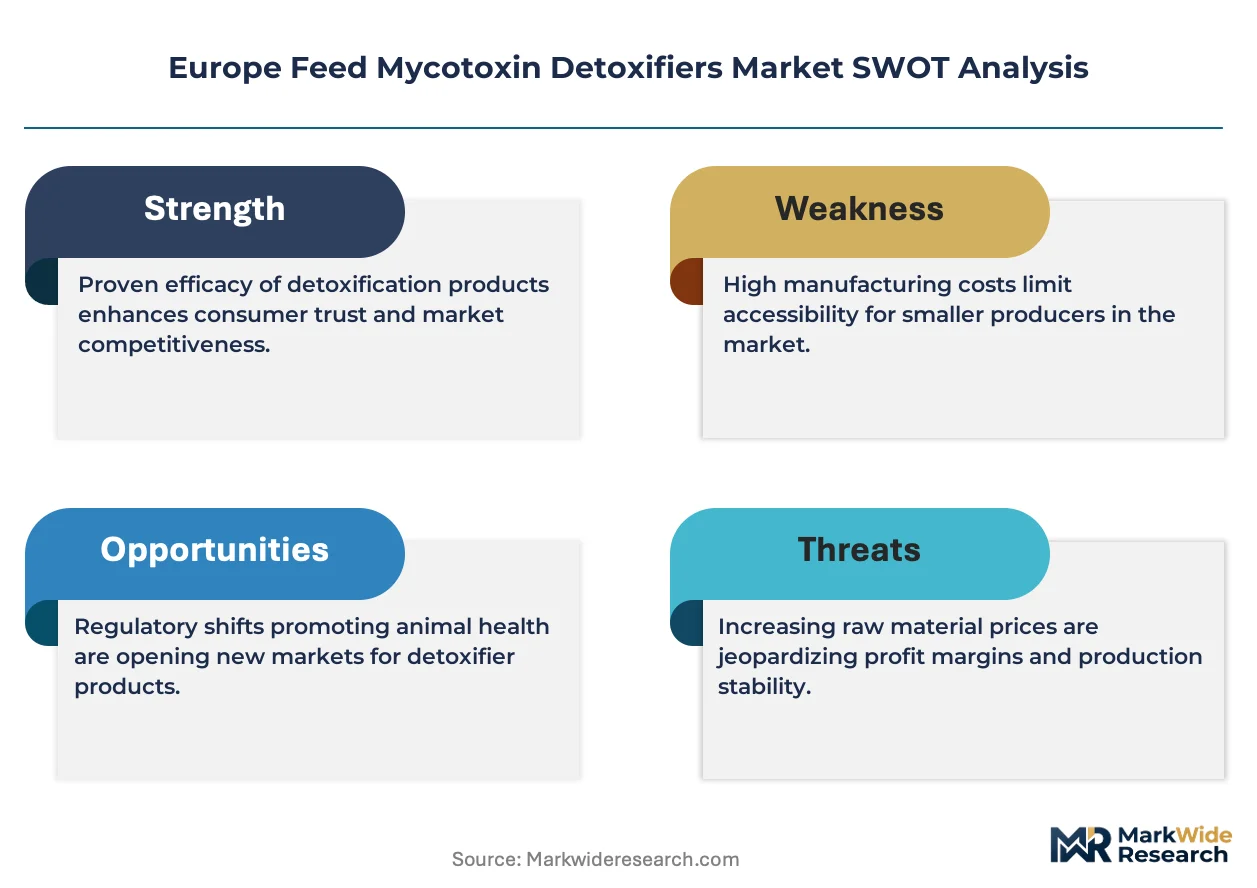
EFSA-aligned procurement mandates from Dutch and Danish cooperative feed manufacturers are forcing compounders to qualify biological detoxifier suppliers against REACH dossier standards, compressing vendor pools and elevating price floors for certified enzymatic platforms.
Pricing Analysis
Capacity additions in Belgium and Germany are reshaping price floors for microbial detoxifiers as fermentation platforms compete with pharmaceutical biologics for bioreactor access. Three-tier pricing structure across premium enzymatic, standard biological, and economy clay adsorbent levels reflects certification grade and volume scale differentiation. Cost compression in aluminum silicate tiers is intensifying because of mineral processing overcapacity in Eastern Europe. Ruminant feed compounders exhibit highest price sensitivity, while poultry integrators in France absorb premiums for proven deoxynivalenol biotransformation.
Supply Chain Analysis
REACH registration requirements for novel biological actives gate supplier qualification, extending lead times for compound feed manufacturers seeking alternative detoxifier sources. Production concentrates in Belgium, Germany, and the Netherlands, with fermentation capacity anchored in the Rhine-Ruhr corridor and mineral processing clustered in Bavaria. Supply chains draw from pharmaceutical-grade glucose substrates, modified yeast cell wall precursors, and aluminum silicate clay deposits. Single-source vulnerability persists in esterase enzyme supply from concentrated bioreactor networks. Distribution runs through premix suppliers with in-house regulatory affairs capabilities serving mid-tier compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EFSA threshold tightening for deoxynivalenol and zearalenone mandates certified detoxifier inclusion, converting compliance expenditure into structural demand for validated biological platforms.
For Market Incumbents: Deploy REACH dossier consolidation as a competitive moat. Deepen backward integration into pharmaceutical-grade fermentation substrates to secure bioreactor capacity against human biologics competition. Channel control through premix supplier partnerships defends margin position against commodity clay adsorbent erosion in Eastern European ruminant segments. For New Entrants and Emerging Players: Begin with Poland and Romania's underdeveloped mycotoxin management infrastructure before EFSA-aligned national regulations fully harmonize. Target swine precision-delivery formulations as the most penetrable segment, where Dutch integrators already pilot encapsulated products. A go-to-market angle bundling residue testing services with detoxifier supply bypasses distributor technical support gaps. For Investors and Strategic Acquirers: Asymmetric upside sits with precision-delivery encapsulation technology developers serving ruminant deoxynivalenol applications. Long-term viability hinges on CSRD-aligned sustainability reporting requirements deepening ESG-mandated procurement from integrated protein producers. The signal to watch is Commission Regulation (EC) No 1881/2006 revision timing, which could trigger formulation freeze periods or accelerate biological substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Substrates | Secures bioreactor capacity against pharmaceutical biologics competition in Belgium and Germany. |
| REACH Dossier Consolidation | Extends development timelines for rivals while cementing incumbent regulatory moats. |
| Precision-Delivery Encapsulation Development | Unlocks ruminant deoxynivalenol applications previously dominated by aluminum silicate adsorbents. |
| Long-Term Supply Agreement Bundling | Captures Dutch and Danish cooperative procurement through integrated risk assessment and residue testing. |
| ESG-Aligned Sustainability Certification | Attracts CSRD-mandated procurement from integrated protein producers in Denmark and France. |
Research Methodology
Multiple input streams — compound feed manufacturer procurement directors, fermentation platform technical leads, EFSA regulatory affairs specialists, and premix supplier account managers — were reconciled against customs data, FEFAC production statistics, REACH registration databases, and SEC filings from diversified chemical conglomerates. Bottom-up volume modeling triangulated with top-down expenditure analysis across the projection horizon.
Data-stream reconciliation applied analytical frameworks across product chemistry, livestock application, formulation format, and distribution channel segmentation. CAGRs were derived from elasticity-adjusted adoption curves for enzymatic versus adsorbent platforms, incorporating EFSA guidance revision probabilities and EU Green Deal Farm to Fork implementation timelines as scenario-weighted inputs.
Several conditions sit outside the modeled scope, including pending revisions to Commission Regulation (EC) No 1881/2006 and unforeseen REACH authorization delays for novel biological actives. Forecasts reflect assumptions about regulatory harmonization velocity and fermentation capacity expansion rates. A model refresh is warranted upon material change in EFSA maximum level thresholds or bioreactor input cost volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
South America Silage Additives Market
Agricultural Chemicals
Plant Growth Promoters Market
Agricultural Chemicals
Middle East Feed Enzymes Market
Agricultural Chemicals
China Castor Oil Market
Agricultural Chemicals
Asia-Pacific Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Agricultural Insect Pheromones Market
Agricultural Chemicals
Global Agricultural Disinfectant Market
Agricultural Chemicals
Feed Flavor Market
Agricultural Chemicals
North America Feed Antibiotics Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
South America Silage Inoculant Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
South America Feed Minerals Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Argentina Feed Additives Market
Agricultural Chemicals
Feed Antioxidants Market