
 China Herbicide Market | 2026-2036
China Herbicide Market Size, Share, and Industry Trends Forecast 2026-2036
China Herbicide Market Insights
China's dual carbon goals is repositioning herbicide demand toward lower-emission manufacturing and precision application technologies. Syngenta Group leverages its integrated crop protection platform to sustain leadership in premium formulation development. Jiangsu Yangnong Chemical Group anchors its position through captive production of key active ingredients in Yangzhou. Shandong Weifang Rainbow Chemical dominates export-oriented glyphosate manufacturing from its Weifang base.
Herbicides are chemical agents formulated to inhibit or destroy unwanted vegetation through interference with photosynthesis, amino acid synthesis, or cell division, typically containing active concentrations of glyphosate, atrazine, or 2,4-D derivatives applied at rates calibrated by crop type and weed pressure. Their primary purpose is to protect yield in row-crop agriculture, orchards, and managed turf systems by reducing competition for water, nutrients, and light. Selective herbicides lead the product type structure due to entrenched use in rice and wheat rotations, while non-selective formulations capture the fastest expansion as no-till farming spreads in the Northeast. Suspension concentrate formulations command margin premiums through superior stability and reduced drift compared with soluble powders.
MEE enforces emissions caps on active ingredient synthesis facilities under China's dual carbon framework, pushing producers toward catalytic oxidation and solvent recovery investments. GB standards administered by SAMR set maximum residue limits for domestic food crops, directly shaping product registration priorities and label restrictions. CDSCO-aligned provincial agricultural bureaus conduct batch testing of imported and domestically produced herbicides, creating compliance friction for non-integrated distributors. Stakeholders must monitor how tightening MEE carbon intensity benchmarks reshape manufacturing cost structures and whether provincial subsidy shifts favor precision application equipment over bulk chemical purchases.
Market Dynamics
China's dual carbon framework under MEE oversight is compressing manufacturing margins while redirecting capital toward catalytic oxidation and solvent recovery systems. This structural force is fragmenting the supplier base between integrated producers with compliance capital and exposed mid-tier compounders.
Growth Catalysts
- North China Plain crop expansion:Wheat and corn cultivation intensification is pulling glyphosate and atrazine volumes into Hebei and Henan provinces. No-till adoption in the Northeast is accelerating non-selective herbicide demand.
- MEE emissions benchmarking:Carbon intensity caps on active ingredient synthesis are advantaging producers with captive catalytic oxidation capacity. Early compliance investments are securing operating permits ahead of 2025-2030 tightening cycles.
- Precision application hardware:Drone-mounted variable-rate sprayers are penetrating Shandong rice operations. Equipment subsidies from provincial agricultural bureaus are lowering adoption thresholds for mid-scale cooperatives.
Market Restraints
- Glyphosate feedstock volatility:Phosphorus trichloride and glycine price swings compress formulation margins. Sichuan and Guizhou phosphate concentrate supply disruptions transmit directly to Yangzhou and Weifang production economics.
- GB residue limit stringency:SAMR-administered maximum residue limits for domestic wheat and rice are narrowing the registrable product pipeline. Label restrictions are extending development-to-market timelines.
- Bioherbicide efficacy gaps:Glufosinate and microbial alternatives face yield-protection shortfalls against perennial grasses. Corn and soybean growers in Jilin retain chemical dependency despite subsidy nudges.
Strategic Opportunities
- Xinjiang cotton belt mechanization:Large-format state farms are consolidating into 10,000-hectare blocks suited to satellite-guided broadcast application. Herbicide volume per hectare is compressing while premium formulation share expands.
- Suspension concentrate premiumization:Drift reduction and tank-mix compatibility are commanding 15-20% price lifts over soluble powders in Jiangsu orchard operations. Stability patents are becoming competitive moats.
- Provincial precision equipment subsidies:Agricultural machinery purchase incentives in Anhui and Hubei are redirecting chemical budgets toward integrated weed management systems with embedded sensing.
Industry Challenges
- Process chemist scarcity:Catalytic oxidation and continuous flow synthesis expertise concentrates in Yangzhou and Nanjing. Second-tier producers in Shandong face recruitment friction against pharmaceutical sector wage competition.
- CDSCO-aligned batch testing delays:Provincial agricultural bureau inspection queues for imported active ingredients are stretching lead times. Non-integrated distributors face working capital compression from inventory detention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Herbicide Market |
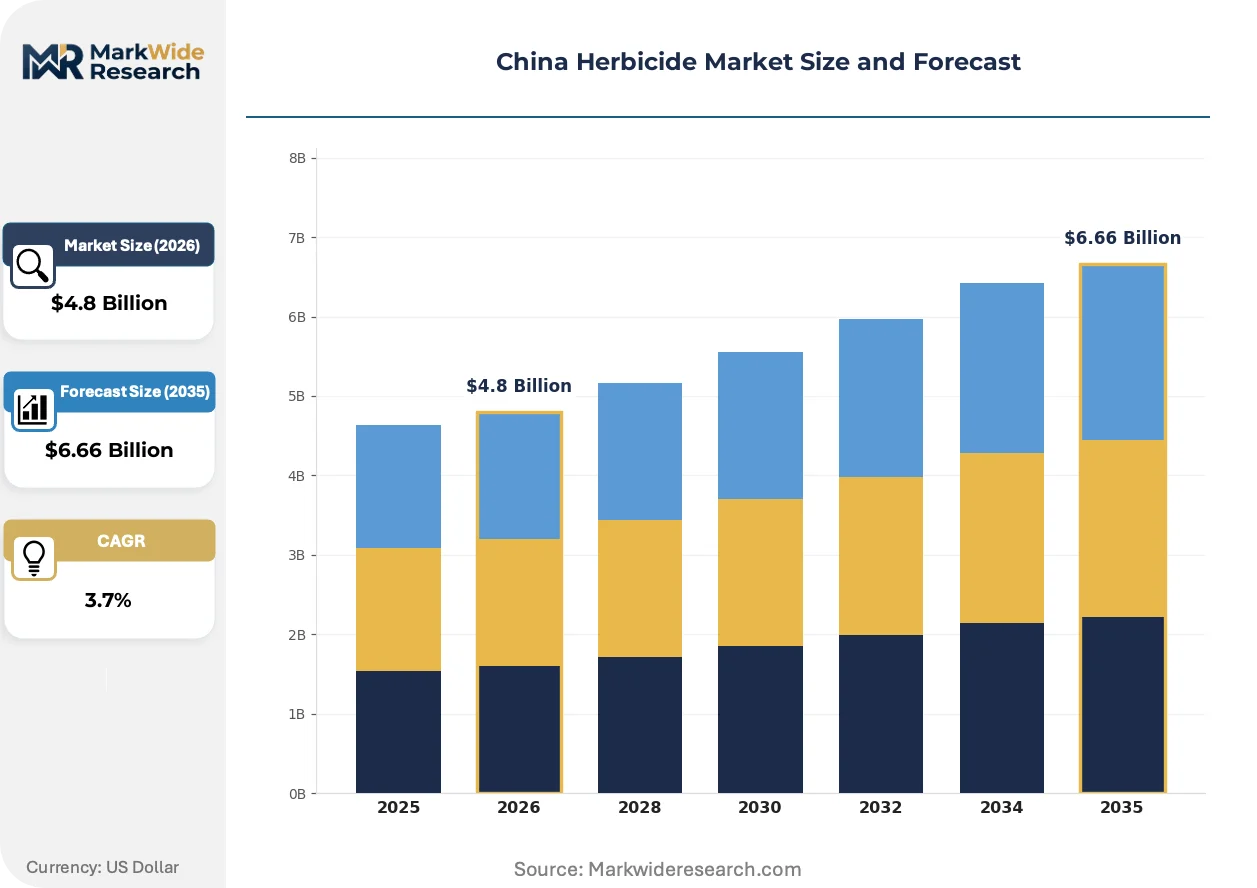
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Selective Herbicide, Non-Selective Herbicide, Pre-Emergent Herbicide, Post-Emergent Herbicide Application: Agricultural, Residential, Industrial, Lawn & Garden Formulation: Liquid, Granular, Soluble Powder, Suspension Concentrate Distribution Channel: Wholesale, Retail, Online, Direct Sales |
| Companies Covered | Syngenta Group, Bayer AG, BASF SE, FMC Corporation, Corteva Agriscience, ADAMA Agricultural Solutions, Jiangsu Yangnong Chemical Group, Shandong Weifang Rainbow Chemical Co., Ltd., Zhejiang Wynca Chemical Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Herbicide Market Trends and Innovations
Formulation chemistry and application hardware are converging around drift reduction and dose precision. Regulatory pressure on manufacturing emissions is accelerating process intensification investments.
Micro-encapsulation technology is extending herbicide release profiles for residual weed control in rice paddies. Large cooperatives in Jiangsu are adopting encapsulated atrazine formulations at 20-25% annual expansion rates. This controlled-release architecture is modularizing the traditional split-application model into single-pass systems.
MEE's dual carbon framework is tightening emissions caps on phosphorus trichloride synthesis facilities. Catalytic oxidation and solvent recovery investments are becoming permit prerequisites for active ingredient production. Shandong glyphosate manufacturers with integrated environmental systems are securing operating continuity ahead of 2025 benchmark tightening.
Cooperative procurement consolidation is displacing individual farmer purchases in the North China Plain. County-level agricultural service companies are aggregating herbicide demand and negotiating direct manufacturer contracts. This volume aggregation is most visible in Hebei wheat operations where 50-hectare minimum orders are becoming standard.
China Herbicide Market Segmentation
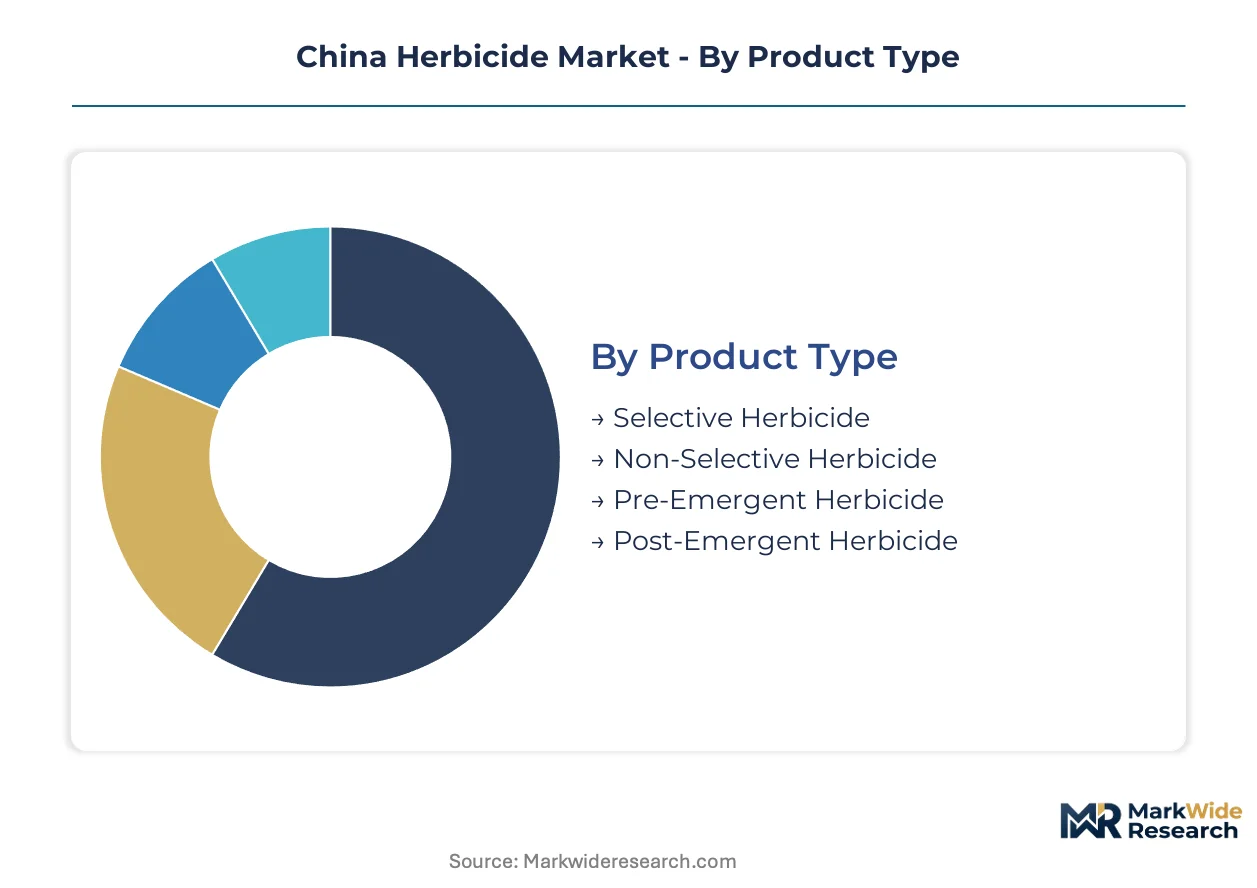
Herbicide segmentation in China reflects divergent manufacturing capabilities across the Yangtze and Yellow River basins. Supply concentration in Shandong and Jiangsu provinces shapes which formulations and product types achieve scale economies under tightening MEE emissions benchmarks.
Product Type:
Active ingredient synthesis capacity clusters around glyphosate and atrazine producers with integrated environmental systems.
- Selective Herbicide:Formulations containing 2,4-D derivatives and atrazine analogs that target broadleaf weeds without damaging monocot crops. Demand concentrates in Jiangsu rice-wheat rotation zones where MEE emissions caps favor producers with captive catalytic oxidation. Label restrictions under SAMR-administered GB standards are narrowing registrable chemistries.
- Non-Selective Herbicide:Glyphosate and glufosinate-based total vegetation control agents disrupting amino acid synthesis pathways. Hebei and Henan corn-soybean expansion in the North China Plain is pulling volumes from Weifang manufacturing bases. No-till adoption in Jilin is accelerating demand despite bioherbicide subsidy competition.
- Pre-Emergent Herbicide:Soil-applied residual inhibitors including acetanilide and dinitroaniline classes.
- Post-Emergent Herbicide:Foliar-contact formulations applied after crop emergence for targeted weed control.
Selective herbicides absorb the bulk of installed capacity; non-selective herbicides are expanding most quickly.
Application:
End-use demand splits between volume-driven row-crop agriculture and margin-rich specialized segments.
- Agricultural:Row-crop protection across wheat, corn, rice, and soybean cultivation spanning the North China Plain and Northeast. County-level agricultural service companies in Hebei are consolidating procurement into 50-hectare minimum orders. Cooperative aggregation is displacing individual farmer purchases.
- Residential:Consumer-format glyphosate for home garden and driveway weed control. Urban household penetration remains shallow outside tier-one cities due to price sensitivity and manual weeding persistence.
- Industrial:Rights-of-way and infrastructure maintenance applications including railway and power line corridors.
- Lawn & Garden:Turf management formulations for golf courses and municipal green spaces.
Agricultural applications command the dominant volume share; lawn and garden represents the steepest expansion trajectory.
Formulation:
Physical form determines manufacturing capital intensity and drift compliance margins.
- Suspension Concentrate:Aqueous dispersions of solid active ingredients with superior stability and reduced drift profiles. Jiangsu orchard operations are paying 15-20% premiums over soluble powders. Stability patents are becoming competitive moats against generic competition.
- Liquid:Emulsifiable concentrates and ready-to-use solutions dominating broadcast application in mechanized operations.
- Granular:Slow-release carrier formulations for pre-emergent soil incorporation.
- Soluble Powder:Dry formulations requiring tank-mixing; losing share to suspension concentrates in premium segments.
Liquid formulations retain the largest production footprint; suspension concentrates are gaining share fastest.
Distribution Channel:
Channel structure is restructuring around cooperative procurement and direct manufacturer relationships.
- Wholesale:Bulk supply to county-level agricultural service companies and provincial distributors. Shandong production clusters ship predominantly through this channel to Hebei and Henan demand centers.
- Retail:Township-level agrochemical stores serving individual farmers. Working capital pressure from CDSCO-aligned batch testing delays is compressing inventory turns.
- Online:E-commerce platforms penetrating rural markets with drone-mounted sprayer bundles.
- Direct Sales:Manufacturer-to-cooperative contracts bypassing distributor margins. Volume aggregation is most advanced in Anhui and Hubei where machinery subsidies redirect chemical budgets.
Wholesale channels handle the majority of volume throughput; direct sales are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Weifang anchors China's herbicide production capacity through its Shandong Peninsula agrochemical cluster, where glyphosate synthesis facilities operate under tightening MEE emissions benchmarks. Provincial agricultural service companies in Hebei and Henan are consolidating procurement volumes as wheat and corn cultivation intensifies across the North China Plain.
Shandong Province
Glyphosate manufacturing concentrates in Weifang's chemical industrial park, where producers with integrated catalytic oxidation systems secure operating permits ahead of MEE's 2025 tightening cycle. SAMR-administered GB residue limits shape product registration priorities for export-oriented formulations. County-level agricultural service companies in Hebei source bulk atrazine and 2,4-D derivatives through Shandong's wholesale channels.
Jiangsu Province
Rice-wheat rotation zones in Yangzhou and Nanjing pull selective herbicide volumes, with suspension concentrate formulations commanding 15-20% price premiums over soluble powders. MEE emissions caps favor producers with captive solvent recovery capacity. Yangzhou's chemical industrial corridor hosts active ingredient synthesis facilities serving domestic orchard and row-crop segments.
Hebei Province
Wheat and corn expansion across the North China Plain is aggregating herbicide demand into 50-hectare minimum orders through cooperative procurement structures. Provincial agricultural machinery subsidies redirect chemical budgets toward precision application equipment. CDSCO-aligned batch testing by provincial agricultural bureaus creates compliance friction for non-integrated distributors.
Henan Province
Corn-soybean intensification accelerates non-selective herbicide demand as no-till farming spreads from neighboring provinces. County-level service companies negotiate direct manufacturer contracts, bypassing traditional retail channels. Zhengzhou logistics hubs coordinate bulk shipments from Shandong production bases to interior demand centers.
Xinjiang Uygur Autonomous Region
Mechanized cotton production on 10,000-hectare state farms compresses herbicide volume per hectare while expanding premium formulation share. Satellite-guided broadcast application systems reduce drift and enable variable-rate spraying. Provincial consolidation of land management creates concentrated demand for bulk glyphosate and glufosinate formulations.
China Herbicide Market Competitive Landscape
The competitive structure tilts toward integrated producers with captive environmental compliance systems. MEE emissions benchmarking fragments the supplier base between capital-rich manufacturers and exposed mid-tier compounders. Three archetypes dominate: multinational crop protection platforms with formulation R&D depth, domestic chemical groups with backward-integrated active ingredient capacity, and export-focused manufacturers serving Southeast Asian and Latin American markets. Competitive moves concentrate on catalytic oxidation capacity expansion and direct procurement relationships with county-level agricultural service companies.
Among integrated multinational platforms, Syngenta Group and Bayer AG occupy positions defined by premium formulation development and crop protection portfolio breadth. Domestic chemical groups include Jiangsu Yangnong Chemical Group and Shandong Weifang Rainbow Chemical Co., Ltd., which exemplify the archetype of regionally anchored producers with captive synthesis capacity. These companies sit within the compliance-advantaged tier as MEE carbon intensity benchmarks reshape manufacturing cost structures.
| Leading Market Players |
|---|
| Syngenta Group |
| Bayer AG |
| BASF SE |
| FMC Corporation |
| Corteva Agriscience |
| ADAMA Agricultural Solutions |
| Jiangsu Yangnong Chemical Group |
| Shandong Weifang Rainbow Chemical Co., Ltd. |
| Zhejiang Wynca Chemical Group |
| Others |
Pricing and Supply Chain Analysis
Phosphorus trichloride and glycine price indices cascade through China's herbicide supply chain, compressing formulation margins at Shandong production bases while amplifying price premiums for suspension concentrate formulations with drift-reduction patents. MEE emissions caps on active ingredient synthesis feed into a three-tier pricing structure across premium, standard, and economy levels, where catalytic oxidation compliance separates compliant producers from exposed compounders.
Pricing Analysis
Yield-protection value anchors pricing for suspension concentrate formulations, with Jiangsu orchard operations paying 15-20% premiums over soluble powders for tank-mix compatibility and stability. Price differentiation hinges on drift-reduction certification and captive catalytic oxidation capacity, with integrated producers capturing margin while mid-tier compounders face cost compression from phosphorus feedstock volatility. Price erosion runs through generic soluble powder tiers as cooperative procurement consolidation in Hebei and Henan squeezes distributor markups. County-level agricultural service companies exhibit highest price sensitivity on bulk glyphosate orders, while Xinjiang state farms show lowest sensitivity for precision-formulation bundles with satellite-guided application.
Supply Chain Analysis
Empty container return flows and solvent recovery systems form reverse logistics loops at Yangzhou chemical industrial corridor facilities, where catalytic oxidation byproducts feed back into synthesis processes. Supply concentrates in Shandong and Jiangsu provinces, with Weifang glyphosate synthesis and Yangzhou selective herbicide production anchoring domestic capacity. Raw material flows draw from Sichuan and Guizhou phosphate concentrate, with phosphorus trichloride and glycine dependencies creating single-source vulnerability during provincial supply disruptions. Distribution runs through wholesale channels to county-level agricultural service companies, bypassing traditional retail as direct manufacturer contracts proliferate in Anhui and Hubei.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's herbicide market operates as a cost-of-compliance story where MEE dual carbon emissions caps erect barrier-to-entry moats favoring producers with captive catalytic oxidation and solvent recovery investments.
For Market Incumbents: Hedge against phosphorus feedstock volatility through backward integration into Sichuan phosphate concentrate supply or long-term offtake agreements with Guizhou mining operations. Secure operating permit continuity by accelerating catalytic oxidation capacity expansion ahead of MEE benchmark tightening cycles, while defending formulation margins via stability patents in suspension concentrate segments against generic drift. For New Entrants and Emerging Players: MEE dual carbon goals in China open a window for bio-based formulation specialists with precision application hardware integration. Target Xinjiang cotton belt mechanization as the most penetrable geography, where 10,000-hectare state farms consolidate demand for satellite-guided broadcast systems. Pursue provincial machinery subsidy alignment in Anhui and Hubei as the primary go-to-market angle, bundling drone-mounted variable-rate sprayers with residual herbicide formulations. For Investors and Strategic Acquirers: The window for entry favors integrated producers with captive environmental compliance systems and direct cooperative procurement relationships. Long-term viability centers on manufacturing assets with catalytic oxidation permits secured under tightening MEE frameworks. Monitor provincial agricultural machinery subsidy shifts from bulk chemical purchases toward precision application equipment as the inflection indicator for formulation demand composition.| Strategic Initiative | Industry Significance |
|---|---|
| Catalytic Oxidation Capacity Expansion | MEE emissions compliance secures operating permits for active ingredient synthesis in Shandong and Jiangsu. |
| Backward Integration into Phosphate Supply | Sichuan and Guizhou concentrate sourcing hedges glyphosate feedstock volatility for Weifang manufacturers. |
| Suspension Concentrate Patent Development | Stability patents create 15-20% pricing premiums in Jiangsu orchard and premium row-crop segments. |
| Direct Cooperative Procurement Contracts | County-level agricultural service company relationships bypass distributor margins in Hebei and Henan. |
| Precision Application Equipment Bundling | Drone-mounted sprayer integration captures provincial machinery subsidies in Anhui and Hubei. |
Research Methodology
Independent corroboration across plant managers at Shandong and Jiangsu synthesis facilities, procurement leads at county-level agricultural service companies, and distribution channel partners in Hebei and Henan underwrites the qualitative findings in this study. Primary interviews with technical R&D directors at integrated manufacturers combined with secondary validation from customs and trade data, MEE emissions disclosure filings, and SAMR product registration databases establish demand and supply parameters. Bottom-up volume aggregation across provincial agricultural bureaus and top-down macroeconomic alignment complete the triangulation.
Rate-of-change decomposition separates volume drivers from price dynamics across the analysis window. Segmentation dimensions include product type, application, formulation, and distribution channel, with provincial regulatory cluster and cooperative procurement penetration as industry-specific modeling layers. CAGRs derive from fitted growth curves against historical shipment data and forward-looking MEE compliance cost assumptions. Key inputs encompass phosphorus trichloride price trajectories and precision application equipment subsidy allocation patterns.
The model assumes a particular technology adoption path for catalytic oxidation and continuous flow synthesis; alternative pathways for bioherbicide microbial alternatives would alter the outlook if yield-protection gaps narrow against perennial grasses. Forecasts reflect assumptions about MEE emissions benchmark enforcement consistency and provincial machinery subsidy continuity. Practitioners should monitor CDSCO-aligned batch testing queue lengths and phosphorus concentrate supply disruptions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Bird Repellent Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Europe Feed Antioxidants Market
Agricultural Chemicals
Humic and Fulvic Acid Based Biostimulants Market
Agricultural Chemicals
Berry Greenhouse Premium Micronutrient Package Market
Agricultural Chemicals
Soil Treatment Market
Agricultural Chemicals
Asia-Pacific Swine Feed Premix Market
Agricultural Chemicals
North America Feed Enzymes Market
Agricultural Chemicals
Foliar Spray Market
Agricultural Chemicals
Agricultural Coatings Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Middle East Feed Binders Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
Glyphosate Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market