
 Europe Feed Enzymes Market | 2026-2036
Europe Feed Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Enzymes Market Foresight
Specialized compound feed producers are reorganizing procurement priorities around phytase-enhanced formulations as livestock operators face mounting pressure to reduce phosphorus excretion. BASF SE leverages its integrated biotechnology platform to supply high-activity phytase concentrates across northwestern European feed mills. DSM Nutritional Products AG sustains competitive distance through its precision-fermentation capabilities and veterinary nutrition partnerships. Novonesis Group anchors its position in microbial enzyme innovation, competing on thermostability profiles that survive pelleting temperatures above eighty-five degrees Celsius.
Feed enzymes comprise biocatalytic proteins—primarily carbohydrases, proteases, and phytases—produced through submerged fermentation of fungal or bacterial strains, then concentrated via spray-drying or liquid formulation for incorporation at one hundred to five hundred grams per metric ton of feed. These additives degrade anti-nutritional factors, liberate bound minerals, and improve apparent metabolizable energy in monogastric diets. Phytase dominates value contribution due to its direct substitution for inorganic phosphate supplements, while protease gains fastest traction in young animal diets where endogenous enzyme secretion remains underdeveloped. Powder formulations occupy the largest volume share among delivery formats, though liquid enzymes penetrate aquafeed and on-farm mixing systems where uniform distribution challenges persist.
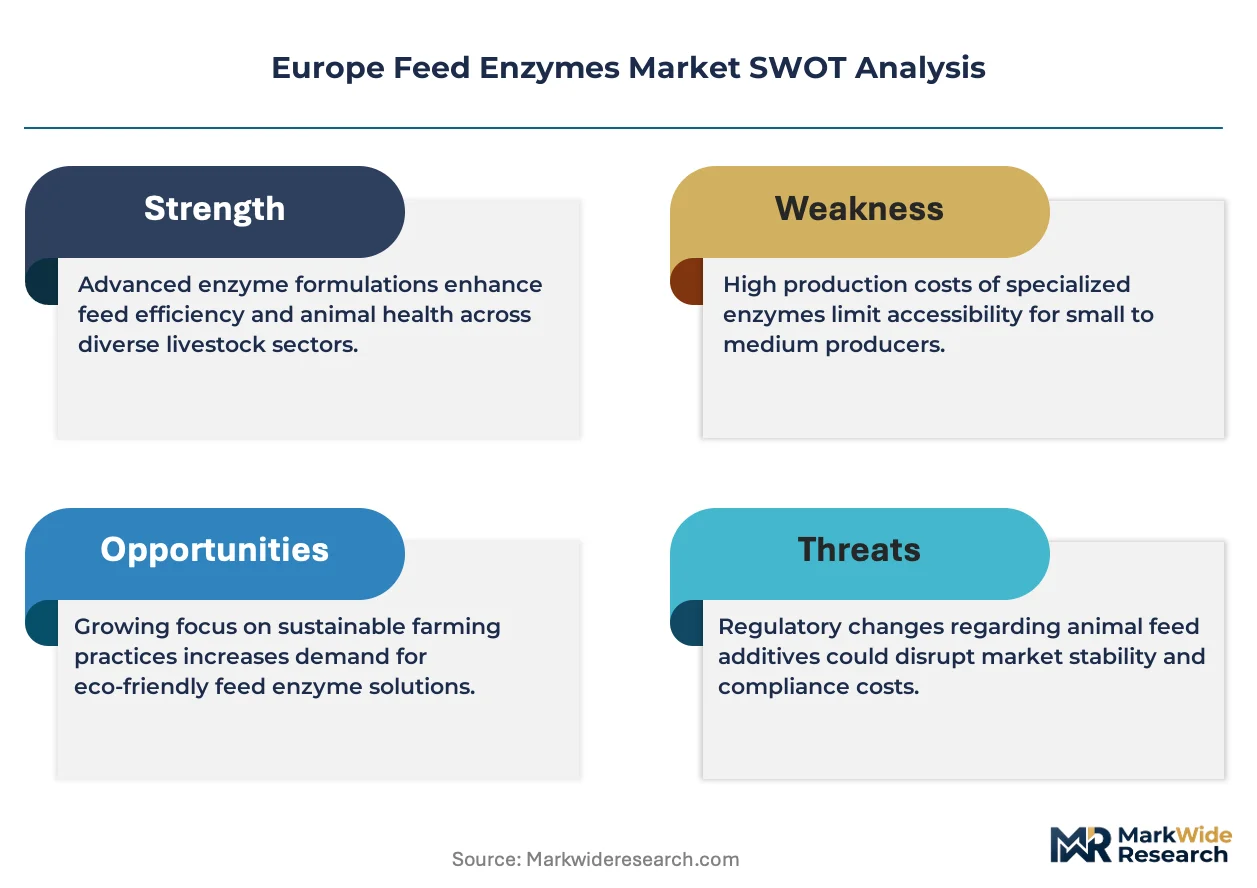
EMA guidelines on feed additive efficacy substantiation, REACH compliance for enzyme production strains, and the EU Green Deal nitrogen emission targets collectively reshape product registration pathways and on-farm application rates. The F-Gas Regulation indirectly pressures manufacturers toward energy-efficient fermentation technologies, tightening capital requirements for new production capacity. Stakeholders must monitor pending revisions to the EU Feed Additives Regulation and assess whether national derogations for environmental claims will create segmented approval timelines across member states.
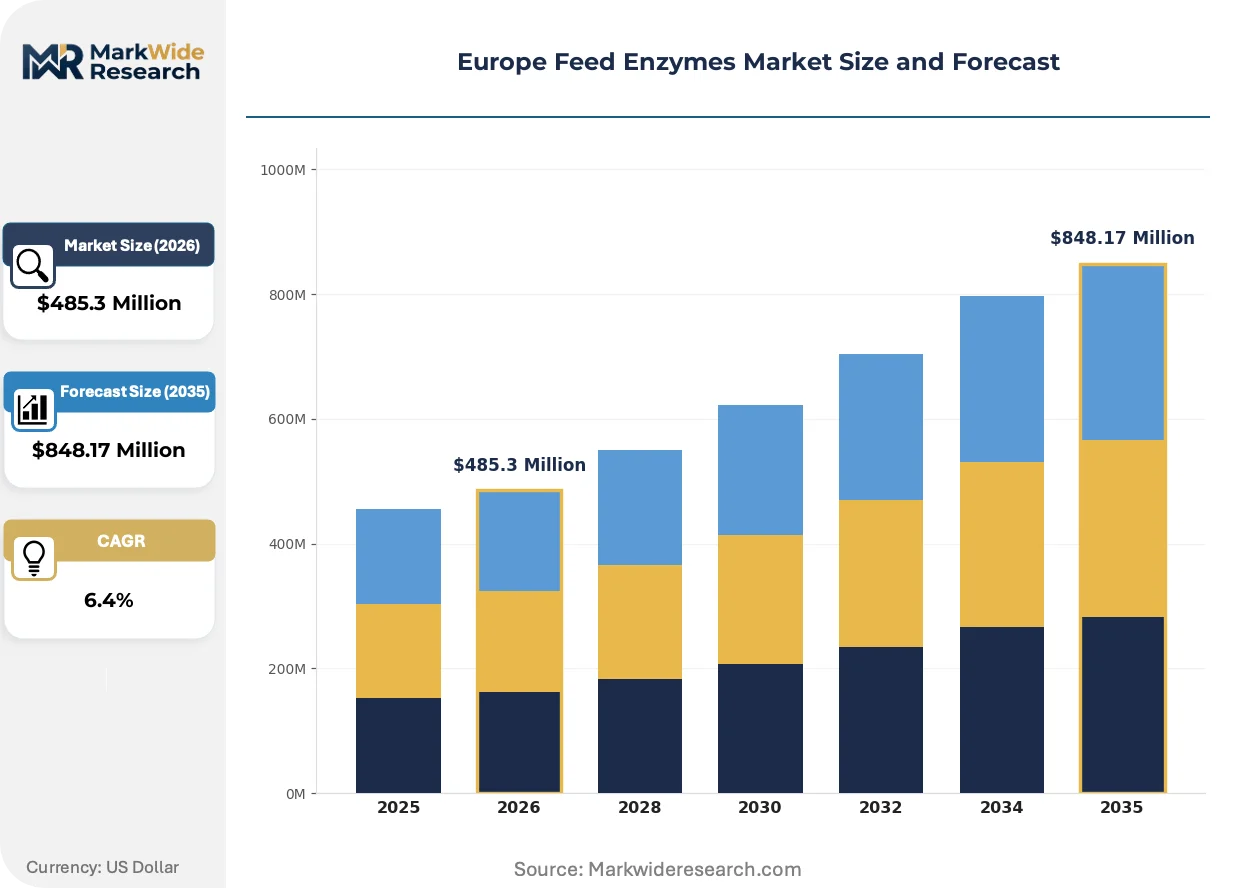
Market Dynamics
EU Green Deal nitrogen emission ceilings are forcing livestock operators to reformulate compound feed around enzyme-supplemented diets that reduce nutrient excretion without compromising growth performance.
Growth Catalysts
- EU Green Deal mandates:Member states must cut agricultural ammonia emissions by 2030, pushing swine and poultry integrators toward phytase-enhanced feed that lowers phosphorus runoff.
- Carbohydrase innovation:New thermostable xylanase and β-glucanase variants survive pelleting above 85°C, unlocking energy release in wheat and barley-based diets across northwestern European mills.
- Netherlands livestock density:Concentrated animal feeding operations in Gelderland and Noord-Brabant face strict manure disposal limits, creating concentrated demand for protease-supplemented starter feeds that improve protein digestibility.
Market Restraints
- REACH strain registration costs:ECHA compliance for novel production organisms demands multi-year toxicological dossiers that freeze smaller fermentation houses out of enzyme innovation pipelines.
- F-Gas fermentation energy intensity:The regulation pressures manufacturers toward heat-recovery systems and renewable-powered bioreactors, raising capital intensity for new production capacity in Denmark and Germany.
- Inorganic phosphate price volatility:Fluctuating diammonium phosphate costs from Moroccan and Russian suppliers create intermittent substitution economics that disrupt phytase adoption cycles.
Strategic Opportunities
- Poland aquafeed expansion:Carp and trout production in Pomerania and Warmia-Masuria remains underpenetrated by liquid enzyme formulations suited to extruded feeds.
- CSRD supply chain disclosure:Corporate sustainability reporting mandates create procurement preference for enzyme suppliers with verified lifecycle carbon footprints, favoring regional fermentation over imports.
- Precision-fermentation convergence:Integration of AI-driven strain optimization with continuous bioprocessing promises 40% yield improvements and novel enzyme activities beyond current fungal platforms.
Industry Challenges
- EMA efficacy substantiation timelines:Feed additive authorization dossiers require multi-site trial data that stretches 18-24 months from submission to marketing authorization.
- Spray-drying energy costs:Powder formulation dominance ties margins to natural gas prices, complicating capacity planning across Iberian and Italian production sites.
- Liquid enzyme distribution cold-chain gaps:On-farm mixing systems in eastern European markets lack temperature-controlled logistics, limiting penetration of high-activity liquid concentrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Enzymes Market |
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $848.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phytase, Protease, Amylase, Cellulase End User: Poultry, Swine, Ruminants, Aquaculture Form: Powder, Liquid, Granule, Pelleted Application: Animal Feed, Pet Food, Aquafeed, Nutritional Supplements |
| Companies Covered | BASF SE, DSM Nutritional Products AG, Adisseo, Cargill Inc, IFF (Danisco Animal Nutrition), Novonesis Group, Alltech Inc, Archer Daniels Midland Company, Kemin Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Enzymes Market Shifts & Advancements
Biocatalytic feed additives are undergoing rapid specification changes as thermostability demands rise and regulatory substantiation tightens, reshaping both production technology and procurement criteria across European livestock sectors.
Next-generation phytase variants with enhanced pH profiling and protease resistance are fragmenting the traditional single-enzyme application model. Poultry integrators in France and Germany now specify enzyme cocktails rather than standalone phytase, compressing margins on commodity concentrates while rewarding suppliers with multi-activity platforms. This fragmentation is accelerating consolidation among mid-tier fermentation houses unable to sustain parallel strain development pipelines.
F-Gas Regulation implementation is redirecting capital toward energy-efficient bioprocess design. Manufacturers must demonstrate heat integration and renewable power sourcing to maintain social license in jurisdictions with aggressive decarbonization timelines. Anaerobic digestion-linked facilities in Denmark and the Netherlands gain operational cost advantages while meeting CSRD disclosure requirements for Scope 2 emissions.
Compound feed procurement is consolidating around long-term enzyme supply agreements with embedded sustainability metrics. Major poultry cooperatives in Spain and Italy now contract directly with fermentation specialists, bypassing traditional distributor networks that lack carbon accounting capabilities. This channel compression is most advanced in markets where retailer-driven animal welfare standards create audit complexity that integrated suppliers can absorb more efficiently than fragmented distributors.
Europe Feed Enzymes Market Segmentation
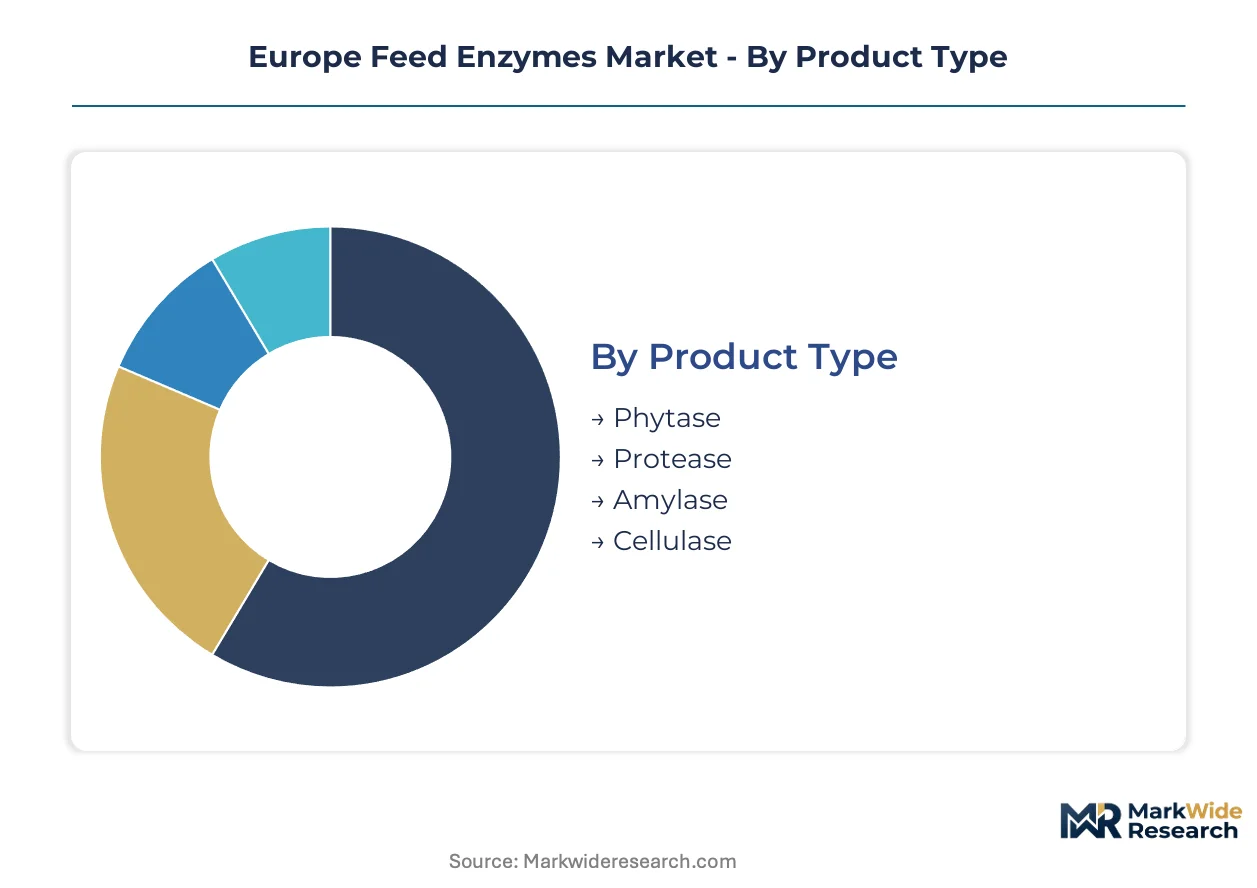
Enzyme procurement patterns across European livestock sectors diverge sharply by product chemistry, target species, and delivery format. Compound feed mills prioritize segments that withstand pelleting stress while satisfying EFSA efficacy requirements and EU Green Deal nitrogen targets.
Product Type:
Phytase concentrates face the most acute substitution pressure from next-generation variants with enhanced thermostability and pH profiling, while carbohydrase blends compete against precision-fermented alternatives.
- Phytase:Fungal-derived 3-phytase and bacterial 6-phytase variants hydrolyze phytic acid to liberate bound phosphorus. Dutch and German poultry integrators specify high-activity concentrates to eliminate inorganic phosphate supplements and comply with manure disposal limits in Gelderland and Lower Saxony.
- Protease:Serine and acid proteases from Bacillus and Aspergillus strains degrade storage proteins and lectins. French swine starter feed producers in Brittany source thermostable protease to improve amino acid digestibility in soybean-meal-based diets for weaner pigs.
- Amylase:α-amylase and glucoamylase enzymes target starch gelatinization in wheat-barley diets common across northwestern European mills.
- Cellulase:β-glucanase and cellulase complexes address non-starch polysaccharides in barley-heavy rations favored in Scandinavian compound feeds.
Phytase anchors the volume base while protease gains share at the steepest rate.
End User:
Customer procurement sophistication varies by species-specific regulatory scrutiny and environmental compliance intensity.
- Poultry:Broiler and layer operations in Spain's Catalonia and Italy's Veneto regions specify multi-enzyme cocktails for energy matrix reformulation. EFSA authorization dossiers for poultry-specific claims require multi-site trial data that favors suppliers with integrated research capabilities.
- Swine:Danish and Dutch finishers face the strictest ammonia emission ceilings under EU Green Deal implementation, driving phytase-enhanced feed adoption to reduce phosphorus excretion and manure disposal costs.
- Ruminants:Dairy and beef operations in Ireland and Poland apply fibrolytic enzymes to silage and concentrate mixes, though rumen microbial competition limits efficacy substantiation.
- Aquaculture:Norwegian salmon and Polish carp producers represent distinct demand profiles, with cold-water species requiring liquid formulation stability and warm-water species tolerating powder delivery.
Poultry commands the procurement volume while aquaculture expands most quickly as Mediterranean and Baltic producers scale extruded feed capacity.
Form:
Manufacturing capital allocation tilts toward formats that minimize distribution friction and on-farm handling complexity.
- Powder:Spray-dried concentrates dominate volume through compatibility with standard feed mill mixing lines. Natural gas price volatility in Italian and Iberian production sites compresses margins on this energy-intensive format.
- Liquid:High-activity concentrates suit aquafeed extrusion and on-farm mixing where uniform distribution challenges persist. Cold-chain gaps in eastern European markets constrain penetration despite superior thermostability profiles.
- Granule:Fluid-bed granulation improves flowability and dust control for automated dosing systems in large-scale German and French mills.
- Pelleted:Post-pelleting liquid application or thermostable dry formulations address enzyme denaturation risks in high-temperature conditioning processes.
Powder retains the installed base while liquid climbs the fastest as Norwegian and Spanish aquafeed investments accelerate.
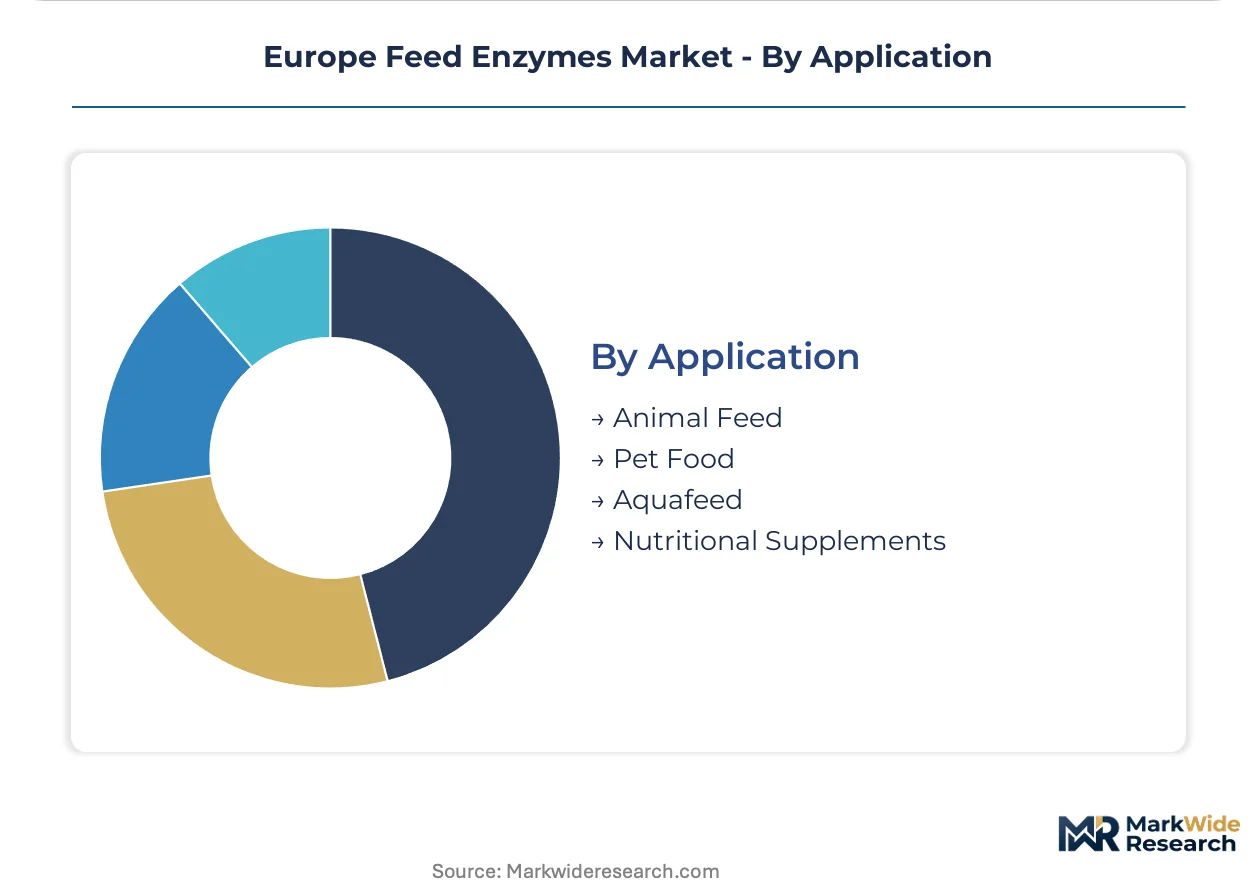
Application:
Regulatory pathway complexity and sustainability disclosure requirements reshape segment prioritization for enzyme suppliers.
- Animal Feed:Compound feed production for monogastrics represents the core demand pool, with CSRD supply chain disclosure mandates favoring regional fermentation over imports.
- Pet Food:Premium kibble and wet food formulations in France and Germany incorporate protease for palatability and digestibility claims.
- Aquafeed:Extruded salmon, trout, and carp feeds require thermostable carbohydrase and phytase that survive high-shear processing conditions.
- Nutritional Supplements:Direct-fed microbial and enzyme blends for young animal gut health occupy a niche positioned between feed additive and veterinary product classifications.
Animal feed absorbs the bulk of manufacturing capacity while aquafeed demonstrates the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's liquid bulk terminals and Rhine-Ruhr rail corridors distribute fermentation-derived enzyme concentrates to compound feed mills across northwestern Europe. This infrastructure underwrites the region's dominance in phytase and carbohydrase procurement.
Germany
Lower Saxony's intensive swine operations face the strictest ammonia ceilings under the EU Green Deal's national implementation plan. ECHA REACH compliance costs for novel production strains filter out smaller fermentation houses. BASF SE's Ludwigshafen biotechnology complex supplies high-activity phytase concentrates to poultry integrators in the Münsterland region.
Netherlands
Gelderland and Noord-Brabant livestock density triggers manure disposal limits that accelerate protease adoption in starter feeds. The F-Gas Regulation pressures manufacturers toward anaerobic digestion-linked facilities. DSM Nutritional Products AG's Delft precision-fermentation capabilities serve the Randstad's concentrated feed milling corridor.
France
Brittany's swine starter feed producers specify thermostable protease to improve amino acid digestibility in soybean-meal-based weaner diets. EFSA authorization dossiers require multi-site trial data that favors integrated research capabilities. Cargill Inc's compound feed operations in the Grand Est region anchor carbohydrase demand for wheat-barley formulations.
Spain
Catalonia and Italy's Veneto poultry cooperatives specify multi-enzyme cocktails for energy matrix reformulation. CSRD supply chain disclosure mandates create procurement preference for regional fermentation over imports. Adisseo's Barcelona-area distribution network contracts directly with retailer-driven animal welfare audit systems.
Poland
Pomerania and Warmia-Masuria carp and trout production remains underpenetrated by liquid enzyme formulations suited to extruded feeds. Cold-chain gaps in eastern European markets constrain high-activity concentrate penetration. Novonesis Group's microbial enzyme platforms target the Baltic aquafeed expansion trajectory.
Europe Feed Enzymes Market Competitive Landscape
Concentration sits with diversified biotechnology conglomerates and precision-fermentation specialists that control strain development pipelines and EMA efficacy substantiation capabilities. The vendor base spans three tiers: integrated chemical-biotech majors with captive fermentation capacity, mid-scale enzyme houses competing on thermostability specifications, and regional distributors losing ground to direct procurement contracts. Strategic moves center on backward integration into production strain IP and sustainability-linked long-term supply agreements with CSRD-reporting livestock cooperatives.
Among the integrated biotechnology majors, BASF SE and DSM Nutritional Products AG exemplify the archetype of chemical conglomerates leveraging fermentation infrastructure for feed additive diversification. Novonesis Group occupies a specialist position in microbial enzyme innovation, representing the precision-fermentation tier that competes on thermostability profiles rather than commodity scale. These three anchors demonstrate how regulatory substantiation capabilities and ESG disclosure readiness now determine competitive access more than manufacturing volume alone.
| Leading Market Players |
|---|
| BASF SE |
| DSM Nutritional Products AG |
| Adisseo |
| Cargill Inc |
| IFF (Danisco Animal Nutrition) |
| Novonesis Group |
| Alltech Inc |
| Archer Daniels Midland Company |
| Kemin Industries |
| Others |
Supply & Pricing Matrix
Phytase substitution for inorganic phosphate supplements simultaneously redraws procurement geography toward northwestern European fermentation clusters and compresses margin structures for commodity-grade enzyme concentrates. This input replacement dynamic intensifies price competition among suppliers serving Dutch and German poultry integrators while rewarding producers with captive strain development capabilities.
Pricing Analysis
Volume-discount tiering structures separate long-term contract holders from spot-market purchasers across the European feed enzyme trade. Pricing stratifies across premium thermostable formulations, standard activity concentrates, and economy-grade commodity phytase based on EFSA authorization status and pelleting survival rates. Cost compression in economy tiers is intensifying because Moroccan diammonium phosphate price volatility disrupts substitution economics. Compound feed mills in Spain and Italy exhibit the sharpest price sensitivity, while Danish and Dutch integrators prioritize performance guarantees over per-kilogram costs.
Supply Chain Analysis
Denmark and the Netherlands anchor submerged fermentation capacity for high-activity phytase and carbohydrase production, drawing from fungal Aspergillus and bacterial Bacillus strain banks. Raw material dependencies center on glucose feedstocks, nitrogen sources, and specialized bioreactor equipment sourced from German and Swiss engineering houses. Single-source vulnerability concentrates in precision-fermentation strain IP controlled by a limited cohort of biotechnology majors. Distribution runs through Rotterdam liquid bulk terminals and Rhine-Ruhr rail corridors to compound feed mills across Germany, France, and the Benelux.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme suppliers increasingly monetize formulation advisory and on-farm dosing optimization as recurring-revenue services that expand faster than commodity concentrate sales. This service-attach layer captures value from EFSA compliance complexity and CSRD carbon accounting mandates that strain livestock operator technical capabilities.
For Market Incumbents: Secure long-term supply agreements with CSRD-reporting poultry cooperatives before channel compression eliminates distributor intermediaries entirely. BASF SE and DSM Nutritional Products AG must defend their installed base against precision-fermentation specialists by deepening backward integration into production strain IP and expanding Ludwigshafen and Delft capacity for thermostable enzyme variants. For New Entrants and Emerging Players: Differentiate on liquid formulation stability for Polish and Baltic aquafeed applications where cold-chain gaps have constrained incumbent penetration. Target Pomerania carp producers and Norwegian salmon integrators with extrusion-compatible carbohydrase blends, leveraging direct technical service relationships that bypass established distributor networks lacking temperature-controlled logistics expertise. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-scale fermentation houses holding EMA-approved strain dossiers but lacking integrated sustainability disclosure capabilities. Five-to-ten-year viability hinges on CSRD alignment and F-Gas Regulation compliance capital deployment. Watch for national derogation timelines on environmental claims as the signal indicating segmented approval pathways that favor regionally integrated suppliers over import-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain IP | Captive production organism ownership locks out REACH-registered competitors from EMA authorization pathways. |
| Anaerobic Digestion-Linked Facility Expansion | Denmark and Netherlands bioreactor sites gain F-Gas Regulation compliance cost advantages plus CSRD Scope 2 disclosure benefits. |
| Direct Procurement Contracting | Spanish and Italian poultry cooperatives bypass distributors lacking carbon accounting capabilities under retailer audit pressure. |
| Liquid Formulation Cold-Chain Investment | Eastern European temperature-controlled logistics unlock Polish aquafeed penetration for extruded carp and trout feeds. |
| Multi-Enzyme Cocktail Development | Thermostable phytase-protease-carbohydrase platforms capture margin from French and German broiler integrators specifying energy matrix reformulation. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EFSA feed additive authorization dossiers, EU customs trade data, and REACH registration databases to construct bottom-up enzyme demand estimates and top-down market sizing. Interviews with compound feed procurement managers, fermentation plant technical directors, regulatory affairs specialists at enzyme suppliers, and livestock cooperative sustainability officers provided operational validation. Secondary sources included ECHA substance registration data, EU Green Deal national implementation plans, and CSRD disclosure frameworks.
Segmentation dimensions modeled span enzyme product chemistry (phytase, protease, carbohydrase), target livestock species (poultry, swine, ruminants, aquaculture), delivery format (powder, liquid, granule, pelleted), and geographic production cluster across the analysis window. CAGRs were derived from trend extrapolation of EMA authorization timelines, F-Gas Regulation compliance cost trajectories, and livestock density projections in nitrogen-critical regions. Industry-specific forecast inputs incorporated pelleting temperature survival rates and inorganic phosphate price substitution elasticities.
Material uncertainties — EMA efficacy substantiation delays, REACH strain registration cost inflation, and EU Feed Additives Regulation revision outcomes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory pathway stability and livestock operator reformulation willingness under EU Green Deal ammonia ceilings. Recalibration cycles align with material shifts in EFSA authorization precedents and national derogation announcements for environmental performance claims.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
Feed Amino Acids Market
Agricultural Chemicals
Agricultural Antibacterials Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
North America Plant Growth Regulators Market
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
ASEAN Livestock Disinfectant Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
Asia-Pacific Plant Growth Regulators Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
Thailand Feed Additives Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Global Agricultural Micronutrients Market
Agricultural Chemicals
Europe Feed Acidifiers Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market