
 North America Feed Acidifiers Market | 2026-2036
North America Feed Acidifiers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Acidifiers Market Analytics
Subscription-based feed formulation software is broadening how acidifier vendors monetize technical expertise beyond commodity chemical sales. Cargill Inc. leverages its integrated nutrition platforms to bundle acidifier recommendations with real-time diet optimization. BASF SE anchors its position through dedicated animal nutrition R&D facilities in North America. Kemin Industries differentiates via specialized organic acid blends targeting gut health metrics in poultry operations.
Feed acidifiers comprise organic acids such as formic, propionic, and citric acid, alongside inorganic acids and buffered salt formulations, typically incorporated at inclusion rates between 0.5% and 2.5% of total feed weight to reduce gastric pH and inhibit pathogenic bacterial colonization in monogastric animals. The organic acids category leads value contribution due to superior palatability acceptance and established efficacy data in swine and poultry diets. Powder and liquid forms dominate volume flows, though granule formulations are gaining traction among large feed manufacturers seeking improved handling characteristics and reduced dust exposure during mill operations.
The FDA's Veterinary Feed Directive and EPA antimicrobial discharge guidelines constrain product claims and environmental release profiles for acidifier manufacturers operating in the United States. CFIA feed regulations in Canada impose parallel but distinct ingredient approval pathways that vendors must navigate for cross-border product registration. Stakeholders should monitor evolving state-level nutrient management plans and integrated livestock operation sustainability certifications, as these frameworks increasingly specify feed additive environmental performance criteria that will determine market access and premium positioning.
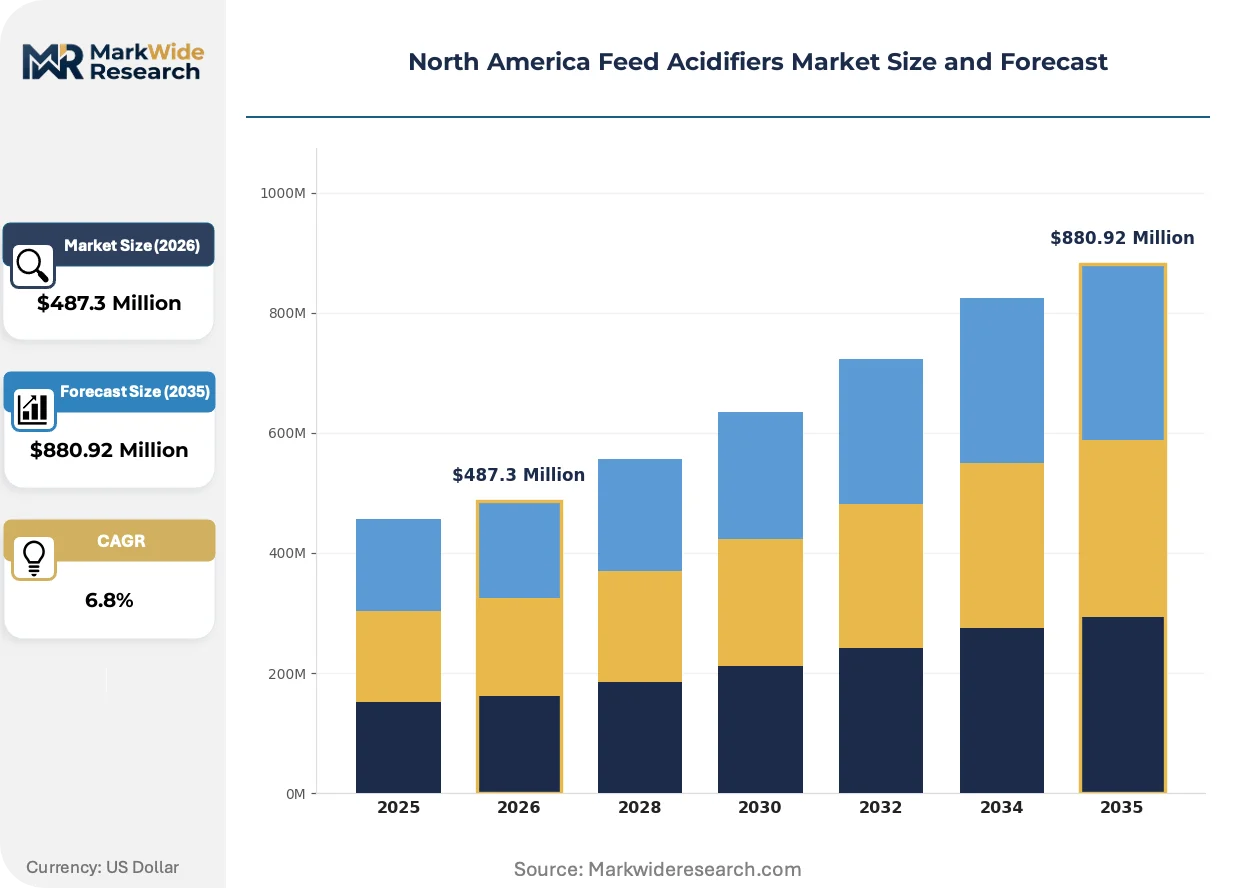
Market Dynamics
The FDA's Veterinary Feed Directive has restructured how acidifier vendors register products and validate claims, shifting competitive advantage toward firms with dedicated regulatory affairs infrastructure and documented efficacy datasets.
Growth Catalysts
- Antibiotic-free poultry mandates:Broiler integrators in the southeastern United States are expanding acidifier programs to meet retailer procurement specifications for reduced antimicrobial use.
- Formic acid inclusion protocols:Swine nutritionists in the U.S. Midwest corn-belt corridor are standardizing organic acid blends at 1.0-1.5% inclusion rates to improve feed conversion ratios in nursery diets.
- CFIA ingredient approval harmonization:Canadian feed regulations are creating cross-border product registration efficiencies that reduce time-to-market for U.S.-based manufacturers.
Market Restraints
- Propionic acid feedstock volatility:Petrochemical-derived organic acids face input cost pressure from ethylene oxide supply fluctuations and refinery capacity constraints.
- Buffered salt technical ceiling:Sodium formate and calcium propionate formulations exhibit reduced gastric pH lowering efficacy compared to pure acid equivalents, limiting premium pricing power.
- EPA discharge guideline friction:Antimicrobial environmental release profiles constrain product claims and require additional toxicological documentation for manufacturing facility permits.
Strategic Opportunities
- Granule formulation adoption:Large feed manufacturers in Ontario and Quebec are converting from powder to granule acidifiers to reduce dust exposure and improve mill handling characteristics.
- Subscription software bundling:Acidifier vendors can monetize technical expertise through feed formulation platforms that integrate real-time diet optimization with additive recommendations.
- State nutrient management tailwinds:Integrated livestock operation sustainability certifications in Iowa and Minnesota are specifying feed additive environmental performance criteria that reward compliant suppliers.
Industry Challenges
- CFIA-FDA registration divergence:Parallel but distinct ingredient approval pathways require duplicate toxicological studies and label submissions, stretching regulatory affairs capacity.
- Legacy mill equipment compatibility:Acidifier corrosion profiles necessitate stainless steel upgrades in feed manufacturing facilities, creating capex barriers for mid-scale operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Acidifiers Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Acids, Inorganic Acids, Salt-Based Acidifiers, Others Application: Poultry, Swine, Ruminants, Aquaculture Form: Liquid, Powder, Granule, Blends End User: Farmers, Feed Manufacturers, Livestock Integrators, Veterinarians |
| Companies Covered | Cargill Inc., BASF SE, SHV (Nutreco NV), Brenntag SE, Adisseo, Kemin Industries, Alltech Inc., Yara International AS, EW Nutrition, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Acidifiers Market Evolving Landscape
Acidifier delivery systems are fragmenting into application-specific formats as feed manufacturers demand precision dosing and reduced handling friction. This specialization is compressing commodity margins while opening premium tiers for validated performance.
Microencapsulated organic acid blends are modularizing how nutritionists target specific gut segments in monogastric animals. Large poultry integrators in Georgia and Arkansas are adopting these precision-release formulations for antibiotic-free broiler programs. The technology is modularizing supplier relationships by requiring co-development partnerships between chemical manufacturers and feed formulators rather than arm's-length commodity transactions.
The EPA's antimicrobial discharge guidelines are tightening environmental release documentation requirements for acidifier manufacturing facilities. Industrial consequence includes mandatory toxicological resubmissions for products with historical registrations. Midwestern U.S. production facilities face the most acute compliance burden, with several operators investing in on-site wastewater treatment infrastructure to maintain product claims.
Buyer concentration among top-ten U.S. feed manufacturers is compressing supplier negotiation cycles and unbundling technical advisory services from chemical supply contracts. Procurement teams now source acidifiers through centralized commodity desks while engaging specialized nutrition consultants separately. This bifurcation is most visible in the corn-belt states, where integrated pork and poultry operations have consolidated purchasing authority at corporate headquarters.
North America Feed Acidifiers Market Segmentation
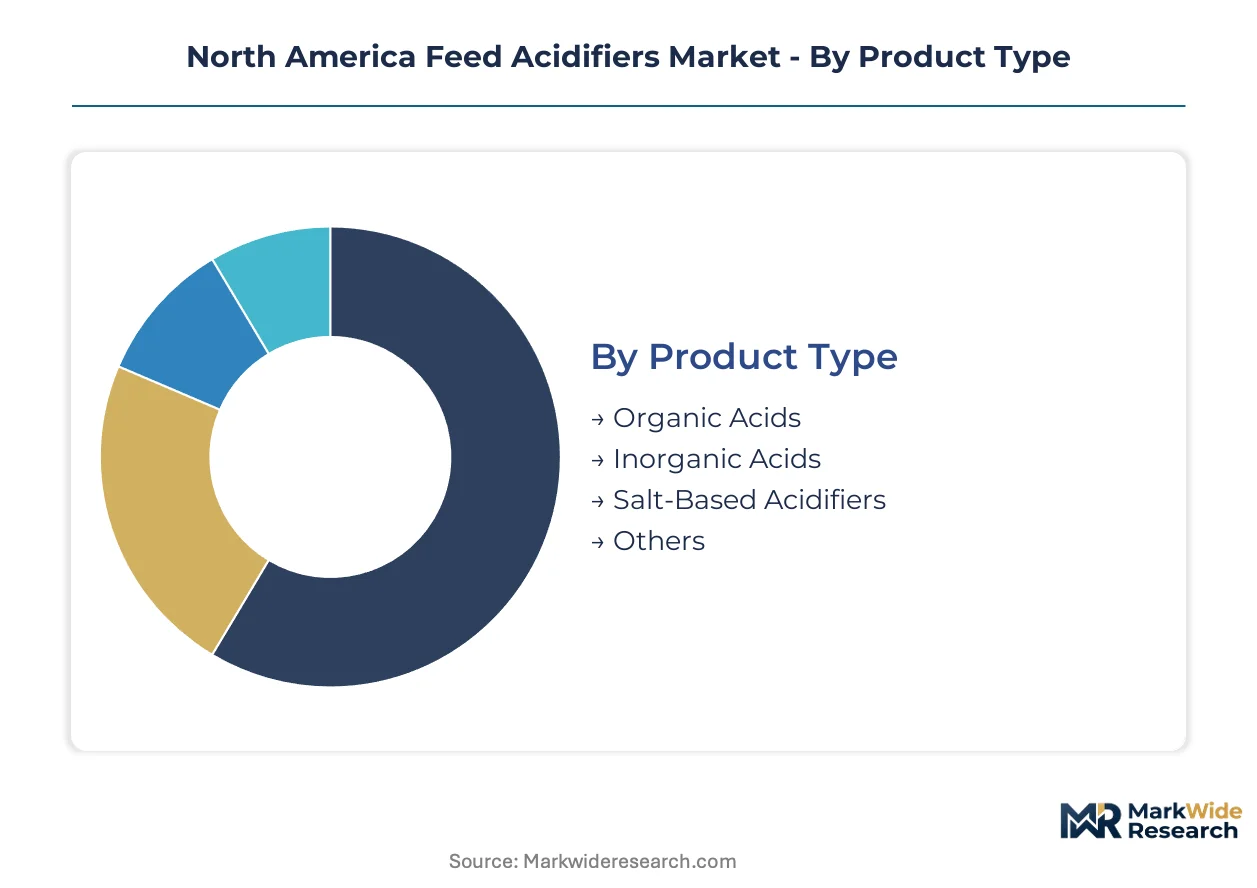
Acidifier purchasing patterns fragment sharply across product chemistry, animal species, physical form, and buyer sophistication. Each dimension carries distinct margin profiles and regulatory exposure that reshape vendor go-to-market priorities.
Product Type:
Capital intensity peaks with organic acid production facilities requiring dedicated fermentation or petrochemical synthesis infrastructure.
- Organic Acids:Formic, propionic, and citric acid formulations dominate value capture due to established efficacy datasets in swine and poultry nutrition. Demand concentrates among broiler integrators in Georgia and Arkansas executing antibiotic-free transitions under FDA Veterinary Feed Directive compliance pressure.
- Salt-Based Acidifiers:Sodium formate and calcium propionate buffers trade reduced gastric pH efficacy for handling safety and equipment compatibility. Midwest feed manufacturers favor these formulations to avoid stainless steel mill upgrades.
- Inorganic Acids:Sulfuric and phosphoric acid derivatives occupy niche applications in mineral feed fortification.
- Others:Novel acidifier complexes and hybrid organic-inorganic systems remain pre-commercial.
Most installed capacity flows through Organic Acids. Expansion is steepest in Salt-Based Acidifiers.
Application:
Volume distribution tracks the monogastric concentration of North American livestock production.
- Poultry:Broiler and layer operations drive granular demand for acidifiers in antibiotic-free programs. Southeastern U.S. integrators specify organic acid blends at 1.0-1.5% inclusion rates to meet retailer procurement mandates.
- Swine:Nursery diet optimization in the Iowa-Minnesota corridor anchors formic acid consumption. Nutritionists standardize acidifier protocols to improve feed conversion ratios in wean-to-finish systems.
- Ruminants:Beef and dairy applications remain limited by rumen pH buffering capacity.
- Aquaculture:Salmonid and shrimp feed trials in British Columbia and Mexico generate pilot-scale orders.
Procurement volume concentrates in Poultry. Technical innovation is advancing fastest in Swine.
Form:
Handling characteristics and dosing precision determine manufacturing capital allocation.
- Liquid:Bulk tank delivery systems suit large feed mills with automated dosing infrastructure. Ontario and Quebec manufacturers prefer liquid acidifiers for continuous flow operations.
- Powder:Conventional dry mixing compatibility preserves existing equipment investments. Dust exposure liabilities are compressing share in unionized mill environments.
- Granule:Ontario feed manufacturers are converting from powder to reduce dust exposure and improve flow characteristics. Granule production requires extrusion or spray-drying capex that excludes smaller compounders.
- Blends:Pre-mixed acidifier complexes simplify procurement for mid-scale operations lacking formulation expertise.
Current throughput dominates in Powder. Facility conversion is accelerating most quickly in Granule.
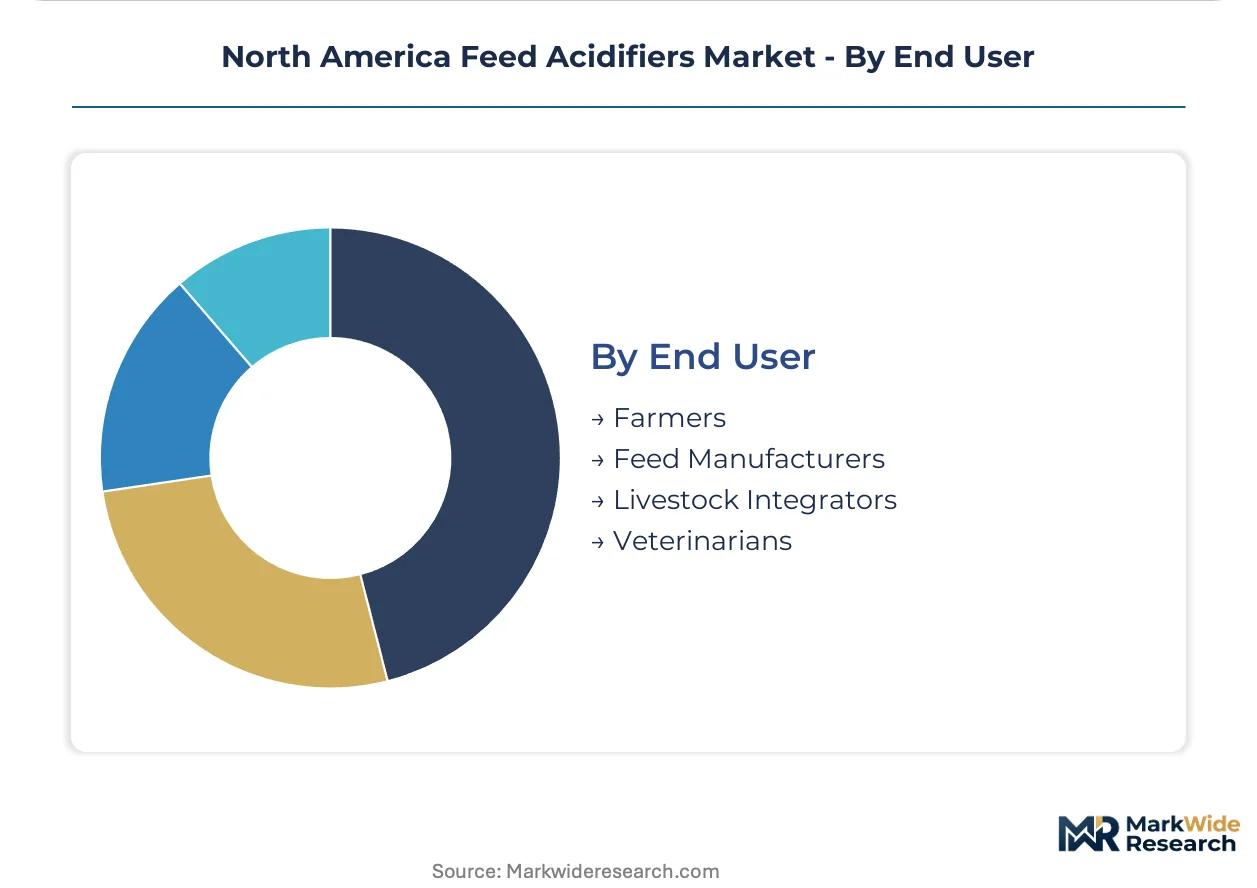
End User:
Buyer sophistication tiers separate commodity procurement from technical advisory relationships.
- Feed Manufacturers:Centralized purchasing desks at top-ten U.S. compounders compress supplier margins while demanding validated performance datasets. These buyers unbundle chemical supply from nutrition consulting.
- Livestock Integrators:Vertically coordinated pork and poultry operations specify acidifier protocols at corporate headquarters. Iowa and Minnesota integrators tie additive selection to state nutrient management certification requirements.
- Farmers:Independent producers rely on distributor recommendations and price-driven selection.
- Veterinarians:Prescription-linked acidifier recommendations carry regulatory weight under FDA Veterinary Feed Directive frameworks.
Contract volume concentrates with Feed Manufacturers. Relationship depth is expanding fastest among Livestock Integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands larger absolute volumes than Canada, though Canadian regulatory harmonization is accelerating cross-border product flows. Mexico's livestock sector expansion creates incremental demand for acidifier imports from both northern neighbors.
United States
Broiler integrators in Georgia and Arkansas drive organic acid consumption for antibiotic-free poultry programs under FDA Veterinary Feed Directive compliance pressure. The EPA's antimicrobial discharge guidelines constrain manufacturing facility permits in the Midwest. Iowa and Minnesota feed manufacturers anchor formic acid demand for swine nursery diet optimization.
Canada
Ontario and Quebec feed manufacturers convert from powder to granule acidifiers to reduce dust exposure and improve mill handling characteristics. CFIA ingredient approval pathways operate parallel to FDA frameworks, requiring duplicate toxicological documentation for cross-border vendors. British Columbia aquaculture trials generate pilot-scale orders for salmonid feed applications.
Mexico
Poultry sector modernization in Jalisco and Nuevo León expands acidifier incorporation in commercial broiler operations. The country's national agricultural regulator maintains distinct feed additive registration requirements from US and Canadian frameworks. Yucatán Peninsula shrimp aquaculture development creates emerging demand for acidified larval feeds.
North America Feed Acidifiers Market Competitive Landscape
Top-tier vendors anchor integrated nutrition platforms, while mid-scale specialists compete on formulation customization and regional service density. The vendor base stratifies across three tiers: multinational chemical conglomerates with dedicated animal nutrition divisions, regional compounders with captive distribution networks, and technology-focused specialists monetizing technical advisory through subscription software. Dominant competitive moves include backward integration into organic acid production and strategic partnerships with feed formulation software providers.
Within the integrated nutrition tier, Cargill Inc. and BASF SE exemplify platform-based bundling of acidifier supply with real-time diet optimization capabilities. Kemin Industries occupies a position among specialized organic acid blenders targeting gut health metrics in poultry operations.
| Leading Market Players |
|---|
| Cargill Inc. |
| BASF SE |
| SHV (Nutreco NV) |
| Brenntag SE |
| Adisseo |
| Kemin Industries |
| Alltech Inc. |
| Yara International AS |
| EW Nutrition |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap compounders across the U.S. Midwest corn-belt anchor feed acidifier supply, translating operational continuity into pricing discipline that resists spot-market volatility. Their conservative leverage profiles and captive distribution networks insulate contract negotiations from the margin compression visible among petrochemical-dependent pure-play organic acid suppliers.
Pricing Analysis
Capacity additions in Louisiana and Texas petrochemical corridors are reshaping price floors for propionic and formic acid derivatives, pressuring legacy fermentation-based producers. Contract-based long-term offtake dominates procurement relationships between top-ten U.S. feed manufacturers and acidifier vendors, with price differentiation hinging on FDA Veterinary Feed Directive compliance documentation and organic certification tier. Cost compression in standard-grade organic acids is intensifying because ethylene oxide feedstock volatility feeds through to spot pricing, while livestock integrators in Iowa and Minnesota exhibit lowest price sensitivity due to state nutrient management certification requirements that lock in premium-tier suppliers.
Supply Chain Analysis
Domestic-content mandates under the Buy American Act reshape sourcing for acidifiers deployed in federally funded agricultural research programs, nudging procurement toward U.S.-based fermentation and petrochemical synthesis facilities. Supply concentrates in Texas, Louisiana, and Illinois, with raw material dependencies spanning ethylene oxide, methanol, and agricultural carbohydrate feedstocks. Single-source vulnerability runs through Gulf Coast refinery complexes where hurricane disruption risk elevates inventory carrying costs for Midwest feed mills. Distribution runs through captive distributor networks and direct mill-tanker delivery systems serving large compounders in Ontario and Quebec.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feed acidifier margins are expanding through precision-formulation premiums that capture value from antibiotic-free poultry mandates, while input cost discipline in salt-based buffers protects standard-tier profitability.
For Market Incumbents: Cement regulatory affairs infrastructure as a defensive moat by expanding toxicological documentation teams to manage parallel FDA and CFIA submission requirements. Deepen backward integration into organic acid production through fermentation facility acquisitions in the U.S. Midwest, neutralizing petrochemical feedstock volatility that threatens margin stability in pure-play chemical supply relationships.
For New Entrants and Emerging Players: Launch via subscription-based feed formulation software partnerships that monetize technical advisory separately from commodity chemical sales, bypassing entrenched procurement desks at top-ten U.S. compounders. Target granule formulation white space in Ontario and Quebec feed mills converting from powder to reduce dust exposure, exploiting capex barriers that exclude smaller compounders from extrusion capacity investments.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional compounders with captive distribution networks and underutilized granulation capacity, offering platform consolidation upside. Long-term viability over a five-to-ten-year horizon rests on regulatory compliance infrastructure rather than pure production scale, making CFIA-FDA dual-registration capabilities the critical acquisition filter. Watch EPA antimicrobial discharge guideline enforcement intensity as the inflection signal determining manufacturing facility permit costs and product claim validity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Acid Production | Captive supply of formic acid insulates margins from ethylene oxide volatility in Gulf Coast petrochemical corridors. |
| Granule Formulation Capacity Expansion | Ontario and Quebec feed mills prioritize dust-reduced handling characteristics in unionized mill environments. |
| Regulatory Affairs Infrastructure Buildout | Parallel FDA and CFIA submission capabilities accelerate cross-border product registration for U.S. manufacturers. |
| Subscription Software Platform Partnership | Real-time diet optimization bundling separates technical advisory revenue from commodity chemical pricing pressure. |
| State Nutrient Management Certification Alignment | Iowa and Minnesota sustainability criteria reward compliant suppliers with preferred procurement status among integrators. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with feed mill procurement directors, swine nutritionists at Iowa-Minnesota integrators, regulatory affairs leads at acidifier manufacturers, and CFIA compliance officers with secondary validation against FDA Veterinary Feed Directive filings, EPA discharge permit databases, USDA feed production statistics, and SEC 10-K disclosures from listed chemical conglomerates. Bottom-up volume estimates from state-level feed production data triangulated against top-down market sizing from petrochemical capacity utilization rates.
Segment-weighted modeling applied differential growth assumptions across organic acids, salt-based acidifiers, and inorganic acid categories, with poultry, swine, ruminant, and aquaculture applications tracked separately throughout the projection horizon. Physical form splits between liquid, powder, granule, and blends incorporated handling infrastructure capex and dust exposure liability trends. CAGRs derived from historical feed conversion ratio improvement correlations with acidifier inclusion rates, cross-referenced against antibiotic-free program adoption curves in Georgia and Arkansas broiler operations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EPA discharge guideline enforcement shifts or CFIA-FDA harmonization delays. Forecasts reflect assumptions around feed grain price stability, petrochemical feedstock availability, and state-level nutrient management plan adoption timelines. A small set of named triggers—FDA Veterinary Feed Directive scope expansion, Ontario dust exposure regulatory action, and Gulf Coast refinery disruption events—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Mexico Feed Additives Market
Agricultural Chemicals
Field Marking Paint Market
Agricultural Chemicals
China Feed Enzymes Market
Agricultural Chemicals
North America Silage Additives Market
Agricultural Chemicals
Stored Grain Insecticides Market
Agricultural Chemicals
China Herbicide Market
Agricultural Chemicals
Europe Swine Feed Premix Market
Agricultural Chemicals
Feed Binders Market
Agricultural Chemicals
South America Feed Acidifiers Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
North America Feed Phytogenics Market
Agricultural Chemicals
South America Agricultural Disinfectants Market
Agricultural Chemicals
Feed Antibiotics Market
Agricultural Chemicals
Soilless Substrate-Specific Fertility Solution Market
Agricultural Chemicals
North America Feed Premix Market
Agricultural Chemicals
Global Agricultural Chelates Market