
 Agricultural Insect Pheromones Market | 2026-2036
Agricultural Insect Pheromones Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Insect Pheromones Market Analysis
Specialty fruit growers is rotating toward pheromone-based mating disruption as their primary pest management architecture, displacing conventional broad-spectrum spraying programs. Koppert Biological Systems leverages its biological control portfolio to anchor integrated pest management bundles that pair pheromones with beneficial insects. Shin-Etsu Chemical Co., Ltd. sustains manufacturing scale across its polymer-dispenser supply chain, controlling critical formulation inputs. Suterra LLC dominates the North American orchard segment through proprietary release-matrix technologies.
Agricultural insect pheromones are semiochemical signal compounds, typically synthesized as precise ratios of aliphatic aldehydes, acetates, or alcohols, that mimic species-specific female sex attractants to disrupt male mate location. Manufacturers embed these active molecules into controlled-release polymer dispensers or sprayable microcapsules to maintain field efficacy across growing seasons. Synthetic pheromone formulations currently occupy the largest value share due to cost-efficient scale-up of lepidopteran blends, while biological fermentation routes gain traction for complex multi-component species. Application-driven demand clusters in crop protection, where mating disruption protocols for tree nuts and stone fruits generate recurring seasonal revenue.
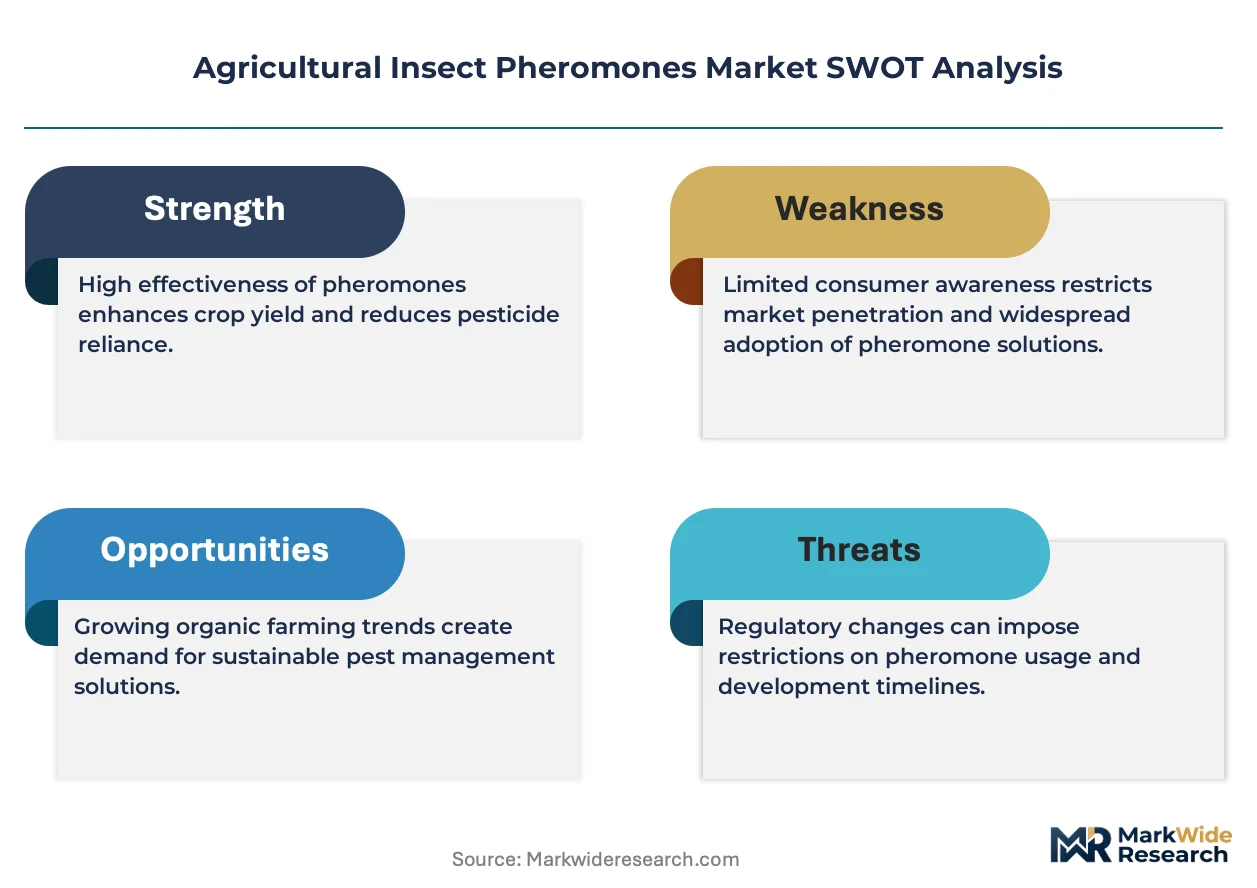
The EPA's Federal Insecticide, Fungicide, and Rodenticide Act registration pathway governs pheromone product commercialization in the United States, while the EU's Sustainable Use of Pesticides Directive accelerates substitution mandates across member states. REACH compliance in Europe and emerging biopesticide data requirements in Brazil's national health surveillance agency reshape formulation standards and market access timelines. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate registration cost structures and first-mover advantages in newly opened markets.
Market Dynamics
The EPA's neonicotinoid restrictions are forcing California almond and pistachio growers to restructure pest management programs around mating disruption protocols, collapsing demand for conventional spraying architectures while concentrating pheromone procurement among specialty crop cooperatives.
Growth Catalysts
- EU Sustainable Use of Pesticides Directive:Member state substitution mandates accelerate pheromone registration timelines and create guaranteed procurement floors for biological pest control inputs.
- Polymer-dispenser manufacturing scale:Shin-Etsu's captive supply of controlled-release matrices reduces formulation costs for lepidopteran blends across Mediterranean-climate growing zones.
- Integrated pest management bundling:Koppert Biological Systems pairs pheromone dispensers with beneficial insect releases, locking in recurring seasonal revenue from stone fruit and tree nut operations.
Market Restraints
- Petrochemical feedstock volatility:Aliphatic aldehyde and acetate precursors fluctuate with naphtha cracking margins, compressing formulation margins during energy price spikes.
- Single-source supply concentration:Japan and Germany host the only commercial-scale pheromone synthesis facilities capable of multi-ton lepidopteran blend output.
- Species-specific formulation limits:Each target pest requires distinct molecular ratios, preventing economies of scope across crop types.
Strategic Opportunities
- Brazilian soybean belt expansion:ANVISA biopesticide pathway revisions open registration for helicoverpa armigera mating disruption in Mato Grosso and Goiás production zones.
- Sprayable microencapsulation convergence:Combining pheromone payloads with drone application platforms enables precision deployment across irregular orchard topography.
- Direct-to-grower channel development:Bypassing traditional agrochemical distributors through cooperative procurement aggregators captures margin previously lost to wholesale markups.
Industry Challenges
- Synthetic organic chemist scarcity:Multi-step stereoselective synthesis of species-specific pheromone blends requires specialized expertise concentrated in legacy pharmaceutical talent pools.
- Field efficacy validation timelines:Mating disruption protocols demand multi-season demonstration data before cooperative procurement committees authorize program-scale adoption.
- Cross-jurisdiction registration divergence:EPA FIFRA, REACH, and Brazil's ANVISA maintain incompatible data requirements, forcing redundant toxicology and environmental fate studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Insect Pheromones Market |
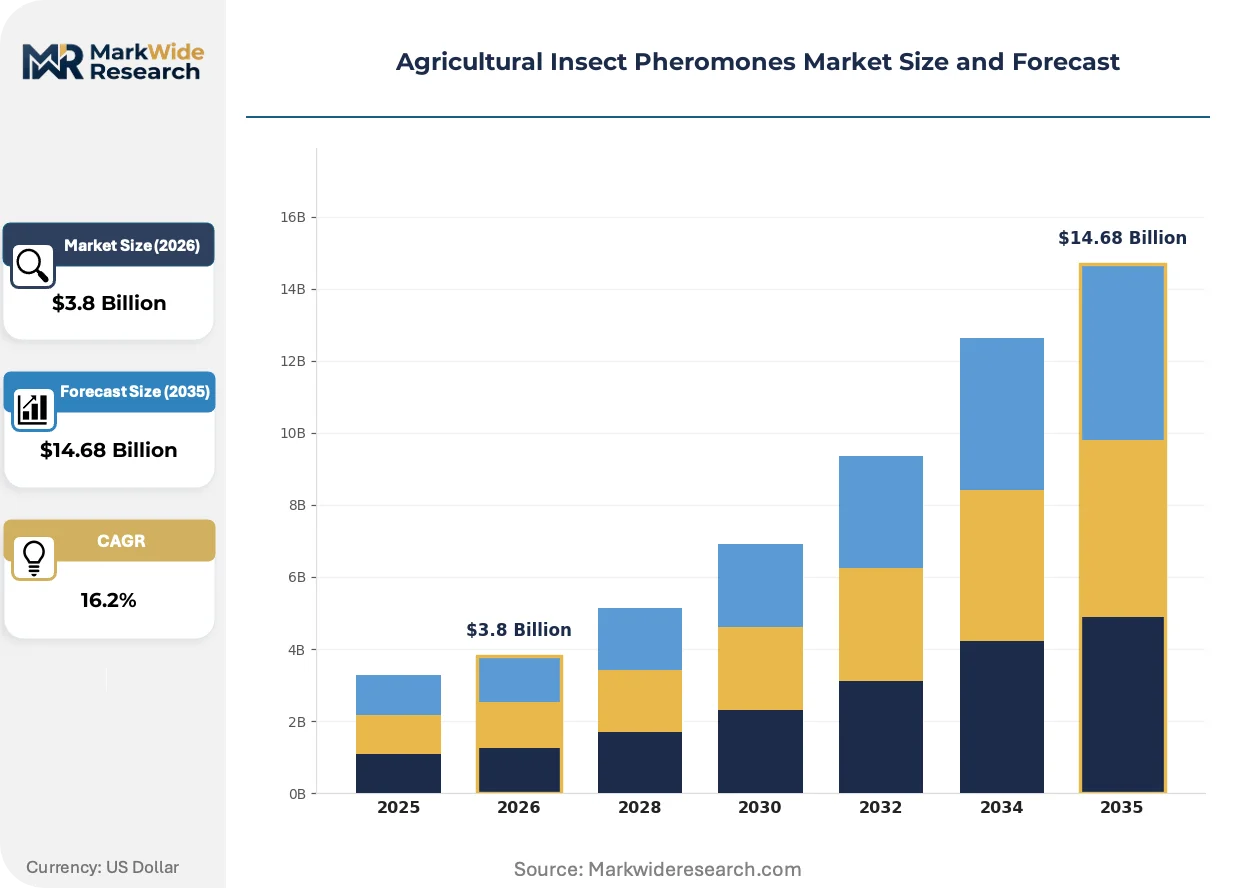
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $14.68 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semiochemical, Synthetic, Biological, Trap Application: Pest Control, Crop Protection, Monitoring, Trapping Formulation: Lures, Dispensers, Mats, Granules Crop Type: Cereals, Fruits, Vegetables, Ornamental |
| Companies Covered | Russell IPM Ltd, Bayer AG, Shin-Etsu Chemical Co., Ltd., Koppert Biological Systems, Provivi, Inc., Suterra LLC, ISCA Technologies, Inc., Pacific Biocontrol Corporation, Biobest Group NV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Insect Pheromones Market Emerging Trajectories
Active ingredient delivery architectures are fragmenting as manufacturers compete to extend field persistence while reducing labor inputs for orchard and vineyard applications.
Microencapsulated sprayable formulations are fragmenting the dispenser-dominant pheromone market by enabling aerial application and eliminating hand-hung labor requirements. Drone operators in Washington State apple districts and Australian wine regions now contract directly with growers for precision pheromone deployment. This technology compression is collapsing the traditional dispenser supply chain into two competing delivery paradigms with incompatible equipment requirements.
REACH authorization timelines for polymer-based controlled-release matrices are tightening environmental fate data requirements across EU member states. Formulators must now submit extended aquatic toxicity profiles and soil metabolite identification studies before market authorization. Mediterranean stone fruit cooperatives in Spain and Italy face 18-24 month registration delays, compressing first-mover advantage windows for novel dispenser chemistries.
Certification-driven procurement is restructuring buyer-seller relationships as GLOBALG.A.P. and organic certifying bodies mandate documented non-chemical pest control percentages. Almond handlers in California's Central Valley now require grower-suppliers to achieve 70% pheromone-based mating disruption coverage for premium contract tiers. This behavioral shift is forcing independent growers into cooperative purchasing arrangements to meet volume thresholds for distributor pricing.
Agricultural Insect Pheromones Market Segmentation
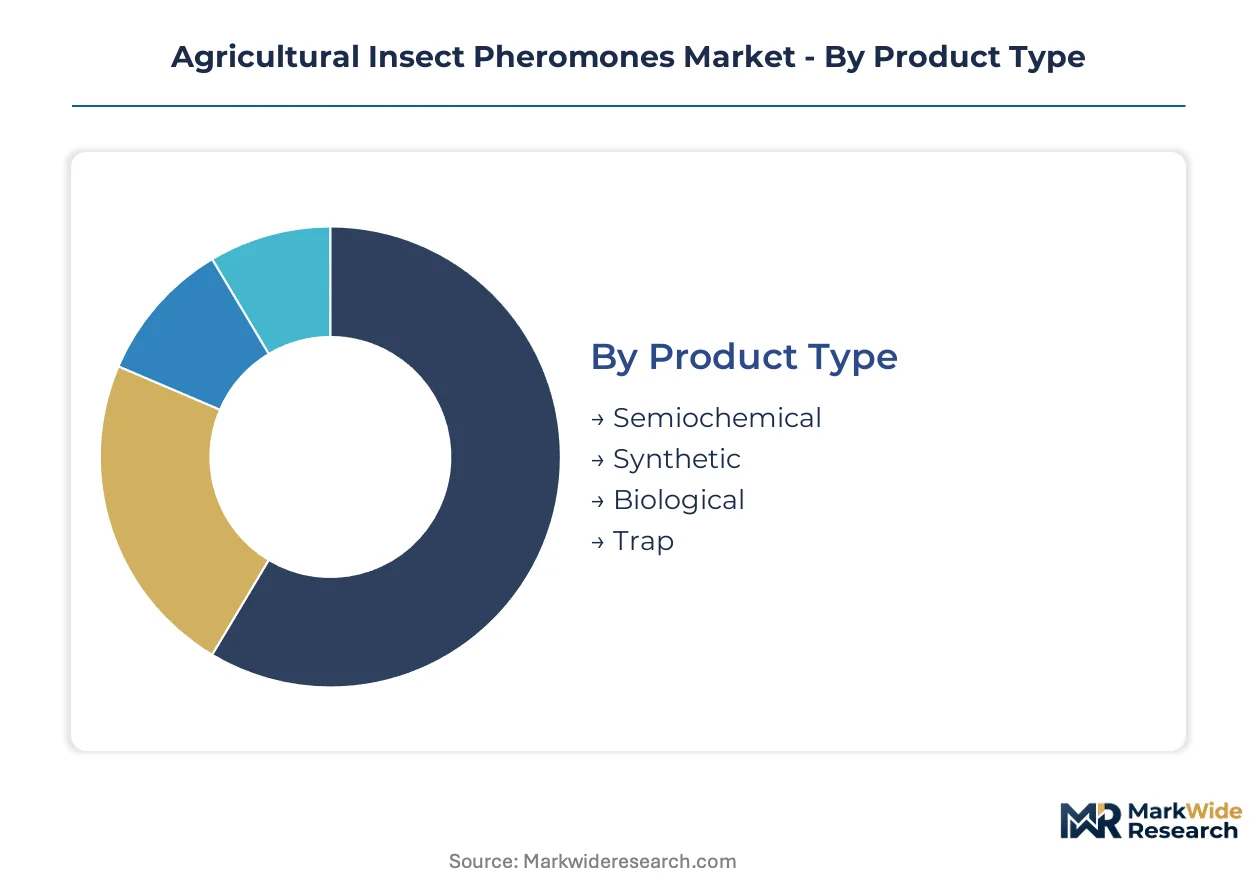
Pheromone procurement patterns diverge sharply across crop systems and delivery formats. Specialty fruit cooperatives prioritize mating disruption protocols, while row-crop operators favor monitoring traps for threshold-based intervention.
Product Type:
Synthetic formulations command the deepest margin pools due to scale-efficient multi-ton production of lepidopteran blends. Biological routes capture premium pricing for complex multi-component species where fermentation yields stereochemical precision.
- Synthetic:Aliphatic aldehyde and acetate blends synthesized through stereoselective organic chemistry dominate commercial volumes. California almond and pistachio cooperatives procure synthetic codling moth and navel orangeworm formulations under multi-season supply contracts.
- Biological:Fermentation-derived pheromones produced via engineered yeast strains achieve chirality control for species with intricate multi-component attractants. Mediterranean stone fruit growers in Spain and Italy pay formulation premiums for biological helicoverpa armigera blends where synthetic routes fail.
- Semiochemical:Plant-derived kairomones and synomones extend pest disruption through behavioral manipulation beyond mating interference.
- Trap:Monitoring devices with pheromone-baited adhesive surfaces enable threshold detection for spray timing decisions.
Synthetic formulations hold installed capacity. Biological routes are rotating up the share rankings.
Application:
Crop protection commands procurement volumes where mating disruption replaces calendar spraying. Monitoring applications concentrate margin in data services rather than chemical supply.
- Crop Protection:Mating disruption protocols deploy controlled-release dispensers or microencapsulated sprays to prevent fertilization across entire orchards. Washington State apple districts and Australian wine regions now contract drone operators for precision aerial deployment.
- Pest Control:Area-wide management programs coordinate pheromone coverage across contiguous production zones to suppress immigrant moth pressure.
- Monitoring:Delta and funnel traps with species-specific lures track population fluctuations to time intervention thresholds.
- Trapping:Mass-trapping configurations deploy high-density lure arrays to deplete male populations directly rather than disrupt location behavior.
Crop protection commands grower procurement budgets. Monitoring is climbing the fastest as data-driven IPM adoption spreads.
Formulation:
Dispenser manufacturing concentrates margin in polymer-matrix chemistry and controlled-release kinetics. Sprayable formats capture application efficiency premiums through labor reduction.
- Dispensers:Polymer-reservoir devices suspend active ingredients in silicone or PVC matrices for 90-180 day field persistence. Shin-Etsu's captive supply of controlled-release matrices reduces per-unit costs for Mediterranean-climate stone fruit operations.
- Lures:Rubber septa and polyethylene vials deliver high initial release rates for monitoring trap applications.
- Mats:Laminated fiberboard substrates provide flat-profile deployment for vineyard trellis integration.
- Granules:Microencapsulated sprayable particles enable aerial application across irregular topography without hand-hung labor.
Dispensers hold installed capacity. Sprayable granules are gaining share fastest as drone platforms proliferate.
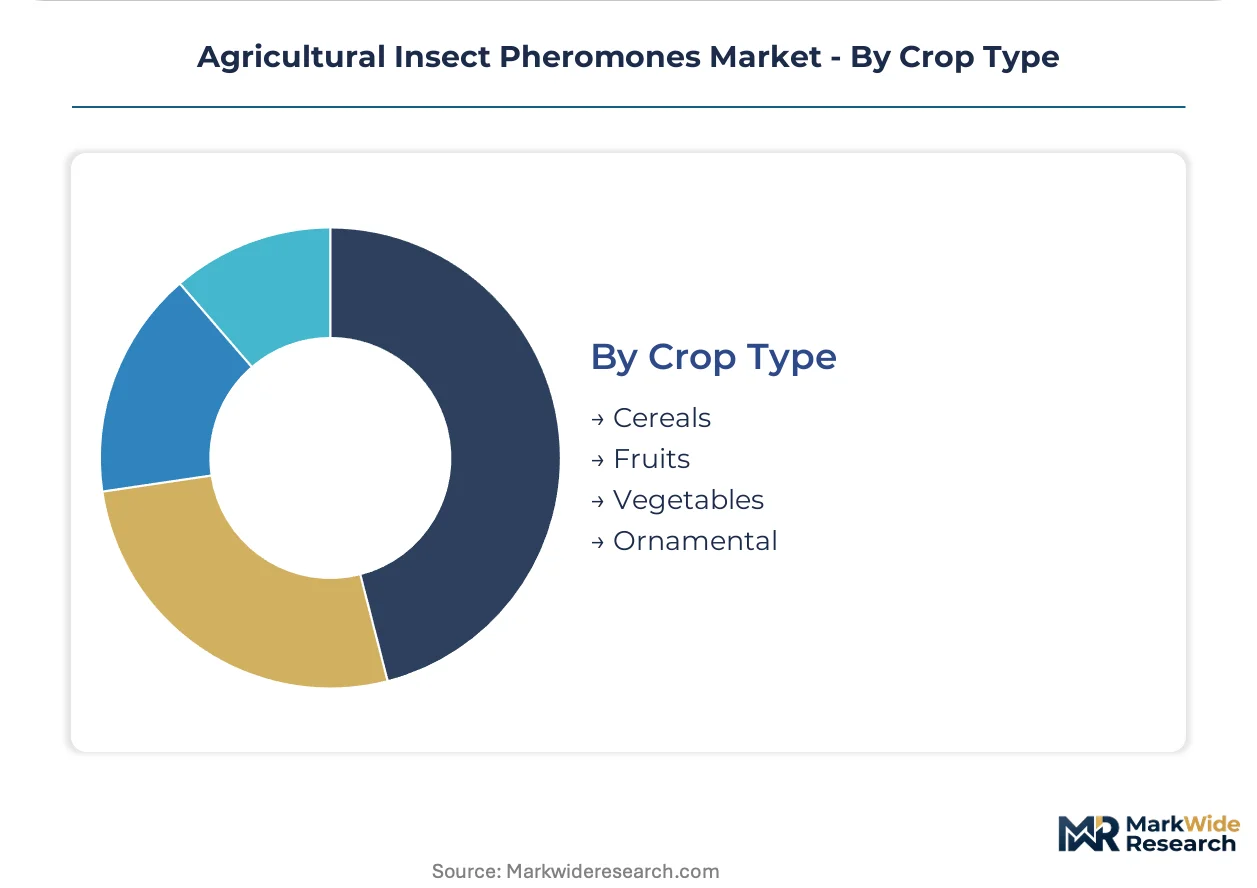
Crop Type:
Fruits concentrate pheromone expenditure per hectare due to high value-at-risk and zero-tolerance cosmetic standards. Vegetable applications expand through protected cultivation systems.
- Fruits:Tree nuts and stone fruits drive mating disruption adoption where navel orangeworm and codling moth infestations trigger rejections at handler receiving stations. California's Central Valley specialty crop cooperatives now mandate 70% pheromone coverage for premium almond contract tiers.
- Vegetables:Protected tomato and pepper operations in Spain's Almería province deploy pheromones for tuta absoluta management within integrated biological control programs.
- Cereals:Maize and rice systems utilize monitoring traps for stem borer complexes where economic thresholds justify intervention.
- Ornamental:Nursery and cut-flower operations deploy pheromones for quarantine-sensitive pest exclusion in export-oriented production.
Fruits hold installed capacity. Vegetables are rotating up the share rankings through greenhouse sector expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial-scale synthesis of lepidopteran pheromone concentrates in Japan and Germany. Mediterranean-climate growing zones in California, Spain, and Italy drive formulation demand through cooperative procurement mandates.
United States
California almond and pistachio cooperatives mandate pheromone coverage for premium contract tiers. EPA neonicotinoid restrictions under FIFRA accelerate mating disruption adoption. The Central Valley specialty crop cluster concentrates procurement volume through Sutter County and Fresno County grower associations.
Spain
Almería greenhouse complexes deploy pheromones for tuta absoluta management in protected tomato operations. REACH authorization timelines tighten environmental fate data requirements for polymer matrices. Mediterranean stone fruit cooperatives in Valencia and Murcia face registration delays compressing first-mover windows.
Italy
Emilia-Romagna and Apulia stone fruit growers pay premiums for biological helicoverpa armigera formulations. EU Sustainable Use of Pesticides Directive substitution mandates create guaranteed procurement floors. The Po Valley orchard belt concentrates dispenser deployment through integrated pest management bundling.
Japan
Shin-Etsu's captive polymer-dispenser manufacturing reduces per-unit costs for lepidopteran blends. METI industrial policy supports stereoselective synthesis capacity expansion. The Niigata-Tokyo chemical corridor hosts multi-ton pheromone synthesis facilities serving Asia-Pacific export markets.
Brazil
Mato Grosso and Goiás soybean producers await ANVISA biopesticide pathway revisions for helicoverpa armigera mating disruption. The country's national health surveillance agency reshapes formulation standards through emerging data requirements. Cerrado agricultural frontier expansion drives monitoring trap deployment for threshold-based intervention.
Agricultural Insect Pheromones Market Vendor Landscape
Concentration sits with polymer-dispenser manufacturers and biological control integrators. The vendor base separates into three tiers: multinational chemical conglomerates with captive synthesis capacity, specialized biological control firms bundling pheromones with beneficial insects, and regional distributors serving cooperative procurement channels. Strategic moves center on backward integration into polymer-matrix supply and direct-to-grower channel development bypassing wholesale markups.
Among Japanese and German chemical manufacturers, Shin-Etsu Chemical Co., Ltd. exemplifies scale-driven polymer-dispenser production. Within the biological control integration tier, Koppert Biological Systems and Biobest Group NV represent European specialists anchoring integrated pest management bundles. Suterra LLC occupies a position in North American orchard-focused release-matrix technologies.
| Leading Market Players |
|---|
| Russell IPM Ltd |
| Bayer AG |
| Shin-Etsu Chemical Co., Ltd. |
| Koppert Biological Systems |
| Provivi, Inc. |
| Suterra LLC |
| ISCA Technologies, Inc. |
| Pacific Biocontrol Corporation |
| Biobest Group NV |
| Others |
Supply Flow & Price Mechanics
Ninety-day polymer-resin inventory cycles in controlled-release matrix manufacturing concentrate pricing power with Shin-Etsu and Suterra, while California almond cooperatives face procurement premiums during naphtha price spikes. This lead-time structure forces specialty crop growers into multi-season contract commitments that lock in formulation costs before field deployment.
Pricing Analysis
EPA FIFRA registration dictates the pricing tier structure across the Agricultural Insect Pheromones Market, separating premium biological fermentation routes from standard synthetic aldehyde blends. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume procurement scale. Cost compression in synthetic lepidopteran formulations is intensifying because petrochemical feedstock volatility compresses margins during energy price spikes. Smallholder vegetable growers in Spain's Almería province exhibit highest price sensitivity, while California tree nut cooperatives with handler-mandated coverage thresholds show lowest sensitivity due to contract tier penalties.
Supply Chain Analysis
Strategic stockpile preferences dominate polymer-dispenser procurement, with California cooperatives maintaining 120-day safety stocks ahead of spring deployment windows. Commercial-scale synthesis concentrates in Japan and Germany, drawing from aliphatic aldehyde and acetate precursors sourced from naphtha cracking operations. Single-source vulnerability in multi-ton lepidopteran blend capacity creates structural risk, as no alternative facilities exist outside Niigata-Tokyo and Rhine-Ruhr chemical corridors. Distribution runs through specialty crop cooperative procurement aggregators that bypass traditional agrochemical wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic organic chemist scarcity constrains multi-step stereoselective synthesis capacity, creating a bottleneck where fermentation expertise and polymer-matrix engineering determine competitive survival. This capability gap separates incumbent manufacturers from aspirants across the Agricultural Insect Pheromones Market.
For Market Incumbents: Shield formulation margins by securing captive supply of controlled-release matrices through backward integration into silicone and PVC resin production. Counter single-source synthesis vulnerability by expanding stereoselective organic chemistry capacity in Mediterranean-climate growing zones near demand clusters. Certification investment in GLOBALG.A.P.-aligned mating disruption protocols locks in cooperative procurement contracts before regulatory substitution mandates accelerate. For New Entrants and Emerging Players: Anchor in Brazilian soybean belt expansion where ANVISA biopesticide pathway revisions open registration for helicoverpa armigera mating disruption in Mato Grosso and Goiás production zones. Sprayable microencapsulation for drone deployment represents the most penetrable application format, as labor cost reduction drives adoption across irregular orchard topography. Direct-to-grower channel development through cooperative procurement aggregators captures margin previously lost to wholesale distribution markups. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-substitution play because EPA neonicotinoid restrictions and EU Sustainable Use of Pesticides Directive mandates create guaranteed procurement floors for biological pest control inputs. Acquisition targets should display integrated pest management bundling capabilities that pair pheromone dispensers with beneficial insect releases. Watch for ANVISA authorization timelines in Brazil as the inflection indicator for South American market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer-Matrix Supply | Shin-Etsu's captive silicone resin production reduces per-unit dispenser costs for lepidopteran blends. |
| Drone Application Platform Partnership | Washington State apple districts contract operators for precision microencapsulated pheromone deployment. |
| Direct-to-Grower Channel Development | California almond cooperatives bypass wholesale markups through Sutter County procurement aggregators. |
| Biological Fermentation Capacity Expansion | Spain and Italy stone fruit growers pay premiums for engineered yeast-derived helicoverpa armigera formulations. |
| Cross-Jurisdiction Registration Harmonization | REACH, EPA FIFRA, and ANVISA alignment reduces redundant toxicology study costs for novel chemistries. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with formulation chemists, cooperative procurement managers, and drone application operators; and secondary validation through EPA FIFRA registration databases, ECHA REACH authorization records, and ANVISA biopesticide pathway documentation. Triangulation across bottom-up cooperative procurement volume estimates and top-down chemical manufacturer capacity assessments anchored value projections.
Across the analysis window, forecasts model crop protection versus monitoring application splits, synthetic versus biological formulation routes, and dispenser versus sprayable delivery formats. CAGRs derive from cooperative mandate adoption curves and regulatory substitution timeline assumptions. Field efficacy validation timelines and polymer-resin inventory cycles constitute key forecast inputs specific to mating disruption protocol deployment.
Material uncertainties — petrochemical feedstock volatility, ANVISA authorization delays, and synthetic organic chemist labor scarcity — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory substitution pace and cooperative procurement committee decision timelines. Revision becomes warranted when EPA neonicotinoid restriction enforcement intensity or EU member state mandate implementation crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Agricultural Chemicals
Asia-Pacific Feed Binders Market
Agricultural Chemicals
South America Plant Growth Regulators Market
Agricultural Chemicals
Global Dinotefuran Market
Agricultural Chemicals
Neonicotinoid Insecticides Market
Agricultural Chemicals
Glyphosate Herbicide Market
Agricultural Chemicals
Middle East and Africa Agricultural Pheromones Market
Agricultural Chemicals
Seed Binders Market
Agricultural Chemicals
Aquafeed Additives Market
Agricultural Chemicals
Paclobutrazol Market
Agricultural Chemicals
China Feed Amino Acids Market
Agricultural Chemicals
Feed Acid Market
Agricultural Chemicals
Asia-Pacific Feed Enzymes Market
Agricultural Chemicals
United States Feed Amino Acids Market
Agricultural Chemicals
Global Agricultural Chelates Market
Agricultural Chemicals
Feed Mycotoxin Detoxifiers Market
Agricultural Chemicals
Global Agricultural Disinfectant Market