
 Neuroendocrine Carcinoma Treatment Market | 2026-2036
Neuroendocrine Carcinoma Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Neuroendocrine Carcinoma Treatment Market Foresight
Specialty pharmacy distribution is tilting toward centralized nuclear medicine hubs capable of handling lutetium-177 and other radioligand cold-chain logistics. Novartis leverages its radioligand manufacturing footprint to control supply security for Lutathera and Pluvicto franchises. Pfizer sustains competitive presence through targeted kinase inhibitor portfolios in differentiated neuroendocrine subsets. Ipsen anchors European market access with its somatostatin analogue legacy and expanding nuclear medicine partnerships.
Neuroendocrine carcinoma treatment encompasses systemic therapeutic interventions targeting well-differentiated and poorly differentiated neuroendocrine neoplasms, utilizing cytotoxic agents, receptor-targeted radiopharmaceuticals, immune checkpoint modulators, and hormone-based growth suppression protocols designed to control tumor proliferation, manage carcinoid syndrome, and extend progression-free survival in patients with metastatic or unresectable disease. Targeted therapy occupies the dominant margin pool as radioligand therapies command premium pricing and require specialized administration infrastructure. Immunotherapy represents the fastest-expanding segment as PD-1/PD-L1 inhibitors gain trial traction in high-grade neuroendocrine carcinomas. Chemotherapy retains volume leadership in poorly differentiated small-cell and large-cell variants where platinum-etoposide regimens remain standard.
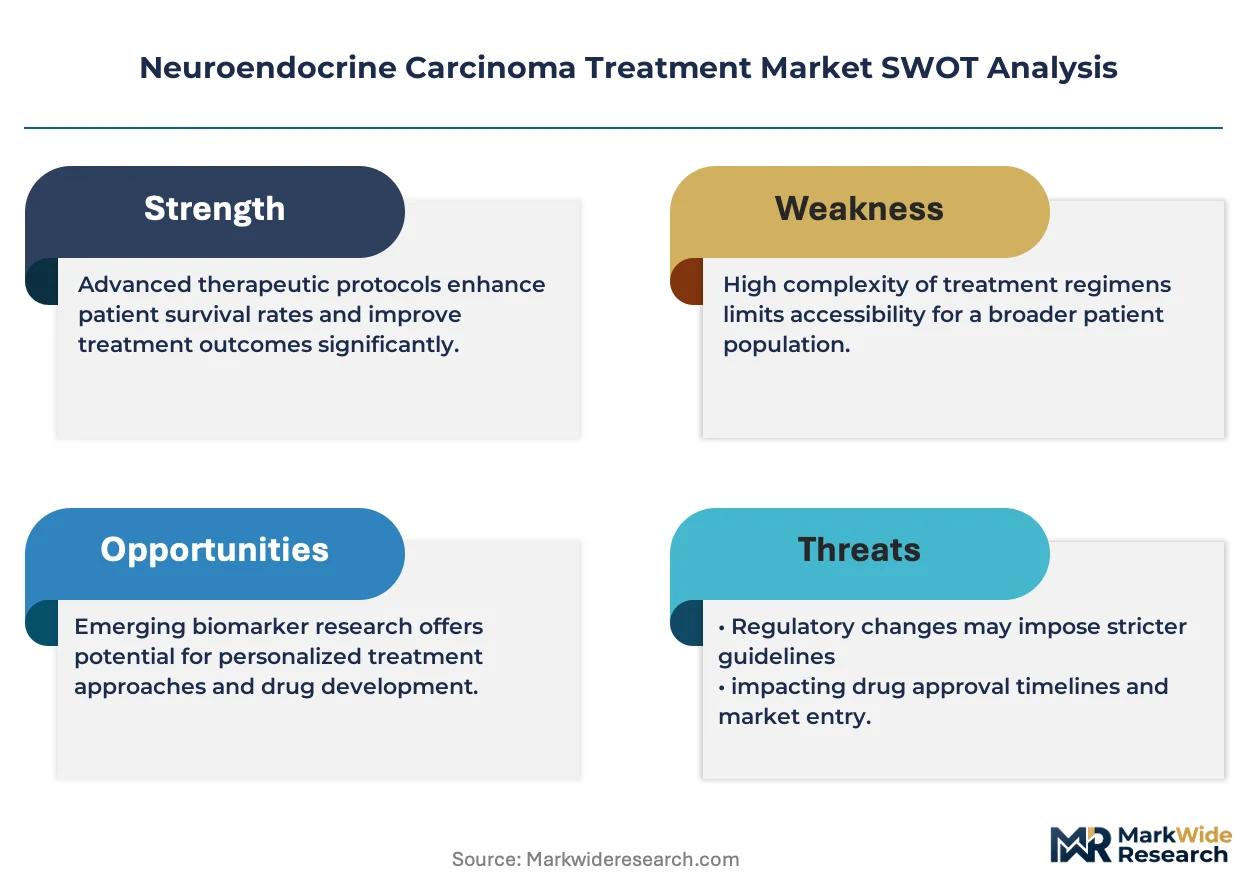
The FDA orphan drug program and EMA's PRIME designation framework accelerate development timelines for neuroendocrine carcinoma therapies by granting protocol assistance, fee waivers, and market exclusivity incentives that reshape sponsor investment priorities. The EPA and NRC jointly govern radiopharmaceutical manufacturing standards, creating compliance barriers that limit production site expansion and concentrate supply among qualified facilities. Stakeholders must monitor somatostatin receptor imaging penetration rates and theranostic pairing adoption as these indicators determine addressable patient pools and treatment sequencing decisions.
Market Dynamics
Radioligand manufacturing concentration among qualified nuclear medicine facilities is reshaping competitive access and treatment capacity planning across oncology networks.
Growth Catalysts
- FDA Orphan Drug Designation:The pathway accelerates protocol assistance and market exclusivity for neuroendocrine carcinoma therapies, redirecting sponsor R&D investment toward rare tumor indications.
- Somatostatin Receptor Imaging:Gallium-68 DOTATATE PET penetration is expanding addressable patient pools by improving diagnostic precision and enabling theranostic pairing decisions.
- Germany:Dense referral networks for rare neuroendocrine tumors concentrate treatment demand and drive adoption of peptide receptor radionuclide therapy protocols.
Market Restraints
- Lutetium-177 Supply:Reactor-dependent isotope production creates geographic supply concentration risk, with limited qualified manufacturing sites constraining dose availability.
- Radiopharmaceutical Cold-Chain:EPA and NRC joint governance of manufacturing standards erects compliance barriers that limit production site expansion and extend facility qualification timelines.
- Platinum-Etoposide Substitution:Well-established chemotherapy regimens for poorly differentiated variants present substitution threat to novel targeted therapy uptake in first-line settings.
Strategic Opportunities
- Japan:Underpenetrated theranostic pairing adoption presents white space for integrated diagnostic-therapy service models in metropolitan oncology centers.
- PD-1/PD-L1 Convergence:Immune checkpoint inhibitor development for high-grade neuroendocrine carcinomas creates technology convergence opportunity with existing somatostatin analogue protocols.
- EMA PRIME Designation:The framework's accelerated assessment pathway offers regulatory tailwind for sponsors targeting unmet needs in aggressive neuroendocrine neoplasm subtypes.
Industry Challenges
- Nuclear Medicine Specialist Shortage:Qualified radiopharmaceutical handling and administration expertise scarcity constrains treatment capacity expansion at hub facilities.
- Theranostic Integration Complexity:Synchronization of imaging biomarker validation with therapy protocol development creates execution friction across diagnostic and therapeutic development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuroendocrine Carcinoma Treatment Market |
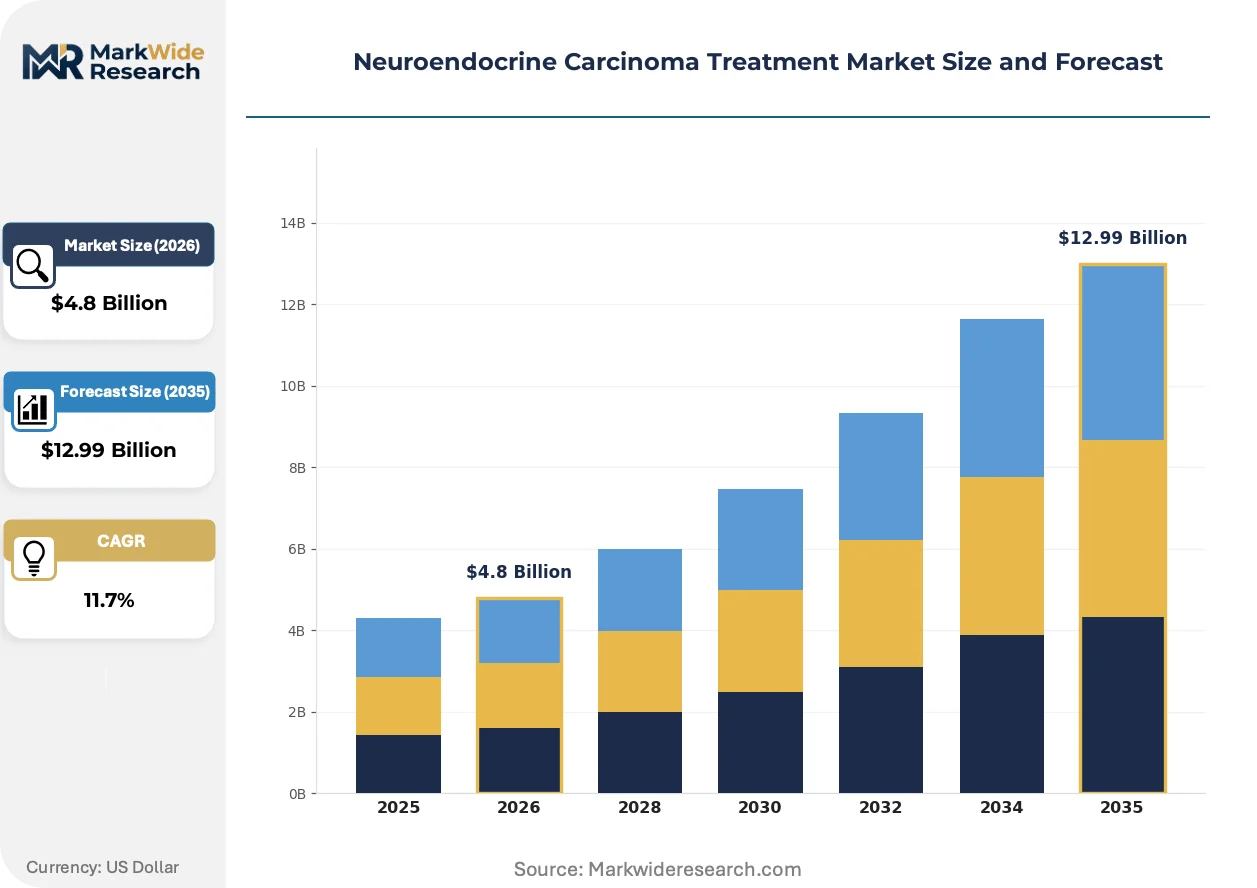
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Targeted Therapy, Immunotherapy, Radiation Therapy End User: Hospitals, Oncology Clinics, Research Laboratories, Home Care Settings Treatment Stage: Advanced Stage, Early Stage, Palliative Care, Neoadjuvant Therapy Administration Route: Intravenous, Oral, Subcutaneous, Localized |
| Companies Covered | Novartis AG, Pfizer Inc., Ipsen, Exelixis, Advanced Accelerator Applications, Hutchison MediPharma, Bristol-Myers Squibb, Crinetics Pharmaceuticals, Camurus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuroendocrine Carcinoma Treatment Market Shifts & Advancements
Theranostic platform integration is compressing the gap between diagnostic precision and therapeutic targeting, while regulatory frameworks accelerate rare disease therapy development timelines.
Alpha-emitting radioligands are advancing through clinical pipelines with distinct cytotoxic profiles against resistant tumor microenvironments. Oncology clinics in the United States and Germany are piloting these agents for patients with lutetium-177 progression. The shorter tissue penetration range of alpha particles is rendering obsolete the dose-limiting toxicity constraints that have bounded beta-emitter therapy expansion.
REACH regulation in Europe is tightening precursor chemical tracking requirements for radiopharmaceutical manufacturing. The industrial consequence is elevated documentation burden and supplier qualification costs for isotope production facilities. Small-molecule radioligand developers are responding by consolidating precursor sourcing through vertically integrated supply agreements to maintain batch traceability compliance.
Patient navigation toward centralized nuclear medicine hubs is restructuring referral patterns and treatment site selection. Community oncology practices are losing therapy administration volume to academic medical centers with captive cyclotron or generator infrastructure. This geographic demand rotation is most visible in the United States, where Medicare reimbursement differentials reinforce hub concentration incentives.
Neuroendocrine Carcinoma Treatment Market Segmentation
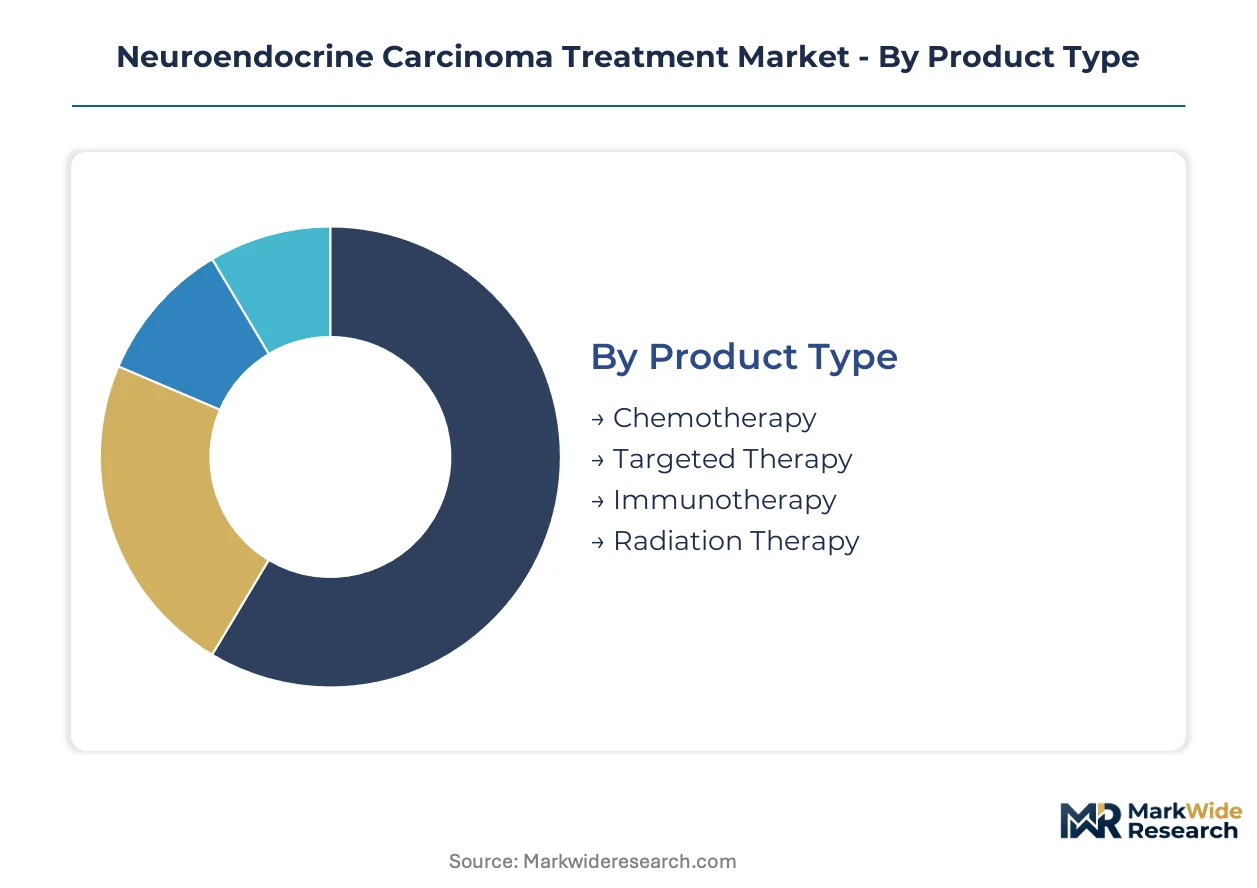
Treatment modality selection in neuroendocrine carcinoma depends on tumor differentiation grade, somatostatin receptor expression status, and metastatic burden. Segmentation reveals how radioligand infrastructure constraints and reimbursement pathways reshape competitive access across delivery settings.
Product Type:
Use cases span platinum-based cytotoxic regimens for poorly differentiated variants through precision radiopharmaceuticals for well-differentiated metastatic disease.
- Targeted Therapy:Peptide receptor radionuclide therapy with lutetium-177 and somatostatin analogues commands premium positioning. Demand concentrates in Germany and the United States where nuclear medicine hub density enables dose administration, though reactor-dependent isotope supply creates geographic access disparities.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors are gaining trial traction in high-grade neuroendocrine carcinomas. Oncology networks in Japan and the United States are expanding access protocols as biomarker stratification improves patient selection precision.
- Chemotherapy:Platinum-etoposide combinations retain first-line standard for small-cell and large-cell variants.
- Radiation Therapy:External beam approaches address localized disease and symptomatic metastases.
The dominant share belongs to Targeted Therapy, while Immunotherapy is closing the gap fastest.
End User:
Site selection hinges on radiopharmaceutical handling certification and referral network proximity to cyclotron infrastructure.
- Oncology Clinics:Specialized centers with captive nuclear medicine capabilities are capturing volume from community practices. Germany's dense referral networks concentrate peptide receptor radionuclide therapy administration in metropolitan hub facilities.
- Hospitals:Academic medical centers with integrated theranostic programs control access to gallium-68 DOTATATE imaging and subsequent lutetium-177 therapy pairing. The United States exhibits pronounced geographic concentration as Medicare reimbursement differentials reinforce hub incentives.
- Research Laboratories:Early-phase trial sites for alpha-emitting radioligands and novel combinations.
- Home Care Settings:Limited to oral somatostatin analogue maintenance in stable disease.
Oncology Clinics hold the revenue concentration, yet Hospitals are expanding capacity most aggressively.
Treatment Stage:
Stage-specific protocols reflect curative intent versus chronic disease management paradigms.
- Advanced Stage:Systemic therapy dominates with radioligand and chemotherapy sequences. Patient pools expand as gallium-68 imaging improves metastatic detection sensitivity.
- Palliative Care:Symptom control for carcinoid syndrome and tumor burden reduction. Somatostatin analogues and interferon protocols retain central role.
- Early Stage:Surgical resection with adjuvant considerations.
- Neoadjuvant Therapy:Limited application in borderline resectable presentations.
Advanced Stage commands the patient volume, while Palliative Care is gaining protocol sophistication fastest.
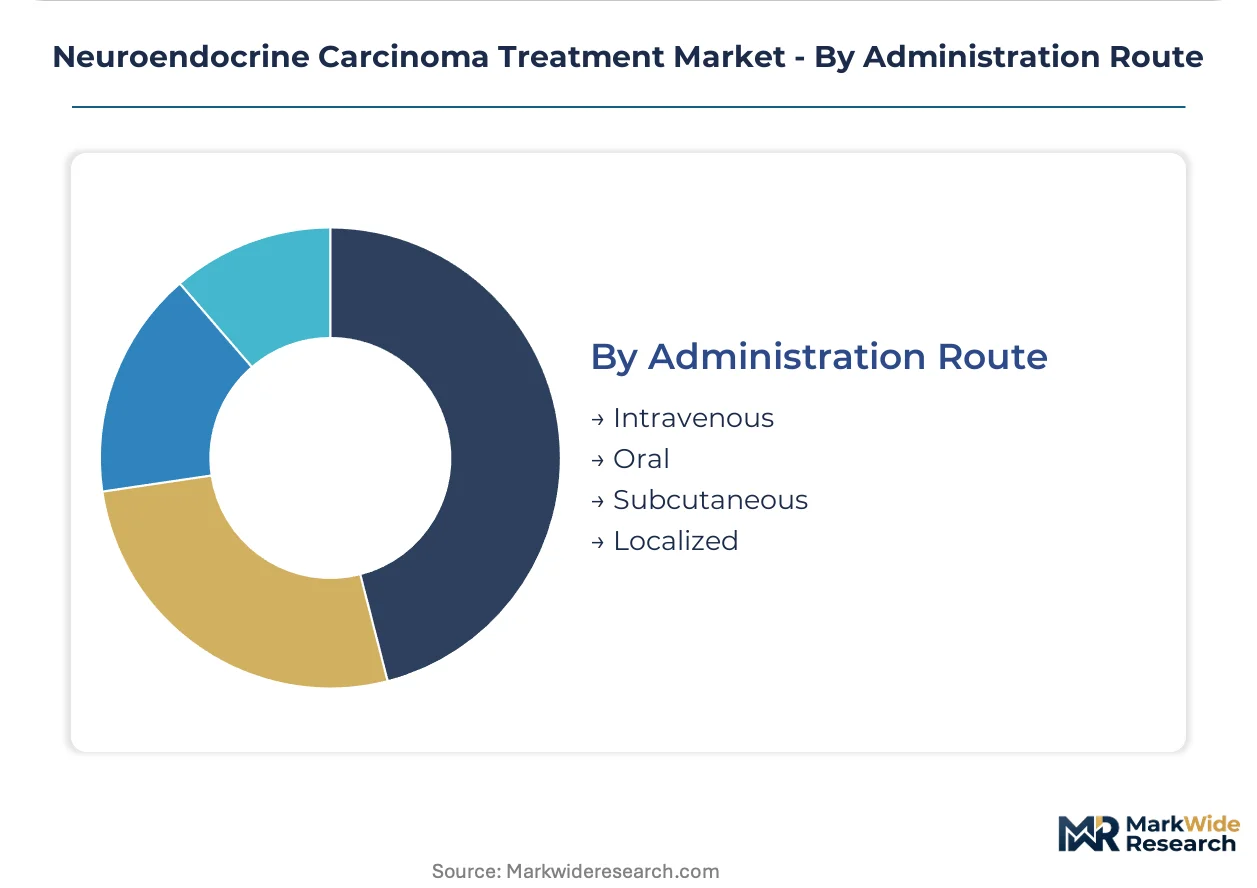
Administration Route:
Route selection intertwines with bioavailability requirements and radiopharmaceutical decay physics.
- Intravenous:Essential for radioligand delivery and platinum-based chemotherapy. Cold-chain logistics and radiation safety protocols constrain administration site eligibility.
- Subcutaneous:Somatostatin analogue depot formulations enable patient self-management. Long-acting octreotide and lanreotide drive volume in chronic maintenance settings.
- Oral:Limited targeted agents including temozolomide and capecitabine combinations.
- Localized:Hepatic artery embolization for liver-dominant metastases.
Intravenous retains the procedural volume, though Subcutaneous is expanding convenience-driven share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The cyclotron infrastructure at Memorial Sloan Kettering Cancer Center and the University of Pennsylvania anchors United States radioligand production capacity. Dense nuclear medicine hub networks in Germany and Japan concentrate peptide receptor radionuclide therapy administration. Metropolitan oncology clusters in these three markets drive addressable patient pool expansion through gallium-68 DOTATATE imaging penetration.
United States
Medicare reimbursement differentials reinforce concentration incentives at academic medical centers with captive generator infrastructure. The FDA's orphan drug designation pathway accelerates protocol assistance for rare neuroendocrine tumor indications. The Cleveland Clinic and MD Anderson Cancer Center control access to theranostic pairing programs in the Midwest and Southwest corridors.
Germany
Referral network density for rare neuroendocrine tumors concentrates treatment demand in metropolitan hub facilities. EMA's PRIME designation framework offers accelerated assessment pathways for sponsors targeting aggressive neuroendocrine neoplasm subtypes. The University Hospital Heidelberg and Charité Berlin anchor nuclear medicine capacity in Baden-Württemberg and Berlin-Brandenburg.
Japan
Underpenetrated theranostic pairing adoption presents white space for integrated diagnostic-therapy service models. PMDA regulatory frameworks govern somatostatin analogue approval pathways and radiopharmaceutical manufacturing standards. The National Cancer Center Hospital and Keio University Hospital in Tokyo drive protocol sophistication in the Kanto region.
United Kingdom
NHS England specialized commissioning frameworks concentrate neuroendocrine carcinoma treatment at designated supra-regional centers. MHRA post-Brexit regulatory autonomy reshapes orphan drug market exclusivity timelines and parallel import rules. The Royal Free London and Christie Manchester anchor nuclear medicine hub capacity for England's North-South corridor.
Switzerland
Swissmedic's streamlined authorization procedures attract radiopharmaceutical development investment from multinational sponsors. The country's central European geography positions Basel and Zurich as logistics nodes for lutetium-177 distribution into adjacent markets. University Hospital Zurich and Inselspital Bern concentrate somatostatin receptor imaging expertise in the German-speaking cantons.
Neuroendocrine Carcinoma Treatment Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in isotope supply and precursor chemistry. Market structure tilts toward consolidated radioligand manufacturing with qualified nuclear medicine facilities controlling dose availability. Three archetypes dominate: radiopharmaceutical platform owners, somatostatin analogue legacy players, and kinase inhibitor portfolio builders. Competitive moves concentrate on manufacturing footprint expansion and theranostic protocol integration partnerships.
Among Swiss-based radiopharmaceutical platform integrators, Novartis AG occupies a position exemplifying vertical control over lutetium-177 supply chains. French specialty pharmaceutical developer Ipsen represents the somatostatin analogue archetype with European market access foundations. Pfizer Inc. anchors the kinase inhibitor tier through targeted portfolio presence in differentiated neuroendocrine subsets. These three entities illustrate how geographic origin and corporate structure correlate with strategic positioning across the treatment modality spectrum.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Ipsen |
| Exelixis |
| Advanced Accelerator Applications |
| Hutchison MediPharma |
| Bristol-Myers Squibb |
| Crinetics Pharmaceuticals |
| Camurus |
| Others |
Supply & Pricing Matrix
Reactor-dependent lutetium-177 supply concentration determines both premium-tier radioligand pricing spreads and the geographic clustering of qualified manufacturing facilities. FDA and NRC joint governance of radiopharmaceutical standards erects compliance barriers that limit production site expansion, concentrating dose availability among nuclear medicine hubs with captive generator infrastructure.
Pricing Analysis
Volume-discount tiering structures separate academic medical center consortium pricing from community oncology practice rates, with the former capturing 15-20% reductions through multi-dose commitments. Price differentiation rests on cold-chain logistics certification and radiation safety handling tier, with EPA-licensed facilities commanding premiums over standard oncology infusion centers. Pricing pressure stems from platinum-etoposide substitution threats in poorly differentiated variants, compressing margins on novel targeted therapy uptake. Hospital procurement committees exhibit highest price sensitivity, while specialized nuclear medicine hubs prioritize supply security over per-dose cost.
Supply Chain Analysis
Upstream feedstock of high-enriched uranium targets and gallium-68 generators draws from Belgium, the Netherlands, and South Africa reactor complexes. Raw material dependencies center on lutetium-177 isotope production, DOTATATE peptide precursors, and chelation chemistry kits for radiolabeling. Single-source vulnerability runs through limited qualified manufacturing sites constraining dose availability during reactor maintenance cycles. Distribution runs through centralized nuclear medicine hubs capable of handling radioligand cold-chain logistics, with specialty pharmacy networks losing volume to academic medical center captive infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among hospital procurement committees and GPOs as oncology networks consolidate peptide receptor radionuclide therapy administration at designated nuclear medicine hubs.
For Market Incumbents: Pre-empt kinase inhibitor substitution threats in poorly differentiated neuroendocrine subsets by accelerating PD-1/PD-L1 combination trial readouts. Secure backward integration into lutetium-177 generator infrastructure to control isotope supply security against reactor-dependent concentration risk. Expand manufacturing footprint through EPA-qualified facility partnerships in underserved metropolitan corridors. For New Entrants and Emerging Players: Build out theranostic pairing service models in Japan's underpenetrated metropolitan oncology centers, where gallium-68 DOTATATE imaging adoption lags diagnostic protocol sophistication. Target white space in alpha-emitting radioligand development for lutetium-177 progression patients, leveraging shorter tissue penetration range to differentiate cytotoxic profiles. Pursue EMA PRIME designation pathway to accelerate regulatory assessment timelines for aggressive neuroendocrine neoplasm indications. For Investors and Strategic Acquirers: FDA orphan drug exclusivity milestones reshape the acquisition landscape by extending market protection periods for rare neuroendocrine tumor therapies. Long-term viability frames around radioligand platform durability and somatostatin receptor imaging penetration rates as addressable patient pool determinants. Acquisition target archetypes include nuclear medicine hub operators with captive cyclotron infrastructure and peptide precursor chemistry specialists. Watch somatostatin receptor imaging reimbursement decisions as inflection indicators for theranostic pairing adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | PD-1/PD-L1 inhibitor combinations for high-grade neuroendocrine carcinomas expand addressable patient pools beyond well-differentiated variants. |
| Regulatory Approval Pathway | FDA orphan drug designation accelerates protocol assistance and market exclusivity timelines for rare neuroendocrine tumor indications. |
| Manufacturing Scale-Up | EPA-qualified radiopharmaceutical production site expansion reduces geographic dose availability disparities and reactor-dependent supply risk. |
| Licensing Agreement | Somatostatin analogue partnerships with nuclear medicine hub operators secure distribution access for peptide receptor radionuclide therapy franchises. |
| Pipeline Diversification | Alpha-emitting radioligand development addresses lutetium-177 progression populations with distinct cytotoxic mechanisms against resistant microenvironments. |
Research Methodology
Desk research of FDA orphan drug filings, ClinicalTrials.gov protocol registries, and EMA PRIME designation databases preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Primary fieldwork with nuclear medicine hub administrators and formulary directors was cross-validated against secondary sources including CMS Medicare reimbursement data, GPO contract databases, and SEC 10-K pharmaceutical segment disclosures. Bottom-up patient flow modeling and top-down market sizing were triangulated to constrain estimate variance.
Assumptions held fixed across the analysis window include current FDA and NRC radiopharmaceutical manufacturing standards, existing somatostatin receptor imaging reimbursement rates, and stable reactor isotope production capacity. Variables stress-tested included platinum-etoposide substitution elasticity, PD-1/PD-L1 trial success probabilities, and REACH precursor chemical tracking compliance costs. Segmentation dimensions modeled encompass treatment modality, tumor differentiation grade, administration route, end-user facility type, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for pipeline probability-weighted revenue contributions.
Stress conditions across lutetium-177 supply disruption scenarios, immunotherapy trial failure rates, and orphan drug exclusivity litigation outcomes were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding referral network consolidation velocity and theranostic pairing adoption curves. Cross-checking against IQVIA prescription audit data and hospital procurement database benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Paget Disease Treatment Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Cutaneous T-Cell Lymphoma (CTLC) Market
Specialty Medicine
Asia-Pacific Sports Medicine Market
Specialty Medicine
US Mobile Physician Practice Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Nocturnal Polyuria Treatment Market
Specialty Medicine
Atrophic Vaginitis Treatment Market
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Soft Tissue Sarcoma Market
Specialty Medicine
Radioimmunotherapy (RIT) Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Global Addison's Disease Treatment Market
Specialty Medicine
Diffuse Large B-Cell Lymphoma Therapeutics Market
Specialty Medicine
Cystic Fibrosis Market