
 Silicon Battery Market | 2026-2036
Silicon Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Silicon Battery Market Analysis
The silicon battery supply base is consolidating around two distinct performance tiers. Premium tier producers leverage proprietary nanostructuring to command cell-level energy density above four hundred watt-hours per kilogram. Amprius Technologies anchors this segment through its silicon nanowire architecture. Panasonic Holdings competes with established cylindrical formats adapted for partial silicon loading. LG Chem sustains scale advantages in hybrid silicon-carbon electrodes serving automotive qualification timelines.
Silicon batteries replace conventional graphite anodes with silicon-dominant active material to multiply lithium-ion storage capacity per unit mass. Manufacturing requires controlled volumetric expansion management, typically below three hundred percent during lithiation, to preserve cycle stability across five hundred to one thousand charge events. Solid-state batteries attract structural investment as their ceramic electrolytes accommodate silicon's mechanical stress without liquid decomposition. Silicon anode technology dominates current pilot production, while silicon-graphene composite formulations lead research intensity due to conductivity enhancement. Electric vehicle applications command the largest committed offtake volumes, though aerospace qualification represents the fastest margin pool expansion.
The EPA governs domestic battery material waste streams under emerging extended producer responsibility frameworks. The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations for cells placed on the European market. China's MIIT enforces GB standards for power battery safety testing, including nail penetration and thermal runaway propagation protocols. Stakeholders must monitor which jurisdiction's certification timeline becomes the binding constraint for multi-regional product launches.
Market Dynamics
The silicon battery market is compressing around a single structural tension: automotive OEMs demand four-hundred-plus watt-hour-per-kilogram cells for next-generation electric vehicle platforms, yet current manufacturing yields cannot scale nanostructured silicon anodes beyond pilot volumes without catastrophic cost inflation. This gap between performance targets and production economics is forcing simultaneous bets on hybrid silicon-carbon architectures and solid-state electrolyte integration.
Growth Catalysts
- EU Battery Regulation recycled content mandates:The regulation's phased thresholds for recovered lithium, cobalt, and nickel are pulling silicon anode chemistry forward as manufacturers seek to bypass scarce critical mineral supply chains entirely.
- Stuttgart-Munich automotive cluster qualification timelines:German OEMs are locking in silicon-dominant cell designs for 2028-2030 model year platforms, creating committed offtake volumes that de-risk capital deployment for anode material suppliers.
- Solid-state electrolyte convergence:Ceramic electrolytes from sulfide and oxide chemistries accommodate silicon's three-hundred-percent volumetric expansion without the liquid decomposition that degrades conventional lithium-ion cells.
Market Restraints
- Silane gas supply concentration:High-purity silane feedstock for silicon anode production concentrates among a handful of electronics-grade chemical suppliers, exposing cell manufacturers to input cost volatility and allocation risk.
- Cycle stability technical ceiling:Silicon anodes remain limited to five-hundred-to-one-thousand full depth-of-discharge cycles before capacity degradation, constraining warranty terms for automotive applications against graphite baselines.
- China GB standards safety testing friction:MIIT-mandated nail penetration and thermal runaway propagation protocols for power batteries impose additional certification timelines that delay multi-regional product launches.
Strategic Opportunities
- India PLI scheme for advanced cell chemistry:The production-linked incentive scheme for battery manufacturing offers twenty-five percent capex support for silicon-anode-qualified gigafactories, opening an underpenetrated geography outside Chinese supply chain dominance.
- Aerospace qualification margin pool:Electric vertical take-off and landing aircraft and regional electric aviation platforms are accepting premium pricing for silicon-anode cells that deliver the energy density-to-weight ratios required for viable flight endurance.
- Silicon-graphene composite research intensity:Laboratory-scale formulations combining silicon nanoparticles with graphene conductive networks are resolving conductivity limitations, positioning for technology convergence that bridges performance and manufacturability.
Industry Challenges
- Electrode slurry formulation talent scarcity:The specialized knowledge required to stabilize silicon particle dispersions in aqueous and solvent-based binders concentrates among a narrow cohort of materials scientists, constraining manufacturing scale-up velocity.
- Dry electrode coating capex intensity:Transitioning from conventional wet slurry coating to dry electrode processes suitable for silicon's mechanical properties requires entirely new capital equipment lines, straining balance sheets during pre-revenue qualification phases.
- UN 38.3 lithium battery certification timeline compression:The UN Manual of Tests and Criteria transport certification for prototype cells creates a binding constraint on customer sampling programs, with third-party test house queues extending six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silicon Battery Market |
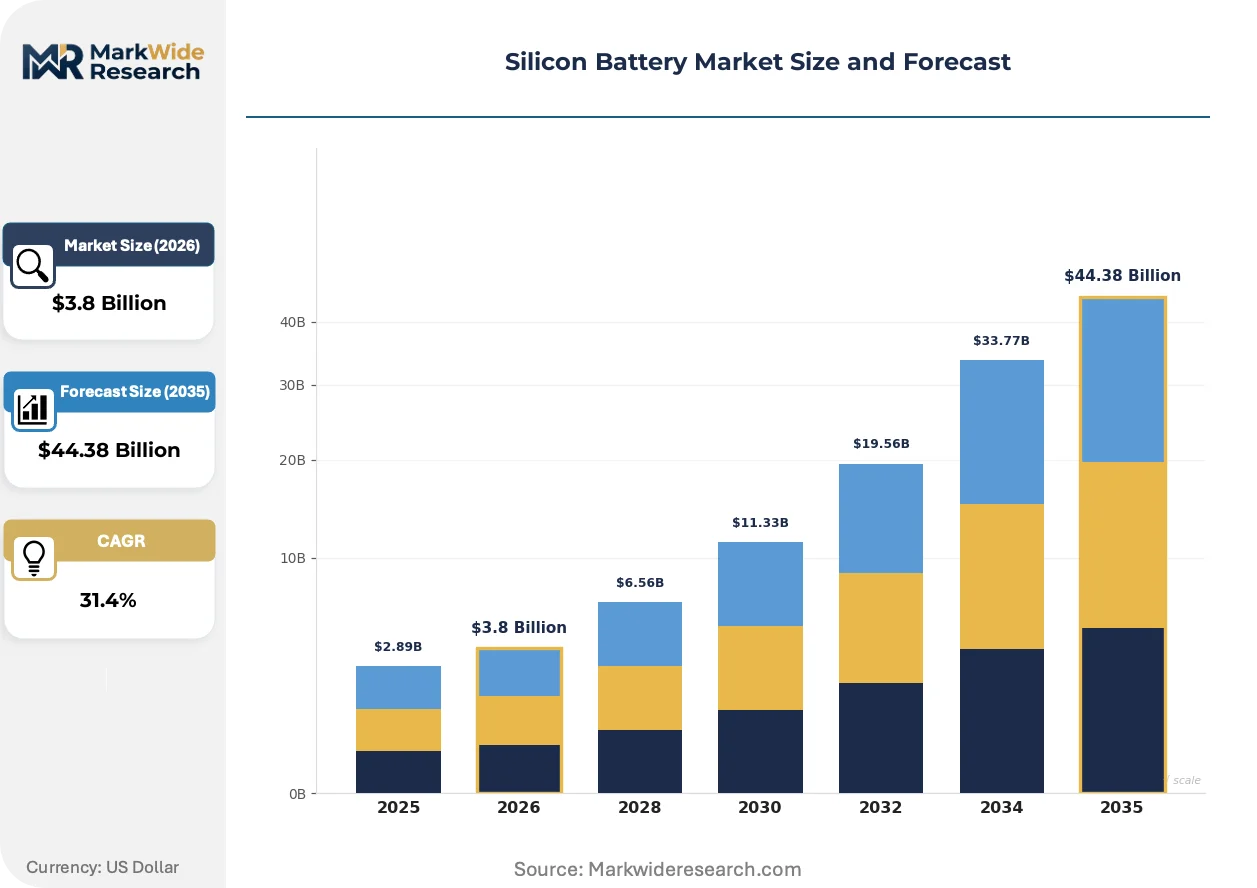
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $44.38 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thin Film Batteries, Flexible Batteries, 3D Batteries, Solid-State Batteries Technology: Silicon Anode, Nanostructured Silicon, Silicon-Graphene Composite, Silicon-Carbon End User: Consumer Electronics, Electric Vehicles, Grid Storage, Aerospace Application: Portable Devices, Renewable Energy Storage, Automotive, Smart Grids |
| Companies Covered | Enovix, Panasonic Holdings, Amprius Technologies, LG Chem, Samsung SDI, Sila Nanotechnologies, Nexeon, Contemporary Amperex Technology, Group14 Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silicon Battery Market Emerging Trajectories
Silicon battery technology is fragmenting along two parallel development tracks: near-term hybrid architectures that incrementally displace graphite, and long-term solid-state platforms that fully exploit silicon's theoretical capacity. The competitive boundary between these tracks is shifting faster than supply chains can adapt.
Pre-lithiation techniques are decentralizing manufacturing risk by compensating for first-cycle capacity loss in silicon anodes without requiring cell-level formation protocols. Korean cell manufacturers are adopting vapor-deposited lithium metal layers on anode surfaces to accelerate automotive qualification timelines. This approach is compressing the competitive window for pure-play silicon nanowire architectures that rely on proprietary formation cycling.
REACH substance restriction pre-notifications for fluorinated electrolyte additives are forcing reformulation of liquid electrolyte systems used in hybrid silicon-graphite cells. The European Chemicals Agency's scrutiny of per- and polyfluoroalkyl substances is accelerating migration to localized high-concentration electrolyte salts. German electrolyte suppliers are responding with sulfone-based solvent systems that maintain ionic conductivity without restricted fluorinated compounds.
Automotive cell procurement is consolidating around long-term offtake agreements with embedded price-volume flex mechanisms, displacing spot-market purchasing for silicon-anode-qualified volumes. Battery makers are accepting take-or-pay structures that guarantee minimum volumes in exchange for dedicated production lines. This shift is most visible in the German automotive cluster, where OEMs are locking in ten-to-fifteen-year supply commitments to secure allocation from constrained anode material capacity.
Silicon Battery Market Segmentation
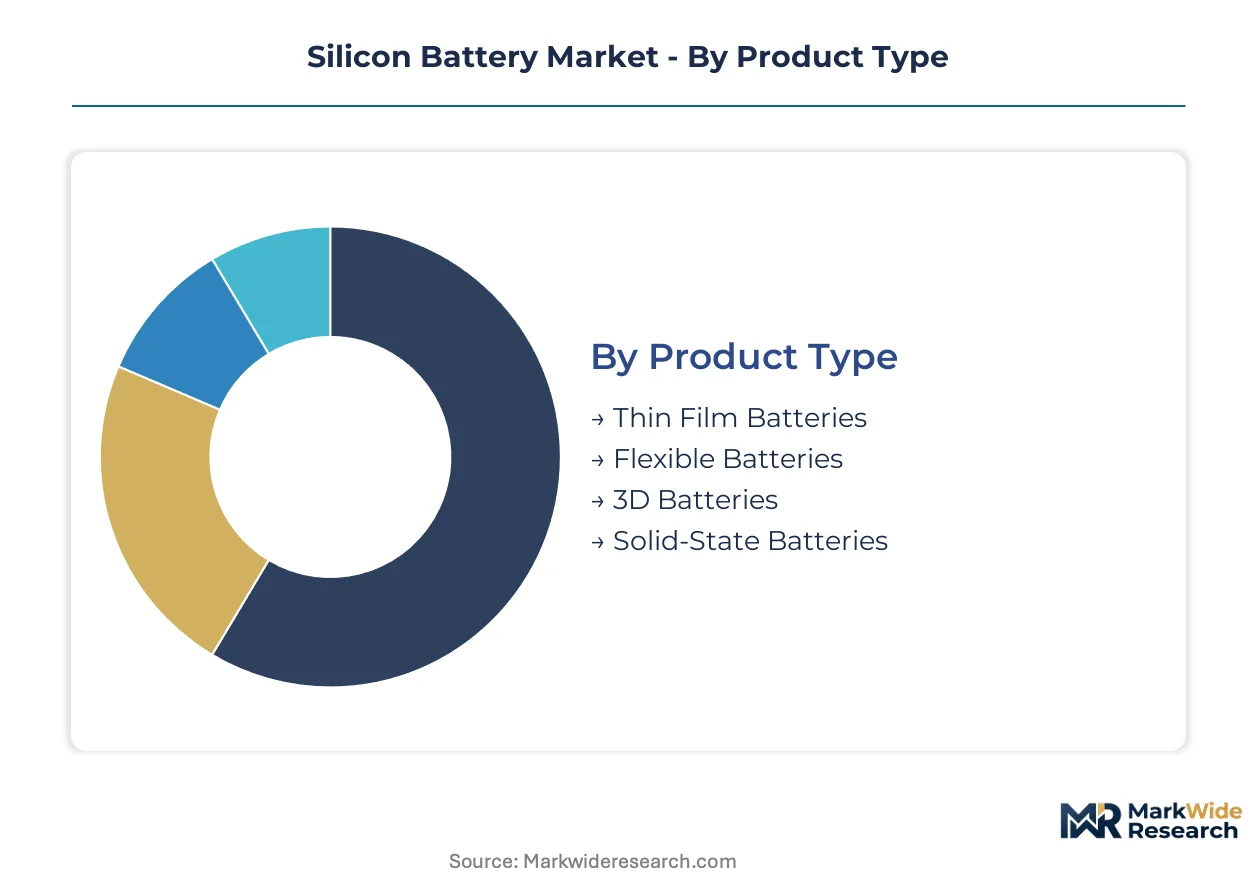
Silicon battery segmentation reflects divergent maturity curves across form factors and integration depths. Cell architecture choices determine which applications unlock volume scale versus margin capture.
Product Type:
Form factor selection maps directly to mechanical integration requirements, separating standalone power sources from embedded energy systems.
- Solid-State Batteries:Ceramic electrolyte architectures accommodate silicon anode expansion without liquid decomposition. German automotive OEMs in Stuttgart and Munich are prioritizing solid-state qualification for 2028-2030 electric vehicle platforms. The EU Battery Regulation's recycled content mandates accelerate development by bypassing critical mineral supply chains.
- Flexible Batteries:Polymer substrate designs enable conformal mounting in wearable electronics and medical patches. South Korean consumer electronics manufacturers drive pilot volumes for foldable device integration. Manufacturing yields remain constrained by electrode delamination during repeated flex cycling.
- Thin Film Batteries:Micro-scale energy storage for sensor networks and RFID applications.
- 3D Batteries:Architectured electrodes multiplying active surface area per footprint.
Solid-state batteries lead volumes today; flexible batteries are gaining share fastest.
Technology:
Active material engineering determines the trade-off between energy density multiplication and manufacturing scalability.
- Silicon Anode:Pure silicon active material delivers theoretical capacity ten times graphite baselines. Volumetric expansion management below three hundred percent during lithiation preserves cycle stability. EPA emerging frameworks for extended producer responsibility are shaping domestic waste stream protocols.
- Silicon-Carbon:Hybrid electrodes blending silicon nanoparticles with graphite matrices balance performance and process compatibility. LG Chem sustains scale advantages serving automotive qualification timelines. China's MIIT GB standards for nail penetration testing impose additional certification friction.
- Nanostructured Silicon:Proprietary architectures from silicon nanowire to porous particle designs.
- Silicon-Graphene Composite:Conductive network formulations resolving silicon's intrinsic conductivity limitations.
Silicon-carbon hybrids dominate current production; nanostructured variants are climbing the fastest.
End User:
Customer segmentation separates volume-driven automotive procurement from premium aerospace qualification pathways.
- Electric Vehicles:Automotive OEMs demand four-hundred-plus watt-hour-per-kilogram cells for next-generation platforms. Committed offtake volumes from Germany's Stuttgart-Munich cluster de-risk capital deployment for anode suppliers. Solid-state electrolyte convergence accommodates silicon's mechanical stress without liquid decomposition.
- Aerospace:Electric vertical take-off and landing aircraft and regional electric aviation platforms accept premium pricing for energy density-to-weight ratios. The FAA governs certification timelines for aviation battery systems under emerging airworthiness directives.
- Consumer Electronics:Smartphone and laptop manufacturers seeking incremental capacity improvements.
- Grid Storage:Utility-scale installations prioritizing cycle life over energy density.
Electric vehicles anchor current demand; aerospace represents the steepest expansion trajectory.
Application:
Use case segmentation distinguishes mobility systems from stationary infrastructure based on duty cycle and packaging constraints.
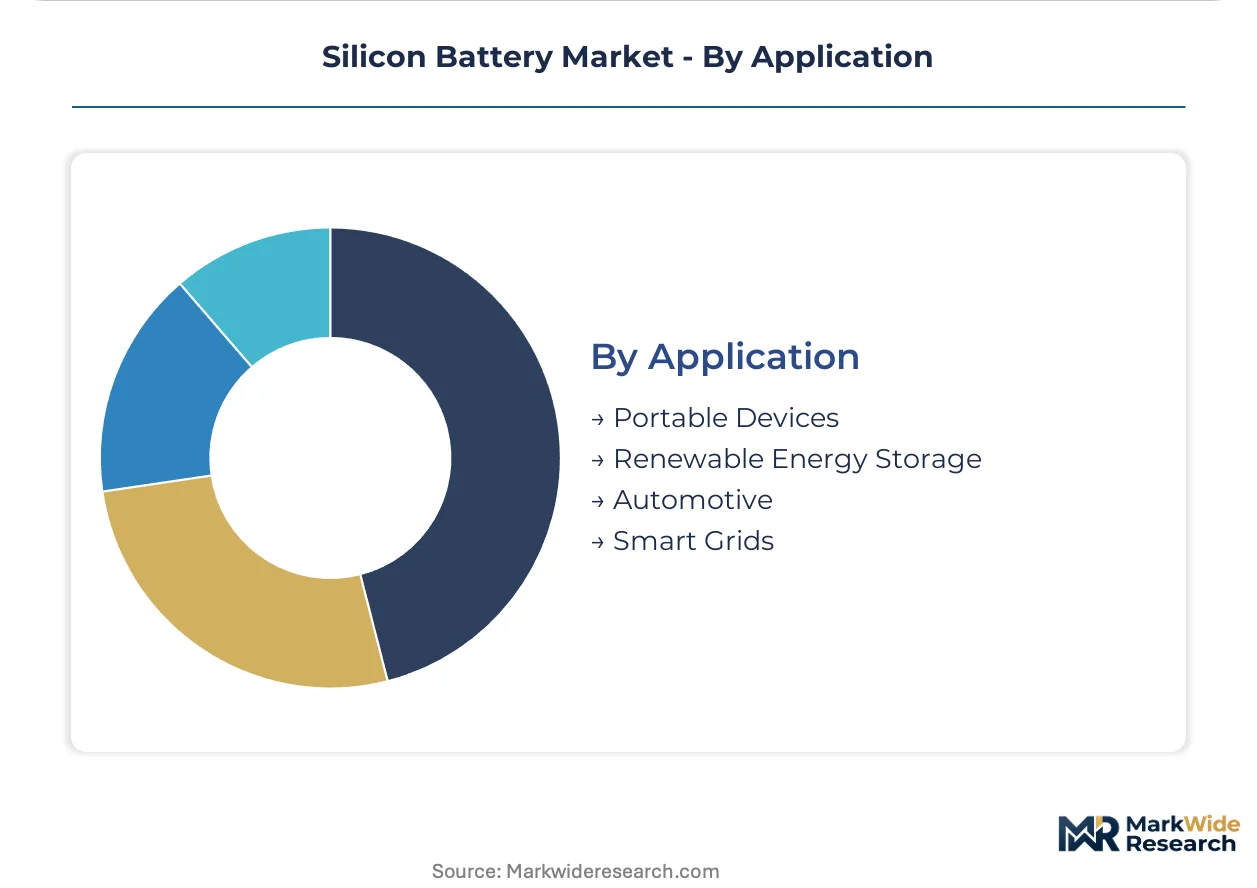
- Automotive:Traction battery systems for passenger and commercial electric vehicles. Long-term offtake agreements with embedded price-volume flex mechanisms are displacing spot-market purchasing. German OEMs lock in ten-to-fifteen-year supply commitments to secure allocation from constrained anode capacity.
- Portable Devices:Smartphones, laptops, and tablets requiring compact energy storage. REACH substance restrictions for fluorinated electrolyte additives force reformulation of liquid electrolyte systems. German suppliers respond with sulfone-based solvent systems maintaining ionic conductivity.
- Renewable Energy Storage:Solar and wind pairing for intermittency management.
- Smart Grids:Distributed energy resources enabling grid flexibility services.
Automotive applications command the largest committed volumes; portable devices show the quickest share gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands the largest installed cell manufacturing base for silicon-anode-qualified production, while Germany concentrates the most advanced automotive qualification activity for 2028-2030 platform integration.
China
CATL and BYD are scaling silicon-carbon hybrid electrode production for domestic electric vehicle lines. MIIT enforces GB standards for nail penetration and thermal runaway propagation testing that add certification friction for export-bound cells. The Yangtze River Delta cluster around Shanghai and Suzhou hosts the densest concentration of anode material pilot lines.
Germany
BMW and Mercedes-Benz have locked in ten-to-fifteen-year offtake commitments for silicon-dominant cells. The EU Battery Regulation mandates recycled content thresholds and carbon footprint declarations that favor silicon chemistry over critical mineral-dependent alternatives. The Stuttgart-Munich corridor anchors European automotive qualification timelines for solid-state silicon platforms.
United States
Tesla and Rivian are driving demand for four-hundred-plus watt-hour-per-kilogram cells in premium electric vehicle segments. The EPA is developing extended producer responsibility frameworks for battery material waste streams that will shape domestic recycling infrastructure. The San Francisco Bay Area concentrates venture-funded silicon nanowire startups alongside Lawrence Berkeley National Laboratory research programs.
South Korea
Hyundai and Kia are accelerating silicon-anode adoption through partnerships with domestic cell manufacturers. MFDS-equivalent battery safety protocols align with UN 38.3 transport certification requirements. The Seoul Capital Area houses Samsung SDI and LG Chem headquarters where hybrid silicon-carbon electrode scale-up decisions are made.
Japan
Toyota and Honda are prioritizing solid-state silicon platforms for next-generation electric vehicle architectures. METI funding programs support pre-lithiation technique development to compress automotive qualification timelines. The Nagoya-Toyota industrial corridor concentrates ceramic electrolyte research facilities serving sulfide-based solid-state programs.
Silicon Battery Market Vendor Landscape
Top-tier vendors anchor premium nanostructured silicon architectures, while mid-tier players compete on hybrid silicon-carbon scale and automotive qualification speed. The supply base consolidates around two performance tiers separated by cell-level energy density thresholds. Specialist archetypes include pure-play silicon nanowire innovators, diversified chemical conglomerates with electrode material divisions, and solid-state electrolyte developers integrating silicon anodes. Capacity expansion and strategic partnerships dominate competitive moves as firms secure silane gas supply and lock in automotive offtake.
Among US-based technology developers, Amprius Technologies and Sila Nanotechnologies occupy distinct positions within the premium-performance archetype. Panasonic Holdings exemplifies the diversified industrial conglomerate model with established cylindrical cell formats. Korean manufacturers Samsung SDI and LG Chem sit within the scale-driven tier serving automotive qualification timelines.
| Leading Market Players |
|---|
| Enovix |
| Panasonic Holdings |
| Amprius Technologies |
| LG Chem |
| Samsung SDI |
| Sila Nanotechnologies |
| Nexeon |
| Contemporary Amperex Technology |
| Group14 Technologies |
| Others |
Supply Flow & Price Mechanics
Specialized electrode slurry formulation scientists concentrated in South Korea's Seoul Capital Area and Germany's Stuttgart corridor command compensation premiums that widen spreads between premium nanostructured silicon tiers and commodity hybrid electrodes. Labor-cost differentials between these talent clusters and emerging manufacturing hubs in India feed directly into pricing-tier stratification across automotive qualification timelines.
Pricing Analysis
Bundled long-term offtake agreements with embedded formation-cycling services dominate premium tiers, while unbundled anode material supply contracts serve mid-market hybrid silicon-carbon procurement. Price differentiation separates nanostructured architectures warranting above-four-hundred watt-hour-per-kilogram performance from silicon-carbon blends qualified for standard electric vehicle platforms. Cost compression in hybrid tiers is intensifying because LG Chem and Samsung SDI are scaling solvent-based coating capacity faster than demand absorption. Automotive OEMs in Germany's Stuttgart-Munich cluster show least price sensitivity due to platform energy density requirements, while Indian PLI-scheme entrants face acute margin pressure on initial volumes.
Supply Chain Analysis
Freight costs for silane gas feedstock concentrate supply chain leverage among semiconductor-grade chemical suppliers in Japan, Germany, and the United States. Raw material dependencies center on high-purity silane, lithium metal for pre-lithiation layers, and ceramic electrolyte precursors from sulfide and oxide chemistries. Single-source vulnerability for electronics-grade silane exposes cell manufacturers to allocation risk during semiconductor demand spikes. Distribution runs through qualified anode material suppliers to dedicated cell production lines under take-or-pay structures, bypassing spot-market liquidity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The silicon battery market reads as a late-cycle quality story where automotive OEM procurement is filtering toward qualified suppliers capable of four-hundred-plus watt-hour-per-kilogram sustained output. This demand-shift toward premium specifications compresses margins for unqualified hybrid-tier producers while concentrating returns among nanostructured architecture holders.
For Market Incumbents: Lock in silane gas supply through backward integration into high-purity chemical production or captive offtake agreements with Japanese and German feedstock suppliers. Defend position against solid-state electrolyte convergence by accelerating pre-lithiation technique deployment to compress automotive qualification timelines before ceramic electrolyte platforms reach scale. For New Entrants and Emerging Players: Capture aerospace qualification pathways for electric vertical take-off and landing applications where premium pricing tolerates lower initial manufacturing yields. Target India's PLI-scheme geography for silicon-anode-qualified gigafactory deployment, leveraging twenty-five percent capex support outside Chinese supply chain dominance. Lead with silicon-graphene composite formulations that resolve conductivity limitations without requiring proprietary nanowire infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among dry electrode coating equipment specialists stranded in pre-revenue phases before automotive qualification completion. Long-term viability over the next decade hinges on solid-state electrolyte convergence timelines and whether sulfide or oxide ceramic platforms achieve manufacturing scale first. Watch for UN 38.3 certification queue compression as the signal indicating prototype cell sampling velocity is accelerating beyond third-party test house capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Silane Gas Supply Security | Backward integration into high-purity feedstock production reduces allocation risk from Japanese and German chemical suppliers. |
| Solid-State Electrolyte Convergence | Ceramic sulfide and oxide platforms accommodate silicon volumetric expansion without liquid decomposition pathways. |
| Pre-Lithiation Technique Deployment | Vapor-deposited lithium metal layers compress automotive qualification timelines for Korean cell manufacturers. |
| India PLI Gigafactory Qualification | Production-linked incentives open silicon-anode manufacturing outside Yangtze River Delta supply chain concentration. |
| Aerospace Certification Pathway | FAA airworthiness directives for electric aviation platforms accept premium cells delivering energy density-to-weight ratios. |
Methodological Framework
Direct dialogue with electrode material R&D directors, automotive cell procurement officers, Tier 1 supplier quality engineers, and solid-state electrolyte startup founders grounded qualitative findings in operational reality. Secondary validation drew from EPA emerging framework disclosures, MIIT GB standard publication records, EU Battery Regulation delegated acts, and SEC filings from listed cell manufacturers. Bottom-up capacity build-out models triangulated against top-down automotive platform energy density requirements across the analysis window.
Segmented outputs by product type, active material technology, end-use application, and geographic production cluster informed the projection horizon. CAGRs derived from automotive offtake commitment volumes, aerospace qualification timeline assumptions, and solid-state electrolyte manufacturing yield curves. Forecast inputs incorporated silane gas supply elasticity, electrode slurry formulation talent availability, and UN 38.3 certification queue dynamics.
MIIT safety testing protocol revisions, REACH substance restriction enforcements, and solid-state electrolyte manufacturing yield breakthroughs are the dominant revision risks to modeled outputs. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Smart Battery Charger Market
Batteries
Dry Cell Battery Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
ASEAN Countries Electric Vehicle Battery Electrolyte Market
Batteries
Southeast Asia Battery Market
Batteries
Europe Lead-Acid Battery Market
Batteries
Nuclear Battery Sales Market
Batteries
Middle-East and North Africa Rechargeable Battery Market
Batteries
Lithium Carbon Monofluoride Battery Market
Batteries
Lead Acid Battery Market
Batteries
Carbon Foam Battery Market
Batteries
Portable Battery Station Market
Batteries
Secondary Battery Market
Batteries
Zinc Ion Batteries Market
Batteries
Marine Powerboat Battery Market
Batteries
Global Lithium Titanate (LTO) Batteries Market