
 FORTELION Battery Module Market | 2026-2036
FORTELION Battery Module Market Size, Share, and Industry Trends Forecast 2026-2036
FORTELION Battery Module Market Insights
Solid-state electrolyte integration is rewriting the competitive architecture of battery module assembly. Murata Manufacturing Co., Ltd. leverages its ceramic capacitor heritage to anchor high-reliability cell packaging for industrial applications. Samsung SDI Co., Ltd. competes through vertical control over separator and electrode production. LG Energy Solution differentiates with scaled prismatic cell-to-pack architectures for automotive OEMs.
FORTELION Battery Modules are lithium-ion power units built around olivine-type lithium iron phosphate cathodes, typically operating at nominal voltages of 3.2V with enhanced thermal stability compared to nickel-cobalt alternatives. These modules serve primarily as electrochemical energy reservoirs in systems where cycle longevity and safety margins outweigh raw energy density requirements. Cylindrical Cells dominate current production volumes due to established winding equipment and quality control protocols inherited from consumer electronics supply chains. Electric Vehicles command the largest application share as OEMs phase in cobalt-reduced chemistries to meet due diligence requirements. Solid-State technology represents the fastest-growing R&D trajectory, though commercial module integration remains constrained by interfacial impedance challenges.
Japan's METI enforces stringent battery safety benchmarks under the Electrical Appliance and Material Safety Act, directly shaping cell design rules for domestic module suppliers. China's SAMR administers GB/T standards that gate market access for lithium-ion modules deployed in energy storage and electric mobility. The EU Battery Regulation mandates carbon footprint disclosure and recycled content quotas that will restructure upstream material sourcing. Stakeholders must monitor how solid-state manufacturing scale-up alters the balance between cell format standardization and application-specific customization.
Market Dynamics
Solid-state electrolyte integration is compressing traditional module assembly timelines as automakers demand cobalt-free chemistries with higher thermal thresholds. This technological pivot reconfigures supplier relationships around ceramic processing capabilities and dry electrode coating equipment.
Growth Catalysts
- Electric vehicle powertrain electrification:Automakers in Germany, Japan, and China are phasing nickel-cobalt-manganese cathodes out of premium battery-electric vehicle lines to satisfy due diligence sourcing requirements.
- METI safety certification alignment:Japan's Electrical Appliance and Material Safety Act creates procurement preference for olivine-type lithium iron phosphate modules in industrial energy storage installations.
- Shenzhen-Nagoya manufacturing corridor:Concentrated cathode precursor refining and cell winding equipment clusters reduce module assembly lead times for Asian automotive OEMs.
Market Restraints
- Graphite anode supply concentration:Spherical purified graphite for high-cycle cells depends on Heilongjiang and Shandong processing facilities with limited alternative sourcing.
- Interfacial impedance in solid-state integration:Ceramic-electrode contact resistance remains unresolved at module scale, constraining energy density gains promised by sulfide electrolyte research.
- EU Battery Regulation carbon accounting:Mandatory upstream emissions disclosure for lithium iron phosphate cathode material increases compliance overhead for non-European suppliers.
Strategic Opportunities
- Stationary energy storage in India:CEA grid-scale battery mandates and PLI scheme incentives create first-mover advantage for thermal-stable module suppliers.
- Marine electrification:Classification society rules from DNV and Lloyd's Register favor inherently safer cathode chemistries in passenger vessel battery rooms.
- Dry electrode coating convergence:Elimination of solvent-based slurry processing reduces energy consumption and facility footprint for module manufacturers.
Industry Challenges
- Solid-state manufacturing talent scarcity:Ceramic sintering and thin-film deposition expertise resides predominantly in semiconductor and capacitor industries, not battery module operations.
- GB/T certification timeline compression:China's SAMR accelerated testing protocols for grid-connected energy storage modules strain validation laboratory capacity.
- Legacy thermal management system incompatibility:Existing liquid cooling architectures designed for nickel-cobalt cells require complete redesign for lower-temperature olivine-chemistry operation profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FORTELION Battery Module Market |
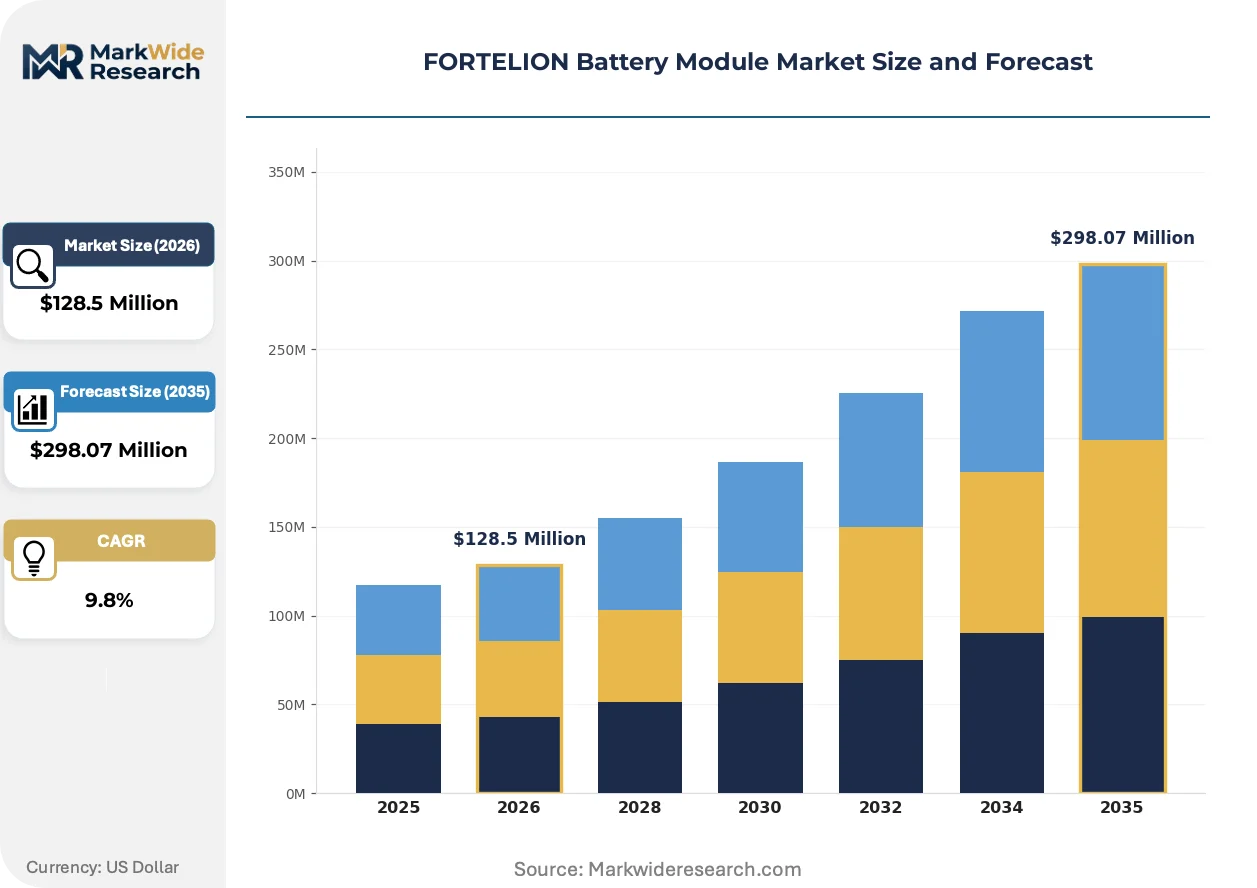
| Market Size in 2026 | $128.5 Million |
| Market Size in 2035 | $298.07 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pouch Cells, Cylindrical Cells, Prismatic Cells, Modules Application: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Power Tools Technology: Lithium-Ion, Lithium Polymer, Solid-State, Lead-Acid End User: Automakers, Energy Providers, Electronics Manufacturers, Industrial Users |
| Companies Covered | Murata Manufacturing Co., Ltd., Sony Corporation, Contemporary Amperex Technology Co. Limited (CATL), BYD Company Limited, LG Energy Solution, Panasonic Holdings Corporation, Samsung SDI Co., Ltd., Gotion High-tech Co., Ltd., EVE Energy Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FORTELION Battery Module Market Trends and Innovations
Module architecture is abandoning traditional cell-to-module hierarchy in favor of direct cell-to-pack integration. This structural simplification eliminates redundant housings and busbar connections.
Dry electrode coating is migrating from pilot-scale demonstration to commercial module production. BMW and Ford procurement teams have qualified suppliers using this process for 2026 platform launches. The technology is migrating from niche industrial applications toward high-volume automotive contracts, compressing incumbent wet-slurry equipment replacement cycles.
Japan's METI revised safety benchmarks now mandate nail penetration and overcharge testing at module level rather than cell level. This regulatory tightening forces redesign of battery management system architectures and fuse protection topologies. Industrial forklift and automated guided vehicle manufacturers face the steepest compliance recertification burden.
Fleet operators and independent power producers now specify cycle-life guarantees rather than upfront capital expenditure in procurement tenders. This performance-contracting model transfers degradation risk from asset owners to module suppliers. The shift is most visible in California and Texas utility-scale solar-plus-storage deployments.
FORTELION Battery Module Market Segmentation
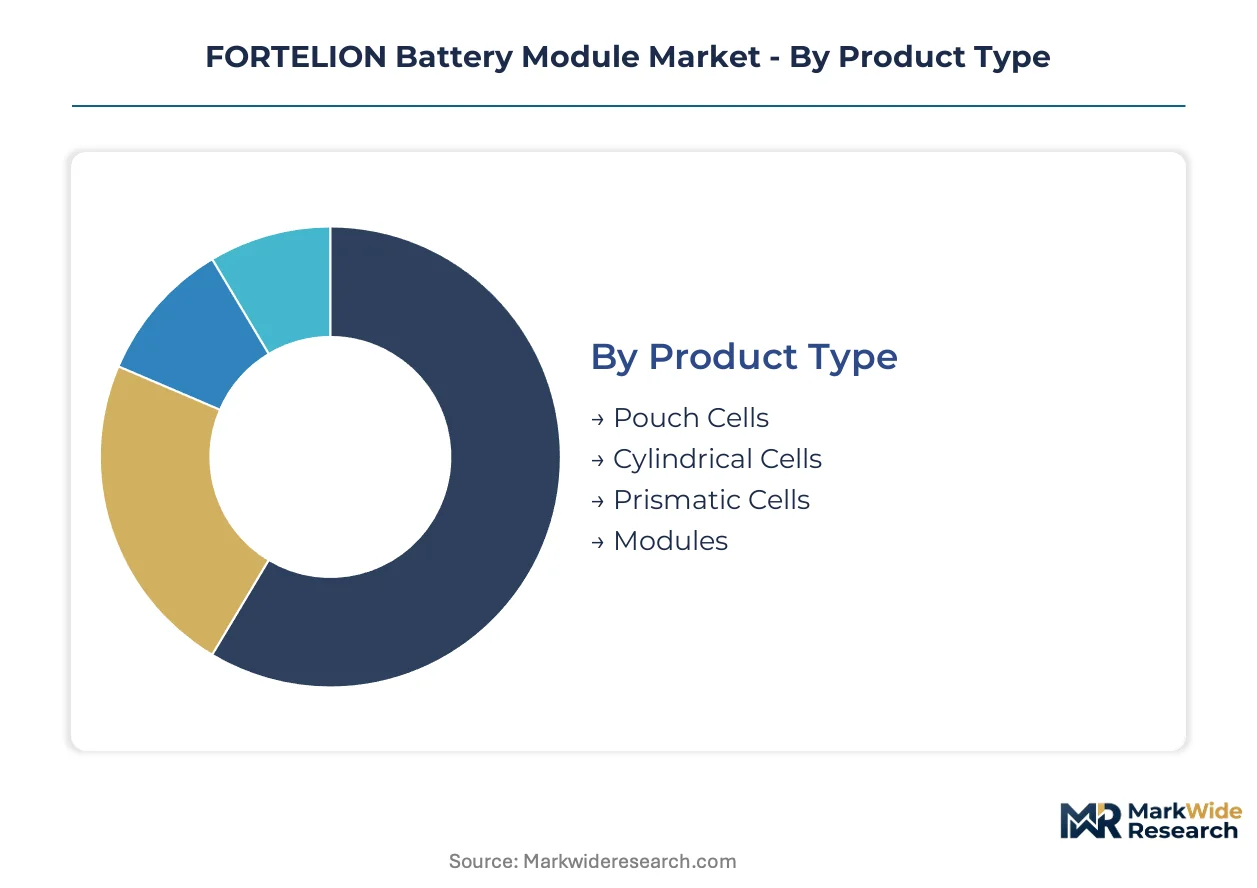
Module format selection dictates thermal management architecture and assembly automation requirements across FORTELION battery production lines. Customer procurement specifications diverge sharply between automotive qualification protocols and industrial energy storage acceptance criteria.
Product Type:
After-sales service intensity escalates with cell format complexity, as pouch designs require specialized recalibration equipment while cylindrical formats leverage standardized replacement protocols.
- Cylindrical Cells:Wound electrode structures in metal cans accommodate established high-speed winding equipment from consumer electronics supply chains. Demand concentrates in Japanese and Chinese automotive OEM supply contracts where METI nail penetration testing mandates robust mechanical containment.
- Prismatic Cells:Laminated flat-plate geometries optimize volumetric efficiency in cell-to-pack architectures. Korean battery producers dominate output for European automakers seeking cobalt-free chemistry compliance under EU Battery Regulation carbon disclosure rules.
- Pouch Cells:Aluminum-laminate flexible packaging reduces dead space in custom-shaped modules. Electronics manufacturers in Shenzhen specify these for wearable device integration where space constraints override cycle life requirements.
- Modules:Pre-assembled cell arrays with integrated battery management systems simplify OEM integration. Industrial forklift producers in Nagoya prefer these for reduced field commissioning time.
Cylindrical Cells hold the largest share; momentum sits with Prismatic Cells as cell-to-pack adoption accelerates.
Application:
Cost tier stratification separates premium automotive qualification costs from standardized industrial procurement benchmarks.
- Electric Vehicles:Powertrain integration demands cycle-life guarantees exceeding 3000 cycles at 80% depth of discharge. German automakers specify olivine-type cathodes to satisfy supply chain due diligence requirements for cobalt-free material sourcing.
- Energy Storage Systems:Grid-scale installations prioritize calendar life degradation rates over power density. Indian CEA mandates and PLI incentives are concentrating demand among domestic project developers seeking thermal-stable chemistry certification.
- Consumer Electronics:Portable device manufacturers prioritize energy density and form factor flexibility. Shenzhen-based OEMs dominate procurement for smartphone and laptop power units.
- Power Tools:High-discharge-rate cells support cordless industrial equipment. Japanese manufacturers specify these for construction and manufacturing automation applications.
Electric Vehicles command the dominant revenue position; Energy Storage Systems are climbing the fastest as grid-scale deployment timelines compress.
Technology:
Volume concentration patterns reflect manufacturing maturity and capital equipment replacement cycles across electrolyte systems.
- Lithium-Ion:Liquid electrolyte systems with olivine-type lithium iron phosphate cathodes deliver proven thermal stability. Chinese GB/T certification requirements gate market access for grid-connected installations.
- Solid-State:Ceramic or sulfide electrolyte architectures promise higher energy density with reduced fire risk. Interfacial impedance challenges constrain commercial module integration despite intensive R&D investment.
- Lithium Polymer:Gel polymer electrolytes enable ultra-thin form factors for wearable electronics. Korean producers specialize in these for premium consumer device segments.
- Lead-Acid:Mature technology serves price-sensitive backup power applications. Replacement demand concentrates in emerging market telecommunications infrastructure.
Lithium-Ion retains the installed base dominance; Solid-State exhibits the steepest expansion trajectory in development pipelines.
End User:
Customer type determines specification rigor, with automakers imposing the most exhaustive qualification protocols.
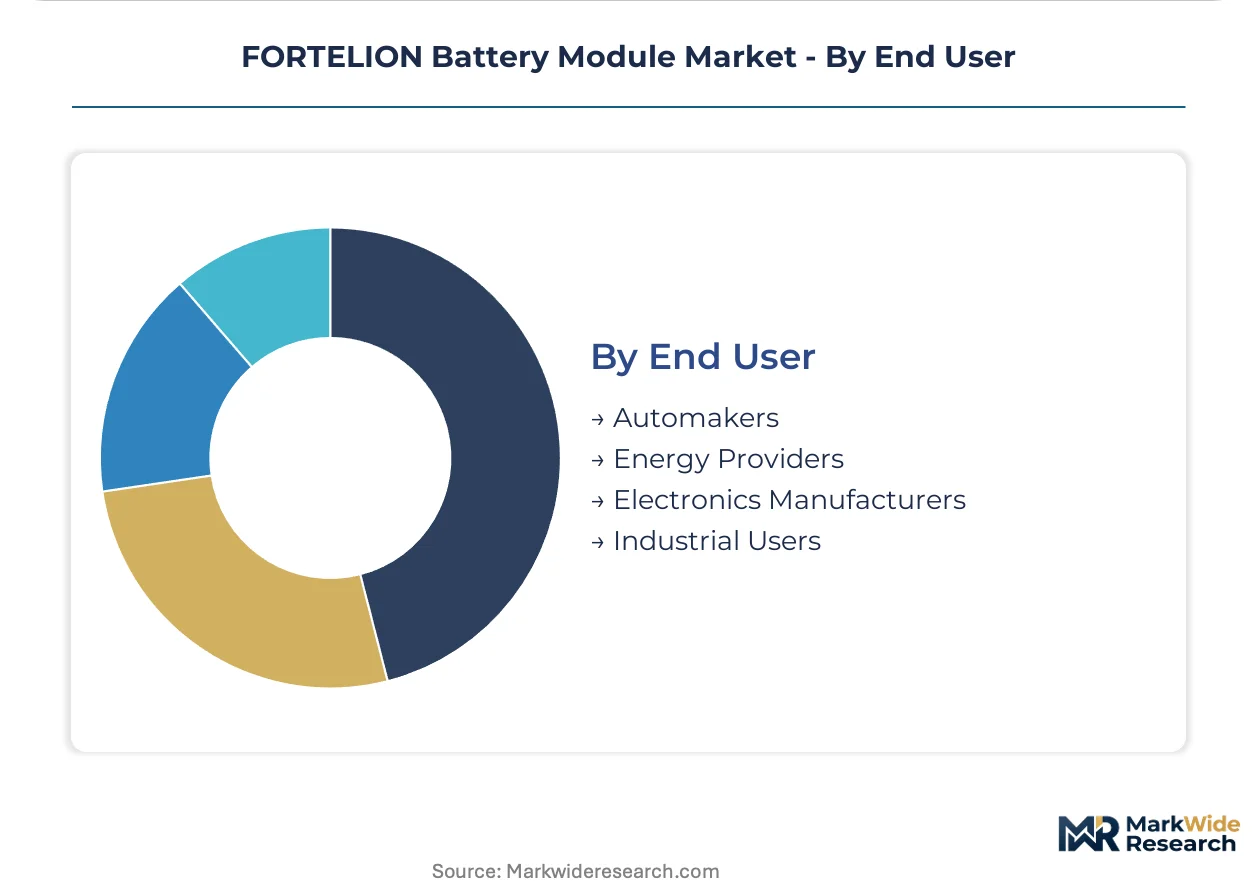
- Automakers:Battery-electric vehicle platforms require module-level nail penetration and overcharge testing under revised METI safety benchmarks. Procurement teams specify cycle-life performance contracting rather than upfront capital expenditure.
- Energy Providers:Utility-scale solar-plus-storage developers in California and Texas specify degradation risk transfer to suppliers through availability-based contracts.
- Electronics Manufacturers:Consumer device OEMs prioritize supply security and form factor customization over extended cycle guarantees.
- Industrial Users:Forklift and automated guided vehicle operators face compliance recertification burdens from module-level safety testing requirements.
Automakers represent the most demanding customer segment; Energy Providers are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement teams and industrial energy storage developers concentrate demand across three East Asian manufacturing corridors, with secondary clusters emerging in Germany and the United States as cobalt-free chemistry mandates reshape supplier qualification protocols.
China
Shenzhen-based module integrators supply cell-to-pack architectures for domestic EV platforms seeking GB/T certification compliance. SAMR accelerated testing timelines compress validation cycles for grid-connected energy storage deployments. Cathode precursor refining concentrates in Fujian and Hunan provinces, feeding Nagoya-bound export channels.
Japan
Nagoya industrial automation OEMs specify olivine-type modules for forklift and AGV applications under revised METI nail penetration mandates. METI's Electrical Appliance and Material Safety Act drives procurement preference toward thermally stable chemistries. Murata Manufacturing leverages ceramic capacitor heritage for high-reliability cell packaging serving industrial segments.
Germany
Bavarian automakers phase nickel-cobalt-manganese cathodes out of premium BEV lines to satisfy EU Battery Regulation carbon disclosure and recycled content quotas. KBA type-approval processes integrate module-level safety testing into vehicle homologation. Stuttgart and Munich procurement teams specify cycle-life performance contracting rather than upfront capital expenditure.
South Korea
Seoul Capital Area battery producers dominate prismatic cell output for European automakers seeking cobalt-free compliance. MFDS battery safety benchmarks align with EU MDR traceability requirements for medical device power units. Ulsan-Busan manufacturing clusters specialize in gel polymer electrolytes for premium consumer electronics segments.
United States
Texas and California utility-scale solar-plus-storage developers specify degradation risk transfer through availability-based contracts. NHTSA battery safety investigations inform OEM module architecture decisions. Detroit automotive qualification teams impose 3000-cycle guarantee thresholds for powertrain integration.
FORTELION Battery Module Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven Korean and Chinese producers anchor automotive supply contracts while Japanese ceramic specialists occupy industrial reliability niches. The vendor base separates into three strategic archetypes: vertically integrated cell-to-pack architects, component-specialist module assemblers, and materials-heritage diversification players. Dominant competitive moves include dry electrode coating equipment partnerships and ceramic processing capability acquisitions.
Within the materials-heritage archetype, Murata Manufacturing Co., Ltd. and Panasonic Holdings Corporation exemplify capacitor and electronics component legacies repurposed for battery module reliability engineering. Samsung SDI Co., Ltd. occupies a position between scale and specialization, representing Korean vertical control over separator and electrode production. Contemporary Amperex Technology Co. Limited anchors Chinese capacity expansion in prismatic and cell-to-pack architectures.
| Leading Market Players |
|---|
| Murata Manufacturing Co., Ltd. |
| Sony Corporation |
| Contemporary Amperex Technology Co. Limited (CATL) |
| BYD Company Limited |
| LG Energy Solution |
| Panasonic Holdings Corporation |
| Samsung SDI Co., Ltd. |
| Gotion High-tech Co., Ltd. |
| EVE Energy Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Shenzhen's concentrated cathode precursor refining capacity feeds Nagoya-bound export channels, translating upstream chemical processing dominance into downstream pricing leverage for module integrators serving Japanese automotive OEMs. Heilongjiang and Shandong spherical graphite processing facilities anchor anode material costs, with limited alternative sourcing amplifying supplier bargaining power across contract negotiations.
Pricing Analysis
Cost-plus contracts indexed to lithium carbonate and cobalt metal price benchmarks dominate procurement between Chinese cell producers and European automakers. Price differentiation rests on METI certification tier and volume scale, with nail penetration-tested modules commanding premiums over standard industrial grades. Cost compression in cylindrical cell tiers is intensifying because dry electrode coating equipment partnerships reduce solvent processing overhead. Industrial forklift operators exhibit highest price sensitivity due to thin margins on replacement cycle procurement, while German automakers prioritize cycle-life guarantees over upfront capital expenditure minimization.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates strategic planning for cathode active material shipments bound for Stuttgart and Munich assembly plants. Supply concentrates in Fujian and Hunan provinces for precursor refining, South Korea for separator membrane production, and Japan for ceramic electrolyte development. Raw material dependencies span lithium carbonate from Chilean and Australian brine operations, spherical purified graphite from Heilongjiang processing facilities, and nickel sulfate from Indonesian integrated facilities. Single-source vulnerability in sulfide electrolyte ceramic sintering equipment constrains solid-state scale-up timelines. Distribution runs through direct OEM supply contracts for automotive qualification, with industrial segments served through Nagoya-based distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Module suppliers increasingly attach performance-contracting services to hardware sales, with cycle-life guarantee underwriting and degradation risk transfer expanding faster than standalone equipment revenue across California and Texas utility-scale deployments.
For Market Incumbents: Insulate automotive supply relationships by acquiring dry electrode coating equipment partnerships before 2026 platform qualification deadlines. Backward integration into cathode precursor refining in Fujian province reduces exposure to lithium carbonate price volatility. METI's revised module-level safety testing mandates threaten incumbent industrial forklift market positions requiring rapid battery management system architecture redesign. For New Entrants and Emerging Players: Pursue marine electrification classification society approvals from DNV and Lloyd's Register as the most penetrable application segment, where inherently safer cathode chemistries face lower incumbent lock-in. India's CEA grid-scale battery mandates and PLI scheme incentives create first-mover terrain for thermal-stable module suppliers without established channel relationships. Partner with Shenzhen electronics OEMs on pouch cell customization for wearable device integration. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors materials-heritage diversification players with ceramic processing capabilities repurposed from capacitor manufacturing. Solid-state electrolyte commercialization represents the critical inflection window across a five-to-ten year horizon. Acquisition targets should demonstrate qualified dry electrode coating processes or established GB/T certification laboratory relationships. Watch ceramic-electrode interfacial impedance resolution in pilot production lines as the signal separating development-stage from commercial-ready solid-state module suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Coating Equipment Partnership | BMW and Ford procurement teams have qualified suppliers using this process for automotive platform launches. |
| GB/T Certification Laboratory Investment | SAMR accelerated testing protocols strain validation capacity for grid-connected energy storage module entrants. |
| Ceramic Processing Capability Acquisition | Murata Manufacturing leverages capacitor heritage to anchor high-reliability cell packaging for industrial applications. |
| Cell-to-Pack Architecture Scale-Up | LG Energy Solution differentiates with scaled prismatic designs eliminating redundant housings and busbar connections. |
| Performance-Contracting Service Launch | Fleet operators in California and Texas now specify availability-based contracts transferring degradation risk to suppliers. |
Research Methodology
Desk research of customs trade data, SAMR GB/T certification filings, and METI safety benchmark revisions preceded structured interviews with automotive procurement directors, industrial energy storage project developers, and ceramic electrolyte R&D leads. Primary fieldwork captured cell-to-pack architecture adoption timelines and dry electrode coating equipment qualification status. Secondary validation drew from SEC 10-K battery segment disclosures, EIA utility-scale storage deployment databases, and IHS Markit electric vehicle production forecasts. Bottom-up module shipment estimates triangulated against top-down cathode material demand projections.
Assumptions held fixed include current METI and GB/T safety certification requirements, existing lithium iron phosphate cathode chemistry dominance, and observed dry electrode coating equipment partnership timelines. Variables tested across the analysis window encompass solid-state electrolyte commercialization pace, EU Battery Regulation carbon disclosure implementation stringency, and Indian PLI scheme incentive continuity. Segmentation modeling spanned cell format, application, technology, and end user dimensions with automotive qualification protocol tier as an industry-specific layer. CAGRs derived from regression against historical module shipment trajectories and projected electric vehicle platform rollouts.
The forecast holds incumbent behavior within observed patterns; aggressive moves by sulfide electrolyte specialists or ceramic sintering equipment manufacturers would shift outcomes. Solid-state interfacial impedance breakthroughs or abrupt EU carbon border adjustment mechanism expansion represent specific revision risks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Italy Rechargeable Battery Market
Batteries
Liquid Metal Battery Market
Batteries
Automotive Starting Battery Market
Batteries
United States SLI Battery Market
Batteries
Sodium Nickel Chloride Battery Market
Batteries
Italy SLI Battery Market
Batteries
Global Battery Market
Batteries
Yacht Battery Market
Batteries
Elastic Battery Binders Market
Batteries
Zinc Ion Batteries Market
Batteries
DMC for Battery Market
Batteries
Lithium Battery Testing System Market
Batteries
Europe Battery Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Asia-Pacific Dual Carbon Battery Market
Batteries
North Africa Battery Market