
 Trailer Canopy Market | 2026-2036
Trailer Canopy Market Size, Share, and Industry Trends Forecast 2026-2036
Trailer Canopy Market Analysis
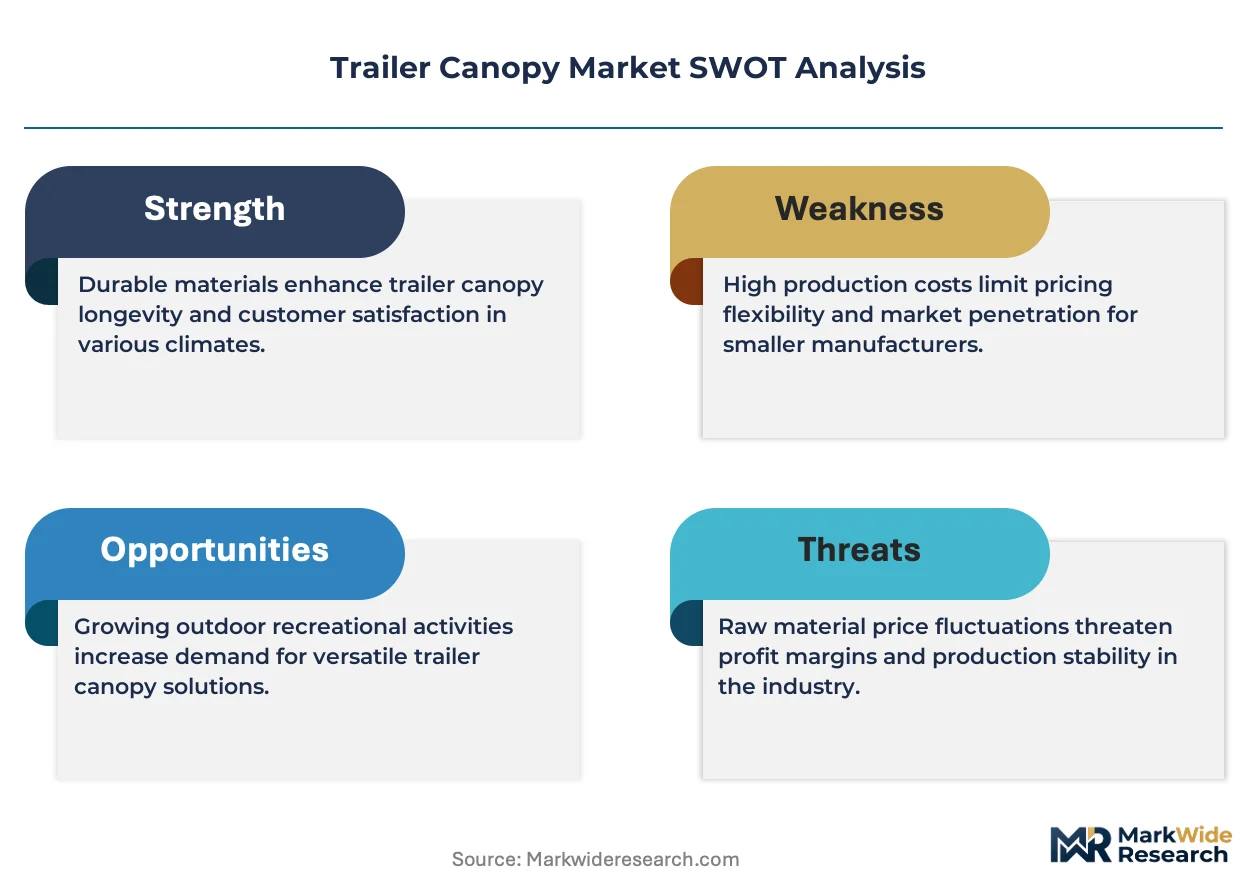
Composite manufacturing is fragmenting traditional metal fabrication across the trailer canopy supply chain as thermoplastic panels and bonded aluminum-honeycomb assemblies displace welded steel construction. ARB 4x4 Accessories leverages its Australian distribution network to dominate aftermarket channels across Oceania. RSI SmartCap anchors its position through proprietary modular rail systems that enable tool-free accessory mounting. Alu-Cab competes on expedition-grade sealing technology developed for overland racing applications.
A trailer canopy constitutes a rigid or semi-rigid protective enclosure mounted atop a towed or vehicle-integrated cargo platform, typically fabricated from aluminum extrusions, polymer composites, or treated fabric membranes with specified wind-load and water-head ratings, designed to secure equipment, goods, or living accommodations against environmental exposure and theft. Heavy-duty canopy configurations command premium positioning due to integrated roof-rack load ratings and dust-proof sealing demanded by mining and remote construction contractors. Pop-up canopy demand accelerates fastest among weekend campers prioritizing rapid deployment and collapsed transport height. Enclosed canopy variants sustain margin pools through climate-controlled interiors and integrated electrical pass-throughs serving mobile tradespeople.
FAA regulations governing cargo containment on airfield support trailers, plus NHTSA lighting and visibility standards for towed equipment, shape product compliance requirements for manufacturers accessing North American commercial fleets. Australia's ADR (Australian Design Rules) and load-rating enforcement by state transport authorities dictate structural certification for canopy systems exceeding rooftop mass limits. Stakeholders must monitor evolving material fire-retardancy mandates and weight-reduction incentives as electrified tow vehicles impose stricter payload constraints on accessory manufacturers.
Market Dynamics
Composite thermoplastic panels are fragmenting traditional welded-steel fabrication across trailer canopy supply chains, forcing aluminum-extrusion suppliers to reposition around bonded honeycomb assemblies and modular rail integration.
Growth Catalysts
- Expedition Vehicle Attachment Culture:Recreational overlanding communities in Australia and the western United States are normalizing canopy systems as standard equipment, expanding addressable demand beyond commercial fleets into consumer retail channels.
- ASTM D4851 Fabric Durability Standards:Tightened international specifications for tear strength and UV degradation are disqualifying low-grade suppliers, consolidating procurement toward certified manufacturers with in-house testing facilities.
- Mining Contractor Fleet Renewal:Australian and Chilean resource extraction operators are specifying dust-proof sealing and integrated roof-rack load ratings as mandatory tender requirements, elevating heavy-duty canopy configurations.
Market Restraints
- Aluminum Sheet Volatility:Primary aluminum input costs tied to LME pricing swings compress margin stability for extrusion-dependent fabricators clustered around Brisbane and Perth manufacturing zones.
- Electrified Tow Vehicle Payload Constraints:Battery-electric trucks and SUVs impose stricter rooftop mass limits, forcing canopy redesigns that sacrifice structural reinforcement for weight reduction.
- Regional Load-Rating Fragmentation:Inconsistent enforcement between Australian state transport authorities and NHTSA standards creates compliance duplication costs for manufacturers serving multiple markets.
Strategic Opportunities
- Mobile Tradespeople Climate Control:Enclosed canopy variants with integrated electrical pass-throughs and HVAC compatibility remain underpenetrated among electrician and plumbing contractors in Germany and France.
- Pop-Up Rapid Deployment Systems:Weekend camper segments prioritize collapsed transport height and tool-free assembly, creating white space for pneumatic or gas-strut assisted mechanisms.
- EU Green Deal Material Incentives:Recyclable thermoplastic panel constructions qualify for circular economy procurement preferences in public-sector fleet tenders across Nordic member states.
Industry Challenges
- Composite Bonding Technician Scarcity:Adhesive chemistry expertise and automated layup programming skills lag demand as thermoplastic assembly displaces traditional welding workflows.
- Multi-Jurisdiction Certification Timelines:Simultaneous ADR, NHTSA, and ISO 9001 approval processes extend product launch cycles by 8-14 months for new canopy platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trailer Canopy Market |
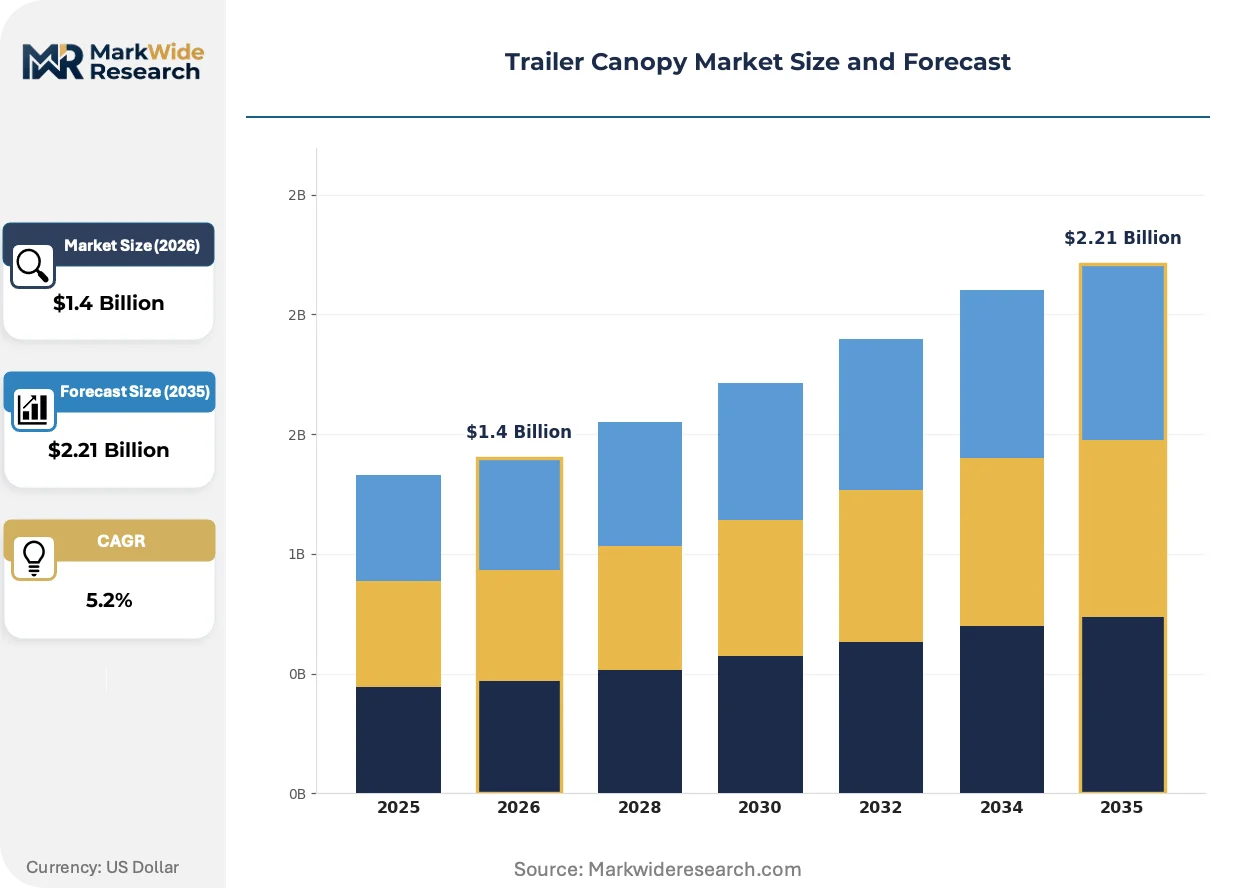
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.21 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Canopy, Heavy-Duty Canopy, Pop-Up Canopy, Enclosed Canopy Material: Polyester, Vinyl, Canvas, Nylon Application: Camping, Commercial Use, Temporary Shelter, Event Hosting End User: Retailers, Outdoor Enthusiasts, Event Organizers, Contractors |
| Companies Covered | Williams Trailers, ARB 4x4 Accessories, RSI SmartCap, Alu-Cab, Norweld, Tru-Cape Canopies, Razorback Canopies, Carryboy, Blackburn Trailers Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trailer Canopy Market Emerging Trajectories
Active material substitution and regulatory tightening are compressing traditional manufacturing methods while opening modular, software-integrated canopy architectures. Three developments dominate strategic planning.
Thermoplastic composite panels with embedded fiber reinforcement are migrating from aerospace prototyping into mainstream canopy production. Mining fleet operators in Western Australia and Chilean Atacama operations specify these assemblies for corrosion resistance and repairability. The technology is migrating from premium expedition-grade suppliers into mid-market fabrication, compressing price positioning for welded-aluminum incumbents.
NHTSA lighting and visibility standards for towed equipment are tightening photometric requirements for rear marker illumination and reflective tape placement. Commercial fleet managers must retrofit existing inventory or specify compliant factory configurations, accelerating LED-integrated canopy designs. North American rental and logistics operators face the steepest compliance costs, driving consolidation toward turnkey suppliers with in-house homologation capabilities.
Direct-to-consumer digital configuration tools are displacing traditional dealer-assisted specification processes. Weekend camper and overlanding enthusiasts in Colorado, Utah, and Victoria now design modular rail layouts and accessory packages through manufacturer portals, compressing the sales cycle and reducing distributor margin capture. This channel shift is most visible in premium aftermarket segments where brand community engagement drives repeat accessory purchases.
Trailer Canopy Market Segmentation
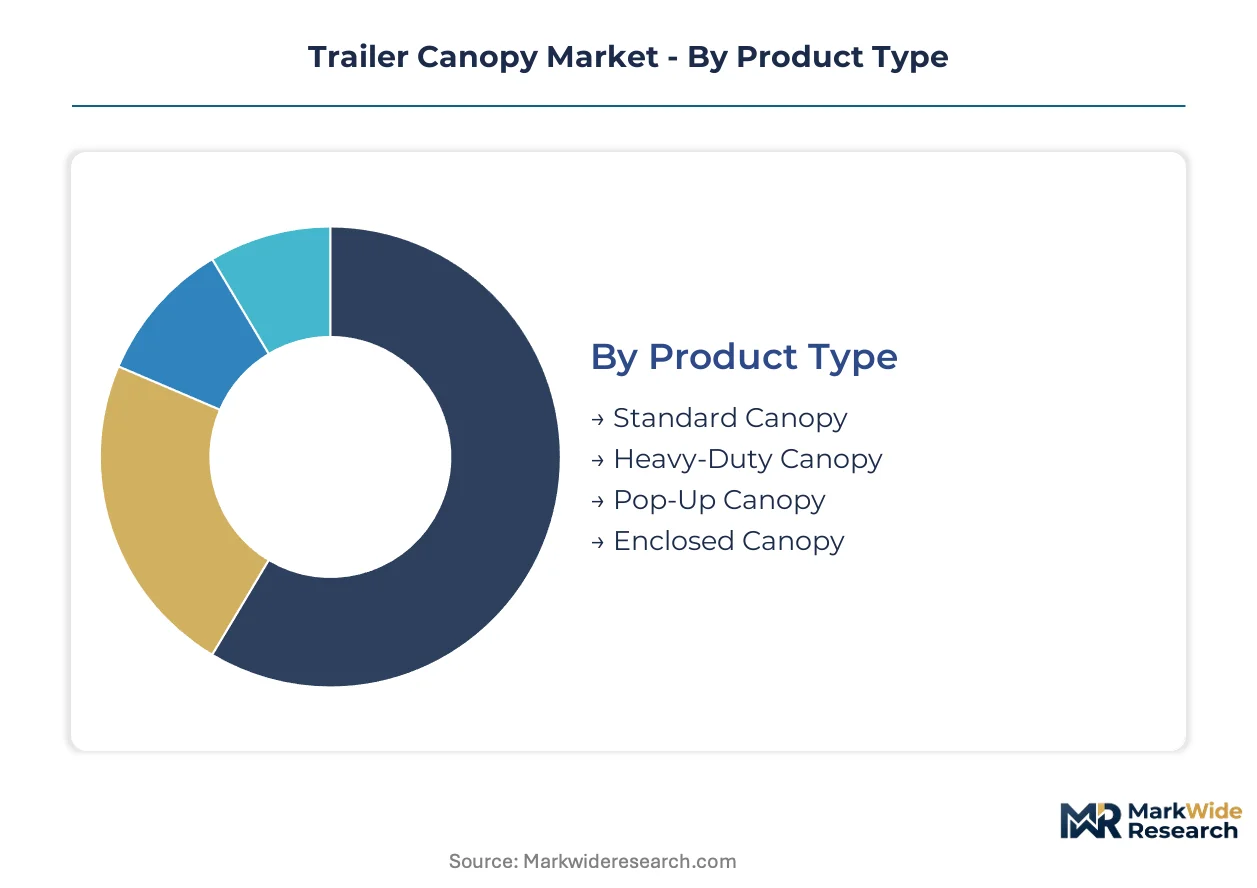
Trailer canopy purchasing decisions split across payload requirements, environmental exposure severity, and deployment frequency. Manufacturers configure production lines around these divergent specifications, with material chemistry and structural engineering depth determining margin capture.
Product Type:
Cost tier stratification in trailer canopy fabrication separates weekend recreational buyers from mining fleet procurement officers with distinct engineering mandates.
- Standard Canopy:Aluminum extrusion frames with polyester fabric membranes dominate entry-level configurations. Australian outdoor retailers in Brisbane and Perth distribution corridors move highest volumes through dealer networks serving casual campers.
- Heavy-Duty Canopy:Welded steel or bonded aluminum-honeycomb assemblies integrate dust-proof sealing and certified roof-rack load ratings. Mining contractors in Western Australia and Chilean Atacama operations specify these as mandatory tender requirements, with ASTM D4851 fabric durability certification now standard.
- Pop-Up Canopy:Gas-strut or pneumatic assisted mechanisms enable sub-60-second deployment from collapsed transport height. Weekend overlanding communities in Colorado and Utah prioritize these for rapid campsite transitions.
- Enclosed Canopy:Rigid panel construction with integrated electrical pass-throughs and HVAC compatibility serves mobile tradespeople. Electrician and plumbing contractors in Germany and France remain underpenetrated despite climate-controlled interior advantages.
Heavy-Duty Canopy holds installed capacity across resource extraction fleets. Pop-Up Canopy is rotating up the share rankings among recreational attachment culture adopters.
Material:
Application severity dictates fabric selection, with UV degradation resistance and tear strength specifications tightening under international standards.
- Polyester:Coated woven synthetic with polyurethane backing dominates mid-market production for balanced weight-to-durability ratios. Australian canopy fabricators around Brisbane manufacturing zones source bulk rolls from Southeast Asian textile suppliers.
- Vinyl:PVC-laminated constructions deliver superior water-head ratings for commercial fleet operators facing NHTSA visibility compliance requirements. North American rental and logistics procurement favors these for extended service intervals.
- Canvas:Cotton-polyester blends with mildew-resistant treatments retain heritage appeal among expedition-grade suppliers. Overland racing applications in Australian desert conditions validate breathability performance.
- Nylon:Ripstop weaves with silicone impregnation enable ultralight configurations for collapsed transport height minimization. Backpacking-derivative canopy designs in Victoria and New South Wales recreational channels adopt these for weight-constrained electric tow vehicle compatibility.
Polyester commands current procurement volumes. Nylon is climbing the fastest as electrified payload constraints reshape material specifications.
Application:
Customer use-case intensity spans from intermittent weekend deployment to continuous commercial operation with divergent durability expectations.
- Camping:Recreational overlanding and weekend expedition use drives modular rail integration for tool-free accessory mounting. RSI SmartCap proprietary systems anchor this segment through direct-to-consumer configuration portals.
- Commercial Use:Fleet operators in mining, construction, and logistics specify integrated lighting, sealing, and load-rating certifications. Australian ADR compliance and NHTSA standards create dual-certification burdens for multinational suppliers.
- Temporary Shelter:Disaster response and military procurement requires rapid deployment with minimal site preparation. Fabric durability under cyclic wind loading becomes critical specification.
- Event Hosting:Catering and mobile retail applications prioritize aesthetic finish and side-panel configurability. European festival circuit demand concentrates in German and French rental channels.
Commercial Use holds installed capacity across fleet renewal cycles. Camping is gaining share fastest as vehicle attachment culture normalizes canopy systems as standard equipment.
End User:
Procurement authority and technical specification capability separate institutional buyers from individual consumers with distinct sales channel requirements.
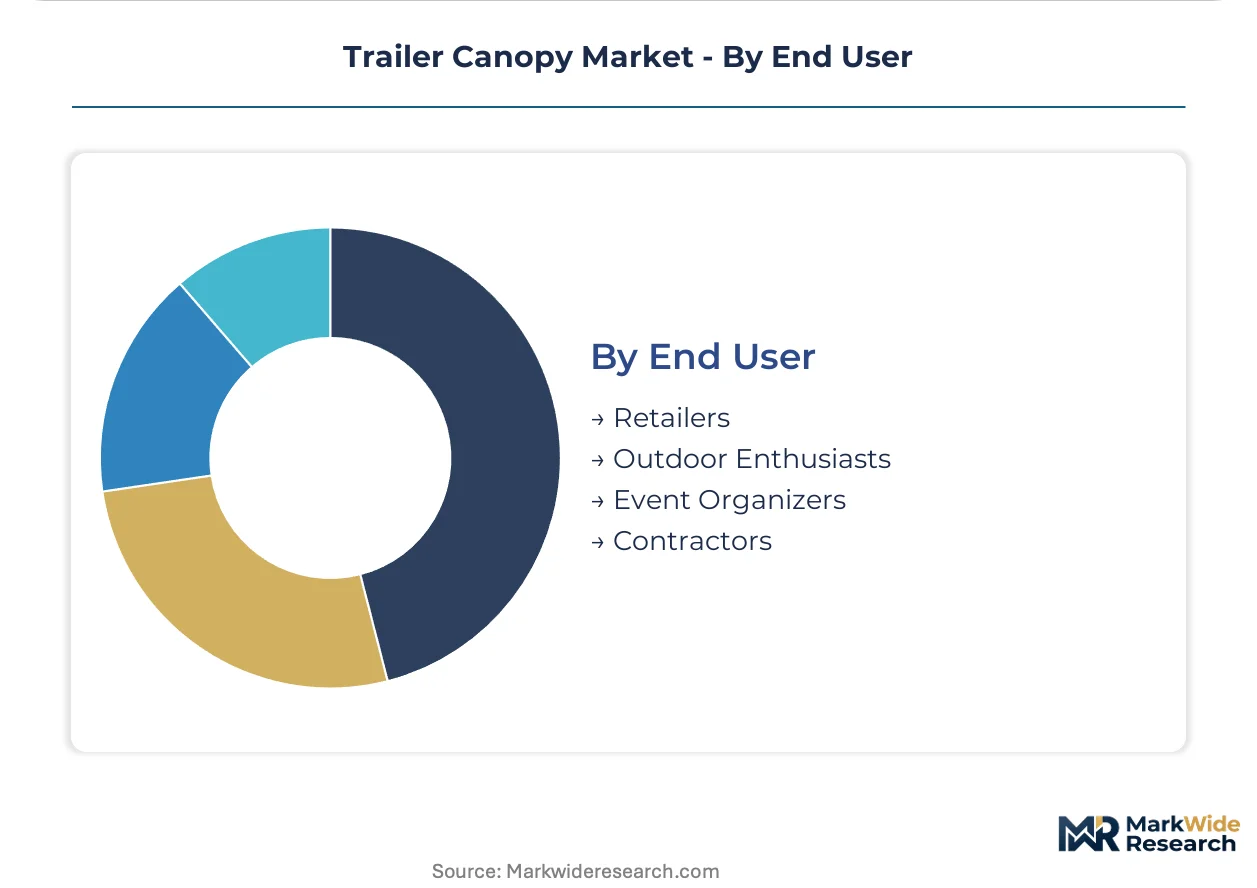
- Retailers:Dealer networks and outdoor specialty stores aggregate consumer demand with assisted specification processes. ARB 4x4 Accessories leverages Australian distribution dominance across Oceania aftermarket channels.
- Outdoor Enthusiasts:Direct-to-consumer digital configuration displaces traditional dealer relationships. Colorado, Utah, and Victoria buyers now design modular layouts through manufacturer portals, compressing sales cycles.
- Event Organizers:Rental fleet operators and festival contractors prioritize rapid inventory turnover and damage repairability. Thermoplastic panel constructions enable field-replaceable components.
- Contractors:Electrician, plumbing, and construction trades require climate-controlled interiors with electrical pass-through integration. EU Green Deal material incentives steer Nordic public-sector procurement toward recyclable thermoplastic options.
Retailers hold installed capacity through established distribution infrastructure. Outdoor Enthusiasts are rotating up the share rankings as digital configuration tools displace assisted sales processes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented canopy fabricators in Australia and Chile supply mining fleets across the Pacific Rim, while import-dependent European markets source aluminum extrusions from Southeast Asian mills. Trade flows concentrate around Brisbane-Perth manufacturing corridors and German distribution hubs serving Nordic contractor demand.
Australia
Western Australian mining contractors drive heavy-duty canopy procurement with dust-proof sealing and certified roof-rack specifications. ADR compliance enforced by state transport authorities mandates structural certification for rooftop mass limits. Fabrication clusters around Brisbane and Perth manufacturing zones supply domestic fleets and export to Chilean resource operations.
United States
Weekend overlanding communities in Colorado and Utah normalize canopy systems as standard vehicle equipment. NHTSA lighting and visibility standards tighten photometric requirements for rear marker illumination and reflective tape placement. Domestic suppliers face compliance retrofit costs for existing rental and logistics fleet inventory.
Germany
Electrician and plumbing contractors generate underpenetrated demand for climate-controlled enclosed canopies with electrical pass-through integration. EU Green Deal material incentives steer public-sector procurement toward recyclable thermoplastic panel constructions. Industrial distribution concentrates in Bavaria and North Rhine-Westphalia serving Nordic member state tenders.
Chile
Atacama mining operations specify corrosion-resistant thermoplastic composite panels for fleet durability under extreme arid exposure. The national mining regulator enforces load-rating compliance for contractor equipment tenders. Import channels from Australian manufacturers dominate premium heavy-duty canopy supply.
France
Festival circuit rental operators prioritize rapid inventory turnover and field-repairable thermoplastic components for mobile retail applications. REACH chemical compliance shapes material specifications for imported fabric membranes. Logistics clusters in Île-de-France aggregate European distribution for event hosting canopy deployments.
Trailer Canopy Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated fabricators with in-house homologation capabilities and fragmented among regional specialists serving single-country mining fleets. Three strategic archetypes dominate: expedition-grade sealing technology developers, modular rail system proprietors, and aluminum-extrusion fabricators clustered near raw material inputs. Competitive moves center on direct-to-consumer digital configuration platforms and multi-jurisdiction certification investments compressing product launch timelines.
Among Australian-based specialists, ARB 4x4 Accessories, RSI SmartCap, and Alu-Cab occupy distinct positioning vectors within premium aftermarket channels. ARB represents the established distribution network archetype with Oceania-wide dealer infrastructure. RSI SmartCap exemplifies the modular integration specialist tier through proprietary rail systems enabling tool-free accessory mounting. Alu-Cab anchors the expedition-grade technology segment with sealing architectures developed for overland racing applications. These three fabricators collectively illustrate how regional manufacturing depth translates into differentiated competitive positioning against import-dependent distributors in European and North American markets.
| Leading Market Players |
|---|
| Williams Trailers |
| ARB 4x4 Accessories |
| RSI SmartCap |
| Alu-Cab |
| Norweld |
| Tru-Cape Canopies |
| Razorback Canopies |
| Carryboy |
| Blackburn Trailers Limited |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Brisbane aluminum extrusion clusters compresses supplier pricing power while forcing fabricators toward bonded honeycomb assemblies to defend margin pools. Utilization rates below regional breakeven thresholds incentivize extended payment terms and inventory financing concessions that reshape procurement negotiations across Australian manufacturing zones.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on certification grade and volume scale, with ADR-compliant heavy-duty configurations commanding substantial premiums over uncertified alternatives. Cost compression in standard polyester canopy tiers intensifies because Southeast Asian textile suppliers compete on bulk roll pricing. Mining contractors exhibit lowest price sensitivity due to tender-mandated durability specifications, while weekend camper segments drive hardest bargain negotiations through direct-to-consumer portals.
Supply Chain Analysis
Extended payment terms from Australian fabricators to Southeast Asian aluminum mills and textile suppliers lubricate working capital through the production cycle. Geographic supply concentration centers on Australia, China, and Indonesia for extrusions and coated fabrics. Raw material dependencies draw from LME-priced primary aluminum, polyurethane-coated polyester rolls, and thermoplastic resin feedstocks. Single-source vulnerability runs through Brisbane-Perth manufacturing corridors concentrated around resource extraction demand. Distribution runs through dealer networks serving mining fleets and direct-to-consumer portals capturing recreational attachment culture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflects as modular rail ecosystems displace fixed-configuration canopy architectures, with interoperability between accessory manufacturers becoming the decisive value driver.
For Market Incumbents: Pre-empt composite panel displacement by securing captive supply of thermoplastic resin feedstocks and adhesive chemistry expertise. Invest in in-house homologation capabilities to compress multi-jurisdiction certification timelines against emerging bonded-honeycomb specialists. Vertical integration into Southeast Asian textile sourcing defends margin position against polyester roll price volatility. For New Entrants and Emerging Players: Pursue climate-controlled enclosed canopy penetration among German and French electrical contractors, where HVAC-compatible configurations remain underdeveloped. Target weekend camper segments in Colorado and Utah through gas-strut rapid deployment mechanisms that prioritize collapsed transport height. Deploy direct-to-consumer digital configuration tools to bypass established dealer margin capture. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across thermoplastic composite assembly lines as automated layup equipment displaces skilled welding workflows. Long-term viability favors fabricators with backward integration into raw material conversion and certified testing facilities. The signal to monitor is ADR enforcement tightening by Australian state transport authorities, which would accelerate consolidation toward homologation-capable incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Rail Platform Standardization | RSI SmartCap proprietary systems demonstrate how tool-free accessory mounting captures recurring aftermarket revenue. |
| Bonded Honeycomb Assembly Investment | Alu-Cab expedition-grade sealing technology validates premium positioning through overland racing applications. |
| Direct-to-Consumer Portal Launch | ARB 4x4 Accessories leverages digital configuration to compress sales cycles among Victoria recreational buyers. |
| Multi-Jurisdiction Certification Buildout | Simultaneous ADR and NHTSA approval capabilities differentiate suppliers serving Australian and North American mining fleets. |
| Thermoplastic Panel Recycling Program | EU Green Deal circular economy preferences steer Nordic public-sector procurement toward recyclable construction materials. |
Methodological Framework
A spread of perspectives from canopy fabrication plant managers, mining fleet procurement officers, outdoor retailer category buyers, and aftermarket accessory distributors converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against SEC filings from listed automotive accessory manufacturers, Australian Bureau of Statistics trade data, and Chilean mining regulator equipment tender databases. Bottom-up unit economics from individual fabrication facilities triangulated against top-down demand modeling from vehicle registration and fleet renewal projections.
Demand-supply balance dynamics across the analysis window shaped volume and value outputs through segmented modeling. Segmentation dimensions included product type, material chemistry, application intensity, and end-user procurement authority. CAGRs were derived from installed base depreciation curves and replacement cycle analysis. Industry-specific forecast inputs incorporated electrified tow vehicle payload constraint trajectories and evolving ASTM D4851 fabric durability certification adoption rates.
Sensitivities concentrate around aluminum LME price volatility, ADR enforcement variance across Australian states, and thermoplastic composite technician availability. Forecasts reflect documented assumptions about mining fleet renewal timing and recreational vehicle attachment culture diffusion. Macroeconomic contraction in resource extraction, regulatory harmonization failure between NHTSA and ADR standards, or breakthrough lightweight material substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Child Seats Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Aircraft and Marine Turbochargers Market
Vehicle Components
Engine Mounting Brackets Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Trailer Brake Controllers Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Wheel Speed Sensor Market
Vehicle Components
Global Automotive Battery Sensor Market
Vehicle Components
Automotive Rubber Molded Components Market
Vehicle Components
Global Air Spring Components Market