
 Naval Combat Weapons Market | 2026-2036
Naval Combat Weapons Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Combat Weapons Market Foresight
Platform lifecycle sustainment revenue is fragmenting across original equipment manufacturers and third-party defense contractors. BAE Systems leverages its shipyard integration capabilities to capture refurbishment contracts for aging destroyer fleets. Leonardo anchors European naval munitions supply through its torpedo and lightweight missile production lines. RTX competes in the guided weapons segment with sensor-to-shooter networking technologies that reduce engagement timelines.
Naval combat weapons encompass munitions and delivery systems engineered for maritime engagement, typically integrating guidance electronics, propulsion modules, and warheads rated for saltwater corrosion and pressure cycling. These systems serve national navies and allied defense coalitions seeking sea control, area denial, or fleet protection. Missiles and torpedoes command the largest development budgets due to precision-strike requirements against maneuvering surface and subsurface targets. Guidance Systems technology differentiates procurement decisions as navies prioritize counter-jamming and autonomous targeting in contested electromagnetic environments. Kinetic weapons retain niche roles in close-range defense where electronic warfare saturation threatens sensor-dependent munitions.
The US Department of Defense mandates NAVAIR certification for air-launched naval weapons, while the EU Green Deal's defense procurement guidelines increasingly influence ammunition chemical composition standards across European navies. NATO's STANAG interoperability protocols shape cross-border weapons integration on multinational frigate programs. Stakeholders must weigh sovereign supply chain requirements against cooperative development costs as AUKUS and similar pacts redefine technology-sharing boundaries.
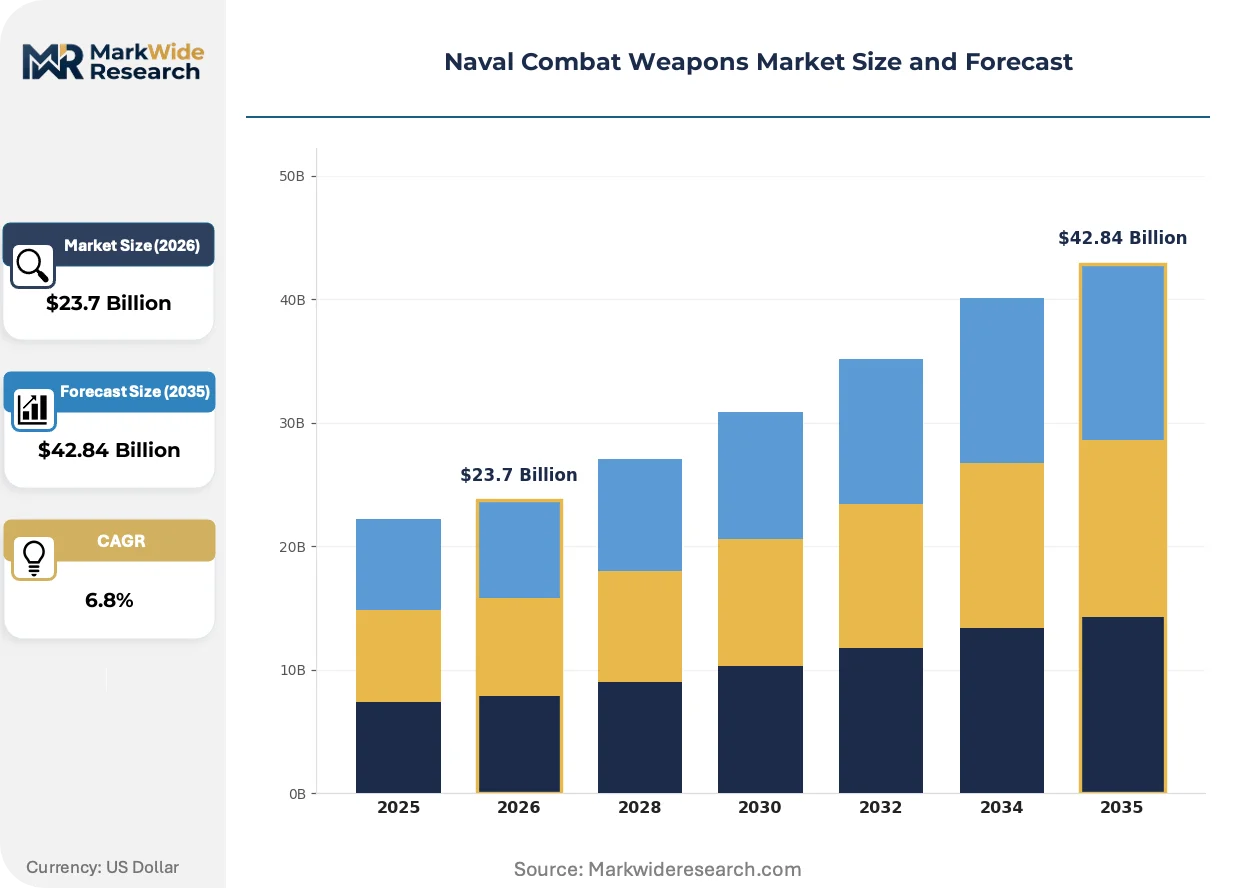
Market Dynamics
Integrated undersea warfare systems are reshaping fleet procurement as AUKUS submarine technology-sharing and DDG(X) destroyer programs demand weapons with interoperable guidance electronics and networked sensor-to-shooter architectures.
Growth Catalysts
- AUKUS Pact Technology Sharing:The trilateral security agreement between Australia, the United Kingdom, and the United States is accelerating joint development of next-generation torpedo and missile systems with common guidance modules.
- Indo-Pacific Territorial Tensions:China's naval modernization and South China Sea disputes are driving allied rearmament across Japan, South Korea, and Southeast Asian littoral states.
- NATO STANAG Interoperability Protocols:Cross-border weapons integration mandates on multinational frigate programs are standardizing procurement specifications across European allied navies.
Market Restraints
- Rare Earth Supply Concentration:Guidance system magnet and sensor production depends on processed rare earth inputs concentrated in Chinese refining capacity.
- NAVAIR Certification Timelines:The US Department of Defense's air-launched weapons approval process extends development cycles by 18-36 months beyond initial technical readiness.
- Saltwater Corrosion Material Costs:Titanium alloys and specialized coatings for pressure-cycling munitions face volatile pricing tied to aerospace and energy sector demand.
Strategic Opportunities
- Autonomous Targeting Convergence:Machine vision and acoustic signature fusion technologies are creating new product categories for contested electromagnetic environments.
- EU Green Deal Defense Guidelines:The European Union's ammunition chemical composition standards are opening retrofit markets for legacy munitions with reduced toxic payload formulations.
- Unmanned Undersea Vehicle Integration:Naval forces are weaponizing autonomous underwater platforms for mine countermeasures and payload delivery in denied access zones.
Industry Challenges
- Electromagnetic Warfare Talent Scarcity:Counter-jamming algorithm development requires specialized signal processing expertise concentrated in defense contractor and academic research centers.
- Legacy Fleet Integration Complexity:Retrofitting aging destroyer classes with networked weapons demands custom mechanical and electrical interface engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Combat Weapons Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Missiles, Torpedoes, Guns, Naval Mines Technology: Electromagnetic, Kinetic, Chemical, Guidance Systems End User: Navies, Defense Contractors, Government Agencies, Security Forces Application: Anti-Ship, Anti-Submarine, Naval Warfare, Defense Systems |
| Companies Covered | Terma, Leonardo, Thales Group, L3Harris Technologies, General Dynamics, BAE Systems, Lockheed Martin, Northrop Grumman, RTX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Combat Weapons Market Shifts & Advancements
Precision-strike requirements against maneuvering targets are compressing engagement timelines and forcing convergence between sensor data processing and autonomous terminal guidance.
Hypersonic glide vehicle technology is migrating from experimental demonstration programs to operational naval strike missile variants. The US Navy and select allied fleets are funding accelerated test sequences for sea-launched boost-glide weapons. This migration is collapsing the traditional separation between ballistic and cruise missile procurement categories.
REACH chemical registration requirements in the European Union are mandating substitution of legacy explosive formulations and stabilizer compounds. Defense contractors reformulating torpedo and missile warheads must now document full substance life-cycle impacts. Naval munitions suppliers with established European production lines are capturing refurbishment contracts as compliance deadlines approach.
Life-cycle availability contracts are displacing unit-based weapons purchases among NATO-aligned procurement agencies. National navies now contract for guaranteed operational readiness rather than discrete munitions inventories. This pattern is most pronounced in the United Kingdom and Scandinavian fleets, where platform sustainment budgets increasingly flow to integrated logistics providers.
Naval Combat Weapons Market Segmentation
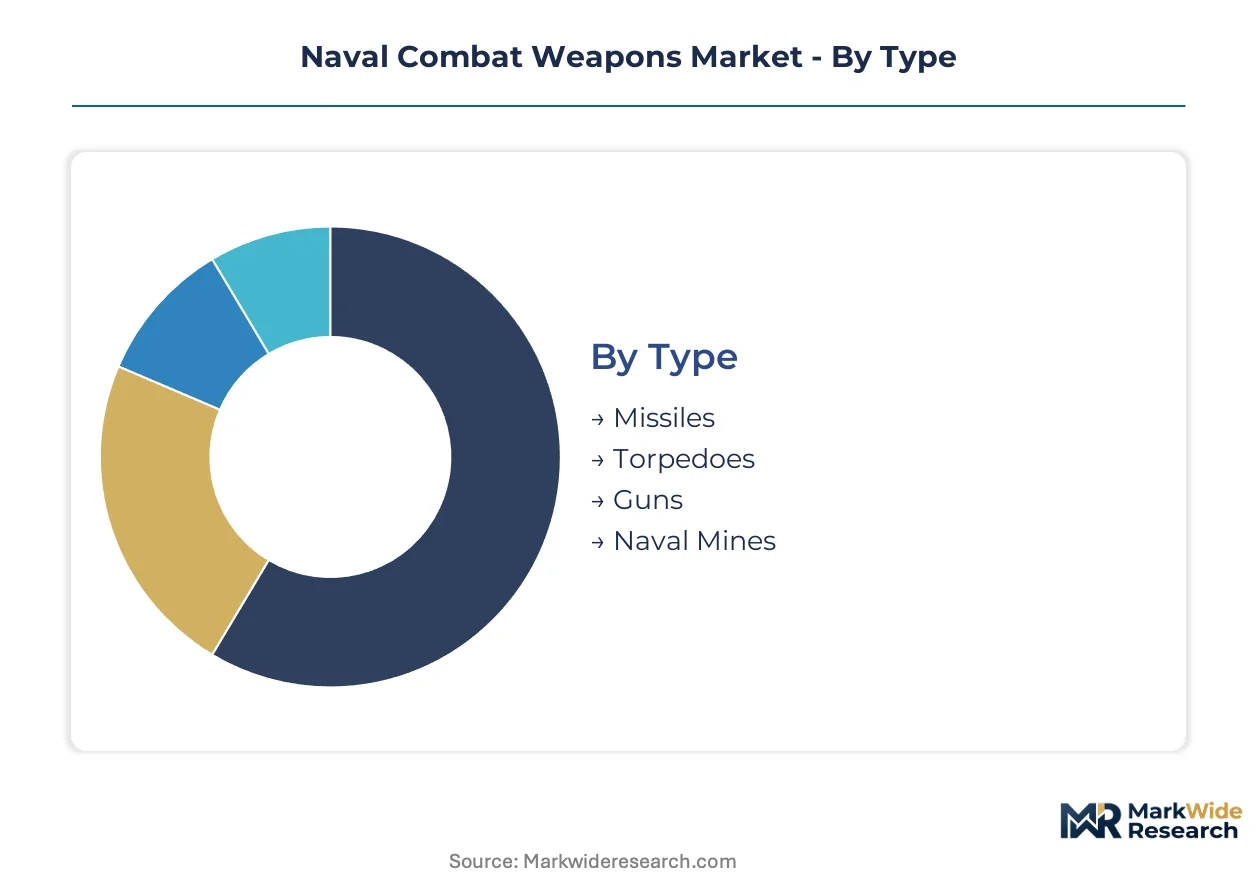
Segmentation in naval combat weapons reflects divergent procurement priorities across fleet modernization cycles and threat response requirements. Procurement agencies balance precision-strike investment against area-denial capabilities while navigating electromagnetic warfare readiness.
Type:
Naval forces deploy distinct weapon families calibrated to target mobility, engagement range, and platform integration constraints.
- Missiles:Sea-launched variants integrate active radar homing and infrared seekers for surface target prosecution at standoff distances. Demand concentrates in Indo-Pacific fleets responding to China's naval expansion, with AUKUS partners prioritizing common vertical-launch compatibility.
- Torpedoes:Acoustic-homing and wake-homing variants deliver subsurface kills through pressure-resistant guidance electronics. Procurement is accelerating in NATO destroyer programs and Australian submarine modernization, driven by undersea warfare interoperability mandates.
- Guns:Naval artillery retains close-range defense roles where electronic warfare threatens precision-guided alternatives.
- Naval Mines:Bottom-influence and moored variants enable sea denial without platform exposure in contested littorals.
The dominant share belongs to Missiles, while Torpedoes are closing the gap fastest.
Technology:
Technology selection determines survivability in contested electromagnetic environments and lifecycle sustainment costs.
- Guidance Systems:Inertial navigation fused with terminal seekers enables precision engagement against maneuvering targets. Investment clusters in counter-jamming algorithm development for GPS-denied operations, with US and allied fleets mandating anti-spoofing resilience.
- Electromagnetic:Railgun and directed-energy prototypes promise hypervelocity engagement without chemical propellant logistics. Development concentrates in US Navy surface warfare research programs, constrained by power density and barrel-wear challenges.
- Kinetic:Simple projectile weapons bypass electronic vulnerability in close-quarters defense scenarios.
- Chemical:Conventional propellant and explosive formulations face REACH compliance pressure in European procurement.
Guidance Systems command procurement priority, with Electromagnetic posting the steepest expansion trajectory as demonstration programs mature.
End User:
End-user categories reflect distinct acquisition authority patterns and operational employment doctrines.
- Navies:Fleet operators specify weapon performance requirements and platform integration standards. Procurement budgets from US, UK, Australian, Japanese, and South Korean naval services dominate volume, shaped by AUKUS and bilateral alliance structures.
- Defense Contractors:Prime integrators acquire subsystems for platform installation and lifecycle support. Activity concentrates in shipyard-based weapons integration for DDG(X) and multinational frigate programs.
- Government Agencies:Research establishments fund technology maturation prior to operational deployment.
- Security Forces:Coast guard and maritime constabulary units acquire lighter systems for territorial water enforcement.
Navies retain absolute budget authority, though Defense Contractors are gaining share through availability-based sustainment contracts.
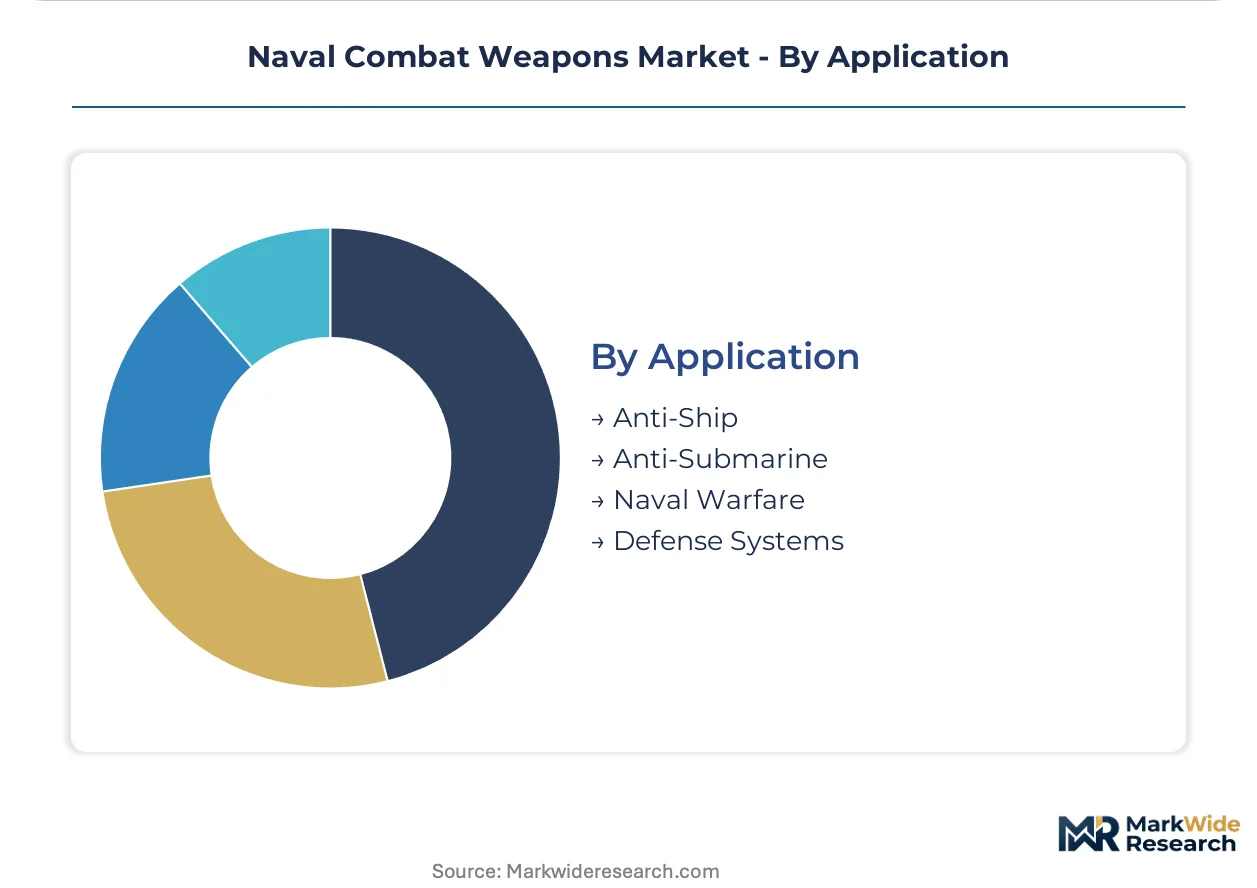
Application:
Application segmentation aligns with fleet mission profiles and adversary capability targeting priorities.
- Anti-Ship:Weapons optimized for surface combatant engagement at over-the-horizon ranges. Demand is surging in Pacific rim navies confronting China's destroyer and carrier fleet growth, with emphasis on saturation-resilient seekers.
- Anti-Submarine:Systems targeting submerged threats through acoustic, magnetic, or pressure anomaly detection. Procurement is intensifying in Atlantic and Pacific allied fleets responding to Russian and Chinese submarine force expansion.
- Naval Warfare:General-purpose systems supporting fleet action and sea control operations.
- Defense Systems:Point-defense weapons protecting high-value units against missile and small-craft threats.
Anti-Ship holds established primacy, while Anti-Submarine is gaining share fastest as undersea warfare competition intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for naval combat weapons varies sharply across procurement systems. Allied navies with integrated logistics contracts show lower price sensitivity than emerging fleet operators financing discrete platform acquisitions.
United States
The US Navy's DDG(X) program and AUKUS submarine commitments drive sustained procurement of torpedo and guided missile systems. NAVAIR certification mandates shape supplier qualification timelines for air-launched naval weapons. Industrial concentration clusters around Virginia's shipbuilding corridor and Connecticut's submarine manufacturing base, where prime integrators coordinate weapons platform integration.
United Kingdom
Royal Navy modernization and AUKUS technology-sharing obligations sustain investment in undersea warfare systems. Ministry of Defence availability-based contracts now dominate procurement, shifting budget flows to integrated logistics providers. Scottish shipyards and southern England defense corridors host concentrated weapons integration activity for multinational frigate programs.
Australia
AUKUS submarine acquisition and regional deterrence requirements accelerate torpedo and cruise missile procurement. Defence Strategic Review commitments mandate sovereign industrial capability development alongside technology transfer agreements. South Australian shipbuilding precincts and Western Australian naval support hubs concentrate workforce development for nuclear-powered submarine sustainment.
Japan
Maritime Self-Defense Force expansion responds to Chinese naval modernization in the East China Sea. METI industrial policy coordinates domestic defense contractor consolidation for autonomous underwater vehicle and anti-ship missile development. Kure and Yokosuka naval districts anchor weapons system integration for fleet destroyer programs.
South Korea
Navy force modernization and indigenous submarine programs sustain demand for heavyweight torpedoes and sea-launched cruise missiles. Defense Acquisition Program Administration guidelines prioritize technology transfer in offset arrangements with foreign suppliers. Busan-Ulsan shipbuilding clusters and Seoul defense R&D corridors concentrate systems integration capabilities.
Naval Combat Weapons Market Competitive Landscape
Capability concentration sits with specialized guidance electronics developers; scale advantage sits with diversified aerospace-defense conglomerates. The market structures around three tiers: prime systems integrators with shipyard relationships, component specialists in acoustic and electromagnetic sensors, and platform-agnostic munitions suppliers. Competitive positioning hardens through availability-based service contracts and sovereign supply chain mandates rather than unit price competition. Consolidation pressure operates through defense ministry industrial base policies and AUKUS-aligned technology-sharing requirements.
Within the prime integrator tier, BAE Systems and Leonardo exemplify geographic anchoring strategies that capture refurbishment and sustainment revenue. RTX occupies a position bridging component supply and networked weapons architecture. These three represent distinct competitive archetypes: British shipyard-integrated systems provision, European munitions specialization with torpedo production concentration, and US sensor-to-shooter networking technology.
| Leading Market Players |
|---|
| Terma |
| Leonardo |
| Thales Group |
| L3Harris Technologies |
| General Dynamics |
| BAE Systems |
| Lockheed Martin |
| Northrop Grumman |
| RTX |
| Others |
Supply & Pricing Matrix
Shipyard undercapacity in the United Kingdom and Australia is compressing weapons integration timelines and elevating premium pricing for certified naval munitions suppliers with available production slots. This utilization squeeze simultaneously tightens buyer negotiating leverage and rewards contractors holding sovereign security clearances.
Pricing Analysis
Long-term availability contracts now dominate procurement over discrete unit purchases, with navies contracting for guaranteed operational readiness rather than munitions inventories. Price differentiation rests on NAVAIR certification status and sovereign supply chain compliance, with US-certified systems commanding substantial premiums over non-certified alternatives. Pricing pressure stems from rare earth magnet cost volatility concentrated in Chinese refining capacity. Allied navies with integrated logistics contracts exhibit lowest price sensitivity, while emerging Southeast Asian fleet operators financing discrete platform acquisitions face acute budget constraints.
Supply Chain Analysis
Titanium alloy feedstock and rare earth element processing anchor upstream dependencies for pressure-resistant guidance electronics and specialized corrosion coatings. Manufacturing concentrates in the United States, United Kingdom, and Japan, with critical magnet and sensor inputs drawing from Chinese refining operations. Single-source vulnerability in processed rare earth supply creates structural exposure to export restriction risks. Distribution runs through prime integrators with shipyard relationships rather than direct munitions procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through availability-based contracting consolidation among NATO-aligned navies, fragmenting procurement authority away from discrete platform operators toward integrated logistics providers.
For Market Incumbents: Insulate revenue streams by deepening sovereign security clearance portfolios and capturing lifecycle sustainment contracts for aging destroyer fleets. Counter electromagnetic warfare talent scarcity through targeted acquisition of signal processing specialists. Prioritize backward integration into rare earth magnet alternative sourcing to reduce Chinese supply chain exposure. For New Entrants and Emerging Players: Southeast Asian littoral states with accelerating naval modernization programs present the most penetrable demand concentration. Target autonomous underwater vehicle weaponization as the fastest-expanding application segment with lower incumbent lock-in. Pursue technology transfer partnerships with established European torpedo specialists as the optimal go-to-market pathway. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across guidance systems development as counter-jamming algorithm investment requirements escalate. Long-term viability favors specialized acoustic sensor developers with established naval relationships over diversified aerospace conglomerates. Monitor AUKUS technology-sharing implementation pace as the critical inflection signal for undersea warfare system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Security Clearance Expansion | Unlocks access to classified weapons integration contracts with AUKUS partner navies. |
| Guidance Electronics Backward Integration | Captures margin from rare earth magnet substitution and sensor module production. |
| Availability-Based Service Contract Conversion | Transforms transactional munitions sales into recurring revenue with NATO procurement agencies. |
| Autonomous Targeting R&D Partnership | Positions for machine vision and acoustic fusion product categories in contested electromagnetic environments. |
| REACH Compliance Retrofit Service Launch | Captures legacy munitions refurbishment demand as EU chemical registration deadlines approach. |
Research Methodology
Desk research of defense procurement databases, NATO STANAG documentation, and national naval budget submissions preceded structured interviews with naval weapons program officers, shipyard integration engineers, defense contractor business development leads, and rare earth supply chain specialists. Secondary validation drew from US Congressional Research Service reports, UK Ministry of Defence equipment plans, Australian Defence Strategic Review publications, and customs trade data for titanium alloy and guidance component flows. Bottom-up segment sizing triangulated against top-down fleet modernization budget aggregation.
Assumptions regarding AUKUS technology-sharing implementation pace, NATO STANAG protocol adoption timelines, and rare earth supply chain stability were held fixed across the projection horizon, while fleet procurement volume and electromagnetic warfare investment intensity were varied. Segmentation modeling spanned weapon type, guidance technology tier, end-user procurement authority, and regional threat response priority. CAGRs were derived from fitted trend extrapolation against historical procurement cycles, with specific inputs including destroyer fleet age profiles and submarine force expansion commitments.
Macroeconomic conditions sit as an overlay; deviation in defense budget allocation priorities or allied technology-sharing political commitment would shift the trajectory. Forecasts reflect documented assumptions regarding procurement system evolution and supply chain configuration stability. Cross-checking against national parliamentary defense budget authorization benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Europe Naval Vessels Market
Naval Warfare
Global Naval Vessel MRO Market
Naval Warfare
Fast Attack Craft (FAC) Market
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Littoral Warship Market
Naval Warfare
Naval Missiles and Missile Launch Systems Market
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Naval Vessel Defense Systems Market
Naval Warfare
Military Marine Vessel Engines Market
Naval Warfare
Sea Skimmer Missile Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Combat Management System Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Amphibious Landing Craft Market