
 Sea Based C4ISR Market | 2026-2036
Sea Based C4ISR Market Size, Share, and Industry Trends Forecast 2026-2036
Sea Based C4ISR Market Analytics
Aftermarket service revenue for sensor integration and mission-system upgrades is tilting toward platform-agnostic architectures. Lockheed Martin leverages its Aegis combat system franchise to sustain long-term fleet modernization contracts across multiple navies. BAE Systems anchors trans-Atlantic submarine electronics programs through its UK-US engineering footprint. Thales competes on acoustic sensor specialization, particularly in sonar and underwater warfare domains where European navies maintain distinct requirements.
Sea Based C4ISR denotes naval command, control, communications, computers, intelligence, surveillance, and reconnaissance architectures operating from surface vessels, submarines, and maritime aircraft, typically integrating radar, electro-optical, and acoustic sensor streams through hardened data-fusion networks for real-time battlespace awareness. Communication Systems command the largest installed base given continuous fleet-wide networking refresh cycles, while Data Fusion technology represents the fastest-expanding segment as navies prioritize automated threat correlation across distributed sensor grids. Surveillance Systems occupy mature margin pools in fixed-wing maritime patrol, though UAV-based platforms are displacing legacy manned architectures in littoral zones.
The US Navy's Program Executive Office for Integrated Warfare Systems enforces open-architecture mandates that shape contractor R&D priorities, while NATO STANAG protocols govern cross-alliance interoperability and force European suppliers toward modular designs. The UK's Defence Equipment and Support authority and Australia's Defence Science and Technology Group coordinate AUKUS technology release frameworks, creating dual-track compliance obligations for multinational vendors. Stakeholders must monitor how classified data-sharing thresholds between allied procurement systems reshape competitive access to next-generation undersea surveillance programs.
Market Dynamics
Naval modernization programs across NATO member fleets are accelerating procurement of integrated command systems. The US Navy's distributed maritime operations doctrine and compliance with NATO STANAG interoperability standards are reshaping platform integration requirements.
Growth Catalysts
- Interoperability Mandates:NATO STANAG protocols force cross-alliance equipment compatibility, compelling navies to upgrade legacy C4ISR architectures toward modular, open-standard designs.
- Undersea Surveillance Expansion:AUKUS technology-sharing arrangements between the United States, the United Kingdom, and Australia are driving coordinated investment in next-generation submarine detection and acoustic sensor networks.
- Network-Centric Warfare Doctrine:The US Navy's distributed maritime operations framework prioritizes real-time data fusion across dispersed surface and subsurface platforms.
Market Restraints
- Classification Barriers:National security restrictions on sensitive acoustic and signals intelligence technologies fragment supplier access to allied procurement programs.
- Specialized Manufacturing Concentration:Production of radiation-hardened processors and submarine-grade pressure vessels concentrates among a limited set of qualified defense contractors.
- Extended Certification Cycles:Military qualification testing for maritime electronics stretches development timelines, compressing competitive windows for technology refresh.
Strategic Opportunities
- Unmanned Platform Integration:UAV-based maritime patrol architectures in littoral zones create demand for compact, low-power C4ISR payloads adapted from manned systems.
- Platform-Agnostic Architectures:Aftermarket service revenue for sensor integration is tilting toward hardware-agnostic middleware that operates across heterogeneous fleet vintages.
- AUKUS Pillar Two Technologies:Hypersonics, quantum sensing, and artificial intelligence development under trilateral agreements opens access to classified R&D funding streams.
Industry Challenges
- Cleared Workforce Scarcity:Security clearance requirements for systems engineering roles constrain staffing for classified submarine electronics programs.
- Legacy System Integration:Hardened data-fusion networks must interoperate with decades-old shipboard combat management systems without degrading real-time performance.
- Dual-Track Compliance:Multinational vendors face overlapping obligations from the US Navy's open-architecture mandates and European modular design standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sea Based C4ISR Market |
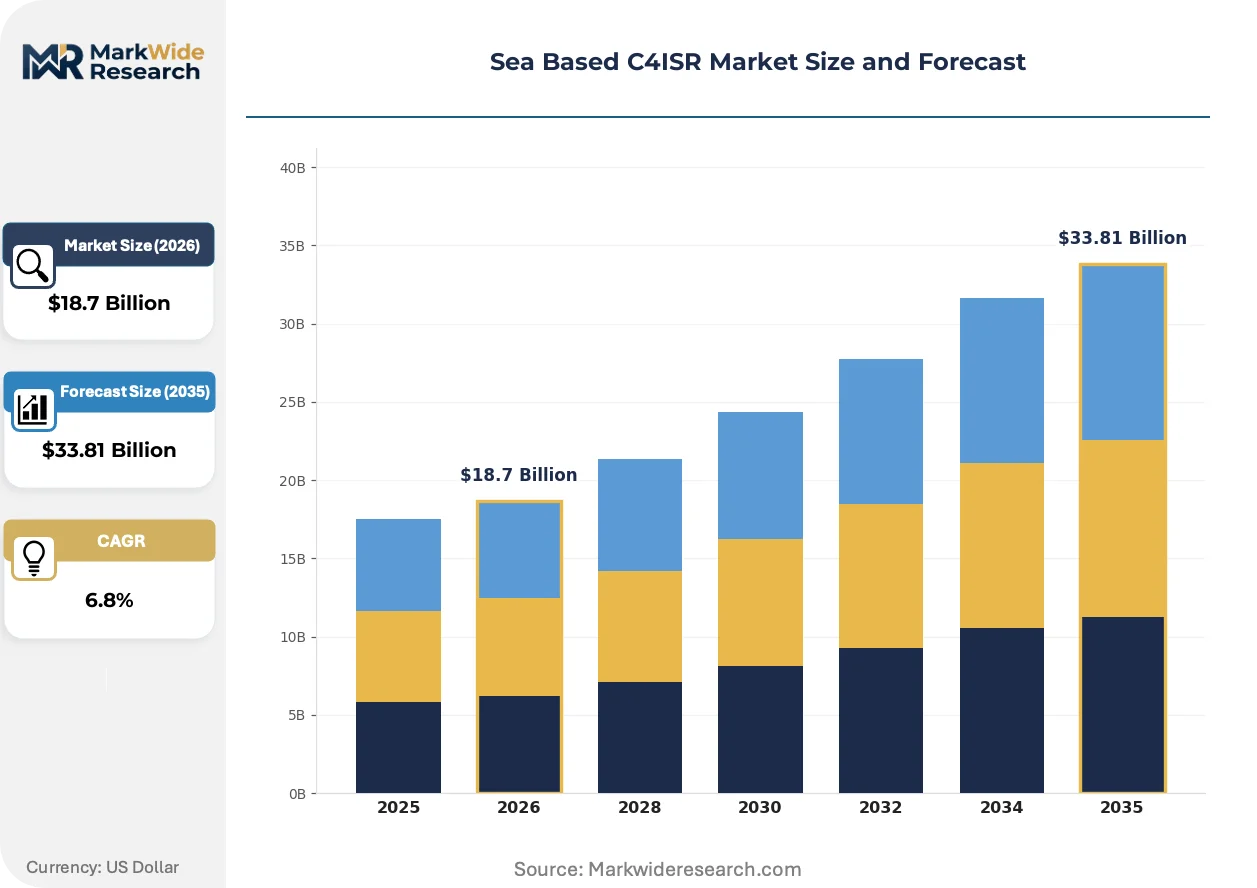
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Radar Systems, Communication Systems, Surveillance Systems, Control Systems Platform: Surface Ships, Submarines, UAVs, Fixed Wing Aircraft Application: Maritime Security, Anti-Submarine Warfare, Naval Operations, Intelligence Gathering Technology: Electro-Optical, Acoustic Sensors, Data Fusion, Satellite Communication |
| Companies Covered | Lockheed Martin Corporation, L3Harris Technologies, Inc., BAE Systems plc, Northrop Grumman Corporation, General Dynamics Corporation, RTX Corporation, Thales Group, Elbit Systems Ltd., Leonardo S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sea Based C4ISR Market Evolving Landscape
Artificial intelligence is compressing threat correlation timelines across distributed naval sensor grids. Automated decision-support tools are displacing manual operator workflows in combat information centers.
Software-defined radio architectures are digitizing legacy hardware-dependent communications systems. The US Navy's Program Executive Office for Integrated Warfare Systems mandates open-architecture interfaces that accelerate fleet-wide networking refresh cycles. European navies under NATO STANAG protocols are adopting modular radio configurations that swap frequency bands without physical hardware replacement.
The EU AI Act establishes risk-classification requirements for autonomous threat-detection algorithms deployed in maritime patrol aircraft. Military applications fall under high-risk categories demanding documented training data provenance and human oversight protocols. French and German naval aviation programs are restructuring procurement specifications to embed compliance checkpoints prior to operational deployment.
Buyer organizations are consolidating vendor relationships around long-term fleet modernization contracts rather than discrete platform acquisitions. The UK's Defence Equipment and Support authority and Australia's Defence Science and Technology Group coordinate multi-year technology roadmaps that bundle development, integration, and sustainment phases. This pattern compresses competitive entry points for new suppliers while rewarding incumbents with demonstrated AUKUS compliance histories.
Sea Based C4ISR Market Segmentation
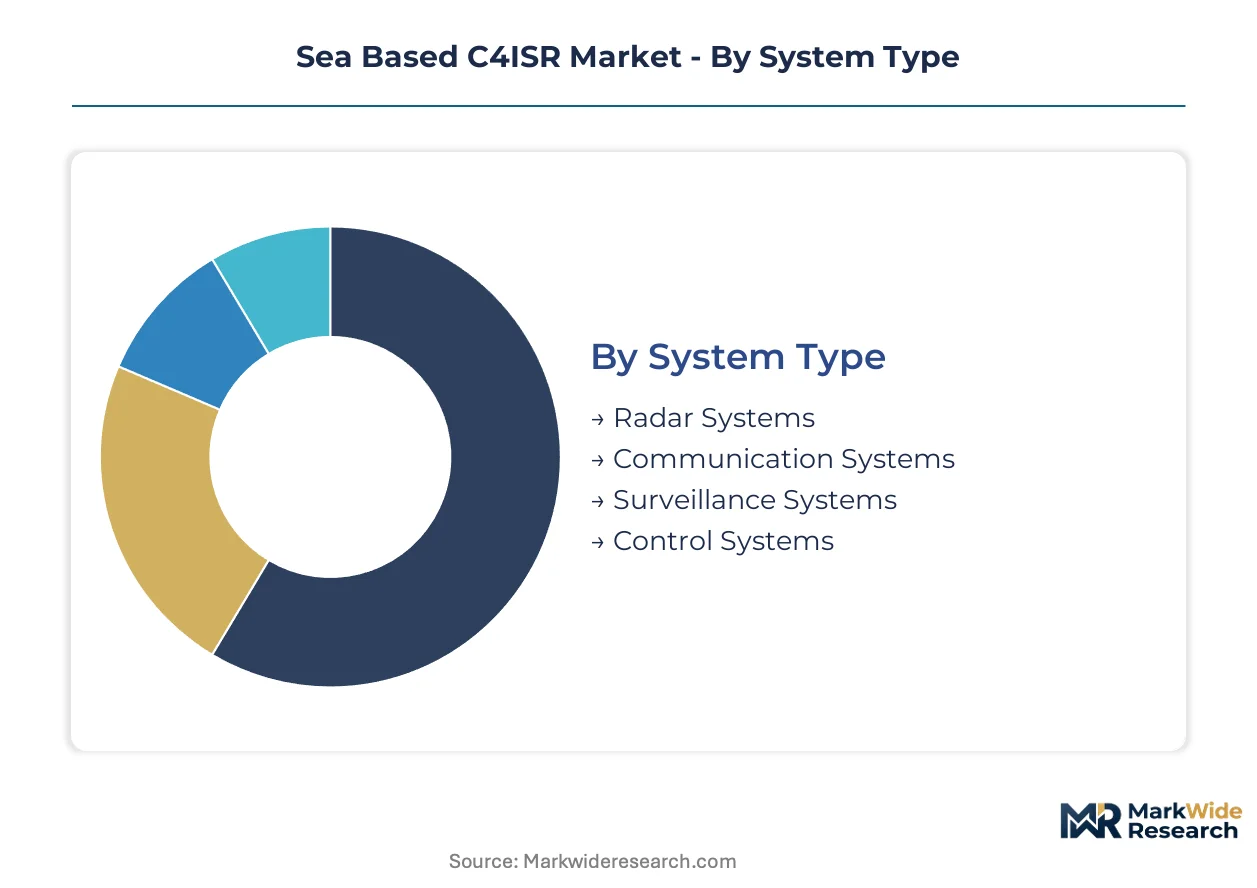
Sea Based C4ISR procurement patterns diverge sharply by operational environment and threat mission. Platform constraints, acoustic signatures, and data throughput requirements reshape component specifications across naval architectures.
System Type:
Naval operators deploy distinct sensor and command layers spanning detection, connectivity, and decision support.
- Radar Systems:Active electronically scanned arrays dominate surface combatant configurations for air and surface target tracking. The US Navy's distributed maritime operations doctrine drives demand for low-probability-of-intercept waveforms across Arleigh Burke-class destroyers.
- Communication Systems:Satellite-linked beyond-line-of-sight networks and tactical data links form the backbone of fleet-wide coordination. NATO STANAG interoperability mandates compel European navies toward software-defined radio architectures with modular frequency modules.
- Surveillance Systems:Integrated electro-optical and infrared suites provide passive target identification for rules-of-engagement decisions.
- Control Systems:Combat management computers execute threat evaluation and weapon assignment algorithms under electromagnetic interference conditions.
Established volume favors Communication Systems; emerging adoption favors Data Fusion integration layers.
Platform:
Host vessel characteristics dictate packaging constraints, power budgets, and survivability specifications.
- Surface Ships:Destroyers and frigates accommodate full-spectrum C4ISR suites with dedicated combat information centers. The US Navy's open-architecture mandates from PEO Integrated Warfare Systems accelerate refresh cycles across Ticonderoga and Burke-class hulls.
- Submarines:Acoustic stealth requirements limit topside sensor protrusions and mandate through-hull sonar arrays. AUKUS technology-sharing arrangements between the United States, United Kingdom, and Australia concentrate investment in next-generation undersea detection networks.
- UAVs:Compact maritime patrol drones displace manned platforms in littoral surveillance roles.
- Fixed Wing Aircraft:P-8 Poseidon and comparable platforms sustain long-endurance ocean patrol with integrated radar and signals intelligence payloads.
Procurement concentration tilts toward Surface Ships; capability expansion is climbing the fastest in Submarines under trilateral modernization programs.
Application:
Mission profiles determine sensor prioritization and data fusion algorithm training sets.
- Maritime Security:Exclusive economic zone patrol and counter-piracy operations emphasize electro-optical identification and non-lethal escalation pathways. Coast guard organizations in Australia and the United Kingdom favor modular C4ISR configurations for constabulary tasking.
- Anti-Submarine Warfare:Active and passive sonar processing demands specialized acoustic signal processing chains. The US Navy's integrated undersea surveillance system modernization drives towed array and hull-mounted sonar procurement.
- Naval Operations:Carrier strike group coordination requires real-time track management across distributed platforms.
- Intelligence Gathering:Signals intelligence collection suites intercept communications and electronic emissions for national-level analysis.
Defense budgets prioritize Naval Operations; steepest expansion trajectory appears in Anti-Submarine Warfare amid undersea domain awareness investments.
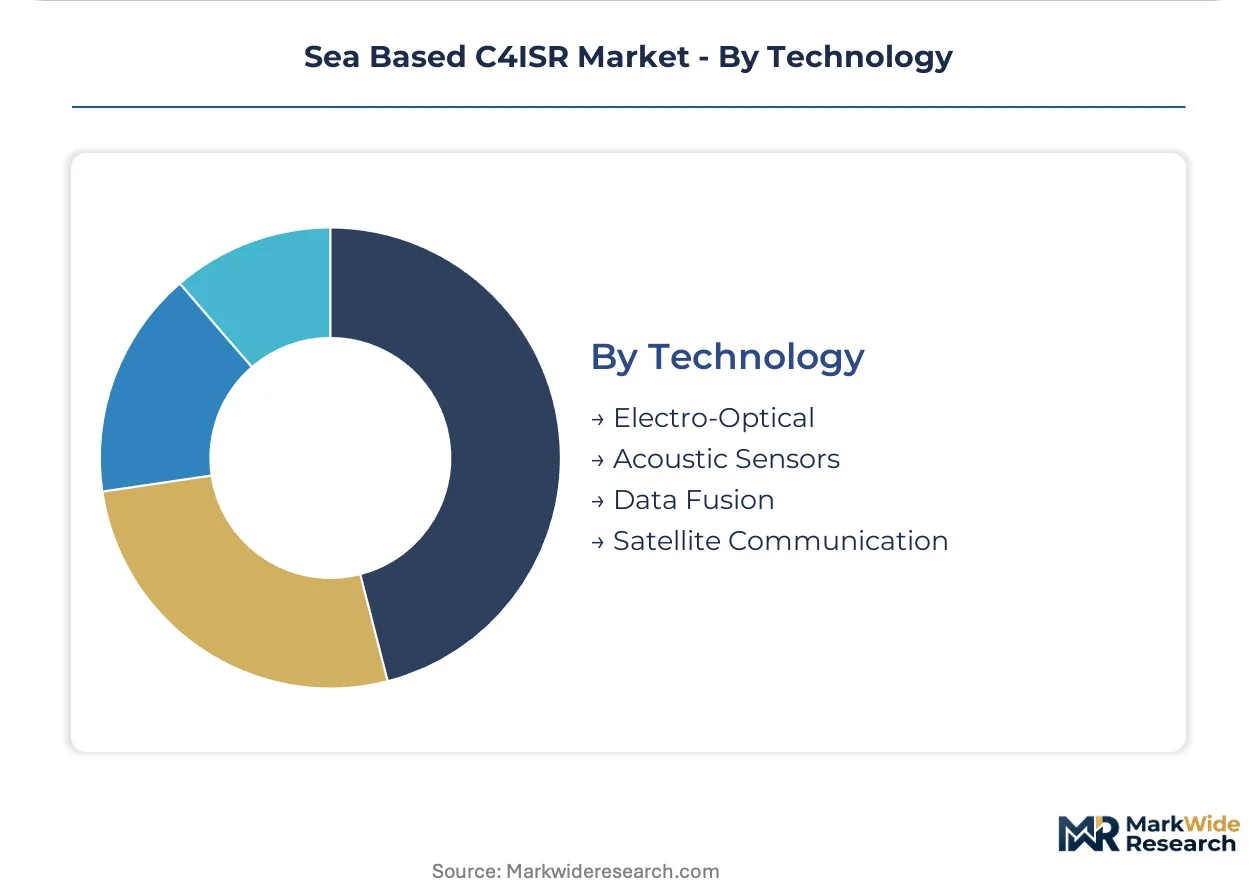
Technology:
Underlying sensor and processing technologies differentiate performance tiers and integration complexity.
- Electro-Optical:Stabilized multi-spectral cameras deliver positive identification at standoff ranges under varying atmospheric conditions. Surface combatants and maritime patrol aircraft integrate these systems for visual confirmation of radar contacts.
- Acoustic Sensors:Sonar arrays and underwater acoustic networks dominate submarine and anti-submarine warfare architectures. European navies maintain distinct requirements that shape Thales and specialized supplier product development.
- Data Fusion:Automated correlation algorithms integrate heterogeneous sensor streams into unified tactical pictures. The EU AI Act's high-risk classification mandates human oversight protocols for autonomous threat-detection systems in French and German naval aviation programs.
- Satellite Communication:Protected and wideband satellite links enable beyond-line-of-sight command connectivity for dispersed fleets.
Fielded inventory concentrates in Satellite Communication; capability modernization is gaining share fastest in Data Fusion under artificial intelligence integration programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Australia and the United Kingdom exhibit the lowest price elasticity, absorbing premium costs for AUKUS-compliant systems, while procurement offices in continental European navies operate under tighter budget constraints that favor modular, upgradeable architectures over platform-specific solutions.
United States
The US Navy's distributed maritime operations doctrine drives continuous fleet-wide networking refresh cycles across Arleigh Burke-class destroyers and Virginia-class submarines. The Program Executive Office for Integrated Warfare Systems enforces open-architecture mandates that reshape contractor R&D priorities toward interoperable designs. Defense contractors cluster around Washington DC, Norfolk, and San Diego, where systems integration facilities support Pacific Fleet readiness requirements.
United Kingdom
The UK's Defence Equipment and Support authority coordinates multi-year technology roadmaps that bundle development, integration, and sustainment phases for submarine electronics programs. AUKUS Pillar Two frameworks govern classified data-sharing thresholds for quantum sensing and artificial intelligence development. Engineering activity concentrates in Barrow-in-Furness for submarine construction and Bristol for maritime systems integration.
Australia
Australia's Defence Science and Technology Group manages technology release frameworks that create dual-track compliance obligations for multinational vendors seeking undersea surveillance contracts. The Royal Australian Navy's transition to nuclear-powered submarines under AUKUS Pillar One accelerates investment in acoustic sensor networks and combat management systems. Procurement activity clusters in Adelaide, Canberra, and Perth, where shipyard modernization supports fleet expansion timelines.
France
French naval aviation programs restructure procurement specifications to embed EU AI Act compliance checkpoints for autonomous threat-detection algorithms in maritime patrol aircraft. The Direction Générale de l'Armement oversees qualification testing that stretches development timelines for radiation-hardened processors. Industrial concentration in Toulouse and Paris-Saclay sustains electro-optical and data fusion capabilities for FREMM frigates and Barracuda submarines.
Germany
German shipyards under NATO STANAG protocols adopt modular radio configurations that swap frequency bands without physical hardware replacement, reducing long-term sustainment costs. The Federal Office of Bundeswehr Equipment, Information Technology and In-Service Support mandates interoperability certification for C4ISR components entering Type 212CD submarine programs. Systems engineering activity concentrates in Kiel, Hamburg, and Munich, where acoustic sensor specialists address European undersea warfare requirements.
Sea Based C4ISR Market Competitive Landscape
Systems integrators and sensor specialists split the market into complementary capability layers, with full-spectrum platform providers occupying long-term fleet modernization contracts while component-focused suppliers capture upgrade cycles for specific mission areas. The vendor base concentrates among cleared defense contractors with demonstrated AUKUS compliance histories, creating elevated barriers for new market entry. Two dominant competitive moves define current positioning: backward integration into classified software development to capture recurring sustainment revenue, and strategic partnerships with national procurement authorities to anchor multi-year technology roadmaps.
Within the full-spectrum systems integrator tier, Lockheed Martin Corporation and BAE Systems plc represent the archetype of platform-agnostic combat management franchises that sustain revenue across multiple allied navies. Thales Group occupies a position among European sensor specialists competing on acoustic and electro-optical domains where national sovereignty requirements preserve distinct procurement channels.
| Leading Market Players |
|---|
| Lockheed Martin Corporation |
| L3Harris Technologies, Inc. |
| BAE Systems plc |
| Northrop Grumman Corporation |
| General Dynamics Corporation |
| RTX Corporation |
| Thales Group |
| Elbit Systems Ltd. |
| Leonardo S.p.A. |
| Others |
Value Network & Pricing Analysis
Single-source dependency on radiation-hardened semiconductor foundries determines both tiered pricing spreads across mission-critical system tiers and supply chain concentration among cleared defense contractors serving NATO STANAG-compliant programs.
Pricing Analysis
Aftermarket service revenue tiers anchored by multi-year fleet modernization contracts drive lifetime value capture in this market. Pricing stratifies across AUKUS-compliant premium configurations, NATO-interoperable standard architectures, and national-customized economy tiers based on security clearance levels and integration complexity. Cost compression in sensor integration middleware is intensifying because platform-agnostic architectures displace proprietary hardware lock-ins. Coast guard and constabulary buyers exhibit highest price sensitivity, while nuclear submarine program offices absorb premium costs without elasticity.
Supply Chain Analysis
Upstream feedstock concentration in specialized acoustic sensor materials, radiation-hardened processors, and submarine-grade pressure vessel alloys draws from qualified supplier bases in the United States, United Kingdom, and France. Component dependencies rest on rare-earth magnet supply for sonar arrays, gallium nitride substrates for radar transmitters, and high-purity titanium for pressure hull penetrations. Single-source vulnerability concentrates in ITAR-controlled encryption modules and acoustic processing chipsets. Distribution runs through national procurement authorities with multi-year technology roadmaps bundling development, integration, and sustainment phases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
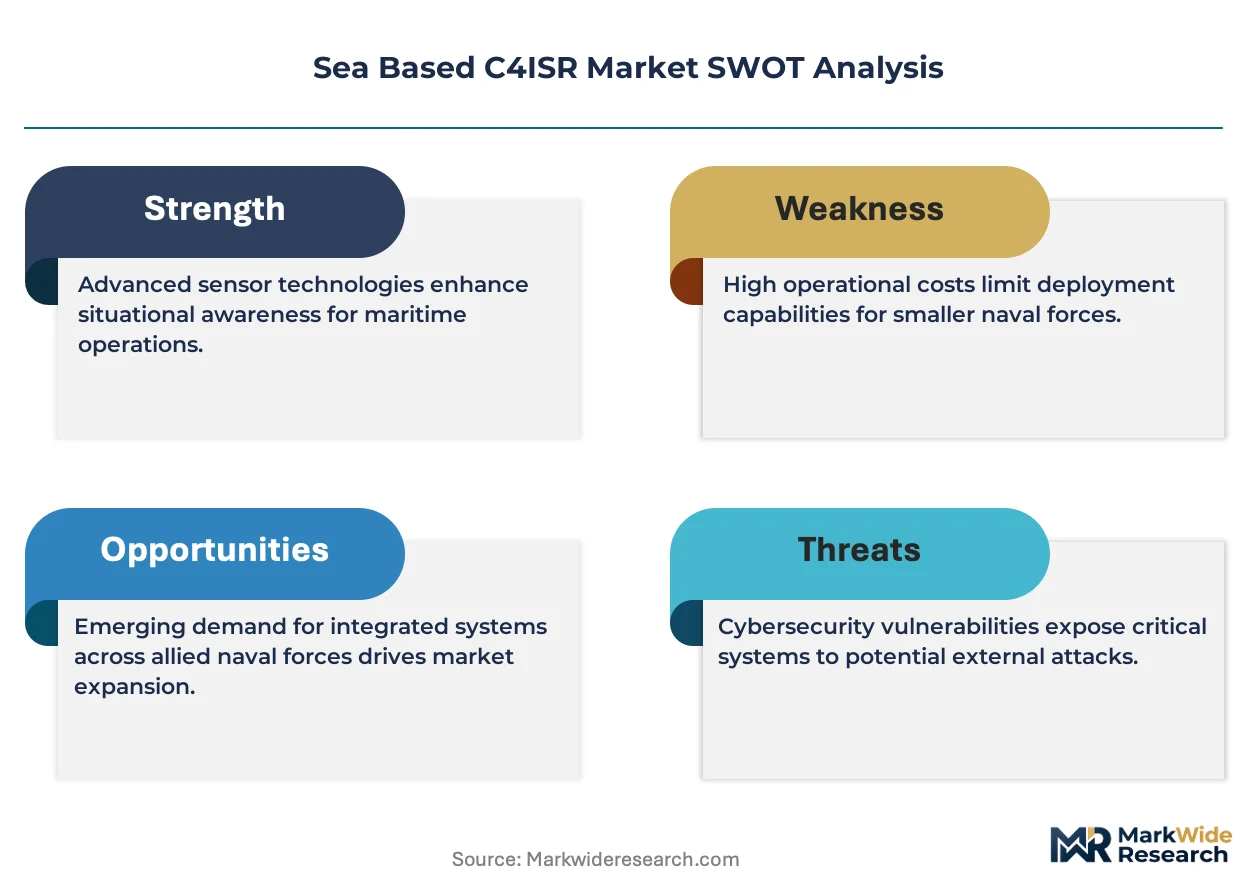
Software-defined architectures and commercial-off-the-shelf processing substitutes threaten incumbent hardware-dependent revenue streams, demanding active defense of platform-agnostic integration positions.
For Market Incumbents: Harden proprietary positions through backward integration into classified data-fusion algorithm development and exclusive anchoring of AUKUS Pillar Two technology roadmaps. Lockheed Martin's Aegis franchise demonstrates how combat system ecosystems capture recurring sustainment revenue across allied fleet modernization cycles. Counter emerging platform-agnostic middleware threats by embedding hardware-agnostic software layers within proprietary architectures.
For New Entrants and Emerging Players: Build out specialized acoustic sensor capabilities targeting European navies with distinct national sovereignty requirements outside AUKUS compliance frameworks. Unmanned maritime patrol platforms present the most penetrable white space, with compact C4ISR payload adaptation from manned systems offering lower clearance barriers. Pursue go-to-market angles through NATO STANAG modular radio certification as a stepping stone to broader fleet integration contracts.
For Investors and Strategic Acquirers: EU AI Act high-risk classification mandates reshape the acquisition landscape toward targets with documented training data provenance and human oversight protocol infrastructure. Five-to-ten year viability favors cleared defense contractors with demonstrated AUKUS compliance histories and recurring revenue from multi-year technology roadmaps. Monitor AUKUS Pillar Two funding release schedules as the primary inflection signal for next-generation quantum sensing and artificial intelligence development access. Cross-checking against national security clearance pipeline capacity is advised before commitment-grade decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| AUKUS Compliance Certification | Unlocks access to trilateral submarine electronics procurement pools across US, UK, and Australian naval programs. |
| Open-Architecture Mandate Adoption | Aligns R&D priorities with US Navy PEO Integrated Warfare Systems interoperability requirements for fleet-wide integration. |
| Platform-Agnostic Middleware Development | Captures aftermarket sensor integration revenue across heterogeneous fleet vintages without hardware lock-in dependency. |
| Acoustic Sensor Specialization | Addresses European naval sovereignty requirements where Thales and national champions maintain distinct procurement channels. |
| Cleared Workforce Expansion | Resolves staffing constraints for classified submarine electronics programs through security clearance pipeline investment. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with program executives at naval systems integrators, combat system engineers, procurement officers at national defense equipment authorities, and acoustic sensor specialists; alongside secondary validation through NATO STANAG protocol documentation, national defense budget appropriations, AUKUS technology release framework filings, and EU AI Act implementation guidance. Bottom-up segment sizing triangulated against top-down fleet modernization expenditure patterns.
Forecast inputs considered platform-specific installation bases, technology refresh cycle timing, interoperability mandate compliance deadlines, and trilateral technology-sharing arrangement progressions across the projection horizon. Segmentation modeling spanned system type, platform category, mission application, and underlying sensor technology dimensions. CAGRs derived from fitted growth curves accounting for extended military qualification timelines and multi-year procurement contract structures.
The forecast holds incumbent behavior within observed patterns; aggressive moves by quantum sensing startups or commercial space-based maritime surveillance providers would shift outcomes. Cross-checking against national defense budget authorization trajectories and classified program funding disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Aircraft Carrier Market
Naval Warfare
Anti-Ship Missile Defense System Market
Naval Warfare
Naval Combat Systems Market
Naval Warfare
Asia-Pacific Naval Vessels Market
Naval Warfare
Naval Radar Market
Naval Warfare
Naval Artillery System Market
Naval Warfare
Amphibious Landing Craft Market
Naval Warfare
Anti-Submarine Warfare Market
Naval Warfare
Naval Gas Turbine Market
Naval Warfare
Digital Shipbuilding Market
Naval Warfare
Combat Management System Market
Naval Warfare
Air and Naval Countermeasures Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Europe Naval Vessels Market
Naval Warfare
Africa Undersea Warfare Systems Market
Naval Warfare
Littoral Warship Market