
 Asia-Pacific Naval Vessels Market | 2026-2036
Asia-Pacific Naval Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Naval Vessels Market Outlook
Integrated electric propulsion and lithium-ion battery storage is rewriting how submarines and surface combatants achieve submerged endurance and acoustic stealth. China State Shipbuilding Corporation leverages captive supply chains across hull steel and propulsion systems to dominate domestic fleet replacement. Mitsubishi Heavy Industries Limited anchors Japan's maritime self-defense capabilities through specialized destroyer construction. LARSEN & TOUBRO LIMITED sustains India's strategic autonomy by competing across both naval and commercial shipbuilding segments.
Asia-Pacific naval vessels encompass surface combatants and submarines engineered to military specifications for displacement, draft, and weapons payload integration, primarily serving territorial defense, sea-lane protection, and power-projection missions. Frigate and destroyer segments absorb the largest share of procurement budgets as navies prioritize multi-role surface combatants with integrated air-defense suites. Submarine demand accelerates fastest across the technology dimension as lithium-ion battery propulsion and air-independent power systems displace traditional diesel-electric architectures. Weapons systems and command & control technologies concentrate margin pools where sovereign cybersecurity requirements limit foreign vendor participation.
Japan's Ministry of Economy, Trade and Industry (METI) and India's Ministry of Defence shape demand through local-content mandates and offset requirements that redirect procurement toward domestic shipyards. China's Ministry of Industry and Information Technology (MIIT) enforces GB standards and dual carbon goals that filter into naval propulsion efficiency targets and hull-material specifications. Stakeholders must monitor how Australia's AUKUS submarine commitment reshapes regional supply chains and whether India's PLI scheme for defense manufacturing expands to capture critical subsystem production.
Market Dynamics
Integrated electric propulsion architectures are compressing traditional mechanical drivetrain supply chains across Asia-Pacific naval procurement, forcing shipyards to requalify supplier bases around power electronics and battery integration competencies.
Growth Catalysts
- India's PLI scheme for defense manufacturing:Production-linked incentives redirect submarine component sourcing toward domestic foundries and specialized steel mills, building captive industrial capacity under the Make in India framework.
- Lithium-ion battery propulsion:Submerged endurance gains from solid-state energy storage are accelerating submarine procurement cycles across Southeast Asian navies seeking enhanced acoustic stealth.
- Australia's AUKUS commitment:Nuclear-powered submarine technology transfer agreements are reshaping regional alliance structures and driving allied shipyard coordination requirements.
Market Restraints
- Nickel and cobalt price volatility:Battery-grade mineral supply concentration in Indonesian and Philippine processing facilities creates input cost instability for lithium-ion submarine programs.
- Single-source dependency for air-independent power systems:German and Swedish fuel-cell technology licensors control critical intellectual property for extended submerged operations.
- MIIT hull-material specifications:China's domestic GB standards for high-tensile naval steel fragment regional interoperability and complicate cross-border maintenance protocols.
Strategic Opportunities
- Vietnam's blue-water expansion:Underpenetrated demand for corvette-class vessels creates openings for shipyards offering technology transfer packages with local assembly provisions.
- Dual carbon goals integration:China's military modernization directives are mandating energy-efficient hull designs that reward electric propulsion specialists with proven efficiency credentials.
- Convergence of autonomous underwater vehicles with mothership submarines:Unmanned system integration requirements are creating new specification categories for modular torpedo-tube launch interfaces.
Industry Challenges
- Naval architect scarcity:Specialized skills in hydrodynamic optimization for electric propulsion hull forms concentrate in Japanese and South Korean maritime engineering programs, constraining regional expansion.
- Classification society recertification timelines:Lloyd's Register and Bureau Veritas protocols for battery safety systems extend delivery schedules for first-of-class lithium-ion submarine builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Naval Vessels Market |
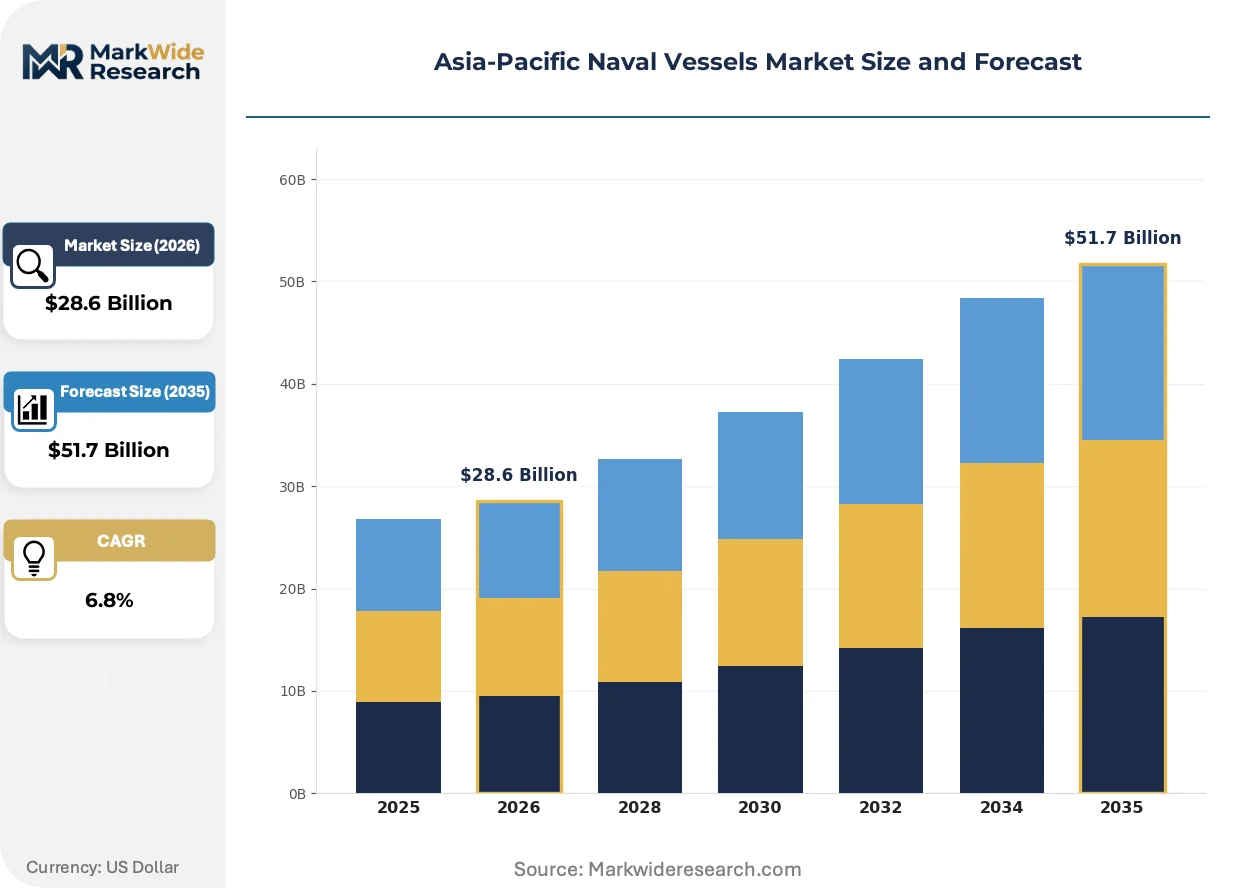
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Corvette, Frigate, Destroyer, Submarine Technology: Stealth, Command & Control, Weapons Systems, Propulsion End User: Naval Forces, Coast Guard, Defense Contractors, Research Institutions Deployment Mode: Onshore, Offshore, Amphibious, Support Operations |
| Companies Covered | China State Shipbuilding Corporation, LARSEN & TOUBRO LIMITED, Mitsubishi Heavy Industries Limited, Singapore Technologies Engineering Limited, Garden Reach Shipbuilders and Engineers Limited, Cochin Shipyard Limited, Kawasaki Heavy Industries Ltd, Mazagon Dock Shipbuilders Limited, HD Hyundai, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Naval Vessels Market Strategic Shifts
Propulsion electrification is fragmenting established mechanical engineering supply chains while sovereign cybersecurity mandates are constraining foreign vendor participation in command and control subsystems.
Air-independent propulsion technology is migrating from Stirling-cycle engines toward fuel-cell architectures using stored hydrogen. South Korean and Japanese submarine programs are accelerating fuel-cell adoption for operational endurance advantages. This transition is compressing demand for traditional diesel-electric generator sets and rewiring supplier relationships toward chemical storage specialists.
METI local-content mandates for Japan's maritime self-defense vessel construction are tightening domestic sourcing requirements for combat system integration. These regulations are elevating in-house electronics capabilities at specialized shipyards while excluding foreign radar and sonar vendors from core platform awards. Destroyer and frigate programs face extended qualification timelines for non-domestic subsystem alternatives.
Naval procurement offices across Southeast Asia are consolidating fleet modernization decisions under centralized defense acquisition authorities. Malaysia and Indonesia have shifted vessel specification authority from individual service branches to unified defense ministry structures, compressing vendor negotiation cycles and standardizing multi-role platform requirements. This concentration is visible in synchronized frigate replacement timelines across ASEAN member states.
Asia-Pacific Naval Vessels Market Segmentation
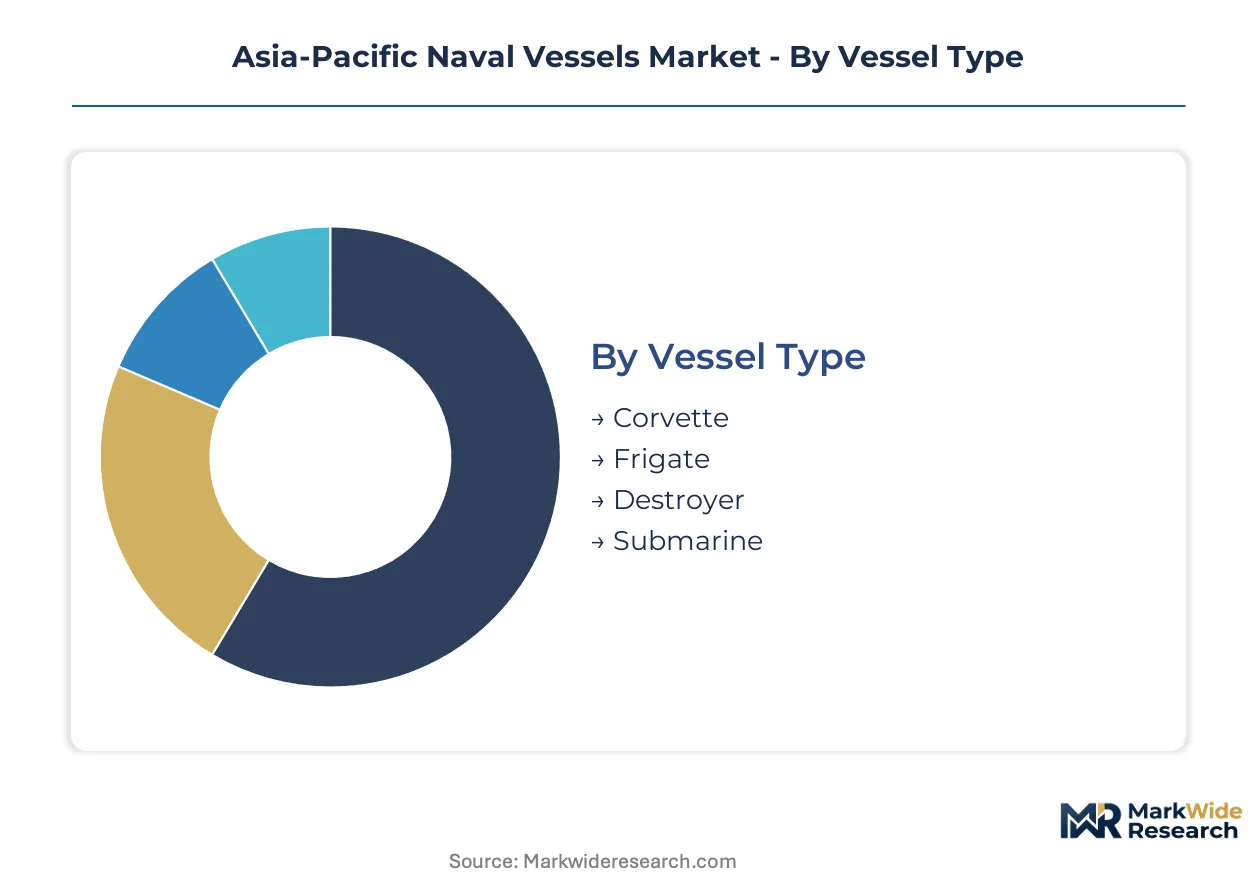
Segmentation reveals how procurement priorities diverge across Asia-Pacific naval modernization programs. Vessel type and technology choices determine maintenance infrastructure requirements and supplier qualification timelines for regional shipyards.
Vessel Type:
After-sales-service intensity peaks with submarines due to specialized dry-dock requirements and classified propulsion maintenance protocols.
- Frigate:Multi-role surface combatants integrate air-defense suites and anti-submarine warfare systems in hulls displacing 2,000-5,000 tonnes. India's Make in India framework concentrates frigate demand at domestic shipyards seeking technology transfer partnerships with European designers.
- Submarine:Diesel-electric and air-independent propulsion variants demand the most intensive through-life support, with battery replacement cycles and hull pressure testing creating recurring revenue streams for qualified service providers. Australia's AUKUS commitment redirects regional attention toward nuclear-powered sustainment capabilities.
- Destroyer:High-displacement combatants exceeding 7,000 tonnes carry integrated sensor networks requiring periodic combat system upgrades.
- Corvette:Coastal defense platforms under 2,000 tonnes suit Southeast Asian navies with constrained procurement budgets.
By volume, frigates lead procurement pipelines across ASEAN member states. By growth pace, submarines are ahead as lithium-ion propulsion and AIP systems displace legacy architectures.
Technology:
Cost tier separation is pronounced, with propulsion systems commanding premium pricing against commoditized hull steel.
- Propulsion:Integrated electric architectures and fuel-cell air-independent systems represent the highest-value subsystem category, with Chinese yards captive-producing power electronics under MIIT efficiency mandates while Japanese and South Korean programs import specialized fuel-cell stacks.
- Weapons Systems:Vertical launch systems, torpedo tubes, and naval gun mounts integrate with platform combat management systems under strict sovereign cybersecurity protocols that exclude foreign vendors from core integration roles.
- Command & Control:Combat management systems and sensor fusion networks require continuous software updates and classified maintenance access.
- Stealth:Radar-absorbent materials and hull-form optimization reduce acoustic and electromagnetic signatures.
Propulsion absorbs the largest share of platform unit cost. Weapons systems are expanding most quickly as navies prioritize multi-domain strike capabilities.
End User:
Customer type determines specification authority and contract structure, with naval forces retaining design control against contractor-led programs.
- Naval Forces:Uniformed service branches specify platform requirements and maintain operational control, driving procurement through defense ministry acquisition authorities in Malaysia, Indonesia, and Vietnam that have consolidated fleet modernization decisions under centralized structures.
- Defense Contractors:Prime integrators manage subsystem procurement and platform assembly under fixed-price or cost-plus contracts, with India's PLI scheme redirecting component sourcing toward domestic foundries.
- Coast Guard:Maritime law enforcement agencies prioritize patrol endurance and boarding capabilities over combat systems.
- Research Institutions:Naval research organizations commission experimental platforms and technology demonstrators.
Naval forces dominate unit volume. Defense contractors are gaining share fastest as governments outsource platform integration complexity.
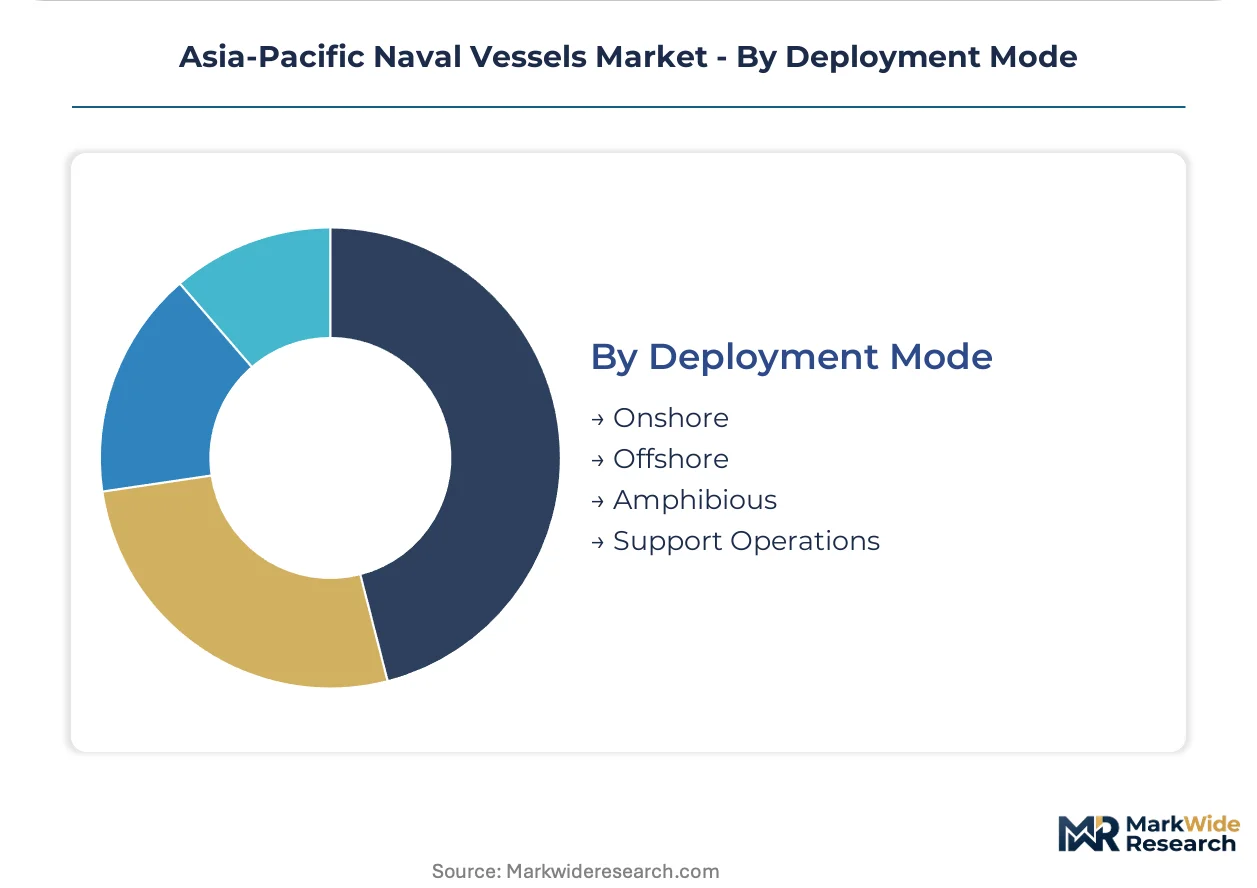
Deployment Mode:
Application context shapes platform specifications, with offshore operations demanding blue-water endurance against littoral constraints.
- Offshore:Blue-water patrol and power-projection missions require replenishment-at-sea compatibility and extended range, driving demand for larger frigates and destroyers across Japan's maritime self-defense expansion and Australia's regional presence requirements.
- Onshore:Port defense and territorial water patrol prioritize shallow-draft vessels with rapid response capabilities.
- Amphibious:Landing platform dock and assault ship categories support expeditionary operations.
- Support Operations:Fleet replenishment, salvage, and submarine rescue vessels sustain operational tempo.
Offshore deployment commands the largest vessel count. Amphibious platforms are climbing the fastest as regional powers invest in expeditionary capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean shipyards export lithium-ion battery propulsion systems to Southeast Asian navies modernizing submarine fleets. Japanese defense contractors supply integrated electric architectures to regional allies under technology transfer frameworks. Australian procurement decisions now cascade through AUKUS partnership structures, reshaping supplier relationships across the Indo-Pacific.
China
MIIT enforces GB standards for high-tensile naval steel and dual carbon efficiency mandates across military modernization programs. China State Shipbuilding Corporation operates captive supply chains spanning hull steel and power electronics. Dalian and Shanghai shipbuilding clusters dominate domestic fleet replacement and export contracts to Belt and Road partner navies.
India
The Ministry of Defence's PLI scheme redirects submarine component sourcing toward domestic foundries under Make in India procurement rules. Garden Reach Shipbuilders and Mazagon Dock compete for frigate and submarine awards with technology transfer requirements. Mumbai and Visakhapatnam harbor specialized facilities for pressure hull fabrication and combat system integration.
Japan
METI local-content mandates tighten domestic sourcing requirements for maritime self-defense vessel construction. Mitsubishi Heavy Industries anchors specialized destroyer production with in-house electronics capabilities. Kobe and Nagasaki shipyards concentrate advanced hydrodynamic engineering talent for electric propulsion hull form optimization.
Australia
The AUKUS nuclear-powered submarine commitment drives allied shipyard coordination and regional alliance restructuring. Defence procurement offices consolidate specification authority under centralized acquisition structures. Adelaide and Henderson facilities host submarine sustainment infrastructure and combat system upgrade capabilities.
South Korea
HD Hyundai accelerates fuel-cell air-independent propulsion adoption for operational endurance advantages in submarine programs. The country's national defense regulator shapes local-content requirements for combat system integration. Busan and Ulsan maritime engineering programs supply specialized naval architects for electric propulsion optimization.
Asia-Pacific Naval Vessels Market Competitive Environment
Channel-controlling players compete with product-specialist players across segmented procurement channels. State-affiliated shipyards dominate domestic fleet replacement through captive supply chains and sovereign contract awards. Three archetypes define competitive positioning: integrated prime contractors managing platform assembly, subsystem specialists supplying propulsion and weapons technologies, and state-owned enterprises leveraging policy-protected domestic markets. Capacity expansion and technology licensing represent the dominant competitive moves as shipyards requalify supplier bases around battery integration competencies.
Among Asia-Pacific-based fabricators, China State Shipbuilding Corporation exemplifies the state-integrated archetype through vertical control across hull materials and propulsion systems. Mitsubishi Heavy Industries occupies a position within the specialized defense contractor tier, anchoring Japan's maritime self-defense capabilities through platform integration expertise. LARSEN & TOUBRO LIMITED represents the diversified industrial conglomerate model, competing across both naval and commercial shipbuilding segments while sustaining India's strategic autonomy objectives.
| Leading Market Players |
|---|
| China State Shipbuilding Corporation |
| LARSEN & TOUBRO LIMITED |
| Mitsubishi Heavy Industries Limited |
| Singapore Technologies Engineering Limited |
| Garden Reach Shipbuilders and Engineers Limited |
| Cochin Shipyard Limited |
| Kawasaki Heavy Industries Ltd |
| Mazagon Dock Shipbuilders Limited |
| HD Hyundai |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency for German and Swedish fuel-cell air-independent propulsion technology compresses both pricing power for licensors and supply chain flexibility for Asian shipyards, widening cost spreads between premium fuel-cell submarine programs and legacy diesel-electric alternatives.
Pricing Analysis
Next-generation lithium-ion battery propulsion commands 40-60% premiums over prior-generation diesel-electric architectures across submarine procurement contracts. Three-tier pricing structure separates fuel-cell air-independent systems at premium levels, integrated electric propulsion at standard tiers, and conventional mechanical drivetrains at economy levels. Cost compression in economy-tier mechanical systems intensifies as Chinese yards achieve captive production of power electronics under MIIT efficiency mandates. Southeast Asian navies with constrained procurement budgets exhibit highest price sensitivity, while Australia's AUKUS commitment demonstrates lowest sensitivity due to nuclear technology transfer requirements.
Supply Chain Analysis
Tariff exposure between Indonesian nickel processing facilities and South Korean battery assembly plants dominates supply chain risk calculations for submarine propulsion programs. Geographic supply concentration centers on China for hull steel and power electronics, South Korea for fuel-cell stack integration, and Japan for specialized hydrodynamic engineering components. Raw material dependencies rest on nickel and cobalt from Indonesian and Philippine processing facilities, high-tensile naval steel from Chinese mills under GB standards, and lithium carbonate from Australian extraction operations. Single-source vulnerability for German and Swedish fuel-cell intellectual property creates procurement bottlenecks. Distribution runs through defense ministry acquisition authorities with consolidated specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized naval architect talent for electric propulsion hull form optimization concentrates in Japanese and South Korean maritime engineering programs, constraining regional expansion for shipyards lacking established training pipelines or technology licensing arrangements.
For Market Incumbents: Pre-empt emerging competition from Chinese yards expanding export contracts by securing exclusive fuel-cell technology licensing agreements with German and Swedish licensors before patent windows narrow. Anchor defensive positioning through backward integration into battery-grade mineral processing partnerships in Indonesia and the Philippines, mitigating nickel and cobalt price volatility that threatens margin stability across submarine programs. For New Entrants and Emerging Players: Pursue Vietnam's underpenetrated corvette-class vessel demand through technology transfer packages with local assembly provisions, leveraging consolidated defense ministry acquisition structures that compress vendor negotiation cycles. Target technology demonstration contracts for autonomous underwater vehicle integration with mothership submarines, where modular torpedo-tube launch interfaces represent specification categories without entrenched incumbent relationships. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors subsystem specialists with proven battery integration competencies over pure-play platform assemblers. Long-term viability across the projection horizon hinges on exposure to lithium-ion and fuel-cell propulsion architectures displacing legacy mechanical drivetrains. Acquisition targets should demonstrate active Lloyd's Register or Bureau Veritas certification progress for battery safety systems. Monitor classification society recertification timeline announcements as inflection indicators for first-of-class program delays that reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Fuel-Cell Technology Licensing | Secures operational endurance advantages for South Korean and Japanese submarine programs against Stirling-cycle competitors. |
| Backward Integration into Battery Minerals | Mitigates Indonesian and Philippine nickel-cobalt price volatility threatening lithium-ion submarine program costs. |
| Naval Architect Training Partnerships | Addresses hydrodynamic optimization scarcity constraining electric propulsion hull form development at emerging shipyards. |
| Classification Society Pre-Certification | Compresses Lloyd's Register and Bureau Veritas battery safety timelines that extend first-of-class submarine delivery schedules. |
| Autonomous Underwater Vehicle Integration | Creates modular torpedo-tube launch specification categories for unmanned system deployment from mothership submarines. |
Study Parameters
Desk research of customs and trade data, defense ministry procurement disclosures, and classification society certification records preceded structured interviews with naval program executives, shipyard procurement directors, maritime engineering faculty, and battery system technical leads. Primary fieldwork across Chinese, Indian, Japanese, South Korean, and Australian shipbuilding clusters combined with secondary validation against Lloyd's Register and Bureau Veritas protocol documentation. Bottom-up vessel delivery tracking and top-down defense budget allocation analysis provided triangulation anchors.
Forecast assumptions held fixed the AUKUS technology transfer timeline, MIIT dual carbon efficiency mandates, and India's PLI scheme structure while varying nickel-cobalt price trajectories and fuel-cell licensor availability. The analytical framework segmented by vessel type, propulsion technology, end user category, and deployment mode across the analysis window. CAGRs derived from defense ministry budget trajectory modeling and shipyard capacity utilization assessments. Industry-specific inputs incorporated submarine battery replacement cycle data and combat system upgrade frequency patterns for destroyer and frigate segments.
Macroeconomic conditions sit as an overlay; deviation in defense budget allocation priorities or critical mineral export restrictions would shift the trajectory. Forecasts reflect documented assumptions regarding technology transfer agreement progress and classification society protocol evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Naval Warfare
Naval Radar Systems Market
Naval Warfare
Naval Smart Weapons Market
Naval Warfare
Naval Vessels and Surface Combatants Market
Naval Warfare
Aircraft Carrier Market
Naval Warfare
Sea-Based Remote Weapon Systems Market
Naval Warfare
Littoral Warship Market
Naval Warfare
Naval Combat Systems Market
Naval Warfare
Aircraft Carrier Ship Market
Naval Warfare
Submarine Combat System Market
Naval Warfare
Air and Naval Countermeasures Market
Naval Warfare
Naval Gun System Market
Naval Warfare
Naval Combat Weapons Market
Naval Warfare
Military Frigate Market
Naval Warfare
Warship and Naval Vessels Market
Naval Warfare
Europe Naval Vessels Market
Naval Warfare
Bow and Stern Thrusters Market