
 Global Food Storage Container Market | 2026-2036
Global Food Storage Container Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Storage Container Market Analysis
Commercial foodservice operators is redrawing procurement patterns across the Global Food Storage Container Market as institutional buyers gain share over traditional household consumers. Tupperware Brands dominates direct-to-consumer channel relationships across emerging economies. Silgan Holdings anchors North American manufacturing scale through metal and composite container operations. Newell Brands leverages Rubbermaid's brand equity to sustain shelf presence in big-box retail.
Food storage containers are engineered receptacles fabricated from polymer resins, borosilicate glass, aluminum alloys, or food-grade silicone, designed to preserve organoleptic quality through moisture barriers, thermal insulation, and hermetic sealing mechanisms. Plastic remains the volume leader due to cost efficiency and injection-molding scalability, though glass commands premium positioning in health-conscious segments. Vacuum-sealed and airtight types capture the fastest expansion as sous-vide cooking and extended freshness protocols spread from restaurants to households. Modular systems concentrate margin pools through stackable interoperability and space-optimization value propositions.
FDA food-contact substance notifications govern polymer migration limits in the United States, while EFSA and REACH compliance requirements shape material selection across European supply chains. China's GB standards and SAMR food-contact regulations impose additional testing protocols for export-bound manufacturers. Stakeholders must monitor evolving extended producer responsibility frameworks and biopolymer certification schemes to align portfolio development with compliance trajectories.
Market Dynamics
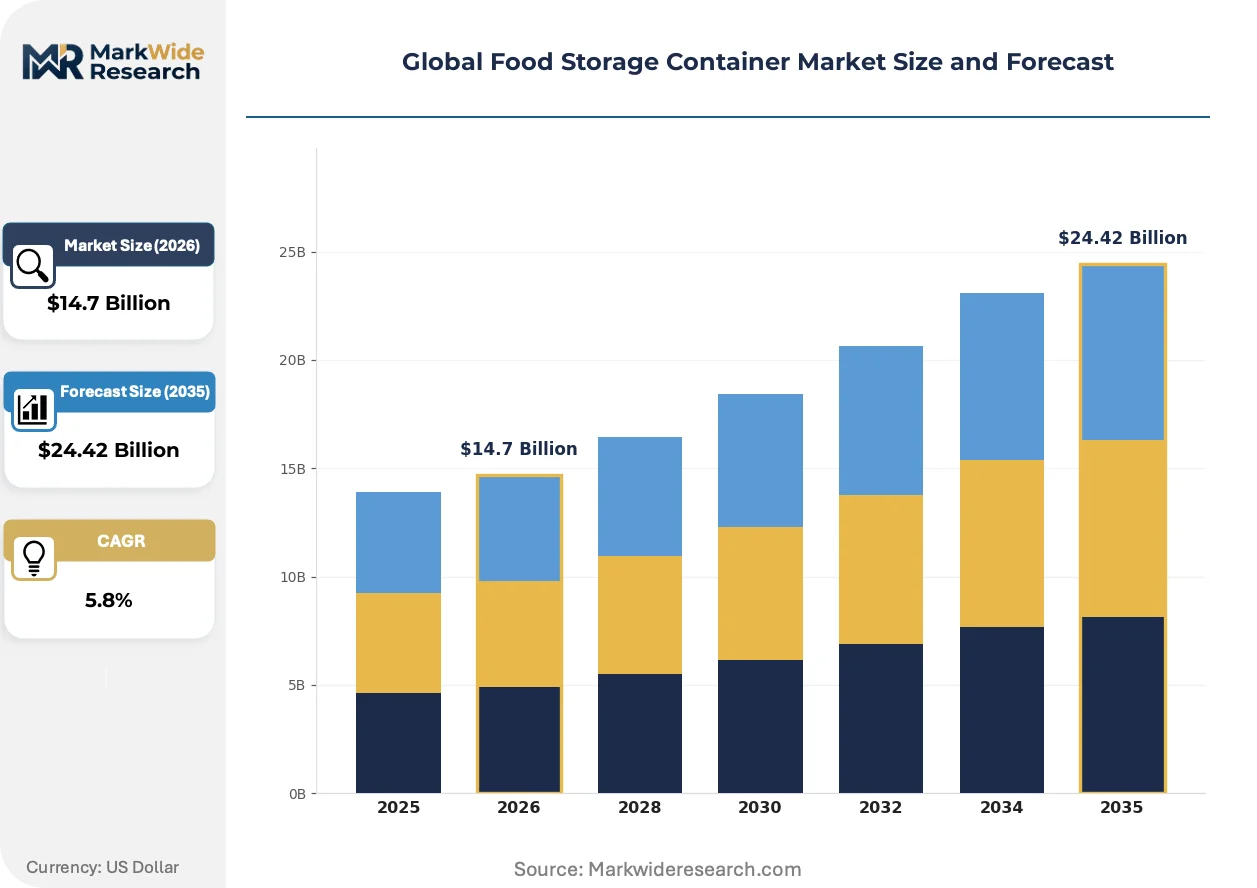
Commercial foodservice operators are redrawing procurement patterns as institutional buyers gain share over traditional household consumers, while tightening FDA food-contact material rules force material substitution across polymer supply chains.
Growth Catalysts
- Institutional Kitchen Modernization:Hospital and university foodservice directors are replacing single-use disposables with reusable container systems to meet waste-reduction mandates.
- REACH Compliance Migration:European manufacturers are accelerating phthalate-free polymer development to preempt EFSA migration limit revisions.
- Sous-Vide Protocol Expansion:Vacuum-sealed container demand is accelerating as precision cooking techniques migrate from restaurants to meal-prep subscription services.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyethylene resin costs swing with crude oil benchmarks, compressing margin stability for injection-molded product lines.
- Chinese Supply Concentration:Borosilicate glass lid manufacturing clusters in Shandong and Jiangsu provinces create single-point vulnerability for premium container brands.
- Silicone Substitution Ceiling:Platinum-cured silicone's temperature resistance tops out below 220°C, limiting penetration into high-heat commercial sterilization workflows.
Strategic Opportunities
- Indian Institutional Catering:IRCTC and corporate cafeteria operators are piloting modular stainless-steel container leasing programs for railway and IT campus feeding operations.
- EU Green Deal Packaging Mandates:The Packaging and Packaging Waste Regulation is creating certified compostable biopolymer demand for quick-service restaurant takeaway containers.
- Smart-Label Convergence:NFC-enabled freshness trackers are integrating with glass container lids, enabling premium positioning through spoilage-alert functionality.
Industry Challenges
- Migration Testing Bottlenecks:FDA food-contact substance notification queues now extend 18-24 months, delaying new polymer commercialization timelines.
- Retrofit Integration Friction:Automated dishwashing systems in legacy institutional kitchens require container dimension standardization that conflicts with proprietary modular designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Storage Container Market |
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $24.42 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Plastic, Glass, Metal, Silicone Type: Stackable, Vacuum-Sealed, Modular, Airtight End User: Households, Restaurants, Catering Services, Food Retailers Capacity: Small, Medium, Large, Extra-Large |
| Companies Covered | Amcor plc, Berry Global, Tupperware Brands, Silgan Holdings, Newell Brands, Plastipak Holdings, Lock & Lock, Rubbermaid, Ardagh Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Storage Container Market Emerging Trajectories
Material science breakthroughs and regulatory tightening are converging to reshape competitive positioning across container categories, with sustainability certification becoming a mandatory filter for institutional procurement.
Bio-based polymer formulations are fragmenting the traditional petroleum-derived plastic dominance in food storage applications. PHA and PLA blends now offer sufficient barrier properties for dry goods and refrigerated items. Whole Foods Market and regional co-op buyers are mandating biopolymer content minimums in private-label container specifications. This fragmentation is compressing commodity polypropylene volumes while opening margin pools for certified compostable alternatives.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are forcing fluoropolymer coating phase-outs in European markets. Manufacturers are pivoting to ceramic-reinforced silicone and plasma-treated glass surfaces for non-stick performance. Premium cookware brands with container extensions are most exposed, accelerating R&D partnerships with German coating specialists to maintain release properties without regulatory liability.
Meal-kit operators are consolidating supplier relationships around vertically integrated container-leasing platforms. HelloFresh and Sunbasket are piloting return-loop logistics where consumers ship used containers back for industrial sanitization and redeployment. This model is most advanced in Germany and the Netherlands, where reverse-logistics infrastructure and deposit-return mentalities reduce consumer friction compared to North American markets.
Global Food Storage Container Market Segmentation
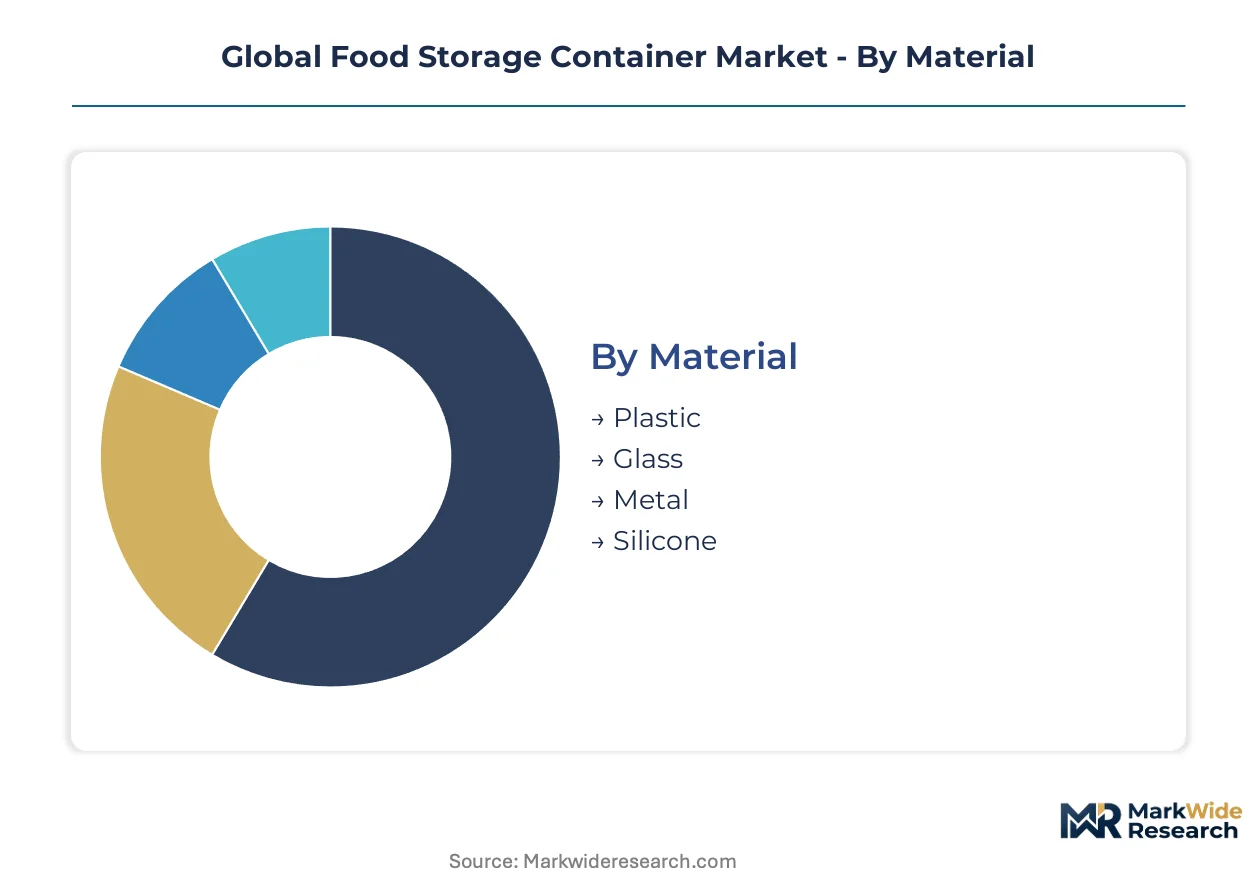
Food storage container procurement splits sharply between cost-driven institutional buyers and performance-seeking household segments. Material substitution pressures and end-use specification divergence create distinct margin pools across each axis.
Material:
Substitution pressure concentrates most intensely on petroleum-derived polymers as biopolymer barriers improve and regulatory migration limits tighten across FDA and REACH jurisdictions.
- Plastic:Polypropylene and polyethylene injection-molded containers dominate unit economics through high-speed manufacturing scalability. Hospital and university foodservice directors in the United States are replacing single-use disposables with reusable polypropylene systems to meet waste-reduction mandates, though phthalate-free reformulations face extended FDA notification queues.
- Glass:Borosilicate formulations command premium shelf positioning through thermal shock resistance and organoleptic neutrality. Shandong and Jiangsu province manufacturing clusters in China create supply vulnerability for lid components, constraining volume expansion for premium cookware brand extensions.
- Metal:Stainless-steel containers serve high-heat commercial sterilization workflows where silicone temperature ceilings fail. IRCTC railway catering and Indian IT campus operators pilot leasing programs for modular stainless systems.
- Silicone:Platinum-cured formulations offer collapsible convenience and microwave compatibility. Temperature resistance tops out below 220°C, limiting penetration into institutional autoclave protocols.
Plastic retains volume leadership; glass holds the steepest expansion curve.
Type:
Application-driven specification divergence separates household meal-prep convenience from commercial kitchen interoperability requirements.
- Stackable:Space-optimization value propositions drive modular system adoption. Big-box retail chains in the United States specify dimensional standardization for shelf efficiency.
- Vacuum-Sealed:Hermetic sealing mechanisms preserve organoleptic quality through oxygen exclusion. Sous-vide cooking technique migration from restaurants to meal-prep subscription services accelerates demand concentration.
- Modular:Interoperable component systems enable customized storage configurations. Proprietary designs conflict with legacy institutional dishwasher dimension requirements.
- Airtight:Moisture barrier performance targets dry goods preservation in humid climates. EFSA migration limit revisions are forcing gasket material reformulations across European supply chains.
Vacuum-sealed formats are gaining share fastest; stackable configurations maintain the broadest installed base.
End User:
Customer-type margin stratification reflects procurement sophistication divergence between institutional scale and household fragmentation.
- Households:Direct-to-consumer channels dominate through brand equity and convenience positioning. Health-conscious segments drive glass container premiumization.
- Restaurants:Food-contact material compliance and durability specifications govern purchasing. FDA food-contact substance notifications force material substitution across polymer supply chains.
- Catering Services:High-turnover logistics demand standardized container pools for sanitization efficiency. German and Dutch reverse-logistics infrastructure supports return-loop leasing models.
- Food Retailers:Private-label specifications increasingly mandate biopolymer content minimums. Whole Foods Market and regional co-op buyers drive certified compostable alternative adoption.
Households anchor volume absorption; catering services are climbing the fastest.
Capacity:
Volume-scale economics and storage footprint constraints shape specification patterns across end-use contexts.
- Small:Single-serve and condiment portions target meal-kit component packaging. Precision cooking protocols favor portion-controlled vacuum-sealed formats.
- Medium:Standard meal-prep and leftovers storage represents the most contested specification zone. Injection-molding scale economies concentrate manufacturing in high-volume resin processing centers.
- Large:Bulk ingredient storage and batch cooking applications drive institutional procurement. Space-optimization value propositions favor stackable interoperability.
- Extra-Large:Commercial kitchen and foodservice operations require reinforced structural integrity. Automated dishwashing system compatibility demands dimensional standardization.
Medium capacity commands the widest application footprint; small formats are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional procurement concentration in the United States, Germany, China, India, and Japan shapes regional demand trajectories for food storage containers. Each market exhibits distinct buyer archetypes and regulatory pressures that govern material selection and distribution channel development.
United States
Hospital and university foodservice directors drive reusable container adoption under waste-reduction mandates. FDA food-contact substance notifications extend 18-24 months, delaying phthalate-free polymer commercialization. Shandong and Jiangsu province manufacturing clusters supply borosilicate glass lid components to premium cookware brand extensions.
Germany
HelloFresh and Sunbasket pilot return-loop logistics for container leasing programs. REACH Annex XVII restrictions on per- and polyfluoroalkyl substances force fluoropolymer coating phase-outs. Reverse-logistics infrastructure in the Netherlands reduces consumer friction for redeployment models.
China
GB standards and SAMR food-contact regulations impose additional testing protocols for export-bound manufacturers. Dual carbon goals accelerate biopolymer development for quick-service restaurant takeaway containers. Yangtze River Delta injection-molding centers concentrate polypropylene volume production.
India
IRCTC railway catering and IT campus operators pilot modular stainless-steel container leasing programs. FSSAI compliance requirements govern food-contact material specifications for institutional feeding operations. Maharashtra and Gujarat fabrication clusters supply high-heat sterilization-grade metal systems.
Japan
Precision cooking technique migration drives vacuum-sealed container demand in meal-prep subscription services. METI standards shape silicone temperature resistance specifications for microwave-compatible formulations. Kanto region retail chains specify dimensional standardization for shelf efficiency.
Global Food Storage Container Market Vendor Landscape
Player mix skews toward diversified packaging conglomerates with captive polymer processing capabilities. Consolidation pressure concentrates manufacturing scale among vertically integrated resin-to-container operators. Three archetypes dominate: direct-to-consumer heritage brands, North American metal-and-composite specialists, and Asian precision-molding exporters. Competitive moves center on biopolymer certification partnerships and automated dishwashing compatibility standardization.
Among heritage direct-to-consumer operators, Tupperware Brands and Lock & Lock exemplify channel control through established household relationships. Silgan Holdings and Newell Brands occupy positions in North American institutional supply chains through metal fabrication scale and Rubbermaid brand equity respectively. These four anchors represent divergent strategic vectors: brand-driven household penetration versus specification-driven foodservice procurement.
| Leading Market Players |
|---|
| Amcor plc |
| Berry Global |
| Tupperware Brands |
| Silgan Holdings |
| Newell Brands |
| Plastipak Holdings |
| Lock & Lock |
| Rubbermaid |
| Ardagh Group |
| Others |
Supply Flow & Price Mechanics
FDA food-contact substance notification queues extending 18-24 months simultaneously gate supply qualification and stratify price tiers across polymer container categories, forcing buyers to pay premiums for pre-certified materials or absorb extended commercialization delays.
Pricing Analysis
Current-generation phthalate-free polypropylene commands 15-25% premiums over legacy formulations, while next-generation PHA and PLA biopolymers occupy super-premium positioning above both. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in commodity polypropylene is intensifying because Shandong and Jiangsu manufacturing clusters face energy cost volatility. Institutional foodservice buyers exhibit lowest price sensitivity due to waste-reduction mandate compliance requirements, while household segments in emerging economies drive volume through economy-tier procurement.
Supply Chain Analysis
Just-in-time resin procurement dominates North American and European molding operations, while Chinese manufacturers maintain strategic stockpiles of polypropylene and polyethylene feedstocks to buffer crude oil benchmark volatility. Supply concentrates in China, the United States, and Germany for injection-molded components, with borosilicate glass lid fabrication anchored in Shandong and Jiangsu provinces. Raw material dependencies span petroleum-derived resins, platinum-cured silicone, and food-grade stainless steel. Single-source vulnerability in Chinese glass manufacturing creates supply chain risk for premium cookware brand extensions. Distribution runs through big-box retail chains, direct-to-consumer platforms, and institutional foodservice procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container-leasing and return-loop logistics represent a service-attach opportunity expanding faster than hardware sales, as HelloFresh and Sunbasket pilot models where recurring sanitization and redeployment revenues outpace one-time container purchases.
For Market Incumbents: Consolidate manufacturing scale through backward integration into resin compounding operations to offset petrochemical feedstock volatility. Lock in biopolymer certification partnerships with BPI and TÜV Austria to preempt EU Green Deal Packaging mandates. Channel control through exclusive institutional foodservice contracts defends against emerging modular stainless-steel leasing specialists. For New Entrants and Emerging Players: FDA food-contact substance notification fast-tracks for phthalate-free polymer formulations open white-space in premium household segments. Target Indian IRCTC railway catering and IT campus feeding operations with modular stainless-steel leasing programs. Go-to-market through vertically integrated container-leasing platforms bypasses established retail shelf competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates seeking to divest non-core food-contact container divisions. Long-term viability centers on biopolymer transition completion and automated dishwashing compatibility standardization. Acquisition target archetype: mid-cap specialists with captive PHA/PLA formulation capabilities and existing FDA notification clearances. Signal to watch: REACH Annex XVII expansion beyond per- and polyfluoroalkyl substances to additional polymer additives.| Strategic Initiative | Industry Significance |
|---|---|
| Biopolymer Certification Partnership | BPI and TÜV Austria certifications unlock EU Green Deal Packaging Regulation compliance for quick-service restaurant takeaway containers. |
| Container-Leasing Platform Launch | Return-loop logistics integration with HelloFresh and Sunbasket pilots captures recurring sanitization revenues in Germany and the Netherlands. |
| Backward Integration into Resin Compounding | In-house polypropylene formulation capabilities insulate margin stability from crude oil benchmark volatility. |
| Automated Dishwashing Compatibility Standardization | Dimensional interoperability with legacy institutional kitchen systems removes retrofit friction blocking modular adoption. |
| Smart-Label Convergence Development | NFC-enabled freshness tracker integration with glass container lids enables premium positioning through spoilage-alert functionality. |
Methodological Framework
A standing panel of foodservice procurement directors, polymer R&D leads, retail category buyers, and regulatory affairs specialists provided ongoing calibration across primary interview rounds and secondary validation. FDA food-contact substance notification databases, EFSA migration limit guidance documents, SAMR GB standard filings, and customs trade records anchored bottom-up volume estimation. Top-down triangulation against macroeconomic indicators and petrochemical feedstock pricing benchmarks ensured cross-method consistency.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation dimensions modeled include material type, container format, end-user category, and geographic regulatory cluster. CAGRs were derived from fitted growth curves applied to base-year market sizing, with sensitivity analysis around institutional procurement acceleration scenarios and biopolymer substitution elasticity. Industry-specific forecast inputs incorporated hospital waste-reduction mandate adoption curves and meal-kit subscription service expansion trajectories.
Underlying assumptions cover FDA notification queue duration stability, REACH Annex XVII enforcement intensity, and Chinese dual carbon goal implementation pace, with deviation risk concentrated in petrochemical feedstock price volatility and biopolymer barrier property improvement rates. Revision becomes warranted when institutional leasing program adoption crosses 15% penetration in any single national market.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Thin Wall Plastic Containers Market
Containers
Canning Jars Market
Containers
Clear Hinged Container Market
Containers
PET Hinged Containers Market
Containers
Container Coating Market
Containers
Steel Containers Market
Containers
Jug Shipper Market
Containers
Roll Containers Market
Containers
Packaging Bins Market
Containers
Foldable Container Market
Containers
Multi Cavity Tray Market
Containers
Lab Storage Container Market
Containers
LDPE Containers Market
Containers
Trays Market
Containers
Global Container Monitoring Market
Containers
Feeder Containers Market