
 Collapsible Sleeve Containers Market | 2026-2036
Collapsible Sleeve Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Collapsible Sleeve Containers Market Analysis
The EU Packaging and Packaging Waste Regulation is expanding compliance obligations for reusable transport packaging across member states. DS Smith plc leverages its European fiber-based sleeve portfolio to capture food-grade returnable flows. Schoeller Allibert Services B.V. sustains leadership in injection-molded polypropylene sleeves through captive tooling capacity. ORBIS Corporation dominates North American automotive sleeve programs with plant locations clustered near Detroit, Nashville, and Spartanburg.
Collapsible sleeve containers are rigid or semi-rigid receptacles with fold-down sidewalls, typically fabricated from corrugated polypropylene, high-density polyethylene, or laminated fiberboard, designed to collapse to one-quarter or less of assembled height for empty return transport. Their primary purpose is to replace single-use shipping boxes in closed-loop supply chains, cutting return freight volume and eliminating disposable packaging spend. Plastic sleeve variants lead on durability and washability in pharmaceutical and food verticals, while paper-based formats anchor cost-sensitive consumer goods applications where limited trip cycles suffice. Metal-reinforced edge options occupy a premium niche in heavy industrial storage where load stacking exceeds five hundred kilograms.
The U.S. Food and Drug Administration maintains migration limits for food-contact polypropylene under 21 CFR 177.1520, directly shaping resin selection for collapsible sleeve containers serving dairy and produce distribution. The EU REACH regulation restricts phthalate plasticizers in sleeve coatings, while ISO 18600 series standards govern reusability declarations in European procurement tenders. Stakeholders must monitor evolving extended producer responsibility fee structures, as these will determine whether sleeve pooling models or outright purchase contracts deliver lower total cost of ownership across the forecast horizon.
Market Dynamics
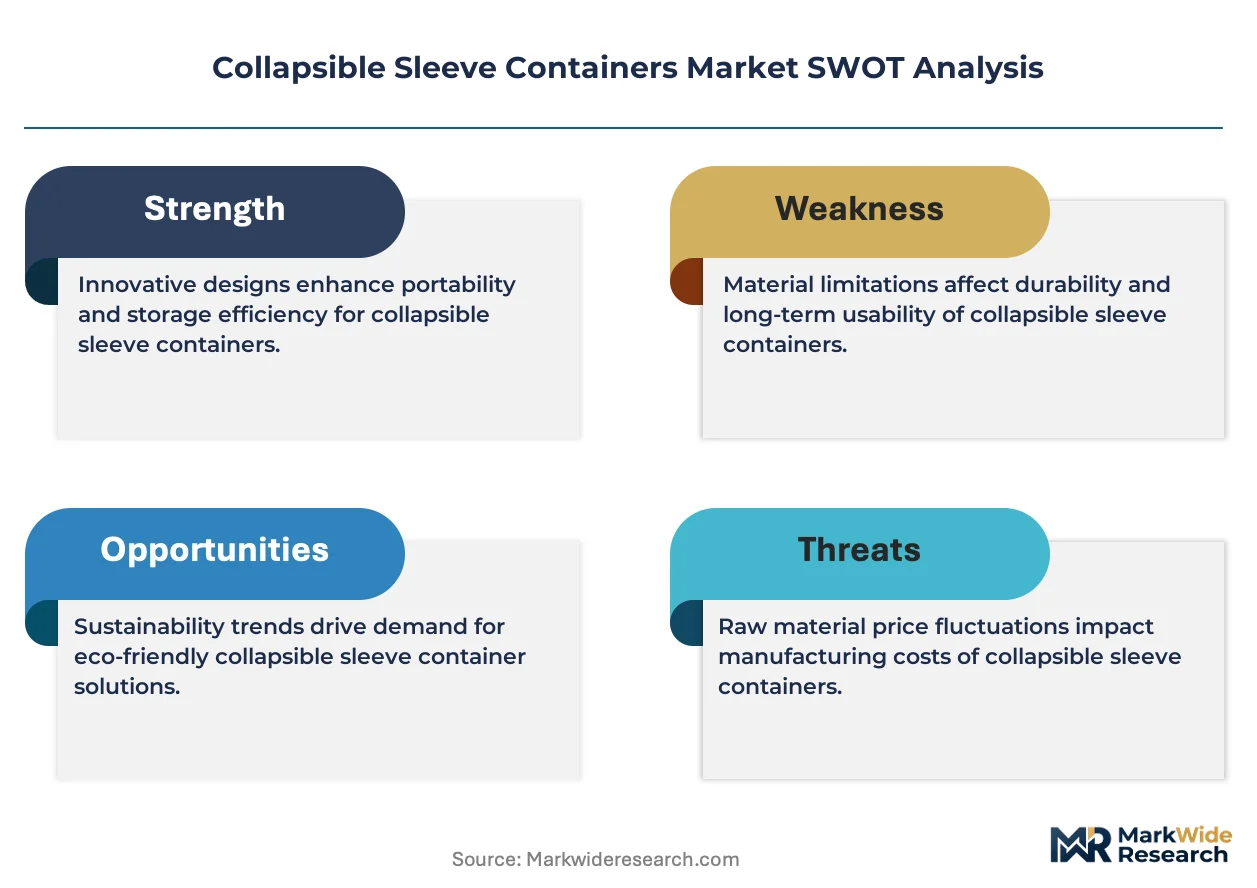
The EU Packaging and Packaging Waste Regulation is forcing converters toward mono-material polypropylene designs, collapsing the technical diversity that previously segmented sleeve container suppliers by material specialty.
Growth Catalysts
- Automotive just-in-sequence delivery:German component suppliers deploy sleeve systems to synchronize assembly line feeds with tiered supplier networks. The operational savings from reduced empty-haul fuel consumption compound across multi-tier supply chains.
- REACH compliance on plasticizers:ECHA restrictions on phthalate coatings in sleeve finishes are accelerating migration to compliant polypropylene formulations. Food-grade pooling operators gain procurement preference in EU closed-loop tenders.
- Corrugated polypropylene durability:Washable plastic sleeve variants displace fiberboard in pharmaceutical distribution where trip cycle counts exceed fifty rotations. Sterilization compatibility extends reuse intervals.
Market Restraints
- Resin price volatility:Polypropylene feedstock costs fluctuate with propylene monomer supply disruptions from Gulf Coast petrochemical complexes. Converter margins compress during input spikes without pass-through contract terms.
- Tooling concentration in Germany:Captive injection mold capacity for sleeve frames clusters around Stuttgart and Munich tooling houses. New entrants face eighteen-month lead times for qualified production equipment.
- Fiberboard substitution ceiling:Paper-based sleeves fail moisture resistance thresholds in cold-chain produce logistics. Temperature excursion damage limits fiberboard penetration in fresh food verticals.
Strategic Opportunities
- North American automotive expansion:Tiered suppliers near Detroit, Nashville, and Spartanburg lack sufficient sleeve pooling infrastructure. Regional service gaps create entry points for European operators with proven plant location models.
- ISO 18600 reusability certification:Procurement tenders across EU member states are mandating standardized trip-count declarations. Early certifiers capture specification advantages in public-sector packaging contracts.
- RFID-embedded inventory tracking:Sleeve fleets with integrated transponders enable real-time location monitoring. Pharmaceutical distributors in Switzerland and the Netherlands pilot subscription-based fleet management services.
Industry Challenges
- Multi-material recycling infrastructure:Laminated fiberboard sleeves with metal edge reinforcements require specialized separation processes. Municipal sorting facilities in France and Italy reject mixed-material loads, creating end-of-life liability for pooling operators.
- Legacy warehouse automation compatibility:Existing conveyor and storage-retrieval systems dimensioned for rigid totes demand retrofit investment. Distribution centers face downtime costs during sleeve system integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collapsible Sleeve Containers Market |
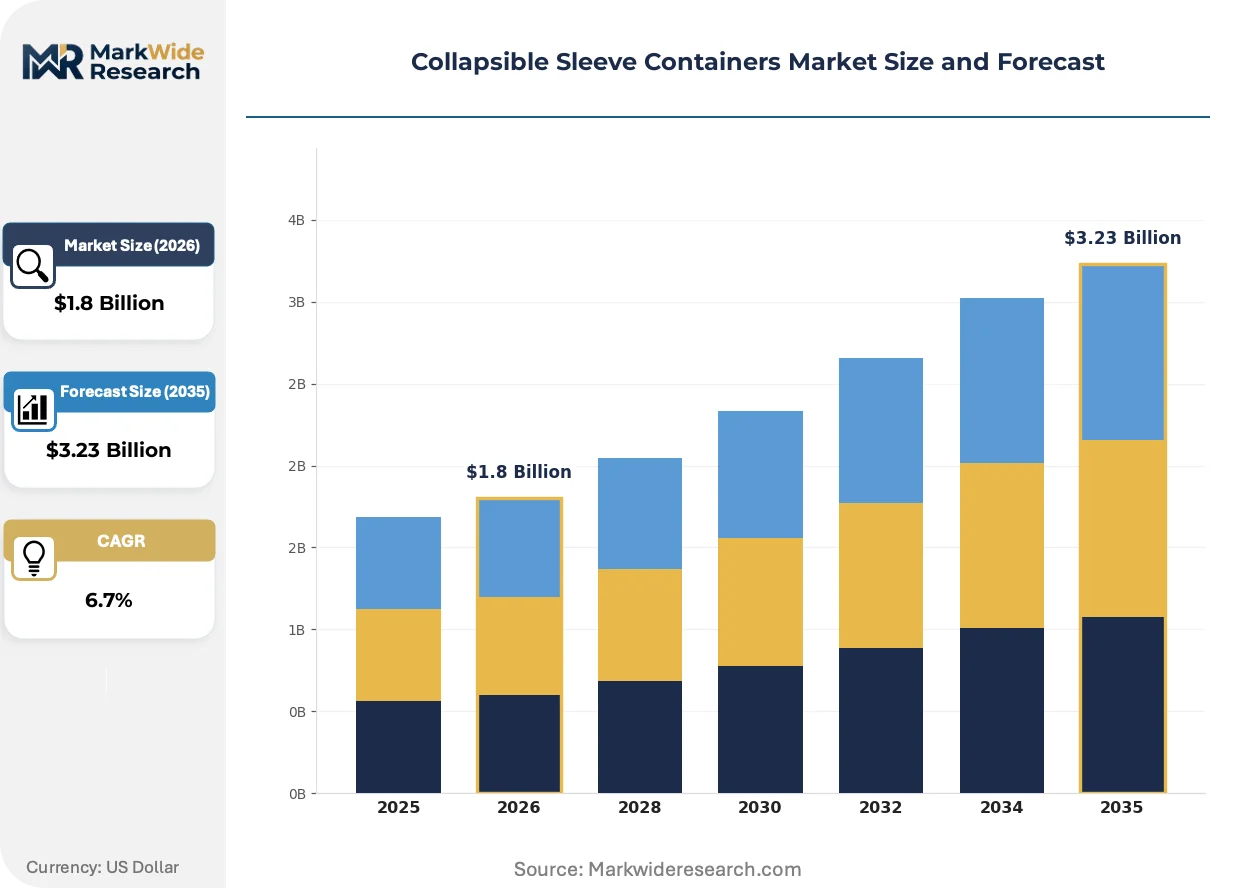
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Metal, Glass, Paper Application: Packaging, Shipping, Storage, Marketing Industry Vertical: Food & Beverage, Pharmaceuticals, Cosmetics, Consumer Goods Distribution Channel: Retail, Online, Direct Sales, Distributors |
| Companies Covered | DS Smith plc, Schoeller Allibert Services B.V., ORBIS Corporation, Buckhorn Inc., Rehrig Pacific Company Inc., TranPak Inc., RPP Containers, CABKA Group, SSI Schaefer Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collapsible Sleeve Containers Market Emerging Trajectories
Active material science development and regulatory compliance automation are compressing product development cycles while expanding the addressable application set for sleeve container systems.
Fold-down hinge mechanisms using glass-reinforced polypropylene are modularizing frame assembly processes. Tier one automotive suppliers in Germany specify interchangeable corner posts and base decks to standardize fleet configurations across multiple OEM programs. This interoperability is modularizing supplier qualification requirements and reducing tooling duplication.
EU REACH Annex XVII updates on substance restrictions are tightening coating migration limits for food-contact applications. Sleeve converters serving dairy distribution must reformulate anti-slip finishes to maintain compliance. The regulatory pressure is accelerating laboratory certification investments among mid-size European producers.
Fleet leasing models are displacing outright purchase contracts in pharmaceutical logistics. Third-party pooling operators in Switzerland and the Netherlands assume capital burden and maintenance liability. This financial restructuring concentrates buyer decision authority with procurement functions rather than operations engineering.
Collapsible Sleeve Containers Market Segmentation
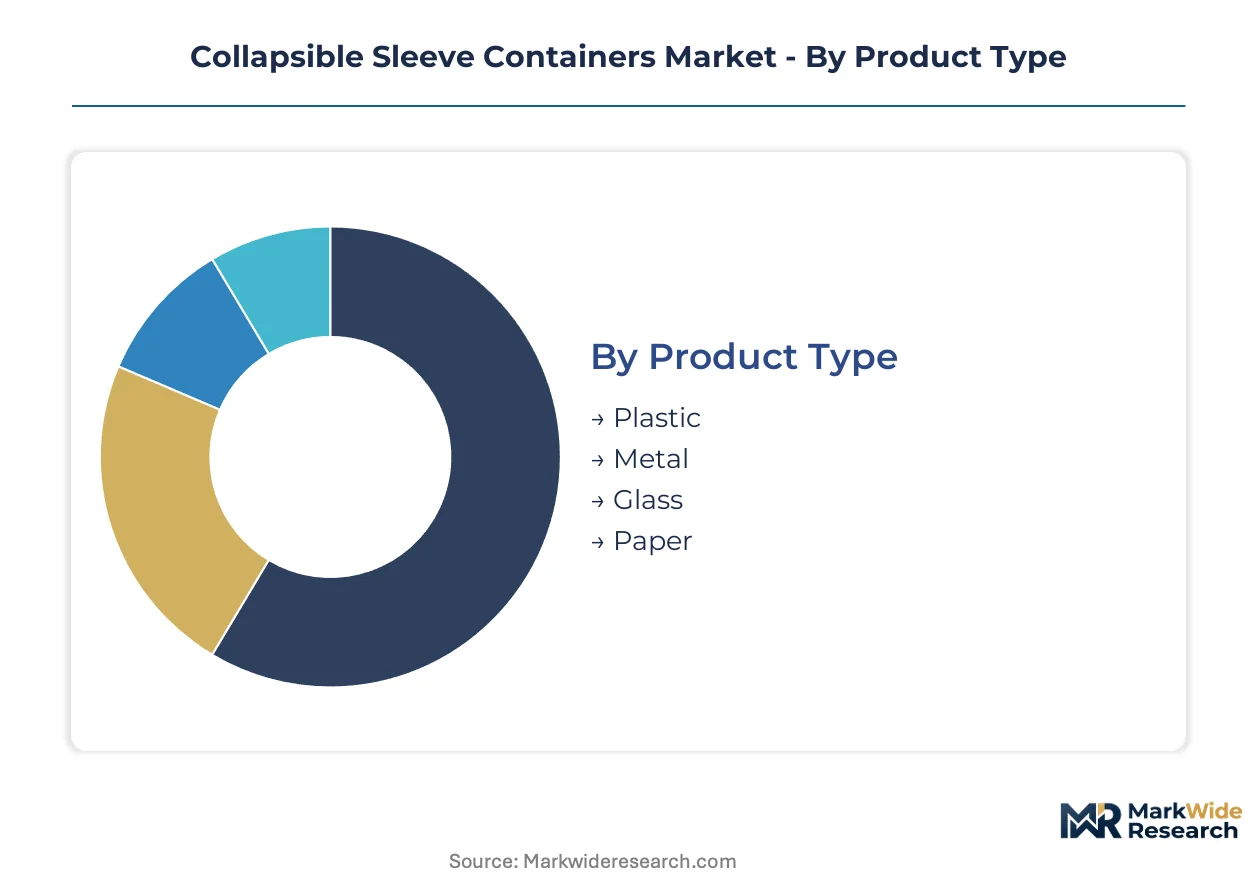
Collapsible sleeve containers serve distinct operational needs across material types, applications, and industry verticals. Segmentation reveals where standardization yields pooling economies versus where customization commands premium positioning. Procurement patterns diverge sharply between automotive just-in-sequence programs and pharmaceutical cold-chain logistics.
Product Type:
Standalone sleeve systems dominate closed-loop pooling models, while embedded configurations integrate with automated warehouse infrastructure.
- Plastic:Corrugated polypropylene and high-density polyethylene variants withstand fifty-plus wash cycles in pharmaceutical distribution. German automotive suppliers specify glass-reinforced polypropylene frames for interchangeable corner-post modularity. REACH-compliant formulations displace phthalate-coated alternatives in EU food-grade tenders.
- Metal:Steel-reinforced edge bands and hinge hardware enable load stacking above five hundred kilograms in heavy industrial storage. Stuttgart tooling houses supply captive injection molds for metal-polypropylene hybrid frames. Moisture resistance extends service life in uncontrolled warehouse environments.
- Glass:Tempered glass panel inserts serve premium cosmetics presentation requirements with collapsible outer frames.
- Paper:Laminated fiberboard sleeves anchor cost-sensitive consumer goods where trip cycles remain below fifteen rotations.
Plastic leads volumes today; metal is gaining share fastest in heavy-load industrial applications.
Application:
Cost tiers separate capital-intensive pooling infrastructure from disposable single-use deployments.
- Packaging:Primary protective enclosures for finished goods transit dominate sleeve fleet utilization. Swiss pharmaceutical distributors deploy RFID-embedded sleeves for real-time location tracking. EU extended producer responsibility fees favor reusable formats over corrugated cardboard.
- Shipping:Inter-facility bulk transport between tiered suppliers and assembly plants drives collapsible design adoption. Nashville automotive clusters lack sufficient sleeve pooling infrastructure relative to Detroit and Spartanburg. Empty-haul fuel savings compound across multi-tier supply chains.
- Storage:Semi-permanent warehouse organization systems use sleeve containers for dynamic slotting flexibility.
- Marketing:Point-of-sale display sleeves with branded graphics serve temporary promotional campaigns.
Shipping commands the largest installed base; packaging is climbing the fastest as pooling models mature.
Industry Vertical:
Customer type stratification separates regulated pharmaceutical operators from price-driven consumer goods procurement.
- Food & Beverage:Dairy and produce distribution demands FDA-compliant polypropylene under 21 CFR 177.1520 migration limits. Cold-chain temperature excursions degrade fiberboard sleeves, pushing converters toward washable plastic variants. German retailers specify mono-material designs for simplified recycling.
- Pharmaceuticals:Sterilization-compatible sleeve systems support validated distribution networks in Switzerland and the Netherlands. ISO 18600 reusability certification is becoming mandatory in EU public-sector tenders. Fleet leasing models displace outright purchase contracts.
- Cosmetics:Premium brand presentation requirements drive glass-panel and custom-printed sleeve specifications.
- Consumer Goods:High-volume, low-margin operations prioritize fiberboard sleeves for limited reuse cycles.
Food & Beverage anchors current deployment; Pharmaceuticals is expanding most quickly under regulatory compliance pressure.
Distribution Channel:
Supply concentration in captive tooling capacity shapes channel access for new market entrants.
- Retail:Big-box and grocery chains source sleeve containers through centralized procurement functions with sustainability mandates. French and Italian municipal sorting facilities reject mixed-material loads, creating end-of-life liability considerations.
- Online:E-commerce fulfillment networks adopt sleeve pooling for last-mile return logistics. Third-party operators assume capital burden through subscription-based fleet management.
- Direct Sales:OEM automotive programs contract directly with sleeve converters for just-in-sequence delivery.
- Distributors:Regional packaging distributors stock standard sleeve sizes for small-batch industrial customers.
Direct Sales dominates automotive vertical value; Online is gaining traction fastest in pharmaceutical subscription services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive suppliers pioneered collapsible sleeve container adoption for just-in-sequence assembly line delivery, establishing the technical specifications and pooling models that later diffused across European manufacturing clusters and into North American automotive corridors.
Germany
Automotive component suppliers in Stuttgart and Munich deploy sleeve systems to synchronize tiered supplier networks with final assembly plants. The EU Packaging and Packaging Waste Regulation mandates mono-material polypropylene designs, collapsing technical diversity among converters. Stuttgart tooling houses maintain captive injection mold capacity that creates eighteen-month lead times for new entrants seeking qualified production equipment.
United States
The FDA enforces migration limits for food-contact polypropylene under 21 CFR 177.1520, directly shaping resin selection for dairy and produce distribution sleeves. Tiered automotive suppliers near Detroit, Nashville, and Spartanburg lack sufficient sleeve pooling infrastructure relative to European benchmarks. Nashville automotive clusters represent the fastest-expanding regional demand center for just-in-sequence delivery systems.
Switzerland
Pharmaceutical distributors pilot RFID-embedded sleeve fleets for real-time location monitoring under subscription-based fleet management services. Swissmedic oversees sterilization compatibility standards that extend reuse intervals in validated distribution networks. Basel and Zurich logistics operators concentrate procurement authority with sustainability-mandated centralized functions.
Netherlands
Third-party pooling operators assume capital burden and maintenance liability through fleet leasing models displacing outright purchase contracts. ECHA REACH restrictions on phthalate plasticizers in sleeve finishes accelerate migration to compliant polypropylene formulations. Rotterdam and Amsterdam distribution hubs serve as European entry points for North American automotive operators seeking proven plant location models.
France
Municipal sorting facilities reject mixed-material loads including laminated fiberboard sleeves with metal edge reinforcements, creating end-of-life liability for pooling operators. ANSM oversees pharmaceutical packaging standards that influence sleeve sterilization requirements. Lyon and Paris industrial zones concentrate consumer goods procurement functions prioritizing cost-sensitive fiberboard formats for limited trip cycles.
Collapsible Sleeve Containers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material specialization and captive tooling access. The vendor base stratifies into three tiers: European fiber-based sleeve specialists, injection-molded polypropylene frame manufacturers with captive German tooling, and North American automotive program operators with plant locations clustered near Detroit. Consolidation pressure concentrates among mid-size converters lacking ISO 18600 reusability certification. Strategic moves center on backward integration into injection mold capacity and geographic expansion into underserved Nashville and Spartanburg automotive corridors.
Among European-based operators, DS Smith plc exemplifies the fiber-based sleeve archetype with food-grade returnable flow positioning. Schoeller Allibert Services B.V. represents the injection-molded polypropylene frame tier with German tooling house relationships. ORBIS Corporation anchors the North American automotive program specialist position. These three occupy distinct competitive vectors without direct overlap in core material technologies or primary end-use verticals.
| Leading Market Players |
|---|
| DS Smith plc |
| Schoeller Allibert Services B.V. |
| ORBIS Corporation |
| Buckhorn Inc. |
| Rehrig Pacific Company Inc. |
| TranPak Inc. |
| RPP Containers |
| CABKA Group |
| SSI Schaefer Ltd |
| Others |
Supply Flow & Price Mechanics
Family-owned German tooling houses with captive injection mold capacity anchor supply-side discipline, translating eighteen-month equipment lead times into pricing power for qualified sleeve frame producers while squeezing converter margins during resin volatility spikes.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by certification grade and trip-cycle durability. ISO 18600 reusability certification commands premium positioning in EU public-sector tenders, while uncertified fiberboard variants compete on unit cost for limited-rotation consumer goods applications. Cost compression in standard-grade polypropylene intensifies because propylene monomer supply disruptions from Gulf Coast petrochemical complexes transmit directly to converter input costs. Automotive just-in-sequence programs show least price sensitivity due to operational savings from reduced empty-haul fuel consumption, whereas cost-sensitive consumer goods procurement functions drive fiberboard demand.
Supply Chain Analysis
Domestic-content mandates in EU member states are reshaping sourcing patterns for sleeve frame components and raw resin procurement. Captive production clusters in Germany, supplemented by tooling partnerships in the Netherlands and Switzerland, supply qualified injection molds for automotive and pharmaceutical programs. The supply chain draws from polypropylene resin, glass-reinforced composite corner posts, and metal edge reinforcements as primary inputs. Single-source vulnerability concentrates in Stuttgart-area tooling houses qualified for OEM automotive specifications. Distribution runs through direct sales channels for large automotive programs and regional packaging distributors for industrial small-batch customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Packaging and Packaging Waste Regulation functions as a regulatory compounder, tightening recyclability thresholds that accelerate converter migration toward mono-material polypropylene designs and reshape competitive positioning across the forecast horizon.
For Market Incumbents: To counter emerging pooling operators with subscription-based fleet management services, Schoeller Allibert and ORBIS should deepen backward integration into captive injection mold capacity in Germany and accelerate ISO 18600 reusability certification investments to defend specification advantages in EU public-sector tenders. For New Entrants and Emerging Players: RFID-embedded inventory tracking technology offers a technology-first wedge for pharmaceutical distributors in Switzerland and the Netherlands piloting real-time location monitoring. White-space targets include Nashville automotive clusters lacking sufficient sleeve pooling infrastructure and mid-size European producers without laboratory certification investments for REACH-compliant coating reformulation. For Investors and Strategic Acquirers: Packaging pooling specialists are the most active acquirer in this space, consolidating mid-size converters lacking certification infrastructure. The long-term viability window favors operators with backward integration into German tooling capacity and proven plant location models near Detroit or Spartanburg. Watch for ECHA REACH Annex XVII enforcement intensity as the inflection indicator for compliance-driven consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Injection Mold Capacity | Captive German tooling access eliminates eighteen-month lead times for qualified production equipment. |
| ISO 18600 Reusability Certification Investment | Early certifiers capture specification advantages in EU public-sector packaging procurement tenders. |
| RFID-Embedded Fleet Management Service Launch | Swiss and Dutch pharmaceutical distributors pilot subscription-based real-time location monitoring. |
| Geographic Expansion into Nashville Automotive Corridor | Tiered suppliers near Nashville lack sufficient sleeve pooling infrastructure relative to Detroit benchmarks. |
| Mono-Material Polypropylene Design Migration | EU Packaging and Packaging Waste Regulation mandates simplify recycling and collapse technical diversity. |
Methodological Framework
Multiple input streams — primary interviews with automotive procurement directors, pharmaceutical supply chain managers, and packaging converter executives; secondary validation through EU regulatory filings, FDA 21 CFR documentation, and customs trade data; plus bottom-up and top-down triangulation — were reconciled to construct market estimates.
Historical shipment volumes were cross-referenced against panel input from tiered supplier networks to anchor growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include material type, application function, industry vertical, and regional regulatory cluster. CAGRs were derived from weighted average growth rates across these segments, incorporating propylene monomer price elasticity and automotive production forecast inputs specific to German, US, and Swiss manufacturing corridors.
The model holds under stable EU regulatory enforcement and intact automotive supply chain relationships; deviation in REACH substance restriction timelines or Gulf Coast petrochemical disruption frequency would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Intermediate Bulk Container (IBC) Market
Containers
Single Wall Jars Market
Containers
Dual-Ovenable Trays and Containers Market
Containers
Snap-Lock Container Market
Containers
Thermoformed Containers Market
Containers
Collapsible Crate Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Child-Resistant Containers Market
Containers
Intermediate Bulk Container Liner Market
Containers
ISO Container Market
Containers
Asia and Africa Food Cans Market
Containers
Durable Insulated Containers Market
Containers
PP Container Liner Market
Containers
Safety Bottle Tote Carriers Packaging Market
Containers
Global Cardboard Box and Container Market
Containers
Oblong Tub Lids Market