
 Flip Top Caps and Closures Market | 2026-2036
Flip Top Caps and Closures Market Size, Share, and Industry Trends Forecast 2026-2036
Flip Top Caps and Closures Market Foresight
The EU Single-Use Plastics Directive is shifting procurement criteria across European personal care and food packaging supply chains, compelling converters to validate recycled content ratios in flip top designs. Berry Global Inc. leverages its North American manufacturing scale to supply certified post-consumer resin closures at volume. AptarGroup, Inc. differentiates through precision dosing mechanisms integrated into pharmaceutical-grade flip tops. Silgan Holdings Inc. anchors its position via backward integration into resin compounding and decoration capabilities.
Flip top caps and closures are hinged dispensing closures typically molded from polypropylene or polyethylene with living-hinge geometries enabling repeated open-close cycles; wall thickness, hinge fatigue resistance, and thread torque specifications determine functional lifespan in filled-goods applications. Polypropylene dominates material selection due to its fatigue resistance and compatibility with hot-fill processes, while polyethylene gains ground in cost-sensitive household chemical segments. Tamper evident flip tops command margin premiums in pharmaceutical and food channels where regulatory compliance creates switching costs.
The FDA enforces child-resistant packaging standards under 16 CFR 1700, directly shaping flip top design geometries for over-the-counter and prescription applications. REACH and ECHA substance restrictions in Europe limit certain plasticizers and colorants, forcing reformulation of hinge compounds and sealing liners. Stakeholders must monitor evolving extended producer responsibility frameworks in multiple geographies, as fee structures and collection targets will increasingly determine material economics and regional sourcing decisions.
Market Dynamics
Post-consumer recycled resin mandates are compressing virgin polypropylene economics while forcing hinge geometry redesigns to accommodate material property variance. Living-hinge fatigue performance degrades with recycled content above 30%, compelling molders to invest in compounding capabilities or risk specification disqualification from personal care and pharmaceutical buyers.
Growth Catalysts
- EU Single-Use Plastics Directive:Binding recycled content targets for 2030 are accelerating converter qualification programs across German and French cosmetics packaging clusters. Pharmaceutical-grade flip tops with validated post-consumer resin ratios command sourcing priority from multinational personal care brands.
- Hot-fill compatibility advances:Modified polypropylene formulations now withstand 85°C filling temperatures without hinge crystallization failure. Food sauce and condiment manufacturers are migrating from two-piece closures to unitary flip tops for line speed and capping torque consistency.
- Travel-size format proliferation:TSA-compliant personal care packaging below 100ml is driving demand for miniaturized flip tops with reduced thread engagement depths. Airport retail and hospitality amenity channels specify these formats for inventory density and shelf differentiation.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker operating rate fluctuations in the US Gulf Coast and Rotterdam ARA hubs transmit directly to polypropylene homopolymer pellet pricing. Molders with fixed-price annual contracts face margin compression during feedstock spike periods.
- Living-hinge fatigue ceiling:Current injection molding tolerances limit guaranteed open-close cycles to approximately 5,000 operations for standard polypropylene hinges. Premium cosmetic dispensers requiring 10,000+ cycle warranties necessitate costly hinge reinforcement inserts or alternative elastomeric materials.
- Substitution by pump dispensers:High-viscosity personal care formulations increasingly specify lotion pumps with dip tubes over flip tops for controlled dosing precision. This displacement concentrates in prestige skincare and sun care segments where dosage accuracy drives repurchase behavior.
Strategic Opportunities
- Brazil ANVISA pharmaceutical packaging modernization:Updated stability testing requirements for tropical climate zones are creating specification windows for moisture-resistant flip tops with induction heat-seal liners. Domestic converters lack validated production capacity, opening entry paths for certified foreign suppliers.
- Digital watermark integration:Covert spectral markers embedded in closure resin enable automated sortation of polypropylene packaging in advanced recycling facilities. Early adopters in German extended producer responsibility schemes are securing preferential fee structures through demonstrable recyclability verification.
- Direct-to-consumer refill formats:Concentrate and tablet-based personal care brands require companion flip-top dispensing bottles designed for repeated refill cycles. Subscription commerce channels favor durable closure designs that survive 12+ months of household use without hinge degradation.
Industry Challenges
- Multi-material separation complexity:Flip tops incorporating co-molded thermoplastic elastomer seals or metal spring hinges complicate mechanical recycling streams. Sortation facility operators in California and Germany are imposing negative value assessments on these designs, forcing redesign for mono-material construction.
- Validation timeline compression:Pharmaceutical and food contact applications require 12-18 month migration testing and stability protocols under FDA and EFSA guidelines. Accelerated customer launch schedules are colliding with these fixed-duration certification requirements, risking non-compliance or delayed market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flip Top Caps and Closures Market |
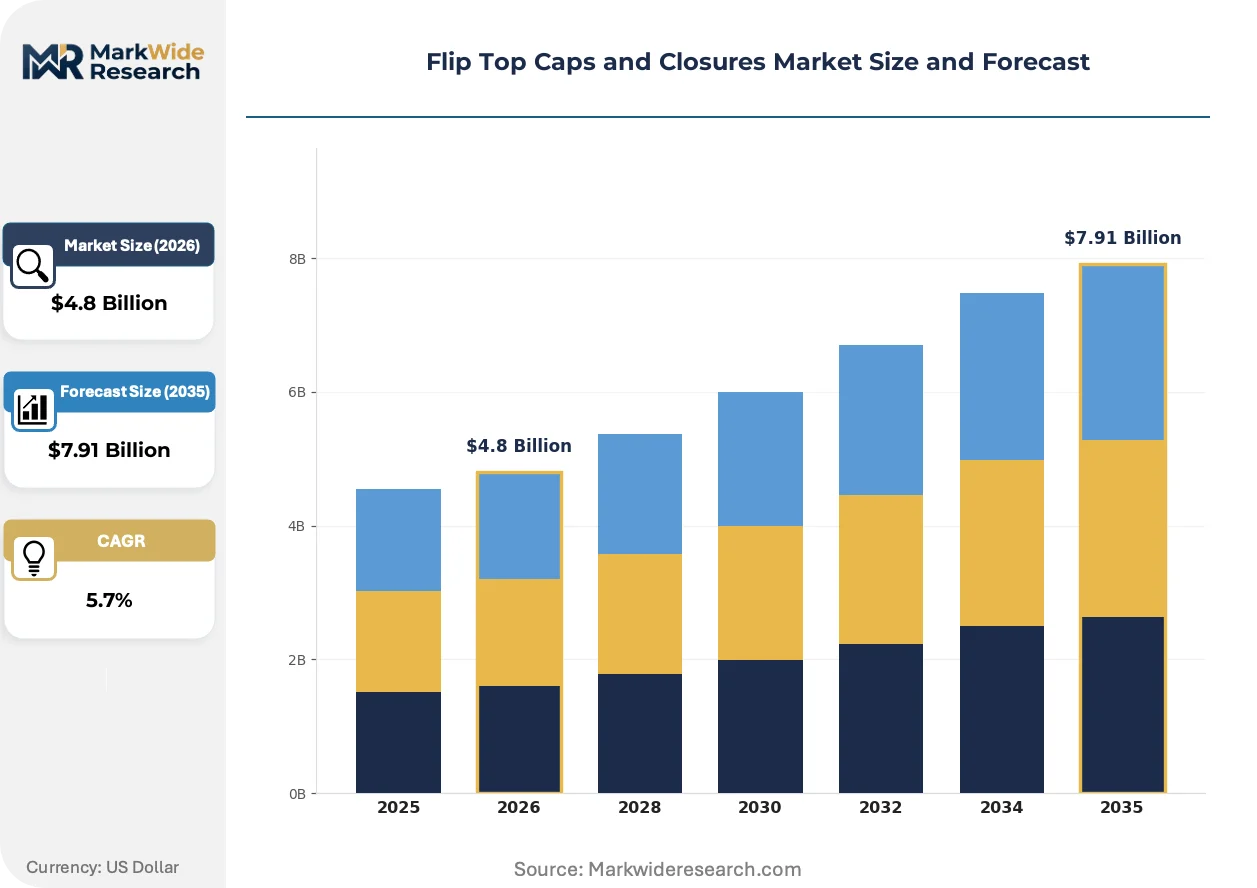
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Polypropylene, Polyethylene, Acrylonitrile Butadiene Styrene, Polycarbonate, Polystyrene, Nylon End Use Industry: Personal Care, Food & Beverage, Pharmaceuticals, Household Chemicals, Agrochemicals, Cosmetics Product Type: Standard Flip Tops, Customizable Flip Tops, Tamper Evident Flip Tops, Child Resistant Flip Tops, Sports Caps, Pump Closures Distribution Channel: Direct Sales, E-commerce, Distributors, Wholesalers, Retailers, Contract Manufacturers |
| Companies Covered | Berry Global Inc., AptarGroup, Inc., Silgan Holdings Inc., Amcor Plc, BERICAP, Closure Systems International, Guala Closures S.p.A, Crown Holdings, United Caps, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flip Top Caps and Closures Market Shifts & Advancements
Material science breakthroughs and regulatory compliance architectures are converging to redefine flip top specification criteria across personal care, pharmaceutical, and food packaging verticals. Hinge durability, recyclability verification, and dispensing precision now dominate buyer evaluation matrices.
Biobased polypropylene derived from renewable feedstocks is rewriting resin sourcing strategies for premium cosmetic brands targeting carbon footprint reduction claims. Neste and Braskem supply chain partnerships are securing offtake agreements with European personal care multinationals seeking mass-balance certified closures. This material transition is compressing the price premium versus fossil-based alternatives from 40% to 15% across the analysis window, enabling broader format adoption beyond niche organic product lines.
REACH Annex XVII restrictions on intentionally added microplastics are forcing reformulation of hinge lubricants and mold release agents used in high-speed injection molding operations. ECHA substance evaluation timelines are creating compliance uncertainty for converters with legacy additive packages. German pharmaceutical packaging clusters are responding fastest, with several molders completing third-party audits to validate additive-free process protocols ahead of enforcement deadlines.
Retail buyer consolidation into centralized procurement functions is compressing supplier qualification cycles and demanding standardized torque specifications across multiple stock-keeping units. Walmart and Carrefour sustainability scorecards now weight recyclability and recycled content above unit cost in flip top vendor selection. This behavioral shift is most visible in North American mass-market personal care, where private-label manufacturers are consolidating supplier bases to three approved molders per category to simplify compliance documentation.
Flip Top Caps and Closures Market Segmentation
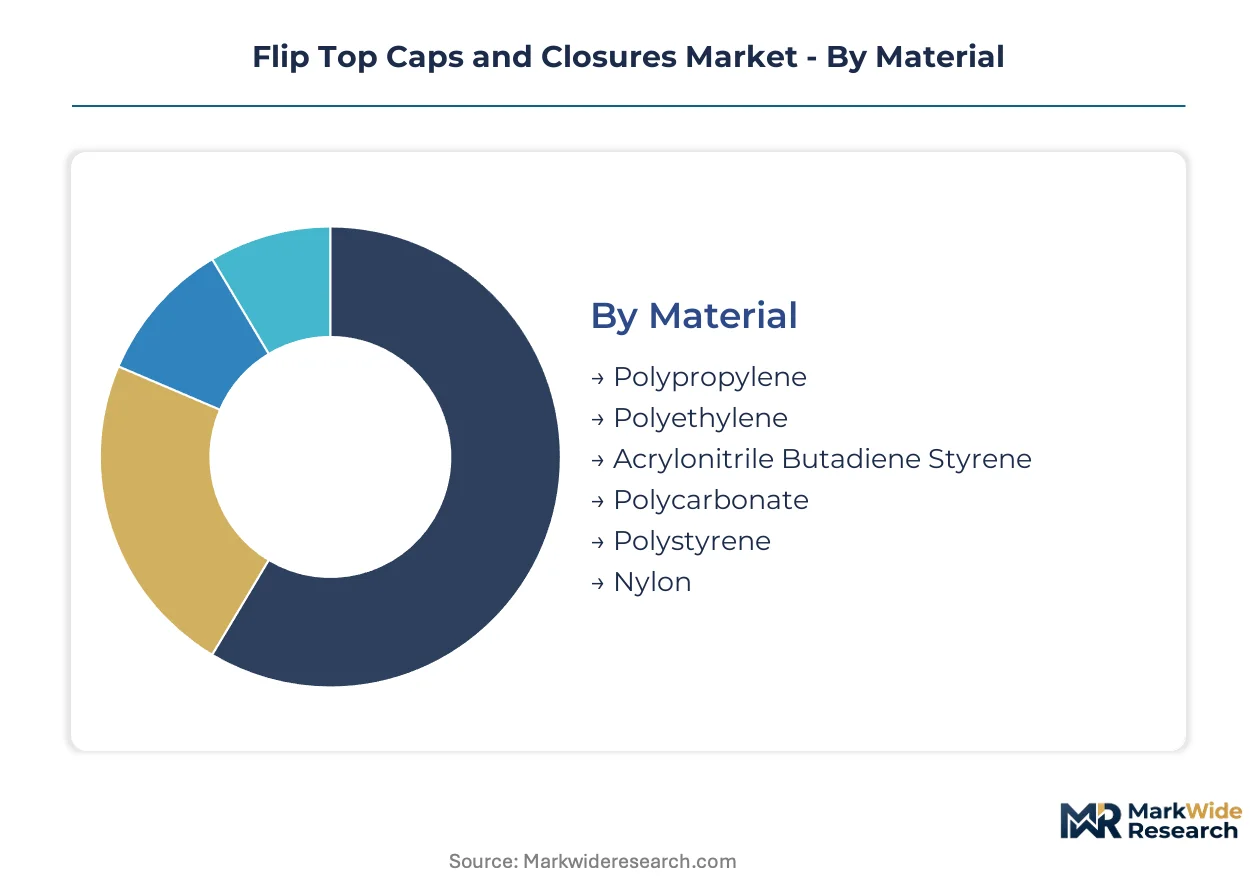
Flip top caps and closures serve divergent performance requirements across pharmaceutical dosing precision, food safety compliance, and cosmetic shelf differentiation. Material selection and hinge geometry specifications cascade through procurement decisions, creating distinct supplier qualification barriers for each segment cluster.
Material:
Polypropylene fatigue resistance and recycled content compatibility define the specification hierarchy for living-hinge applications.
- Polypropylene:Dominates injection-molded flip top production through superior flexural endurance and hot-fill tolerance. German pharmaceutical packaging clusters specify homopolymer grades for moisture-barrier applications under EMA stability guidelines.
- Polyethylene:Gains volume in cost-sensitive household chemical segments where hinge cycle requirements fall below 2,000 operations. Brazilian converters favor linear low-density grades for agrochemical closures exposed to UV degradation.
- Acrylonitrile Butadiene Styrene:Delivers surface gloss and decoration adhesion for premium cosmetic presentations requiring metallized finishes.
- Polycarbonate:Serves high-temperature sterilization protocols in pharmaceutical vial closures where steam autoclave exposure exceeds 120°C.
- Polystyrene:Occupies disposable food service applications with limited reuse specifications and tight unit economics.
- Nylon:Resists hydrocarbon permeation in solvent-based household chemical formulations where polypropylene swells.
Mature deployment sits with polypropylene. Newer deployment is concentrated in post-consumer recycled polyethylene blends.
End Use Industry:
Regulatory compliance intensity and dosing precision requirements fragment demand across end-use verticals.
- Personal Care:Travel-size format proliferation drives miniaturized hinge geometries with reduced thread engagement. TSA-compliant specifications below 100ml command sourcing priority from airport retail channels.
- Pharmaceuticals:Child-resistant mechanisms under FDA 16 CFR 1700 mandate push-turn or squeeze-and-lift actuation forces. ANVISA tropical stability testing creates specification windows for moisture-resistant induction seals.
- Food & Beverage:Hot-fill compatibility advances enable 85°C sauce dispensing without hinge crystallization failure.
- Cosmetics:Premium skincare brands specify 10,000-cycle hinge warranties through elastomeric reinforcement inserts.
- Household Chemicals:Bleach and ammonia formulations demand nylon or fluoropolymer liners to prevent stress cracking.
- Agrochemicals:UV stabilizer packages extend field service life for crop protection products in tropical storage conditions.
Volume concentration favors personal care. Margin expansion is climbing the fastest in pharmaceutical-grade certifications.
Product Type:
Functional differentiation through tamper evidence and dosing control separates commodity from premium positioning.
- Tamper Evident Flip Tops:Ring-pull or break-band mechanisms provide visual integrity assurance for over-the-counter pharmaceuticals. EFSA migration testing protocols extend qualification timelines to 18 months.
- Child Resistant Flip Tops:Senior-friendly actuation force windows balance accessibility with poison prevention compliance. US retail pharmacy chains mandate ISO 8317 certification for generic medication packaging.
- Standard Flip Tops:Unitary living-hinge designs dominate mass-market personal care with 5,000-cycle baseline specifications.
- Customizable Flip Tops:Brand-owner color matching and embossed logo capabilities serve private-label differentiation strategies.
- Sports Caps:One-handed actuation geometries target athletic beverage consumption with flow-control orifices.
- Pump Closures:Dip tube integration displaces traditional flip tops in high-viscosity lotion segments requiring controlled dosing precision.
Specification density peaks in tamper evident designs. Volume scaling is expanding most quickly in customizable formats for direct-to-consumer brands.
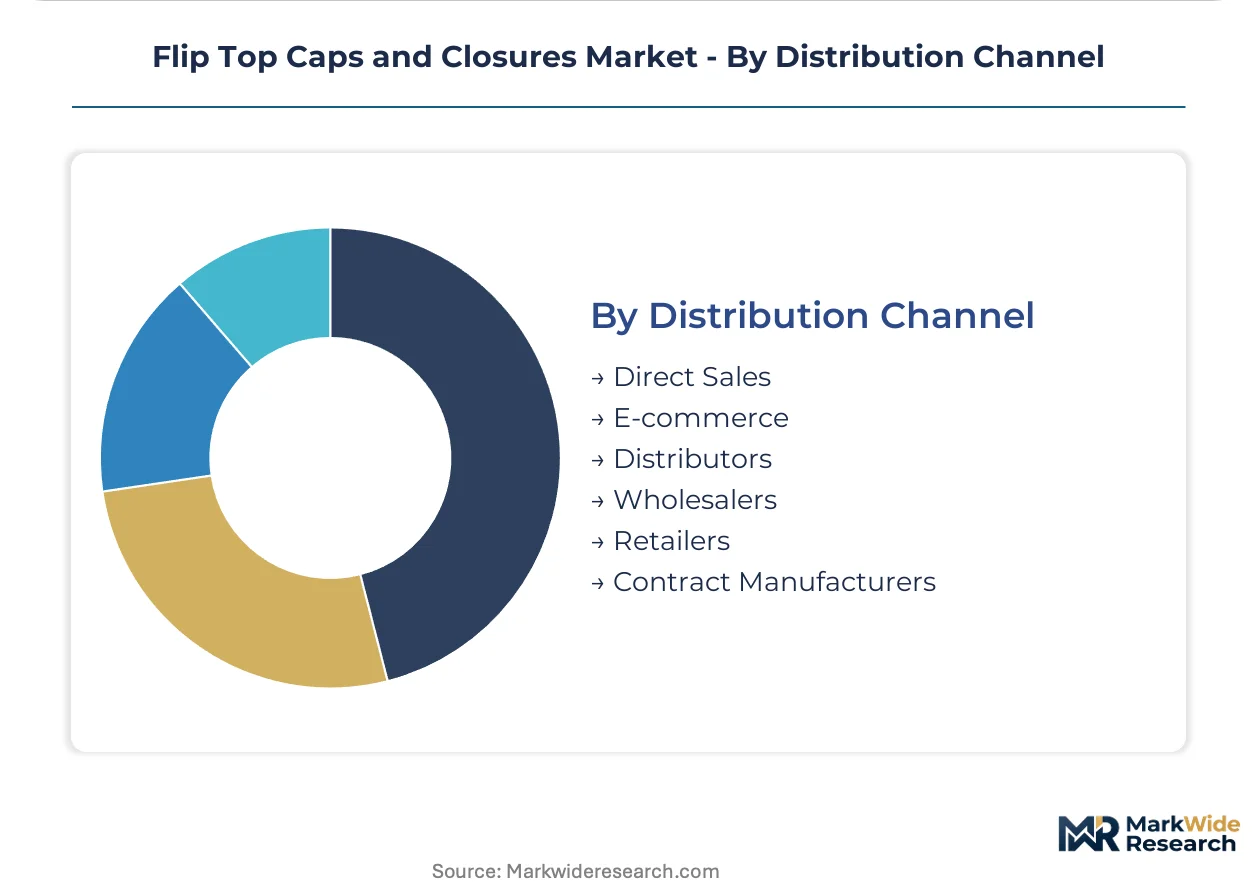
Distribution Channel:
Supply chain configuration determines compliance documentation burden and inventory velocity for molders.
- Direct Sales:Multinational personal care brands negotiate annual volume commitments with qualified molder panels. REACH documentation and recycled content certificates transfer directly without intermediary verification gaps.
- Contract Manufacturers:Full-service packaging integrators specify closure torque tolerances across multiple SKUs to simplify line changeover efficiency.
- Distributors:Regional inventory pooling serves mid-tier food processors lacking volume for direct molder relationships.
- E-commerce:Digital watermark integration enables automated sortation verification for extended producer responsibility fee optimization.
- Wholesalers:Price-sensitive agrochemical channels favor standard specifications with minimal customization overhead.
- Retailers:Walmart and Carrefour sustainability scorecards weight recyclability above unit cost in vendor selection matrices.
Relationship depth concentrates in direct sales. Channel experimentation is gaining share fastest in e-commerce sustainability verification platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Neckar corridor anchors European flip top manufacturing, with pharmaceutical packaging clusters in Frankfurt and Heidelberg driving precision closure specifications for export markets.
Germany
Pharmaceutical and cosmetics packaging clusters in Baden-Württemberg and Hesse demand premium flip tops with validated post-consumer resin ratios under EU Single-Use Plastics Directive timelines. ECHA substance restrictions under REACH Annex XVII compel molders in the Stuttgart region to eliminate legacy hinge lubricants ahead of enforcement deadlines. The Heidelberg-Frankfurt corridor concentrates pharmaceutical-grade certification capacity serving EMA stability guidelines.
United States
Personal care brands in New Jersey and California are expanding flip top adoption for TSA-compliant travel formats below 100ml. FDA child-resistant packaging standards under 16 CFR 1700 shape push-turn hinge geometries for over-the-counter applications. The Gulf Coast petrochemical corridor transmits propylene feedstock volatility directly to Midwest molders serving mass-market household chemical channels.
China
Domestic personal care multinationals in Shanghai and Guangzhou are qualifying post-consumer recycled resin suppliers for export-compliant flip top production. GB standards for food contact materials govern migration testing protocols for sauce and condiment closures. The Yangtze River Delta concentrates injection molding capacity serving both domestic consumption and Southeast Asian re-export markets.
Brazil
ANVISA pharmaceutical packaging modernization creates specification windows for moisture-resistant flip tops with induction heat-seal liners. Tropical climate stability testing requirements favor UV-stabilized polypropylene grades for crop protection products. São Paulo state hosts the primary domestic converter base, though certified foreign suppliers are capturing qualification opportunities in Rio de Janeiro pharmaceutical corridors.
India
Personal care contract manufacturers in Maharashtra and Gujarat are consolidating supplier bases to three approved molders per category to simplify REACH documentation for European export. BIS certification requirements for food contact closures extend qualification timelines for domestic sauce brands. The Mumbai-Pune corridor concentrates decoration and compounding capabilities serving direct-to-consumer refill format startups.
Flip Top Caps and Closures Market Competitive Landscape
The competitive structure tilts toward integrated resin compounders with captive recycling streams. Tiered supplier qualification barriers separate pharmaceutical-grade certifiers from commodity personal care molders. Three archetypes dominate: multinational converters with North American manufacturing scale, precision dosing specialists serving FDA-regulated channels, and backward-integrated resin compounders controlling additive formulations. Capacity expansion and sustainability certification partnerships constitute the dominant competitive moves.
Among North American integrated packaging groups, Berry Global Inc. and Silgan Holdings Inc. exemplify scale-driven archetypes with compounding and decoration capabilities. AptarGroup, Inc. occupies a position within the precision-mechanism tier serving pharmaceutical dosing applications. These three entities anchor the supplier landscape without exhausting competitive positioning variations across the value chain.
| Leading Market Players |
|---|
| Berry Global Inc. |
| AptarGroup, Inc. |
| Silgan Holdings Inc. |
| Amcor Plc |
| BERICAP |
| Closure Systems International |
| Guala Closures S.p.A |
| Crown Holdings |
| United Caps |
| Others |
Supply & Pricing Matrix
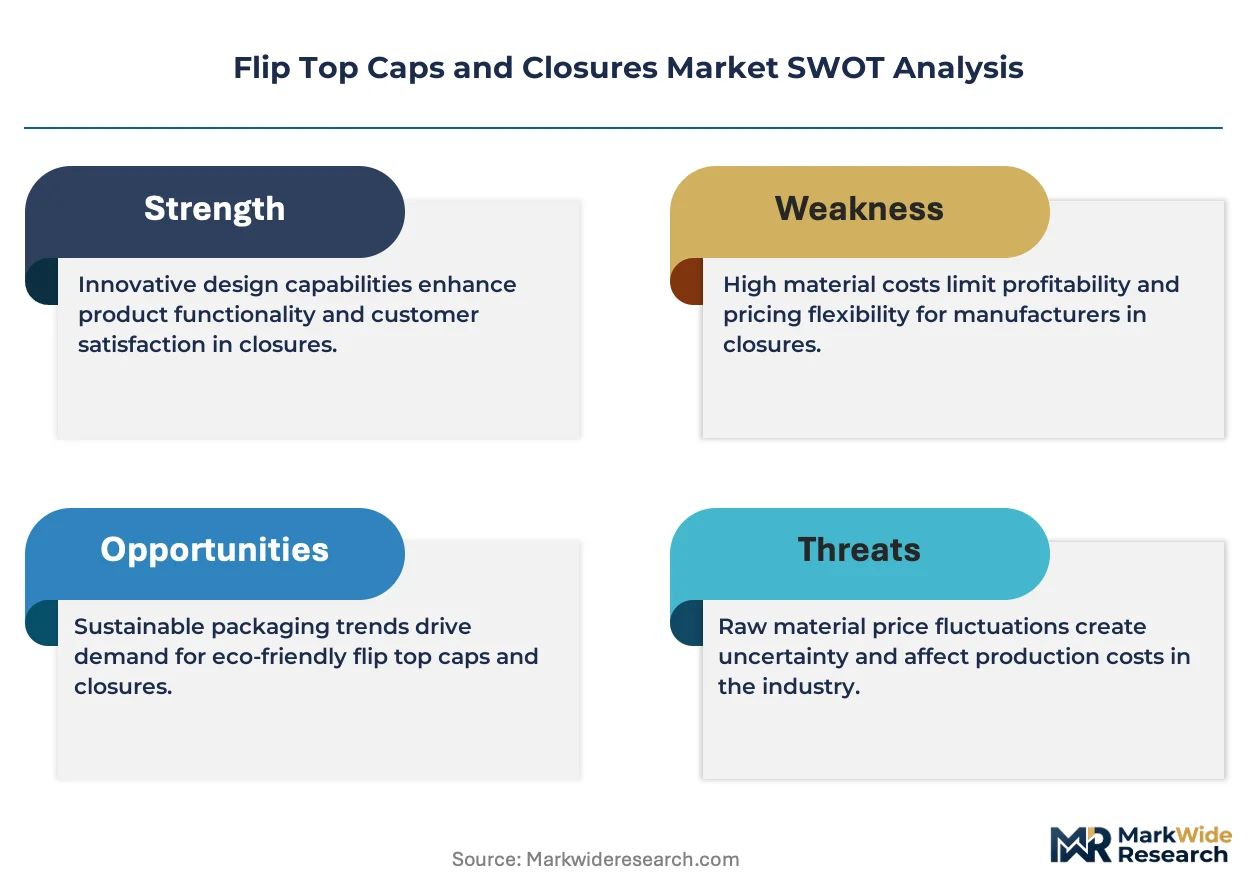
EU Single-Use Plastics Directive recycled content mandates are forcing converters to requalify resin suppliers and absorb compounding cost premiums, compressing margins on standard polypropylene hinges while creating pricing power for certified post-consumer resin compounders.
Pricing Analysis
Certified pharmaceutical-grade hinge warranties command the strongest value-based pricing anchors in this market. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated child-resistant designs from mass-market personal care specifications. Price differentiation hinges on EMA stability certification and hot-fill temperature tolerance. Cost compression in commodity polypropylene segments is intensifying because Brazilian and Indian converters are absorbing feedstock volatility to maintain European export contracts. Mass-market household chemical buyers exhibit highest price sensitivity; pharmaceutical multinationals prioritize compliance documentation over unit cost.
Supply Chain Analysis
Regional distribution centers in Rotterdam ARA and US Gulf Coast hubs coordinate resin flows to injection molders serving pharmaceutical clusters. Supply concentrates in Germany, China, and the United States for precision hinge manufacturing. Raw material sourcing draws from naphtha-cracker propylene in Rotterdam, shale-gas derived feedstocks on the US Gulf Coast, and coal-to-olefins complexes in China's Shandong province. Single-source vulnerability sits with European post-consumer resin compounders lacking capacity expansion timelines. Distribution runs through direct sales channels for multinational personal care brands and contract manufacturers serving food packaging integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified post-consumer resin compounding capacity is the binding constraint propping pricing for certified closures, as pharmaceutical and cosmetics buyers consolidate supplier panels ahead of EU directive deadlines.
For Market Incumbents: Hedge propylene feedstock exposure through long-term offtake agreements with Rotterdam ARA crackers or captive recycling stream investments. Defend specification lock-in by accelerating EMA stability certification for post-consumer resin hinge designs before enforcement deadlines tighten. Pump dispenser substitution in prestige skincare represents the most acute displacement threat requiring hinge durability differentiation. For New Entrants and Emerging Players: Enter via ANVISA pharmaceutical packaging modernization in Brazil, where domestic converters lack validated moisture-resistant induction seal capacity. Target direct-to-consumer refill format startups in India's Mumbai-Pune corridor demanding 12-month hinge durability warranties. Lead with digital watermark integration for German extended producer responsibility fee optimization as the primary go-to-market wedge. For Investors and Strategic Acquirers: The window for entry favors backward-integrated resin compounders with captive recycling infrastructure and pharmaceutical certification track records. Long-term viability centers on converters controlling additive formulations ahead of REACH Annex XVII enforcement. Watch living-hinge fatigue performance thresholds as the inflection signal—designs exceeding 10,000 cycles without elastomeric reinforcement will consolidate premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Compounding Capacity Expansion | Secures supply security for EU Single-Use Plastics Directive compliance ahead of 2030 targets. |
| Pharmaceutical-Grade Certification Investment | Opens EMA stability guideline contracts with Heidelberg-Frankfurt packaging clusters. |
| Digital Watermark Integration | Enables preferential extended producer responsibility fee structures in German sorting facilities. |
| Hot-Fill Compatibility Formulation | Captures food sauce manufacturers migrating from two-piece closures to unitary flip tops. |
| Direct-to-Consumer Refill Format Partnerships | Locks in 12+ month durability specifications with subscription commerce personal care brands. |
Research Methodology
Document review covered FDA 16 CFR 1700 filings, EMA stability guideline documentation, REACH Annex XVII substance restriction updates, and SEC 10-K disclosures from integrated packaging groups, complemented by interviews with injection molding plant managers, personal care brand procurement leads, pharmaceutical packaging engineers, and extended producer responsibility scheme administrators. Secondary validation drew from customs trade data, EU Single-Use Plastics Directive implementation reports, and resin compounding industry publications. Bottom-up volume estimates triangulated against top-down market sizing across material grades and end-use verticals.
Historical shipment data cross-referenced against panel input from molders and brand-owner procurement functions shaped the analytical framework. Segmentation dimensions modeled include material type, end-use industry, product functionality tier, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand projections and capacity expansion timelines. Industry-specific forecast inputs incorporated propylene feedstock volatility indices and pharmaceutical qualification timeline compression effects.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated REACH enforcement or naphtha-cracker supply disruptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Brush and Dauber Caps Market
Caps and Closures
Sport Caps and Closures Market
Caps and Closures
Italy Plastic Caps and Closures Market
Caps and Closures
PET Dome Lids Market
Caps and Closures
Clic Loc Closure Market
Caps and Closures
Peelable Lid Stock Market
Caps and Closures
Fez Caps Market
Caps and Closures
Crown Caps Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Morocco Plastic Caps and Closures Market
Caps and Closures
Cone Lined Caps Market
Caps and Closures
Egypt Plastic Caps and Closures Market
Caps and Closures
Crown Closures Market
Caps and Closures
Steel Ring Pull Caps Market
Caps and Closures
Elastomeric Closures Market
Caps and Closures
US Caps and Closure Market