
 Belgium Container Glass Market | 2026-2036
Belgium Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Belgium Container Glass Market Outlook
Belgian craft beverage producers is decoupling from mass-market beer volumes, creating specialized demand for premium bottle formats. AGC Glass Europe SA/NV leverages its regional furnace network to sustain supply security across Benelux pharmaceutical accounts. Gerresheimer AG anchors its position through dedicated vial capacity serving Brussels-area biotech clusters. Vetropack Group competes on lightweighting technology leadership for export-bound Belgian food brands.
Belgium container glass denotes soda-lime silica vessels formed through blow-and-blow or press-and-blow processes, typically achieving wall thicknesses of 2–5 millimeters for mechanical durability and chemical inertness. These containers protect oxygen-sensitive contents across food, beverage, and pharmaceutical supply chains while enabling infinite recycling without quality degradation. Bottles occupy the dominant volume position, though vials command superior margin pools from Brussels-pharma proximity. Jars sustain steady demand from Belgian artisanal food processors seeking shelf differentiation. Shape customization represents the fastest-growing configuration as premium brands pursue tactile identity.
Belgian producers navigate REACH chemical safety registrations, EU Packaging and Packaging Waste Directive recycling thresholds, and Flemish environmental permitting through OVAM. These frameworks elevate recycled content minimums and restrict heavy-metal colorants, directly influencing furnace feedstock sourcing and decoration technology choices. Stakeholders must monitor evolving EU glass recycling rate targets and carbon border adjustment mechanisms to calibrate capital allocation between furnace refurbishment and alternative forming investments.
Market Dynamics
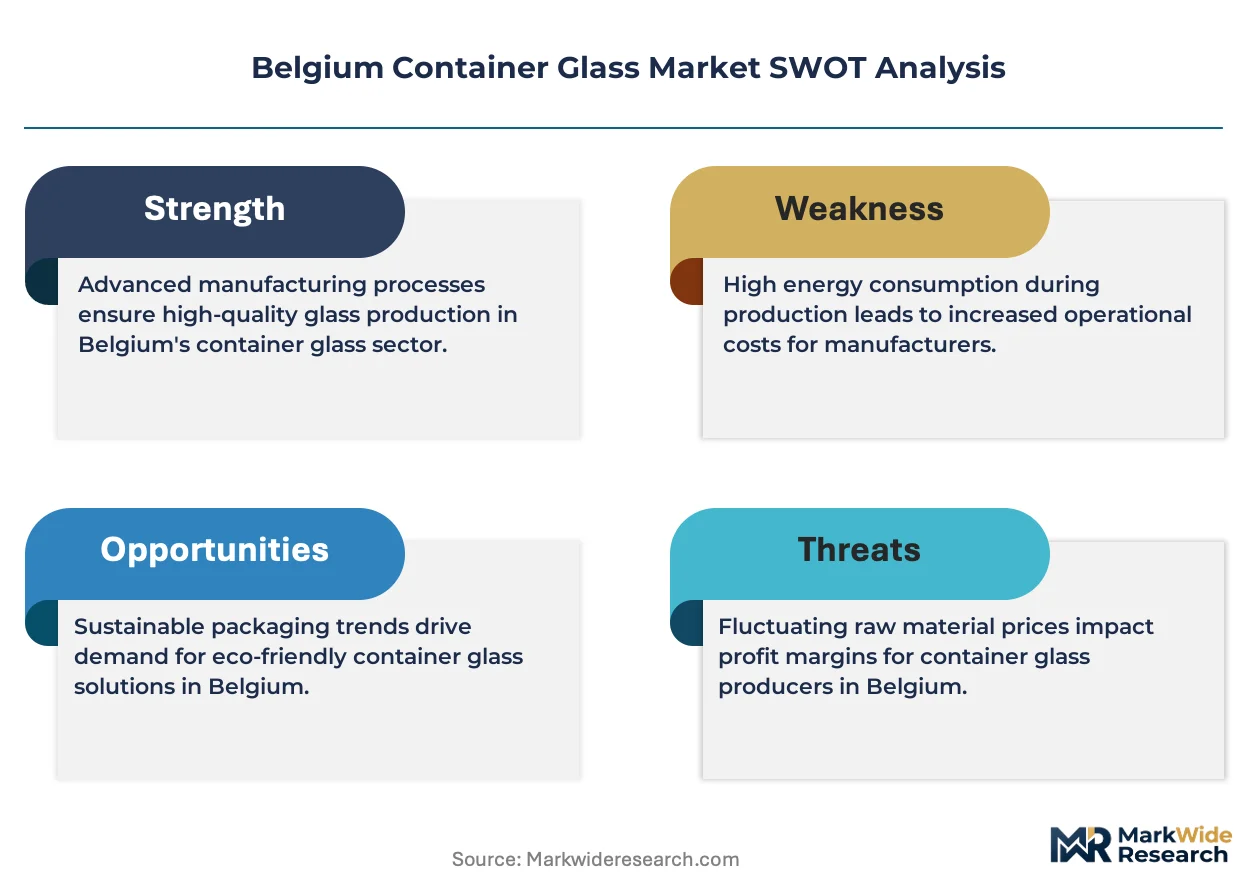
Belgium's container glass sector faces intensifying furnace feedstock pressure as the EU Green Deal mandates accelerate recycled content minimums, forcing simultaneous investment in cullet sorting infrastructure and lightweighting R&D while natural gas price volatility persists.
Growth Catalysts
- EU Packaging and Packaging Waste Directive:Recycling threshold escalations drive Belgian producers to expand cullet preprocessing capacity, creating equipment upgrade cycles across Flanders manufacturing clusters.
- Brussels biotech corridor:Pharmaceutical vial demand from the capital's dense biotech R&D ecosystem pulls specialized borosilicate capacity expansion.
- Lightweighting technology:Wall-thickness reduction below 2.5 millimeters enables freight cost savings for export-bound Belgian food brands competing in Northern European retail.
Market Restraints
- Natural gas price volatility:Furnace energy intensity ties Belgian glass margins to TTF hub fluctuations, compressing operating leverage during winter demand spikes.
- Cullet supply concentration:Post-consumer glass collection relies on Flemish municipal sorting facilities, creating single-point vulnerability for high-recipe production.
- Aluminum can substitution:Beverage brands seeking weight-based logistics savings are piloting metal alternatives for standard beer formats below 33 centiliters.
Strategic Opportunities
- Wallonia underpenetration:Southern Belgium's smaller glass manufacturing footprint offers greenfield furnace sites with proximity to Luxembourg and French border markets.
- Carbon border adjustment mechanism:CBAM phase-in creates competitive insulation for EU-produced glass against imported alternatives from carbon-intensive production regimes.
- Digital printing convergence:Direct-to-glass decoration technology eliminates label substrates, enabling batch-size-one customization for craft beverage limited releases.
Industry Challenges
- Furnace engineering talent scarcity:Specialized refractory and combustion expertise required for oxy-fuel conversions faces demographic retirement waves across Belgian technical institutes.
- REACH compliance timelines:Chemical safety dossier updates for colorant formulations extend product development cycles, delaying new shade introductions by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Belgium Container Glass Market |
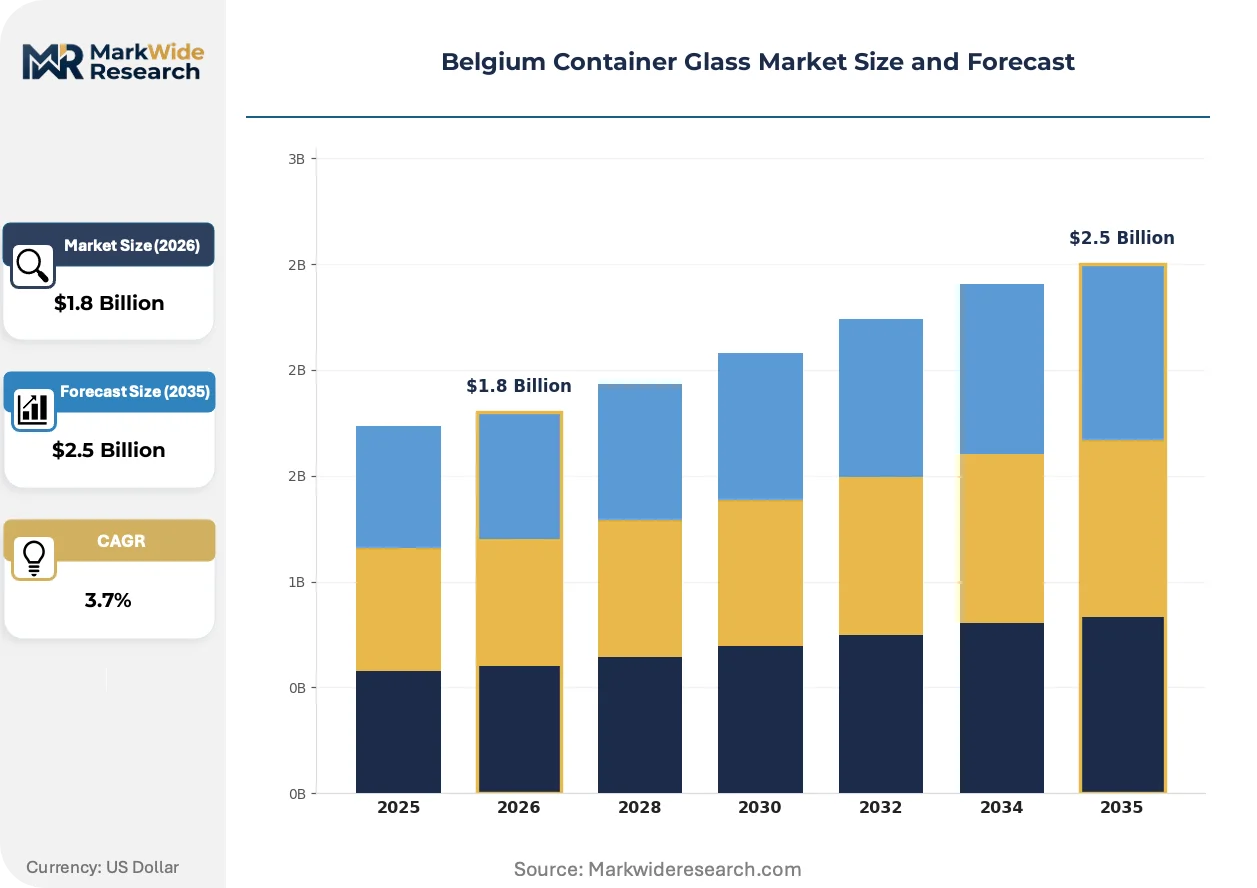
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Vials End User: Food & Beverage, Pharmaceuticals, Cosmetics, Personal Care Shape: Round, Square, Rectangular, Custom Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Konings plc, AGC Glass Europe SA/NV, Gerresheimer AG, AYANO HOLLAND BV, Bormioli Rocco, Ciner Glass Belgium, AXA GLASS bv/srl, Vetropack Group, SAVERGLASS Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Belgium Container Glass Market Strategic Shifts
Belgian container glass manufacturing is undergoing simultaneous pressure from energy transition imperatives and premiumization demands, with technology investments clustering around decarbonization pathways and tactile differentiation capabilities.
Electrified melting technology is consolidating as the dominant furnace retrofit pathway for Belgian producers seeking Scope 1 emission reductions. Mid-scale beverage glass manufacturers in the Antwerp-Ghent corridor are piloting hybrid electric-boosted furnaces at 30-50 tonne-per-day scale. This transition is consolidating technical partnerships between furnace builders and regional utilities around grid-stabilization load management.
REACH chemical safety registrations are tightening permissible heavy-metal thresholds in glass colorants, forcing reformulation of traditional amber and green bottle recipes. Belgian decoration houses are accelerating ceramic ink substitutions to maintain shelf differentiation under restricted substance lists. Pharmaceutical vial producers face the steepest compliance timelines given EMA documentation requirements for primary packaging materials.
Belgian craft brewers are compressing bottle format switching cycles, demanding shorter production runs with accelerated changeover capabilities. Contract packaging facilities in East Flanders are replacing dedicated lines with quick-change modular systems to capture fragmented premium volumes. This pattern concentrates in seasonal release schedules where limited-edition tactile finishes command shelf price premiums.
Belgium Container Glass Market Segmentation
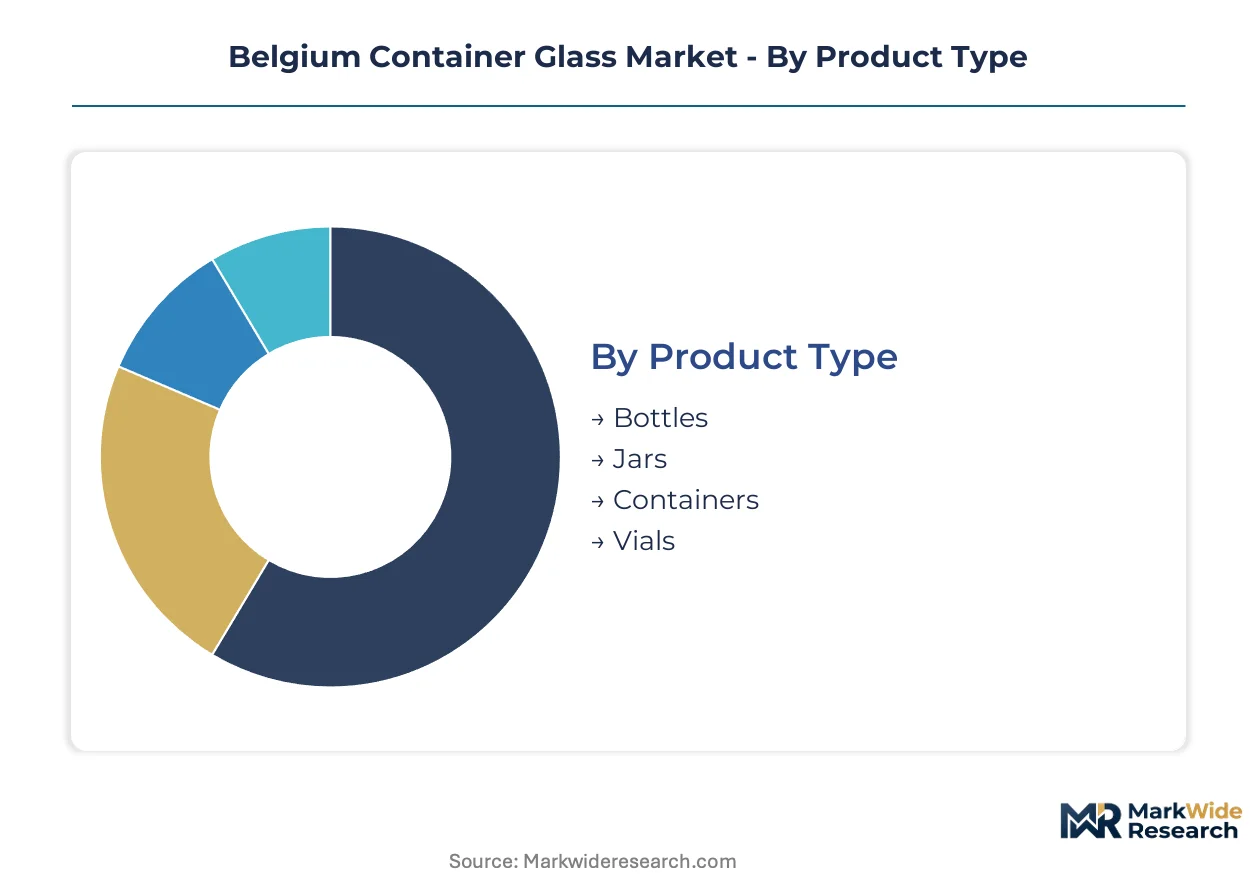
Belgian container glass buyers exhibit sharply divergent technical requirements across end-use applications, with pharmaceutical and craft beverage segments driving format specialization. Understanding these fault lines enables suppliers to calibrate furnace output, decoration capabilities, and logistics configurations against margin-differentiated demand pools.
Product Type:
Beverage producers prioritize mechanical durability and oxygen barrier performance, while pharmaceutical accounts demand borosilicate thermal stability and chemical inertness.
- Bottles:Soda-lime silica construction with 2–4 millimeter wall thickness dominates Belgian beer and mineral water packaging. Antwerp-Ghent manufacturing clusters supply standard formats, though craft brewers are compressing changeover cycles for limited-release tactile finishes.
- Vials:Borosilicate glass withstands autoclave sterilization and freeze-thaw cycles for Brussels-area biotech injectables. EMA documentation requirements for primary packaging materials extend development timelines, creating captive relationships with qualified suppliers.
- Jars:Wide-mouth configurations serve Belgian artisanal food processors seeking shelf differentiation through embossed shoulder designs and ceramic ink decoration.
- Containers:Generic terminology covers non-standard pharmaceutical and cosmetic formats where shape customization commands premium positioning.
Bottles lead volumes today; vials are gaining share fastest.
End User:
Regulatory intensity and batch size requirements separate pharmaceutical procurement patterns from commodity beverage purchasing.
- Food & Beverage:Belgian brewers and specialty food producers generate the dominant demand base, with sustainability mandates from EU Packaging and Packaging Waste Directive accelerating lightweighting investments and recycled content minimums.
- Pharmaceuticals:Brussels biotech corridor pulls specialized borosilicate capacity expansion, with REACH chemical safety registrations tightening permissible heavy-metal thresholds in colorant formulations.
- Cosmetics:Premium fragrance and skincare brands in the Antwerp-Ghent corridor demand shape customization for tactile identity, though volumes remain fragmented across short-run production schedules.
- Personal Care:Standard jar and bottle formats for Belgian toiletries manufacturers compete on decoration speed rather than structural innovation.
Food & Beverage anchors absolute volumes; Pharmaceuticals climbs the fastest on biotech corridor expansion.
Shape:
Manufacturing complexity and mold investment recovery periods determine which geometries achieve commercial scale versus remaining specialty propositions.
- Round:Lowest mold cost and highest line efficiency sustain dominance in mass-market Belgian beer and mineral water, with Flemish producers optimizing blow-and-blow cycle speeds for 33-centiliter standards.
- Custom:Direct-to-glass digital printing convergence enables batch-size-one decoration for craft beverage limited releases, eliminating label substrate costs while compressing lead times.
- Square:Space-efficient palletization drives adoption for Belgian food export brands competing on Northern European retail shelf economics.
- Rectangular:Niche positioning in premium spirits and cosmetics where flat panel surfaces accommodate applied ceramic labeling with higher resolution.
Round configurations dominate throughput; custom shapes show steepest expansion trajectory on premiumization demands.
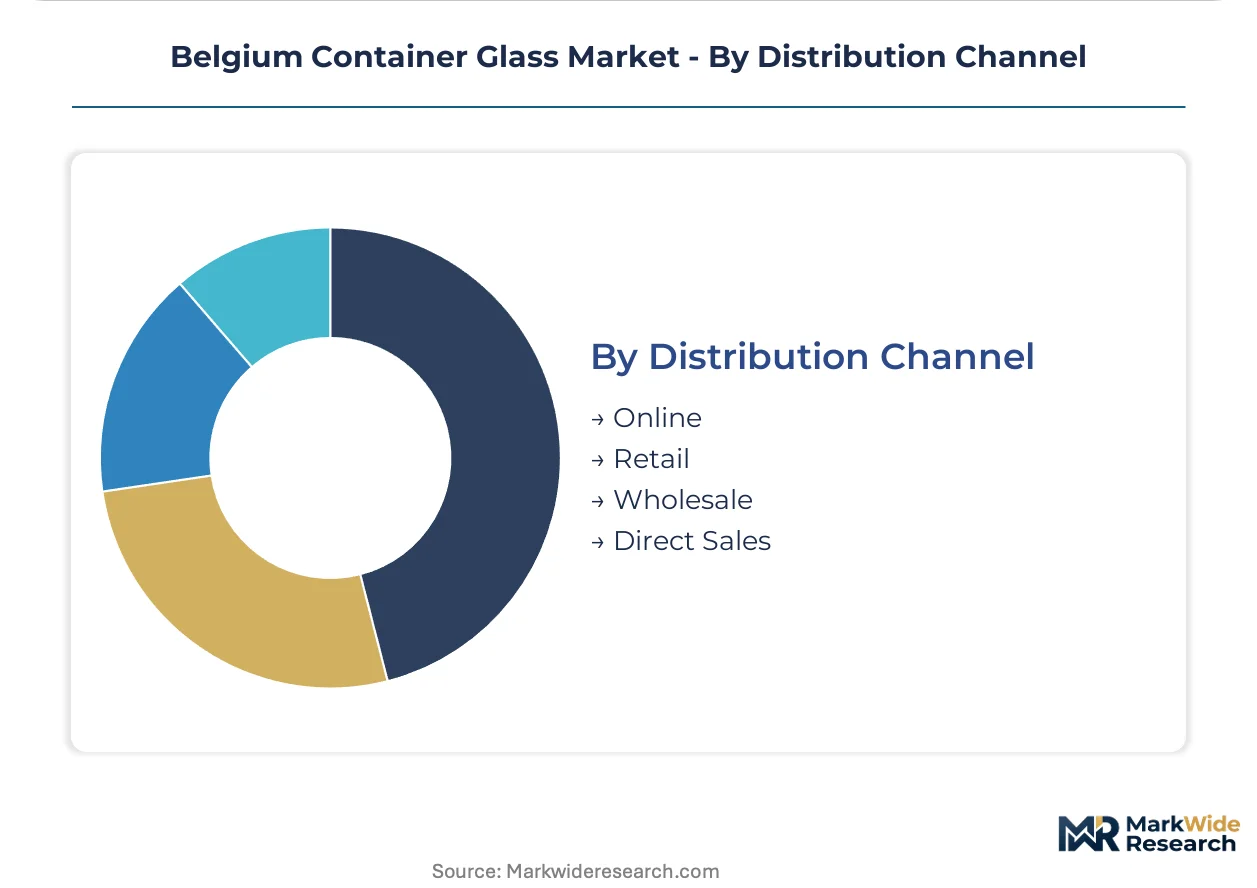
Distribution Channel:
Order fragmentation and logistics cost absorption separate direct contractual relationships from intermediated procurement.
- Direct Sales:Large Belgian brewers and pharmaceutical manufacturers negotiate furnace-dedicated output with volume commitments, securing supply security through multi-year offtake agreements.
- Wholesale:Regional distributors aggregate fragmented demand from East Flanders contract packaging facilities serving seasonal craft beverage release schedules.
- Retail:Limited penetration given bulk shipment economics; specialty glass retailers in Brussels and Antwerp serve replacement and small-batch decoration markets.
- Online:Emerging channel for standardized jar formats among Belgian artisanal food startups, though freight cost sensitivity constrains adoption.
Direct Sales commands volume concentration; Wholesale captures fragmented premium growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping European container glass production as compliance cost differentials between member states influence furnace investment location decisions. Producers evaluate national recycling infrastructure maturity and energy subsidy regimes when siting new capacity. Belgium's dense Flemish manufacturing corridor competes for capital allocation against neighboring jurisdictions with divergent environmental permitting timelines.
Flanders
Antwerp and Ghent host the densest concentration of Belgian glass manufacturing, with blow-and-blow furnaces supplying standard beverage formats to domestic brewers. OVAM environmental permitting governs emissions thresholds for these facilities. The Port of Antwerp's logistics integration enables efficient cullet import for high-recipe production runs.
Wallonia
Southern Belgium's smaller glass footprint offers greenfield development opportunities with proximity to Luxembourg and French border markets. Regional development incentives from the Walloon government support industrial diversification beyond traditional steel and coal sectors. Liège's logistics connectivity positions the province for pharmaceutical vial supply to Brussels-area biotech demand.
Brussels-Capital Region
The dense biotech R&D ecosystem pulls specialized borosilicate capacity expansion for pharmaceutical primary packaging. EMA documentation requirements for vial qualification create captive supplier relationships. Urban zoning restrictions limit furnace siting, concentrating value-added decoration and finishing operations rather than primary melting.
Netherlands
Dutch glass producers compete directly with Belgian facilities for Northern European beverage accounts, with Rotterdam port access enabling cost-efficient natural gas supply. National circular economy targets under the EU Green Deal accelerate cullet collection infrastructure investment. Cross-border supply chains integrate Belgian decoration houses with Dutch-formed base glass.
France
Northeastern French glass manufacturing in the Grand Est region competes for Belgian export-bound food brand contracts. ANSM pharmaceutical regulations align with Belgian EMA requirements, enabling qualified supplier status reciprocity. Lille's proximity to the Belgian border supports just-in-time delivery configurations for seasonal beverage release schedules.
Belgium Container Glass Market Competitive Environment
Capacity expansion dominates the current landscape as producers retrofit furnaces for electrified melting and lightweighting capability. The Belgian market exhibits moderate consolidation with a mix of multinational furnace networks and specialized decoration houses. Three archetypes define competitive positioning: integrated furnace-to-finish conglomerates, pharmaceutical-specialist borosilicate producers, and agile contract packagers serving craft beverage fragmentation. Strategic moves cluster around oxy-fuel conversion partnerships and digital printing technology licensing.
Within the integrated conglomerate tier, AGC Glass Europe SA/NV and Vetropack Group anchor regional supply security through multi-furnace networks spanning Benelux markets. Gerresheimer AG occupies the pharmaceutical-specialist position, with its Brussels-area proximity supporting EMA-qualified vial supply to biotech clusters. These three entities exemplify divergent capability investments: furnace scale versus pharmaceutical compliance versus lightweighting technology leadership.
| Leading Market Players |
|---|
| Konings plc |
| AGC Glass Europe SA/NV |
| Gerresheimer AG |
| AYANO HOLLAND BV |
| Bormioli Rocco |
| Ciner Glass Belgium |
| AXA GLASS bv/srl |
| Vetropack Group |
| SAVERGLASS Group |
| Others |
Value Chain & Pricing Dynamics
Large Belgian brewers negotiating furnace-dedicated output through multi-year offtake agreements anchor contract-based pricing that insulates volume commitments from spot market volatility. This buyer concentration enables producers to recover lightweighting R&D investments across committed tonnage while maintaining margin buffers against natural gas price fluctuations.
Pricing Analysis
Distributor margins in East Flanders contract packaging facilities compress pricing for seasonal craft beverage runs, while direct sales to pharmaceutical manufacturers command premium positioning through EMA qualification requirements. Three-tier pricing structure across premium, standard, and economy levels separates borosilicate vial specifications from mass-market beer bottles and generic jar formats. Cost compression in standard beverage glass is intensifying because aluminum can substitution pilots threaten volume retention below 33-centiliter formats. Pharmaceutical procurement exhibits least price sensitivity given regulatory captive relationships, while artisanal food startups drive highest sensitivity through fragmented order sizes.
Supply Chain Analysis
Regional distribution centers in the Port of Antwerp enable hub-and-spoke patterns that aggregate cullet imports for high-recipe production runs across Flemish manufacturing clusters. Primary melting capacity concentrates in Belgium, Netherlands, and Germany, with cross-border decoration chains integrating Belgian finishing houses with Dutch-formed base glass. Raw material dependencies center on soda ash from Solvay operations, silica sand from regional quarries, and natural gas from TTF hub pricing. Single-source vulnerability runs through Flemish municipal sorting facilities for post-consumer cullet collection. Distribution runs through direct contractual relationships for large accounts, with wholesale intermediation capturing fragmented premium volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Belgium container glass market functions as a stable compounder anchored by EU circular economy mandates that institutionalize recycled content demand across Northern European supply chains.
For Market Incumbents: Hedge against aluminum can substitution by accelerating lightweighting R&D partnerships with Antwerp-Ghent brewery accounts, while securing captive pharmaceutical vial relationships through EMA documentation investment. Furnace engineering talent scarcity demands oxy-fuel conversion knowledge transfer programs with Belgian technical institutes before demographic retirement waves erode specialized refractory expertise. Backward integration into cullet preprocessing infrastructure defends margin position against Flemish municipal sorting bottlenecks. For New Entrants and Emerging Players: Launch via digital printing decoration services targeting East Flanders contract packaging facilities serving compressed craft beverage changeover cycles. Wallonia greenfield furnace sites offer the most penetrable geography given regional development incentives and proximity to Luxembourg export markets. Pharmaceutical borosilicate capacity expansion near Brussels biotech clusters provides specialized entry angle with higher qualification barriers protecting incumbent retaliation. For Investors and Strategic Acquirers: Integrated packaging conglomerates represent the most active acquirer in this space, seeking furnace network consolidation across Benelux markets. Long-term viability frames around carbon border adjustment mechanism insulation creating competitive moats for EU-produced glass against carbon-intensive imports. Acquisition target archetype: mid-scale decoration houses with digital printing capabilities and established brewery relationships. Monitor natural gas price volatility as inflection indicator for operating leverage compression and distressed asset availability.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Furnace Conversion | Reduces Scope 1 emissions ahead of EU ETS tightening and OVAM permitting thresholds. |
| Digital Printing Technology Licensing | Eliminates label substrate costs while enabling batch-size-one customization for craft releases. |
| Cullet Preprocessing Capacity Expansion | Secures feedstock supply for Green Deal recycled content minimums across Flemish clusters. |
| Pharmaceutical Vial Qualification Investment | Creates captive supplier status with Brussels-area biotech accounts under EMA documentation requirements. |
| Wallonia Greenfield Furnace Development | Captures regional incentives while positioning for Luxembourg and French border market access. |
Study Parameters
Coverage spans Belgium, Netherlands, France, and Germany, with primary inputs from each market combining interviews with furnace operations managers, brewery procurement directors, pharmaceutical packaging engineers, and OVAM regulatory officials with secondary validation. Secondary sources include EU Packaging and Packaging Waste Directive implementation reports, EMA pharmaceutical packaging guidance documents, Flemish environmental permitting databases, and Benelux customs trade statistics. Bottom-up volume modeling from individual facility capacities triangulates against top-down demand segmentation from end-use consumption patterns.
Rate-of-change decomposition separates volume growth from price/mix effects across the projection horizon, with CAGRs derived from segment-level trend extrapolation calibrated against macroeconomic drivers. Segmentation dimensions modeled include product type, end user vertical, shape configuration, and distribution channel structure. Industry-specific forecast inputs incorporate natural gas price scenario modeling and EU glass recycling rate target trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extreme energy price volatility or accelerated aluminum substitution adoption. Forecasts reflect documented assumptions around regulatory implementation timelines and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Wire Containers Market
Containers
Concentrate Containers Market
Containers
Europe Plastic Bottles and Containers Market
Containers
Grab and Go Containers Market
Containers
2 Piece Cans Market
Containers
Single Wall Jars Market
Containers
PP Container Liner Market
Containers
Rotomolded Containers Market
Containers
Injection Molding Containers Market
Containers
Screw Top Pails Market
Containers
Canning Jars Market
Containers
Asia and Africa Food Cans Market
Containers
North America Plastic Bottles and Containers Market
Containers
Disposable Cups and Lids Market
Containers
Jug Shipper Market
Containers
Car Lube Container Market