
 Bucket Elevator Market | 2026-2036
Bucket Elevator Market Size, Share, and Industry Trends Forecast 2026-2036
Bucket Elevator Market Analysis
The gap between premium engineered systems and commodity bucket elevators is consolidating around material grade, with stainless-steel construction and abrasion-resistant alloys separating high-reliability installations from price-driven tenders. BEUMER Group leverages its German engineering heritage to dominate large-capacity mining applications across Australia and Brazil. SKANDIA Elevator AB anchors Nordic grain logistics through compact vertical designs optimized for cold-climate silo operations. Sweet Manufacturing Company differentiates via modular chain-and-belt platforms that cut field assembly time for mid-scale agriculture processors.
A bucket elevator is a continuous bulk-material handling device comprising an endless belt or chain fitted with buckets that scoop, elevate, and discharge free-flowing solids vertically or at steep angles, typically operating at speeds of 1.0–2.5 m/s depending on material abrasiveness. Its primary purpose is to transfer powders, granules, and lumps between process stages with minimal degradation in industries where floor space constraints prohibit inclined conveyors. Belt-type configurations lead in food-processing hygiene applications where plastic or stainless-steel buckets prevent contamination, while chain-type units capture margin pools in mining through heavy-duty forged-link designs rated for extra-large capacities exceeding 500 tph. The steel material segment sustains dominant volume across cement and mining verticals, though composite bucket segments gain traction in recycling facilities seeking reduced elevator weight and lower drive energy.
OSHA grain handling standards in the United States mandate explosion venting and bearing temperature monitoring, compelling retrofit demand across legacy agricultural installations. REACH and CE marking requirements in Europe restrict certain polymer additives in plastic buckets, redirecting material specification toward compliant thermoset formulations. China's SAMR enforces GB standards for mechanical conveyor safety and dust emission limits that filter market access for uncertified imports. Stakeholders must monitor how divergent regional testing protocols for fatigue-rated chain assemblies reshape supplier qualification timelines and aftermarket parts interoperability.
Market Dynamics
China's GB standards for mechanical safety and dust containment are compressing supplier margins while filtering uncertified imports, forcing procurement teams to rebuild qualification timelines around dual carbon compliance and fatigue-rated chain assembly testing.
Growth Catalysts
- Cement capacity expansions:Southeast Asian producers are commissioning new clinker lines that require high-capacity vertical conveying systems rated for abrasive materials and continuous operation cycles.
- OSHA grain handling standards:Mandated explosion venting and bearing temperature monitoring in the United States are compelling retrofit investments across legacy agricultural installations built before 2020.
- Abrasion-resistant alloys:Stainless-steel construction grades are separating high-reliability mining installations from price-driven tenders in Australia's iron ore corridor.
Market Restraints
- Steel input cost volatility:Hot-rolled coil price swings directly impact fabricated casing and head section margins for domestic fabricators in India.
- Chain assembly supply concentration:Forged-link heavy-duty designs rated above 500 tph remain concentrated among German and Japanese specialty manufacturers.
- REACH polymer restrictions:ECHA limitations on certain thermoplastic additives are redirecting food-grade bucket specifications toward compliant thermoset formulations with longer lead times.
Strategic Opportunities
- India's grain handling corridor:The Punjab-to-port logistics network lacks modern vertical conveying infrastructure, creating whitespace for compact belt-type installations.
- EU Green Deal alignment:Carbon border adjustment mechanisms are incentivizing European cement producers to source energy-efficient elevator retrofits with regenerative drive systems.
- Recycling facility weight reduction:Composite bucket segments are penetrating municipal waste and e-waste sorting plants seeking lower drive energy and reduced structural load.
Industry Challenges
- Fatigue-rated welding certification:GB standards for chain assembly testing are extending supplier qualification timelines by six to nine months for new market entrants.
- Legacy system integration:Belt-to-chain conversion projects in Brazilian mining operations face downtime risks from incompatible discharge chute geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bucket Elevator Market |
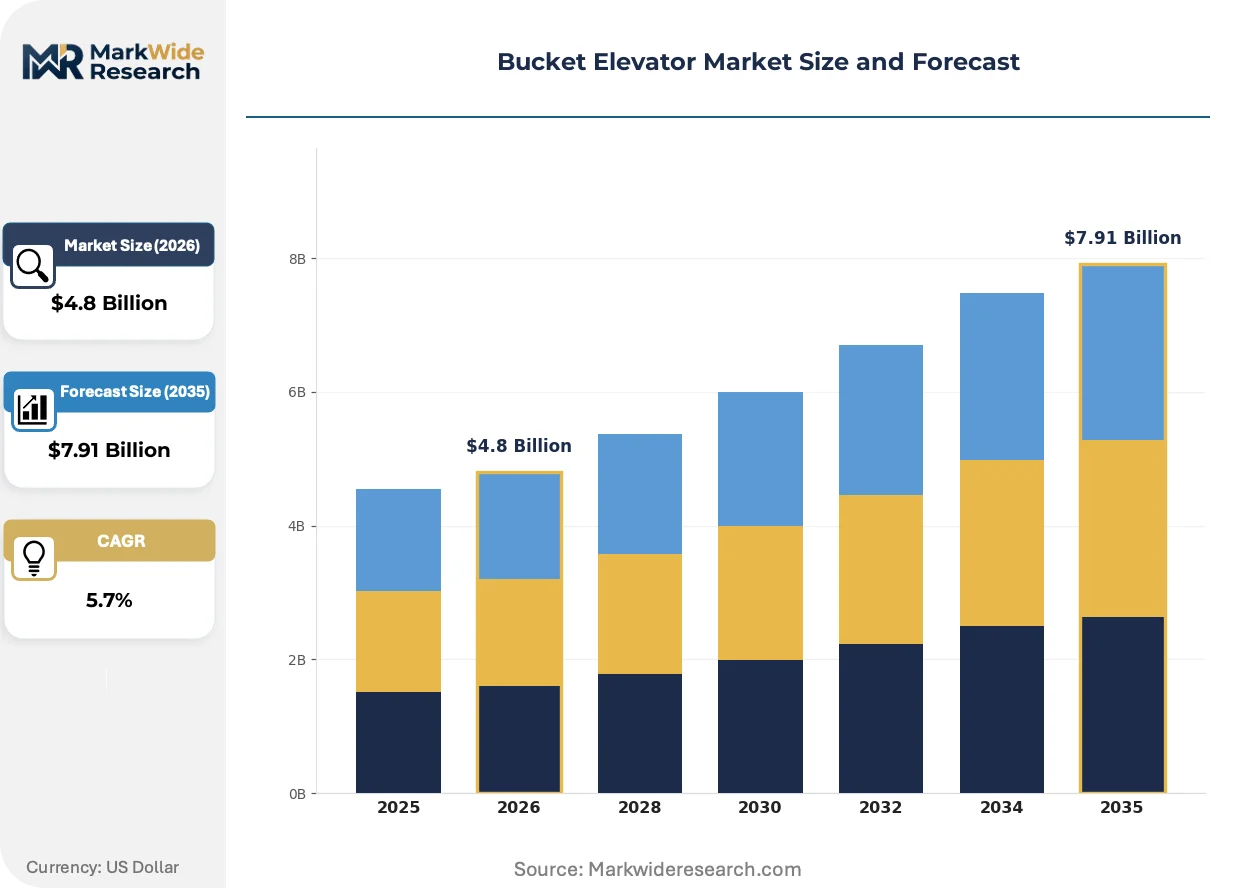
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Vertical, Catenary, Belt, Chain Capacity: Small, Medium, Large, Extra Large Material: Steel, Plastic, Aluminum, Composite Industry Vertical: Agriculture, Mining, Food Processing, Recycling |
| Companies Covered | KWS Manufacturing Co Ltd, SKANDIA Elevator AB, FEECO International Inc, AGI, Ryson International Inc, BEUMER Group, Sweet Manufacturing Company, Meyer Industries, Sukup Manufacturing Co, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bucket Elevator Market Emerging Trajectories
Intelligent monitoring systems and material science advances are compressing maintenance cycles while enabling predictive failure models that reshape aftermarket service economics across heavy bulk handling.
IoT-enabled vibration sensors paired with edge computing analytics are decentralizing maintenance decision-making from centralized plant engineering offices to on-site technician tablets. Mining operators in Australia's Pilbara region are deploying these systems at half their previous diagnostic labor cost. The technology is decentralizing aftermarket service relationships from OEM captive contracts toward independent predictive maintenance providers.
China's SAMR enforcement of GB/T conveyor safety standards is mandating redundant braking systems and emergency stop logic for all new installations above 50 meters lift height. Domestic cement producers are absorbing compliance costs through bundled procurement with certified integrators. The regulation most affects mid-scale agricultural processors importing uncertified belt-type units from Southeast Asian fabricators.
Buyer consolidation among multinational grain traders is compressing equipment specification cycles from twelve months to six, privileging suppliers with modular platform architectures. Nordic cooperatives are unbundling after-sales service from initial capital contracts, sourcing spare parts through third-party logistics hubs. The shift is most visible in Denmark and Sweden where elevator replacement rates exceed European averages by a factor of two.
Bucket Elevator Market Segmentation
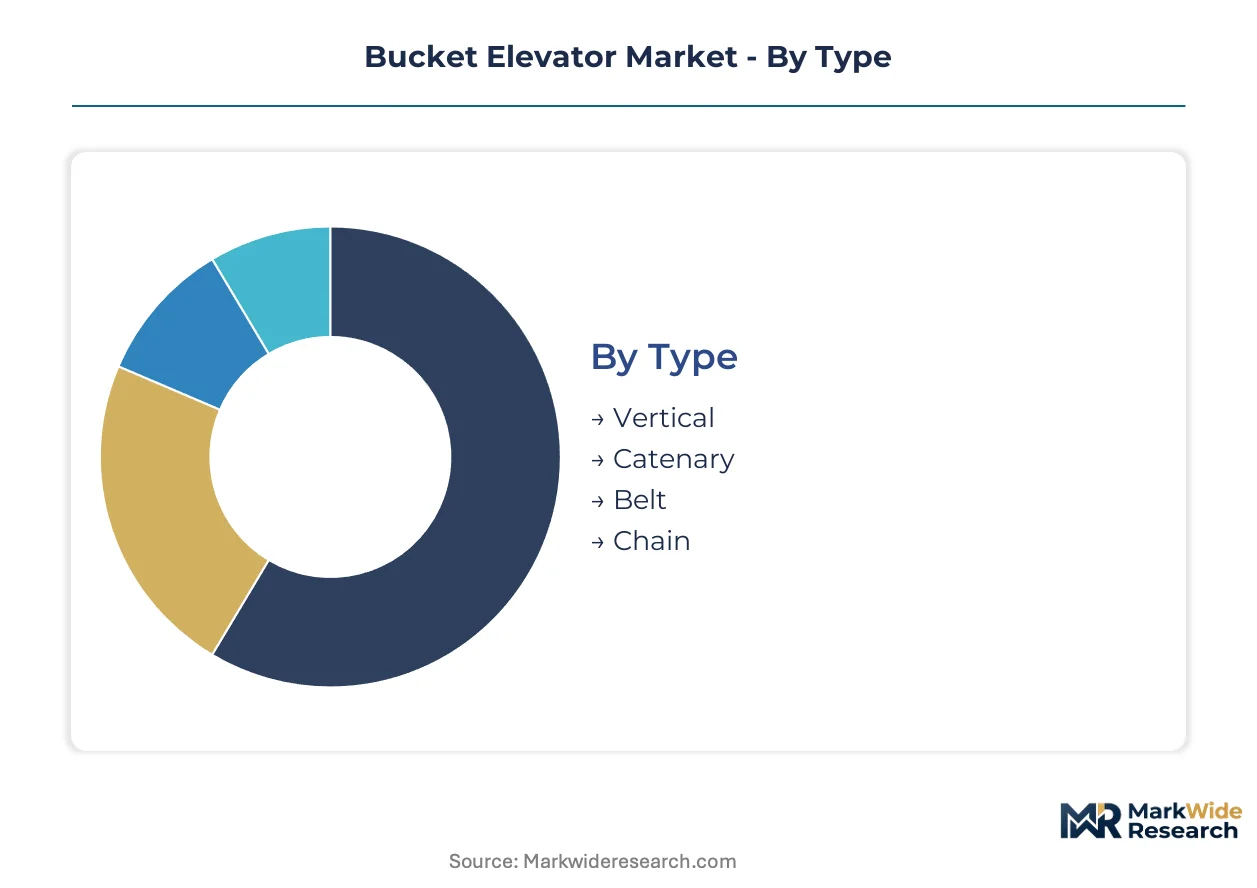
Bucket elevator procurement decisions hinge on material abrasiveness, lift height, and duty cycle intensity. Specification mismatches between conveyor type and bulk density drive premature wear and unplanned downtime across cement and grain handling operations.
Type:
Standalone vertical configurations dominate greenfield installations, while catenary and inclined variants embed into constrained retrofit sites.
- Vertical:Straight-up lift designs handle the steepest elevation gains with minimal footprint. Cement producers in Vietnam and Indonesia specify these for clinker transfer between kiln and storage silos amid space-constrained plant layouts.
- Catenary:Curved-path systems navigate around existing structures without structural modifications. Australian iron ore ports deploy catenary configurations to thread through dense material handling corridors where straight runs are impossible.
- Belt:Continuous rubber or synthetic belt platforms with molded buckets suit fine powders and food-grade applications. Belt-type units capture hygiene-sensitive grain elevators across India's Punjab corridor.
- Chain:Forged-link or roller chain drives rated for abrasive lumps and high shock loads. Chain configurations anchor heavy mining operations in Brazil's Carajás iron ore district.
Vertical leads volumes today; belt configurations are gaining share fastest in food processing retrofits.
Capacity:
Cost tier stratification separates price-driven tenders from engineered reliability contracts across the tonnage spectrum.
- Small:Units below 50 tph serve farm-scale grain cooperatives and specialty chemical batching. Small-capacity elevators concentrate in Denmark's Nordic cooperative network where replacement rates exceed European averages.
- Medium:50–200 tph systems balance capital efficiency with operational flexibility. Medium-capacity installations dominate India's port terminal modernization linking Punjab grain belts to export infrastructure.
- Large:200–500 tph configurations serve integrated cement and mining complexes with continuous duty requirements. Large units anchor clinker lines across Southeast Asian capacity expansions.
- Extra Large:Systems exceeding 500 tph demand fatigue-rated forged-link chains from German and Japanese specialty manufacturers. Extra-large capacities concentrate in Australia's Pilbara mining region where single-conveyor reliability eliminates redundant parallel lines.
Large capacity dominates capital expenditure today; extra-large configurations are climbing the fastest as mining operators consolidate parallel elevators.
Material:
Application severity dictates material grade selection, with abrasion resistance and corrosion tolerance separating premium from commodity procurement tiers.
- Steel:Carbon and abrasion-resistant alloy casings, buckets, and head sections withstand high-impact mining and cement environments. Steel construction sustains dominant volume across Australian iron ore and Southeast Asian clinker handling.
- Plastic:Polyethylene and polyurethane buckets prevent contamination in food-grade grain and powder applications. Plastic segments penetrate Nordic grain elevators where REACH-compliant thermoset formulations replace restricted thermoplastic additives.
- Aluminum:Lightweight casings reduce structural load in elevated installations and corrosive atmospheres. Aluminum configurations serve coastal grain terminals in Brazil where salt exposure accelerates carbon steel degradation.
- Composite:Fiber-reinforced polymer buckets and casing segments cut elevator weight and drive energy. Composite materials are expanding most quickly in European recycling facilities seeking reduced structural loads and regenerative drive compatibility.
Steel leads installed base today; composite segments are expanding most quickly in waste handling and e-waste sorting plants.
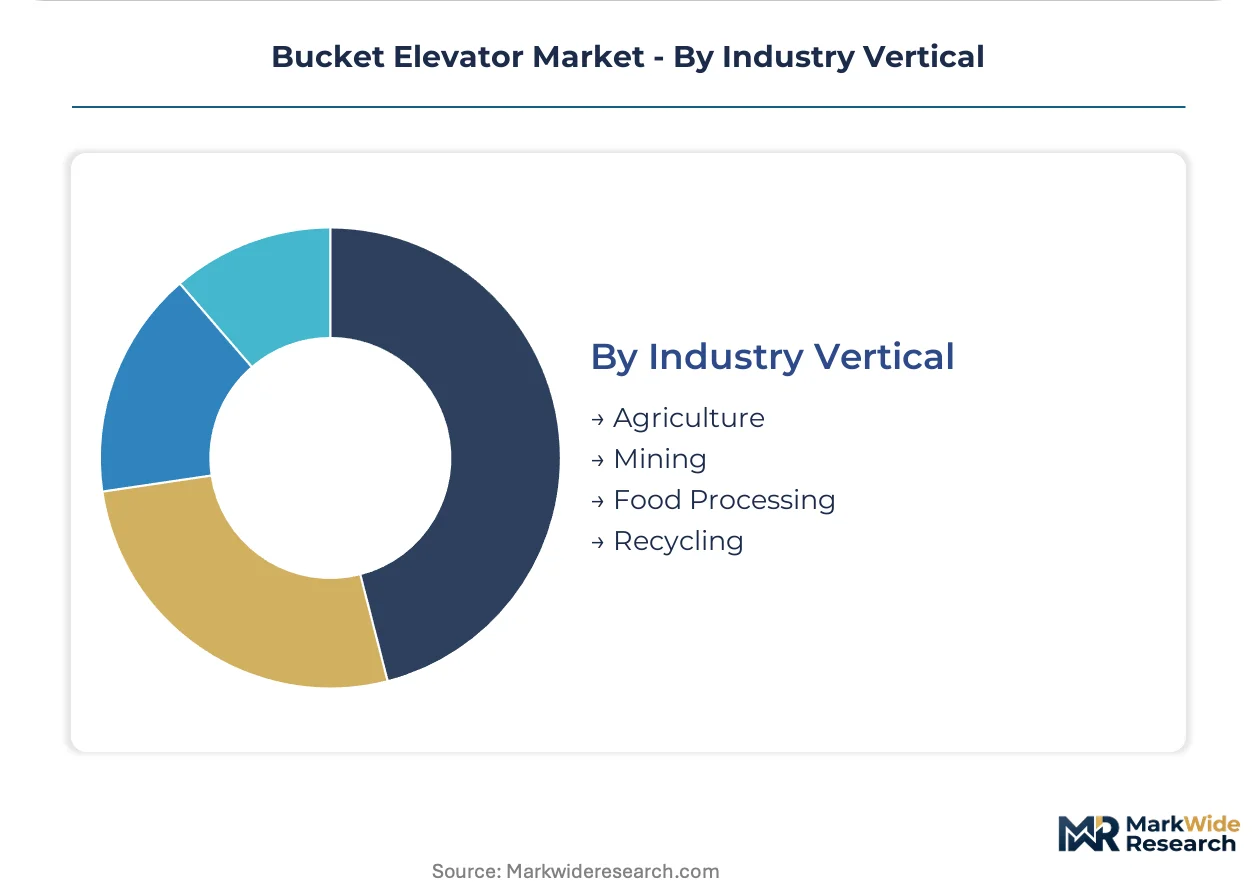
Industry Vertical:
Customer type diversity spans multinational miners, cooperative grain handlers, and municipal waste authorities with divergent specification priorities.
- Agriculture:Grain elevators, silo loading, and seed processing demand hygiene certification and explosion protection. Agricultural procurement concentrates in India's Punjab-to-port corridor and US Midwest retrofit markets where OSHA mandates bearing temperature monitoring.
- Mining:Iron ore, copper, and aggregate handling requires extra-large capacities with abrasion-resistant alloy construction. Mining demand anchors in Australia's Pilbara and Brazil's Carajás district where continuous duty cycles dominate specification.
- Food Processing:Flour, sugar, and specialty ingredient handling mandates stainless-steel or food-grade plastic contact surfaces. Food processing specifications concentrate in European installations where ECHA polymer restrictions redirect bucket material selection.
- Recycling:Municipal waste, e-waste, and construction debris sorting plants prioritize reduced weight and energy efficiency. Recycling verticals are expanding most quickly in European facilities aligning with EU Green Deal carbon border adjustment mechanisms.
Agriculture leads unit volumes today; recycling verticals are gaining share fastest amid circular economy infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering talent anchors premium conveyor design, while Brazilian mining clusters and Indian agricultural corridors concentrate operational demand for vertical bulk handling systems.
United States
OSHA grain handling standards drive retrofit investments across Midwest agricultural cooperatives. The 1987 Grain Handling Facilities Standard mandates explosion venting and bearing temperature monitoring. Iowa and Illinois elevator networks upgrade legacy installations to comply with federal workplace safety enforcement.
Germany
REACH polymer restrictions redirect food-grade bucket specifications toward compliant thermoset formulations. ECHA limitations on certain plastic additives extend procurement lead times. Engineering consultancies in North Rhine-Westphalia certify fatigue-rated chain assemblies for export to Asian mining operations.
China
SAMR enforcement of GB/T conveyor safety standards mandates redundant braking systems for installations above 50 meters lift height. Domestic cement producers absorb compliance costs through bundled procurement with certified integrators. Shandong Province fabricators face margin compression from dual carbon compliance requirements.
Australia
Iron ore producers in the Pilbara region deploy IoT-enabled vibration sensors at half previous diagnostic labor costs. METI-aligned technical standards influence procurement specifications for extra-large capacity systems. Western Australian mining corridors consolidate parallel elevators into single 500+ tph units.
Brazil
Carajás iron ore district operations require continuous-duty chain configurations rated for abrasive lump materials. ANVISA industrial safety protocols intersect with mining sector equipment certification. São Paulo-based integrators manage belt-to-chain conversion projects facing downtime risks from incompatible discharge geometries.
Bucket Elevator Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the bucket elevator supply base. German and Japanese specialty manufacturers concentrate forged-link chain production for extra-large capacity applications above 500 tph. The market structures around three archetypes: integrated mining-systems providers, modular agricultural-equipment fabricators, and regional maintenance-service contractors. Capacity expansion and strategic partnerships dominate competitive moves as suppliers rebuild qualification timelines around fatigue-rated welding certification.
Among German-based engineering groups, BEUMER Group occupies a position representing integrated systems provision for mining applications. SKANDIA Elevator AB exemplifies the compact-design archetype serving Nordic grain logistics. Sweet Manufacturing Company sits within the modular-platform tier, cutting field assembly time for mid-scale agricultural processors through standardized chain-and-belt configurations.
| Leading Market Players |
|---|
| KWS Manufacturing Co Ltd |
| SKANDIA Elevator AB |
| FEECO International Inc |
| AGI |
| Ryson International Inc |
| BEUMER Group |
| Sweet Manufacturing Company |
| Meyer Industries |
| Sukup Manufacturing Co |
| Others |
Supply Flow & Price Mechanics
Specialized fatigue-rated welders in North Rhine-Westphalia command premium labor rates that compress margins for forged-link chain assemblies while widening the spread between certified premium systems and commodity tenders from uncertified Southeast Asian fabricators.
Pricing Analysis
After-sales service bundling separates procurement tiers across the bucket elevator market. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with OEM captive contracts capturing the top tier and independent service providers eroding mid-tier margins. Cost compression in the economy tier intensifies as Indian fabricators absorb steel input volatility. Agricultural cooperatives in Denmark exhibit the highest price sensitivity, while Australian iron ore operators prioritize reliability over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale mining demand while regional integrators serve fragmented agricultural procurement. Forged-link chain production concentrates in Germany and Japan, with fabricated casing segments sourcing from China and India. The supply chain draws from hot-rolled coil steel, abrasion-resistant alloy castings, and compliant thermoset polymer formulations. Single-source vulnerability in fatigue-rated welding certification extends supplier qualification timelines. Distribution runs through certified integrators bundling installation with compliance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA grain handling standards and China's GB/T conveyor safety mandates are accelerating replacement cycles across legacy agricultural and cement installations.
For Market Incumbents: Extend predictive maintenance service contracts to capture aftermarket revenue streams as Nordic cooperatives unbundle capital from service procurement. Deepen backward integration into fatigue-rated welding certification to defend against German and Japanese specialty manufacturers. Capacity expansion in India's Punjab-to-port corridor addresses the fastest-growing demand cluster. For New Entrants and Emerging Players: Mid-scale agricultural processors importing uncertified belt-type units represent the most penetrable buyer archetype as China's SAMR enforcement filters market access. Target compact vertical designs optimized for cold-climate silo operations in Nordic markets where replacement rates exceed European averages. Pursue third-party logistics hub partnerships to bypass OEM captive service networks. For Investors and Strategic Acquirers: Mining-systems integrators are the most active acquirer in this space as Australia's Pilbara operators consolidate parallel elevators into single 500+ tph units. Asset-light modular-platform designers with standardized chain-and-belt configurations offer the strongest five-to-ten-year viability. Monitor GB standards fatigue-rated chain assembly testing protocol divergence as the signal for supplier qualification timeline inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Fatigue-Rated Welding Certification Investment | BEUMER Group and German engineering groups leverage certified assemblies to dominate Australian and Brazilian mining contracts. |
| Modular Platform Architecture Development | Sweet Manufacturing Company cuts field assembly time for mid-scale agricultural processors through standardized configurations. |
| Predictive Maintenance Service Expansion | IoT-enabled vibration sensors at Pilbara operations decentralize aftermarket relationships from OEM captives. |
| Composite Material R&D Partnership | European recycling facilities align with EU Green Deal mechanisms through fiber-reinforced polymer bucket segments. |
| India Grain Corridor Distribution Buildout | SKANDIA Elevator AB anchors Nordic designs into Punjab-to-port infrastructure lacking modern vertical conveying systems. |
Methodological Framework
Direct dialogue with plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors at cement and mining operations grounded qualitative findings in operational reality. Secondary validation drew from SEC filings of listed industrial equipment manufacturers, customs and trade data on steel and polymer inputs, and SAMR GB standards documentation. Bottom-up installation counts across capacity tiers triangulated with top-down capital expenditure estimates from regional construction databases.
Installed base projections across the analysis window segmented by type, capacity, material, and industry vertical, with CAGRs derived from regression against cement capacity expansion announcements and grain handling infrastructure budgets. Model inputs included OSHA enforcement intensity indices, REACH polymer restriction compliance costs, and iron ore production forecasts from Australia's Pilbara region.
Underlying measurement precision varies by segment; extra-large capacity mining installations carry tighter precision than fragmented small-capacity agricultural cooperatives. Forecasts reflect assumptions on regulatory enforcement continuity and steel input cost stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Dust Suppression Fog Cannon Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Concrete Mixer Market
Construction Equipment
Welding Equipment Market
Construction Equipment
Self-Pierce Riveting (SPR) Equipment Market
Construction Equipment
Press Fit Machines Market
Construction Equipment
Horizontal Machining Center Market
Construction Equipment
Compressed Earth Block Machine Market
Construction Equipment
Hybrid Construction Equipment Market
Construction Equipment
Tunnel Boring Machines Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Backhoe Bucket Market
Construction Equipment
Welding Equipment and Consumables Market
Construction Equipment
Industrial Grout Pumps Market
Construction Equipment
Jib Crane Market